
 Lithium-Ion Battery Reuse and Recycling Market | 2026-2036
Lithium-Ion Battery Reuse and Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium-Ion Battery Reuse and Recycling Market Insights
Automotive-grade cell recovery is rotating toward higher purity thresholds that qualify materials for direct cathode remanufacturing. Redwood Materials leverages proprietary hydrometallurgical processes to sustain domestic lithium recovery in the United States. Li-Cycle Corp anchors North American processing capacity through its spoke-and-hub distributed model. Umicore differentiates via integrated smelting and refining operations that span battery metals and specialty chemicals.
Lithium-ion battery reuse and recycling encompasses the collection, testing, disassembly, and material recovery of spent cells to extract cobalt, nickel, lithium, and graphite for re-entry into manufacturing supply chains. The process requires controlled discharge, mechanical shredding, and either high-temperature smelting or chemical leaching to achieve battery-grade purity standards for cathode precursor production. Electric Vehicles dominates product type inflow volumes as automotive end-of-life pipelines mature across OEM take-back programs. Hydrometallurgical recycling captures the fastest expansion trajectory among methods due to superior lithium recovery rates and lower energy intensity relative to pyrometallurgical alternatives.
The EPA administers hazardous waste classification under RCRA that governs spent battery transport and storage protocols across the United States. The EU Battery Regulation establishes mandatory minimum recycled content rates and due diligence frameworks that condition market access for recyclers serving European OEMs. China's MEE enforces discharge standards for recycling effluent that shape facility permitting and capital requirements. Stakeholders must monitor how evolving extended producer responsibility schemes redistribute collection costs between automakers and independent recyclers.
Market Dynamics
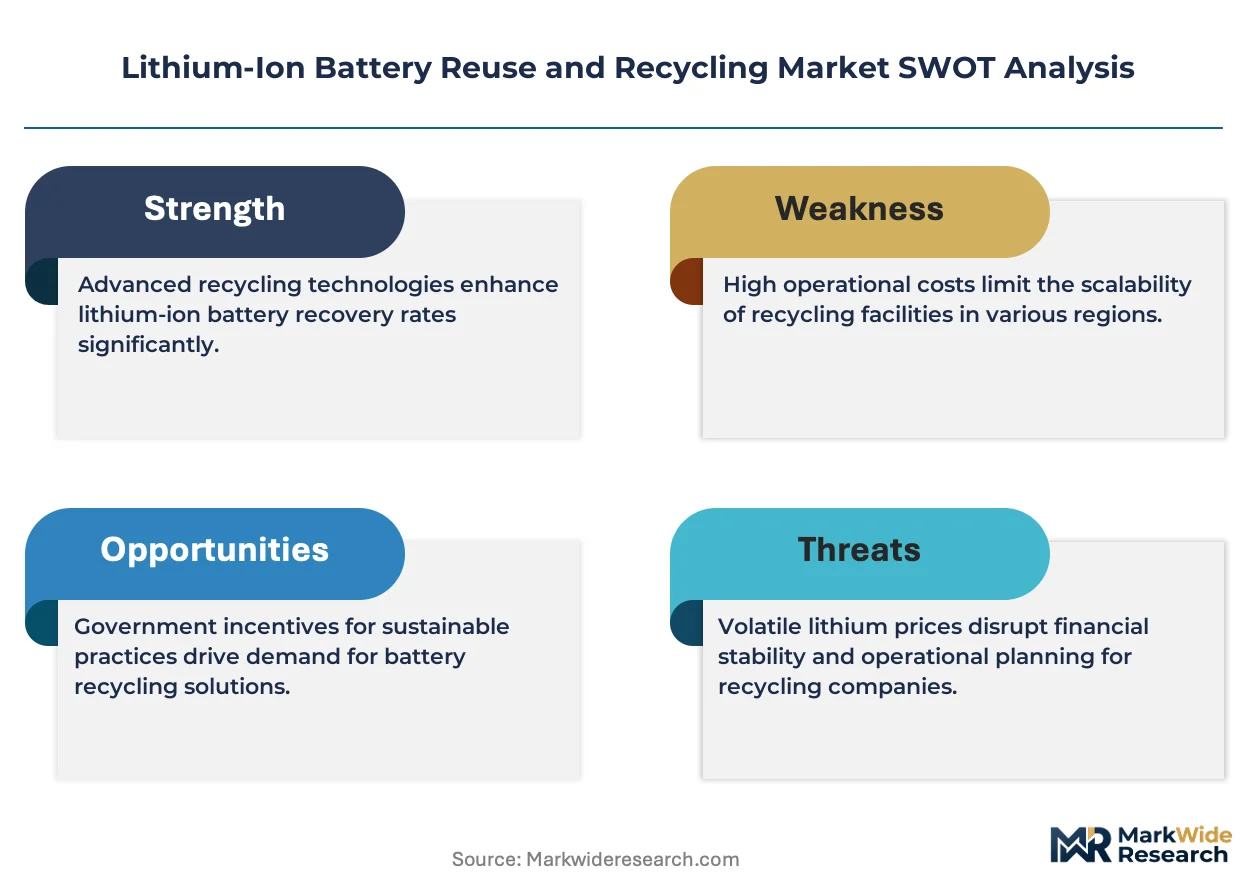
EU Battery Regulation recycled content quotas are compressing virgin material demand curves while forcing OEMs to contract directly with hydrometallurgical processors rather than spot-market traders.
Growth Catalysts
- EU Battery Regulation mandates:Minimum recycled lithium thresholds create guaranteed offtake contracts for qualified processors serving European automotive OEMs.
- Electric vehicle end-of-life pipelines:First-generation EV fleets from 2015-2018 model years are entering systematic collection channels at commercial scale.
- Hydrometallurgical lithium recovery:Direct solvent extraction methods achieve battery-grade purity without energy-intensive pyrometallurgical smelting stages.
Market Restraints
- Cobalt price volatility:DRC concentrate supply disruptions transmit directly to black mass valuation spreads and processor margin compression.
- Collection infrastructure gaps:Rural and secondary city networks lack certified transport capacity for hazardous battery classification under EPA RCRA protocols.
- Cell format heterogeneity:Cylindrical, prismatic, and pouch architectures require modular disassembly lines that resist standardization.
Strategic Opportunities
- India PLI scheme incentives:Domestic cell manufacturing mandates create captive recycling demand as local gigafactories scale through 2030.
- Second-life stationary storage:Degraded automotive packs retain 70-80% capacity for grid-balancing applications before final material recovery.
- Blockchain traceability integration:Digital battery passports enable premium pricing for verified recycled content across European supply chains.
Industry Challenges
- Battery-grade purity certification:Cathode precursor qualification timelines extend 18-24 months, locking processors into single OEM validation queues.
- Skilled pyrometallurgist shortage:High-temperature process engineering expertise concentrates in legacy mining regions rather than emerging recycling clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium-Ion Battery Reuse and Recycling Market |
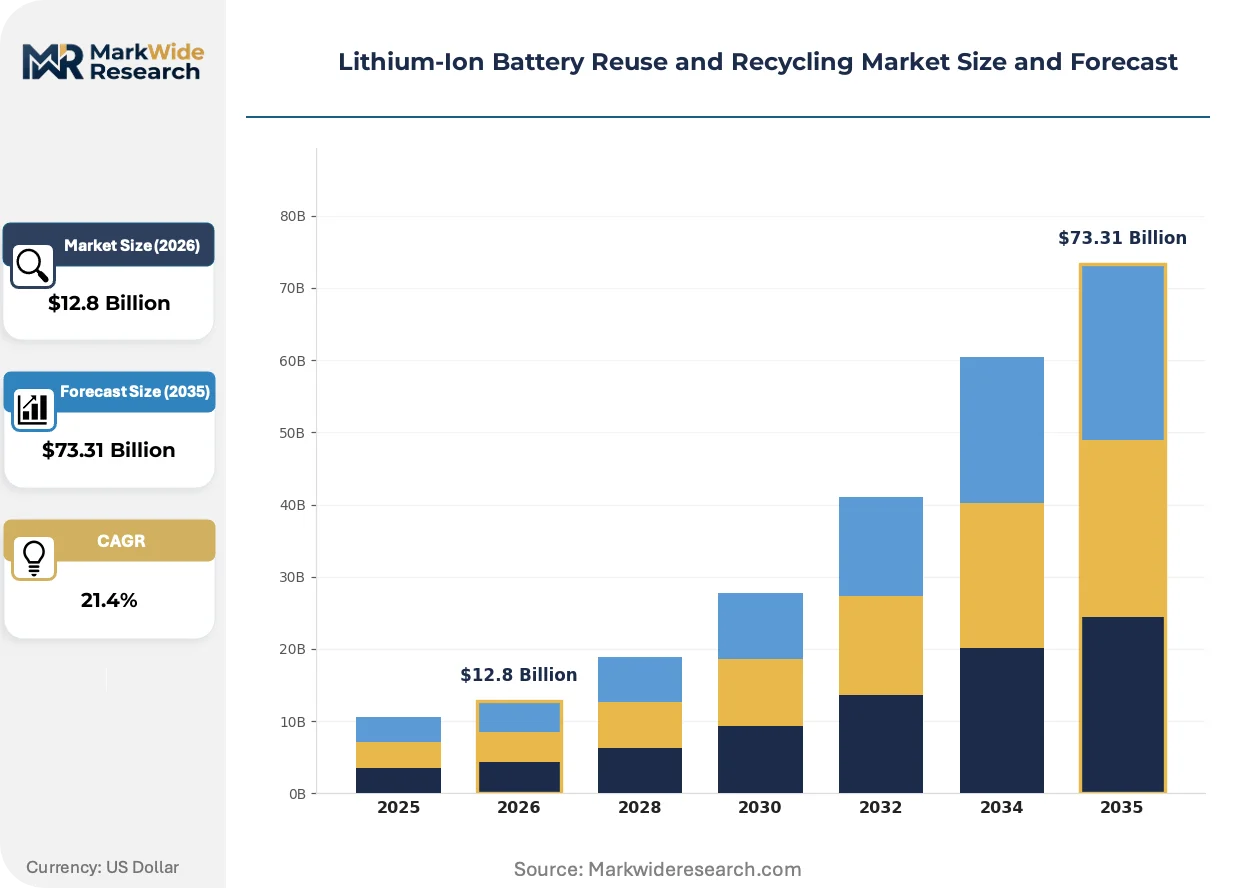
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $73.31 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consumer Electronics, Electric Vehicles, Industrial Applications, Energy Storage Systems Recycling Method: Hydrometallurgical, Pyrometallurgical, Direct Recycling, Mechanical Separation End User: OEMs, Battery Manufacturers, Recycling Facilities, Research Institutions Material Type: Cobalt, Nickel, Graphite, Lithium, Others |
| Companies Covered | Umicore, Li-Cycle Corp, Redwood Materials, Glencore, Cirba Solutions, GEM Co., Ltd, RecycLiCo Battery Materials Inc., Ecobat, Brunp Recycling Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium-Ion Battery Reuse and Recycling Market Trends and Innovations
Direct cathode regeneration is bypassing intermediate precursor production, collapsing traditional refining stages while demanding precision diagnostic sorting at collection points.
Direct regeneration technology is decomposing the conventional black mass-to-salt-to-precursor pipeline. Automotive OEMs in Germany and South Korea are piloting closed-loop contracts that return spent cells to original cathode chemistry without intermediate trading. This compression is decomposing merchant processor margins and concentrating value capture within vertically integrated battery manufacturers.
REACH authorization requirements for nickel and cobalt compounds are tightening material documentation standards across European recycling imports. The regulation forces non-EU processors to adopt EU-equivalent audit protocols or face exclusion from premium cathode supply chains. Asian exporters are responding by establishing EU-located subsidiary entities to maintain market access.
Fleet operators are consolidating second-life battery procurement through long-term service agreements rather than asset purchases. Energy storage integrators are displacing spot-market traders as the primary counterparty for degraded automotive packs. This shift is most visible in California and Texas, where utility-scale storage developers contract directly with rideshare and delivery fleet managers for systematic cell retirement streams.
Lithium-Ion Battery Reuse and Recycling Market Segmentation
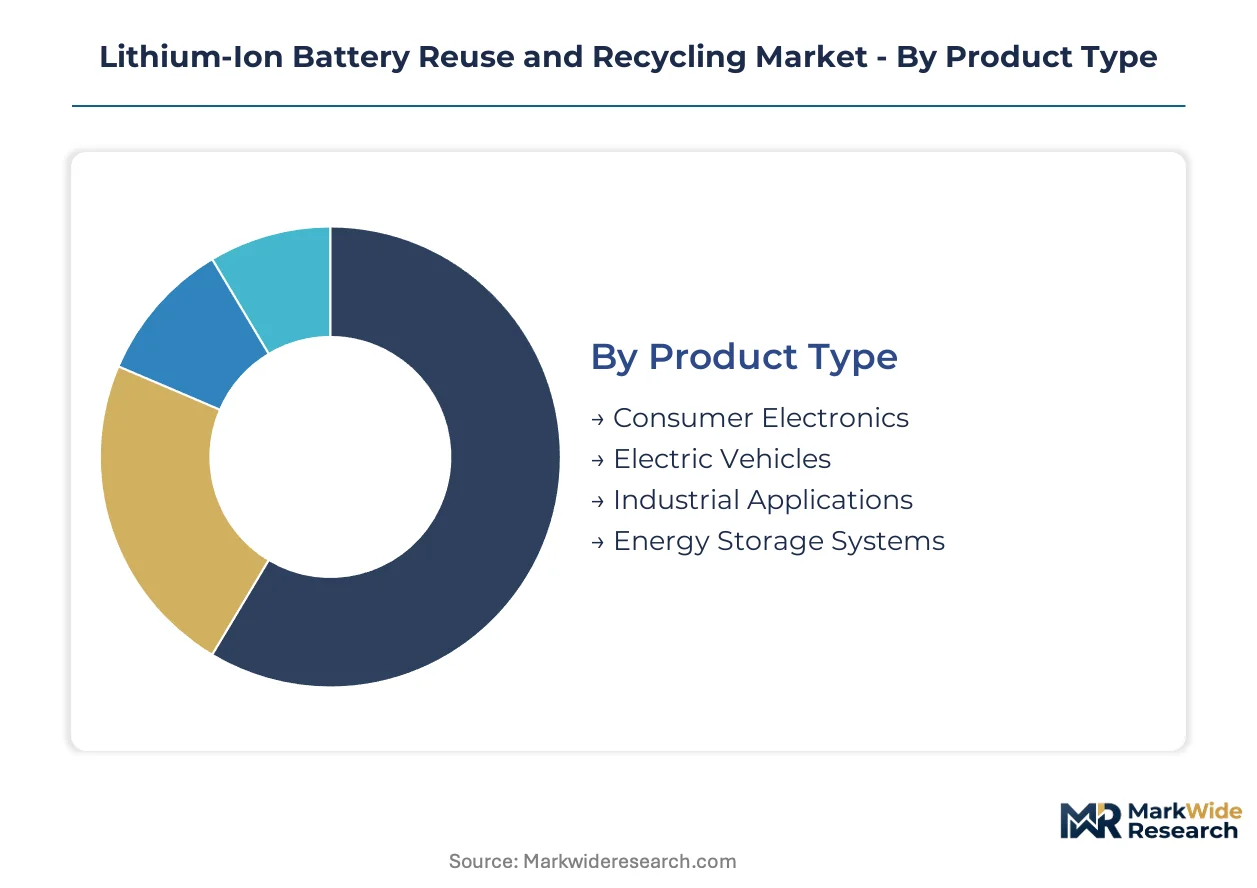
Segmentation in battery reuse and recycling reveals how regulatory mandates, chemistry heterogeneity, and end-of-life pipeline maturity create divergent processing economics across collection channels. Understanding these divisions enables processors to align capital deployment with the highest-yield material recovery streams.
Product Type:
EU Battery Regulation recycled content quotas apply differentially across product categories, with automotive applications facing the strictest compliance timelines and documentation requirements.
- Electric Vehicles:Automotive-grade lithium-ion cells contain high nickel-cobalt-manganese cathode formulations that command premium recovery economics. Fleet operators in Germany and California are establishing systematic collection partnerships with hydrometallurgical processors to secure compliant material streams for European OEM qualification.
- Consumer Electronics:Portable device batteries present lower cobalt concentrations and higher format heterogeneity that complicates automated disassembly. Collection concentrates in urban China and South Korea where reverse logistics networks for smartphones and laptops achieve sufficient density to justify dedicated processing lines.
- Industrial Applications:Forklift and stationary power systems utilize larger format cells with extended duty cycles that delay end-of-life timing.
- Energy Storage Systems:Grid-scale battery installations generate concentrated volume streams but require specialized discharge protocols due to residual energy capacity.
Established volume favors Electric Vehicles; emerging adoption favors Energy Storage Systems.
Recycling Method:
Capital intensity and energy requirements separate processing approaches into distinct competitive tiers that attract different investor profiles and offtake contract structures.
- Hydrometallurgical:Chemical leaching and solvent extraction achieve battery-grade lithium recovery rates exceeding pyrometallurgical alternatives while operating at substantially lower energy intensity. China MEE discharge standards favor this method for new facility permitting in Jiangsu and Guangdong provinces.
- Direct Recycling:Cathode regeneration preserves crystalline structure and bypasses intermediate precursor production, collapsing processing stages. South Korean battery manufacturers are piloting closed-loop contracts that return spent cells to original chemistry without black mass trading.
- Pyrometallurgical:High-temperature smelting remains dominant for mixed-waste streams and facilities with legacy mining infrastructure.
- Mechanical Separation:Shredding and physical sorting provides feedstock preparation for downstream refining operations.
Scale economics favor Hydrometallurgical; technology disruption potential favors Direct Recycling.
End User:
Contract structures and purity requirements vary sharply between integrated manufacturers seeking captive supply and merchant processors serving spot markets.
- OEMs:Automotive manufacturers are internalizing recycling capabilities through acquisition and partnership to secure qualified recycled content for EU Battery Regulation compliance. Volkswagen and BMW have established direct offtake agreements with hydrometallurgical facilities in Germany and Belgium.
- Battery Manufacturers:Cell producers require cathode precursor materials that meet stringent qualification timelines extending 18-24 months for new supplier validation.
- Recycling Facilities:Merchant processors face margin compression as direct regeneration technology reduces intermediate trading opportunities.
- Research Institutions:Academic and national laboratory partnerships drive pilot-scale validation of novel recovery chemistries.
Contract security favors OEMs; margin expansion potential favors Battery Manufacturers.
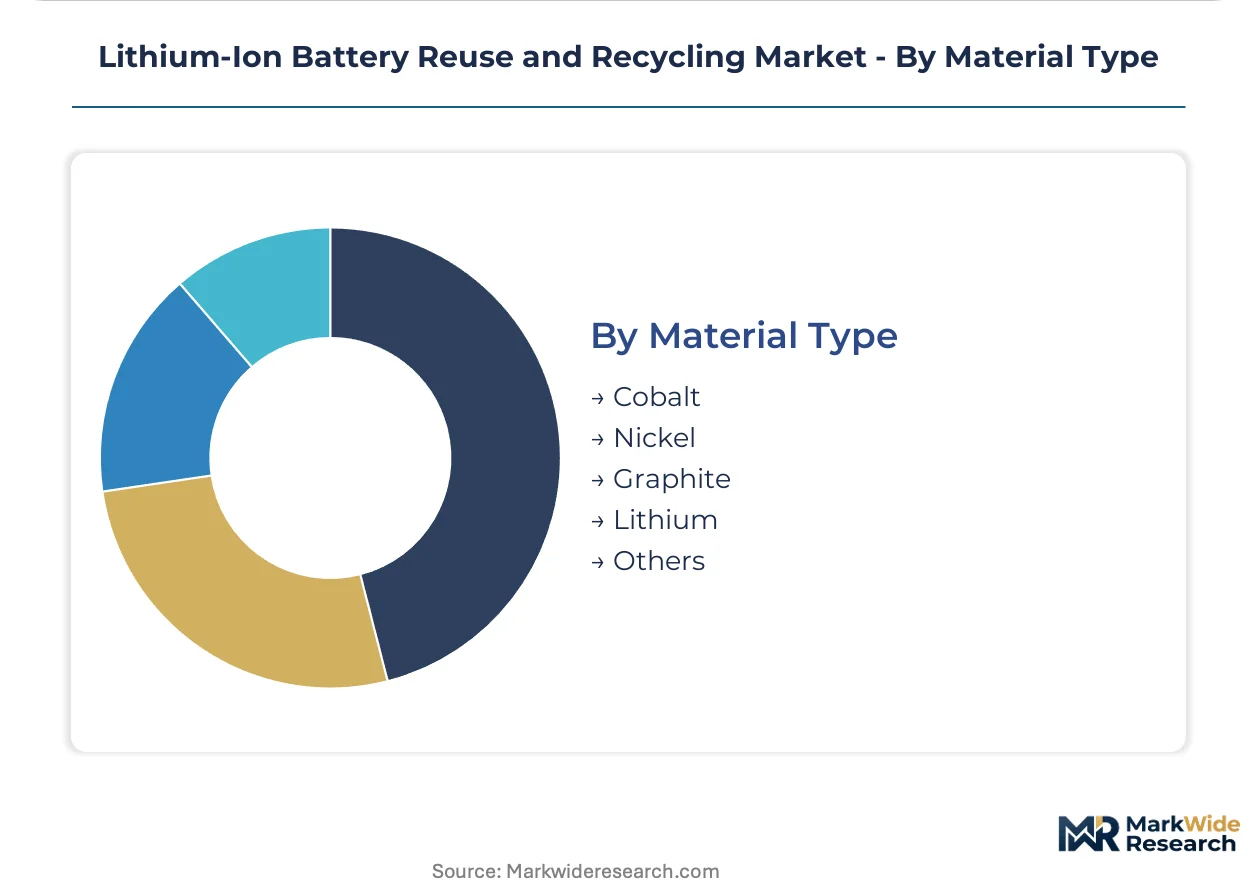
Material Type:
Price volatility and supply concentration create divergent investment priorities across the elemental recovery portfolio.
- Lithium:Hard rock and brine supply concentration in Australia and Chile makes domestic recovery strategically significant for battery manufacturing regions. Direct solvent extraction methods are expanding fastest among lithium-specific recovery technologies.
- Cobalt:Democratic Republic of Congo mining concentration exposes supply chains to ESG scrutiny and price volatility that amplifies recycling economics. REACH authorization requirements for cobalt compounds tighten documentation standards across European imports.
- Nickel:Stainless steel competition and cathode chemistry shifts toward high-nickel formulations are expanding recovery demand.
- Graphite:Anode material recovery remains technically challenging due to silicon contamination and structural degradation.
- Others:Manganese, copper, and electrolyte salts contribute secondary revenue streams.
Strategic priority favors Lithium; price volatility exposure favors Cobalt.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in recycled battery materials increasingly favor regions with integrated cathode manufacturing capacity over pure extraction economies. China maintains substantial export surpluses in processed lithium salts and precursor chemicals, while the United States and Germany run structural deficits that drive domestic recycling investment. Regulatory fragmentation across jurisdictions is accelerating regional supply chain localization.
China
Domestic EV fleet retirement generates the world's largest feedstock pipeline for hydrometallurgical processing. MEE discharge standards in Jiangsu and Guangdong provinces favor chemical leaching methods for new facility permitting. Brunp Recycling Technology operates integrated campuses in Changsha and Ningde that supply cathode precursors to adjacent gigafactories.
United States
IRA production credits for domestic battery material recovery are redirecting investment toward Nevada and South Carolina processing clusters. EPA RCRA hazardous waste classification governs interstate transport of spent cells, creating compliance costs that favor localized spoke-and-hub collection networks. Redwood Materials anchors western processing capacity through its Nevada refining complex.
Germany
EU Battery Regulation recycled content mandates are forcing Volkswagen and BMW to contract directly with Belgian and domestic hydrometallurgical facilities. KBA vehicle end-of-life directives coordinate OEM take-back obligations with certified dismantler networks. Industrial concentration in North Rhine-Westphalia hosts Umicore's integrated smelting-refining operations serving European cathode manufacturers.
South Korea
LG Energy Solution and Samsung SDI are piloting closed-loop regeneration contracts that bypass intermediate black mass trading. MFDS chemical safety regulations align with REACH documentation standards for nickel and cobalt compound imports. Metropolitan Seoul functions as the coordination hub for fleet operator partnerships with stationary storage integrators.
India
PLI scheme domestic cell manufacturing mandates are creating captive recycling demand as Reliance and Ola Electric scale production through 2030. BIS standards for recovered battery materials remain under development, creating qualification uncertainty for imported processing equipment. Gujarat and Tamil Nadu industrial corridors attract joint ventures between Korean battery makers and local metal processors.
Lithium-Ion Battery Reuse and Recycling Market Competitive Landscape
Concentration sits with integrated mining-to-materials conglomerates and specialized hydrometallurgical pure-plays rather than diversified waste management contractors. The competitive terrain splits between capital-intensive smelting operators with legacy infrastructure and technology-focused challengers deploying direct solvent extraction methods. Three archetypes dominate: vertically integrated battery manufacturers internalizing recovery capabilities, merchant processors serving spot and contract markets, and mining houses backward integrating into urban mining feedstocks. Capacity expansion and strategic offtake partnerships constitute the dominant competitive moves, with OEMs locking in decade-long supply agreements to secure EU Battery Regulation compliance.
Among North American pure-plays, Li-Cycle Corp and Redwood Materials occupy positions as technology-forward challengers to incumbent smelters. Belgian materials specialist Umicore anchors European integrated processing capacity through its Hoboken refining complex. Chinese operators Brunp Recycling Technology and GEM Co., Ltd exemplify the scale-driven archetype with industrial-campus models that co-locate collection, dismantling, and chemical refining.
| Leading Market Players |
|---|
| Umicore |
| Li-Cycle Corp |
| Redwood Materials |
| Glencore |
| Cirba Solutions |
| GEM Co., Ltd |
| RecycLiCo Battery Materials Inc. |
| Ecobat |
| Brunp Recycling Technology |
| Others |
Pricing and Supply Chain Analysis
Direct cathode regeneration substituting for black mass-to-precursor pipelines is redrawing supply geography toward OEM-integrated facilities in Germany and South Korea while collapsing intermediary trading margins. This substitution simultaneously concentrates pricing power within vertically integrated battery manufacturers and compresses spot-market premiums for merchant processors serving European automotive qualification queues.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock in battery-grade purity premiums through decade-spanning agreements. Price differentiation separates EU Battery Regulation-compliant certified streams from uncertified spot material, with volume scale and cathode chemistry specificity driving tier stratification. Cost compression in standard-grade black mass is intensifying because Chinese hydrometallurgical capacity expansion outpaces feedstock availability. Fleet operators and utility-scale storage developers exhibit highest price sensitivity, while captive OEM supply chains demonstrate lowest sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Strait of Malacca transit underwrites lithium concentrate flows from Australian hard-rock mines to Chinese processing campuses in Jiangsu and Guangdong provinces. Supply geography draws from Chilean brine operations, Indonesian nickel laterite corridors, and DRC cobalt concentrate shipments. Single-source vulnerability concentrates in Chinese cathode precursor manufacturing, where Brunp and GEM Co. control integrated refining-to-cell pipelines. Distribution runs through OEM-direct collection networks and certified dismantler partnerships rather than spot-market traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Second-life stationary storage service contracts expand faster than hardware asset sales, creating recurring-revenue layers that outpace one-time cell recovery transactions. Fleet operators and utility integrators now contract multi-year performance guarantees rather than purchasing degraded packs outright.
For Market Incumbents: Shield qualified supplier status by accelerating EU Battery Regulation certification investments before 2030 compliance deadlines tighten. Consolidate backward integration into collection infrastructure across California and Texas corridor networks to secure feedstock pipelines against emerging hydrometallurgical challengers. Direct regeneration technology from South Korean battery manufacturers threatens merchant processor margins by collapsing intermediate trading stages. For New Entrants and Emerging Players: Lead with modular spoke-and-hub collection networks targeting rural and secondary city gaps under EPA RCRA hazardous waste transport constraints. India PLI scheme incentives create the most penetrable white-space as domestic gigafactory buildouts generate captive recycling demand through 2030. Position through blockchain-integrated battery passport offerings that command premium pricing for verified recycled content across European OEM supply chains. For Investors and Strategic Acquirers: EU Battery Regulation recycled content mandates reshape the acquisition landscape toward hydrometallurgical pure-plays with existing OEM qualification timelines. Five-to-ten-year viability favors processors with demonstrated cathode precursor certification rather than mechanical separation or legacy pyrometallurgical assets. Target acquisition archetype: mid-cap facilities with proven lithium recovery rates and active validation queues at German or Belgian automotive manufacturers. Signal to monitor: closure rates of merchant black mass trading platforms as direct regeneration contracts proliferate.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Infrastructure | Secures feedstock pipelines against Chinese campus competition and EPA RCRA transport constraints. |
| EU Battery Regulation Certification Investment | Unlocks decade-long OEM offtake contracts with Volkswagen, BMW, and Belgian cathode manufacturers. |
| Direct Cathode Regeneration Technology Licensing | Bypasses black mass trading stages and captures value within closed-loop OEM partnerships. |
| Blockchain Battery Passport Integration | Enables premium pricing for verified recycled content across REACH-compliant European supply chains. |
| Joint Venture with Fleet Operator Networks | Locks in systematic cell retirement streams from California and Texas rideshare and delivery operators. |
Research Methodology
Operator-level perspectives from recycling facility managers, OEM procurement leads, hydrometallurgical process engineers, and stationary storage integrators anchored the qualitative base. Secondary validation drew from EPA RCRA guidance documents, EU Battery Regulation delegated acts, China MEE discharge standard filings, and SEC 10-K disclosures from listed battery material processors. Bottom-up feedstock pipeline modeling triangulated against top-down OEM end-of-life volume projections across the analysis window.
Sensitivity analysis tested forecast outputs against variable cathode chemistry adoption rates, EU recycled content mandate enforcement timelines, and Chinese export license restrictions. Segmentation dimensions modeled include product type, recycling method, end-user contract structure, and material recovery priority across the projection horizon. CAGRs derived from installed EV fleet degradation curves, cell retirement timing distributions, and hydrometallurgical capacity expansion schedules.
Forecasts assume regulatory continuity in EU Battery Regulation implementation, EPA RCRA classification stability, and China MEE discharge standard enforcement; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as cobalt price volatility, collection infrastructure buildout delays, and direct regeneration technology maturation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Waste Management
APAC E-Waste Management Market
E-Waste Management
Middle East and Africa Solar Panel Recycling Market
E-Waste Management
E-Scrap Recycling Market
E-Waste Management
Recycling Equipment and Machinery Market
E-Waste Management
Aluminum Cans Recycling Market
E-Waste Management
Europe E-Waste Management Market
E-Waste Management
Electronic Waste Recycling Market
E-Waste Management
Global E-Waste Recycling and Reuse Service Market
E-Waste Management
Solar Waste Recycling Market
E-Waste Management
Solar Trash Compactors Market
E-Waste Management
UAE E-Waste Management Market
E-Waste Management
Smart Waste Management Market
E-Waste Management
North America E-Waste Management Market
E-Waste Management
Solar Panel Recycling Market
E-Waste Management
Solar Panel Recycling Management Market
E-Waste Management
Electronic Scrap Recycling Market