
 North America Solid Waste Management Market | 2026-2036
North America Solid Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
North America Solid Waste Management Market Insights
Zero-landfill certification tiers is rotating toward the center of procurement criteria for Fortune 500 headquarters and retail chains across the continent. Waste Management Inc. leverages its national landfill network and recycling infrastructure to anchor long-term service contracts with major commercial accounts. Republic Services Inc. differentiates through vertical integration into recycling processing and renewable natural gas capture at its landfill sites. GFL Environmental Inc. competes aggressively on price in the Canadian and US Northeast municipal markets while building scale through route density.
Solid waste management encompasses the systematic collection, transportation, processing, recycling, and disposal of municipal, commercial, and industrial refuse, with modern facilities engineered to achieve diversion rates exceeding 50% through integrated material recovery and biological treatment systems. The primary commercial purpose is to minimize environmental externalities while recovering energy and secondary materials from waste streams that would otherwise require virgin resource extraction. Collection services occupy the largest revenue pool due to their recurring contracted nature and high barriers to entry from fleet and route optimization requirements. Waste-to-Energy is expanding fastest as landfill moratoria in the Northeast and West Coast push municipalities toward thermal and biological conversion alternatives. Recycling margins remain compressed by China's National Sword policy aftermath and volatile commodity pricing for paper and plastic bales.
The US EPA enforces landfill methane emissions standards under the Clean Air Act that compel operators to install gas capture systems or face penalties, while state regulators in California enforce SB 1383 mandates requiring 75% organic waste diversion by 2025 with enforcement mechanisms tightening compliance timelines. Canada's federal methane strategy and provincial extended producer responsibility frameworks in British Columbia and Ontario shape investment in curbside collection modernization and post-consumer packaging recovery infrastructure. Stakeholders must monitor pending US Department of Transportation hours-of-service rulemakings that could reshape collection labor economics, alongside evolving state-level per- and polyfluoroalkyl substances contamination liabilities that threaten landfill leachate treatment cost structures.
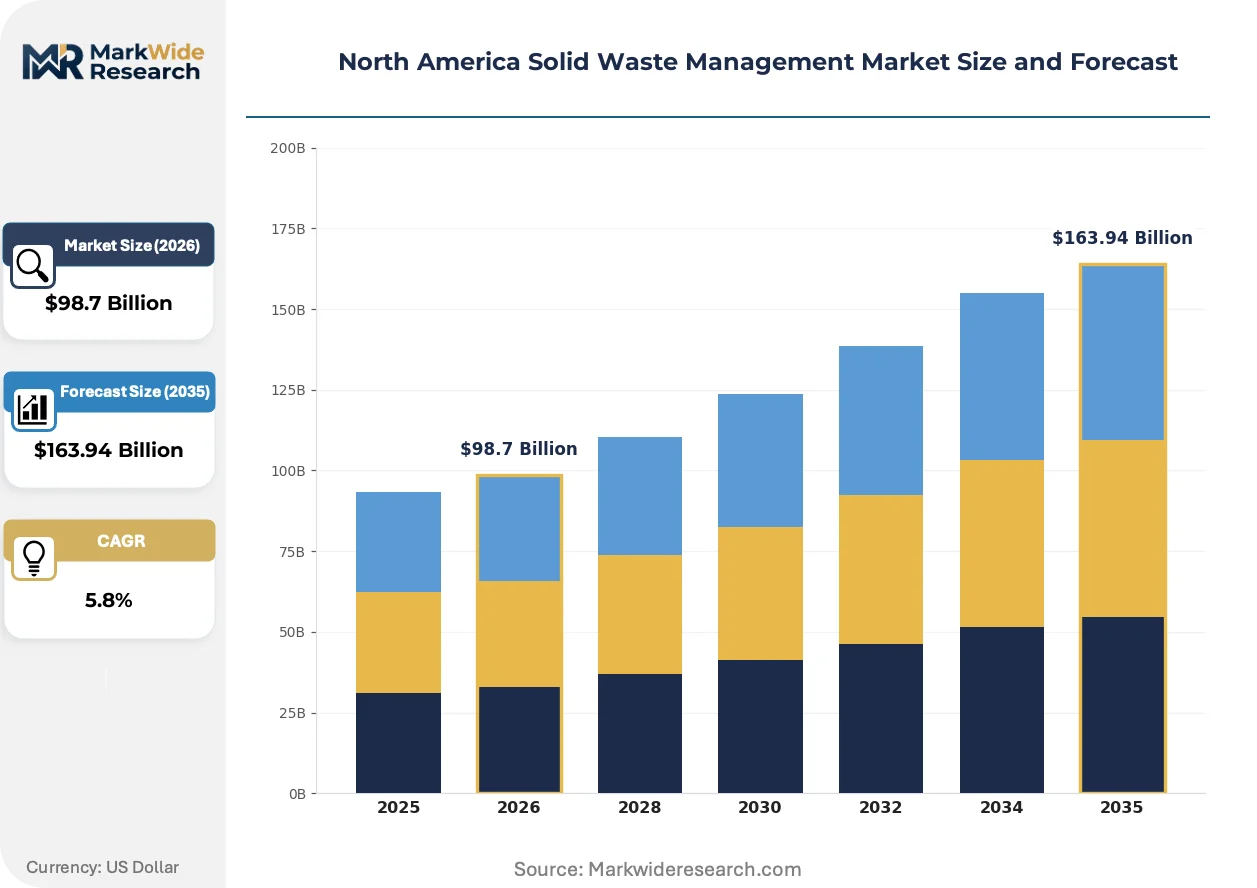
Market Dynamics
Landfill capacity constraints across the US Northeast corridor and California are forcing municipalities and commercial generators toward alternative treatment infrastructure, tightening the economics of traditional disposal and accelerating capital flows into waste-to-energy and anaerobic digestion facilities.
Growth Catalysts
- California SB 1383 mandates:The state's organic waste diversion requirements are compelling municipalities to expand curbside collection and build composting infrastructure, creating sustained equipment procurement cycles.
- Anaerobic digestion technology:Commercial food waste generators are deploying on-site or regional digester facilities to capture biogas and avoid landfill tipping fees, particularly in urban corridors with constrained disposal capacity.
- US Northeast landfill moratoria:State-level disposal restrictions in New York, New Jersey, and Massachusetts are redirecting waste flows toward out-of-region transfer stations and thermal treatment alternatives.
Market Restraints
- Recycled commodity price volatility:China's National Sword policy aftermath has destabilized markets for mixed paper and plastic bales, compressing MRF operating margins and discouraging collection expansion.
- Collection labor economics:Pending US Department of Transportation hours-of-service rulemakings threaten to reshape driver availability and route efficiency across the hauling sector.
- PFAS contamination liabilities:Evolving state-level per- and polyfluoroalkyl substances regulations threaten to escalate landfill leachate treatment costs and closure obligations.
Strategic Opportunities
- Canadian extended producer responsibility frameworks:British Columbia and Ontario's packaging recovery mandates are creating investment openings in post-consumer sorting infrastructure and producer-funded collection systems.
- Renewable natural gas capture:Landfill gas upgrading to pipeline-quality RNG represents an emerging revenue stream as utilities seek low-carbon fuel sources under state clean energy standards.
- Smart collection routing:IoT-enabled bin sensors and dynamic dispatch algorithms are reducing collection frequency and fuel consumption for municipal and commercial fleets.
Industry Challenges
- Route optimization expertise:The shortage of operations research specialists capable of deploying AI-driven collection logistics is constraining efficiency gains for mid-tier haulers.
- Organic waste permitting timelines:Anaerobic digestion and composting facilities face multi-year approval processes under state environmental quality regulations, delaying project returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Solid Waste Management Market |
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $163.94 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Landfilling, Recycling, Waste-to-Energy End User: Residential, Commercial, Industrial, Municipal Waste Type: Organic, Recyclable, Hazardous, E-Waste Technology: Incineration, Composting, Mechanical Biological Treatment, Anaerobic Digestion |
| Companies Covered | Waste Management Inc., Republic Services Inc., GFL Environmental Inc., Clean Harbors Inc., Waste Connections Inc., Casella Waste Systems Inc., Covanta Holding Corporation, Veolia North America, Stericycle Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Solid Waste Management Market Trends and Innovations
Digital tracking systems and biological treatment technologies are converging to transform how waste streams are characterized, routed, and valorized, shifting competitive advantage toward operators with real-time data capabilities and integrated processing assets.
Enzymatic plastic depolymerization is decomposing polyethylene terephthalate and polyester waste at commercial scale in Texas and California pilot facilities. Fast-moving consumer goods brands are contracting for offtake volumes to meet recycled content commitments. The technology is decomposing traditional mechanical recycling's dominance in food-grade resin markets by enabling infinite-loop chemical recycling without quality degradation.
The US EPA's landfill methane emissions standards under the Clean Air Act are tightening compliance thresholds for existing gas capture systems. Operators face capital decisions between upgrading collection infrastructure or accepting emissions penalties. Facilities in the Southeast and Mountain West, where older unlined landfills predominate, are experiencing the steepest retrofit cost escalations.
Zero-landfill certification tiers are displacing generic sustainability claims in Fortune 500 headquarters and retail chain procurement specifications. Third-party auditors are verifying diversion rates above 90% through thermal processing and material recovery. The specification shift is most visible in California and Washington state, where brand reputation risks and supply chain disclosure requirements concentrate buyer attention on verified waste outcomes.
North America Solid Waste Management Market Segmentation
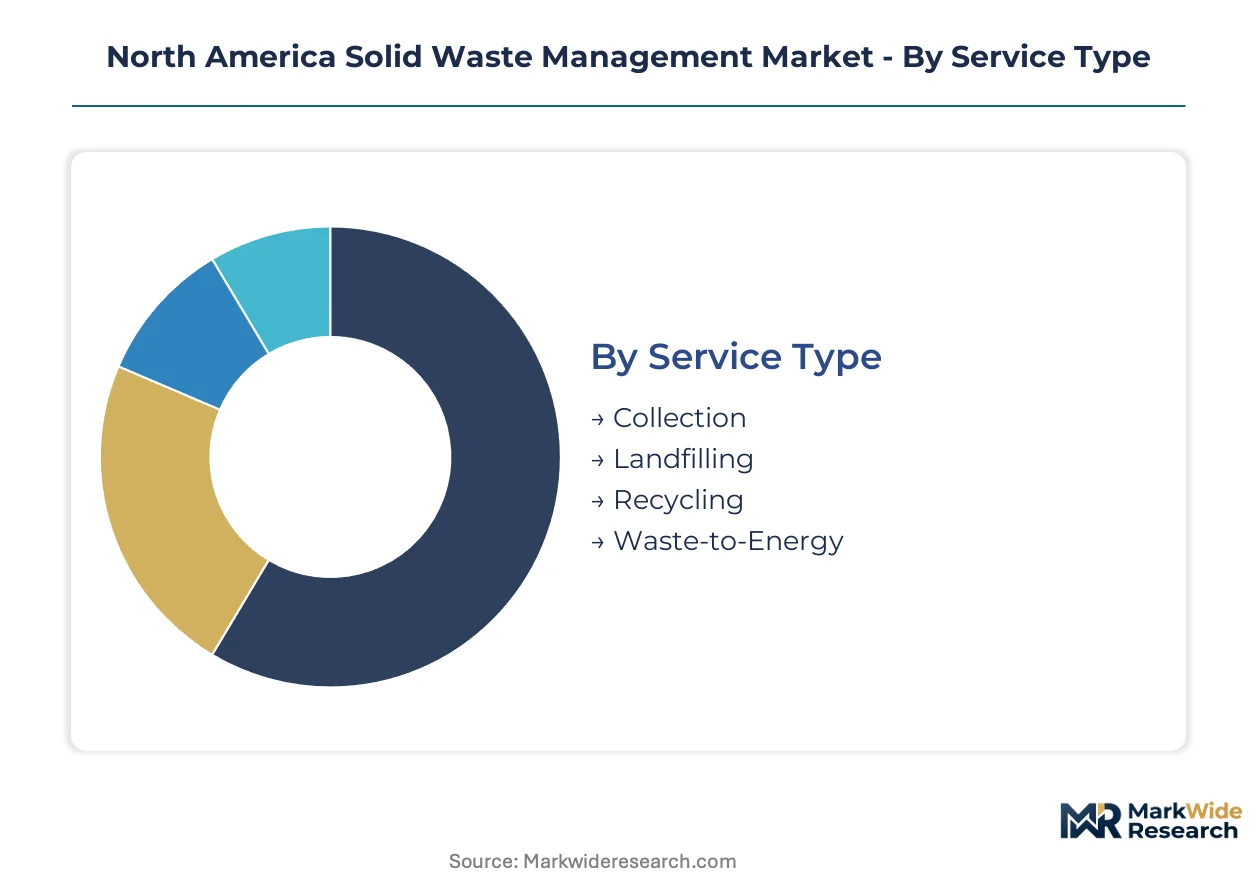
Service configurations in North American solid waste management diverge sharply between densely populated urban corridors and dispersed rural markets, with infrastructure investment clustering where landfill constraints and regulatory mandates overlap.
Service Type:
Collection services dominate domestic revenue pools across the United States and Canada, while waste-to-energy capacity expansion concentrates in export-oriented equipment supply to Asian and European markets.
- Collection:Curbside and commercial container services generate recurring contracted revenue through fleet-based route density. Municipal contracts in the US Northeast corridor and Canadian urban centers drive procurement cycles as cities expand organics collection to meet diversion mandates.
- Waste-to-Energy:Thermal conversion facilities process municipal solid waste into electricity and steam for industrial offtake. New York, New Jersey, and Massachusetts municipalities are redirecting waste flows toward these alternatives as landfill moratoria tighten disposal capacity.
- Recycling:Material recovery facilities sort commingled streams into commodity bales for paper and plastic markets.
- Landfilling:Engineered disposal cells with gas capture systems remain the default for non-recyclable refuse in regions with available capacity.
Collection holds the largest share; momentum sits with waste-to-energy.
End User:
Commercial generators pay premium tipping fees in capacity-constrained markets, while residential service economics depend on municipal tax-base density and route efficiency.
- Commercial:Retail chains, office complexes, and food service operations generate high-volume, concentrated waste streams. Fortune 500 headquarters procurement specifications now require zero-landfill certification tiers, redirecting service contracts toward integrated diversion providers.
- Industrial:Manufacturing facilities and distribution centers produce bulk waste requiring specialized handling. The US Southeast and Midwest industrial corridors drive demand for on-site compaction and regional transfer station networks.
- Residential:Single-family and multi-unit dwellings receive municipally contracted or franchised collection services.
- Municipal:Government-operated systems serve unincorporated areas and small communities outside major metropolitan zones.
Commercial holds the largest share; momentum sits with industrial.
Waste Type:
Organic waste processing infrastructure is expanding most quickly in states with enforceable diversion mandates, while recyclable commodity markets remain volatile following China's National Sword policy disruption.
- Organic:Food scraps, yard trimmings, and agricultural residues comprise the fastest-expanding collection category. California SB 1383 mandates are compelling municipalities to build composting and anaerobic digestion capacity, with biogas capture creating secondary revenue streams.
- Recyclable:Paper, plastic, glass, and metal bales exit material recovery facilities for commodity markets. Mixed paper and plastic pricing instability has compressed MRF operating margins and discouraged collection expansion in secondary markets.
- Hazardous:Industrial chemicals, medical waste, and contaminated materials require specialized disposal permits and manifest tracking.
- E-Waste:Discarded electronics containing recoverable metals and rare earth elements face state-level extended producer responsibility frameworks.
Recyclable holds the largest share; organic is expanding most quickly.
Technology:
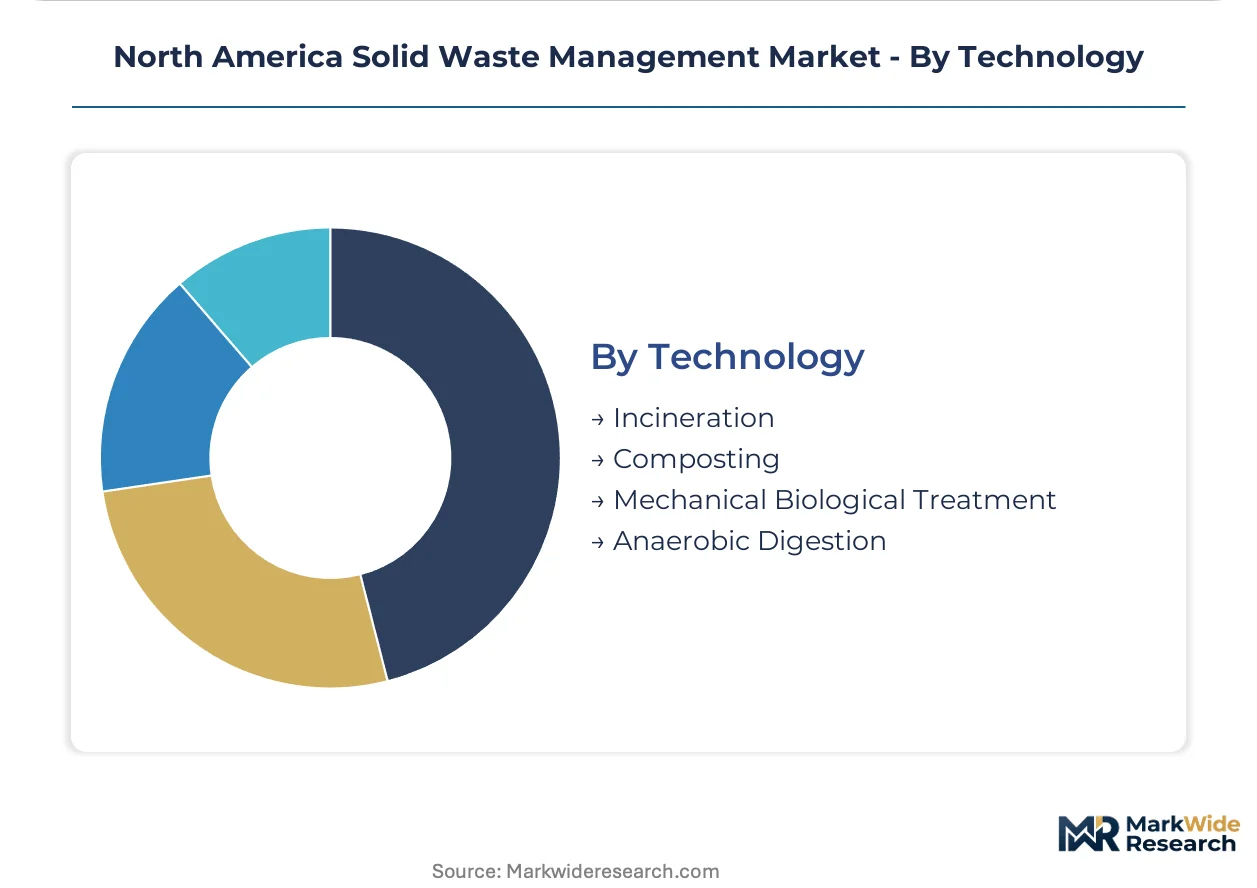
Incineration technology exports from North American engineering firms serve Asian waste crisis responses, while composting and anaerobic digestion deployment concentrates domestically in states with organic diversion mandates.
- Anaerobic Digestion:Biological treatment systems decompose organic waste in oxygen-free environments to capture methane-rich biogas. Commercial food waste generators in urban corridors with constrained landfill capacity are deploying regional digesters to avoid tipping fees and produce renewable natural gas.
- Composting:Aerobic decomposition of yard and food waste produces soil amendments for agricultural and landscaping markets. California, Oregon, and Washington state municipalities are expanding curbside organics collection to feed these facilities under compliance timelines.
- Incineration:Mass-burn and refuse-derived fuel combustion systems reduce waste volume while generating electricity.
- Mechanical Biological Treatment:Combined sorting and biological processing lines recover recyclables while stabilizing residual waste for landfill disposal.
Incineration holds the largest share; anaerobic digestion is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a structural surplus in waste-to-energy technology exports while importing specialized sorting equipment from European and Asian suppliers. Canada maintains near-autarky in collection services but relies on US landfill capacity for excess industrial waste flows. Cross-border waste movements concentrate in the Great Lakes and Pacific Northwest corridors where rail and barge infrastructure supports bulk transfer economics.
United States
Landfill capacity constraints in the Northeast corridor and California drive premium tipping fees and alternative infrastructure investment. The EPA enforces methane capture standards under the Clean Air Act that compel gas system upgrades at older facilities. New York, New Jersey, and Massachusetts municipalities redirect waste flows toward thermal treatment as state moratoria tighten disposal options.
Canada
Extended producer responsibility frameworks in British Columbia and Ontario reshape investment in post-consumer packaging recovery infrastructure. Health Canada coordinates with provincial regulators on methane reduction strategies aligned with federal climate commitments. The Greater Toronto and Vancouver areas concentrate procurement for curbside collection modernization and organic waste diversion systems.
Mexico
Industrial corridor growth in Nuevo León and the Bajío Region generates concentrated commercial waste streams requiring specialized handling. Mexico's federal environmental prosecutor enforces landfill closure timelines that accelerate informal sector formalization. Mexico City Metro's waste crisis drives contract opportunities for integrated collection and transfer station operators.
North America Solid Waste Management Market Competitive Landscape
Concentration sits with vertically integrated national operators controlling landfill networks and collection route density. The market structure tiers between scale-driven integrated providers, regional specialists with geographic focus, and technology-forward players emphasizing diversion and renewable energy capture. Competitive moves center on route density optimization through municipal contract aggregation and landfill gas upgrading infrastructure for renewable natural gas offtake agreements.
Among North American integrated providers, Waste Management Inc., Republic Services Inc., and GFL Environmental Inc. exemplify the scale-driven archetype that anchors long-term service contracts through captive disposal capacity. These operators occupy positions where national route networks and landfill ownership create defensive moats against price competition in capacity-constrained markets.
| Leading Market Players |
|---|
| Waste Management Inc. |
| Republic Services Inc. |
| GFL Environmental Inc. |
| Clean Harbors Inc. |
| Waste Connections Inc. |
| Casella Waste Systems Inc. |
| Covanta Holding Corporation |
| Veolia North America |
| Stericycle Inc. |
| Others |
Pricing and Supply Chain Analysis
RNG upgrading equipment substitution for legacy flare systems is simultaneously reshaping supply geography toward Gulf Coast fabrication hubs and pricing economics around carbon credit monetization.
Pricing Analysis
Industrial OEM buyers anchor long-term service contracts through landfill gas offtake agreements. Three-tier pricing structure across premium certified diversion, standard collection, and economy disposal tiers separates zero-landfill verified providers from commodity haulers. Cost compression in standard collection runs through driver availability constraints and fuel pass-through volatility. Municipal procurement offices exhibit highest price sensitivity due to tax-base limitations, while Fortune 500 sustainability officers accept premiums for verified diversion documentation.
Supply Chain Analysis
Inventory lead times for automated side-load collection trucks now stretch eighteen to twenty-four months as chassis shortages persist. Manufacturing concentrates in the United States, Canada, and Mexico under USMCA rules of origin. Specialized compaction equipment draws from German and Japanese component suppliers for hydraulic systems. Single-source vulnerability sits with domestic steel mills supplying roll-off container fabrication. Distribution runs through manufacturer-direct fleet sales and regional equipment dealer networks serving independent haulers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interoperability between smart bin sensors and municipal fleet dispatch platforms is creating platform-economics inflection, with data-sharing standards determining which operators capture route optimization premiums.
For Market Incumbents: Shield landfill network value through RNG upgrading infrastructure investment before state clean energy standards mature. Anchor defensive position by aggregating municipal contracts in the US Northeast corridor where capacity constraints tighten pricing power. Prioritize backward integration into anaerobic digestion technology licensing to offset organic waste diversion mandates threatening traditional disposal volumes. For New Entrants and Emerging Players: Anchor in Canadian extended producer responsibility frameworks where producer-funded collection systems reduce capital intensity for post-consumer packaging recovery. Target mid-tier industrial generators in Mexico's Bajío Region underserved by integrated national operators. Pursue equipment-leasing partnerships with European sorting technology suppliers to bypass domestic fabrication bottlenecks. For Investors and Strategic Acquirers: Capital is best deployed toward regional specialists with captive landfill positions in capacity-constrained markets and established RNG offtake relationships. Long-term viability across the analysis window favors operators with integrated processing assets rather than pure-play collection scale. Monitor California SB 1383 enforcement timelines as the signal indicating whether organic diversion infrastructure investment accelerates or stalls.| Strategic Initiative | Industry Significance |
|---|---|
| RNG Infrastructure Buildout | Landfill gas upgrading captures EPA methane compliance value and utility clean energy procurement. |
| Curbside Organics Expansion | Municipal contract aggregation in California and Oregon locks in SB 1383-driven equipment procurement cycles. |
| Smart Fleet Integration | IoT-enabled routing reduces fuel consumption and driver hours-of-service exposure under pending DOT rules. |
| Extended Producer Responsibility Partnerships | British Columbia and Ontario frameworks shift collection funding from municipalities to packaging brands. |
| Anaerobic Digestion Technology Licensing | Commercial food waste generators seek on-site biogas capture to avoid Northeast corridor tipping fees. |
Research Methodology
The analysis maps collection services, waste-to-energy processing, recycling infrastructure, and landfill operations, each validated through interviews with municipal procurement officers, fleet operations managers, landfill gas project developers, and anaerobic digestion facility engineers. Secondary sources include EPA enforcement data, state environmental agency permitting records, FERC interconnection filings for RNG projects, and municipal bond prospectuses for infrastructure financing. Bottom-up service revenue estimates triangulate against top-down waste generation forecasts from census and industrial activity data.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporates service type, end-user category, waste stream composition, and processing technology. CAGRs derive from facility capacity expansion announcements, contract renewal pricing trends, and regulatory compliance timeline impacts. Forecast inputs include landfill capacity utilization rates and RNG offtake agreement pricing dynamics.
Decision-makers should treat outputs as directional under assumptions of continued EPA methane enforcement and state organic diversion mandate adherence; material deviation in regulatory intensity or commodity pricing would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Global Pharmaceutical Waste Management Market
Waste Management & Pollution Control
Reusable Sediment Control Wattles Market
Waste Management & Pollution Control
Medical Waste Management Equipment Market
Waste Management & Pollution Control
Global Waste Oil Market
Waste Management & Pollution Control
India Commercial Food Waste Decomposer Market
Waste Management & Pollution Control
APAC Bio-Medical Waste Management Market
Waste Management & Pollution Control
PET Recycling Market
Waste Management & Pollution Control
Retail Food Waste-to-Biogas Logistics and Treatment Networks in Europe Market
Waste Management & Pollution Control
Recycled Waste Management Market
Waste Management & Pollution Control
Landfill Compactor Market
Waste Management & Pollution Control
Industrial Waste Management Market
Waste Management & Pollution Control
North America Municipal Solid Waste Management Market
Waste Management & Pollution Control
Europe Medical Waste Management Market
Waste Management & Pollution Control
Paper Recycling Market
Waste Management & Pollution Control
North America Waste Recycling Services Market
Waste Management & Pollution Control
Scrap Metal Recycling Market