
 United States Trash Bags Market | 2026-2036
United States Trash Bags Market Size, Share, and Industry Trends Forecast 2026-2036
United States Trash Bags Market Analytics
Subscription-based restocking services for commercial facilities is expanding how trash bags move through distribution channels. Reynolds Consumer Products leverages its retail shelf presence to sustain volume leadership in household channels. Novolex anchors industrial and food-service supply through its integrated film extrusion and conversion network. Berry Global differentiates via specialty films and odor-control technologies for premium residential lines.
United States trash bags are polyethylene or biodegradable film enclosures manufactured through blown-film extrusion, typically ranging from 0.5 to 3.0 mil in gauge, designed for containment, transport, and disposal of solid waste across residential, commercial, and institutional settings. Drawstring closures command premium positioning in retail residential segments while flat-seal formats dominate high-volume commercial and municipal contracting due to lower unit economics. Biodegradable and recycled material categories are gaining shelf space as procurement specifications tighten, though HDPE and LDPE still carry the bulk of tonnage throughput.
FDA food-contact regulations, EPA recycled-content guidelines under the National Recycling Strategy, and state-level extended producer responsibility frameworks in California, Oregon, and Maine shape material compliance burdens and reformulation timelines. Municipal procurement standards increasingly require post-consumer recycled content thresholds, forcing resin sourcing adjustments across the value chain. Stakeholders must monitor state legislative calendars and resin price spreads to time capacity commitments and specification upgrades.
Market Dynamics
The United States trash bags market is experiencing structural compression from EPA recycled-content mandates under the National Recycling Strategy, which are forcing resin reformulation across the value chain while state-level plastic restrictions in California, Oregon, and Maine create compliance fragmentation.
Growth Catalysts
- Municipal procurement mandates:Cities across Texas, California, and Florida are scaling high-capacity liner purchases for expanded waste collection programs, driving volume concentration in Sun Belt metros.
- Biodegradable film advancement:PLA and PBAT blends are penetrating premium residential segments as composting infrastructure spreads in the Northeast and Pacific Northwest.
- Commercial construction acceleration:Florida and Texas building permits are generating institutional waste streams that require heavy-gauge contractors' bags above standard retail specifications.
Market Restraints
- Resin price volatility:Ethylene feedstock costs tied to natural gas liquids pricing create margin compression for blown-film extruders serving price-locked municipal contracts.
- Gulf Coast supply concentration:Over 60% of domestic polyethylene resin production clusters along Texas and Louisiana chemical corridors, exposing converters to hurricane disruption risk.
- Mechanical recycling limitations:Post-consumer film contamination rates exceed 15% in curbside streams, limiting viable feedstock for EPA-mandated recycled content targets.
Strategic Opportunities
- Subscription restocking channels:Janitorial supply distributors are piloting automated replenishment for multi-site commercial accounts, bypassing traditional wholesale purchasing.
- Odor-control film premiums:Activated carbon and scented additive technologies command 40-60% price premiums in pet care and food service segments.
- State EPR frameworks:California's extended producer responsibility legislation creates first-mover advantage for converters with verified closed-loop sourcing systems.
Industry Challenges
- Composting certification timelines:BPI and CMA certification processes for biodegradable films require 18-24 month validation cycles, delaying product launches.
- Blown-film technical talent scarcity:Experienced die technicians and extrusion operators are aging out of the workforce faster than vocational programs replenish supply.
- Legacy equipment retrofit costs:Converting lines built for virgin HDPE require capital-intensive screw and die modifications to process high-percentage recycled feedstocks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Trash Bags Market |
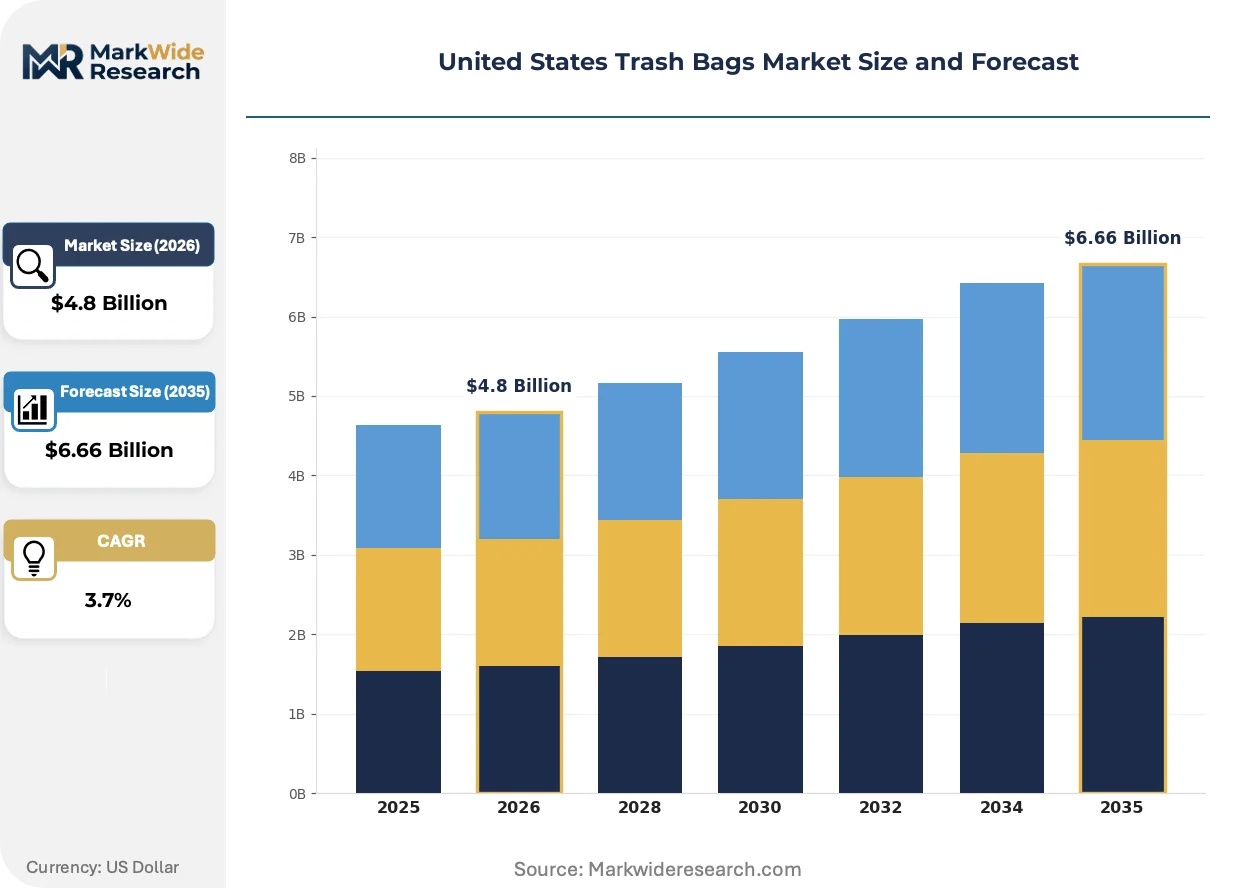
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drawstring, Flat, Gladiator, Specialty Material: HDPE, LDPE, Biodegradable, Recycled Size: Small, Medium, Large, Extra Large End User: Residential, Commercial, Industrial, Municipal |
| Companies Covered | Reynolds Consumer Products, The Clorox Company, Novolex, Inteplast Group, Berry Global, Poly-America, Heritage Bag, Riverside Paper, International Plastics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Trash Bags Market Evolving Landscape
Material science advances and procurement digitization are fragmenting traditional channel structures. Three developments are compressing lead times and reshaping competitive advantage.
Biodegradable polymer formulations incorporating PLA-PBAT blends are decentralizing manufacturing location decisions for converters. Food service operators in the Pacific Northwest are specifying compostable liners at 3x the rate of national averages. This technology is decentralizing production away from Gulf Coast resin corridors toward regional compounding facilities serving coastal regulatory environments.
EPA's National Recycling Strategy recycled-content guidelines are forcing specification rewrites across municipal procurement offices. Industrial buyers must now document post-consumer resin percentages in contract bids, compressing supplier qualification pools. California's CalRecycle enforcement arm is most aggressively auditing compliance, pushing converters toward third-party chain-of-custody certification.
Facility managers are consolidating vendor relationships through integrated supply contracts that bundle liners with cleaning chemicals and disposable goods. Amazon Business and Staples Advantage are capturing mid-market commercial accounts that previously purchased through local distributors. This consolidation is most visible in healthcare and education verticals where procurement departments face headcount pressure.
United States Trash Bags Market Segmentation
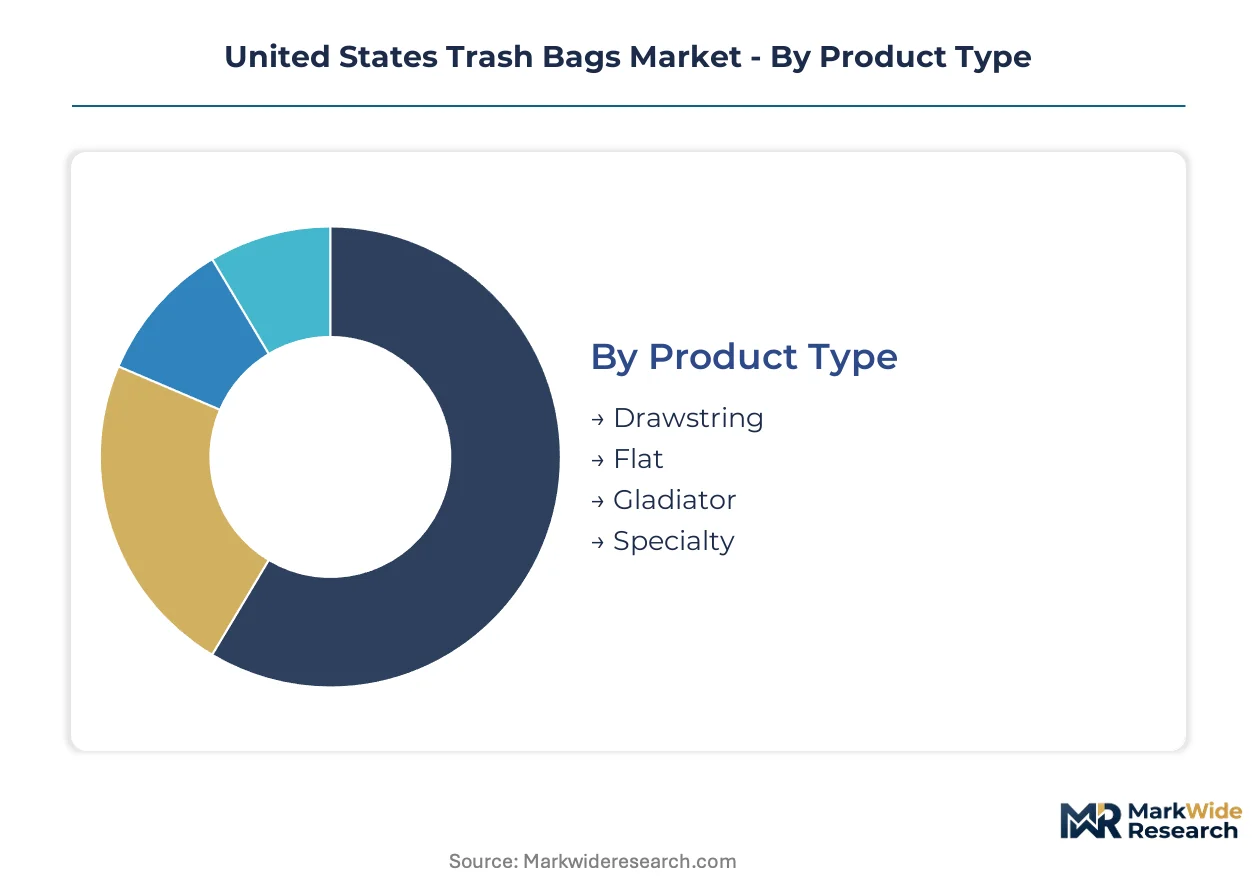
Trash bag segmentation in the United States reflects divergent performance requirements across waste streams. Material specifications and closure mechanisms determine compliance eligibility for municipal contracts, while size and end-use categories map directly to distribution channel strategies.
Product Type:
Closure technology defines the cost-performance tradeoff that separates retail premium positioning from high-volume commercial procurement.
- Drawstring:Integrated tie-band construction using LDPE or LLDPE substrates delivers one-hand closure for residential kitchens. Demand concentrates in suburban households across Texas and California where premium positioning supports 40-60% price premiums over flat-seal alternatives. Consumer preference for convenience drives shelf space allocation at mass retailers.
- Flat:Simple heat-sealed bottom construction with open top minimizes unit economics for institutional buyers. Municipalities in Florida and Sun Belt metros specify flat liners for curbside collection programs where labor costs favor rapid bagging over ergonomic features. Volume contracting locks in multi-year supply relationships with converters.
- Gladiator:Reinforced star-sealed bottom and textured sidewalls engineered for contractor debris and demolition waste.
- Specialty:Odor-control films with activated carbon layers or scented additives targeting pet care, healthcare, and food service applications.
Flat leads on scale; Specialty leads on momentum.
Material:
Resin selection determines regulatory compliance pathways and sourcing geography for blown-film extruders.
- HDPE:High-density polyethylene delivers stiffness and puncture resistance at thin gauges for lightweight residential liners. Gulf Coast resin corridors supply virgin feedstock, though EPA recycled-content mandates are forcing reformulation timelines. HDPE dominates tonnage throughput but faces margin compression from mechanical recycling contamination rates exceeding 15%.
- LDPE:Linear low-density formulations provide tear resistance and flexibility for heavy-gauge commercial applications. Industrial waste streams in Florida construction markets specify LDPE contractors' bags above standard retail gauges. Resin price volatility tied to natural gas liquids pricing creates contract renegotiation pressure.
- Biodegradable:PLA-PBAT blends requiring BPI or CMA certification for composting infrastructure compatibility.
- Recycled:Post-consumer resin content mandated by California CalRecycle enforcement and municipal procurement standards.
HDPE commands volume share; Biodegradable climbs the fastest on regulatory tailwinds.
Size:
Capacity specifications align with waste generation patterns and collection infrastructure dimensions.
- Small:4-8 gallon capacity for bathroom and office wastebaskets, prevalent in commercial facilities with distributed bin placement.
- Medium:13-gallon kitchen standard capturing the largest revenue pool in residential channels through retail and subscription restocking services.
- Large:30-33 gallon construction and yard waste applications concentrated in Texas and Florida building permit corridors.
- Extra Large:55+ gallon drum liners for industrial and municipal roll-off containers requiring heavy-gauge specifications.
Medium dominates household purchasing; Extra Large expands most quickly on commercial construction acceleration.
End User:
Procurement authority structures fragment pricing power and channel access across the value chain.
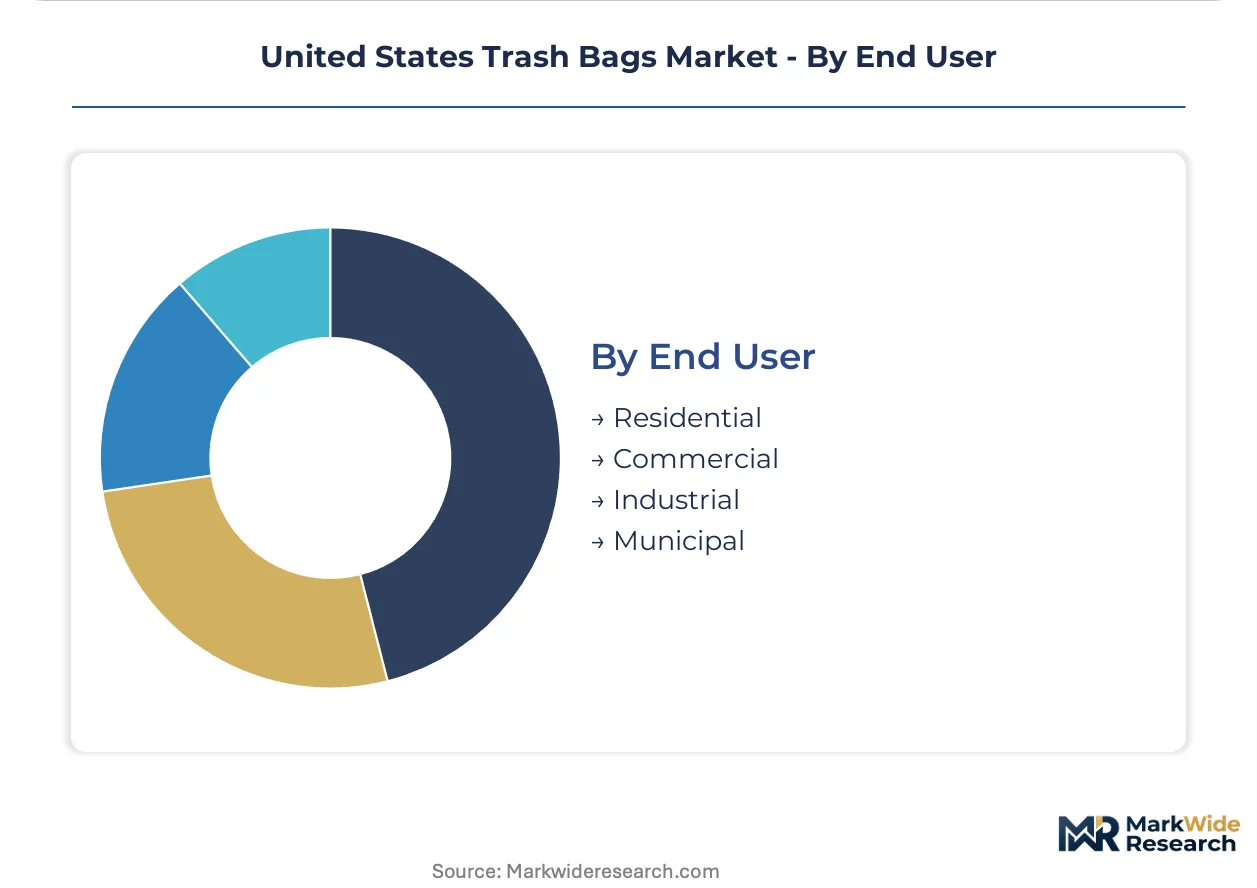
- Residential:Individual household purchasing through retail and e-commerce channels, with drawstring premiums concentrated in suburban markets.
- Commercial:Facility managers consolidating vendor relationships through integrated supply contracts bundling liners with janitorial supplies.
- Industrial:Manufacturing and construction waste streams specifying heavy-gauge gladiator formats above standard commercial specifications.
- Municipal:City procurement offices mandating post-consumer recycled content thresholds under EPA National Recycling Strategy guidelines.
Residential generates transaction volume; Municipal procurement is gaining share fastest on extended producer responsibility frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas generates heavier contractor bag demand than California's municipal procurement volumes, yet both states anchor contrasting regulatory environments that reshape converter strategies across the Sun Belt.
Texas
Houston and Dallas construction corridors drive specification for 3.0 mil gladiator formats in demolition waste streams. The Texas Commission on Environmental Quality maintains lighter recycled-content mandates than coastal states, allowing converters to prioritize virgin resin throughput. Gulf Coast petrochemical clusters near Beaumont and Port Arthur supply captive polyethylene feedstock to regional extrusion networks.
California
CalRecycle enforcement of SB 54 mandates 30% post-consumer recycled content thresholds for state procurement contracts. Los Angeles and San Francisco metro areas specify compostable liners for food waste diversion programs at 3x national adoption rates. Sacramento regulatory pressure pushes converters toward third-party chain-of-custody certification for municipal eligibility.
Florida
Miami-Dade and Orlando building permits accelerate institutional waste generation requiring heavy-gauge commercial specifications. The Florida Department of Environmental Protection defers to municipal recycling goals without state-level EPR frameworks. Tampa Bay distribution hubs serve Caribbean export markets for hospitality-sector liner procurement.
Illinois
Chicago metropolitan procurement offices consolidate multi-site janitorial contracts bundling liners with disposable goods. Cook County waste districts pilot automated collection infrastructure favoring standardized flat-seal formats. Midwest resin distribution networks from Illinois warehousing reduce freight exposure for converters serving Great Lakes manufacturing.
New York
New York City Department of Sanitation mandates clear bag specifications for recycling stream contamination reduction. Albany legislative pressure aligns with neighboring New England composting infrastructure expansion. Buffalo-Niagara extrusion facilities process recycled feedstock for Ontario cross-border supply contracts.
United States Trash Bags Market Competitive Landscape
Top-tier vendors anchor retail shelf presence and municipal contracting relationships, while mid-tier converters compete on regional logistics and specialty film formulations. The vendor base stratifies across integrated resin-to-film producers, independent blown-film specialists, and private-label assemblers. Three archetypes dominate: resin-integrated manufacturers controlling upstream feedstock, technology-differentiated specialists commanding odor-control premiums, and distributor-captive converters serving janitorial supply houses. Competitive moves concentrate on automated extrusion line retrofits for recycled-content compliance and direct e-commerce channel development bypassing traditional wholesale tiers.
Within the resin-integrated tier, Reynolds Consumer Products and Novolex occupy positions reflecting scale-driven throughput advantages. Berry Global exemplifies technology-differentiated positioning through specialty film development. The Clorox Company represents consumer-brand leverage translating household recognition into recurring purchase patterns.
| Leading Market Players |
|---|
| Reynolds Consumer Products |
| The Clorox Company |
| Novolex |
| Inteplast Group |
| Berry Global |
| Poly-America |
| Heritage Bag |
| Riverside Paper |
| International Plastics |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between BPI-verified compostable films and commodity virgin polyethylene creates parallel supply chains serving distinct buyer archetypes. EPA recycled-content mandates and CalRecycle enforcement compress pricing power for non-compliant converters while premium biodegradables command sustained markups through certified channel access.
Pricing Analysis
Capacity additions in Texas and Louisiana chemical corridors are reshaping price floors for virgin HDPE and LDPE feedstocks. Three-tier pricing structure across premium odor-control, standard commercial, and economy municipal tiers reflects certification burden and resin grade differentiation. Cost compression in flat-seal municipal contracts intensifies because multi-year offtake agreements lock converters below spot resin movements. Municipal procurement offices exhibit highest price sensitivity; food-service operators specifying compostable liners show lowest.
Supply Chain Analysis
Experienced die technicians and extrusion operators aging out of Beaumont and Port Arthur manufacturing clusters constrain regional throughput expansion. Gulf Coast petrochemical corridors in Texas and Louisiana supply captive polyethylene feedstock, while Midwest compounding facilities process PLA-PBAT blends for coastal regulatory markets. Raw material sourcing draws from natural gas liquids, post-consumer baled film, and imported biodegradable resin pellets. Hurricane disruption risk concentrates single-source vulnerability along Louisiana-Texas chemical corridors. Distribution runs through janitorial supply distributors, Amazon Business, and direct municipal contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
United States trash bags constitute a late-cycle quality story as procurement specifications tighten toward premium biodegradable and odor-control formats. Municipal food waste diversion programs in California and the Pacific Northwest accelerate demand-shift toward certified compostable specifications.
For Market Incumbents: Deepen backward integration into Gulf Coast resin production to secure feedstock cost stability against natural gas liquids volatility. Accelerate BPI and CMA certification timelines for PLA-PBAT product lines before California SB 54 enforcement expands to additional states. Channel control through janitorial supply distributor relationships defends against Amazon Business consolidation in mid-market commercial accounts.
For New Entrants and Emerging Players: Regional composting facilities in the Northeast represent an underserved buyer archetype requiring localized supply partnerships and shorter logistics loops. Specialty odor-control films for pet care and healthcare verticals offer white-space penetration at 40-60% price premiums with lower certification barriers than biodegradables. Direct e-commerce subscription models bypass entrenched wholesale distributor relationships.
For Investors and Strategic Acquirers: Consolidation pressure builds where converters lack verified closed-loop sourcing systems for post-consumer resin documentation. Long-term viability favors technology-differentiated specialists with proprietary film formulations over commodity extrusion capacity. Acquisition target archetype: mid-tier blown-film operators with CalRecycle-compliant sourcing infrastructure and healthcare vertical penetration. Signal to watch: California EPR framework expansion into additional product categories as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Content Compliance Investment | EPA National Recycling Strategy mandates reshape municipal procurement eligibility across Texas, California, and Florida. |
| Biodegradable Film Certification | BPI and CMA validation cycles unlock premium positioning in Pacific Northwest composting infrastructure markets. |
| Odor-Control Technology Development | Activated carbon and scented additive formulations command sustained price premiums in pet care segments. |
| Subscription Channel Expansion | Automated replenishment models bypass traditional janitorial supply distributor tiers in multi-site commercial accounts. |
| Regional Compounding Facility Siting | PLA-PBAT blend production near coastal regulatory markets reduces freight exposure and certification timeline risk. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged blown-film extrusion plant managers, municipal procurement officers, janitorial supply distributor category buyers, and CalRecycle compliance auditors. Secondary validation drew from EPA National Recycling Strategy documentation, CalRecycle enforcement bulletins, customs polyethylene trade data, and SEC filings from resin-integrated manufacturers. Bottom-up volume modeling triangulated against top-down macroeconomic waste generation indicators.
Segment-weighting approaches distributed value and volume across material type, closure mechanism, end-use category, and regional regulatory cluster. Modeled dimensions included HDPE/LDPE/biodegradable/recycled material tiers, drawstring/flat/gladiator/specialty product formats, and residential/commercial/industrial/municipal buyer archetypes. CAGRs derived from historical trajectory analysis adjusted for policy inflection points and construction permit correlations. Forecast inputs incorporated resin price spread volatility and mechanical recycling contamination rate assumptions.
Underlying measurement precision varies by segment; municipal procurement volumes carry tighter precision than emerging biodegradable categories where certification timelines create supply uncertainty. Forecasts reflect documented assumptions regarding EPA enforcement intensity and state EPR adoption velocity. Material deviation in resin price spreads, hurricane disruption frequency, or composting infrastructure buildout rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Sharp Waste Disposal Market
Waste Management & Pollution Control
Municipal Solid Waste Incineration Market
Waste Management & Pollution Control
Medical Waste Management Equipment Market
Waste Management & Pollution Control
South American Waste Management Market
Waste Management & Pollution Control
Metal Recycling Equipment Market
Waste Management & Pollution Control
Africa Waste Management Market
Waste Management & Pollution Control
Medical Waste Management System Market
Waste Management & Pollution Control
Biomedical Waste Management Market
Waste Management & Pollution Control
India E-Waste Management Market
Waste Management & Pollution Control
Global Waste Management Equipment Market
Waste Management & Pollution Control
North America Waste Management Market
Waste Management & Pollution Control
UAE Biomedical Waste Management Market
Waste Management & Pollution Control
Construction Waste Management Market
Waste Management & Pollution Control
Radioactive Waste Management System Market
Waste Management & Pollution Control
Sludge Management Equipment Market
Waste Management & Pollution Control
North America Municipal Solid Waste Management Market