
 India Waste-To-Energy Market | 2026-2036
India Waste-To-Energy Market Size, Share, and Industry Trends Forecast 2026-2036
India Waste-To-Energy Market Foresight
The Solid Waste Management Rules 2016 is consolidating project economics around tipping fees and power purchase agreements for new entrants. Abellon Clean Energy Ltd leverages its biomass gasification expertise to anchor captive power supply for textile clusters in Gujarat. JITF Urban Infrastructure Limited sustains competitive positioning through integrated engineering-procurement-construction contracts across northern landfill sites. Ramky Enviro Engineers Ltd dominates hazardous-industrial-waste-to-energy streams through its Telangana-based treatment infrastructure.
Waste-to-energy denotes thermochemical and biochemical conversion processes that transform combustible refuse into electricity, heat, or synthetic fuels, typically operating at combustion temperatures between 850°C and 1,200°C for incineration pathways to ensure complete dioxin destruction. The primary purpose centers on simultaneous waste volume reduction and baseload renewable power generation for grid-connected utilities and captive industrial consumers. Incineration technology occupies the largest installed base due to proven operational track records with mixed municipal solid waste streams, though anaerobic digestion segments attract accelerated capital flows where organic fraction separation precedes energy recovery. Gasification deployments remain concentrated in private enterprise off-take arrangements where syngas quality supports combined-cycle efficiency targets.
The Central Electricity Regulatory Commission mandates preferential tariffs for waste-to-energy plants under renewable purchase obligations, while the Central Pollution Control Board enforces stack emission standards that shape flue gas treatment capital requirements. State-level nodal agencies in Maharashtra and Gujarat administer viability gap funding that determines project financial closure timelines. Stakeholders must monitor tariff renegotiation risks and feedstock supply security as landfill mining competition intensifies for legacy waste streams.
Market Dynamics
The Central Electricity Regulatory Commission's preferential tariff mandates under renewable purchase obligations are compressing project payback periods and redirecting capital toward incineration and anaerobic digestion technologies that qualify for grid-connected offtake.
Growth Catalysts
- Landfill Crisis in Tier-1 Cities:Municipal corporations in Mumbai, Delhi, and Chennai face capacity exhaustion that accelerates waste-to-energy procurement timelines and long-term tipping fee contracts.
- Solid Waste Management Rules 2016:This framework mandates waste processing over dumping, creating statutory demand for thermal and biochemical conversion infrastructure with enforceable compliance deadlines.
- Industrial Cluster Captive Demand:Textile and chemical processing zones in Gujarat and Tamil Nadu seek baseload renewable power to offset grid dependency and meet corporate sustainability commitments.
Market Restraints
- Feedstock Supply Volatility:Mixed municipal solid waste streams exhibit calorific value fluctuations that destabilize combustion efficiency and require costly preprocessing equipment.
- Emissions Compliance Capital Burden:Central Pollution Control Board stack standards for dioxins and heavy metals necessitate multi-stage flue gas treatment systems that inflate project capex by 25-35 percent.
- Landfill Mining Competition:Legacy waste recovery operators compete for the same feedstock pools, fragmenting supply security for greenfield energy recovery facilities.
Strategic Opportunities
- Biomethane Grid Injection:Upgraded biogas from anaerobic digestion qualifies for compressed natural gas blending mandates in Maharashtra and Gujarat transport sectors.
- Plasma Gasification Convergence:Syngas cleanup technologies combined with solid oxide fuel cells enable higher electrical efficiency for hazardous industrial waste streams in Telangana.
- Viability Gap Funding Expansion:State nodal agencies in Tamil Nadu and Karnataka are extending capital subsidies to projects below 10 MW capacity previously excluded from central schemes.
Industry Challenges
- Operations and Maintenance Skill Deficit:Combustion chamber refractory management and continuous emissions monitoring system calibration require specialized technicians scarce in secondary cities.
- Power Purchase Agreement Renegotiation Risk:Distribution utilities seek tariff reductions post-commissioning, threatening debt service coverage ratios for projects with limited merchant power alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Waste-To-Energy Market |
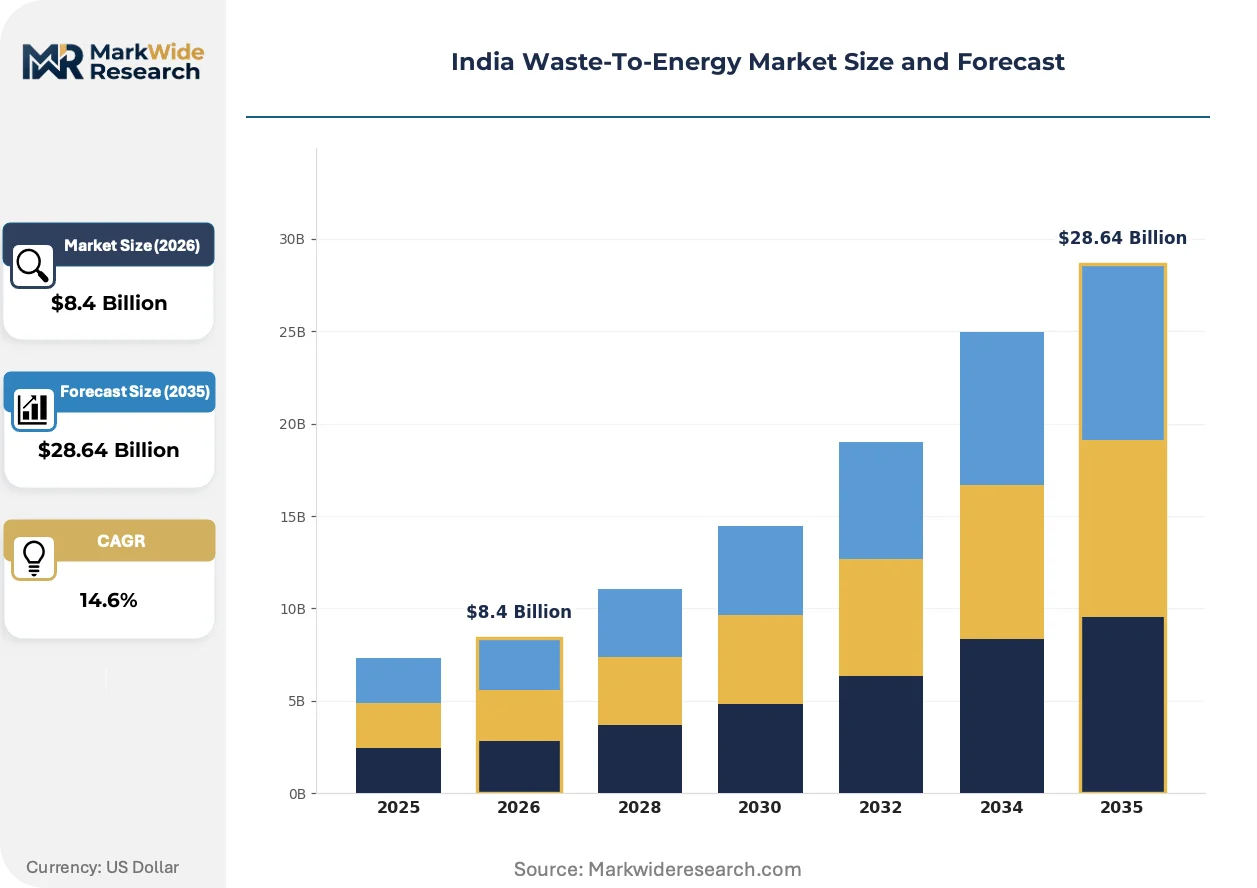
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $28.64 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: Incineration, Gasification, Anaerobic Digestion, Plasma Arc Feedstock Type: Municipal Solid Waste, Agricultural Residues, Industrial Waste, Biomass End User: Energy Utilities, Cement Industries, Government Projects, Private Enterprises Deployment Mode: Onsite, Offsite, Hybrid, Centralized |
| Companies Covered | Suez Group, Abellon Clean Energy Ltd, Il&fs Environnemental Infrastructure And Services Limited, Ecogreen Energy Pvt. Ltd, A2Z Group, JITF Urban Infrastructure Limited, Ramky Enviro Engineers Ltd, Hitachi Zosen Inova, Veolia India Private Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Waste-To-Energy Market Shifts & Advancements
Thermochemical conversion technologies are advancing beyond conventional incineration toward higher-efficiency pathways, while regulatory instruments tighten emissions accountability and procurement models evolve toward service-based contracting.
Plasma arc gasification is expanding into hazardous and medical waste treatment applications where syngas quality supports combined-cycle power generation. Industrial estates in Gujarat and Telangana are piloting modular 5-15 MW units to replace captive diesel generation. This technology is expanding into markets previously dominated by rotary kiln incineration by offering superior destruction removal efficiency for persistent organic pollutants.
The Ministry of New and Renewable Energy's waste-to-energy program has streamlined single-window clearance mechanisms that compress project approval timelines from 18 months to 8 months. This procedural acceleration benefits anaerobic digestion projects with organic fraction separation requirements. Biogas developers in Maharashtra are responding by clustering dairy and food processing waste contracts to achieve feedstock scale.
Power purchase agreements with escalator clauses tied to fuel price indices are displacing fixed-tariff structures that exposed developers to feedstock cost volatility. Municipal corporations in Tamil Nadu and Karnataka are adopting 15-20 year contracts with annual escalation mechanisms. This shift is most visible in projects serving industrial captive consumers seeking price predictability alongside renewable energy certificates.
India Waste-To-Energy Market Segmentation
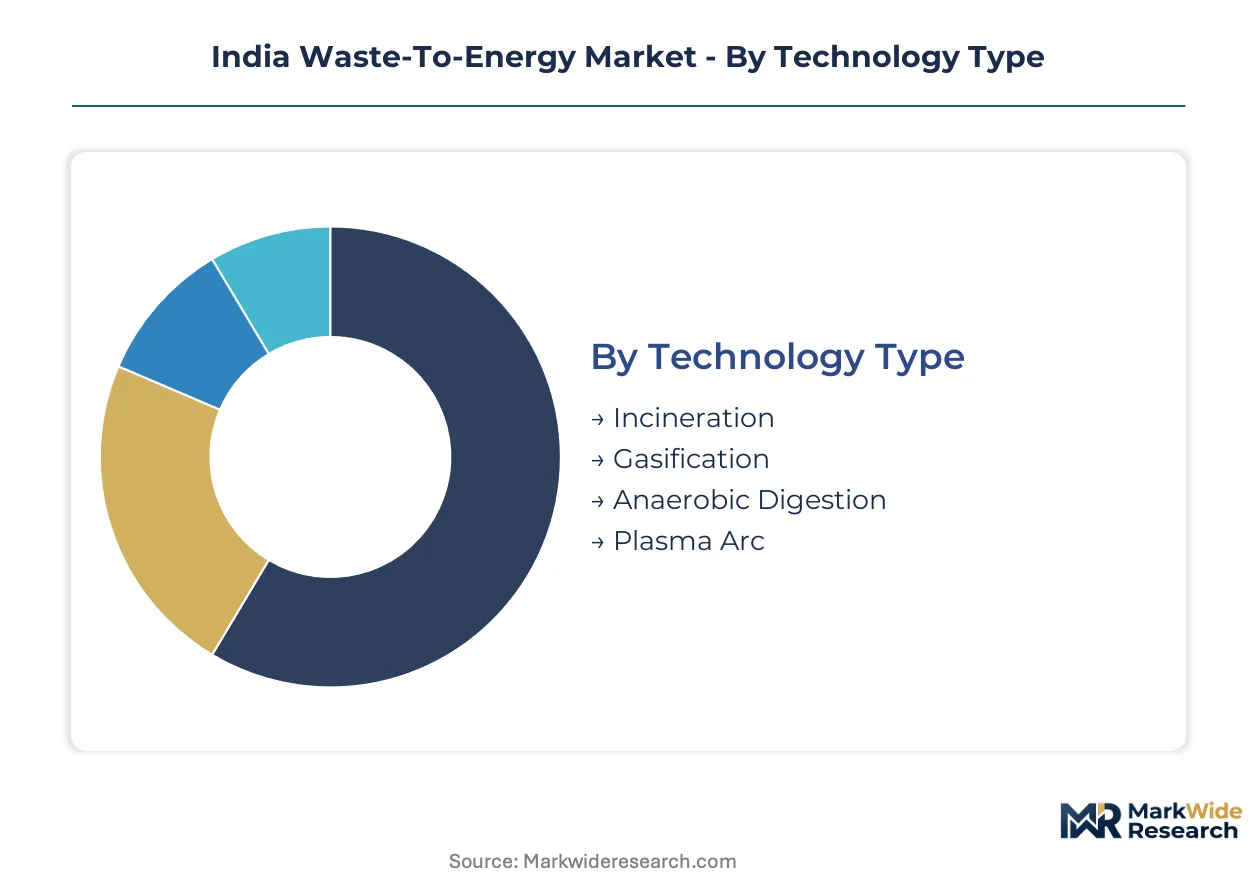
Technology maturity, feedstock calorific value, and offtake contract structures create divergent investment profiles across India's waste-to-energy value chain. Procurement patterns in Maharashtra and Gujarat demonstrate how regulatory enforcement and industrial clustering reshape segment priorities.
Technology Type:
Capital intensity and emissions compliance burdens separate project developers selecting thermal conversion pathways.
- Incineration:Grate combustion systems process mixed municipal solid waste at 850°C to 1,200°C, ensuring complete dioxin destruction through two-second residence times. Municipal corporations in Mumbai and Delhi deploy this technology for grid-connected power under renewable purchase obligations, though flue gas treatment capex inflates project costs by 25-35 percent.
- Anaerobic Digestion:Wet fermentation systems extract biogas from segregated organic fractions with 50-60 percent methane content. Dairy clusters in Maharashtra and food processing zones in Gujarat are scaling biomethane projects to supply compressed natural gas blending mandates for urban transport fleets.
- Gasification:Partial oxidation at 700°C to 1,000°C yields syngas for combined-cycle power generation. Textile parks in Surat and chemical estates in Vadodara favor this pathway for captive baseload supply with higher electrical efficiency than direct combustion.
- Plasma Arc:Electric arc temperatures exceeding 3,000°C vitrify inorganic residues while producing clean syngas. Medical waste treatment facilities in Telangana and hazardous industrial zones in Gujarat pilot modular 5-15 MW units to replace rotary kiln incineration.
Volume sits with Incineration; growth tilts toward Anaerobic Digestion.
Feedstock Type:
Calorific stability and supply security agreements determine project location economics for feedstock procurement.
- Municipal Solid Waste:Mixed refuse streams with 1,200-1,600 kcal/kg net calorific value dominate thermal conversion feedstock. Landfill mining competition in Chennai and Bengaluru is fragmenting supply security for greenfield energy recovery facilities.
- Industrial Waste:Hazardous and non-hazardous manufacturing residues offer consistent thermal properties. Ramky Enviro Engineers anchors hazardous-industrial-waste-to-energy streams through Telangana-based treatment infrastructure with guaranteed destruction removal efficiency.
- Agricultural Residues:Crop stubble and bagasse provide seasonal biomass supply. Punjab and Haryana rice straw collection networks are consolidating around pelletization facilities serving cement kiln co-processing.
- Biomass:Dedicated energy crops and forestry residues support gasification feedstock specifications. Abellon Clean Energy leverages biomass gasification expertise to anchor captive power for Gujarat textile clusters requiring syngas quality consistency.
Volume concentrates in Municipal Solid Waste; Agricultural Residues are climbing the fastest on co-processing demand.
End User:
Contract duration and tariff escalation mechanisms differentiate buyer risk profiles for project developers.
- Energy Utilities:State distribution companies procure power through 15-20 year power purchase agreements with preferential tariffs mandated by the Central Electricity Regulatory Commission. Tamil Nadu and Karnataka utilities are adopting annual escalation clauses tied to fuel price indices.
- Cement Industries:Kiln operators seek refuse-derived fuel to substitute coal in clinker production. UltraTech and Ambuja cement plants in Rajasthan and Madhya Pradesh are contracting preprocessing facilities for consistent calorific input.
- Government Projects:Municipal corporations in tier-1 cities issue engineering-procurement-construction contracts with tipping fee components. JITF Urban Infrastructure sustains positioning through integrated contracts across northern landfill sites.
- Private Enterprises:Industrial estates and commercial complexes deploy captive generation for renewable energy certificate compliance. Gujarat chemical processing zones prioritize baseload supply to offset grid dependency.
Volume flows to Energy Utilities; Private Enterprises represent the steepest expansion trajectory on corporate sustainability mandates.
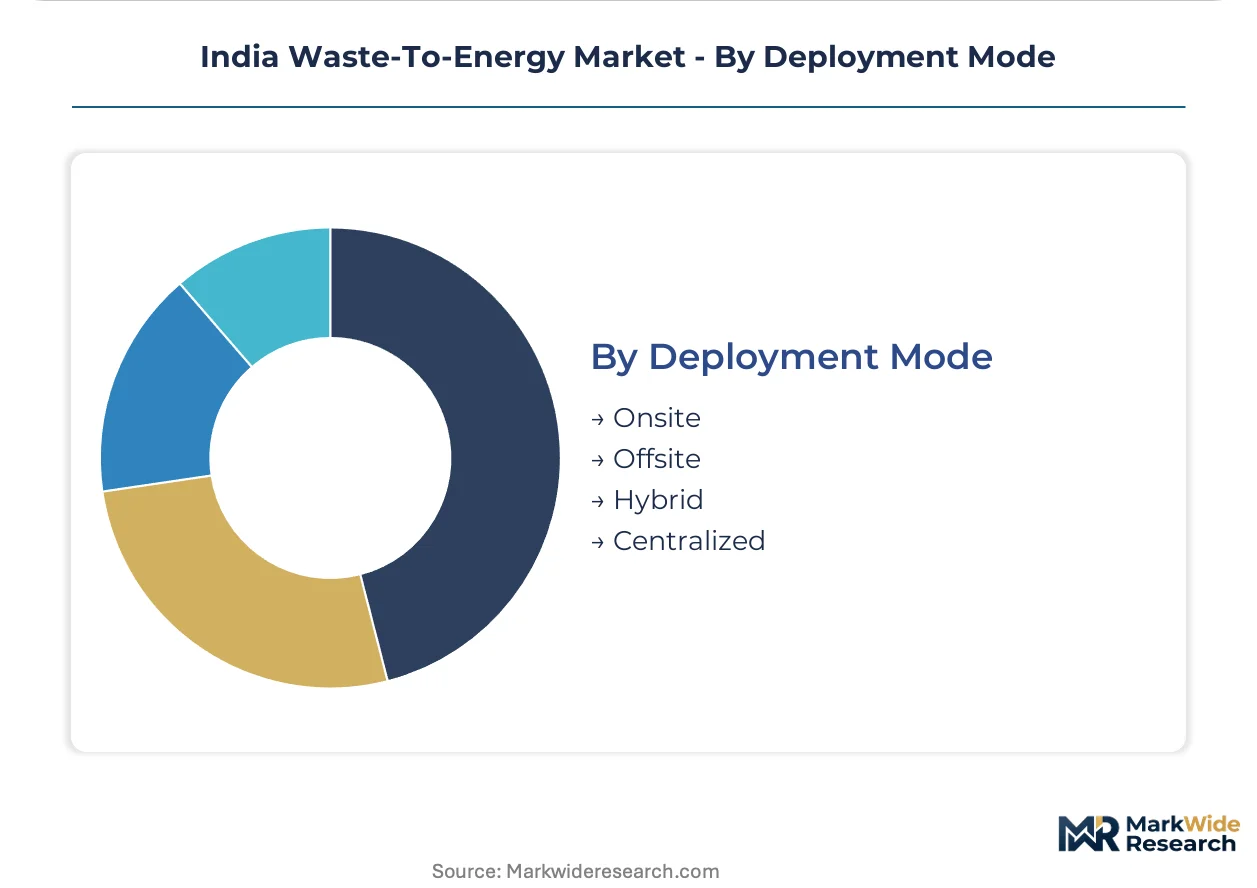
Deployment Mode:
Land availability and grid interconnection costs shape infrastructure configuration decisions.
- Centralized:Large-scale facilities above 10 MW capacity serve urban waste catchments with dedicated transmission infrastructure. State nodal agencies in Tamil Nadu and Karnataka extend viability gap funding to sub-10 MW projects previously excluded.
- Onsite:Captive units at industrial estates eliminate feedstock transport costs. Surat textile parks and Vadodara chemical zones favor this model for process steam and power cogeneration.
- Offsite:Merchant facilities supply multiple offtakers through wheeling arrangements. Open access regulations in Gujarat enable this structure for private enterprise clusters.
- Hybrid:Combined onsite preprocessing with centralized energy recovery balances logistics and scale. Dairy cooperatives in Maharashtra cluster biogas upgrading at village-level digesters with pipeline injection to urban compressed natural gas stations.
Volume accumulates in Centralized deployments; Hybrid configurations are gaining share fastest on distributed feedstock aggregation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Delhi-Mumbai Industrial Corridor tax incentives concentrate waste-to-energy project development in designated manufacturing zones. State-level viability gap funding mechanisms determine financial closure timelines across competing sub-regions. Municipal corporation procurement capacity varies sharply between tier-1 metropolitan clusters and secondary urban centers.
Maharashtra
Mumbai's Deonar and Kanjurmarg landfill saturation drives municipal corporation procurement of large-scale incineration contracts. The state nodal agency administers viability gap funding that accelerates project approvals for grid-connected facilities. Pune and Nagpur industrial estates pilot captive gasification units for textile and automotive component manufacturing zones.
Gujarat
Surat and Vadodara chemical processing clusters generate consistent industrial waste streams for thermal conversion feedstock security. The state's single-window clearance mechanism compresses environmental approval timelines below national averages. Dahej and Mundra special economic zones anchor captive power demand from private enterprise offtakers seeking renewable energy certificate compliance.
Tamil Nadu
Chennai metropolitan landfill capacity exhaustion triggers long-term tipping fee contracts with annual escalation clauses. State distribution utilities adopt preferential tariff structures with fuel price index linkages under Central Electricity Regulatory Commission mandates. Coimbatore and Tiruppur textile belts cluster anaerobic digestion projects around effluent treatment integration requirements.
Telangana
Hyderabad's pharmaceutical and electronics manufacturing zones produce hazardous waste streams requiring high-temperature destruction removal efficiency. The state pollution control board enforces stack emission standards that shape plasma arc gasification pilot deployments. Genome Valley and Pashamylaram industrial parks concentrate medical waste treatment infrastructure with guaranteed feedstock supply agreements.
Karnataka
Bengaluru's municipal solid waste generation exceeds landfill capacity, accelerating engineering-procurement-construction contract issuance for centralized facilities. State nodal agencies extend viability gap funding to sub-10 MW projects previously excluded from central schemes. Mysuru and Mangaluru dairy cooperatives cluster biogas upgrading infrastructure for compressed natural gas grid injection.
India Waste-To-Energy Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology licensing and integrated service contracts. The vendor base separates into three strategic archetypes: multinational environmental services firms with technology transfer capabilities, domestic engineering-procurement-construction contractors with landfill site access, and specialized waste management operators with hazardous material expertise. Competitive positioning depends on securing long-term power purchase agreements and tipping fee contracts with municipal corporations. Market participants pursue capacity expansion through state-level viability gap funding capture and strategic partnerships with industrial estate developers for captive offtake arrangements.
Within the domestic specialist tier, Abellon Clean Energy Ltd and JITF Urban Infrastructure Limited exemplify contrasting positioning archetypes. Ramky Enviro Engineers Ltd occupies a distinctive position in hazardous-industrial-waste-to-energy streams. Multinational entrants including Suez Group and Veolia India Private Limited leverage technology licensing frameworks and global operational protocols. Hitachi Zosen Inova represents the specialized technology provider archetype with grate combustion system expertise.
| Leading Market Players |
|---|
| Suez Group |
| Abellon Clean Energy Ltd |
| Il&fs Environnemental Infrastructure And Services Limited |
| Ecogreen Energy Pvt. Ltd |
| A2Z Group |
| JITF Urban Infrastructure Limited |
| Ramky Enviro Engineers Ltd |
| Hitachi Zosen Inova |
| Veolia India Private Limited |
| Others |
Supply & Pricing Matrix
Municipal corporation procurement of 15-20 year power purchase agreements with annual escalation clauses is forcing project developers to lock in feedstock supply contracts before financial closure, compressing margins and amplifying price sensitivity among tier-2 city entrants lacking tipping fee bargaining power.
Pricing Analysis
Short lead-time premiums dominate project economics as municipal corporations in Mumbai, Delhi, and Chennai accelerate procurement timelines to address landfill saturation. Three-tier pricing structure across premium, standard, and economy levels separates grid-connected utilities with renewable purchase obligation mandates from captive industrial offtakers and merchant power developers. Cost compression in the merchant power tier is intensifying because distribution utilities seek tariff renegotiations post-commissioning. Cement industries and textile clusters demonstrate the least price sensitivity due to renewable energy certificate compliance requirements and process heat substitution economics.
Supply Chain Analysis
Single-source vulnerability sits with European and Japanese suppliers of continuous emissions monitoring systems and refractory materials for combustion chamber linings. Equipment sourcing draws from Germany, Japan, and South Korea for grate combustion systems, flue gas treatment trains, and gasification reactor vessels. Feedstock supply rests on fragmented municipal solid waste collection networks and competing landfill mining operators. Tariff exposure on imported pollution control equipment inflates project capex. Distribution runs through engineering-procurement-construction contractors with landfill site access and state nodal agency relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India Waste-To-Energy Market functions as a cost-of-compliance story where Central Pollution Control Board stack emission standards for dioxins and heavy metals create a barrier-to-entry moat for players with capital to deploy multi-stage flue gas treatment systems.
For Market Incumbents: Extend long-term tipping fee contracts with municipal corporations in tier-1 cities to lock out landfill mining competitors and secure feedstock supply security. Expand backward integration into preprocessing equipment manufacturing to reduce capex inflation from imported pollution control systems. Incumbent positioning strengthens through viability gap funding capture in Tamil Nadu and Karnataka where state nodal agencies extend subsidies to sub-10 MW projects. For New Entrants and Emerging Players: Engineering-procurement-construction contractors with existing landfill site relationships offer the most penetrable channel for market entry without direct municipal procurement capability. Target anaerobic digestion projects in Maharashtra dairy clusters and Gujarat food processing zones where organic fraction separation requirements create technology differentiation. Pursue hybrid deployment models clustering village-level digesters with compressed natural gas grid injection to bypass centralized facility capital intensity. For Investors and Strategic Acquirers: Re-rating potential sits with plasma arc gasification specialists given hazardous waste destruction removal efficiency mandates tightening in Telangana pharmaceutical and electronics zones. Long-term viability frames around 5-10 year regulatory enforcement trajectories for legacy waste recovery versus greenfield energy recovery. Acquisition focus centers on technology licensing firms with syngas cleanup intellectual property. Watch for viability gap funding exhaustion in Karnataka and Tamil Nadu as inflection indicator for project finance availability.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement | 15-20 year contracts with Tamil Nadu utilities lock in preferential tariffs under Central Electricity Regulatory Commission mandates. |
| Backward Integration | In-house production of refuse-derived fuel preprocessing equipment reduces exposure to imported component cost volatility. |
| Technology Licensing | Syngas cleanup patents from European specialists enable plasma arc gasification efficiency gains in Gujarat chemical estates. |
| Viability Gap Funding Capture | State nodal agency subsidies in Maharashtra accelerate financial closure timelines for grid-connected incineration facilities. |
| Feedstock Supply Agreement | Long-term contracts with Mumbai municipal corporation secure calorific value stability against landfill mining competition. |
Research Methodology
Document review covered Ministry of New and Renewable Energy program filings, Central Electricity Regulatory Commission tariff orders, Central Pollution Control Board emission standards, and state nodal agency viability gap funding guidelines, complemented by interviews with waste-to-energy project developers, municipal corporation solid waste management officers, state distribution utility procurement leads, and flue gas treatment equipment suppliers. Secondary validation drew from Ministry of Environment, Forest and Climate Change compliance databases, state pollution control board project approvals, and engineering-procurement-construction contractor order books. Bottom-up project pipeline aggregation triangulated against top-down market sizing from regulatory capacity targets.
Historical project commissioning data cross-referenced against expert panel input on feedstock calorific value trends, tipping fee escalation patterns, and power purchase agreement renegotiation probabilities. Segmentation modeling spanned technology type, feedstock source, end-user category, and deployment mode across the projection horizon. CAGRs derived from capacity addition trajectories under renewable purchase obligation enforcement scenarios and municipal corporation procurement pipeline visibility. Industry-specific inputs included landfill saturation curves for tier-1 cities and industrial cluster captive demand growth from corporate sustainability commitments.
Caveats apply where Central Electricity Regulatory Commission tariff renegotiation rulings, feedstock supply disruptions from landfill mining competition, or plasma arc gasification technology cost breakthroughs could materially shift the outlook. Forecasts reflect documented assumptions on policy continuity, enforcement timelines, and project finance availability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
ASEAN Waste Management Market
Waste Management & Pollution Control
Municipal Solid Waste Management Market
Waste Management & Pollution Control
Asia Pacific Medical Waste Management Market
Waste Management & Pollution Control
Recyclate PET Market
Waste Management & Pollution Control
Reusable Oil Absorbents Market
Waste Management & Pollution Control
Middle-East and Africa Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
UAE Industrial Waste Management Market
Waste Management & Pollution Control
Asia-Pacific Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
Metal Recycling Equipment Market
Waste Management & Pollution Control
Smart Waste Sorting Bin Market
Waste Management & Pollution Control
Medical Waste Management Equipment Market
Waste Management & Pollution Control
Biomedical Waste Management Market
Waste Management & Pollution Control
Waste Recycling Services Market
Waste Management & Pollution Control
Landfill Compactor Market
Waste Management & Pollution Control
Saudi Arabia Waste Management Market
Waste Management & Pollution Control
India Plastic Waste Management Market