
 Dysmenorrhea Treatment Market | 2026-2036
Dysmenorrhea Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Dysmenorrhea Treatment Market Analysis
Aftermarket service revenue from patient support programs and adherence monitoring is fragmenting across digital health platforms and traditional pharmacy networks. Novartis AG leverages its specialty pharmacy infrastructure to sustain direct patient engagement beyond the prescription fill. Sanofi anchors its position through integrated hormone therapy portfolios that span oral and transdermal delivery systems. Bayer AG competes aggressively in the over-the-counter NSAID segment where brand recognition controls shelf placement across European and North American retail chains.
Dysmenorrhea treatment encompasses pharmacological and non-pharmacological interventions targeting menstrual pain of primary or secondary etiology, with NSAIDs functioning through prostaglandin synthesis inhibition and hormonal therapies suppressing endometrial proliferation via estrogen-progestin modulation. The primary commercial purpose centers on restoring functional capacity during menstruation while reducing dependency on opioid rescue medications in chronic presentations. NSAIDs occupy the mature volume base where generic erosion has compressed unit margins, yet hormonal therapies command premium positioning due to extended-cycle formulations and endometriosis co-indications. Transdermal patches represent the fastest-growing delivery mode as patient preference shifts toward steady-state plasma levels and gastrointestinal avoidance, while homecare settings capture margin migration from institutional reimbursement constraints.
The FDA regulates prescription hormonal therapies under risk evaluation and mitigation strategies that elevate clinical trial burdens but protect branded innovators from rapid generic substitution. EMA's pharmacovigilance requirements for gynecological products shape labeling decisions that cascade into physician prescribing patterns across EU member states. Stakeholders must monitor evolving FDA guidance on real-world evidence acceptance for secondary dysmenorrhea indications, as this regulatory flexibility could reshape competitive barriers for novel mechanism drugs against established NSAID dominance.
Market Dynamics
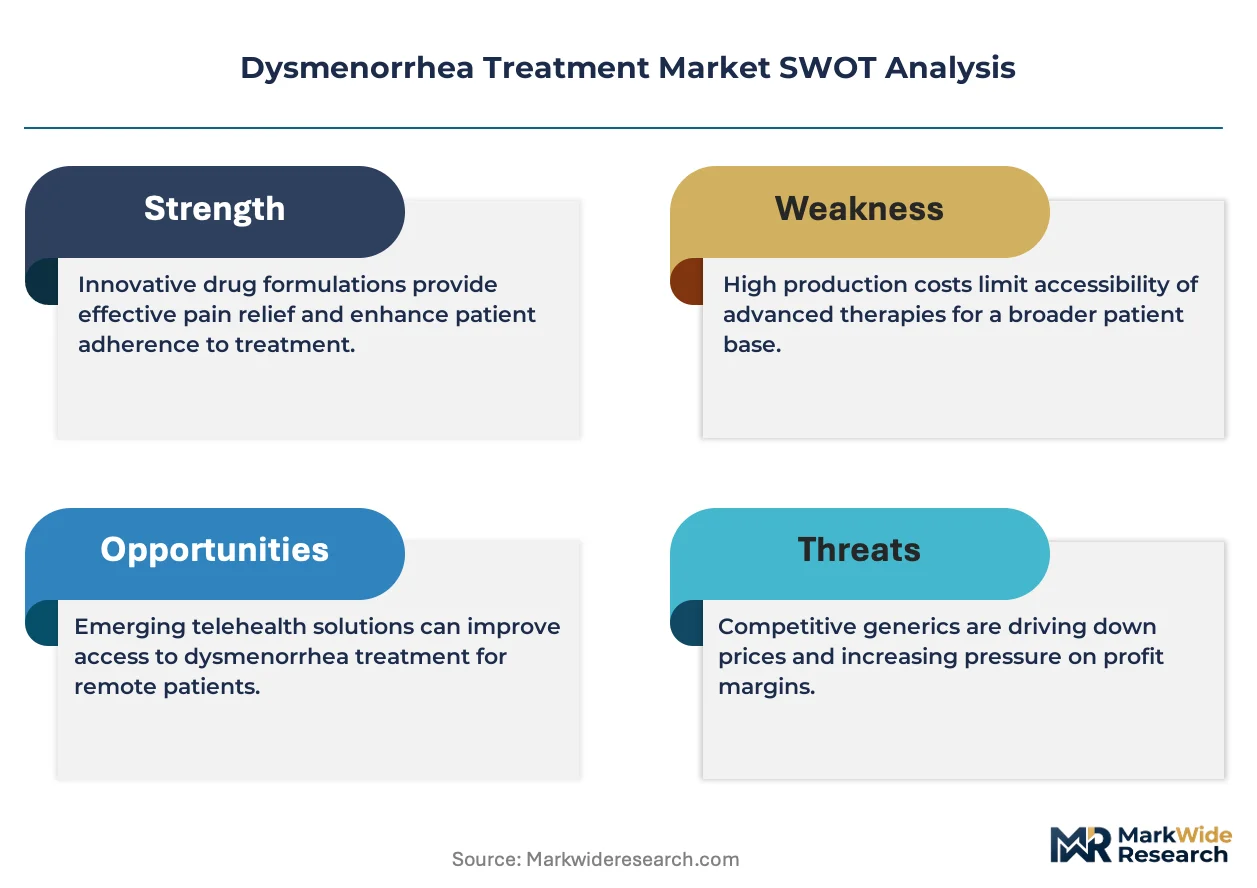
Homecare settings are capturing margin migration from institutional reimbursement constraints, while FDA's streamlined approval pathways for women's health therapeutics compress development timelines and reshape competitive barriers against established NSAID dominance.
Growth Catalysts
- Telehealth Integration:Direct-to-consumer pharmaceutical channels accelerate patient access to hormonal and non-hormonal therapies across United States metropolitan clusters.
- Risk Evaluation and Mitigation Strategies:FDA's REMS framework elevates clinical trial burdens but protects branded innovators from rapid generic substitution in hormonal segments.
- Transdermal Delivery Systems:Patient preference shifts toward steady-state plasma levels and gastrointestinal avoidance drive patch-based adoption in self-administered pain management.
Market Restraints
- Generic Erosion in NSAIDs:Mature volume base faces compressed unit margins as unbranded ibuprofen and naproxen dominate pharmacy shelf placement.
- EMA Pharmacovigilance Requirements:Gynecological product labeling decisions cascade into restrictive physician prescribing patterns across EU member states.
- Opioid Rescue Dependency:Chronic secondary dysmenorrhea presentations retain reliance on controlled substances despite non-opioid alternatives.
Strategic Opportunities
- Real-World Evidence Pathways:Evolving FDA guidance on RWE acceptance for secondary dysmenorrhea indications creates entry points for novel mechanism drugs.
- Extended-Cycle Formulations:Endometriosis co-indications expand addressable patient populations beyond primary menstrual pain.
- Specialty Pharmacy Infrastructure:Direct patient engagement beyond prescription fill captures adherence monitoring revenue streams.
Industry Challenges
- Clinical Trial Recruitment:Women's health studies face enrollment friction due to menstrual cycle synchronization requirements and placebo response variability.
- Reimbursement Coding Fragmentation:Transdermal patches and oral therapies occupy distinct billing categories, complicating formulary placement negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dysmenorrhea Treatment Market |
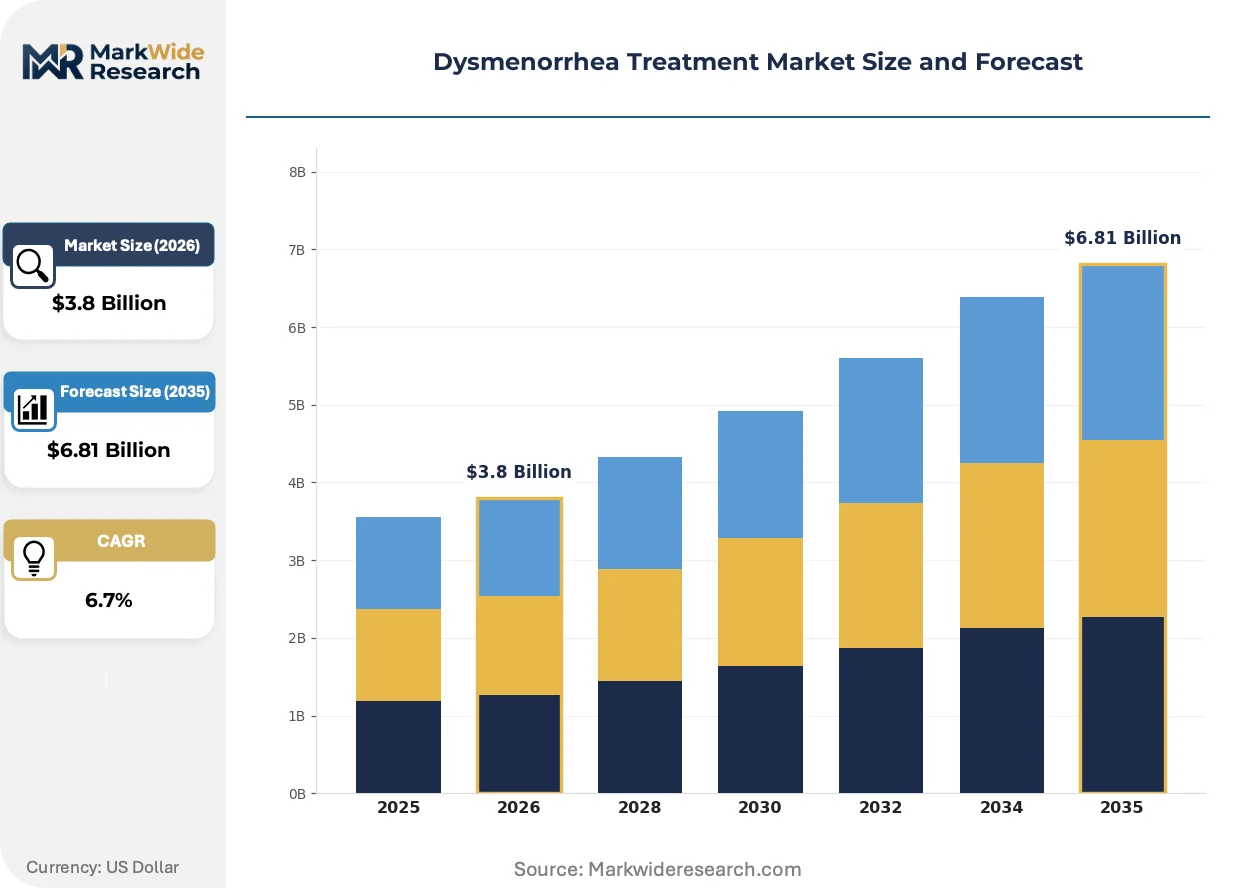
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NSAIDs, Hormonal Therapies, Antidepressants, Lifestyle Products Therapy Area: Primary Dysmenorrhea, Secondary Dysmenorrhea, Chronic Pelvic Pain, Ovulatory Disorders Delivery Mode: Oral Administration, Transdermal Patches, Injectable Solutions, Topical Gels End User: Hospitals, Clinics, Homecare Settings, Online Pharmacies |
| Companies Covered | Novartis AG, Sanofi, Bayer AG, Teva Pharmaceutical Industries Ltd, GlaxoSmithKline plc, Pfizer Inc, AbbVie Inc, F. Hoffmann-La Roche Ltd, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dysmenorrhea Treatment Market Emerging Trajectories
Delivery modality preferences and regulatory data requirements are restructuring how dysmenorrhea therapies reach patients, with digital health platforms fragmenting traditional pharmacy-centric distribution.
Transdermal patches is migrating from niche gastrointestinal intolerance applications toward mainstream first-line therapy for moderate-to-severe primary dysmenorrhea. Adolescent patients and perimenopausal women adopt patch-based estradiol-progestin combinations at accelerating rates. This modality is compressing oral NSAID refill volumes in United States retail pharmacy chains while expanding homecare margin capture.
REACH compliance obligations for pharmaceutical excipients reshape supplier qualification protocols across European manufacturing networks. ECHA's substance restriction candidate list forces reformulation of adhesive matrices in transdermal systems. German and French contract manufacturers invest in bio-based solvent alternatives to maintain CE-marked device access.
Subscription-based medication delivery displaces episodic pharmacy visits among insured patients seeking menstrual predictability. Digital health platforms unbundle adherence monitoring from traditional specialty pharmacy networks. This behavioral shift concentrates in United States coastal metropolitan areas with mature telehealth infrastructure and direct-to-consumer pharmaceutical advertising exposure.
Dysmenorrhea Treatment Market Segmentation
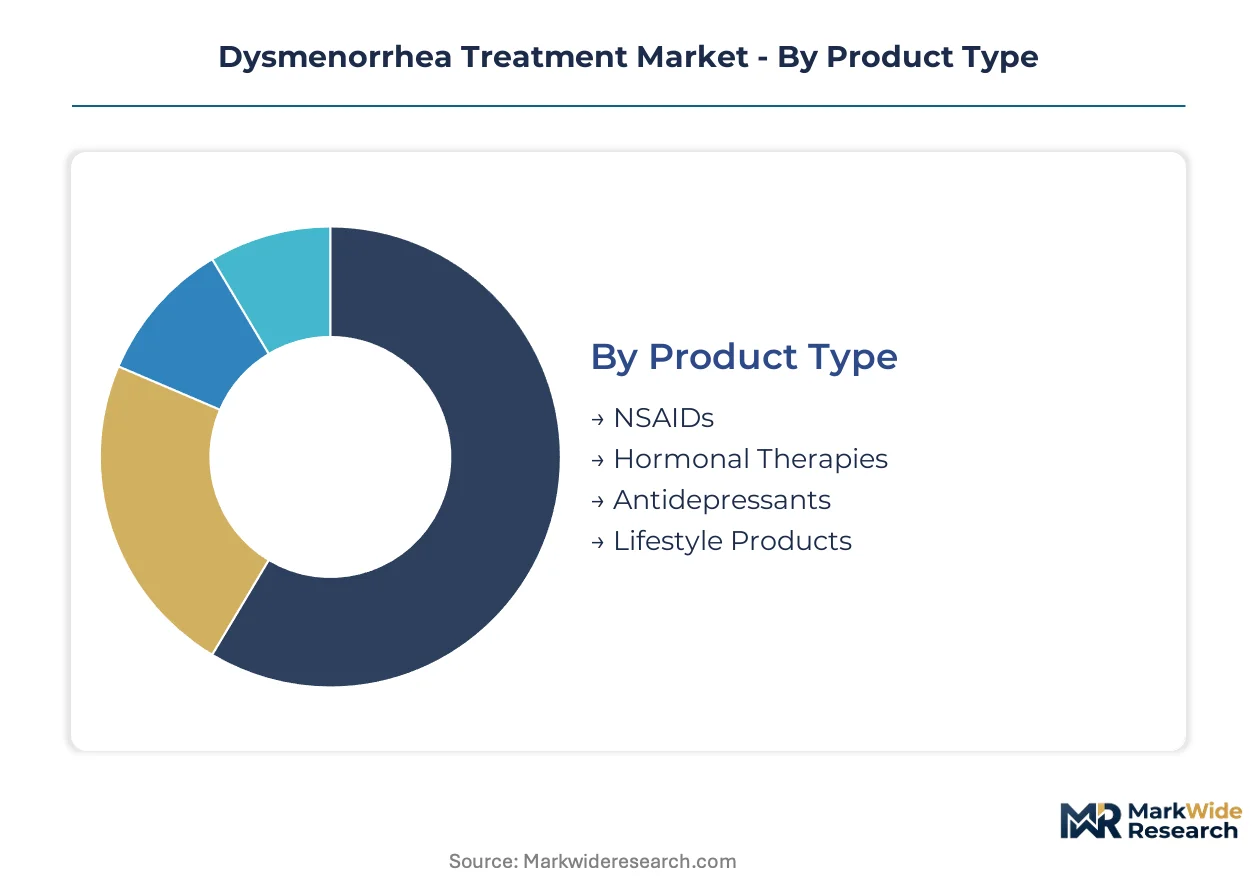
Dysmenorrhea treatment segmentation reveals divergent margin profiles across pharmacological maturity levels, with hormonal innovations commanding premium positioning against commoditized NSAID volumes. Delivery modality and care setting fragmentation create distinct competitive arenas where reimbursement codes and patient self-administration preferences reshape commercial strategy.
Product Type:
Mature oral analgesics anchor volume throughput while novel hormonal mechanisms capture value expansion in specialty channels.
- NSAIDs:Ibuprofen and naproxen formulations inhibit prostaglandin synthesis through COX-1/COX-2 enzyme blockade. Pharmacy chains across Germany, France, and the United States allocate prime shelf space to private-label versions, compressing branded unit economics despite sustained prescription volumes.
- Hormonal Therapies:Extended-cycle oral contraceptives and progestin-only systems suppress endometrial proliferation via estrogen-progestin modulation. Demand concentrates in United States metropolitan clusters where telehealth platforms streamline prescription renewal for menstrual suppression protocols.
- Antidepressants:SNRIs modulate central pain processing in patients with comorbid mood disorders. Prescribing remains concentrated in psychiatric and gynecological co-management settings.
- Lifestyle Products:Heat therapy devices and dietary supplements address non-pharmacological preferences. Direct-to-consumer channels in Japan and South Korea drive category visibility through subscription wellness platforms.
NSAIDs handle the majority of throughput; Hormonal Therapies is the fastest mover on share.
Therapy Area:
Application severity stratifies treatment intensity, with secondary etiologies requiring multidisciplinary intervention beyond standard analgesia.
- Primary Dysmenorrhea:Prostaglandin-mediated menstrual pain without underlying pelvic pathology. Adolescent patients in United States school health programs and Japanese corporate wellness initiatives drive first-line NSAID consumption.
- Secondary Dysmenorrhea:Pain attributable to endometriosis, adenomyosis, or fibroids. Academic medical centers in Boston, London, and Munich anchor specialist referral networks where hormonal suppression and surgical consultation coexist.
- Chronic Pelvic Pain:Persistent discomfort exceeding six months with multifactorial etiology. Pain clinics in Toronto and Sydney integrate neuromodulator trials with physical therapy protocols.
- Ovulatory Disorders:Menstrual irregularity with associated dysmenorrhea symptoms. Fertility practices in Barcelona and Amsterdam prioritize cycle regulation alongside pain management.
Primary Dysmenorrhea commands the largest patient population; Secondary Dysmenorrhea is climbing the fastest as diagnostic awareness expands.
Delivery Mode:
Patient adherence patterns and gastrointestinal tolerance concerns are restructuring route-of-administration preferences across age demographics.
- Oral Administration:Tablets and capsules dominate prescription volume through established familiarity and formulary inclusion. Retail pharmacies in Chicago and Houston process the highest refill frequencies for immediate-release ibuprofen.
- Transdermal Patches:Estradiol-progestin combinations achieve steady-state plasma concentrations without hepatic first-pass metabolism. Homecare adoption accelerates among perimenopausal patients in California and New York seeking gastrointestinal avoidance.
- Injectable Solutions:Depot medroxyprogesterone and GnRH agonists provide extended suppression for severe secondary cases. Hospital outpatient departments in Paris and Milan administer these under specialist supervision.
- Topical Gels:Localized NSAID application targets superficial pelvic pain with reduced systemic exposure. Physiotherapy clinics in Melbourne and Stockholm incorporate these into multimodal protocols.
Oral Administration retains the dominant prescription share; Transdermal Patches is gaining share fastest among self-administered alternatives.
End User:
Care setting migration reflects reimbursement compression and patient preference for privacy and convenience in menstrual health management.
- Hospitals:Emergency departments and gynecological wards manage acute presentations and surgical candidates. Tertiary centers in London, New York, and Singapore handle complex secondary dysmenorrhea with laparoscopic intervention.
- Clinics:Outpatient gynecology and primary care practices issue the majority of ongoing prescriptions. Federally qualified health centers across Texas and Florida serve high-volume Medicaid populations.
- Homecare Settings:Self-administered hormonal and non-hormonal therapies capture margin migration from institutional reimbursement constraints. Subscription delivery services in Seattle and Los Angeles concentrate insured patient acquisition.
- Online Pharmacies:Direct-to-consumer platforms bypass traditional pharmacy visits for maintenance therapies. Regulatory compliance with FDA and state board requirements shapes operational scope in United States markets.
Clinics process the majority of initial diagnoses; Homecare Settings is expanding most quickly as telehealth integration matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty pharmaceutical manufacturing clusters in Switzerland, Germany, and the United States concentrate hormonal therapy production capacity. Contract manufacturing organizations across these jurisdictions serve branded innovators seeking FDA and EMA compliance.
United States
Direct-to-consumer pharmaceutical channels and telehealth platforms accelerate patient access to hormonal therapies in metropolitan clusters. FDA's streamlined approval pathways for women's health therapeutics compress development timelines for novel mechanisms. Boston and New York anchor specialist referral networks where academic medical centers manage complex secondary dysmenorrhea presentations.
Germany
REACH compliance obligations for pharmaceutical excipients reshape supplier qualification protocols across European manufacturing networks. ECHA's substance restriction candidate list forces reformulation of adhesive matrices in transdermal systems. Contract manufacturers in Bavaria and Baden-Württemberg invest in bio-based solvent alternatives to maintain CE-marked device access.
Switzerland
Specialty pharmacy infrastructure sustains direct patient engagement beyond prescription fills through integrated hormone therapy portfolios. Swissmedic's pharmacovigilance requirements shape labeling decisions that cascade into physician prescribing patterns. Basel and Zurich concentrate pharmaceutical R&D facilities serving global hormonal therapy distribution.
United Kingdom
Telehealth integration matures in London and Southeast England, displacing episodic pharmacy visits among insured patients seeking menstrual predictability. MHRA's post-Brexit regulatory autonomy creates divergence from EMA guidance on real-world evidence acceptance. Manchester and Birmingham process high refill frequencies for immediate-release NSAIDs through retail pharmacy chains.
Japan
PMDA's review timelines for gynecological products influence regional development priorities for extended-cycle formulations. METI's healthcare technology assessment frameworks shape reimbursement negotiations for transdermal delivery systems. Tokyo and Osaka drive category visibility for non-pharmacological lifestyle products through subscription wellness platforms.
Dysmenorrhea Treatment Market Vendor Landscape
Branded innovators and generic manufacturers split the market along pharmacological maturity lines. Hormonal therapy specialists command premium positioning through REMS-protected formulations, while commodity NSAID producers compete on pharmacy shelf placement and unit economics. Three archetypes dominate: integrated pharmaceutical conglomerates with women's health divisions, pure-play hormonal therapy developers, and diversified OTC analgesic manufacturers. Competitive moves center on specialty pharmacy infrastructure acquisition and transdermal delivery technology licensing.
Among Swiss-based pharmaceutical conglomerates, Novartis AG and F. Hoffmann-La Roche Ltd exemplify integrated innovators leveraging specialty pharmacy infrastructure for sustained patient engagement. Sanofi and Bayer AG represent European diversified players with spanning hormone therapy portfolios and OTC dominance respectively. AbbVie Inc anchors the North American premium-tier position through extended-cycle formulation expertise. These three archetypes—Swiss integrated innovators, European diversified conglomerates, and North American specialty-focused developers—occupy distinct competitive terrain defined by regulatory protection duration and delivery modality control.
| Leading Market Players |
|---|
| Novartis AG |
| Sanofi |
| Bayer AG |
| Teva Pharmaceutical Industries Ltd |
| GlaxoSmithKline plc |
| Pfizer Inc |
| AbbVie Inc |
| F. Hoffmann-La Roche Ltd |
| Johnson & Johnson |
| Others |
Supply Flow & Price Mechanics
Active pharmaceutical ingredient manufacturing for hormonal therapies clusters in Switzerland and Germany, concentrating margin capture among European contract manufacturers who supply branded innovators with REMS-protected formulations. This upstream concentration positions specialty pharmacy networks and direct-to-consumer platforms as the primary downstream margin pools, while generic NSAID producers compete on pharmacy shelf placement economics.
Pricing Analysis
FDA's REMS framework dictates the pricing tier structure across hormonal therapy portfolios, separating extended-cycle oral contraceptives and transdermal patches from commoditized NSAID volumes. Three-tier pricing structure across premium, standard, and economy levels reflects brand recognition, delivery modality sophistication, and endometriosis co-indication breadth. Cost compression in the NSAID tier is intensifying because private-label ibuprofen and naproxen dominate retail pharmacy chains. Uninsured adolescents and Medicaid populations exhibit highest price sensitivity, while perimenopausal patients seeking gastrointestinal avoidance through transdermal systems demonstrate lowest sensitivity.
Supply Chain Analysis
Extended payment terms from Swiss and German contract manufacturers to adhesive matrix suppliers are restructuring working capital requirements across transdermal patch production. API synthesis for hormonal therapies draws from Switzerland, Germany, and the United States, with excipient sourcing tethered to REACH-compliant European suppliers. Bio-based solvent alternatives and ECHA substance restriction candidate list compliance constitute the primary regulatory risk. Distribution runs through specialty pharmacy infrastructure and direct-to-consumer telehealth platforms for self-administered therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dysmenorrhea treatment market sits in early-cycle expansion as telehealth integration and direct-to-consumer pharmaceutical channels accelerate patient access beyond traditional clinic-based prescribing. Transdermal delivery adoption and subscription-based medication delivery represent structural tailwinds in penetration.
For Market Incumbents: Entrench REMS-protected hormonal therapy positions through backward integration into transdermal patch manufacturing capacity in Switzerland and Germany. Acquire specialty pharmacy infrastructure to capture adherence monitoring revenue streams beyond prescription fills. Generic erosion in NSAIDs and digital health platform fragmentation of traditional distribution threaten incumbent margin structures. For New Entrants and Emerging Players: Japanese and South Korean lifestyle product segments offer underpenetrated white-space for non-pharmacological heat therapy devices and dietary supplements. Target adolescent primary dysmenorrhea populations in United States school health programs with subscription wellness platforms. Partner with telehealth infrastructure providers to bypass established pharmacy network gatekeeping. For Investors and Strategic Acquirers: Capital is best deployed toward pure-play hormonal therapy developers with transdermal delivery expertise and extended-cycle formulation pipelines. Long-term viability hinges on regulatory protection duration and real-world evidence pathway execution. Monitor FDA guidance evolution on secondary dysmenorrhea indications as inflection signal for novel mechanism drug entry viability.| Strategic Initiative | Industry Significance |
|---|---|
| Transdermal Delivery Technology Licensing | Steady-state plasma concentration capabilities attract perimenopausal patients seeking gastrointestinal avoidance. |
| Specialty Pharmacy Infrastructure Acquisition | Direct patient engagement beyond prescription fills captures adherence monitoring revenue from hormonal therapy portfolios. |
| Real-World Evidence Pathway Investment | FDA guidance flexibility on secondary dysmenorrhea indications creates competitive entry points against NSAID dominance. |
| Extended-Cycle Formulation Development | Endometriosis co-indications expand addressable patient populations beyond primary menstrual pain management. |
| Telehealth Platform Integration | Direct-to-consumer channels in United States metropolitan clusters accelerate patient access to hormonal therapies. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with gynecologists, specialty pharmacy directors, formulary managers, and regulatory affairs leads at hormonal therapy developers. Secondary validation drew from FDA filings, EMA pharmacovigilance databases, ClinicalTrials.gov entries, and hospital procurement records. Bottom-up patient population sizing and top-down pharmaceutical revenue triangulation anchored volume and value estimates.
Calibration against historical prescription volume trends and reimbursement code utilization patterns informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, therapy area severity, delivery mode, and care setting migration patterns. CAGRs were derived from regression analysis of adoption curve penetration rates and pricing trajectory assumptions. Transdermal patch manufacturing capacity expansion and telehealth platform patient acquisition metrics served as industry-specific forecast inputs.
Practitioners should monitor regulatory guidance evolution, reimbursement coding consolidation, and generic entry timing for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Women's Health
Mother and Child Healthcare Market
Women's Health
Postmenopausal Vaginal Atrophy Treatment and Drug Market
Women's Health
Women Health Disease Diagnosis and Treatment Market
Women's Health
North America Womens Health Diagnostics Market
Women's Health
Menstrual Cup Foam Wash Market
Women's Health
Women's Health Market
Women's Health
Maternal Health Market
Women's Health
Global Menopausal Hot Flashes Market
Women's Health
US Womens Health Market
Women's Health
Women's Health App Market
Women's Health
Menstrual Health Apps Market
Women's Health
Women's Digital Health Market
Women's Health
Women Health Devices Market
Women's Health
Women Health Software Market
Women's Health
Women Health Care Market
Women's Health
Menopause Market