
 Global Gynecological Dilators Market | 2026-2036
Global Gynecological Dilators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gynecological Dilators Market Foresight
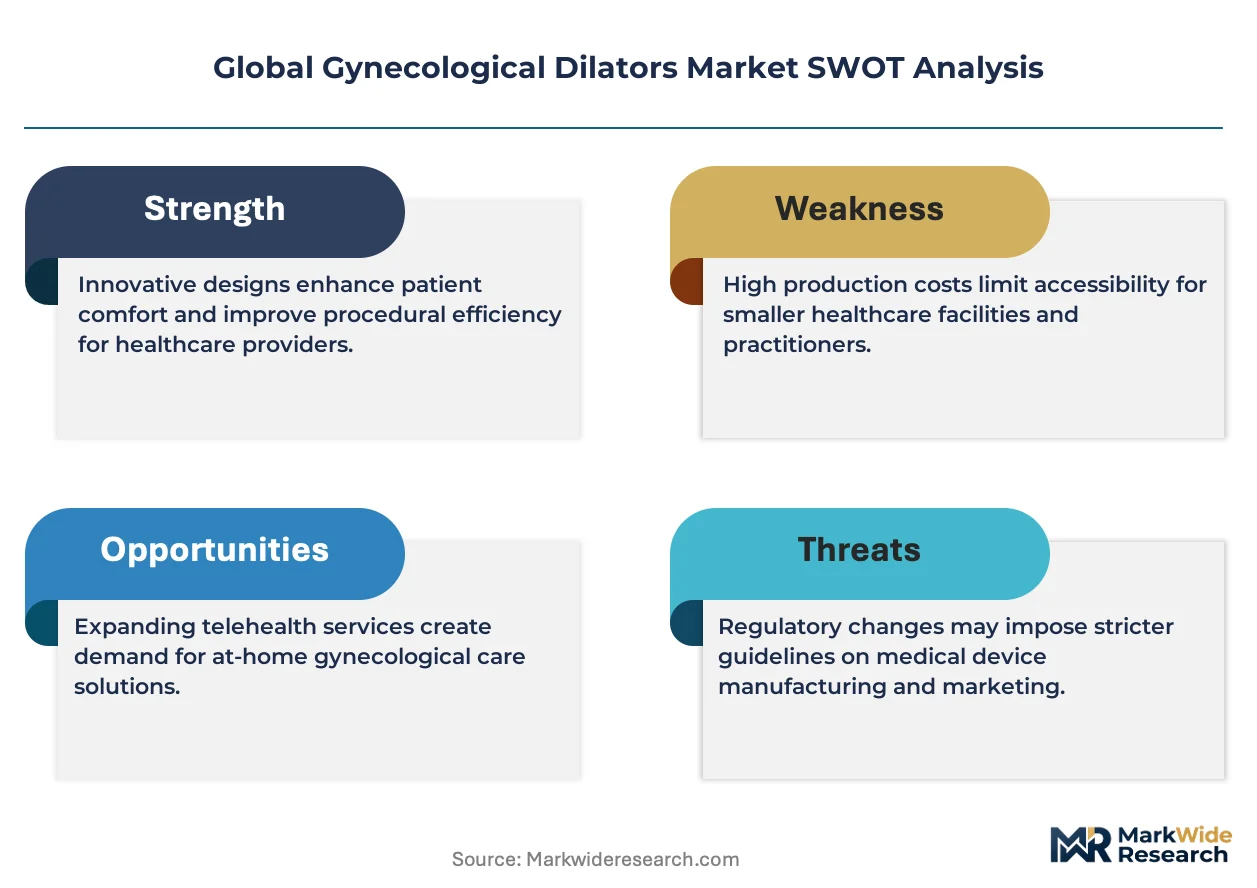
ISO 13485 certification is redrawing competitive boundaries in gynecological dilator manufacturing, forcing smaller suppliers to invest in quality management systems or exit hospital procurement channels. CooperSurgical leverages its vertically integrated sterilization infrastructure to sustain contract renewals with major US health systems. Sklar Corp anchors its position through specialized stainless steel instrument lines that dominate academic medical center preference lists.
Gynecological dilators are graduated cylindrical instruments, typically manufactured from surgical-grade stainless steel, medical silicone, or autoclavable polymers, designed to gradually expand vaginal or cervical canal diameter through mechanical dilation. The device serves primary functions in preparatory cervical dilation before intrauterine procedures and postoperative vaginal stenosis prevention. Silicone dilators now command premium positioning in radiation therapy applications where tissue sensitivity demands biocompatible, temperature-stable materials. Metal dilators retain dominance in diagnostic procedures requiring precise tactile feedback and mechanical rigidity. Post-surgical therapy represents the fastest-expanding application segment as enhanced recovery after surgery protocols shorten hospital stays and shift dilation maintenance to outpatient settings.
FDA 510(k) clearance pathways govern US market entry for polymer-based dilators, while EU MDR technical documentation requirements have extended conformity assessment timelines for European manufacturers. Japan's PMDA enforces JIS T 0313 biocompatibility testing that limits supplier qualification for East Asian hospital tenders. Stakeholders must monitor evolving sterilization validation standards as healthcare systems weigh single-use disposables against reprocessing economics for metal instrument portfolios.
Market Dynamics
EU MDR sterilization protocols are restructuring procurement hierarchies across European ambulatory surgery centers, forcing material transitions from reusable metal to single-use polymer dilators and redistributing contract volumes toward vertically integrated sterilization providers.
Growth Catalysts
- EU MDR sterilization mandates:Stricter conformity assessment timelines for reusable instruments are accelerating hospital procurement of disposable silicone dilators in Germany and France.
- Radiation therapy applications:Biocompatible temperature-stable silicone dilators command premium positioning where tissue sensitivity demands specialized material performance.
- Enhanced recovery protocols:Shortened hospital stays shift postoperative vaginal stenosis prevention to outpatient settings, expanding home-based dilation maintenance demand.
Market Restraints
- Medical-grade silicone cost volatility:Raw material price fluctuations constrain margin stability for polymer-based dilator manufacturers dependent on petrochemical feedstocks.
- ISO 13485 certification barriers:Quality management system investment requirements force smaller suppliers to exit hospital procurement channels, concentrating supply among established players.
- Metal instrument tactile fidelity:Surgical-grade stainless steel retains irreplaceable mechanical rigidity for diagnostic procedures requiring precise haptic feedback.
Strategic Opportunities
- Japanese PMDA market entry:JIS T 0313 biocompatibility testing compliance opens East Asian hospital tenders currently underserved by Western suppliers.
- FDA 510(k) polymer pathways:Streamlined US regulatory clearance for autoclavable polymers enables faster market penetration against legacy metal portfolios.
- Telehealth-integrated home therapy:Remote patient monitoring platforms create subscription-based distribution channels for post-surgical dilation regimens.
Industry Challenges
- Sterilization validation expertise scarcity:Healthcare systems struggle to staff personnel capable of assessing single-use versus reprocessing economics for mixed instrument portfolios.
- Legacy ERP integration friction:Hospital supply chain systems require costly reconfiguration to track lot-specific EU MDR technical documentation alongside traditional metal instrument inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gynecological Dilators Market |
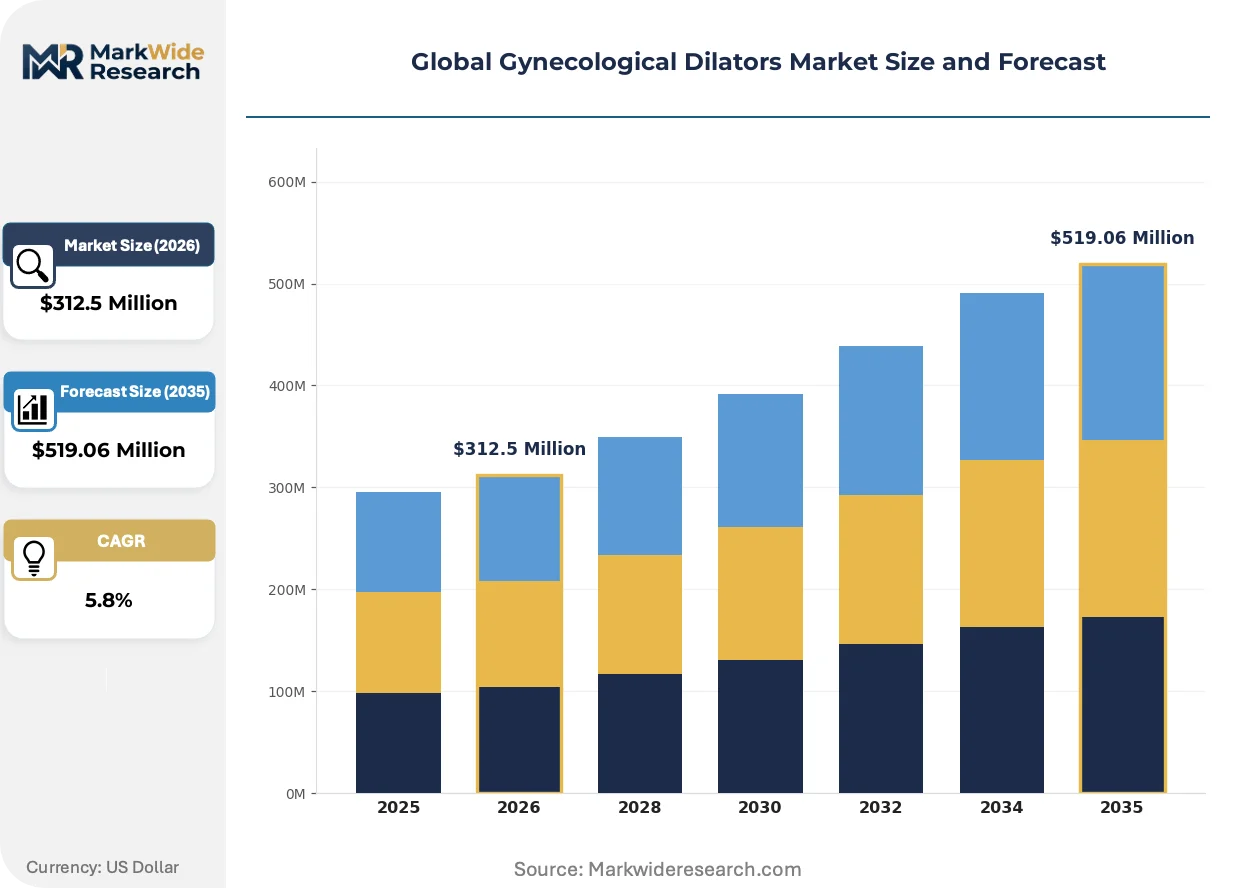
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Dilators, Silicone Dilators, Plastic Dilators, Glass Dilators, Composite Dilators Application: Vaginal Stenosis, Cervical Dilation, Post-Surgical Therapy, Radiation Therapy, Diagnostic Procedures End User: Gynecology Clinics, Ambulatory Surgery Centers, Diagnostic Labs, Postoperative Care Centers Distribution Channel: Direct Sales, Medical Distributors, Online Pharmacies, Hospital Procurement, Specialty Stores |
| Companies Covered | Stingray Surgical Products, Surgical Holdings UK, Sklar Corp, CooperSurgical, Medgyn Products, Soul Source, Pelican Feminine Healthcare, Olympus, Velvi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gynecological Dilators Market Shifts & Advancements
Material science advances and regulatory harmonization pressures are simultaneously diversifying product architectures while compressing certification timelines, creating asymmetric competitive advantages for manufacturers with captive testing infrastructure.
Polymer-based autoclavable dilators are fragmenting traditional metal instrument dominance across North American gynecology clinics. Academic medical centers in Boston and San Francisco pilot hybrid portfolios blending silicone comfort with stainless steel precision. This material diversification is fragmenting procurement standardization, forcing hospitals to maintain parallel sterilization workflows and supplier qualification tracks.
Japan's PMDA enforces JIS T 0313 biocompatibility testing that extends conformity assessment timelines for foreign manufacturers. Domestic Japanese suppliers leverage proximity to regulatory reviewers, compressing time-to-tender for East Asian hospital contracts. European manufacturers attempting Japanese market entry face 18-24 month validation cycles against 8-12 months for domestic competitors.
Hospital buying committees now mandate ISO 13485 certification as a non-negotiable qualification filter, displacing price-only procurement evaluations. Group purchasing organizations in Texas and California embed quality management documentation requirements into contract templates. This certification-driven preference shift most visibly concentrates contract awards among manufacturers with vertically integrated sterilization infrastructure.
Global Gynecological Dilators Market Segmentation
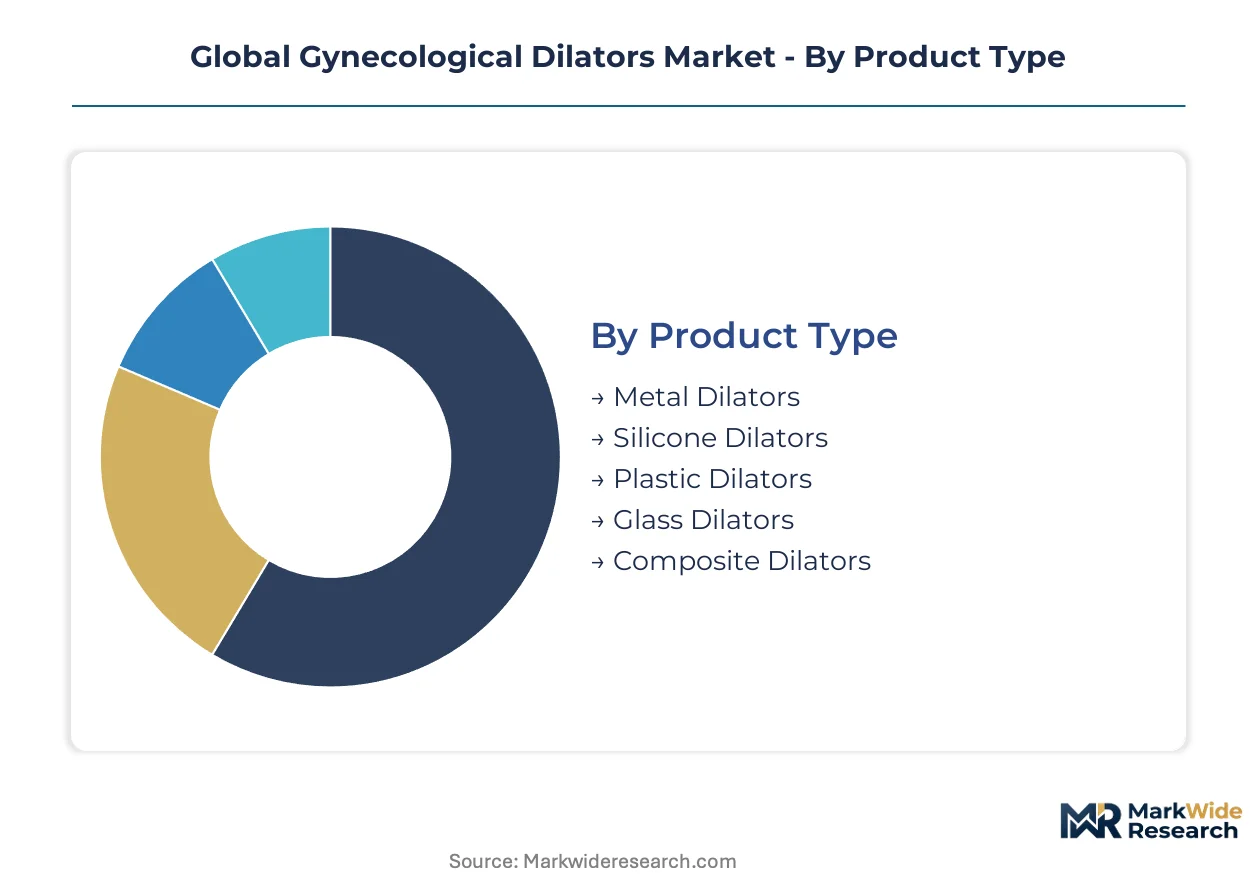
Material composition and sterilization economics split procurement channels across the Global Gynecological Dilators Market. Each segment category carries distinct margin profiles and regulatory burdens that reshape supplier qualification requirements.
Product Type:
Hospital procurement channels route metal instruments through reprocessing departments while silicone and plastic variants flow through disposable supply chains.
- Metal Dilators:Surgical-grade stainless steel construction delivers mechanical rigidity for procedures demanding precise tactile feedback. German and French academic medical centers anchor demand as legacy sterilization infrastructure sustains reusable workflows.
- Silicone Dilators:Biocompatible temperature-stable polymers command premium positioning in radiation therapy applications where tissue sensitivity limits metal contact. North American gynecology clinics drive volume as EU MDR protocols accelerate material transitions.
- Plastic Dilators:Autoclavable polymers offer cost-efficient single-use alternatives for high-volume ambulatory settings.
- Glass Dilators:Specialized optical-grade variants serve diagnostic hysteroscopy procedures requiring translucency.
- Composite Dilators:Hybrid constructions blend silicone comfort layers with rigid cores for post-surgical therapy regimens.
Metal dilators dominate installed base. Silicone dilators are where expansion concentrates.
Application:
Procedure reimbursement codes determine which applications absorb capital equipment versus disposable purchasing.
- Post-Surgical Therapy:Enhanced recovery after surgery protocols shift vaginal stenosis prevention to outpatient settings. Home-based dilation maintenance creates recurring revenue streams through patient-direct distribution channels.
- Radiation Therapy:Oncology departments specify biocompatible materials for patients with compromised tissue integrity. Japanese hospital tenders favor silicone variants meeting JIS T 0313 standards.
- Vaginal Stenosis:Pelvic floor rehabilitation centers standardize graduated dilation protocols.
- Cervical Dilation:Intrauterine procedure preparation drives metal instrument preference for haptic precision.
- Diagnostic Procedures:Hysteroscopy and biopsy workflows demand sterilization-validated instrument sets.
Cervical dilation anchors procedure volume. Post-surgical therapy represents the steepest expansion trajectory.
End User:
Customer scale dictates contract structure, with health systems negotiating enterprise pricing against fragmented clinic purchasing.
- Gynecology Clinics:Independent practices favor polymer disposables to avoid sterilization infrastructure investment. Texas and California buying committees embed ISO 13485 requirements into vendor qualification.
- Ambulatory Surgery Centers:Stricter EU MDR protocols in Germany and France accelerate single-use adoption as reprocessing economics deteriorate.
- Diagnostic Labs:Specimen collection workflows drive demand for sterile single-use sets.
- Postoperative Care Centers:Skilled nursing facilities manage home-transition dilation regimens.
Gynecology clinics dominate installed base. Ambulatory surgery centers are where expansion concentrates.
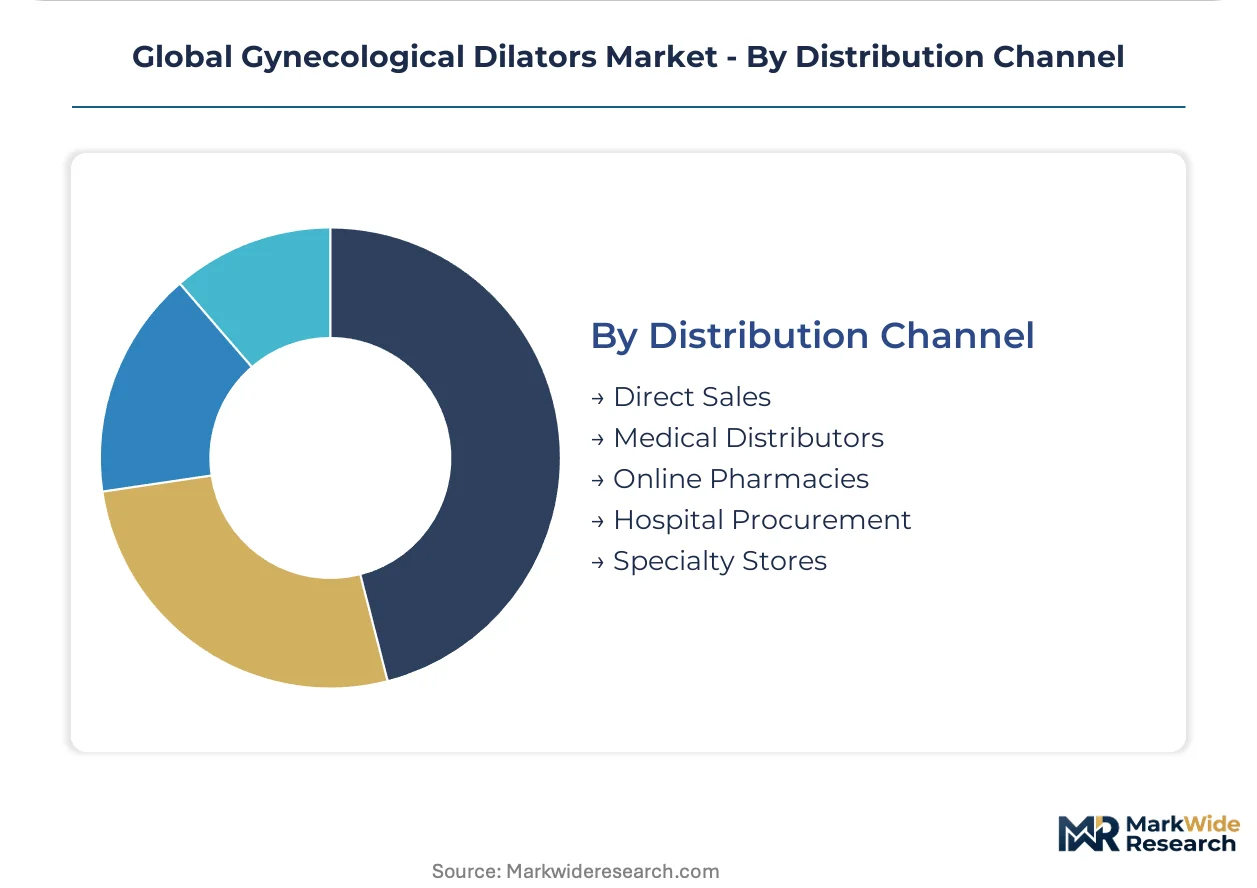
Distribution Channel:
Channel selection reflects customer sophistication, with direct sales serving complex health systems and distributors covering fragmented geographies.
- Hospital Procurement:Centralized buying committees in US health systems negotiate multi-year contracts with sterilization documentation requirements. Group purchasing organizations in California and Texas consolidate vendor pools.
- Medical Distributors:Regional networks cover independent clinics lacking dedicated supply chain staff.
- Direct Sales:Vertically integrated manufacturers bypass intermediaries for enterprise accounts.
- Online Pharmacies:Patient-direct channels serve home-based post-surgical therapy regimens.
- Specialty Stores:Pelvic health retail outlets cater to direct-to-consumer wellness segments.
Hospital procurement dominates contract value. Online pharmacies are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU MDR sterilization mandates are redrawing procurement hierarchies across European ambulatory networks while FDA 510(k) pathways accelerate polymer adoption in US outpatient settings. Japanese PMDA enforcement of JIS T 0313 standards creates asymmetric entry barriers for Western manufacturers. Hospital buying committees in Texas and California now embed ISO 13485 documentation requirements into contract templates.
United States
Group purchasing organizations in Texas and California consolidate vendor pools around sterilization documentation requirements. FDA 510(k) clearance pathways for polymer-based dilators enable faster market penetration against legacy metal portfolios. Academic medical centers in Boston and San Francisco pilot hybrid portfolios blending silicone comfort with stainless steel precision.
Germany
Academic medical centers anchor demand for surgical-grade stainless steel instruments as legacy sterilization infrastructure sustains reusable workflows. EU MDR technical documentation requirements extend conformity assessment timelines for reusable instruments. Hospital procurement channels in Bavaria and North Rhine-Westphalia expand orders for single-use silicone dilators as ambulatory surgery centers adopt stricter protocols.
France
Ambulatory surgery centers accelerate material transitions from reusable metal to single-use polymer dilators as reprocessing economics deteriorate. ANSM oversight of EU MDR implementation redistributes contract volumes toward vertically integrated sterilization providers. Medical device clusters in Île-de-France and Auvergne-Rhône-Alpes concentrate polymer manufacturing capacity.
Japan
Domestic suppliers leverage proximity to PMDA regulatory reviewers, compressing time-to-tender for East Asian hospital contracts. JIS T 0313 biocompatibility testing limits supplier qualification for hospital tenders. European manufacturers face 18-24 month validation cycles against 8-12 months for domestic competitors in the Kanto and Kansai regions.
India
CDSCO medical device regulations are harmonizing with international standards, opening procurement channels for ISO 13485-certified foreign suppliers. State-level health missions in Maharashtra and Karnataka expand gynecology clinic networks. Medical device manufacturing clusters in Gujarat and Tamil Nadu develop polymer processing capabilities for export markets.
Global Gynecological Dilators Market Competitive Landscape
Player mix skews toward vertically integrated sterilization providers and specialized stainless steel fabricators. The vendor base concentrates around manufacturers with captive quality management infrastructure. Three archetypes dominate: diversified surgical instrument conglomerates, single-use polymer specialists, and legacy metal instrument craftsmen. Competitive moves center on M&A to secure sterilization validation expertise and strategic partnerships to bypass regulatory entry barriers.
Within the diversified surgical instrument tier, CooperSurgical and Olympus occupy positions anchored by vertically integrated sterilization infrastructure. Sklar Corp exemplifies the specialized metal instrument archetype through its stainless steel craftsmanship heritage. Medgyn Products represents the polymer-focused specialist segment serving radiation therapy applications. These three companies illustrate how regulatory compliance capabilities now outweigh price positioning in hospital procurement decisions.
| Leading Market Players |
|---|
| Stingray Surgical Products |
| Surgical Holdings UK |
| Sklar Corp |
| CooperSurgical |
| Medgyn Products |
| Soul Source |
| Pelican Feminine Healthcare |
| Olympus |
| Velvi |
| Others |
Supply & Pricing Matrix
Capacity utilization at medical-grade silicone polymerization plants in Germany and Massachusetts shapes both supply concentration and price floors for polymer-based dilators. Scale advantages among ISO 13485-certified manufacturers create asymmetric pricing power against smaller competitors lacking captive sterilization infrastructure.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485, CE marking, and basic FDA registration grades respectively. Pricing pressure stems from medical-grade silicone cost volatility tied to petrochemical feedstock fluctuations. Ambulatory surgery centers in France and Germany demonstrate highest price sensitivity as EU MDR compliance costs erode reprocessing economics, while academic medical centers in Boston and San Francisco absorb premium tiers for hybrid metal-polymer portfolios.
Supply Chain Analysis
Just-in-time inventory strategies dominate hospital procurement channels as EU MDR technical documentation requirements compress order cycles. Manufacturing concentrates in Germany, Massachusetts, and Gujarat. Raw material flows draw from medical-grade silicone suppliers in Bavaria, surgical steel fabricators in Sheffield, and autoclavable polymer compounders in Tamil Nadu. Single-source vulnerability runs through specialized silicone polymerization capacity. Distribution runs through group purchasing organizations in Texas and California alongside regional medical distributors covering fragmented clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telehealth-integrated home therapy platforms are creating platform-economics inflection as remote patient monitoring ecosystems enable subscription-based dilation regimens beyond traditional device sales.
For Market Incumbents: Compound sterilization validation expertise through backward integration into polymer compounding or acquisition of EU MDR technical documentation specialists. ISO 13485 certification barriers are displacing price-only procurement evaluations, threatening margin compression for manufacturers lacking quality management infrastructure. Channel control through direct sales to health systems in California and Texas preserves contract renewal rates against distributor disintermediation. For New Entrants and Emerging Players: FDA 510(k) polymer pathways offer fastest regulatory clearance for autoclavable dilators targeting North American gynecology clinics. White-space concentrates in Japanese PMDA market entry where JIS T 0313 biocompatibility testing limits Western supplier qualification. Telehealth-integrated home therapy distribution bypasses entrenched hospital procurement channels for post-surgical maintenance regimens. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among polymer-based dilator manufacturers serving radiation therapy applications with patient-direct distribution. Long-term viability favors vertically integrated players with captive sterilization infrastructure and ISO 13485 certification. The signal to watch is EU MDR implementation timelines in Germany and France accelerating single-use adoption against reusable metal workflows.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Quality management documentation displaces price-only procurement evaluations in Texas and California GPO contracts. |
| EU MDR Technical Documentation Buildout | Conformity assessment capabilities capture contract volumes as German and French ASCs abandon reusable metal workflows. |
| FDA 510(k) Polymer Pathway Pursuit | Streamlined clearance accelerates market penetration against legacy stainless steel portfolios in US outpatient settings. |
| Telehealth Platform Integration | Remote patient monitoring creates subscription revenue streams for home-based post-surgical dilation maintenance. |
| Japanese PMDA Market Entry | JIS T 0313 compliance opens East Asian hospital tenders currently underserved by Western manufacturers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital procurement managers, biomedical engineers, GPO contracts specialists, and ambulatory surgery center administrators; and secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and customs trade data. Bottom-up and top-down triangulation reconciled segment-level volume estimates with aggregate market sizing.
Across the analysis window, forecasts applied multi-dimensional segmentation by material composition, application, end user, and distribution channel. CAGRs derived from procedure volume elasticity, material substitution rates, and regulatory compliance cost trajectories. Model inputs incorporated EU MDR implementation timelines, FDA 510(k) clearance velocity, and JIS T 0313 biocompatibility testing adoption.
Decision-makers should treat outputs as directional under assumptions of stable regulatory harmonization and silicone feedstock cost trajectories; material deviation would warrant model refresh. Revision becomes warranted when EU MDR sterilization protocol adoption crosses thresholds that fundamentally restructure reprocessing economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Breast Implants Market
Medical Devices
Global Anti-Snoring Device Market
Medical Devices
Vaginal Specula Market
Medical Devices
Global PC-Based Audiometer Market
Medical Devices
Intravaginal Device Market
Medical Devices
Global Stabilometric Platform Market
Medical Devices
United States Organ Preservation Market
Medical Devices
Global Pessary Market
Medical Devices
Radiotherapy Positioning Devices Market
Medical Devices
Radiotherapy Patient Positioning Accessories Market
Medical Devices
North America Pen Needles Market
Medical Devices
Disposable EEG Electrode Market
Medical Devices
Global Orthopedic Power Tools Market
Medical Devices
Partial Ossicular Replacement Prosthesis Market
Medical Devices
Spain Contraceptive Devices Market
Medical Devices
Wearable Atrial Fibrillation Detection Devices Market