
 Women's Health Market | 2026-2036
Women's Health Market Size, Share, and Industry Trends Forecast 2026-2036
Women's Health Market Intelligence
Biologics is pivoting from synthetic hormone platforms to recombinant and peptide-based formulations, compressing production costs while improving efficacy profiles. Pfizer leverages its manufacturing scale across multiple continents to sustain supply security for hormonal treatments. Eli Lilly and Company anchors its position through deep R&D investment in metabolic and reproductive endocrinology. Organon & Co. specializes in women's health portfolio concentration, competing against broader pharmaceutical conglomerates through channel focus.
Women's health encompasses medical products, diagnostic tools, and therapeutic interventions designed to address female-specific physiological conditions across reproductive, hormonal, and oncological domains. These offerings incorporate active pharmaceutical ingredients ranging from synthetic estrogens and progestins to monoclonal antibodies, formulated for oral, injectable, or implantable delivery with bioavailability parameters calibrated to female metabolic profiles. Hormonal Treatments command the largest revenue pool within Product Type segmentation due to chronic therapy duration and patent-protected formulations. Reproductive Health leads Application categories in absolute volume, though Menopause Management represents the fastest-expanding margin segment as aging demographics drive specialty care demand. Subscription Services within Delivery Mode are capturing recurring revenue streams by bundling fertility monitors with telehealth consultations.
FDA oversight of contraceptive and hormone therapy safety shapes clinical trial design and label expansion timelines, while EMA's evolving digital health framework influences connected fertility device market access across Europe. WHO prequalification standards for maternal health products determine procurement eligibility in low-resource settings, directing manufacturer investment toward affordable formulation development. Stakeholders must monitor regulatory divergence between FDA risk-based device classification and EU MDR requirements for software-as-medical-device to avoid fragmented compliance costs.
Market Dynamics
Hospital systems in the United States and Germany are consolidating women's health service lines into vertically integrated care networks, compressing procurement timelines and favoring suppliers with end-to-end platform capabilities over point-solution vendors.
Growth Catalysts
- FDA Digital Health Guidance:The agency's streamlined pre-certification pathway for software-as-medical-device is accelerating connected fertility monitor approvals, reducing time-to-market for sensor-telehealth bundles.
- Peptide Manufacturing Scale-Up:Recombinant hormone production platforms are achieving cost parity with synthetic formulations, enabling chronic therapy pricing that expands addressable patient populations.
- Direct-to-Consumer Channels:Telehealth platforms in the United States are bypassing traditional clinic gatekeepers, capturing recurring subscription revenue for menopause management and contraceptive counseling.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Over 70 percent of estradiol and progestin raw material supply originates from Chinese chemical manufacturers, creating geopolitical exposure for formulated product stability.
- EMA MDR Compliance Burden:The Medical Device Regulation's enhanced clinical evidence requirements for connected diagnostic devices are extending EU market access timelines by 18-24 months for fertility tracking hardware.
- Biosimilar Erosion:Off-patent hormone therapies face pricing pressure from follow-on biologics, compressing margins for originator manufacturers in menopause and contraceptive segments.
Strategic Opportunities
- India Preventive Care Expansion:The country's national health mission is expanding screening infrastructure for cervical and breast oncology, creating procurement demand for diagnostic devices and HPV therapeutics.
- Continuous Glucose Monitoring Convergence:Integration of metabolic sensors with reproductive health platforms is opening adjacent revenue streams for polycystic ovary syndrome and gestational diabetes management.
- Employer-Sponsored Benefit Design:Large self-insured employers in the United States are carving out dedicated women's health benefits, creating direct contracting opportunities that bypass traditional payer intermediaries.
Industry Challenges
- Reproductive Endocrinology Specialist Scarcity:Fellowship-trained clinicians concentrate in academic medical centers, limiting specialty care access in community hospital settings and constraining service line expansion.
- Multi-Jurisdictional Label Harmonization:Divergent FDA and EMA requirements for hormone therapy cardiovascular safety endpoints force parallel clinical programs, inflating development costs for global launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Women's Health Market |
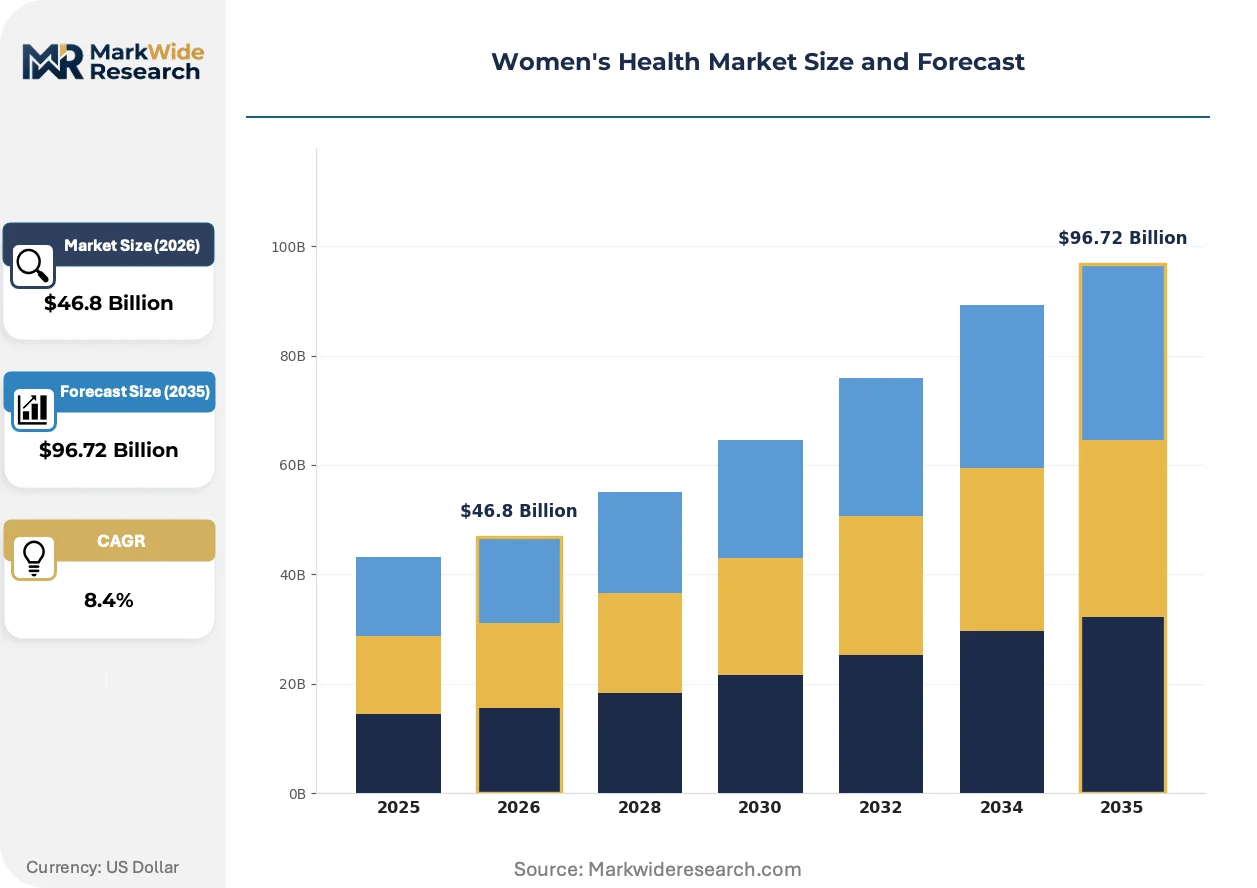
| Market Size in 2026 | $46.8 Billion |
| Market Size in 2035 | $96.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Menstrual Products, Fertility Monitors, Hormonal Treatments, Nutritional Supplements Application: Reproductive Health, Maternal Care, Contraceptive Solutions, Menopause Management End User: Clinics, Pharmacies, Hospitals, Health Centers Delivery Mode: Retail, Online, Direct-to-Consumer, Subscription Services |
| Companies Covered | Pfizer, Bayer AG, AbbVie, Organon & Co., Amgen, Roche, Boston Scientific Corporation, Eli Lilly and Company, Merck & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Women's Health Market Strategic Shifts & Innovations
Biologics manufacturing and connected diagnostic hardware are converging to reshape therapeutic delivery models, with regulatory frameworks racing to catch up to real-world evidence generation capabilities.
Continuous hormone monitoring patches are rewriting chronic disease management protocols. These wearable biosensors track estradiol and progesterone levels in real-time, enabling fertility clinics to optimize in-vitro fertilization protocols with precision dosing adjustments. The technology is compressing the gap between laboratory diagnostics and therapeutic intervention, reducing cycle cancellation rates.
REACH chemical registration requirements are forcing reformulation of excipients in transdermal delivery systems. European manufacturers must substitute legacy plasticizers and adhesives with compliant alternatives, triggering supply chain requalification for menopause patches and contraceptive rings. Fertility device assemblers in Germany and the Netherlands are accelerating supplier audits to preempt authorization gaps.
Subscription bundling is displacing transactional device sales in fertility management. Consumers now expect hardware-software-service packages with unlimited telehealth consultations, forcing traditional diagnostic manufacturers to build recurring revenue infrastructure. This shift is most visible in United States direct-to-consumer channels, where annual contract value now exceeds per-unit device margin by 4-6x.
Women's Health Market Segmentation
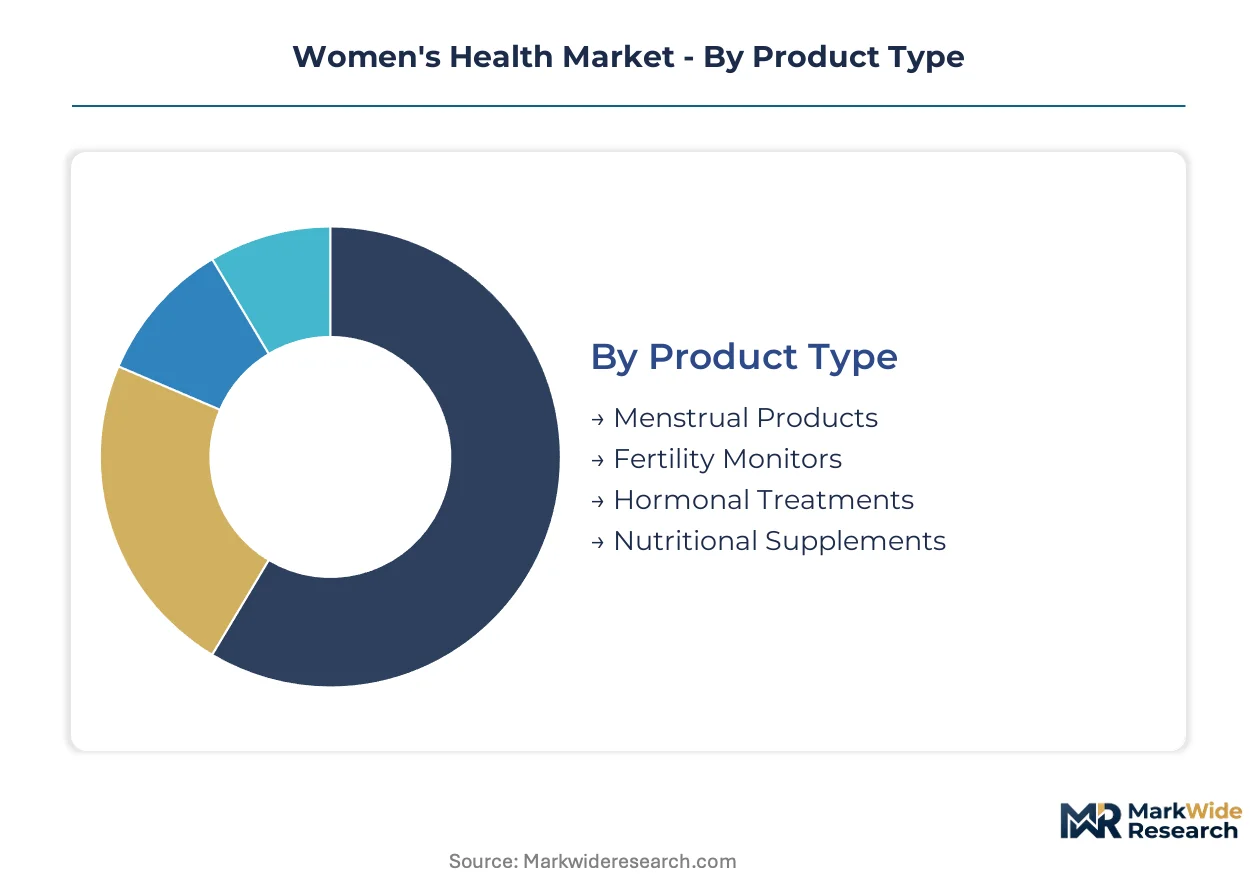
Product specification and delivery modality determine competitive positioning in women's health. Each segmentation axis reveals distinct margin profiles and regulatory exposure, shaping how manufacturers allocate R&D and distribution resources.
Product Type:
Formulation chemistry and bioavailability engineering separate segments by manufacturing complexity and patent protection durability.
- Hormonal Treatments:Recombinant peptide and synthetic estrogen-progestin formulations dominate chronic therapy revenue. Patent-protected delivery mechanisms—implants, intrauterine systems, and transdermal patches—command premium pricing in United States integrated care networks where long-acting reversible contraception protocols are expanding.
- Fertility Monitors:Connected sensor-software platforms track basal body temperature, luteinizing hormone surges, and cervical mucus impedance. FDA pre-certification pathways are accelerating United States market entry for smartphone-integrated hardware, while EMA MDR compliance extends European timelines.
- Menstrual Products:Absorbent materials and silicone-based collection devices address hygiene management across income tiers.
- Nutritional Supplements:Prenatal vitamin and mineral formulations target gestational and perimenopausal micronutrient replacement.
Mature deployment sits with Hormonal Treatments. Newer deployment is concentrated in Fertility Monitors.
Application:
Clinical endpoint severity and therapy duration determine reimbursement tiering and prescriber specialty requirements.
- Reproductive Health:Fertility preservation, ovulation induction, and assisted reproductive technology support span diagnostic workup through embryo transfer. Academic medical centers in the United States and Germany concentrate subspecialist capacity, constraining community access.
- Menopause Management:Vasomotor symptom relief and bone density preservation drive hormone therapy and selective serotonin reuptake inhibitor prescribing. Direct-to-consumer telehealth channels in the United States are capturing recurring consultation revenue for symptom monitoring and dose titration.
- Maternal Care:Prenatal screening, gestational diabetes management, and delivery preparation span trimester-specific interventions.
- Contraceptive Solutions:Long-acting, short-acting, and emergency formulations address compliance and reversibility preferences across age cohorts.
Volume concentration remains in Reproductive Health. Margin expansion is climbing the fastest in Menopause Management.
End User:
Procurement scale and clinical decision-making authority shape pricing negotiation leverage and formulary placement.
- Hospitals:Vertically integrated women's health service lines in the United States and Germany consolidate device and pharmaceutical purchasing, favoring suppliers with platform breadth over point-solution vendors. Value-based care contracts are tightening outcome accountability for maternal and oncological episodes.
- Clinics:Outpatient reproductive endocrinology and gynecology practices concentrate high-margin procedure volume. Fellowship-trained specialist scarcity in community settings limits service line expansion outside academic corridors.
- Pharmacies:Retail and specialty dispensaries manage acute prescription fulfillment and over-the-counter self-care categories.
- Health Centers:Federally qualified and rural facilities address access gaps through sliding-scale and grant-supported delivery models.
Procurement authority centralizes with Hospitals. Patient access expansion is concentrating in Clinics.
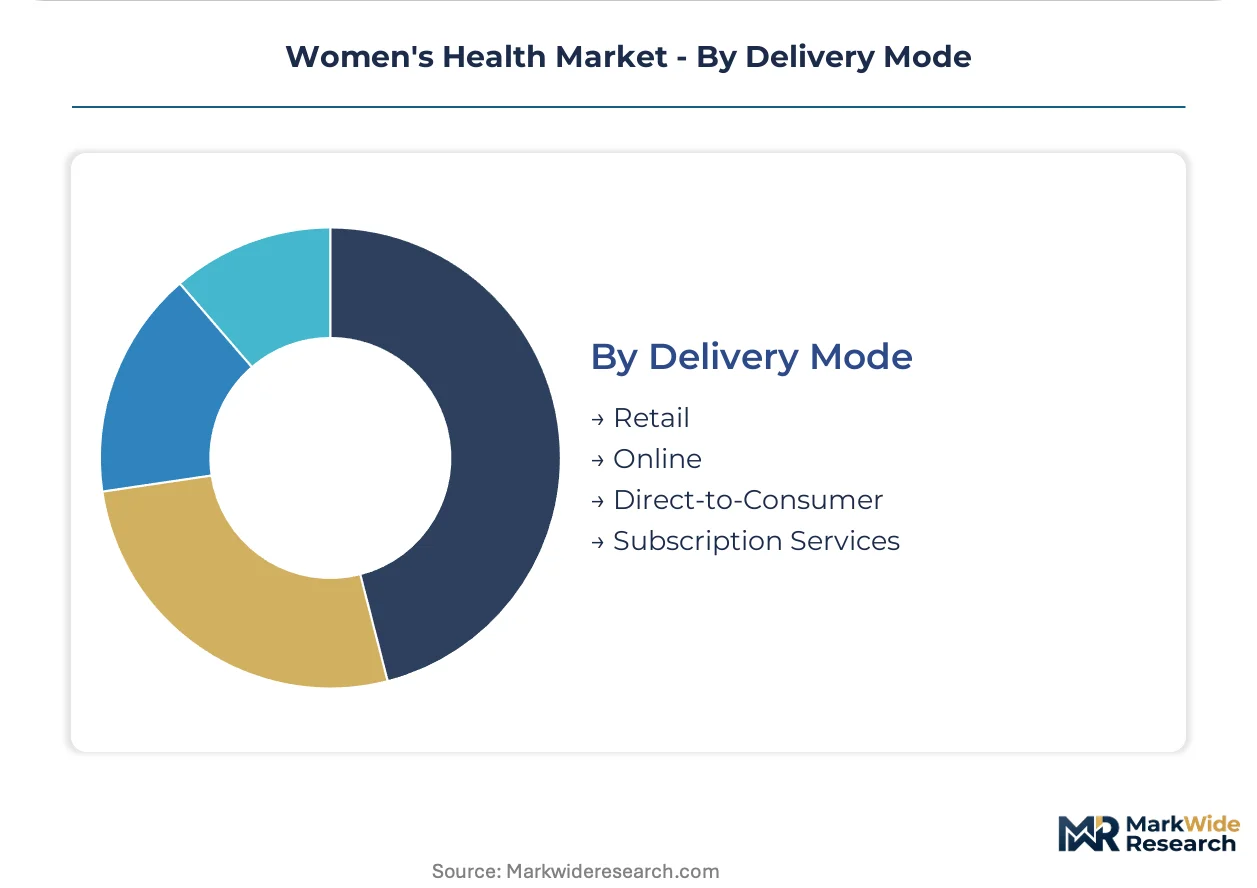
Delivery Mode:
Channel economics and customer acquisition cost structures determine margin retention and lifetime value capture.
- Subscription Services:Hardware-software-service bundles with unlimited telehealth consultations are displacing transactional device sales. Annual contract value in United States direct-to-consumer channels now exceeds per-unit device margin by multiples, forcing traditional manufacturers to build recurring revenue infrastructure.
- Direct-to-Consumer:Telehealth platforms bypass traditional clinic gatekeepers for menopause management and contraceptive counseling. HIPAA compliance and state-level prescribing regulations fragment operational scalability across United States jurisdictions.
- Online:E-commerce marketplaces and pharmacy portals enable price comparison and discrete purchasing for sensitive categories.
- Retail:Brick-and-mortar pharmacies and big-box stores maintain immediate fulfillment convenience for standard formulations.
Established volume flows through Retail. Revenue model innovation is gaining share fastest in Subscription Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for women's health products concentrates in the United States, where integrated care networks and direct-to-consumer channels scale fastest. Hospital systems in Germany and the United Kingdom are consolidating service lines into vertically integrated networks. Emerging procurement demand is surfacing in India as national screening infrastructure expands.
United States
FDA's streamlined pre-certification pathway for software-as-medical-device accelerates connected fertility monitor approvals. Direct-to-consumer telehealth platforms bypass traditional clinic gatekeepers for menopause management and contraceptive counseling. The Greater Boston corridor hosts concentrated reproductive endocrinology research capacity.
Germany
EMA's Medical Device Regulation extends EU market access timelines for fertility tracking hardware by 18-24 months. Hospital systems consolidate women's health service lines into vertically integrated care networks favoring platform suppliers. The Baden-Württemberg region anchors medical device manufacturing clusters for diagnostic hardware.
United Kingdom
NHS long-term plan targets expansion of maternal and reproductive health service access through community hubs. MHRA post-Brexit regulatory divergence from EMA creates parallel compliance requirements for hormone therapy labeling. London's academic medical centers concentrate subspecialist fellowship training capacity.
India
The national health mission expands screening infrastructure for cervical and breast oncology, creating procurement demand for diagnostic devices. CDSCO regulatory harmonization with WHO prequalification standards determines maternal health product eligibility. Maharashtra's pharmaceutical manufacturing belt supplies affordable hormone formulation exports.
Japan
PMDA's evolving framework for digital therapeutics influences connected fertility device market access timelines. Aging demographics drive specialty care demand for menopause management interventions. The Kanto region's medical device clusters concentrate sensor-telehealth bundle development.
Women's Health Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with formulation chemistry expertise commanding premium positioning in hormonal treatments while hardware assemblers compete on scale. The vendor base organizes around three archetypes: diversified pharmaceutical conglomerates with manufacturing scale, portfolio-dedicated women's health specialists, and emerging sensor-software platform builders. Consolidation favors suppliers with end-to-end capabilities over point-solution vendors. Competitive moves concentrate on M&A for platform breadth and backward integration into peptide manufacturing.
Among diversified pharmaceutical conglomerates, Pfizer exemplifies manufacturing scale across multiple continents for supply security. Eli Lilly and Company anchors deep R&D investment in metabolic and reproductive endocrinology. Organon & Co. occupies a position as the portfolio-dedicated specialist competing through channel focus against broader competitors.
| Leading Market Players |
|---|
| Pfizer |
| Bayer AG |
| AbbVie |
| Organon & Co. |
| Amgen |
| Roche |
| Boston Scientific Corporation |
| Eli Lilly and Company |
| Merck & Co. |
| Others |
Cost & Logistics Intelligence
Hospital procurement consolidation across the United States and Germany is compressing vendor margins and forcing suppliers toward platform breadth over point solutions, which in turn drives backward integration into peptide manufacturing to defend pricing power. REACH chemical registration requirements for transdermal delivery systems are triggering excipient reformulation costs that suppliers must absorb or pass through to maintain formulary placement.
Pricing Analysis
Volume concentrates in transactional device sales while margin expansion sits with subscription-based hardware-software-service bundles. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared fertility monitors from CE-marked alternatives and unregulated wellness trackers. Cost compression in menopause hormone therapies is intensifying because biosimilar erosion accelerates pricing pressure on originator formulations. Price-sensitive buyers cluster in retail pharmacy channels for over-the-counter menstrual products, while integrated care networks show lowest sensitivity for long-acting reversible contraception procurement.
Supply Chain Analysis
Specialized workforce availability in peptide synthesis constrains manufacturing expansion in Ireland and Switzerland, where recombinant hormone production clusters concentrate. Active pharmaceutical ingredient supply draws from Chinese chemical manufacturers for estradiol and progestin raw materials, German specialty chemical firms for transdermal adhesives, and Indian pharmaceutical exporters for generic hormone formulations. Single-source vulnerability in Chinese API supply creates geopolitical exposure for formulated product stability. Distribution runs through vertically integrated hospital networks in North America and specialty pharmacy channels for direct-to-consumer telehealth platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation momentum favors suppliers with end-to-end platform capabilities as hospital procurement centralization and regulatory compliance burdens squeeze point-solution vendors from competitive consideration.
For Market Incumbents: Anchor manufacturing scale across multiple continents to sustain supply security for hormonal treatments against API concentration risk. Deepen R&D investment in metabolic and reproductive endocrinology to extend patent-protected delivery mechanisms. Build recurring revenue infrastructure for subscription bundling before traditional diagnostic margins erode completely. For New Entrants and Emerging Players: Direct-to-consumer telehealth channels offer the most penetrable route for menopause management and contraceptive counseling bypassing clinic gatekeepers. Target employer-sponsored benefit carveouts in the United States where self-insured plans seek direct contracting opportunities. Pursue FDA pre-certification pathway for software-as-medical-device to accelerate connected fertility monitor market entry. For Investors and Strategic Acquirers: Re-rating potential sits with portfolio-dedicated women's health specialists given their channel focus against broader pharmaceutical conglomerates. Long-term viability hinges on capturing recurring revenue streams through sensor-telehealth bundles rather than transactional hardware sales. Watch for EMA MDR compliance completion as inflection indicator for European market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Peptide Manufacturing | Captive supply of recombinant hormone APIs reduces Chinese API dependency for European formulators. |
| FDA Pre-Certification Pathway Execution | Streamlined software-as-medical-device approval accelerates connected fertility monitor time-to-market. |
| Hospital System Partnership | Vertically integrated care network procurement favors suppliers with platform breadth over point solutions. |
| Subscription Service Infrastructure Build | Recurring revenue capture exceeds per-unit device margin by multiples in United States direct-to-consumer channels. |
| EMA MDR Compliance Completion | Enhanced clinical evidence requirements determine EU market access timelines for fertility tracking hardware. |
Research Approach
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone for regulatory pathway and pipeline validation. Primary interviews with reproductive endocrinologists, hospital procurement managers, formulary directors, and telehealth platform executives combined with secondary validation through hospital procurement databases and GPO contracts. Bottom-up segmentation modeling and top-down macro trend triangulation anchored volume and value estimates.
Historical trendline analysis across therapeutic category revenue and device shipment patterns informed baseline trajectory assumptions. Segmentation dimensions modeled include product type, application, end user, and delivery mode across the projection horizon. CAGRs were derived from fitted growth curves applied to segment-level baselines. Forecast inputs incorporated regulatory approval timelines, reimbursement policy shifts, and demographic aging patterns.
The model holds under stable regulatory harmonization and continued hospital consolidation; deviation in API supply disruption or EMA-FDA label divergence would shift trajectory assumptions. Forecasts reflect documented assumptions about patient population growth and therapy adherence rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Women's Health
US Womens Health Market
Women's Health
Dysmenorrhea Treatment Market
Women's Health
Dysfunctional Uterine Bleeding Market
Women's Health
Women Health Devices Market
Women's Health
Postmenopausal Vaginal Atrophy Treatment and Drug Market
Women's Health
Women Health Care Market
Women's Health
Menopause Market
Women's Health
Workplace Menstrual Health Benefits Platform Market
Women's Health
Maternal Health Market
Women's Health
Global Menopausal Hot Flashes Market
Women's Health
Women Health Disease Diagnosis and Treatment Market
Women's Health
Mother and Child Healthcare Market
Women's Health
Women Health Software Market
Women's Health
Women's Digital Health Market
Women's Health
North America Womens Health Diagnostics Market
Women's Health
Women's Health App Market