
 South America Mammography Market | 2026-2036
South America Mammography Market Size, Share, and Industry Trends Forecast 2026-2036
South America Mammography Market Analytics
Aftermarket service revenue is tilting toward software upgrades and remote diagnostics as hardware margins compress. GE Healthcare leverages its installed base across Brazilian public hospitals to sustain recurring service contracts. Hologic Inc. anchors its position through specialized 3D tomosynthesis platforms. Siemens Healthineers competes on manufacturing scale for digital mammography systems deployed through regional distributors.
Mammography encompasses X-ray-based breast imaging systems designed to detect microcalcifications and masses at resolutions below 0.1 millimeter, serving primarily as a screening and diagnostic modality for early-stage breast cancer detection. Digital systems now dominate new procurement cycles while 3D tomosynthesis captures the fastest-growing technology slot as radiologists prioritize lesion localization accuracy. Screening applications absorb the largest volume share across hospitals and diagnostic centers, though research-oriented installations remain concentrated at university-affiliated imaging centers in São Paulo and Buenos Aires.
ANVISA governs medical device registration and post-market surveillance in Brazil, while Argentina's national pharmaceutical regulator enforces comparable technical standards for imaging equipment importation. Both frameworks mandate clinical performance validation that shapes product approval timelines and shapes vendor market access strategies. Stakeholders must monitor regulatory harmonization progress across Mercosur member states to anticipate simplified cross-border certification pathways.
Market Dynamics
The South America mammography market pivots on ANVISA's accelerated digital system approval pathways, which compress vendor entry timelines and reshape competitive positioning among equipment suppliers serving Brazilian public health networks.
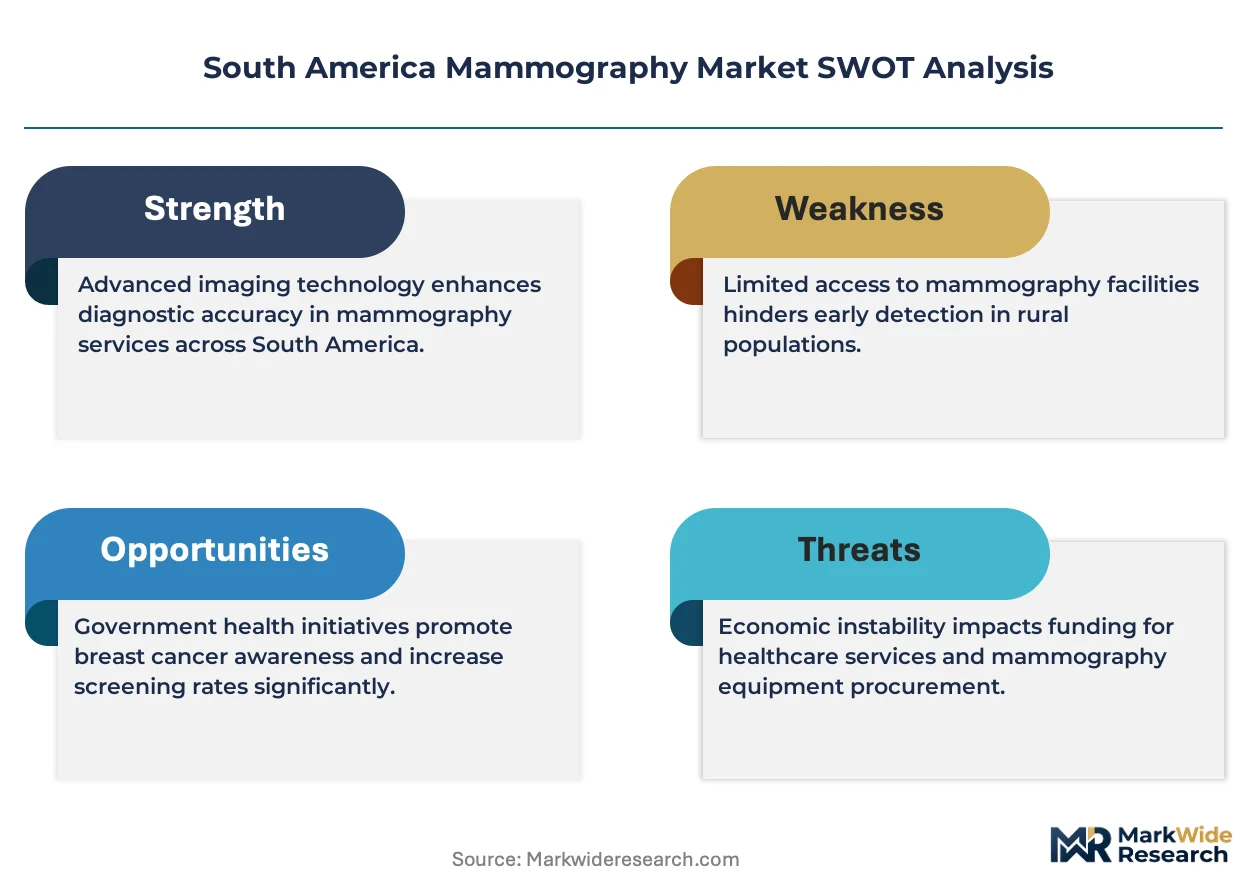
Growth Catalysts
- ANVISA Streamlined Registration:Brazil's medical device regulator has reduced digital mammography system approval timelines, enabling faster deployment of advanced imaging platforms into public hospital networks.
- Diagnostic Center Expansion:Private imaging chains across São Paulo and Rio de Janeiro are scaling screening programs, creating concentrated demand pull for high-throughput systems.
- 3D Tomosynthesis Migration:Radiologists are prioritizing lesion localization accuracy, driving replacement cycles from 2D digital systems toward volumetric breast imaging platforms.
Market Restraints
- Import Tariff Burden:Imaging equipment faces substantial customs duties across Mercosur member states, inflating landed costs for digital mammography systems by 25-40% above manufacturer pricing.
- Single-Source Detector Supply:Amorphous selenium and cesium iodide flat-panel detectors concentrate production in East Asian manufacturing clusters, exposing South American vendors to supply chain disruption risk.
- Specialized Technician Scarcity:Certified mammography technologists remain concentrated in Brazil's southeast region, constraining screening program expansion into northern and central states.
Strategic Opportunities
- Argentine Provincial Penetration:Buenos Aires and Córdoba provinces maintain underdeveloped screening infrastructure relative to population density, presenting first-mover positioning for mobile mammography unit deployment.
- Remote Diagnostics Integration:Cloud-based image transmission paired with AI-assisted preliminary read workflows enables teleradiology services connecting rural clinics to specialized breast imaging centers.
- Mercosur Harmonization:Pending regulatory alignment across member states would enable single-approval market access spanning Brazil, Argentina, Paraguay, and Uruguay, reducing certification duplication costs.
Industry Challenges
- Legacy System Interoperability:PACS integration requirements vary across Brazilian state health systems, forcing vendors to maintain multiple software interface configurations.
- Extended Payback Periods:Public hospital procurement cycles stretch 18-36 months from tender to installation, compressing vendor cash conversion and inflating working capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Mammography Market |
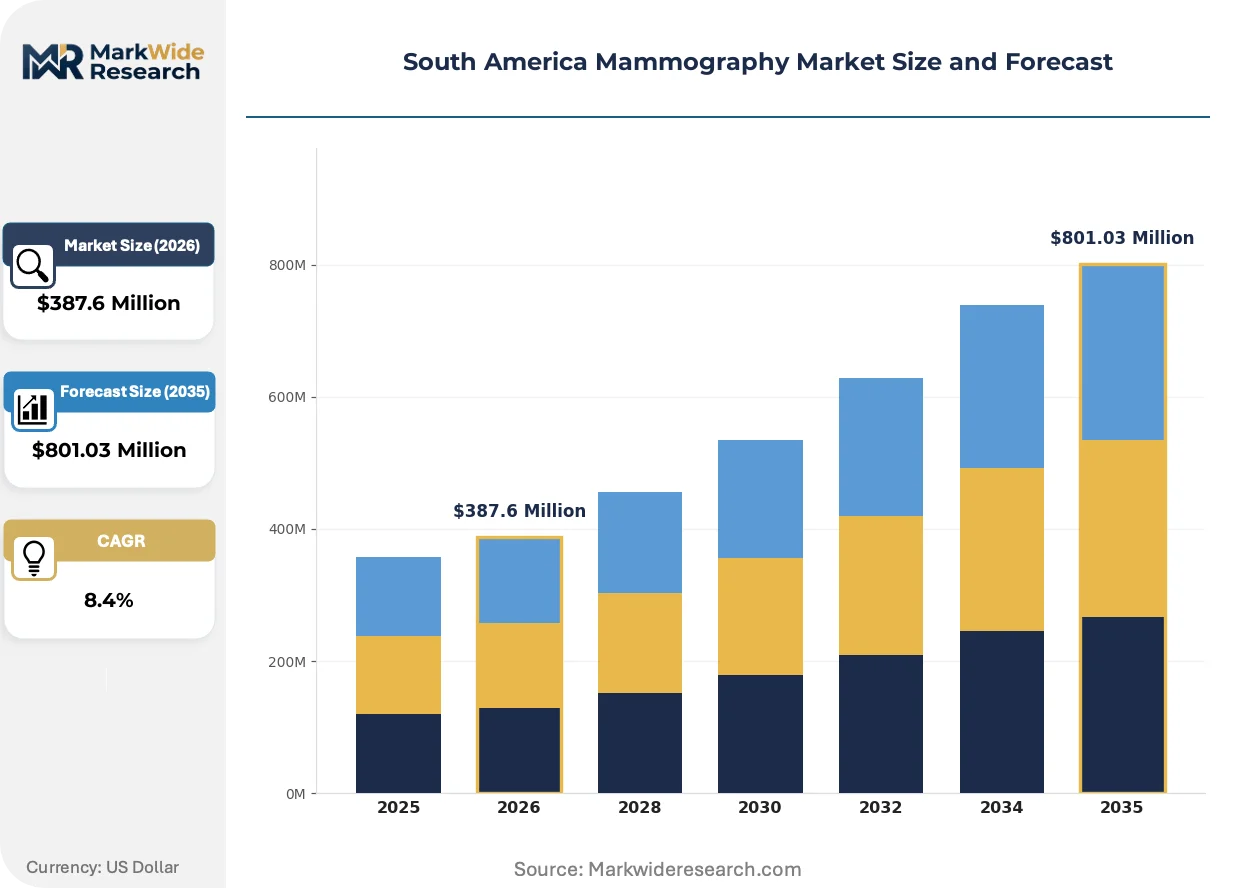
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $801.03 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Systems, Digital Systems, 3D Systems, Full-Field Systems End User: Hospitals, Diagnostic Centers, Clinics, Imaging Centers Technology: X-Ray, Tomosynthesis, MRI, Ultrasound Application: Screening, Diagnosis, Research, Follow-up |
| Companies Covered | GE Healthcare, Hologic Inc., Siemens Healthineers, Fujifilm Holdings Corporation, Canon Medical Systems Corporation, Koninklijke Philips NV, Planmeca Group, IMS Giotto SpA, Konica Minolta Inc., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Mammography Market Evolving Landscape
Digital breast tomosynthesis is rendering film-based and basic 2D digital systems obsolete across South American screening programs. Three concurrent developments are compressing technology adoption cycles and reshaping vendor competitive requirements.
Contrast-enhanced mammography is rendering obsolete conventional diagnostic workup protocols for dense breast tissue evaluation. Breast imaging centers in São Paulo are adopting dual-energy subtraction techniques to reduce false-positive callbacks. The structural consequence is compression of supplemental MRI utilization for high-risk patient stratification, redirecting capital toward angiographic-capable mammography platforms.
ANVISA's post-market surveillance requirements now mandate adverse event reporting for digital mammography systems at 6-month intervals rather than annual submissions. Equipment vendors must maintain localized quality management systems with Portuguese-language documentation. Brazilian public hospital procurement committees are prioritizing suppliers with established in-country service infrastructure over direct-import arrangements.
Radiologist reading workflows are consolidating toward centralized breast imaging centers with subspecialized expertise. Diagnostic chains are unbundling equipment ownership from interpretation services, creating equipment-as-service contracting models. This pattern concentrates most visibly in Brazil's southeast region, where multi-site networks deploy standardized tomosynthesis platforms with remote quality assurance monitoring.
South America Mammography Market Segmentation
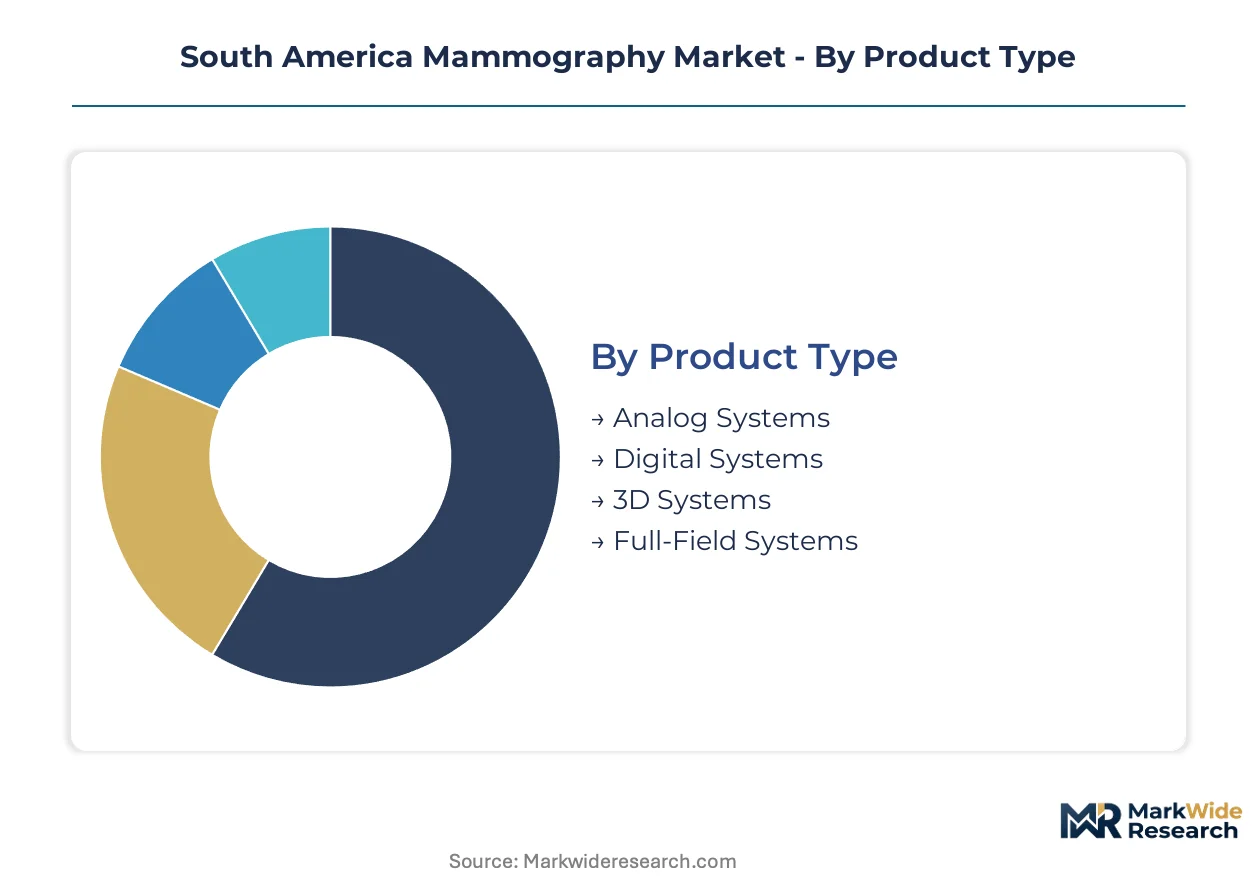
Equipment configuration and service intensity vary sharply across segment boundaries in South America. Procurement committees weigh detector replacement cycles, software licensing terms, and technician training requirements differently for each category.
Product Type:
After-sales service intensity escalates with detector complexity and software dependency, tilting vendor economics toward multi-year maintenance contracts rather than upfront equipment margins.
- Digital Systems:Flat-panel detectors using amorphous selenium or cesium iodide scintillators deliver 50-micron spatial resolution with immediate image availability. Brazilian public hospitals in São Paulo and Rio de Janeiro anchor replacement demand as 2D film-based systems reach end-of-life.
- 3D Systems:Volumetric breast tomosynthesis acquires multiple projection angles across a 15-50 degree arc, reconstructing depth-resolved slices that reduce tissue overlap artifacts. Diagnostic centers across Argentina's Buenos Aires province prioritize these platforms for dense breast evaluation protocols.
- Analog Systems:Screen-film cassettes and wet chemistry processing persist in underfunded municipal clinics.
- Full-Field Systems:Large-field detectors accommodate stereotactic biopsy guidance without patient repositioning.
By volume, Digital Systems leads. By growth pace, 3D Systems is ahead.
End User:
Capital deployment cycles and reimbursement structures diverge across facility types, with private diagnostic chains operating on 3-5 year refresh timelines versus public hospital 7-10 year cycles.
- Diagnostic Centers:Specialized breast imaging facilities concentrate high-throughput screening workflows with dedicated mammography technologists and subspecialized radiologists. São Paulo's private imaging chains drive demand for premium tomosynthesis platforms with AI-assisted reading workstations.
- Hospitals:Integrated health systems combine screening programs with surgical oncology and radiation therapy services, requiring PACS interoperability and multidisciplinary tumor board connectivity. ANVISA procurement regulations govern equipment selection across Brazil's Sistema Único de Saúde networks.
- Imaging Centers:Multi-modality facilities balance mammography against MRI, CT, and ultrasound service lines.
- Clinics:Small-scale practices focus on symptomatic diagnostic workups rather than population screening.
Diagnostic Centers capture the largest installed base. Hospitals show the steepest expansion trajectory for new procurement.
Technology:
Physics-based imaging tradeoffs between spatial resolution, tissue contrast, and radiation dose shape modality selection for specific clinical indications.
- Tomosynthesis:Synthetic mammography reconstruction from volumetric data reduces callback rates for dense breast tissue evaluation. Argentine radiology groups in Córdoba province are adopting these platforms as standard of care for diagnostic workups.
- X-Ray:Conventional projection mammography remains the workhorse for population screening programs due to lower per-exam cost and established quality assurance protocols. Brazil's southeast region screening networks rely on digital X-ray systems for high-volume throughput.
- Ultrasound:Operator-dependent handheld imaging serves as adjunctive modality for cyst characterization and biopsy guidance.
- MRI:Contrast-enhanced magnetic resonance imaging addresses high-risk patient surveillance and implant evaluation.
X-Ray dominates screening volume. Tomosynthesis is gaining share fastest in diagnostic applications.
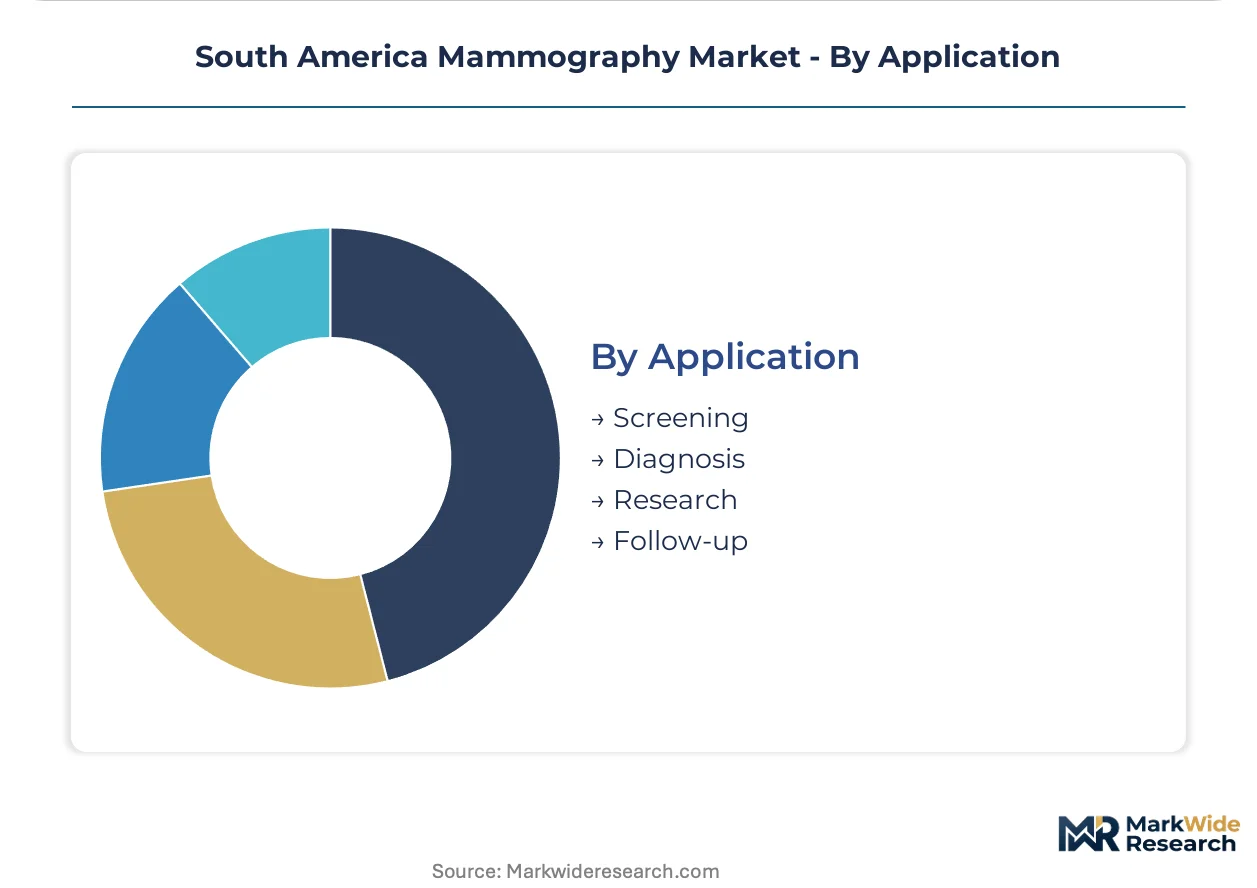
Application:
Reimbursement codes and clinical protocols stratify equipment requirements across the care continuum from asymptomatic screening to treatment monitoring.
- Screening:Population-based early detection programs require high-throughput systems with automated exposure control and rapid image acquisition to minimize patient motion artifacts. Brazil's southeast region public health initiatives concentrate demand for screening-optimized platforms.
- Diagnosis:Symptomatic evaluation and callback workups demand diagnostic mammography with magnification views, spot compression, and tomosynthesis capability. Argentine breast imaging centers prioritize lesion characterization accuracy to reduce unnecessary biopsies.
- Follow-up:Post-treatment surveillance monitors surgical bed changes and contralateral breast status.
- Research:Academic medical centers deploy specialized protocols for imaging biomarker development and AI training dataset generation.
Screening absorbs the highest equipment volume. Diagnosis commands the premium pricing tier per system configuration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across South America, with Argentine provincial buyers demanding flexible financing while Brazilian southeastern hospitals absorb premium tomosynthesis systems without volume discounts. This elasticity gradient shapes vendor go-to-market strategies and service bundling approaches.
Brazil
Southeastern diagnostic chains in São Paulo and Rio de Janeiro drive replacement demand for 3D tomosynthesis platforms. ANVISA's streamlined digital system approvals compress vendor entry timelines from 18 months to under 12 months. The São Paulo metropolitan corridor concentrates over half of national mammography installed base, with private imaging networks standardizing on high-throughput screening configurations.
Argentina
Buenos Aires and Córdoba provinces present underdeveloped screening infrastructure relative to their population density, creating first-mover opportunities for mobile unit deployment. The national pharmaceutical regulator enforces clinical performance validation standards that parallel Brazil's technical requirements. Metropolitan Buenos Aires anchors diagnostic demand, though provincial penetration lags due to reimbursement fragmentation across regional health systems.
Chile
Santiago's public health networks are expanding population-based screening coverage under national cancer control program mandates. The country's medical device regulatory framework emphasizes ISO 13485 quality management certification for equipment importation. Northern mining regions exhibit equipment scarcity, with Calama and Antofagasta relying on quarterly mobile screening visits rather than fixed installations.
Colombia
Bogotá and Medellín hospital networks are modernizing breast imaging capabilities through public-private partnership procurement models. The national health regulator mandates adverse event reporting for imaging equipment that shapes post-market surveillance obligations for vendors. Caribbean coastal cities including Barranquilla show rising diagnostic center formation, though technician certification programs remain concentrated in the Andean highlands.
Peru
Lima's oncology institutes are prioritizing contrast-enhanced mammography for dense breast tissue evaluation protocols. The country's decentralized health system creates procurement complexity across regional government units. Arequipa and Trujillo secondary cities exhibit growing private diagnostic investment, though public hospital budget cycles stretch equipment replacement timelines beyond seven years.
South America Mammography Market Competitive Landscape
Capability concentration sits with specialized imaging technology developers; scale advantage sits with diversified health conglomerates with established service networks. The South America mammography market structures around three tiers: multinational equipment manufacturers with full modality portfolios, regional distributors with deep installation and maintenance capabilities, and niche specialists in breast imaging software and AI-assisted detection. Consolidation pressure favors players with localized service infrastructure over direct-import arrangements, while procurement committees increasingly weight total cost-of-ownership against upfront equipment pricing.
Among the diversified medical technology conglomerates, GE Healthcare, Hologic Inc., and Siemens Healthineers occupy positions defined by installed base scale and recurring service contract penetration. GE Healthcare exemplifies the service-anchored archetype through its Brazilian public hospital relationships. Hologic Inc. represents specialized breast imaging focus with concentrated 3D tomosynthesis positioning. Siemens Healthineers sits within the manufacturing-scale tier competing through regional distributor deployment of digital mammography platforms.
| Leading Market Players |
|---|
| GE Healthcare |
| Hologic Inc. |
| Siemens Healthineers |
| Fujifilm Holdings Corporation |
| Canon Medical Systems Corporation |
| Koninklijke Philips NV |
| Planmeca Group |
| IMS Giotto SpA |
| Konica Minolta Inc. |
| Others |
Value Network & Pricing Analysis
East Asian flat-panel detector manufacturing clusters in Taiwan, South Korea, and Japan anchor component supply for South American mammography systems, concentrating margin capture upstream while Brazilian and Argentine distributors compete on financing flexibility and service bundling downstream.
Pricing Analysis
Multi-year service and software upgrade contracts now drive lifetime value capture, displacing upfront equipment margins as the primary revenue pool. Three-tier pricing structure across premium tomosynthesis, standard digital, and economy analog configurations stratifies the market, with ANVISA certification tiers and after-sales service bundling as the primary differentiation levers. Pricing pressure stems from compressed hardware margins as detector commoditization accelerates. Public hospital procurement committees in Brazil's Sistema Único de Saúde networks exhibit highest price sensitivity, while private diagnostic chains in São Paulo absorb premium configurations with less volume discount pressure.
Supply Chain Analysis
Contract manufacturing for digital mammography systems concentrates with specialized medical imaging OEMs in Germany, the United States, and Japan, with final assembly often performed at regional hubs serving Latin America. Amorphous selenium and cesium iodide scintillators draw from East Asian chemical processing facilities, while precision mechanical components source from German and Swiss machining specialists. Single-source vulnerability in detector substrate supply creates structural risk for South American vendors. Distribution runs through authorized regional distributors with ANVISA-registered quality management systems rather than direct manufacturer-to-hospital sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America mammography market represents an early-cycle expansion story, with 3D tomosynthesis penetration in Brazil and Argentina still below saturation levels despite accelerating radiologist preference for volumetric imaging accuracy.
For Market Incumbents: Insulate installed base relationships through predictive maintenance contracts and remote diagnostics integration, countering emerging AI-native screening software entrants. Deepen backward integration into detector refurbishment capabilities to capture aftermarket margin pools. Prioritize Portuguese-language technical documentation and localized quality management systems to defend ANVISA procurement eligibility against direct-import competitors.
For New Entrants and Emerging Players: Establish a beachhead in Argentine provincial screening infrastructure, where mobile unit deployment remains underdeveloped relative to Buenos Aires metropolitan density. Target Córdoba and Mendoza provinces with equipment-as-service contracting models that unbundle capital ownership from screening program operation. Lead with cloud-based image transmission and AI-assisted preliminary read workflows to bypass the certified technologist scarcity constraining incumbent expansion.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with regional distributors holding ANVISA registrations and established public hospital service contracts but lacking tomosynthesis platform portfolios. The five-to-ten year viability window favors acquisition targets with localized technical teams over pure import arbitrage plays. Monitor Mercosur regulatory harmonization progress as the signal for cross-border certification cost reduction and market access expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Quality Management Localization | Portuguese-language documentation and in-country service infrastructure unlock public hospital procurement eligibility. |
| 3D Tomosynthesis Platform Migration | Volumetric imaging capability addresses radiologist demand for dense breast tissue evaluation accuracy. |
| Mobile Screening Unit Deployment | Provincial penetration in Argentina and northern Brazil bypasses fixed installation infrastructure gaps. |
| AI-Assisted Reading Workstation Integration | Cloud-based preliminary read workflows mitigate certified technologist scarcity in underserved regions. |
| Multi-Year Service Contract Structuring | Recurring revenue streams from software upgrades and remote diagnostics offset hardware margin compression. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with breast imaging radiologists, hospital biomedical engineers, diagnostic center procurement managers, ANVISA regulatory affairs specialists, and regional distributor service heads. Secondary validation drew from ANVISA medical device registration databases, Brazilian Ministry of Health procurement records, Argentine national pharmaceutical regulator filings, hospital GPO contract repositories, and customs import statistics for imaging equipment. Bottom-up equipment installation tracking and top-down healthcare expenditure modeling were triangulated to anchor market size estimates.
Calibration across historical procurement cycles, replacement timelines, and technology migration patterns informed the analytical framework over the projection horizon. Segmentation dimensions modeled include product configuration, end-user facility type, imaging technology, and clinical application, with regional regulatory cluster and reimbursement pathway as additional stratification layers. CAGRs were derived from fitted adoption curves weighted by public health program expansion announcements and private diagnostic chain capital expenditure disclosures. Detector replacement cycles and software licensing renewal rates served as industry-specific forecast inputs.
Stress conditions across ANVISA approval timeline variability, import tariff rate fluctuations, and certified technologist supply constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding screening program expansion commitments and technology substitution elasticities. Quarterly review of provincial procurement tender announcements and Mercosur regulatory harmonization indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Medical Hyperspectral Imaging Market
Medical Imaging
Asia-Pacific Digital Radiology Market
Medical Imaging
AI in Diagnostic Imaging Market
Medical Imaging
Cardiology PACS Market
Medical Imaging
Japan Nuclear Imaging Market
Medical Imaging
Germany Computed Tomography Market
Medical Imaging
Dual and Multi-Energy Computed Tomography (CT) Market
Medical Imaging
Ultrasound Elastography Systems Market
Medical Imaging
Asia-Pacific Digital Pathology Market
Medical Imaging
Latin America Medical Imaging Software Market
Medical Imaging
Cryo-Electron Microscopy Market
Medical Imaging
Argentina Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Spain Diagnostic Imaging Equipment Market
Medical Imaging
Saudi Arabia Diagnostic Imaging Market
Medical Imaging
PACS and RIS Market
Medical Imaging
Computed Tomography (CT) Scanners Market