
 Butterfly Needle Sets Market | 2026-2036
Butterfly Needle Sets Market Size, Share, and Industry Trends Forecast 2026-2036
Butterfly Needle Sets Market Outlook
Hospital group purchasing organization channels is narrowing as integrated delivery networks consolidate supplier lists. Becton, Dickinson and Company leverages its safety-engineered portfolio to anchor contracts with major health systems. Cardinal Health competes through distribution scale and private-label positioning across outpatient settings. Terumo Corporation specializes in precision-ground stainless steel cannula manufacturing for premium segments.
Butterfly needle sets consist of a short hypodermic needle with plastic wing-like tabs for finger grip, connected to flexible tubing and either a Luer lock or slip fitting, typically manufactured with 21-27 gauge stainless steel cannulae and silicone-coated surfaces to reduce venipuncture trauma. These devices enable controlled blood collection and short-term infusion access in patients with fragile or difficult peripheral veins. Safety butterfly needles lead volume due to OSHA compliance requirements, while pediatric butterfly needles command premium positioning in neonatal intensive care units where gauge precision and wing flexibility determine clinical outcomes. Stainless steel material grades differentiate performance tiers, with Japanese and German producers dominating high-lumen-consistency supply.
FDA 510(k) clearance pathways and OSHA Bloodborne Pathogens Standard enforcement shape product development cycles and channel access for domestic manufacturers. The EU MDR and REACH substance restrictions impose additional testing burdens on European market entrants, particularly for phthalate-free tubing formulations. Japan's PMDA maintains distinct sterility validation protocols that filter non-Japanese suppliers. Stakeholders must monitor evolving needlestick prevention regulations in Asia-Pacific jurisdictions and assess captive manufacturing versus contract sterilization decisions before capacity commitments harden.
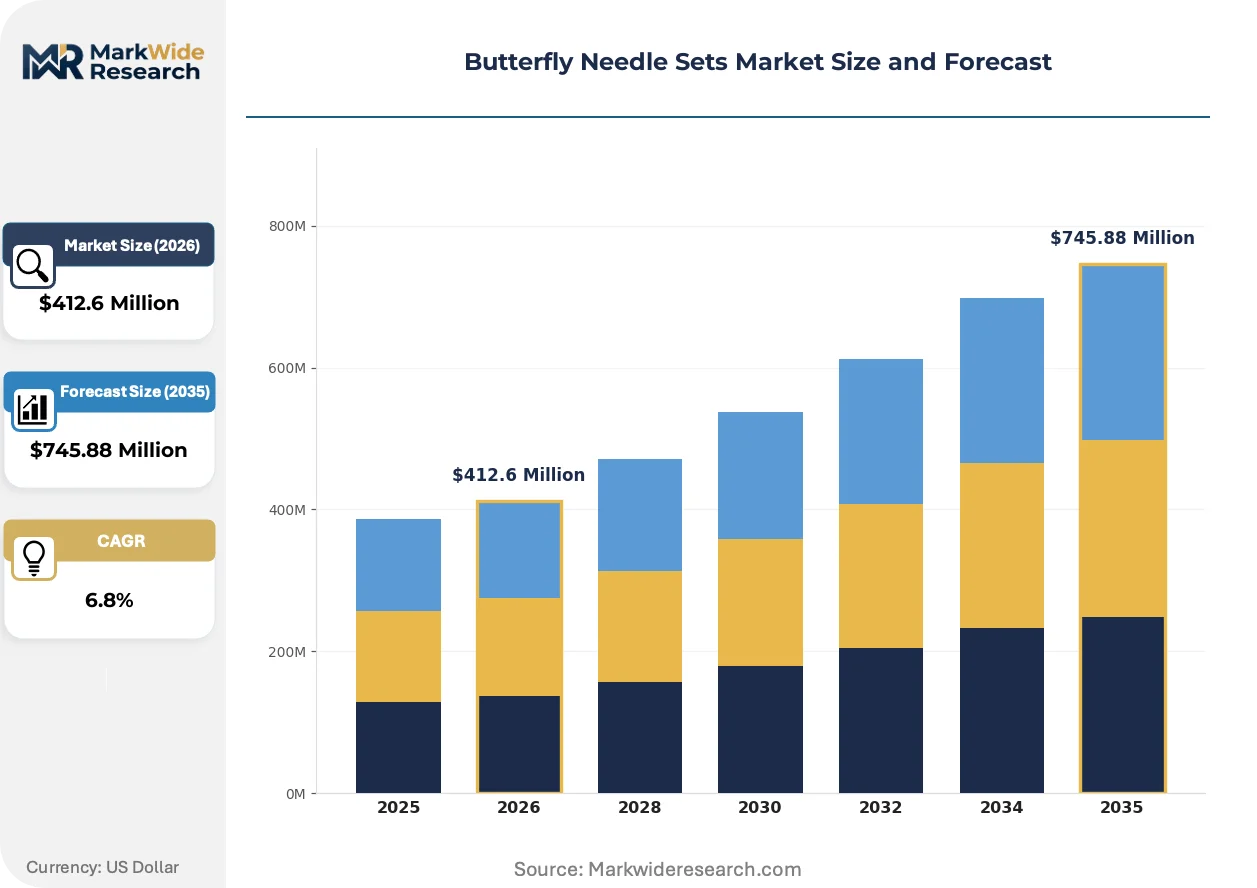
Market Dynamics
Hospital procurement consolidation is compressing supplier margins and forcing device manufacturers to embed safety-engineered features as baseline rather than premium offerings. Integrated delivery networks now demand single-source contracts spanning infusion therapy portfolios.
Growth Catalysts
- OSHA Bloodborne Pathogens Standard:US healthcare facilities face mandatory needlestick prevention compliance, accelerating replacement of conventional devices with safety-engineered butterfly needle sets across acute care and outpatient settings.
- Japan's aging demographic profile:Patients over 65 require frequent venous access for chronic disease management, expanding procedure volumes in Tokyo, Osaka, and Fukuoka metropolitan hospital clusters.
- Silicone surface coating technology:Advanced lubrication chemistries reduce vessel trauma during venipuncture, improving first-attempt success rates in pediatric and geriatric populations with fragile peripheral veins.
Market Restraints
- Stainless steel supply concentration:Precision-ground cannula manufacturing depends on Japanese and German metallurgical suppliers, exposing device assemblers to input cost volatility and allocation constraints.
- EU MDR testing burdens:European device manufacturers face extended sterility validation timelines and phthalate-free tubing reformulation costs before market authorization.
- Peripheral IV catheter substitution:Short-term infusion protocols increasingly favor over-the-needle catheter systems in emergency departments, compressing addressable volume for butterfly needle sets in high-acuity settings.
Strategic Opportunities
- Home infusion therapy expansion:US Medicare reimbursement shifts enable skilled nursing transitions to residential settings, creating demand for user-friendly winged infusion sets with integrated safety mechanisms.
- India's hospital infrastructure buildout:Tier-2 and Tier-3 city medical colleges under the PLI scheme require basic safety devices at price points accessible to government procurement.
- Needlestick prevention mandate diffusion:Asia-Pacific jurisdictions including South Korea and Australia are adopting OSHA-equivalent standards, opening regulatory tailwinds for safety-engineered portfolio entrants.
Industry Challenges
- Gamma sterilization capacity scarcity:Contract sterilization providers face backlog constraints, extending finished goods release timelines and working capital cycles for device manufacturers without captive irradiation facilities.
- Legacy ERP integration friction:Hospital materials management systems require UDI-compliant barcode serialization, forcing mid-tier suppliers to reconfigure labeling infrastructure and validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Butterfly Needle Sets Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adult Butterfly Needles, Pediatric Butterfly Needles, Safety Butterfly Needles, Infusion Butterfly Needles Material: Plastic, Stainless Steel, Latex Free, Coated End User: Hospitals, Clinics, Home Healthcare, Blood Donation Centers Packaging Type: Sterile Pack, Bulk Pack, Individual Pack, Eco-Friendly Pack |
| Companies Covered | Cardinal Health, B. Braun Melsungen AG, Terumo Corporation, ICU Medical, Nipro Corporation, Becton, Dickinson and Company, Medline Industries, Kawasumi Laboratories, Greiner Bio-One International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Butterfly Needle Sets Market Strategic Shifts
Device architecture is converging with digital traceability and passive safety engineering, shifting competitive advantage from cannula metallurgy to integrated system design. Manufacturers now compete on workflow integration rather than component specifications alone.
Passive safety butterfly needle technology is hybridizing mechanical needle retraction with one-handed activation protocols. Neonatal intensive care units and oncology infusion centers are adopting these devices at accelerated replacement cycles. The technology is compressing differentiation opportunities for conventional winged steel needle suppliers who lack integrated safety IP.
Japan's PMDA maintains distinct sterility assurance level requirements that filter non-domestic suppliers from premium hospital contracts. Device manufacturers must duplicate validation studies under PMDA protocols to access Tokyo and Osaka academic medical centers. Pediatric and oncology segments bear the highest compliance burden due to extended patient contact duration requirements.
Hospital group purchasing organizations are consolidating supplier lists around full-line infusion therapy providers. Independent butterfly needle specialists face exclusion from integrated delivery network contracts unless they anchor safety-engineered portfolios with distribution scale. The United States exhibits the most pronounced buyer concentration, with three national GPOs controlling procurement for the majority of acute care beds.
Butterfly Needle Sets Market Segmentation
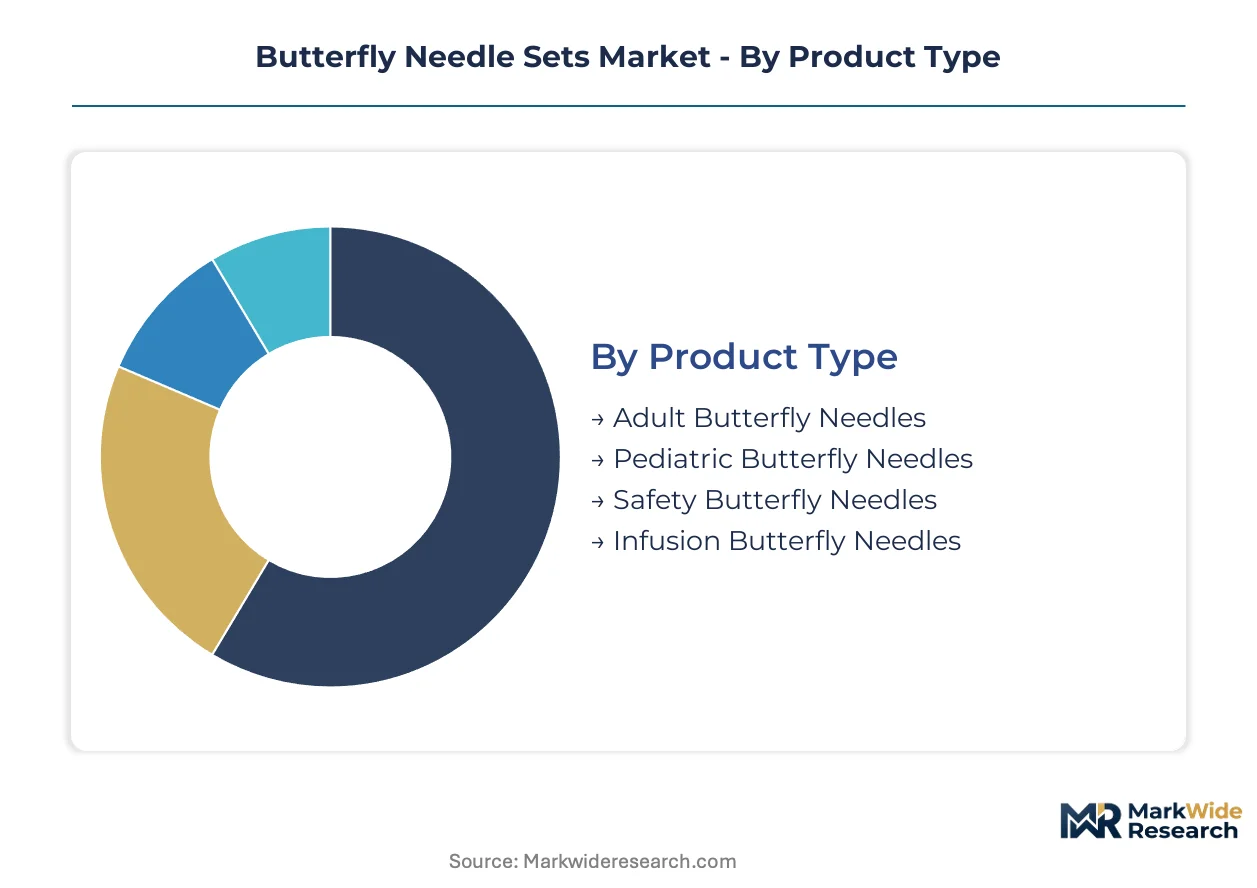
Segmentation in butterfly needle sets reflects divergent clinical workflows and regulatory compliance tiers. Safety-engineered variants turn over fastest in acute care settings, while pediatric and home healthcare segments exhibit slower replacement cycles tied to specialized validation protocols.
Product Type:
Safety butterfly needles cycle through hospital inventory fastest due to OSHA-mandated replacement schedules, while pediatric variants sit longest in NICU supply chains awaiting size-specific procurement approvals.
- Adult Butterfly Needles:Standard 21-23 gauge configurations serve routine venipuncture and short-term infusion across general medical-surgical floors. Demand concentrates in United States integrated delivery networks where OSHA compliance drives systematic conversion from conventional winged steel designs.
- Safety Butterfly Needles:Mechanical retraction or shielding mechanisms activate passively or semi-automatically post-venipuncture. German and Japanese hospital procurement offices specify these devices exclusively for staff needlestick protection, anchoring premium positioning in academic medical centers.
- Pediatric Butterfly Needles:Ultra-thin 25-27 gauge cannulae with flexible wing geometry reduce vessel trauma in neonatal and pediatric populations.
- Infusion Butterfly Needles:Extended tubing configurations support gravity-fed or pump-administered medication delivery.
Adult butterfly needles dominate installed base. Safety butterfly needles is where expansion concentrates.
Material:
Cost tiers separate precision-ground stainless steel cannulae from polymer-based alternatives, with coating technologies commanding intermediate pricing positions.
- Stainless Steel:Surgical-grade 304 or 316L alloys provide lumen consistency and bevel sharpness retention. Japanese metallurgical suppliers in Osaka and Tokyo prefectures control premium feedstock allocation for Tokyo-area device manufacturers.
- Coated:Silicone or polymer surface treatments reduce insertion friction and vessel trauma. German producers leverage advanced deposition chemistries to supply coated cannulae for oncology and geriatric segments where first-attempt success rates determine clinical preference.
- Plastic:Polycarbonate or polypropylene wing components and hub assemblies reduce unit weight.
- Latex Free:Synthetic elastomer alternatives eliminate allergen exposure in sensitive patient populations.
Stainless steel anchors revenue concentration. Coated variants are climbing the fastest.
End User:
Customer type determines volume scale versus margin structure, with hospitals purchasing at scale and home healthcare demanding simplified activation protocols.
- Hospitals:Acute care facilities consume butterfly needle sets across emergency departments, infusion centers, and laboratory phlebotomy services. United States GPO contracts bundle these devices with broader infusion therapy portfolios, compressing standalone supplier margins.
- Home Healthcare:Skilled nursing transitions to residential settings require winged infusion sets with integrated safety mechanisms and intuitive one-handed activation. Medicare reimbursement shifts in the United States are expanding this addressable base.
- Clinics:Outpatient settings prioritize cost efficiency in high-throughput phlebotomy workflows.
- Blood Donation Centers:High-volume collection operations specify 16-18 gauge large-bore configurations for rapid whole blood extraction.
Hospitals dominate installed base. Home healthcare is where expansion concentrates.
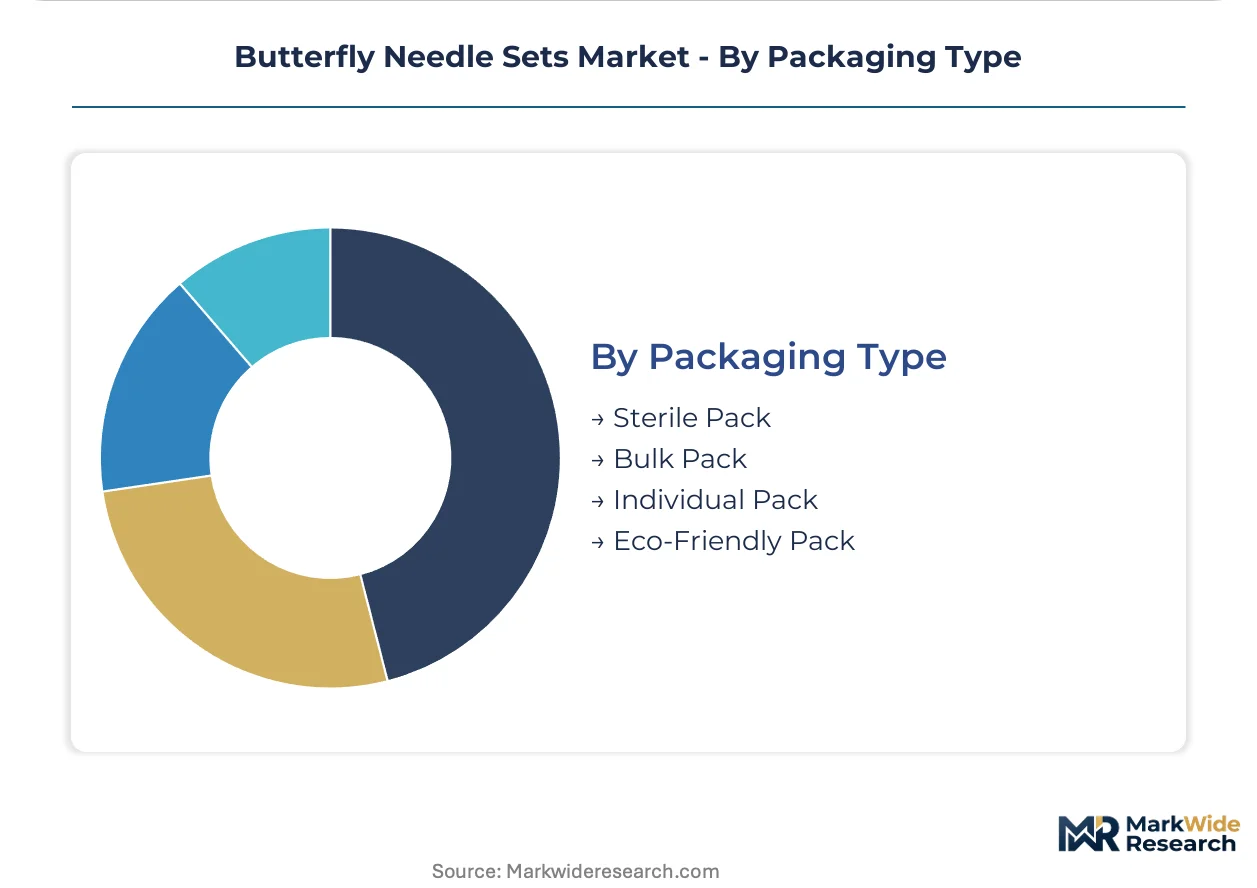
Packaging Type:
Packaging configuration reflects sterility assurance requirements and waste reduction mandates across jurisdictions.
- Sterile Pack:Single-unit pouches with Tyvek-lidded trays maintain sterility assurance levels for invasive procedures. EU MDR and Japan PMDA validation protocols extend release timelines for these configurations.
- Eco-Friendly Pack:Recyclable or biodegradable materials respond to REACH substance restrictions and hospital sustainability procurement criteria. German healthcare facilities increasingly specify these alternatives under federal environmental purchasing guidelines.
- Individual Pack:Unit-of-use packaging supports point-of-care inventory management.
- Bulk Pack:Multi-unit cartons reduce per-unit packaging cost for high-consumption settings.
Sterile pack dominates installed base. Eco-friendly pack is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain infrastructure underwrites European distribution networks for temperature-sensitive medical devices, while the Osaka-Kobe manufacturing corridor anchors precision metallurgy supply for Asian device assemblers.
United States
Integrated delivery networks in Texas and Florida are consolidating supplier contracts around full-line infusion therapy portfolios. OSHA Bloodborne Pathogens Standard enforcement accelerates safety-engineered device conversion across acute care beds. The Boston-Cambridge medical device cluster houses sterile packaging validation facilities serving GPO procurement channels.
Germany
REACH substance restrictions and EU MDR testing timelines filter non-compliant tubing formulations from hospital procurement lists. Federal environmental purchasing guidelines steer Baden-Württemberg healthcare facilities toward recyclable packaging alternatives. The Stuttgart-Tübingen precision engineering corridor supplies coated cannula deposition technologies for oncology segments.
Japan
Patients over 65 in Tokyo, Osaka, and Fukuoka metropolitan clusters require frequent venous access for chronic disease management. PMDA sterility assurance protocols filter non-domestic suppliers from premium academic medical center contracts. The Osaka prefecture metallurgical suppliers control precision-ground stainless steel feedstock allocation for domestic device manufacturers.
India
Tier-2 and Tier-3 city medical colleges under the PLI scheme require basic safety devices at government-accessible price points. CDSCO medical device regulations are converging with international standards for needlestick prevention. The Maharashtra-Gujarat pharmaceutical manufacturing belt is expanding sterile device assembly capacity for domestic hospital procurement.
Australia
Medicare reimbursement shifts enable skilled nursing transitions to residential infusion therapy settings. TGA adoption of OSHA-equivalent needlestick prevention standards opens regulatory tailwinds for safety-engineered portfolio entrants. The Sydney-Melbourne hospital procurement corridor concentrates demand for winged infusion sets with integrated activation mechanisms.
Butterfly Needle Sets Market Competitive Environment
On the supply side, the industry is consolidating around integrated delivery network contracts that bundle butterfly needle sets within broader infusion therapy portfolios. Tiered competitive positioning separates full-line medical device conglomerates from regional specialists and private-label distributors. Strategic archetypes include safety-engineered portfolio anchors, precision metallurgy specialists, and distribution-scale intermediaries. Dominant competitive moves encompass backward integration into cannula manufacturing and sterile packaging capacity expansion.
Among diversified medical technology conglomerates, Becton, Dickinson and Company and Cardinal Health occupy positions as full-line portfolio anchors within United States GPO channels. Terumo Corporation exemplifies the precision manufacturing archetype with its Osaka-based metallurgical supply relationships. B. Braun Melsungen AG represents the European integrated device manufacturer model with captive sterile production capabilities.
| Leading Market Players |
|---|
| Cardinal Health |
| B. Braun Melsungen AG |
| Terumo Corporation |
| ICU Medical |
| Nipro Corporation |
| Becton, Dickinson and Company |
| Medline Industries |
| Kawasumi Laboratories |
| Greiner Bio-One International |
| Others |
Value Chain & Pricing Dynamics
Gamma sterilization capacity undercapacity across North American contract facilities is forcing device manufacturers to prepay for irradiation slots and absorb working capital compression, which feeds directly into premium-tier pricing posture for safety-engineered butterfly needle sets.
Pricing Analysis
Volume-discount tiering structures anchor hospital GPO contracting, with three-tier pricing separating safety-engineered premium devices from standard winged steel and economy private-label alternatives. Price differentiation rests on OSHA compliance certification and silicone coating deposition quality. Cost compression in standard tiers is intensifying because integrated delivery networks are consolidating supplier lists around full-line infusion therapy portfolios. Blood donation centers exhibit highest price sensitivity due to high-throughput commodity procurement, while Japanese academic medical centers show lowest sensitivity given PMDA validation barriers.
Supply Chain Analysis
Supplier-financing through extended 90-120 day payment terms dominates procurement relationships between US device assemblers and Japanese metallurgical feedstock providers. Geographic supply concentrates in Japan, Germany, and the United States for precision-ground stainless steel cannulae, silicone coating chemistries, and sterile packaging materials. Raw material dependencies draw from surgical-grade 304/316L alloys, medical-grade silicone lubricants, and phthalate-free PVC tubing formulations. Single-source vulnerability runs through Osaka prefecture metallurgical suppliers controlling premium lumen-consistency feedstock. Distribution runs through hospital GPO channels and integrated delivery network consolidated supplier lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
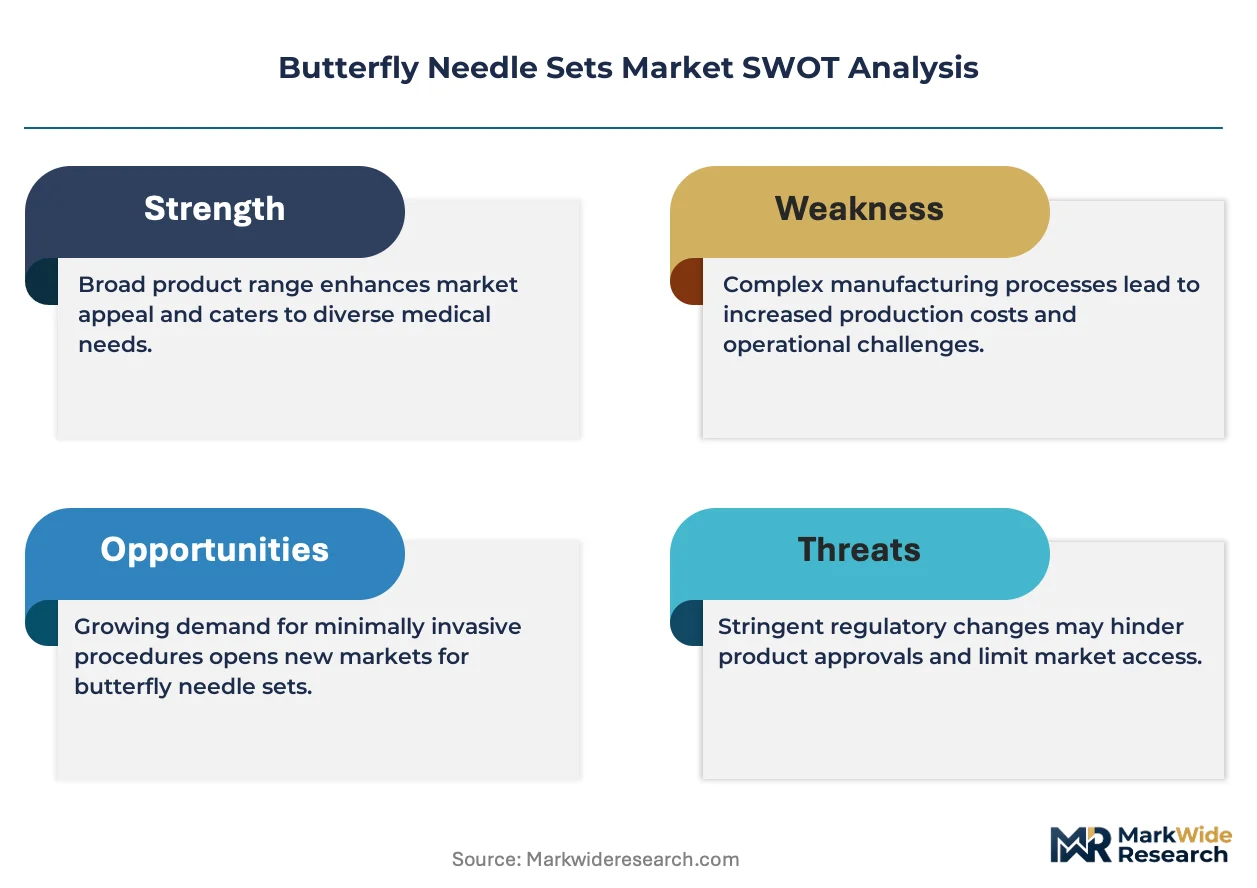
This market functions as a defensive-moat story anchored in regulatory entrenchment, where FDA 510(k) clearance pathways and OSHA compliance mandates create structural barriers that protect incumbent positioning against price erosion.
For Market Incumbents: Harden supply security through backward integration into captive gamma sterilization facilities or long-term offtake agreements with irradiation providers, eliminating contract sterilization backlog exposure. Deepen channel control by anchoring safety-engineered butterfly needle portfolios within full-line infusion therapy contracts at consolidating integrated delivery networks, defending against peripheral IV catheter substitution threats in emergency department settings. For New Entrants and Emerging Players: Establish a beachhead in India's Tier-2 and Tier-3 city medical colleges under PLI scheme procurement, where government-accessible price points and basic safety device requirements create penetrable white space. Target home healthcare skilled nursing transitions in US Medicare reimbursement expansion zones with user-friendly winged infusion sets featuring intuitive one-handed activation protocols, bypassing entrenched GPO channel lock-in. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-composure play because needlestick prevention mandate diffusion across Asia-Pacific jurisdictions creates sustained tailwinds for safety-engineered portfolio entrants with PMDA-validated sterile production capabilities. Acquisition focus should center on mid-tier device manufacturers with captive metallurgy relationships or validated sterile packaging infrastructure. The signal to watch is CDSCO convergence with international needlestick prevention standards accelerating India's safety device procurement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Sterility Validation Investment | Unlocks premium Tokyo and Osaka academic medical center contracts for device manufacturers. |
| Backward Integration into Cannula Manufacturing | Secures precision-ground stainless steel feedstock allocation from Japanese metallurgical suppliers. |
| Hospital System Partnership | Anchors safety-engineered portfolios within consolidating integrated delivery network supplier lists. |
| Reimbursement Strategy Development | Captures Medicare-enabled home healthcare skilled nursing transition demand for winged infusion sets. |
| Software Companion Development | Enables UDI-compliant barcode serialization for hospital materials management system integration. |
Study Parameters
Operator-level perspectives from hospital procurement managers, GPO contracts directors, biomedical engineers, and sterile packaging validation specialists anchored the qualitative base. Primary interviews combined with secondary validation against FDA 510(k) clearance databases, OSHA enforcement records, hospital procurement contract disclosures, and EU MDR technical documentation submissions. Bottom-up procedure volume modeling and top-down infusion therapy market sizing provided triangulation across the analysis window.
Scenario-bracketing framed the analytical approach, with baseline, accelerated safety-conversion, and peripheral IV substitution downside cases tested across product type, material grade, end-user setting, and regional regulatory cluster segmentation dimensions. CAGRs derived from procedure volume elasticity to aging demographic profiles and compliance-driven replacement cycle compression. Industry-specific inputs incorporated PMDA sterility assurance level requirements and gamma sterilization capacity utilization rates.
Sensitivities concentrate around needlestick prevention mandate adoption timelines in Asia-Pacific jurisdictions, stainless steel feedstock allocation constraints from Japanese suppliers, and peripheral IV catheter technology advancement in emergency department protocols. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and hospital procurement consolidation trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Cryoboxes Market
Medical Supplies
North America Nasal Spray Market
Medical Supplies
Asia-Pacific Human Fibrin Glue Market
Medical Supplies
Filter Needles Market
Medical Supplies
Disposable Bed Sheets Market
Medical Supplies
Plastic Blood Bags Market
Medical Supplies
Global Urinary Drainage Bags Market
Medical Supplies
Measured Volume Burette Set Market
Medical Supplies
North America Ostomy Drainage Bags Market
Medical Supplies
Cell Culture Media Bags Market
Medical Supplies
Global IV Tubing Sets and Accessories Market
Medical Supplies
Middle East and Africa Hospital Supplies Market
Medical Supplies
Asia Pacific Medical Rubber and Balloon Product Market
Medical Supplies
Ostomy Care Market
Medical Supplies
Empty IV Bags Market
Medical Supplies
Japan Hospital Supplies Market