
 Saudi Arabia Digital Radiology Market | 2026-2036
Saudi Arabia Digital Radiology Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Digital Radiology Market Insights
The Saudi Green Initiative and Health Sector Transformation Program is broadening the sustainability mandate for medical infrastructure procurement across the Kingdom. GE HealthCare leverages its installed base of imaging platforms to sustain service contract relationships with Ministry of Health facilities. Siemens Healthineers anchors its position through localized technical training centers that address workforce development priorities. Canon Medical Systems competes on compact system footprints suited for clinic and diagnostic center expansion outside major metros.
Digital radiology encompasses the acquisition, processing, storage, and transmission of diagnostic images using electronic detectors and picture archiving systems, replacing analog film with direct digital capture at spatial resolutions exceeding two thousand by two thousand pixels for chest and skeletal applications. Its primary purpose is to reduce examination turnaround time, eliminate chemical processing, and enable remote specialist consultation through integrated PACS networks. CT scanner procurement dominates capital expenditure among product types, reflecting trauma center buildouts and oncology screening program scale-up. Wireless sensor adoption grows fastest within technology categories, driven by portable unit demand in emergency departments and operating suites. Hospitals capture the largest end-user revenue pool, though diagnostic centers represent the fastest-growing channel as privatization accelerates under Vision 2030 health sector restructuring.
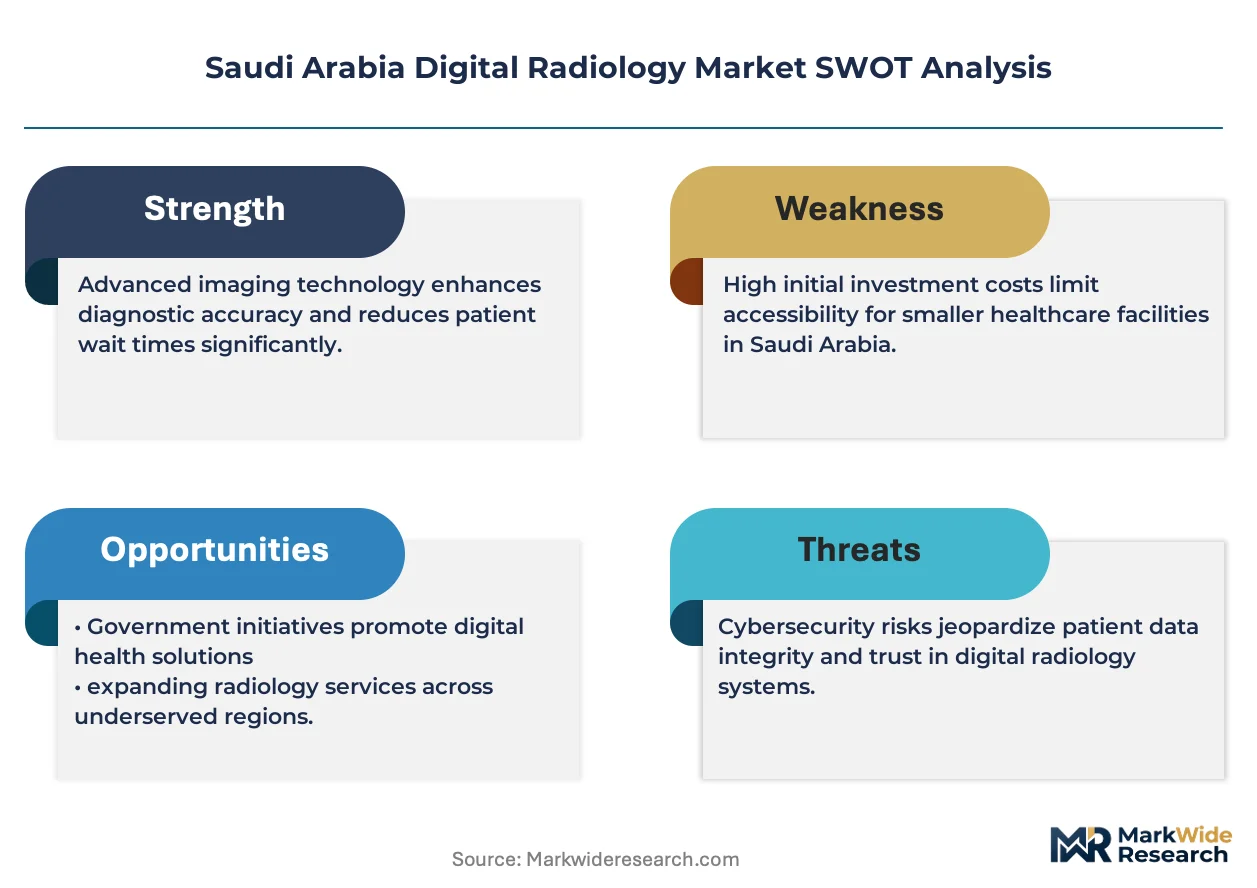
SFDA medical device registration requirements enforce post-market surveillance and quality management system compliance for all imaging equipment commercialized in the Kingdom. NPHIES interoperability standards mandate DICOM conformance and national health information exchange connectivity, effectively filtering market access for vendors lacking certified integration capabilities. The CEDA localization program incentivizes domestic assembly and component sourcing, reshaping supply chain obligations for multinational manufacturers. Stakeholders must monitor procurement framework shifts as the Ministry of Health transitions toward outcome-based service contracts rather than capital purchase models.
Market Dynamics
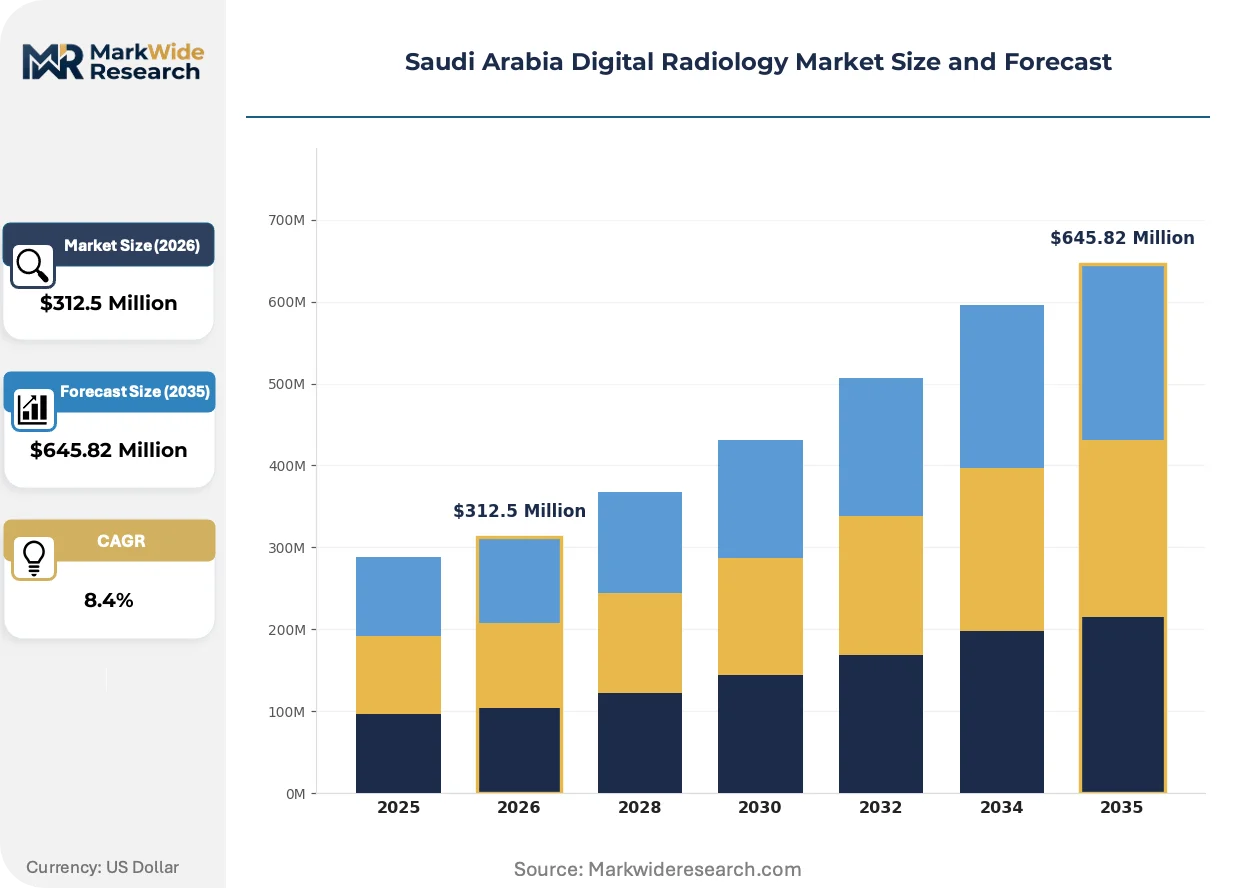
The Saudi Arabia Digital Radiology Market is being restructured by NPHIES interoperability mandates that filter vendor access through DICOM conformance and national health information exchange connectivity requirements.
Growth Catalysts
- SFDA Registration Pathway:The Saudi Food and Drug Authority's medical device registration requirements enforce post-market surveillance and quality management system compliance, elevating standards across imaging equipment commercialization.
- Diagnostic Center Privatization:Vision 2030 health sector restructuring accelerates diagnostic center expansion outside Riyadh and Jeddah, creating distributed demand for compact digital radiology systems.
- Wireless Sensor Technology:Portable unit deployment in emergency departments and operating suites drives rapid adoption of wireless detector panels for bedside and intraoperative imaging.
Market Restraints
- Capital Intensity:CT scanner procurement dominates hospital capital expenditure, squeezing budget availability for complementary digital radiography suites in secondary facilities.
- Technical Workforce Constraints:Specialized biomedical engineering talent for DICOM integration and PACS network maintenance concentrates in Riyadh and Jeddah, limiting deployment velocity in peripheral regions.
- SFDA Compliance Timeline:Extended device registration cycles and quality management system audits delay market entry for manufacturers lacking established Saudi regulatory affairs capabilities.
Strategic Opportunities
- CEDA Localization Incentives:The CEDA program rewards domestic assembly and component sourcing, creating supply chain restructuring opportunities for multinational imaging equipment manufacturers.
- Outcome-Based Contracting Transition:Ministry of Health procurement frameworks are migrating from capital purchase models to performance-linked service contracts, opening recurring revenue streams for integrated solution providers.
- Tertiary Medical City Expansion:Specialist diagnostic volume growth in emerging medical cities outside the two primary metros creates demand for enterprise-grade PACS infrastructure and teleradiology connectivity.
Industry Challenges
- Radiologist Workforce Distribution:Specialist interpretation capacity clusters in Ministry of Health tertiary facilities, creating reporting bottlenecks for diagnostic centers in secondary cities attempting to scale volume.
- Legacy Analog System Integration:Public hospital networks retain substantial film-based radiology infrastructure, complicating phased digital transitions and hybrid workflow management during multi-year modernization programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Digital Radiology Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray, CT Scanner, MRI Scanner, Ultrasound End User: Hospitals, Diagnostic Centers, Research Institutions, Clinics Application: Orthopedics, Cardiology, Oncology, Neurology Technology: Computed Radiography, Digital Radiography, Wireless Sensors, PACS |
| Companies Covered | Canon Medical Systems, United Imaging Healthcare, GE HealthCare, Samsung Medison, Mindray Bio-Medical Electronics, Siemens Healthineers, Fujifilm Holdings, Shimadzu, Koninklijke Philips, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Digital Radiology Market Trends and Innovations
Artificial intelligence integration and national health information exchange maturation are compressing examination turnaround times and enabling remote specialist consultation across the Kingdom's distributed care network.
AI-powered chest and skeletal screening algorithms are automating preliminary image interpretation and anomaly flagging for radiologist review. Ministry of Health tertiary facilities are piloting these tools for trauma and oncology screening programs. The technology is automating workflow prioritization in high-volume emergency departments, reducing report latency for critical findings.
NPHIES interoperability standards now mandate DICOM conformance and national health information exchange connectivity for all new imaging equipment procurements. This regulatory architecture filters market access to vendors with certified integration capabilities and established Saudi technical support infrastructure. Diagnostic centers and hospital networks are responding by consolidating vendor relationships around platforms with proven NPHIES certification.
Service unbundling is separating equipment procurement from maintenance and software subscription components across public hospital networks. Ministry of Health facilities are negotiating multi-year performance contracts that transfer uptime risk to manufacturers while retaining capital budget flexibility. This restructuring is most visible in Riyadh-based tertiary medical cities where procurement autonomy has advanced furthest under Health Sector Transformation Program decentralization.
Saudi Arabia Digital Radiology Market Segmentation
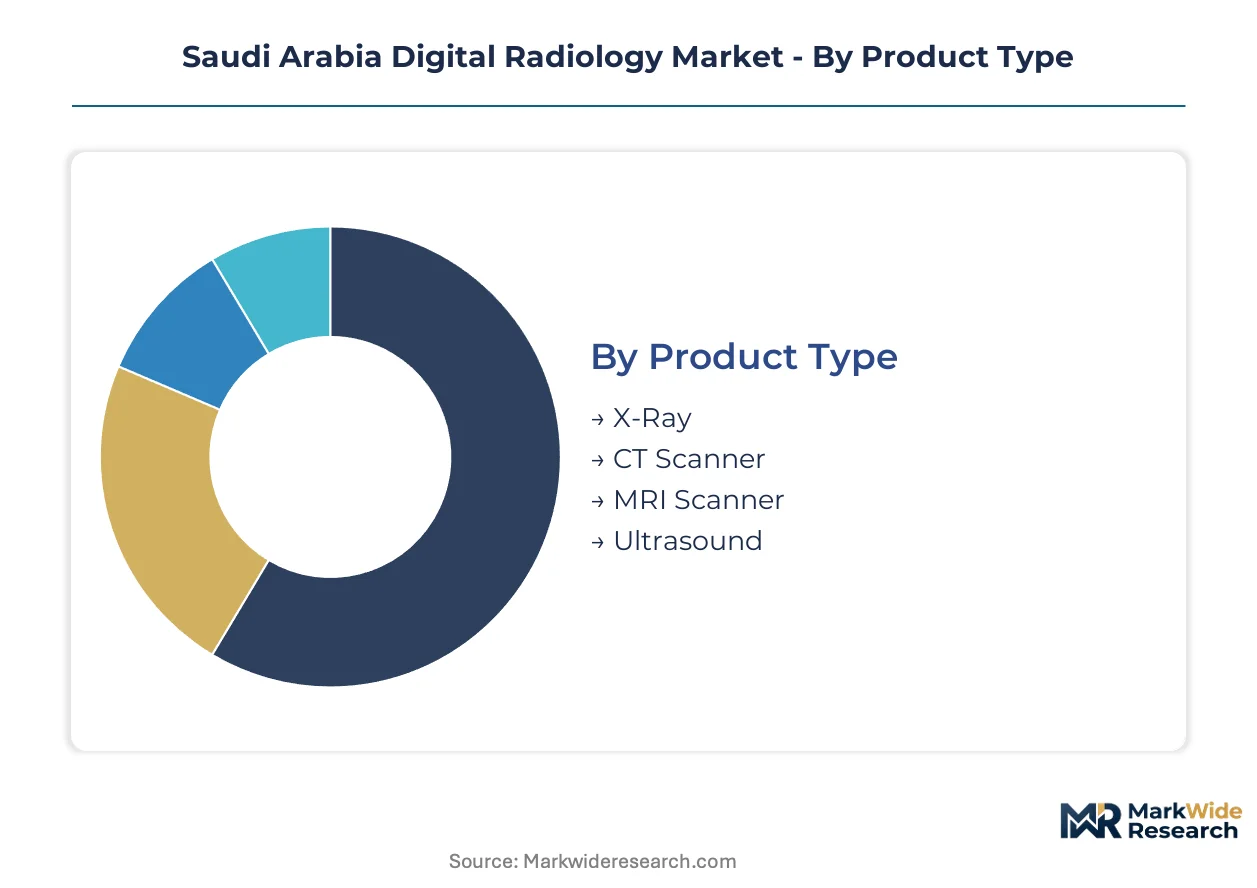
Procurement patterns across Saudi Arabia's digital radiology market diverge sharply between capital-intensive tertiary installations and distributed diagnostic infrastructure. Understanding segment-level supply concentration illuminates where vendor relationships consolidate and where new entrants can penetrate.
Product Type:
CT scanner manufacturing capacity concentrates among three multinational suppliers with established SFDA registration pathways and NPHIES-certified integration stacks.
- CT Scanner:Multi-detector systems with 64-slice and above configurations dominate trauma center and oncology screening procurement. Riyadh-based tertiary medical cities anchor demand volume under Ministry of Health capital expenditure programs.
- X-Ray:Digital radiography systems with flat-panel detectors and automated exposure control serve high-throughput emergency departments. Diagnostic centers in Jeddah and emerging secondary metros drive replacement cycles for aging analog infrastructure.
- MRI Scanner:1.5T and 3T superconducting systems address neurovascular and musculoskeletal diagnostic protocols.
- Ultrasound:Portable and cart-based systems with elastography and contrast-enhanced modes support point-of-care deployment.
CT scanner installations absorb the bulk of installed capacity; diagnostic center X-Ray procurement is expanding most quickly.
End User:
Customer concentration patterns split between consolidated public hospital networks and fragmented private diagnostic operators with diverging procurement autonomy.
- Hospitals:Ministry of Health tertiary facilities and medical cities deploy enterprise-grade PACS infrastructure with teleradiology connectivity. SFDA device registration and NPHIES interoperability mandates filter vendor access to established multinational suppliers.
- Diagnostic Centers:Privatization under Vision 2030 health sector restructuring accelerates distributed imaging capacity outside Riyadh and Jeddah. Compact system footprints and wireless detector portability address space-constrained clinic environments.
- Clinics:Primary care and specialty outpatient facilities require entry-level digital radiography for basic skeletal and chest imaging.
- Research Institutions:Academic medical centers in Riyadh and Jeddah pilot AI-powered screening algorithms and advanced quantitative imaging protocols.
Hospitals retain the largest procurement budgets; diagnostic centers are gaining share fastest as privatization deepens.
Application:
Clinical demand intensity varies with population disease burden and specialist interpretation capacity distribution across the Kingdom's care network.
- Oncology:Screening program scale-up and precision treatment planning drive CT and MRI procurement for tumor characterization and treatment response monitoring. National cancer center expansion in Riyadh concentrates high-end imaging demand.
- Orthopedics:Trauma center buildouts and sports medicine growth generate sustained digital radiography and MRI volume for fracture assessment and joint reconstruction planning.
- Cardiology:CT coronary angiography and cardiac MRI address ischemic and structural heart disease diagnostic protocols.
- Neurology:Stroke center certification requirements and neurosurgical planning drive advanced CT and MRI utilization.
Oncology applications command premium system configurations; orthopedics delivers the steepest volume expansion trajectory.
Technology:
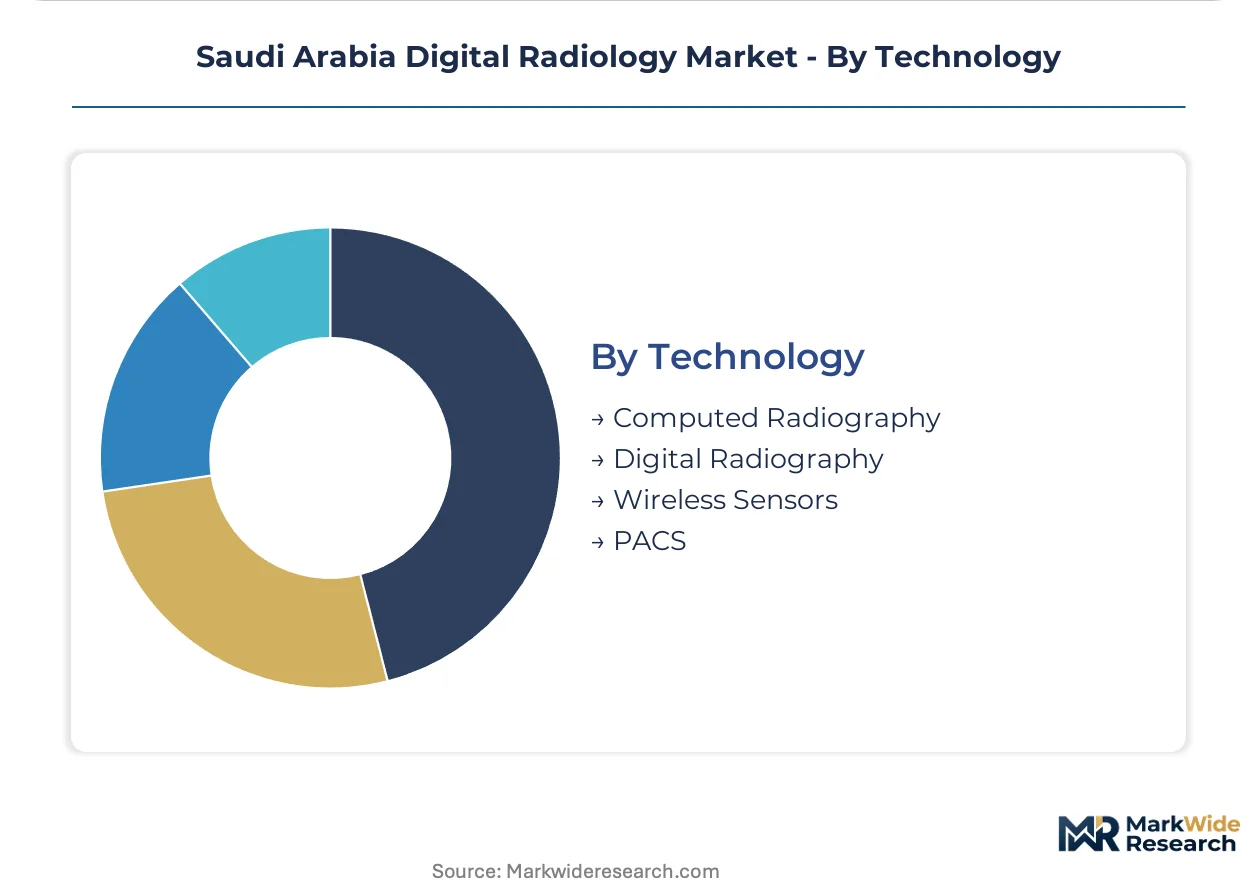
Technology adoption curves separate between mature digital capture systems and emerging wireless and AI-integrated platforms with shorter replacement cycles.
- Digital Radiography:Direct digital capture systems with cesium iodide or amorphous selenium detectors deliver spatial resolution exceeding two thousand by two thousand pixels for chest and skeletal applications. Ministry of Health facilities prioritize these systems for film-to-digital transition programs.
- Wireless Sensors:Portable detector panels with Wi-Fi or proprietary wireless protocols enable bedside and intraoperative imaging without fixed installation requirements. Emergency departments and operating suites in Riyadh medical cities pilot rapid deployment workflows.
- Computed Radiography:Cassette-based phosphor plate systems serve cost-sensitive facilities completing phased analog-to-digital transitions.
- PACS:Enterprise archiving and distribution infrastructure with NPHIES-certified interoperability enables remote specialist consultation across distributed care networks.
Digital Radiography platforms anchor installed base maintenance; Wireless Sensors are climbing the fastest as portable deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity for digital radiology equipment concentrates in East Asian manufacturing clusters, while Saudi consumption absorbs systems through Ministry of Health procurement and Vision 2030 diagnostic center expansion.
Riyadh
Tertiary medical cities anchor specialist diagnostic volume and enterprise-grade PACS infrastructure deployment. SFDA device registration requirements filter vendor access to established multinational suppliers with certified quality management systems. King Faisal Specialist Hospital and Research Centre concentrates high-end CT and MRI procurement for oncology and neurovascular protocols.
Jeddah
Diagnostic center privatization accelerates distributed imaging capacity expansion along the Red Sea corridor. NPHIES interoperability mandates reshape vendor qualification criteria through DICOM conformance requirements. King Abdulaziz Medical City anchors trauma center buildouts driving multi-detector CT procurement.
Eastern Province
Oil industry health infrastructure sustains occupational medicine screening programs and corporate clinic digital radiography deployment. CEDA localization incentives attract domestic assembly investment for component sourcing obligations. Dammam and Al-Khobar medical clusters concentrate secondary hospital network modernization.
Western Region
Pilgrimage health infrastructure drives seasonal surge capacity requirements for portable digital radiography in emergency departments. Wireless sensor adoption grows fastest in operating suites and bedside imaging workflows. Makkah and Madinah hospital networks prioritize compact system footprints for space-constrained environments.
NEOM Northwest
Greenfield health city development creates demand for fully integrated digital radiology infrastructure without legacy analog transition burdens. Outcome-based service contracting models transfer uptime risk to manufacturers under multi-year performance agreements. The giga-project's technology-first procurement framework favors vendors with AI-integrated platforms and teleradiology connectivity.
Saudi Arabia Digital Radiology Market Competitive Landscape
The competitive structure tilts toward multinational imaging equipment conglomerates with established SFDA registration pathways and NPHIES-certified integration capabilities. Three strategic archetypes dominate: diversified medical technology conglomerates with service contract depth, specialized diagnostic imaging pure-plays with compact system expertise, and emerging Asian manufacturers competing on acquisition cost. Dominant competitive moves include outcome-based contracting transitions that convert capital sales to recurring revenue streams, and CEDA localization partnerships that restructure supply chains for domestic assembly incentives.
Within the diversified conglomerate tier, GE HealthCare and Siemens Healthineers occupy positions anchored by installed base maintenance relationships and localized technical training infrastructure. Canon Medical Systems exemplifies the compact imaging specialist archetype, while United Imaging Healthcare represents emerging Asian manufacturing competition. These three manufacturers collectively illustrate the vendor qualification filtering now enforced through SFDA post-market surveillance and NPHIES interoperability mandates.
| Leading Market Players |
|---|
| Canon Medical Systems |
| United Imaging Healthcare |
| GE HealthCare |
| Samsung Medison |
| Mindray Bio-Medical Electronics |
| Siemens Healthineers |
| Fujifilm Holdings |
| Shimadzu |
| Koninklijke Philips |
| Others |
Pricing and Supply Chain Analysis
Backward integration into detector panel manufacturing anchors pricing power for multinational imaging equipment suppliers serving Saudi Arabia's Ministry of Health procurement channels. Captive production of cesium iodide and amorphous selenium sensor substrates insulates vendors from component cost volatility while enabling three-tier pricing structure across premium, standard, and economy levels.
Pricing Analysis
Cost-down pressure on mid-range digital radiography systems accelerates because emerging Asian manufacturers undercut established SFDA-registered suppliers in diagnostic center privatization tenders. Pricing stratifies across premium, standard, and economy tiers differentiated by DICOM certification depth and NPHIES interoperability bundling. Ministry of Health tertiary facilities show lowest price sensitivity due to outcome-based contracting migration, while private diagnostic centers in secondary metros prioritize acquisition cost over after-sales service inclusion.
Supply Chain Analysis
CEDA localization mandates are reshaping sourcing obligations for multinational manufacturers, requiring domestic assembly partnerships to qualify for public hospital network tenders. Manufacturing gravity centers on Japan, South Korea, and China for flat-panel detector substrates, superconducting magnet wire, and X-ray tube assemblies. Supply chains draw from rare earth processing facilities in China for scintillator materials, exposing procurement to export license vulnerability. Distribution runs through authorized service distributors with SFDA quality management certification and NPHIES integration engineering capability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Saudi digital radiology market is becoming a vertical-integration race where control over detector manufacturing and localized technical training infrastructure determines vendor survival. Players capturing upstream sensor production and downstream service contract relationships will dominate outcome-based procurement transitions.
For Market Incumbents: Extend service contract depth into multi-year performance agreements that transfer uptime risk and lock out emerging Asian competitors lacking Saudi biomedical engineering workforces. Deepen backward integration into detector panel production to defend margin position against cost-down pressure in diagnostic center tenders. Prioritize NPHIES certification investment as regulatory filtering intensifies.
For New Entrants and Emerging Players: Authorized service distributors with existing Ministry of Health relationships offer the most viable channel partnership path for market penetration. Target secondary metro diagnostic centers outside Riyadh and Jeddah where procurement autonomy and price sensitivity create white-space opportunity. Lead with compact wireless detector systems suited for space-constrained clinic environments and rapid deployment workflows.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified medical technology conglomerates seeking Saudi installed base expansion. Long-term viability hinges on CEDA localization compliance capability and NPHIES integration engineering depth. Watch for Ministry of Health procurement framework shifts toward outcome-based contracting as the inflection signal for recurring revenue model viability.
| Strategic Initiative | Industry Significance |
|---|---|
| CEDA Localization Partnership | Domestic assembly qualification unlocks Ministry of Health tender access under Saudi content incentives. |
| NPHIES Certification Investment | DICOM conformance and health information exchange connectivity filter vendor market access. |
| Outcome-Based Service Contract | Performance-linked agreements transfer uptime risk while securing recurring revenue streams. |
| Wireless Detector Platform Launch | Portable unit deployment addresses emergency department and operating suite demand growth. |
| Technical Training Center Establishment | Localized workforce development addresses SFDA quality management and biomedical engineering constraints. |
Research Methodology
Independent corroboration across hospital procurement committees, biomedical engineering directors, and diagnostic center operators underwrites the qualitative findings on vendor selection criteria and technology adoption patterns. Primary fieldwork with SFDA regulatory affairs specialists and NPHIES integration engineers combined with secondary validation from GPO contract databases, hospital capital expenditure disclosures, and medical device registration filings. Bottom-up demand modeling across product type, end user, and technology segments triangulates against top-down Ministry of Health budget allocation analysis.
Rate-of-change decomposition separates volume expansion from price trajectory across the projection horizon, modeling segmentation dimensions including product type, end user channel, clinical application, and technology adoption curve. CAGRs derive from installed base replacement cycles, privatization-driven diagnostic center formation, and wireless sensor penetration assumptions. Forecast inputs incorporate SFDA registration timeline delays, CEDA localization compliance thresholds, and radiologist workforce distribution constraints.
Caveats apply where SFDA regulatory timeline extensions, NPHIES interoperability standard revisions, or Ministry of Health procurement framework shifts could materially shift the outlook. Forecasts reflect assumptions about Vision 2030 health sector restructuring pace and diagnostic center privatization depth. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Japan Diagnostic Imaging Market
Medical Imaging
Brazil Nuclear Imaging Market
Medical Imaging
Diagnostic Imaging Markers Market
Medical Imaging
France Computed Tomography Market
Medical Imaging
Africa Nuclear Imaging Market
Medical Imaging
Ultrasound Market
Medical Imaging
Structural Heart Imaging Market
Medical Imaging
Handheld Ultrasound Scanners Market
Medical Imaging
Medical X-Ray Equipment and Imaging Software Market
Medical Imaging
Digital Radiography Detectors Market
Medical Imaging
Ultrasound Elastography Systems Market
Medical Imaging
Perfusion Radiology Market
Medical Imaging
Ultrasound Consoles and Transducers Market
Medical Imaging
North America MRI (Magnetic Resonance Imaging) Market
Medical Imaging
Positron Emission Tomography Devices (PET) Market
Medical Imaging
Brain PET-MRI Systems Market