
 Wireless Microphone Market | 2026-2036
Wireless Microphone Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Microphone Market Intelligence
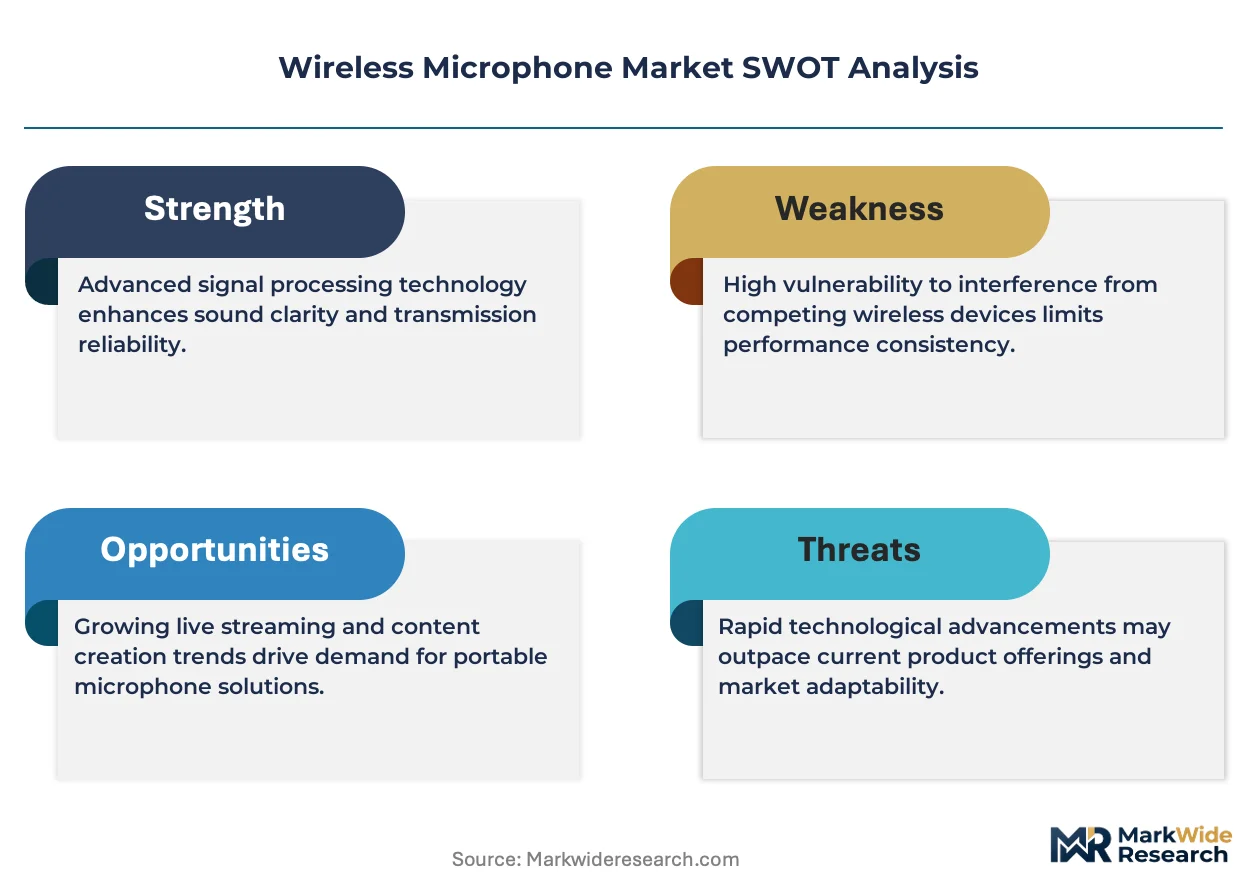
Live event production is broadening the addressable base for wireless microphone systems beyond traditional broadcast studios into touring, corporate AV, and worship installations. Shure Incorporated leverages its domestic manufacturing footprint to sustain rapid fulfillment for North American rental houses. Sennheiser Electronic GmbH & Co. KG anchors European demand through precision-engineered RF stability in crowded spectrum environments. Audio-Technica Corporation competes aggressively in price-sensitive education and house-of-worship channels.
A wireless microphone converts acoustic sound into radio frequency signals for cable-free transmission to a receiver, typically operating between 470-608 MHz in UHF bands or within 2.4 GHz digital protocols, with systems engineered for low latency, frequency agility, and interference rejection in multi-channel deployments. Handheld configurations dominate rental inventory and touring rigs due to durability and performer familiarity, while lavalier and headset variants capture institutional and broadcast demand where discretion and mobility matter. Digital transmission architectures are displacing analog architectures in professional tiers as spectral efficiency mandates tighten across major economies.
The FCC governs frequency allocation and equipment authorization in the United States, while the EU Radio Equipment Directive and CE marking framework standardize interoperability and electromagnetic compatibility across member states; Japan's MIC and South Korea's RRA impose additional local type-approval requirements that shape product variant strategies. Spectrum scarcity is forcing manufacturers to invest in proprietary frequency-coordination software and automated interference-avoidance algorithms. Stakeholders must monitor regulatory auction outcomes and emerging 5G adjacency rules to anticipate channel-loss risk and inventory obsolescence cycles.
Market Dynamics
Spectrum scarcity is compressing channel availability and forcing manufacturers to redesign RF architectures around automated frequency coordination, fundamentally restructuring how multi-channel systems are deployed in congested urban venues.
Growth Catalysts
- Content Creation Infrastructure:Streaming studios and creator economy platforms in the United States, Germany, and China are expanding channel counts per facility, driving replacement cycles for older analog inventories.
- EU Radio Equipment Directive:Harmonized electromagnetic compatibility standards across member states reduce certification fragmentation and accelerate cross-border equipment flows for touring productions.
- Digital Transmission Protocols:Spectral efficiency gains from 2.4 GHz and proprietary digital modulation schemes enable denser channel packing in Broadway theaters and broadcast compound environments.
Market Restraints
- FCC Spectrum Reallocation:The 600 MHz band clearance eliminated approximately 126 MHz of UHF spectrum, forcing legacy system obsolescence and stranding installed base investments in US houses of worship and regional theaters.
- RF Component Concentration:Precision oscillator and filter manufacturing concentrates in Japanese and German specialty component suppliers, creating single-source vulnerability for low-phase-noise designs.
- Lithium-Polymer Supply:Portable transmitter battery packs depend on constrained cell production, with spot price volatility affecting margin structures in rental fleet operations.
Strategic Opportunities
- India Content Production:Bollywood expansion and regional language streaming platforms create underpenetrated demand for cost-optimized multi-channel systems compliant with TRAI frequency allocations.
- 5G Adjacency Rules:Emerging guard-band regulations around mid-band 5G deployments may open protected spectrum blocks for licensed wireless microphone operation in dense metropolitan broadcast zones.
- Software-Defined RF:Firmware-upgradable receiver architectures allow field reconfiguration for changing regulatory environments, extending product lifecycles and reducing inventory risk for rental houses.
Industry Challenges
- RF Coordination Expertise:Frequency planning for 50-plus channel Broadway and touring productions requires scarce broadcast engineering talent, with training pipelines failing to match deployment complexity.
- Cross-Border Certification Lag:Japan's MIC and South Korea's RRA impose divergent spurious emission limits, forcing SKU proliferation and delaying product launches by 8-14 months for Asia-Pacific touring compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Microphone Market |
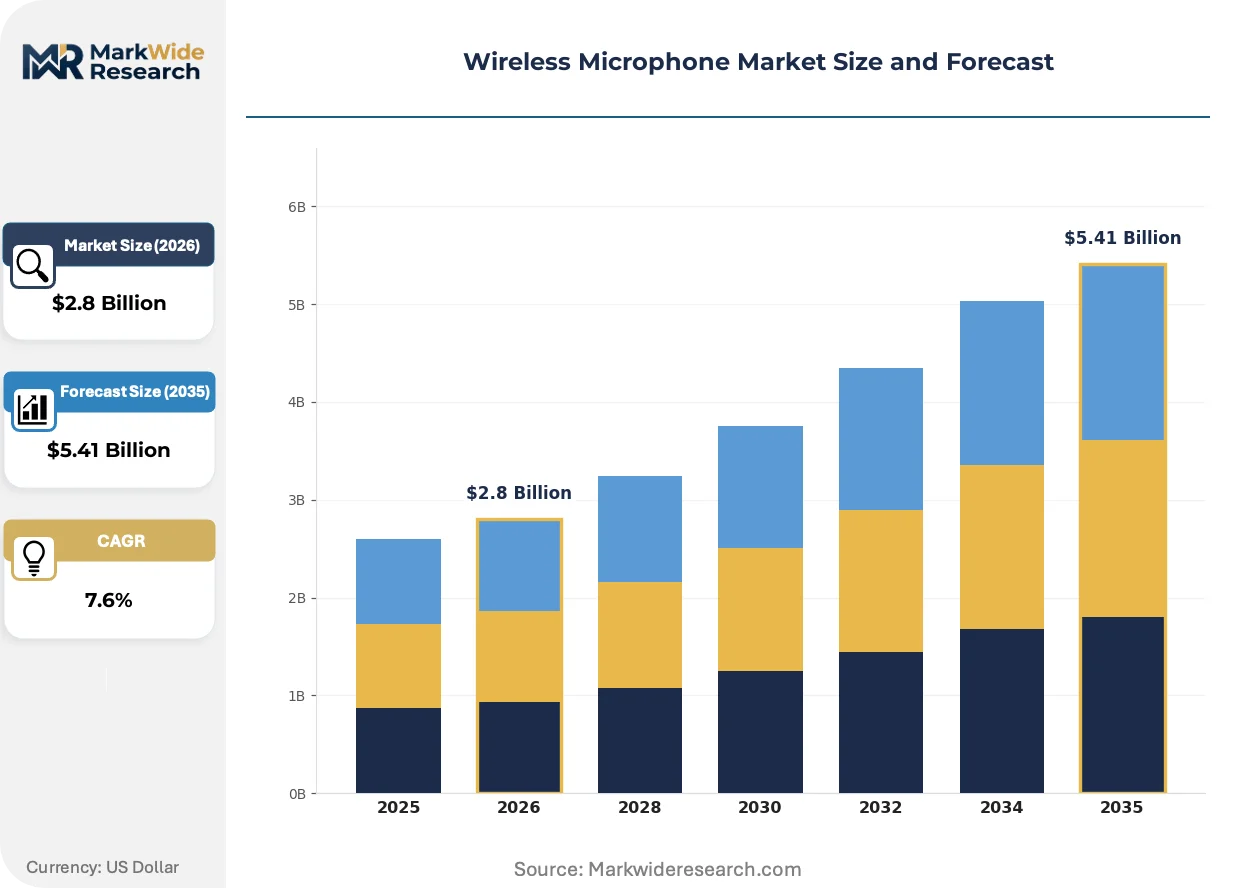
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Lavalier, Headset, Shotgun Technology: UHF, VHF, Digital, Analog Application: Live Events, Broadcasting, Theatre, Conference End User: Musicians, Broadcasters, Educators, Podcasters |
| Companies Covered | Shure Incorporated, Sennheiser Electronic GmbH & Co. KG, Sony Corporation, Audio-Technica Corporation, AKG Acoustics, Rode Microphones, Samson Technologies Corp., Yamaha Corporation, Electro-Voice, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Microphone Market Strategic Shifts & Innovations
Digital signal processing and networked control architectures are displacing standalone analog receivers, compressing rack space requirements while enabling centralized monitoring across distributed venue installations.
AES67 and Dante audio-over-IP protocols are converging with wireless microphone receiver outputs, eliminating analog-to-digital conversion stages in broadcast trucks and performing arts centers. Major touring productions and network sports remote units are standardizing on networked audio infrastructure, collapsing traditional copper snake deployments and reducing setup labor by half. This convergence is compressing the installed base of analog splitters and patch bays while elevating IT networking competency requirements among audio technicians.
The FCC's Part 15 and Part 74 rulemakings continue tightening out-of-band emission limits and mandating frequency-agility capabilities for professional equipment authorization. Manufacturers must redesign front-end filtering and synthesizer architectures to meet revised spurious emission masks, particularly affecting high-density metropolitan broadcast operations. US broadcast networks and rental houses are accelerating depreciation schedules to preempt obsolescence risk from future spectrum proceedings.
Rental houses and institutional buyers are unbundling transmitter packages from receiver chassis, procuring channel counts flexibly against specific production calendars rather than maintaining fixed inventory ratios. This consumption-pattern shift favors receiver architectures with hot-swappable network cards and cloud-based frequency coordination subscriptions over capital-intensive owned-system models. The pattern is most visible in London's West End theater district and Las Vegas residency productions where show turnover compresses equipment utilization cycles.
Wireless Microphone Market Segmentation
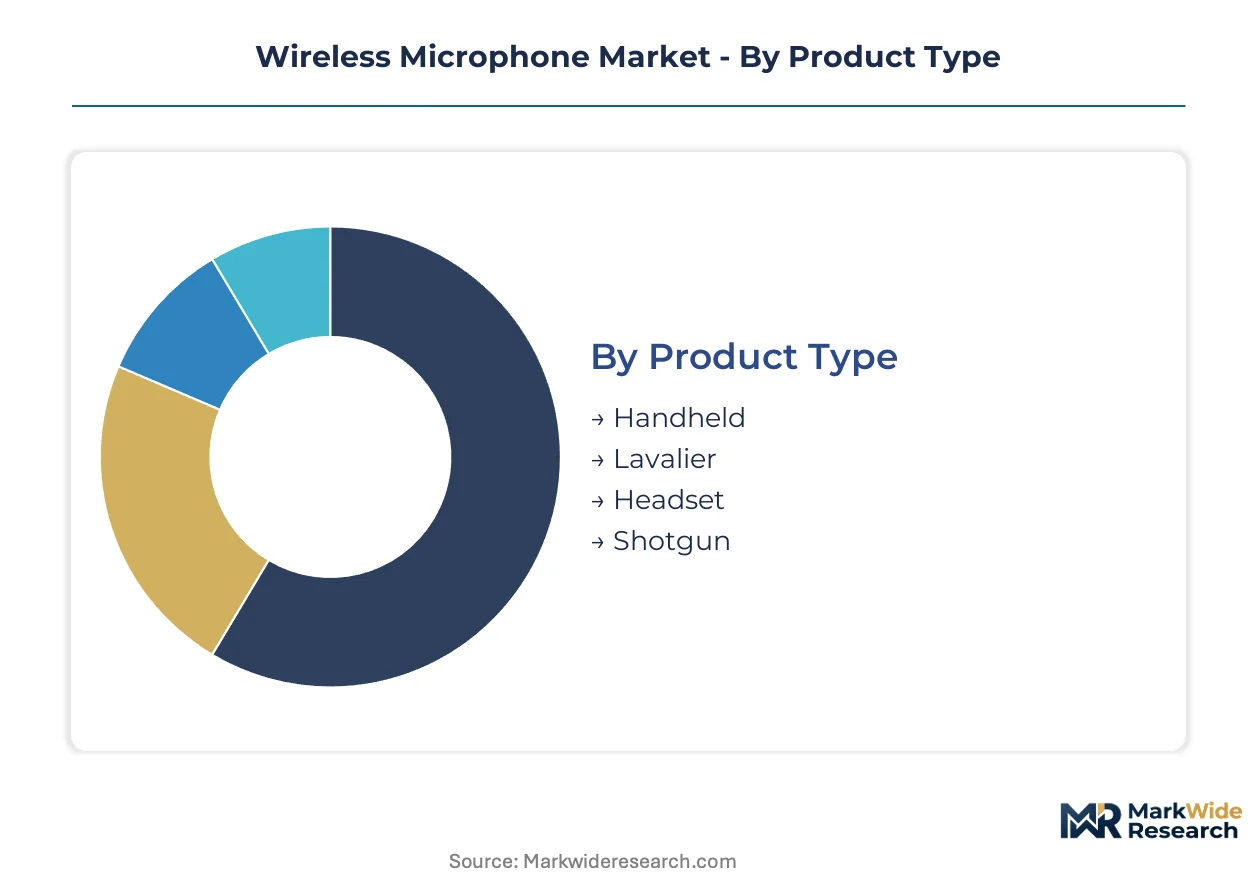
Wireless microphone segmentation reveals distinct upgrade cycles across product architectures, with digital transmission systems displacing analog inventories at divergent speeds depending on regulatory pressure and end-use technical requirements. Replacement timelines compress in touring and broadcast verticals while extending in institutional installations.
Product Type:
Replacement cycles vary dramatically by physical form factor, with durability demands and performer ergonomics dictating refresh timing across rental fleets and permanent installs.
- Handheld:Ruggedized metal enclosures house cardioid or supercardioid capsules engineered for stage moisture and impact resistance. Live touring and concert venues in the United States and Germany concentrate demand, driven by FCC spectrum reallocation forcing simultaneous transmitter and capsule upgrades.
- Lavalier:Subminiature condenser elements mount on clothing via clips or tape for discrete theatrical and broadcast capture. Theatre productions in London's West End and Broadway drive premium-tier procurement, with costume integration complexity extending specification cycles.
- Headset:Ear-worn boom configurations prioritize performer mobility in fitness instruction and active presentation environments. Corporate AV departments and houses of worship favor this format for hands-free operation.
- Shotgun:Interference-tube designs deliver tight polar patterns for film and field production. Location sound operators in California and Bavaria specify these for outdoor dialogue capture.
Handheld sits at the top of the volume ranking, with Headset climbing the fastest.
Technology:
Cost tier stratification separates professional-tier digital deployments from price-sensitive analog retention in secondary markets.
- UHF:Ultra-high frequency transmission between 470-608 MHz delivers stable propagation through walls and crowd density. Broadcast networks and national touring productions anchor demand, though FCC 600 MHz clearance has truncated available spectrum blocks.
- Digital:Proprietary modulation schemes and 2.4 GHz protocols enable AES-256 encryption and spectral efficiency gains. Las Vegas residency shows and network sports remotes lead deployment, motivated by frequency coordination automation.
- VHF:Very-high frequency operation below 174 MHz persists in budget-conscious education and community theater sectors. Interference susceptibility limits this format to single-channel or low-density installations.
- Analog:FM-based architectures retain installed base in houses of worship and regional theaters with constrained capital budgets. Obsolescence risk accelerates depreciation schedules among US rental houses.
Digital commands the steepest expansion trajectory, while Analog retains residual volume in cost-constrained segments.
Application:
Customer type diversity stretches from high-frequency rental turnover to decade-long institutional ownership models.
- Live Events:Multi-channel touring rigs demand RF redundancy and rapid frequency agility for daily venue changes. Rental houses in Nashville and Los Angeles maintain the densest inventory concentrations.
- Theatre:Permanent installations prioritize cosmetic discretion and costume-compatible form factors. London and New York venue districts sustain premium procurement despite longer replacement cycles.
- Broadcast:News gathering and remote production require spectrum resilience and IT network integration. Network affiliate stations face accelerated refresh timelines from FCC emission rule tightening.
- Conference:Corporate meeting rooms and exhibition halls favor tabletop and wearable formats with simple operation. Beijing and Shanghai convention centers drive volume in this tier.
Live Events sits at the top of the volume ranking, with Broadcast gaining share fastest.
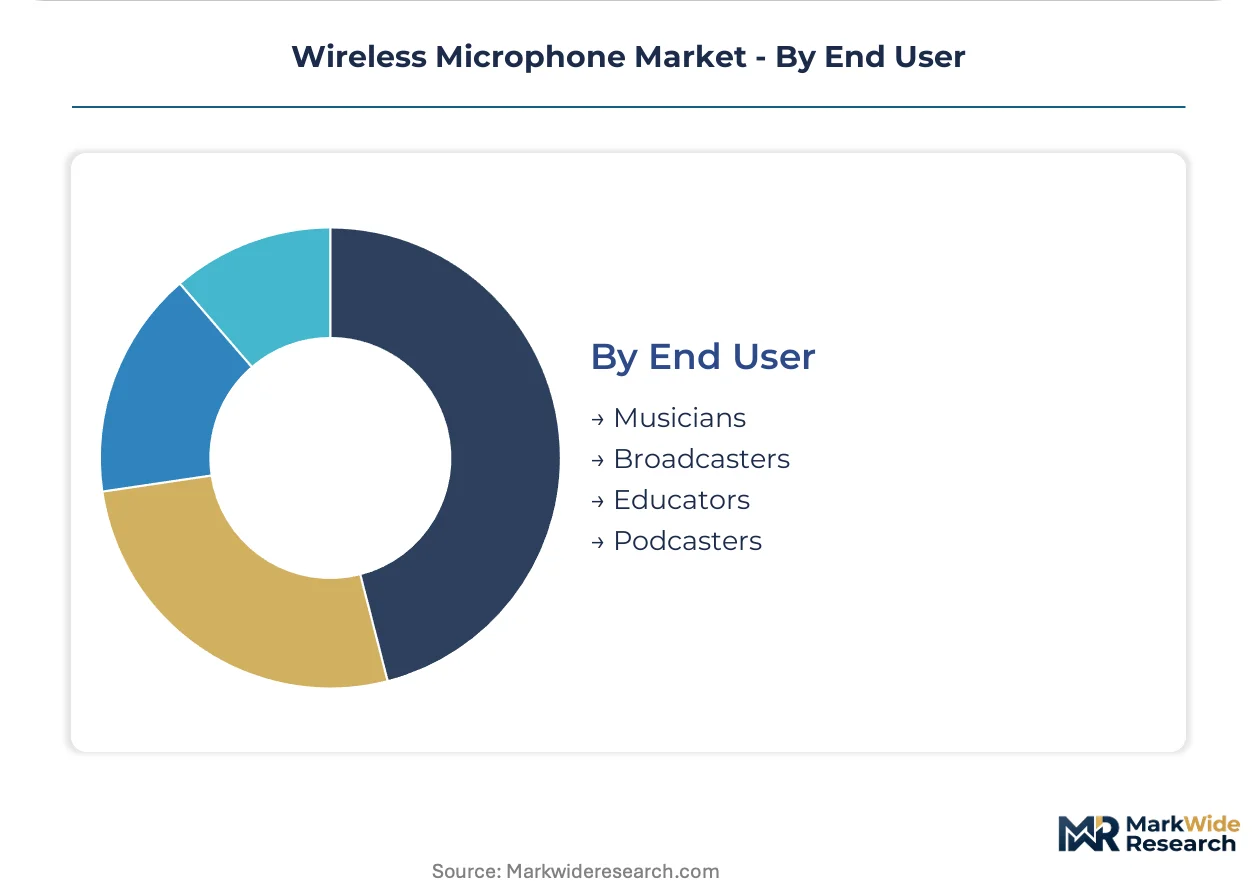
End User:
Application maturity separates professional content creators from emerging creator-economy entrants with divergent technical sophistication.
- Broadcasters:Network engineering departments mandate spectral compliance and networked monitoring capabilities. Regulatory pressure from FCC Part 74 drives synchronized upgrade waves.
- Musicians:Touring artists and session players prioritize sonic transparency and road durability. Nashville and Berlin music production clusters concentrate procurement.
- Podcasters:Independent content creators favor plug-and-play 2.4 GHz systems for home studio simplicity. This segment shows expanding channel counts per creator as production values professionalize.
- Educators:K-12 and university AV departments balance budget constraints against multi-classroom deployment scale. Federal E-Rate funding eligibility shapes US procurement timing.
Broadcasters sit at the top of the volume ranking, with Podcasters climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nashville's music production infrastructure anchors wireless microphone procurement through touring artist demand and broadcast studio buildouts. The United States, Germany, and China concentrate channel deployment as content creation infrastructure professionalizes across streaming and live event verticals.
United States
Network sports remotes and Las Vegas residency productions drive multi-channel system deployment. The FCC's 600 MHz band clearance eliminated 126 MHz of UHF spectrum, forcing rental houses and broadcasters into accelerated replacement cycles. Los Angeles and Nashville maintain the densest rental inventory concentrations for touring and studio applications.
Germany
Broadway-scale theatrical productions and corporate AV installations sustain premium-tier demand. The EU Radio Equipment Directive harmonizes electromagnetic compatibility standards, reducing certification fragmentation for cross-border touring equipment. Berlin and Munich anchor broadcast engineering clusters developing automated frequency coordination software.
China
Convention center buildouts in Beijing and Shanghai and regional streaming platform expansion drive volume procurement. The MIIT governs radio frequency allocation and equipment type-approval requirements that shape local product variant strategies. Shenzhen's electronics manufacturing ecosystem supplies RF component assemblies for domestic and export markets.
Japan
Precision oscillator and filter manufacturing concentrates among specialty component suppliers serving professional audio OEMs. The MIC imposes local type-approval requirements with divergent spurious emission limits that delay product launches for Asia-Pacific touring compatibility. Tokyo's broadcast engineering sector pioneers spectral efficiency algorithms for congested urban venues.
United Kingdom
London's West End theater district sustains premium lavalier and headset procurement despite extended replacement cycles. The national regulator manages spectrum auction outcomes that determine channel availability for performing arts venues. Manchester and Birmingham rental houses serve regional touring productions with flexible channel-count procurement models.
Wireless Microphone Market Key Industry Players
Technology licensing dominates the current landscape as manufacturers navigate divergent regional certification requirements. The vendor base organizes into three tiers: integrated RF component specialists, full-system providers, and software-defined architecture developers. Consolidation pressure concentrates among mid-scale analog-dependent suppliers facing spectrum obsolescence. Strategic partnerships and firmware-upgradeable product architectures represent the dominant competitive vectors for extending equipment lifecycles.
Within the full-system provider tier, Shure Incorporated and Sennheiser Electronic GmbH & Co. KG occupy positions exemplifying geographic specialization strategies. Audio-Technica Corporation represents the price-competitive archetype targeting education and institutional channels. Sony Corporation anchors the diversified electronics conglomerate position, leveraging broadcast sector relationships across imaging and audio product lines.
| Leading Market Players |
|---|
| Shure Incorporated |
| Sennheiser Electronic GmbH & Co. KG |
| Sony Corporation |
| Audio-Technica Corporation |
| AKG Acoustics |
| Rode Microphones |
| Samson Technologies Corp. |
| Yamaha Corporation |
| Electro-Voice |
| Others |
Cost & Logistics Intelligence
Precision oscillator manufacturing costs cascade through receiver architectures into three-tier pricing structures across premium, standard, and economy levels, with Japanese and German component sourcing compressing margins at the mid-tier while FCC compliance investments elevate professional-grade entry points.
Pricing Analysis
Distributor margins absorb spectrum reallocation compliance costs before reaching rental houses and broadcast networks. Three-tier pricing structure across premium, standard, and economy levels separates AES-256 encrypted digital systems from analog retention in education channels. Price differentiation hinges on RF channel density certification and after-sales frequency coordination subscriptions. Podcasters and K-12 educators exhibit highest price sensitivity, while network sports remotes prioritize spectral resilience over unit economics.
Supply Chain Analysis
Transoceanic freight volatility from Japanese precision filter suppliers to German assembly plants strains inventory planning for North American rental fleets. Component sourcing centers on Japan for low-phase-noise oscillators, Germany for RF filtering subassemblies, and China for transmitter battery pack integration. Raw material dependencies include lithium-polymer cells, rare-earth magnets for capsule motors, and copper-clad laminates for circuit boards. Single-source vulnerability in Japanese oscillator manufacturing concentrates risk. Distribution runs through authorized pro-audio dealers and direct OEM contracts for broadcast network volume procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Wireless Microphone Market compounds steadily as streaming infrastructure professionalization sustains replacement cycles across content creation verticals.
For Market Incumbents: Anticipate spectrum scarcity deepening channel-density competition by accelerating firmware-upgradeable receiver development. Shure and Sennheiser should tighten vertical integration into precision oscillator supply through captive partnerships with Japanese component specialists. Defend installed base positions in Las Vegas residency productions against emerging software-defined RF entrants by embedding cloud-based frequency coordination subscriptions. For New Entrants and Emerging Players: E-commerce direct-to-creator channels offer lowest friction penetration for podcasting and independent streaming segments. Target India's Bollywood regional language platforms with TRAI-compliant cost-optimized multi-channel systems. Bypass incumbent dealer networks through influencer partnerships and platform-native tutorial content that reduces RF coordination expertise barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where analog-dependent mid-scale suppliers face FCC obsolescence stranding. Five-to-ten year viability favors software-defined architecture developers with firmware-upgradeable product roadmaps. Acquisition targets include automated frequency coordination software specialists and lithium-polymer battery pack integrators with rental fleet relationships. Monitor FCC Part 15 rulemaking timelines as inflection signals for depreciation acceleration waves.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined RF Architecture Development | Firmware-upgradeable receivers extend product lifecycles against FCC spectrum volatility. |
| Automated Frequency Coordination Software Licensing | Cloud-based subscription models capture recurring revenue from rental house operations. |
| Precision Oscillator Supply Partnership | Japanese component captive agreements reduce single-source vulnerability for low-phase-noise designs. |
| India Content Production Market Entry | TRAI-compliant cost-optimized systems address Bollywood and regional streaming expansion. |
| 5G Guard-Band Spectrum Advocacy | Regulatory engagement may unlock protected blocks for licensed wireless microphone operation. |
Research Approach
Coverage spans the United States, Germany, China, Japan, and the United Kingdom, with primary inputs from each market's broadcast engineering clusters, rental house operations, and regulatory affairs specialists. Primary interviews incorporated RF system designers at network affiliates, touring production managers, pro-audio procurement directors, and FCC policy advisors. Secondary validation drew from FCC Part 74 rulemaking dockets, EU Radio Equipment Directive implementation guidance, MIIT type-approval registries, and customs trade data for RF component flows. Bottom-up channel count modeling triangulated against top-down content production infrastructure investment tracking.
Granularity-level modeling deployed product type, transmission technology, application vertical, and end-user sophistication dimensions across the analysis window. Digital versus analog replacement cycles, FCC spectrum auction outcomes, and streaming platform facility buildouts informed CAGR derivation. Segmentation-specific price points and regional regulatory compliance cost structures anchored value projections. Networked audio protocol adoption curves and rental fleet turnover rates provided industry-specific forecast inputs.
Regulatory auction delays, lithium-polymer supply disruptions, and 5G adjacency rule uncertainties are the dominant revision risks for projection validity. Forecasts reflect documented assumptions regarding spectrum availability trajectories and content creation infrastructure investment continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Europe Wireless Microphone Market
Wireless Technologies
Global Wireless Data Communication Market
Wireless Technologies
Multefire Market
Wireless Technologies
Asia-Pacific Wi-Fi 6 Market
Wireless Technologies
USA Li-Fi Market
Wireless Technologies
Europe Wireless Charging Market
Wireless Technologies
Wireless Connectivity Market
Wireless Technologies
5G Fixed Wireless Access Market
Wireless Technologies
Femtocell Market
Wireless Technologies
Wireless Communication Technologies in Healthcare Market
Wireless Technologies
Mobile Hotspot Device Market
Wireless Technologies
Industrial Wireless Transmitter Market
Wireless Technologies
Industrial Bluetooth Market
Wireless Technologies
Global Gi Fi Technology Market
Wireless Technologies
Global Wireless Mesh Network Market
Wireless Technologies
Fixed LTE Wireless Broadband Market