
 Global Wireless Data Communication Market | 2026-2036
Global Wireless Data Communication Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wireless Data Communication Market Foresight
The gap between proprietary and open radio access network architectures is narrowing as operators demand vendor interoperability. Qualcomm Incorporated leverages its modem-RF system integration to sustain design wins across Android flagships and automotive platforms. Broadcom anchors premium Wi-Fi 7 chipset supply through vertical integration into filter and front-end module production. Cisco Systems competes aggressively in private 5G deployments for manufacturing plants and mining operations.
Wireless data communication encompasses radio-frequency transmission systems that encode digital information onto electromagnetic carriers operating from sub-GHz millimeter-wave bands through protocols including OFDMA, CDMA, and spread-spectrum techniques. These systems enable machine-to-machine coordination, real-time telemetry, and broadband access without physical tethering across distances from centimeters in near-field communication to geostationary satellite links. The technology dimension shows 5G infrastructure commanding the largest capital allocation while LoRaWAN extends its margin pool in low-power wide-area agricultural and utility metering networks. Application-level demand tilts toward industrial automation as smart factory investments require deterministic latency below ten milliseconds for robotic control loops.
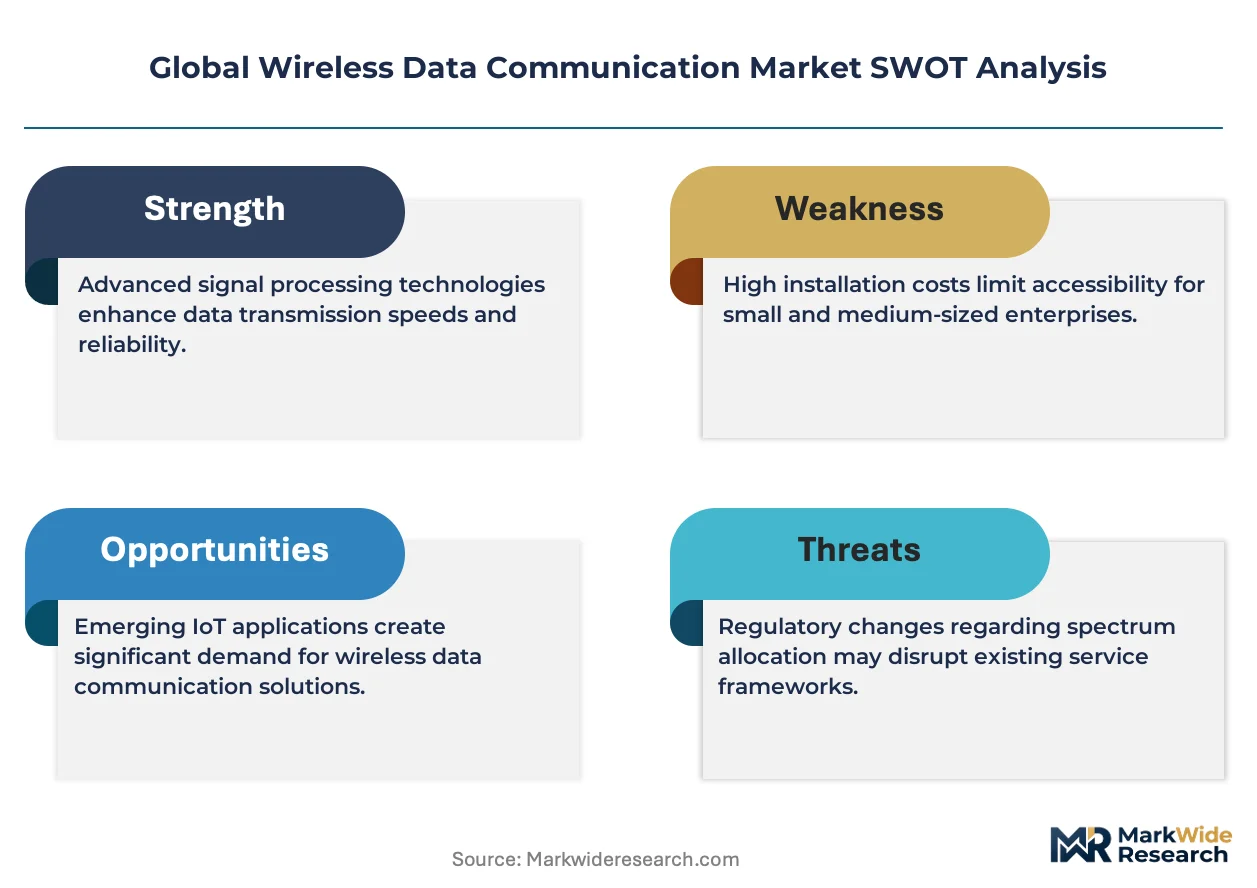
FCC Part 15 rules govern unlicensed device emissions in the United States while ETSI EN 300 328 harmonizes wideband transmission standards across European member states, and China's MIIT allocates dedicated spectrum blocks for industrial 5G through local licensing pilots. These frameworks shape equipment certification costs, regional product variants, and market access timelines for chipset vendors. Stakeholders must monitor spectrum auction outcomes and open RAN interoperability mandates as these decisions will determine which technology suppliers retain socket positions in next-generation network builds.
Market Dynamics
Enterprise demand for deterministic latency below ten milliseconds is compressing equipment refresh cycles across manufacturing automation, forcing chipset vendors to prioritize real-time processing capabilities over peak throughput benchmarks.
Growth Catalysts
- Private 5G spectrum licensing:Germany's Bundesnetzagentur and the FCC have allocated localized frequency blocks for industrial campus networks, enabling automotive plants and container ports to deploy dedicated infrastructure without public operator dependency.
- Smart grid modernization:Utility operators in China and the United States are replacing aging SCADA telemetry with cellular IoT modules capable of bidirectional load balancing and distributed energy resource coordination.
- Open RAN interoperability mandates:The EU AI Act and O-RAN Alliance specifications are compelling baseband suppliers to disaggregate hardware and software layers, lowering switching costs for mobile network operators.
Market Restraints
- Gallium nitride substrate scarcity:RF power amplifier foundry capacity concentrates among Taiwanese and Japanese suppliers, creating input cost volatility for millimeter-wave base station deployments.
- Spectrum auction fragmentation:Divergent mid-band allocation timelines across national regulators force chipset vendors to maintain multiple regional product variants, inflating certification budgets.
- Optical fiber substitution:Dense urban corridors with existing fiber infrastructure favor fixed-wireless access only where trenching costs exceed radio equipment premiums by substantial margins.
Strategic Opportunities
- Indian industrial IoT expansion:TRAI's machine-to-machine registration framework and the PLI scheme for telecom equipment are attracting module manufacturers to establish local assembly for agricultural telemetry and fleet tracking.
- Satellite-terrestrial convergence:Integration of 5G NTN protocols with low-earth orbit constellations is creating coverage extension opportunities for maritime and aviation connectivity previously served by geostationary links.
- Brazilian precision agriculture:ANATEL's simplified certification pathway for LPWAN devices is accelerating LoRaWAN adoption across soybean and sugarcane operations in Mato Grosso and São Paulo states.
Industry Challenges
- Embedded systems talent scarcity:Real-time operating system programming and RF front-end design expertise pools remain shallow relative to deployment timelines for industrial automation integrators.
- Multi-band certification complexity:Equipment vendors must navigate sequential approval processes from the FCC, ETSI, and China's MIIT for global product launches, compressing margin recovery windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wireless Data Communication Market |
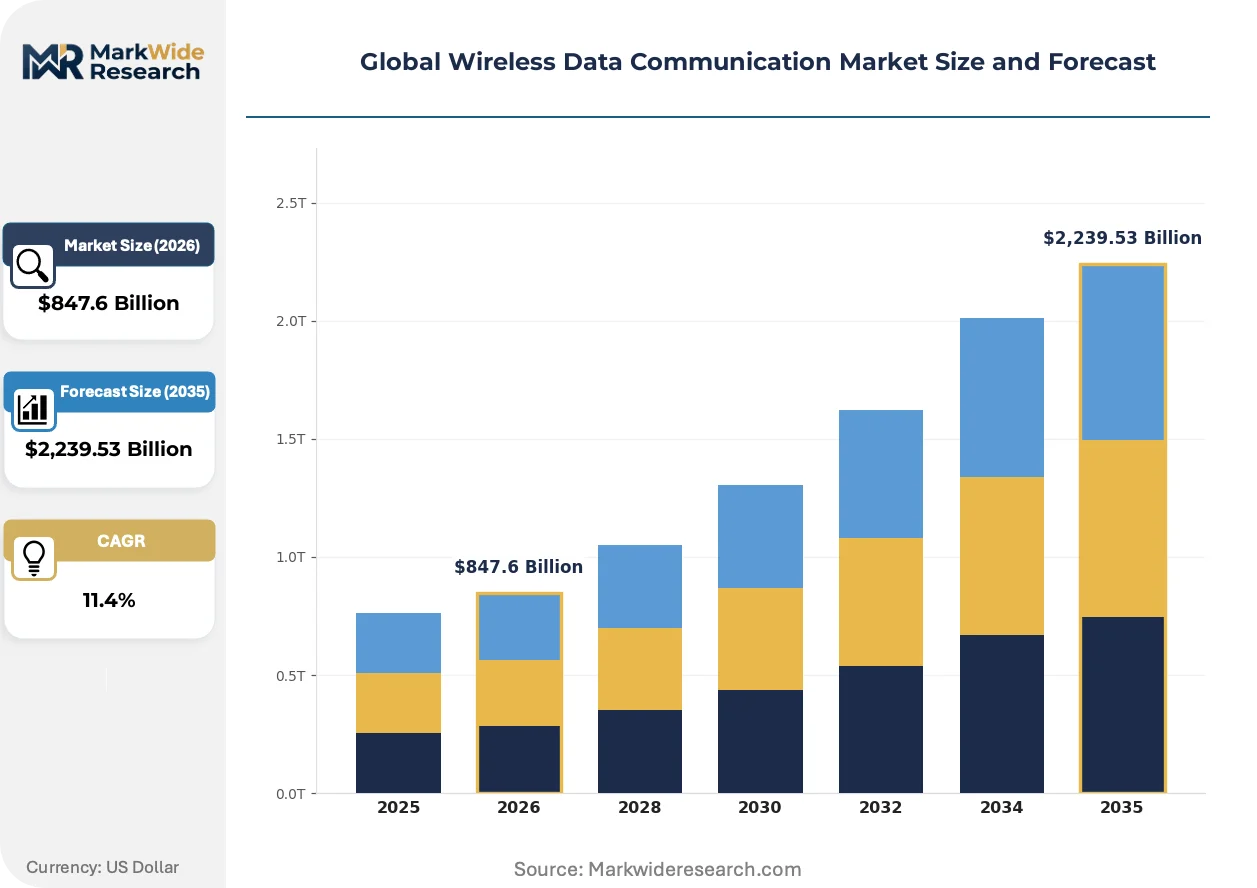
| Market Size in 2026 | $847.6 Billion |
| Market Size in 2035 | $2,239.53 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wi-Fi, Bluetooth, Zigbee, LTE, 5G, LoRaWAN Application: Smart Homes, Industrial Automation, Healthcare Monitoring, Transportation, Agriculture, Smart Grid End User: Telecommunication Providers, Manufacturing Plants, Hospitals, Public Transport Operators, Farming Enterprises, Energy Utilities Deployment: Private Networks, Public Networks, Mesh Networks, Cellular Networks, Satellite Networks |
| Companies Covered | Qualcomm Incorporated, Broadcom, Intel Corporation, Huawei Technologies, Cisco Systems, NXP Semiconductors, STMicroelectronics, MediaTek, Texas Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wireless Data Communication Market Shifts & Advancements
Radio access network architecture is undergoing fundamental disaggregation as operators demand vendor mixing without proprietary lock-in, compressing traditional equipment supplier margins while opening sockets for specialized software vendors.
Virtualized baseband processing is virtualizing network function deployment across commodity server hardware. Tier-one operators in South Korea and Germany are migrating cell site processing to centralized edge data centers, collapsing dedicated hardware footprints by substantial ratios. This shift is virtualizing the traditional RAN equipment market structure, enabling software-centric suppliers to capture value previously absorbed by integrated hardware vendors.
ETSI's F5G fixed-wireless standards and the EU Green Deal connectivity targets are mandating energy efficiency disclosures for broadband access equipment. Equipment vendors must now document power consumption per subscriber under standardized load conditions, altering procurement evaluation criteria for municipal network tenders. German and French operators have begun weighting sustainability metrics at parity with technical specifications in vendor selection processes.
Industrial buyers are consolidating radio module procurement through system integrators rather than direct component sourcing. Manufacturing automation projects in Michigan and Bavaria increasingly specify turnkey wireless infrastructure packages where module selection is subordinate to overall system performance guarantees. This pattern concentrates purchasing influence among Rockwell, Siemens, and comparable platform vendors, compressing direct sales channels for chipset suppliers.
Global Wireless Data Communication Market Segmentation
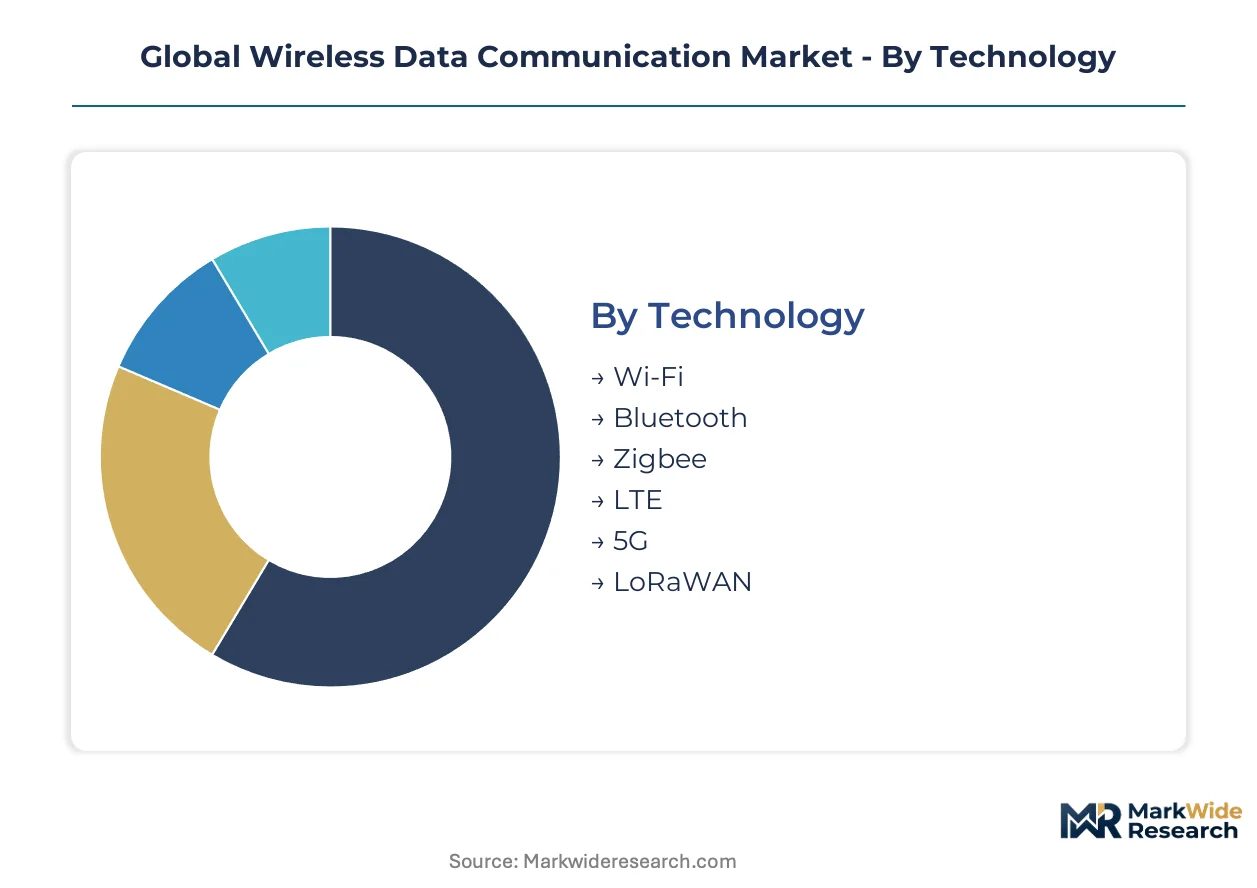
Wireless data communication markets fragment across multiple intersecting dimensions. Technology choices determine spectrum access and power budgets. Application requirements dictate latency tolerances and reliability thresholds. Deployment models shape capital intensity and operational control.
Technology:
Mature protocols coexist with emerging standards across diverging performance envelopes.
- 5G:New Radio specifications deliver sub-10 millisecond latency through massive MIMO antenna arrays and network slicing. German automotive plants and Chinese container ports deploy private 5G for deterministic robotic control where cable replacement is impractical.
- Wi-Fi:IEEE 802.11be (Wi-Fi 7) pushes 320 MHz channel bonding and 4K-QAM modulation for multi-gigabit indoor throughput. Enterprise campuses in the United States prioritize Wi-Fi 7 for high-density conferencing and AR/VR training environments.
- Bluetooth:Low-energy variants enable proximity-based device pairing and indoor positioning.
- Zigbee:Mesh topology protocols serve smart lighting and building automation clusters.
- LTE:Category M1 and NB-IoT modules provide fallback connectivity where 5G coverage remains incomplete.
- LoRaWAN:Sub-GHz spread-spectrum modulation extends battery life to decade scales for agricultural soil sensors and utility meter endpoints.
5G handles the majority of throughput; LoRaWAN is expanding most quickly on share.
Application:
Cost tiers separate capital-intensive industrial deployments from consumer-scale implementations.
- Industrial Automation:Time-sensitive networking overlays synchronize programmable logic controllers and collaborative robots. Manufacturing plants in Michigan and Bavaria demand deterministic wireless for safety-critical motion control loops.
- Smart Grid:Phasor measurement units and distribution automation require bidirectional telemetry for load balancing. Chinese and United States utilities replace aging SCADA with cellular IoT modules capable of distributed energy resource coordination.
- Smart Homes:Consumer electronics integrate multiple radio protocols for seamless device interoperability.
- Healthcare Monitoring:Wearable biosensors transmit continuous vital signs through low-power wide-area links.
- Transportation:Vehicle-to-everything communication enables collision avoidance and traffic optimization.
- Agriculture:Precision farming deployments use soil moisture and weather station networks for irrigation automation.
Industrial Automation commands premium pricing; Smart Grid is gaining share fastest.
End User:
Customer types diverge in procurement sophistication and technical specification authority.
- Telecommunication Providers:Mobile network operators aggregate spectrum licenses and deploy macro-cell infrastructure across national footprints. South Korean and German carriers virtualize baseband processing to collapse hardware footprints.
- Manufacturing Plants:Discrete and process industries specify turnkey wireless infrastructure through system integrators. Rockwell and Siemens platforms concentrate module purchasing influence in Michigan and Bavaria automation projects.
- Hospitals:Healthcare facilities require electromagnetic interference immunity for patient monitoring equipment.
- Public Transport Operators:Railway and bus systems deploy passenger Wi-Fi and operational telemetry.
- Farming Enterprises:Agricultural cooperatives adopt LPWAN for irrigation and livestock tracking.
- Energy Utilities:Electric power companies modernize distribution networks with cellular-connected sensors.
Telecommunication Providers anchor volume; Manufacturing Plants show the steepest expansion trajectory.
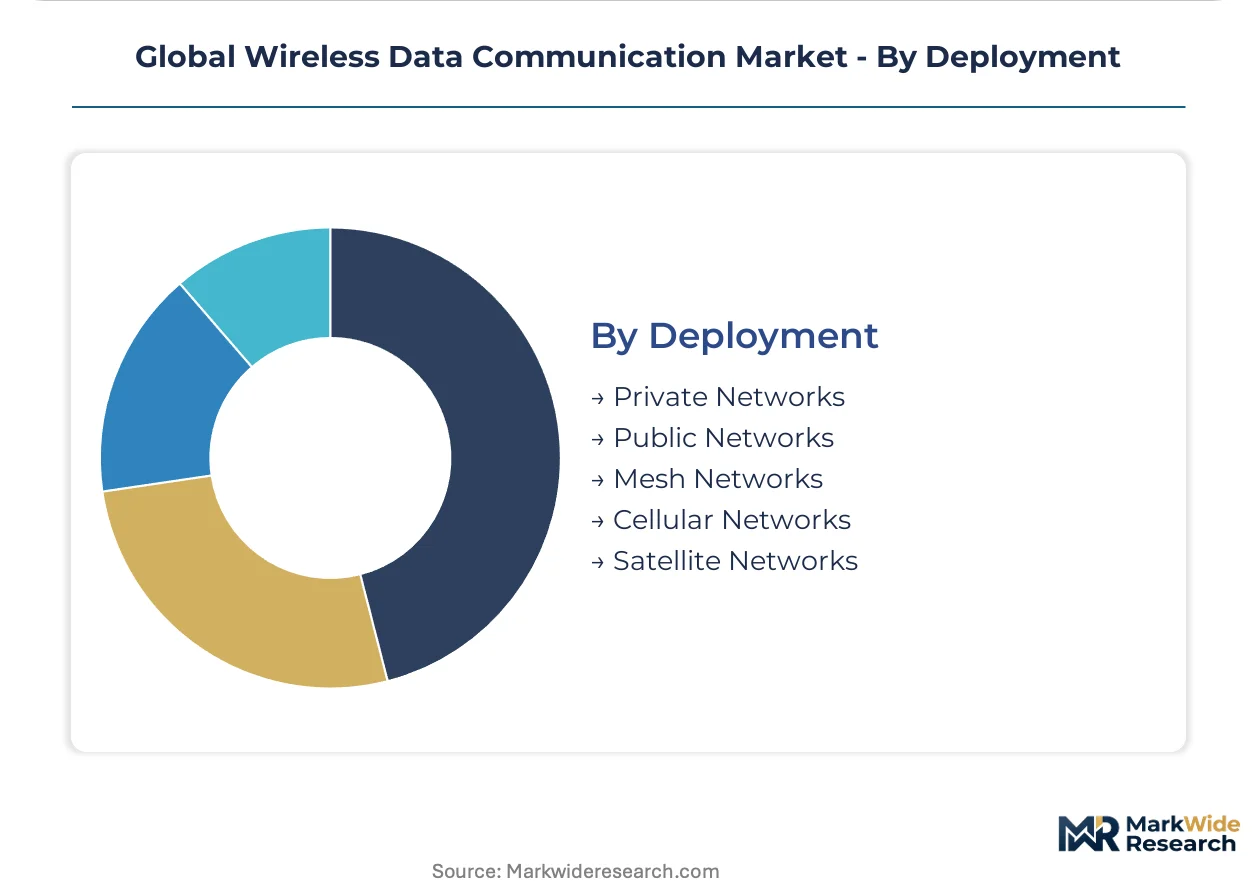
Deployment:
Control models separate infrastructure ownership from service-based consumption.
- Private Networks:Dedicated spectrum allocations enable campus-scale autonomy without public operator dependency. Germany's Bundesnetzagentur and the FCC license localized frequency blocks for automotive plants and mining operations.
- Cellular Networks:Licensed spectrum access through mobile network operators provides wide-area coverage with roaming interoperability.
- Public Networks:Shared infrastructure reduces capital burden for smaller enterprises.
- Mesh Networks:Self-healing topologies extend coverage without backbone dependency.
- Satellite Networks:Geostationary and low-earth orbit constellations serve maritime and aviation corridors.
Private Networks capture the highest margins; Cellular Networks maintain the broadest geographic footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea exports millimeter-wave baseband chipsets to German automotive OEMs for private 5G campus deployments, while Chinese module manufacturers supply LoRaWAN endpoints to Brazilian agricultural cooperatives.
United States
Private 5G spectrum auctions by the FCC have enabled automotive plants in Michigan and container ports in California to deploy deterministic wireless for robotic control. The IRA's clean energy provisions accelerate smart grid modernization, with utilities in Texas replacing aging SCADA systems with cellular-connected sensors for distributed energy coordination.
Germany
Industrial automation demand from Bavarian manufacturing clusters drives adoption of time-sensitive networking overlays. Bundesnetzagentur localized spectrum licensing permits automotive plants in Stuttgart and Wolfsburg to operate campus-scale 5G without public operator dependency, while the EU AI Act mandates open RAN interoperability for baseband procurement.
China
Container ports in Shanghai and Shenzhen deploy private 5G for automated guided vehicle coordination, with MIIT allocating dedicated industrial spectrum blocks through local licensing pilots. State Grid Corporation modernizes distribution networks with cellular IoT modules capable of bidirectional load balancing across provincial grids.
India
TRAI's machine-to-machine registration framework and PLI scheme for telecom equipment attract module manufacturers to establish local assembly. Agricultural telemetry deployments in Maharashtra and Gujarat use LPWAN networks for irrigation automation, while fleet tracking systems expand across Haryana logistics corridors.
Brazil
ANATEL's simplified certification pathway for LPWAN devices accelerates LoRaWAN adoption across soybean operations in Mato Grosso and sugarcane plantations in São Paulo. Precision agriculture investments require soil moisture and weather station networks that operate on decade-scale battery life.
Global Wireless Data Communication Market Competitive Landscape
Channel-controlling players compete with product-specialist players across diverging technology vectors. The vendor base organizes around three strategic archetypes: integrated modem-RF system suppliers, premium Wi-Fi chipset specialists, and private 5G infrastructure deployers. Consolidation pressures concentrate among baseband processor vendors as open RAN mandates disaggregate hardware and software layers. Dominant competitive moves include strategic partnerships for spectrum access and portfolio diversification into automotive platforms.
Within the integrated system tier, Qualcomm Incorporated and Broadcom exemplify contrasting approaches to RF front-end capture. Cisco Systems anchors the private network infrastructure vector. These three entities represent distinct competitive positions: modem-RF integration, vertical silicon production, and turnkey campus deployment capability respectively.
| Leading Market Players |
|---|
| Qualcomm Incorporated |
| Broadcom |
| Intel Corporation |
| Huawei Technologies |
| Cisco Systems |
| NXP Semiconductors |
| STMicroelectronics |
| MediaTek |
| Texas Instruments |
| Others |
Supply & Pricing Matrix
Shanghai-Shenzhen freight corridors carry gallium nitride substrates and RF front-end modules from Taiwanese foundries to mainland Chinese assembly plants, where input cost volatility from concentrated substrate supply reshapes chipset pricing tiers and forces buyers toward long-term contract structures with indexed adjustments.
Pricing Analysis
Cost-plus contracts with gallium nitride substrate indexation dominate millimeter-wave base station procurement, separating premium-tier massive MIMO arrays with FCC and ETSI dual certification from standard-tier single-band equipment and economy-grade unlicensed devices. Price differentiation hinges on certification grade and volume scale, with automotive OEMs in Stuttgart and Wolfsburg showing lowest sensitivity due to deterministic latency requirements while agricultural cooperatives in Mato Grosso face acute pressure. Pricing pressure stems from gallium nitride substrate scarcity among Japanese and Taiwanese suppliers, compressing margins for mid-tier baseband processor vendors.
Supply Chain Analysis
Gallium nitride substrates and silicon germanium wafers feed from specialized foundries in Taiwan, Japan, and the United States into RF power amplifier fabrication. Raw material dependencies center on rare earth processing for filter components, advanced packaging substrates, and millimeter-wave antenna substrates. Single-source vulnerability concentrates in Taiwanese gallium nitride epitaxy capacity, exposing equipment vendors to disruption from regional logistics constraints. Distribution runs through module manufacturers in China and South Korea to system integrators like Rockwell and Siemens, who consolidate procurement influence for manufacturing automation projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Private 5G spectrum licensing and open RAN interoperability mandates are disrupting vendor lock-in architectures, creating asymmetric opportunities across the value chain as software-centric suppliers capture sockets previously held by integrated hardware vendors.
For Market Incumbents: Entrench modem-RF integration advantages through captive supply of filter and front-end modules, while accelerating certification investment for ETSI EN 300 328 and FCC Part 15 dual-approval to defend against emerging software-defined radio entrants. Prioritize capacity addition in South Korean and German edge data center clusters where virtualized baseband processing is collapsing traditional hardware footprints.
For New Entrants and Emerging Players: Establish a beachhead in Indian agricultural telemetry by exploiting TRAI's machine-to-machine registration framework and the PLI scheme's local assembly incentives, where module procurement remains fragmented among farming cooperatives. Target Brazilian precision agriculture through ANATEL's simplified LPWAN certification pathway, leveraging LoRaWAN's decade-scale battery life for soil sensor networks in Mato Grosso soybean operations.
For Investors and Strategic Acquirers: Specialized RF front-end designers with gallium nitride process expertise represent the most defensible acquisition archetype, given the shallow talent pool for real-time operating system programming and millimeter-wave design. Watch for inflection signals in FCC and Bundesnetzagentur private spectrum auction volumes, which indicate industrial automation capital commitment intensity and predict module demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Software Certification | ETSI and O-RAN Alliance compliance unlocks mobile operator procurement channels previously closed to specialized vendors. |
| Gallium Nitride Capacity Expansion | Captive epitaxy growth in Taiwan and Japan insulates RF amplifier supply against substrate scarcity volatility. |
| Private 5G Campus Deployment | FCC and Bundesnetzagentur localized licensing enables automotive plants to bypass public operator dependency. |
| Satellite-Terrestrial Protocol Integration | 5G NTN standardization with low-earth orbit constellations extends coverage to maritime corridors beyond cellular reach. |
| Industrial IoT Module Localization | TRAI's PLI scheme attracts assembly investment for agricultural telemetry in Maharashtra and Gujarat farming belts. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the project, combining primary interviews with network planning executives at German automotive OEMs, RF design leads at Taiwanese foundries, procurement managers at Michigan manufacturing plants, and regulatory affairs specialists navigating FCC and ETSI certification pathways. Secondary validation drew from FCC spectrum auction records, ETSI standardization documents, MIIT local licensing pilot disclosures, and SEC filings from baseband processor vendors. Bottom-up module shipment aggregation and top-down infrastructure capex analysis were triangulated to cross-verify volume estimates.
Calibration against historical 5G base station deployment trajectories and LoRaWAN endpoint adoption curves anchored growth rate derivation across the projection horizon. Segmentation dimensions modeled include technology protocol, application latency requirement, end-user procurement sophistication, and deployment control model, with industrial automation's deterministic sub-10 millisecond threshold treated as a distinct performance tier. CAGRs were synthesized from equipment vendor shipment disclosures, operator capex guidance, and spectrum allocation timelines without year-specific anchoring.
Stress conditions across gallium nitride substrate supply disruption, divergent national spectrum auction timelines, and optical fiber substitution in dense urban corridors were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about open RAN interoperability mandate implementation pace and private spectrum licensing volume. Cross-checking against hyperscaler edge data center capex disclosures and industrial automation system integrator backlog reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Global Wireless Testing Market
Wireless Technologies
Multefire Market
Wireless Technologies
Voice Over Wifi Market
Wireless Technologies
Mobile WLAN Access Points Market
Wireless Technologies
Europe Wireless Charging Market
Wireless Technologies
Femtocell Market
Wireless Technologies
5G Wireless Equipment Market
Wireless Technologies
Near Field Communication Market
Wireless Technologies
Wireless Paging Systems Market
Wireless Technologies
Public Safety Wireless Communication and Municipal Wireless Communication Market
Wireless Technologies
Global in-Building Wireless Market
Wireless Technologies
Distributed Antenna System Market
Wireless Technologies
Outdoor Wi-Fi Market
Wireless Technologies
Wireless Telecommunication Services Market
Wireless Technologies
Industrial Wireless Solution Market
Wireless Technologies
Enterprise WLAN Market