
 Asia-Pacific Wi-Fi 6 Market | 2026-2036
Asia-Pacific Wi-Fi 6 Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Wi-Fi 6 Market Insights
Modular controller-plus-access-point bundles is rebalancing procurement patterns across enterprise buyers. Huawei Technologies Co., Ltd. leverages its integrated silicon-to-system stack to dominate carrier-grade deployments. TP-Link Technologies Co., Ltd. competes aggressively on price-performance ratios in the residential tier. H3C Technologies Co., Ltd. anchors its position through deep vertical specialization in campus networking across Chinese municipalities.
Asia-Pacific Wi-Fi 6 refers to wireless local area network equipment operating in the 2.4 GHz, 5 GHz, and 6 GHz bands, employing 1024-QAM modulation and orthogonal frequency-division multiple access to deliver theoretical peak throughput of 9.6 Gbps. Its primary commercial purpose is to support high-density connectivity for Internet of Things ecosystems, streaming media, and real-time collaboration platforms. Router and access point categories command the largest installed base, though cloud-based deployment models are expanding fastest as managed service providers consolidate operational overhead. Education end users represent a concentrated margin pool where performance optimization solutions offset compressed hardware margins.
China's MIIT enforces GB standards for radio equipment type approval, while Japan's METI coordinates spectrum policy through the Radio Act. India's TRAI regulates unlicensed band power limits that directly shape indoor coverage economics. South Korea's spectrum framework under the Ministry of Science and ICT enables 6 GHz Wi-Fi 6E expansion. Stakeholders must weigh silicon supply security against the pace of 6 GHz regulatory harmonization.
Market Dynamics
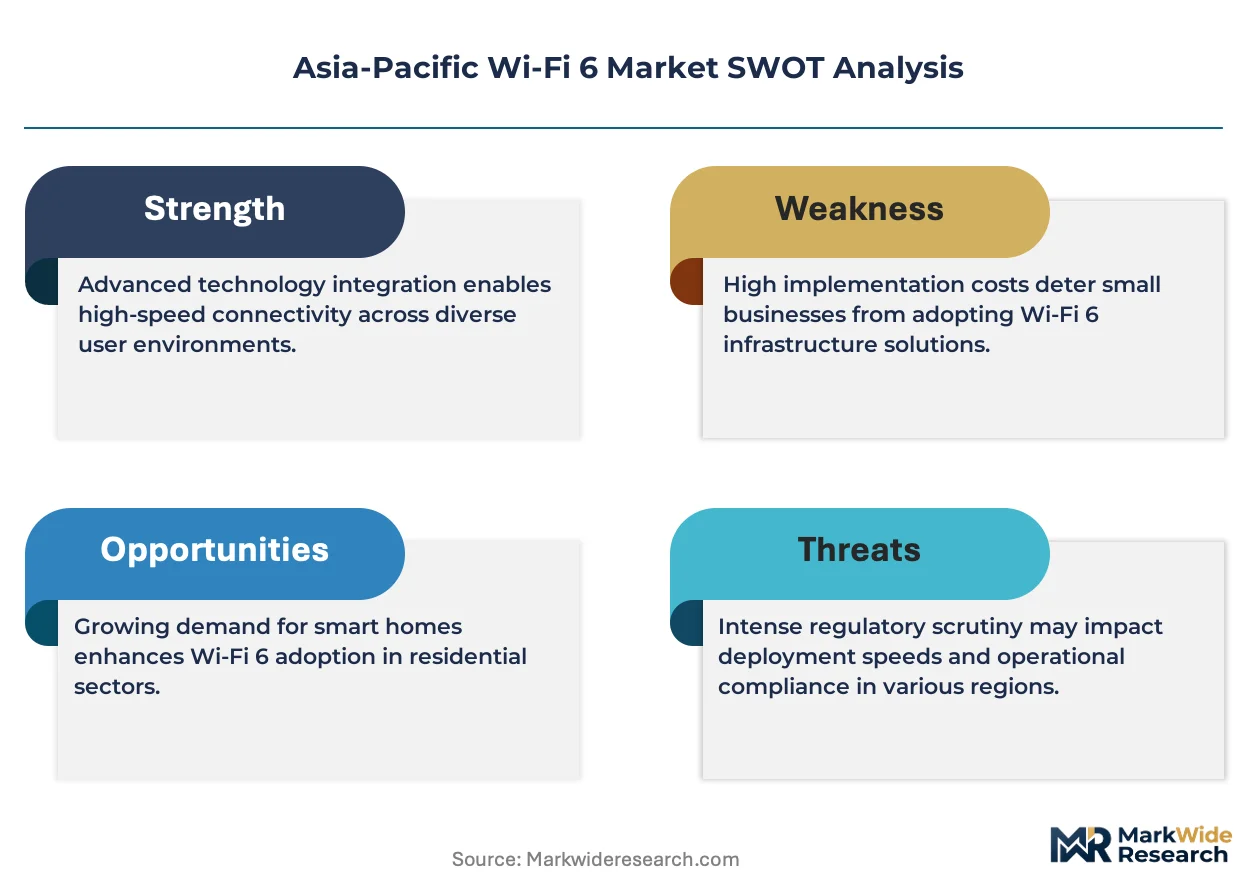
The Asia-Pacific Wi-Fi 6 market is being restructured by regulatory fragmentation across spectrum allocation regimes, where divergent 6 GHz opening timelines in South Korea, Japan, and India are forcing vendors to maintain multiple hardware SKUs and certification tracks simultaneously.
Growth Catalysts
- India's TRAI spectrum liberalization:Licensed-exempt band expansions in the 5.8 GHz and 6 GHz ranges are reducing deployment costs for enterprise campuses and smart manufacturing facilities in Bengaluru and Hyderabad corridors.
- Smart manufacturing backhaul substitution:Low-latency wireless infrastructure is replacing wired Ethernet in China's Guangdong and Jiangsu industrial zones, driven by robotic automation density requirements.
- IoT ecosystem densification:Enterprise campuses in South Korea are upgrading access point counts to support 200+ device densities per classroom and conference zone.
Market Restraints
- Silicon supply concentration:Advanced Wi-Fi 6E system-on-chip fabrication depends on Taiwan-based foundry capacity, creating geographic single-point vulnerability for the entire regional supply base.
- Regulatory harmonization friction:China's MIIT GB standards for 6 GHz power limits diverge from South Korea's Ministry of Science and ICT frameworks, forcing redundant type-approval investments.
- Cabling infrastructure substitution economics:Fiber-to-the-desk deployments in premium Japanese commercial real estate retain cost advantages for sub-50ms latency requirements.
Strategic Opportunities
- Vietnam and Indonesia manufacturing corridors:Greenfield industrial zone developments in Hai Phong and Batang lack legacy wired infrastructure, enabling wireless-first architecture adoption.
- Cloud-managed deployment models:Managed service providers are consolidating operational overhead for mid-market enterprises through subscription-based access point provisioning.
- Japan's METI 6 GHz coordination:The Radio Act amendment process is creating first-mover advantages for vendors with pre-certified 6E hardware portfolios.
Industry Challenges
- RF engineering talent scarcity:Compound semiconductor and antenna design expertise concentrates in Shenzhen and Taipei, constraining vendor R&D scaling in secondary markets.
- Legacy 802.11n/ac interoperability:Brownfield enterprise upgrades require complex band-steering algorithms to prevent performance degradation in mixed-generation device environments.
- Multi-country certification pipeline:Sequential approval processes across China's MIIT, Japan's TELEC, and South Korea's RRA extend product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Wi-Fi 6 Market |
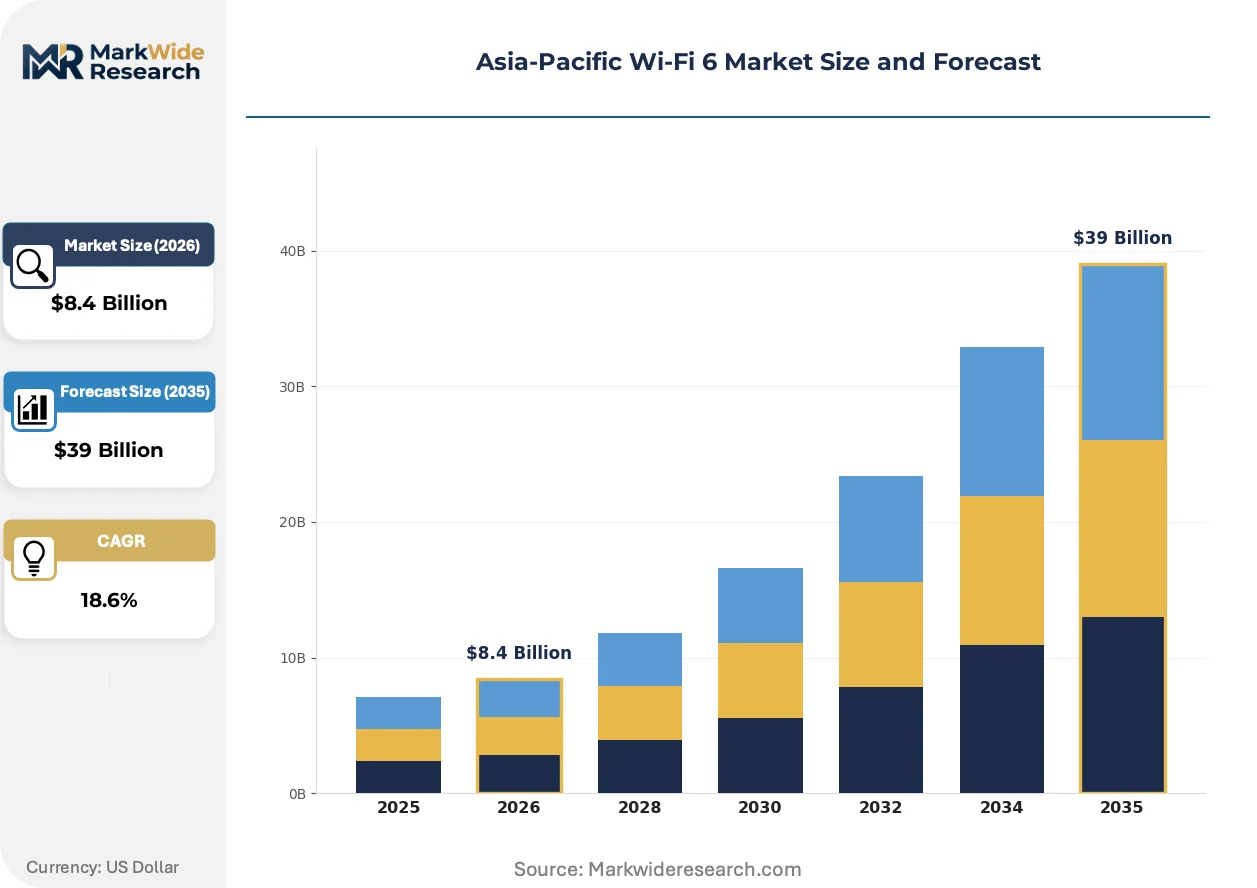
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $39 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
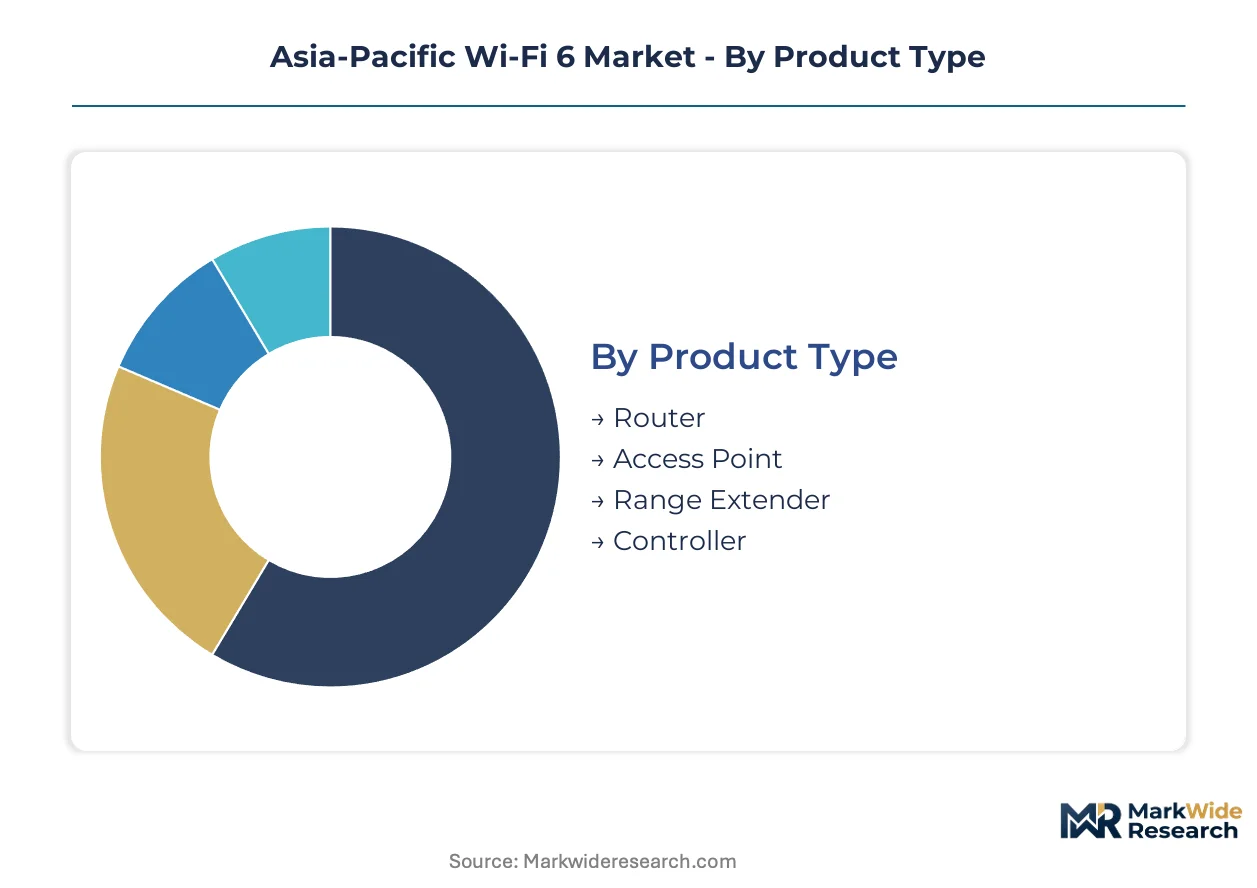
| Segmentation | Product Type: Router, Access Point, Range Extender, Controller End User: Residential, Commercial, Industrial, Education Deployment: On-premises, Cloud-based, Hybrid, Managed Service Solution: Network Security, Performance Optimization, Connectivity Management, Monitoring Tools |
| Companies Covered | Huawei Technologies Co., Ltd., TP-Link Technologies Co., Ltd., D-Link Corporation, ASUSTeK Computer Inc., Zyxel Communications Corp., H3C Technologies Co., Ltd., Ruijie Networks Co., Ltd., ZTE Corporation, Xiaomi Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Wi-Fi 6 Market Trends and Innovations
Wi-Fi 6 infrastructure is being redefined by three concurrent shifts: silicon-level integration of AI-driven radio resource management, regulatory pressure toward 6 GHz harmonization, and procurement model migration from capital expenditure to operational expenditure frameworks.
Artificial intelligence-based radio resource management is integrating directly into access point firmware to enable real-time channel optimization and client steering. South Korean semiconductor firms are embedding neural processing units alongside baseband modems. This capability is compressing the performance gap between enterprise-grade and carrier-grade hardware tiers.
Japan's METI is coordinating 6 GHz Wi-Fi 6E expansion through amendments to the Radio Act, with draft power limit frameworks released for industry consultation. The industrial consequence is accelerated indoor coverage economics for logistics warehouses and automated manufacturing facilities. Japanese system integrators are pre-positioning installation capacity ahead of final rule publication.
Enterprise buyers are consolidating vendor relationships through modular controller-plus-access-point bundle contracts that shift technical support liability to manufacturers. China's state-owned enterprise procurement platforms are mandating five-year total cost of ownership calculations. This behavior is most visible in education vertical tenders across Chinese municipalities, where performance optimization service attachments offset compressed hardware margins.
Asia-Pacific Wi-Fi 6 Market Segmentation
Wi-Fi 6 procurement patterns diver sharply across deployment contexts, with enterprise buyers prioritizing controller-based manageability while residential demand concentrates on standalone router replacements. The upgrade cycle from 802.11ac infrastructure is segmenting purchasing behavior by latency tolerance, device density requirements, and operational control preferences.
Product Type:
Replacement-cycle timing varies by hardware category, with enterprise access points refreshing faster than residential routers due to three-year depreciation schedules.
- Router:Consumer-grade units integrate 1024-QAM modulation and OFDMA for multi-device households. Demand clusters in India's tier-2 cities where fiber-to-the-home rollouts require compatible CPE upgrades.
- Access Point:Enterprise ceiling-mount and wall-plate form factors dominate campus deployments. South Korean education verticals are driving dense AP counts per square meter to support 200+ concurrent connections in lecture halls.
- Range Extender:Mesh-node configurations address coverage gaps in Japanese multi-story residential concrete construction.
- Controller:Physical and virtual appliance form factors aggregate policy management for multi-site enterprises.
Volume placements concentrate in Access Point; the faster expansion belongs to Controller as cloud-managed architectures displace hardware-centric deployments.
End User:
Customer-type economics separate capital-intensive industrial buyers from subscription-oriented commercial segments.
- Residential:Single-family and multi-dwelling unit installations prioritize ease-of-setup over advanced features. India's TRAI spectrum liberalization is reducing equipment costs for mass-market penetration.
- Commercial:Retail, hospitality, and office deployments require captive portal authentication and traffic shaping. China's smart manufacturing corridors are substituting wireless for wired backhaul in Guangdong industrial zones.
- Industrial:Hardened access points withstand temperature extremes and electromagnetic interference in automated production environments.
- Education:K-12 and university tenders specify performance optimization service attachments that offset compressed hardware margins.
Commercial accounts generate the highest absolute volumes; Education is climbing the fastest as municipal procurement platforms mandate five-year total cost of ownership calculations.
Deployment:
Operational expenditure migration is restructuring how organizations acquire and maintain wireless infrastructure.
- On-premises:Controller hardware and local management software retain preference among data sovereignty-sensitive sectors. Japanese financial institutions maintain on-site control for regulatory compliance.
- Cloud-based:Centralized dashboards and firmware-over-the-air updates reduce field technician dispatch requirements. South Korean managed service providers are consolidating mid-market operational overhead through subscription models.
- Hybrid:Split-tunnel architectures route sensitive traffic locally while offloading guest access to cloud controllers.
- Managed Service:Third-party operational liability appeals to enterprises lacking in-house RF engineering expertise.
On-premises retains the largest installed base; Cloud-based is gaining share fastest as mid-market buyers abandon capital-intensive refresh cycles.
Solution:
Software-layer attach rates determine margin outcomes as hardware commoditization accelerates across the region.
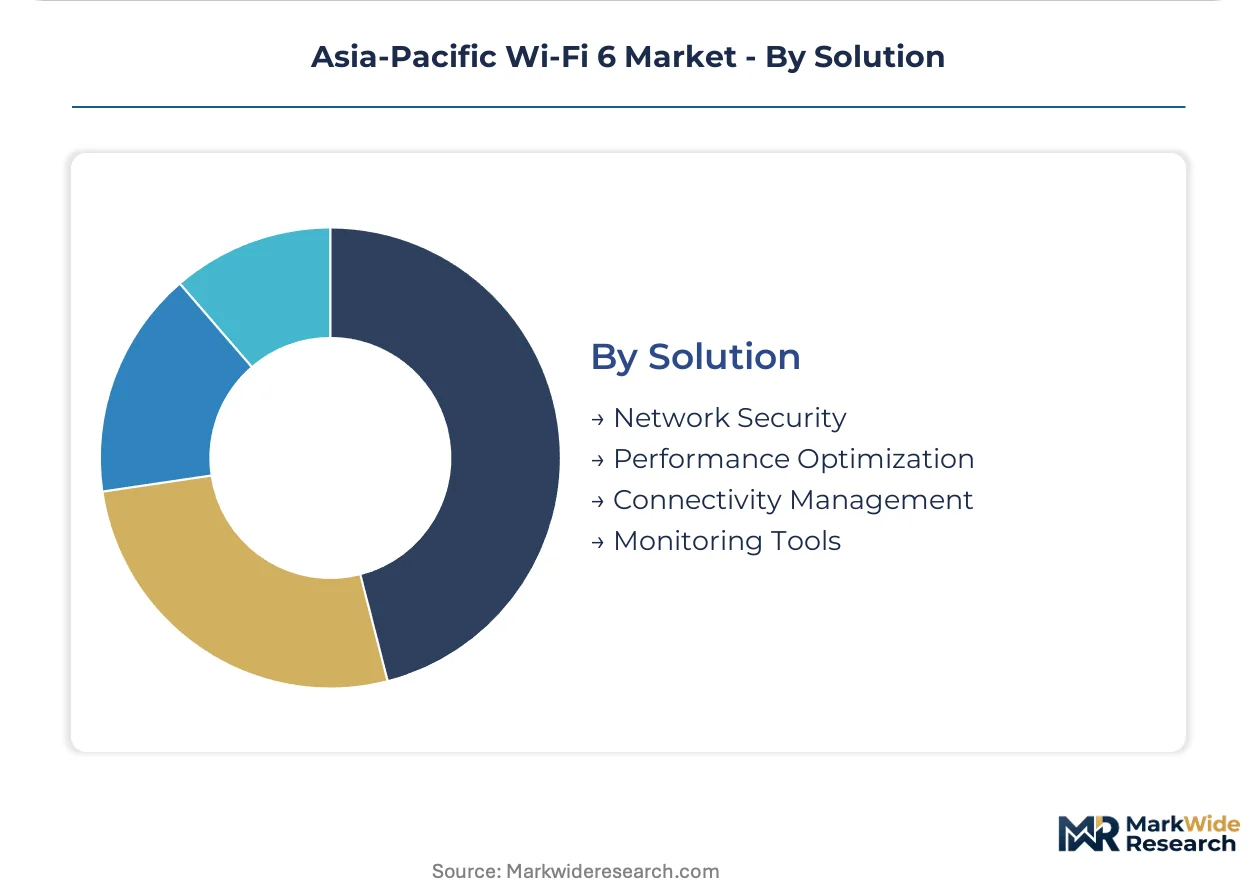
- Network Security:WPA3 encryption, rogue AP detection, and micro-segmentation protect against lateral movement. China's MIIT GB standards mandate specific cryptographic implementations for type approval.
- Performance Optimization:AI-driven radio resource management and band-steering algorithms maximize spectral efficiency. South Korean semiconductor firms embed neural processing units alongside baseband modems for real-time optimization.
- Connectivity Management:Policy engines govern quality-of-service tiers and application prioritization.
- Monitoring Tools:Heat mapping and client analytics support capacity planning and troubleshooting workflows.
Network Security commands the highest attach rates; Performance Optimization shows the steepest expansion trajectory as AI integration compresses the enterprise-carrier hardware tier gap.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's Guangdong province concentrate Wi-Fi 6 manufacturing infrastructure alongside dense deployment corridors. India's software technology parks and South Korea's digital media cities anchor regional demand clusters. Regulatory harmonization friction across MIIT, TRAI, and METI frameworks shapes vendor certification strategies.
China
Smart manufacturing corridors in Guangdong and Jiangsu provinces drive enterprise access point density requirements. MIIT enforces GB standards for radio equipment type approval with specific 6 GHz power limit frameworks. Shenzhen anchors silicon-to-system integration capabilities for carrier-grade deployment manufacturing.
South Korea
Enterprise campuses in Seoul and Daejeon upgrade access point counts to support 200-plus device densities per classroom zone. The Ministry of Science and ICT coordinates 6 GHz Wi-Fi 6E expansion through spectrum framework amendments. Busan-Ulsan industrial zones deploy low-latency wireless backhaul for robotic automation density.
India
Enterprise campuses and smart manufacturing facilities in Bengaluru and Hyderabad corridors expand licensed-exempt band utilization. TRAI spectrum liberalization policies accelerate 5.8 GHz and 6 GHz range allocations for cost reduction. Tier-2 cities drive residential router replacement cycles alongside fiber-to-the-home rollout compatibility.
Japan
Logistics warehouses and automated manufacturing facilities in Kanto and Kansai regions await METI Radio Act amendments for 6 GHz indoor coverage economics. Premium commercial real estate in Tokyo retains fiber-to-the-desk deployments for sub-50ms latency requirements. System integrators pre-position installation capacity ahead of final 6E rule publication.
Vietnam
Greenfield industrial zone developments in Hai Phong lack legacy wired infrastructure and enable wireless-first architecture adoption. The country's national telecommunications regulator manages unlicensed band power limits shaping indoor coverage economics. Manufacturing corridor investments from regional technology firms concentrate deployment demand in northern provinces.
Asia-Pacific Wi-Fi 6 Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware and managed service tiers. The vendor base organizes around silicon-to-system integration depth versus price-performance optimization strategies. Three archetypes dominate: integrated technology conglomerates with captive semiconductor capabilities, networking specialists with vertical campus expertise, and consumer electronics platforms leveraging scale economics. Competitive moves concentrate on cloud-managed deployment model expansion and modular controller-plus-access-point bundle contracting.
Within the integrated technology tier, Huawei Technologies Co., Ltd. and ZTE Corporation represent archetypes of silicon-to-system stack control. TP-Link Technologies Co., Ltd. exemplifies price-performance positioning in volume residential segments. H3C Technologies Co., Ltd. anchors specialized campus networking depth across Chinese municipal procurement platforms. These three structures illustrate how geographic origin and organizational form shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd. |
| TP-Link Technologies Co., Ltd. |
| D-Link Corporation |
| ASUSTeK Computer Inc. |
| Zyxel Communications Corp. |
| H3C Technologies Co., Ltd. |
| Ruijie Networks Co., Ltd. |
| ZTE Corporation |
| Xiaomi Corporation |
| Others |
Pricing and Supply Chain Analysis
Carrier-grade certification tiers diverge sharply from residential commodity tiers, with MIIT GB compliance costs and Taiwan foundry allocation priority embedding directly into landed cost structures across enterprise and consumer segments alike.
Pricing Analysis
Short lead-time premiums command 15-25% markups over standard delivery windows as Taiwan foundry slot scarcity intensifies allocation battles. Three-tier pricing structure across carrier-certified, enterprise-grade, and residential economy levels separates buyers by certification burden and support bundling. Pricing pressure stems from TP-Link's aggressive volume positioning in India's tier-2 cities, compressing hardware margins across the residential tier. Education verticals show lowest price sensitivity due to five-year total cost of ownership procurement mandates, while mass-market residential buyers in Vietnam and Indonesia prioritize spot-price competitiveness above feature depth.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based foundry capacity for advanced Wi-Fi 6E system-on-chip fabrication, creating geographic concentration risk for the entire regional supply base. Component sourcing draws from South Korean memory suppliers, Chinese PCB substrate manufacturers, and Japanese passive component specialists. Tariff exposure intensifies as US-China technology restrictions fragment silicon-to-system integration pathways. Distribution runs through Shenzhen electronics hubs for hardware consolidation, with cloud-managed service platforms disaggregating traditional channel structures across South Korean and Japanese enterprise markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific Wi-Fi 6 market sits in a technology-transition phase where Wi-Fi 6E spectrum expansion is displacing legacy 802.11ac infrastructure across enterprise and industrial deployments.
For Market Incumbents: Cement carrier-grade certification depth through MIIT GB pre-approval investments ahead of 6 GHz harmonization. Prioritize captive silicon supply agreements with Taiwan foundries to defend against allocation scarcity. Deepen controller-plus-access-point bundle attach rates in Chinese municipal education tenders to offset hardware margin compression from TP-Link's residential aggression.
For New Entrants and Emerging Players: Direct-to-cloud managed service platforms offer the lowest barrier-to-entry pathway for mid-market enterprise penetration. Target Vietnam's Hai Phong and Indonesia's Batang greenfield industrial zones where wireless-first architecture lacks incumbent wiring legacy. Lead with subscription-based operational expenditure models that bypass capital-intensive hardware competition.
For Investors and Strategic Acquirers: Re-rating potential sits with vertical-specialist campus networking firms given METI Radio Act amendment catalysts accelerating Japan 6E adoption. Long-term viability favors vendors with pre-certified hardware portfolios and cloud-native management stacks. Monitor TRAI 6 GHz allocation timing as the inflection signal for Indian enterprise demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| 6 GHz Pre-Certification Investment | METI Radio Act amendments create first-mover positioning in Japanese logistics and manufacturing verticals. |
| Cloud-Managed Platform Launch | South Korean MSP consolidation reduces field technician dependency for mid-market enterprise accounts. |
| Taiwan Foundry Capacity Reservation | Silicon supply security anchors carrier-grade delivery commitments against allocation scarcity. |
| Education Vertical Bundle Contracting | Chinese municipal TCO mandates favor vendors attaching performance optimization services to hardware. |
| Vietnam Greenfield Partnership | Hai Phong industrial zone wireless-first deployments bypass legacy cabling infrastructure substitution economics. |
Research Methodology
Trade databases, regulatory filings, and foundry capacity disclosures formed the secondary backbone, cross-referenced with primary interviews across RF engineering directors, carrier procurement leads, cloud MSP operators, and MIIT certification specialists. Bottom-up triangulation against top-down spectrum allocation timelines validated deployment trajectory assumptions.
Historical trendline analysis across product type, end user, and deployment model dimensions anchored the analytical framework, with segmentation modeling incorporating certification tier, vertical specialization depth, and regional regulatory harmonization status. CAGRs derived from installed base refresh cycles and greenfield adoption curves, with foundry utilization rates and TRAI spectrum release schedules as key forecast inputs.
The model holds under stable Taiwan foundry allocation and progressive 6 GHz liberalization; deviation in US-China technology restrictions or METI rule publication delays would shift trajectory. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Wireless Communication Technologies in Healthcare Market
Wireless Technologies
Wi-Fi Hotspot (Dongle) Market
Wireless Technologies
Europe Wireless Charging Market
Wireless Technologies
5G Technology ROI Market
Wireless Technologies
Wireless LAN Controller Market
Wireless Technologies
P2P Antennas Market
Wireless Technologies
Wireless Mesh Networking Market
Wireless Technologies
Multefire Market
Wireless Technologies
Wireless Phone Chargers Market
Wireless Technologies
Global Wi-Fi Market
Wireless Technologies
Global in-Building Wireless Market
Wireless Technologies
Underwater Wireless Communication Market
Wireless Technologies
Voice Over Wifi Market
Wireless Technologies
Global Bluetooth Beacon and Ibeacon Market
Wireless Technologies
APAC Small Cell 5G Market
Wireless Technologies
Global Mobile and Wireless Backhaul Market