
 Home Fitness App Market | 2026-2036
Home Fitness App Market Size, Share, and Industry Trends Forecast 2026-2036
Home Fitness App Market Outlook
Subscription unbundling is decoupling content libraries from hardware ecosystems, giving buyers flexibility to mix app subscriptions with third-party wearables. Nike leverages its brand strength in workout content to sustain engagement across independent device platforms. Peloton anchors its revenue in proprietary hardware-software bundles while competing on instructor-led production quality. Google extends its reach through OS-level fitness APIs that dominate Android distribution channels.
Home fitness apps are software platforms delivering structured exercise programming, biometric tracking, and real-time coaching through mobile and connected-device interfaces, typically requiring 10-50 MB download footprints and Bluetooth 4.0+ peripheral compatibility for heart rate and motion sensor integration. Their commercial purpose centers on converting sedentary users into recurring subscribers through personalized workout progression and social accountability mechanisms. Yoga and HIIT content within the product type dimension occupy the highest-margin pools due to lower production costs and stronger female-skewing retention curves. The freemium subscription model leads in user acquisition velocity, though annual plans capture superior lifetime value through reduced churn exposure.
FDA oversight of apps making specific health claims, GDPR data handling mandates in Europe, and CCPA privacy requirements in California collectively elevate compliance costs while creating barriers for entrants lacking legal infrastructure. These frameworks shape demand by limiting biometric data monetization and mandating explicit user consent workflows. Stakeholders must monitor evolving digital health classification thresholds that could reclassify coaching algorithms as regulated medical devices.
Market Dynamics
Subscription unbundling is fragmenting the hardware-software bundle that once locked users into single-vendor ecosystems. This structural shift enables cross-platform content consumption while eroding proprietary device margins.
Growth Catalysts
- Employer wellness mandates:Corporate benefits administrators in the United States are expanding guided workout platform subsidies as retention tools. Budget allocations for digital fitness benefits now exceed traditional gym reimbursement rates.
- GDPR Article 25:Privacy-by-design architectures mandated under European data protection law are accelerating developer investment in on-device biometric processing. This reduces cloud dependency while lowering long-term compliance overhead.
- Bluetooth 5.3 LE Audio:Low-energy audio streaming protocols are enabling synchronized multi-device workout experiences. Hardware manufacturers are integrating these chipsets into affordable heart rate monitors and motion sensors.
Market Restraints
- Content production cost inflation:Instructor-led video programming requires studio facilities and talent retention contracts that scale linearly with catalog depth. Margins compress as subscriber acquisition costs rise.
- FDA digital health classification uncertainty:Apps making specific therapeutic claims face potential reclassification as regulated medical devices. This regulatory friction delays product roadmaps and elevates legal review expenses.
- Platform commission structures:Apple App Store and Google Play billing systems extract 15-30 percent of subscription revenue. This tax structure disproportionately impacts freemium conversion economics.
Strategic Opportunities
- Medicare Advantage integration:US health plans are piloting fitness app prescriptions as supplemental benefits for aging populations. This channel bypasses direct-to-consumer acquisition costs entirely.
- AI form correction:Computer vision algorithms running on-device are converging with depth-sensing cameras. This technology pairing enables real-time movement coaching without cloud latency.
- India's PLI scheme for wearables:Production-linked incentives for domestic electronics manufacturing are reducing hardware costs for price-sensitive South Asian markets. Local assembly creates regulatory goodwill.
Industry Challenges
- Biometric data science talent scarcity:Machine learning engineers with health signal processing expertise command premium compensation. Recruitment pipelines cannot match platform expansion timelines.
- CCPA consent workflow complexity:California's privacy law mandates granular opt-in mechanisms for heart rate and location tracking. UX friction from these disclosures depresses onboarding completion rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Fitness App Market |
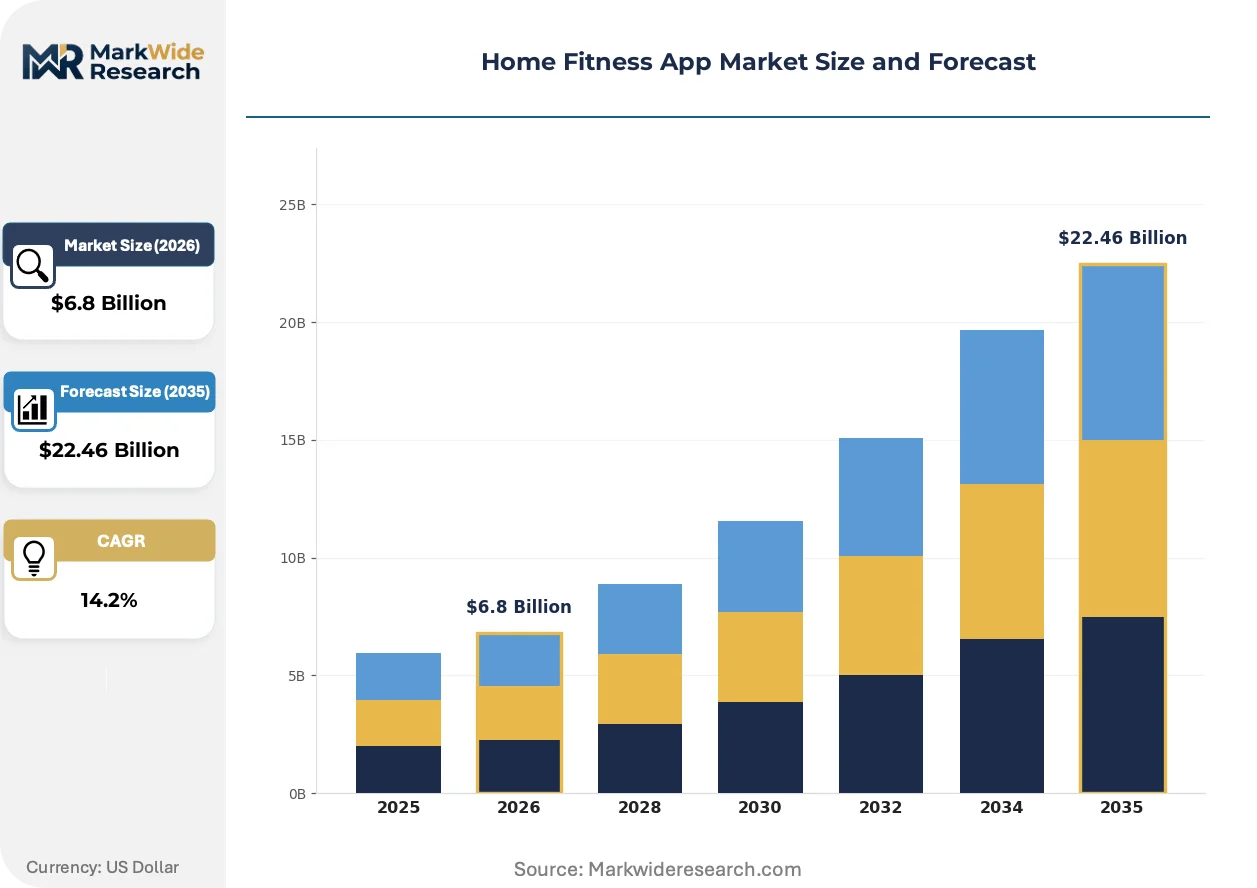
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yoga, HIIT, Strength Training, Cardio Subscription Model: Monthly, Annual, Freemium, One-Time Purchase Target User: Beginner, Intermediate, Advanced, Casual User User Engagement: Gamification, Community Features, Personal Trainer Access, Progress Tracking |
| Companies Covered | MyFitnessPal, Inc., Nike, Inc., Google LLC, Under Armour, Inc., Adidas AG, Peloton Interactive, Inc., Azumio, Inc., Strava, Inc., Samsung Electronics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Fitness App Market Strategic Shifts
Real-time coaching algorithms and cross-platform data portability are collapsing the boundaries between content libraries and sensor ecosystems. These forces are redistributing value toward software intermediaries.
On-device machine learning inference is unifying biometric signal processing with personalized workout adaptation. Fitness platforms are deploying tensor processing units in mobile chipsets to eliminate cloud round-trips. This architecture compresses latency for form feedback while reducing GDPR exposure from data transmission. The structural consequence is shifting competitive advantage from server infrastructure to algorithmic efficiency.
EU AI Act risk classification for health-related recommendation systems is elevating documentation requirements for coaching algorithms. Developers must maintain technical files demonstrating bias mitigation and human oversight protocols. Yoga and meditation content providers face lighter compliance burdens than HIIT platforms making cardiovascular claims. German and French regulators are conducting early enforcement sweeps against unsubstantiated performance promises.
Annual subscription pre-payments are displacing monthly billing as the dominant retention mechanism. Price-sensitive users in the United Kingdom and Australia are accepting upfront commitments in exchange for 40-60 percent discounts. This behavioral shift concentrates cash flow in Q1 while reducing churn volatility. Employer-sponsored wellness programs are negotiating multi-year enterprise licenses that bypass individual app store billing entirely.
Home Fitness App Market Segmentation
Home fitness apps compete across multiple dimensions simultaneously. Product type determines content production economics while subscription models shape cash flow predictability and user lifetime value curves.
Product Type:
Upgrade cycles in home fitness content follow seasonal patterns tied to New Year resolutions and summer preparation windows, with catalog refresh rates varying dramatically by exercise modality.
- Yoga:Content libraries emphasize low-production-cost studio sessions with minimal equipment requirements. Demand concentrates among female subscribers aged 25-44 in the United States, where retention curves outperform high-intensity formats by substantial margins due to stress-reduction positioning and lower physical barriers to entry.
- HIIT:High-intensity interval programming demands dynamic camera work and music licensing synchronization. European markets under GDPR Article 25 scrutiny favor on-device biometric processing for heart rate zone coaching, reducing cloud transmission compliance exposure while maintaining real-time intensity guidance.
- Strength Training:Progressive overload algorithms require equipment integration with smart dumbbells and resistance bands.
- Cardio:Treadmill and bike connectivity protocols dominate this segment's technical requirements.
HIIT sits at the top of the volume ranking, with Yoga climbing the fastest.
Subscription Model:
Cost tier differentiation separates price-sensitive experimenters from committed long-term subscribers, with billing frequency directly correlating to churn probability.
- Monthly:Flexible commitment structures attract trial users with minimal upfront friction. United States consumers show highest cancellation rates within 60 days, though this model dominates acquisition channels for platforms competing on content breadth rather than hardware integration.
- Annual:Pre-payment mechanisms concentrate cash flow in Q1 while reducing churn volatility through sunk-cost psychology. Employer-sponsored wellness programs in the United States negotiate enterprise annual licenses that bypass app store commission structures entirely.
- Freemium:Limited content tiers convert users through progressive feature unlocking.
- One-Time Purchase:Permanent license models appeal to privacy-conscious users avoiding recurring data relationships.
Annual plans dominate revenue concentration, with Freemium expanding most quickly as a user acquisition engine.
Target User:
Skill-based segmentation determines interface complexity, coaching algorithm sophistication, and community feature deployment.
- Beginner:Onboarding flows emphasize habit formation through streak mechanics and simplified equipment requirements. California's CCPA-mandated consent workflows create UX friction that depresses completion rates for this privacy-unaware demographic.
- Intermediate:Progression algorithms introduce periodization and cross-training variety. India's PLI scheme for affordable wearables expands addressable market for users seeking biometric feedback without premium hardware investment.
- Advanced:Performance analytics and competitive leaderboards dominate feature priorities.
- Casual User:Micro-workout formats under 15 minutes capture sporadic engagement patterns.
Intermediate users generate the highest per-capita revenue, with Beginner acquisition costs climbing fastest as platforms compete for conversion.
User Engagement:
Engagement mechanism selection shapes technical architecture requirements and data handling compliance burdens across jurisdictions.
- Gamification:Badge systems and achievement hierarchies drive retention through variable reward scheduling. FDA digital health classification uncertainty constrains apps making specific cardiovascular improvement claims tied to gamified progression metrics.
- Community Features:Social accountability mechanisms include leaderboard rankings and workout sharing. EU AI Act risk classification for health-related recommendation systems elevates documentation requirements for algorithmic social matching in Germany and France.
- Personal Trainer Access:Live video coaching requires low-latency infrastructure and talent supply chains.
- Progress Tracking:Biometric data visualization integrates with Apple HealthKit and Google Fit APIs.
Progress Tracking commands the deepest user investment, with Personal Trainer Access gaining share fastest as premium tier differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The home fitness app industry traces its commercial origins to Silicon Valley garage startups that leveraged smartphone accelerometers for basic activity tracking, with early scaling concentrated in California's venture capital corridor before expanding to hardware-integrated models in Asia-Pacific manufacturing hubs.
United States
Employer-sponsored wellness budgets and Medicare Advantage fitness benefit pilots drive subscription concentration. FDA digital health classification scrutiny constrains therapeutic claim positioning for coaching algorithms. San Francisco and Austin clusters host venture-backed platforms specializing in AI form correction and real-time biometric feedback.
Germany
German consumers demonstrate strong preference for annual subscription pre-payments and data-minimalist app architectures. GDPR Article 25 privacy-by-design mandates accelerate on-device processing adoption among Berlin and Munich developers. Bavaria's industrial sensor manufacturers supply Bluetooth 5.3 LE Audio chipsets for synchronized multi-device workout experiences.
United Kingdom
Price-sensitive users accept upfront annual commitments in exchange for substantial discounts, concentrating platform cash flow in Q1. The Information Commissioner's Office enforces granular consent workflows for heart rate and location tracking. London's fintech infrastructure enables employer wellness program billing integrations that bypass app store commission structures.
India
Production-linked incentives for domestic electronics manufacturing reduce wearable hardware costs for price-sensitive consumers. The central bank's digital payment infrastructure supports micro-transaction models for freemium conversion. Karnataka and Maharashtra host development centers building computer vision algorithms for AI form correction on mid-tier smartphones.
Japan
Aging demographics sustain demand for low-impact yoga and meditation content with superior retention curves. METI guidelines on health data interoperability shape API standardization for biometric platform integration. Tokyo's consumer electronics conglomerates leverage OS-level fitness APIs to pre-install workout platforms on domestic smartphone distributions.
Home Fitness App Market Competitive Environment
The competitive structure tilts toward platform-agnostic content providers over hardware-captive ecosystems. Consolidation pressure concentrates around three strategic archetypes: athletic apparel brands extending into digital workout libraries, technology conglomerates integrating fitness APIs at operating system level, and connected-fitness hardware vendors defending proprietary subscription bundles. Dominant competitive moves include strategic partnerships with employer wellness administrators and technology licensing arrangements that bypass direct-to-consumer acquisition costs.
Among athletic heritage content platforms, Nike, Inc. and Adidas AG exemplify brand-leverage strategies that sustain engagement across independent device platforms. Google LLC occupies the infrastructure-tier position through Android OS fitness API dominance. Peloton Interactive, Inc. represents the hardware-software bundle archetype competing on instructor-led production quality rather than cross-platform flexibility.
| Leading Market Players |
|---|
| MyFitnessPal, Inc. |
| Nike, Inc. |
| Google LLC |
| Under Armour, Inc. |
| Adidas AG |
| Peloton Interactive, Inc. |
| Azumio, Inc. |
| Strava, Inc. |
| Samsung Electronics Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
EU AI Act risk classification for health-related recommendation systems gates qualified supply and premium-tier pricing access. Developers maintaining technical files demonstrating bias mitigation and human oversight protocols command pricing premiums, while platforms lacking compliance infrastructure face margin compression from legal review expenses and delayed product roadmaps.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the subscriber base. Annual pre-payments concentrate cash flow in Q1 while monthly flexibility attracts trial users with elevated churn exposure. Price differentiation rests on instructor production quality and hardware integration depth. Pricing pressure stems from platform commission structures extracting fifteen to thirty percent of subscription revenue through app store billing systems. Employer-sponsored wellness programs demonstrate lowest price sensitivity through enterprise license negotiations, while individual freemium converters exhibit highest sensitivity to upfront commitment thresholds.
Supply Chain Analysis
India's PLI scheme for domestic electronics manufacturing reshapes sourcing patterns for wearable hardware components. Component supply concentrates in China, South Korea, and Taiwan for Bluetooth chipsets, motion sensors, and display panels. Raw material dependencies include lithium-ion cells, semiconductor wafers, and rare earth magnets for haptic feedback systems. Single-source vulnerability runs through Taiwan's foundry concentration for tensor processing units enabling on-device machine learning inference. Distribution runs through direct-to-consumer app store channels and enterprise wellness program procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play. GDPR compliance costs in Europe push developers toward privacy-by-design architectures, while India's PLI scheme enables cost-competitive hardware sourcing for South Asian market entry.
For Market Incumbents: Anticipate FDA digital health classification uncertainty by pre-emptively segregating therapeutic claims from general wellness positioning. Invest in on-device biometric processing to reduce cloud dependency and long-term GDPR exposure. Build backward integration into instructor talent retention contracts to defend against content production cost inflation from studio facility escalation. For New Entrants and Emerging Players: The gap between premium hardware-software bundles and economy-tier freemium offerings creates entry space. Target intermediate skill users in price-sensitive markets seeking biometric feedback without proprietary device lock-in. Deploy computer vision algorithms on mid-tier smartphones through India's PLI-enabled hardware ecosystem as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for platform-agnostic content providers because subscription unbundling fragments hardware-captive ecosystems and erodes proprietary device margins. Acquire targets with established employer wellness channel relationships and on-device processing capabilities. Watch Medicare Advantage fitness benefit pilot expansion as the signal indicating inflection toward institutional reimbursement models.| Strategic Initiative | Industry Significance |
|---|---|
| Privacy-by-Design Architecture Investment | GDPR Article 25 compliance reduces long-term legal overhead while accelerating European market access. |
| Employer Wellness Channel Partnership | Enterprise license negotiations bypass app store commission structures entirely. |
| On-Device Machine Learning Deployment | Tensor processing unit integration eliminates cloud latency for real-time form correction. |
| Annual Subscription Pre-Payment Migration | Upfront commitment mechanisms reduce churn volatility through sunk-cost psychology. |
| Medicare Advantage Integration Pilot | Health plan supplemental benefits channel bypasses direct-to-consumer acquisition costs. |
Study Parameters
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each. The analysis combines structured interviews with fitness platform CTOs, employer benefits administrators, wearable hardware procurement leads, and content production studio executives with secondary validation from SEC filings, app store revenue disclosures, and hyperscaler fitness API documentation. Bottom-up subscriber modeling triangulates against top-down employer wellness budget allocations.
Granularity-level modeling disaggregates the analysis window by product type, subscription model, target user skill tier, and engagement mechanism. The analytical framework projects value expansion across these dimensions while deriving growth rates from historical conversion velocity and retention curve benchmarks. Industry-specific inputs include Bluetooth protocol adoption cycles, biometric sensor cost curves, and regulatory classification threshold monitoring.
The model assumes a particular technology adoption path; alternative pathways for on-device machine learning inference would alter the outlook if cloud processing cost compression outpaces mobile chipset tensor unit deployment. Forecasts reflect assumptions regarding employer wellness mandate expansion and FDA digital health classification stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Orchestration Tools Market
Software & Services
Electronic Batch Records Market
Software & Services
Global Integration Software Market
Software & Services
Embroidery Design Software Market
Software & Services
Lead Scoring Software Market
Software & Services
HVAC Solution Software Market
Software & Services
Global Bug Tracking Software Market
Software & Services
US Content Services Platform Market
Software & Services
Global Recipe Apps Market
Software & Services
Legal Practice Management Software Market
Software & Services
Retail Space Planning Software Market
Software & Services
Global Address Verification Software Market
Software & Services
Global Roofing Software Market
Software & Services
Saas-Based Expense Management Market
Software & Services
Driver Updater Software Market
Software & Services
Design Engineering Software Market