
 Chile Data Center Server Market | 2026-2036
Chile Data Center Server Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Data Center Server Market Insights
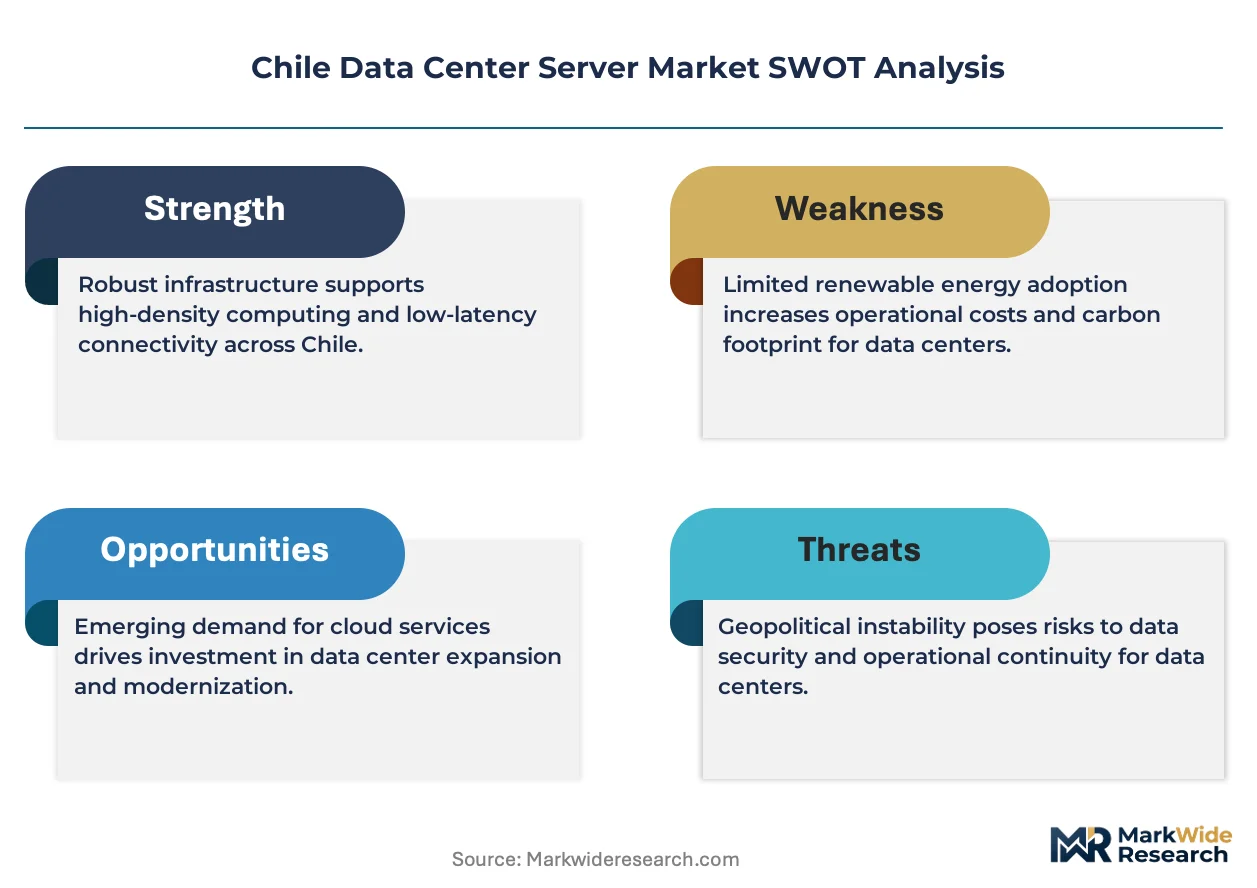
Capital-intensity divergence between custom-built hyperscale racks and standardized enterprise units is bifurcating competitive dynamics in Chile's server landscape. Dell Technologies leverages its direct-to-customer supply chain to control deployment timelines for financial services clients. Hewlett Packard Enterprise anchors its position through integrated liquid-cooling architectures suited to Santiago's rising ambient temperatures. Super Micro Computer Inc. specializes in high-density configurations that reduce rack footprints for colocation operators.
Data center servers are enterprise-grade computing systems engineered with multi-socket processors, redundant power supplies, and hot-swappable components designed for continuous operation in controlled environments. These systems process transactional workloads, virtualization layers, and analytics pipelines for organizations requiring localized data sovereignty. Rack servers occupy the dominant volume position across Chilean installations due to their scalability in standard 42U cabinets. Edge computing configurations represent the fastest-expanding technology segment as mining and logistics operators deploy latency-sensitive nodes in Antofagasta and Valparaíso. Blade server demand concentrates among telecommunications carriers pursuing chassis-level density for 5G core infrastructure.
Chile's Subsecretaría de Telecomunicaciones governs spectrum allocation and infrastructure certification, while the country's data protection authority enforces cross-border transfer restrictions that mandate local server residency. The central bank's cybersecurity frameworks for payment systems directly shape hardware procurement specifications among retail and financial end users. Stakeholders must monitor submarine cable landing investments and renewable energy grid interconnections to assess power cost trajectories for new facility development.
Market Dynamics
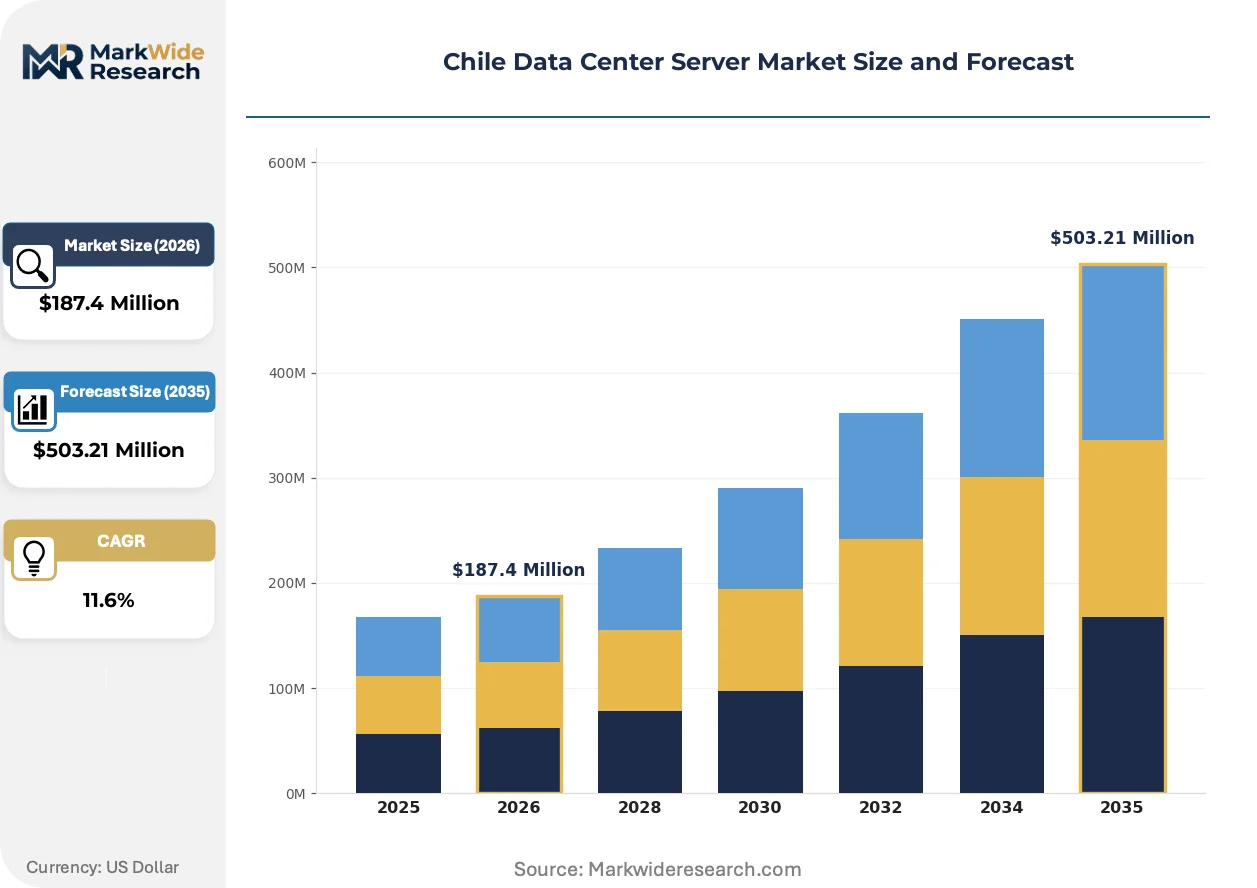
Submarine cable landings and renewable energy grid interconnections are restructuring server deployment economics across Chile's metropolitan and regional zones. Power cost trajectories and data sovereignty mandates now dominate facility location decisions.
Growth Catalysts
- Data Protection Law:Chile's cross-border transfer restrictions mandate local server residency, compelling financial services and retail operators to expand domestic rack capacity.
- Submarine Cable Investments:New fiber landing stations in Valparaíso and Antofagasta reduce latency for cloud service providers deploying Santiago-edge nodes.
- Mining Sector Digitization:Copper and lithium operators in the Bío Bío Region deploy edge computing configurations for autonomous haulage and predictive maintenance workloads.
Market Restraints
- Power Cost Volatility:Santiago's grid interconnection constraints create pricing uncertainty for hyperscale facilities exceeding 10MW demand thresholds.
- Import Equipment Lead Times:Server hardware sourced from Asian manufacturing clusters faces extended customs clearance through Valparaíso port infrastructure.
- Cooling Efficiency Ceiling:Rising ambient temperatures in the metropolitan zone limit air-cooled rack densities without liquid-cooling retrofits.
Strategic Opportunities
- Antofagasta Edge Corridor:Mining logistics operators represent underpenetrated demand for latency-sensitive computing nodes outside Santiago's saturated market.
- Renewable Energy Co-location:Solar and wind grid integration in the Atacama Desert enables power purchase agreements that undercut metropolitan electricity rates.
- 5G Core Infrastructure:Telecommunications carriers require chassis-level blade server density for network function virtualization deployments.
Industry Challenges
- Liquid-Cooling Integration:Retrofitting legacy air-cooled facilities with direct-to-chip cooling architectures demands specialized mechanical contracting capacity scarce in Chile.
- Certification Timeline Compression:Subsecretaría de Telecomunicaciones infrastructure certification processes create deployment delays for financial services clients with fixed go-live mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Data Center Server Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rack Server, Blade Server, Tower Server, Micro Server Technology: Virtualization, Cloud Computing, Edge Computing, Big Data End User: Financial Services, Telecommunications, Healthcare, Retail Installation: On-Premises, Hosted, Managed Services, Colocation |
| Companies Covered | Dell Technologies, Hewlett Packard Enterprise, International Business Machines Corporation, Cisco Systems Inc., Lenovo Group Limited, Super Micro Computer Inc., Huawei Technologies Co. Ltd., Quanta Computer Inc., Inspur Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Data Center Server Market Trends and Innovations
Server architecture specialization is fragmenting procurement patterns as buyers prioritize workload-optimized configurations over general-purpose platforms. Three developments are reshaping competitive positioning.
Liquid-cooled rack architectures address thermal constraints in Santiago's warming climate. Hyperscale operators and colocation providers are adopting these systems fastest. The technology is bifurcating the vendor landscape between integrated cooling specialists and air-cooled commodity suppliers.
Chile's data protection authority enforces residency requirements that shape hardware procurement specifications. Financial institutions must document physical server location for payment system audits. Retail banks now specify domestic rack deployment in vendor contracts.
Leasing structures displace capital purchases among mid-market enterprises. Colocation operators absorb hardware depreciation risk while clients pay monthly capacity fees. This pattern concentrates in Santiago's metropolitan zone where facility competition is densest.
Chile Data Center Server Market Segmentation
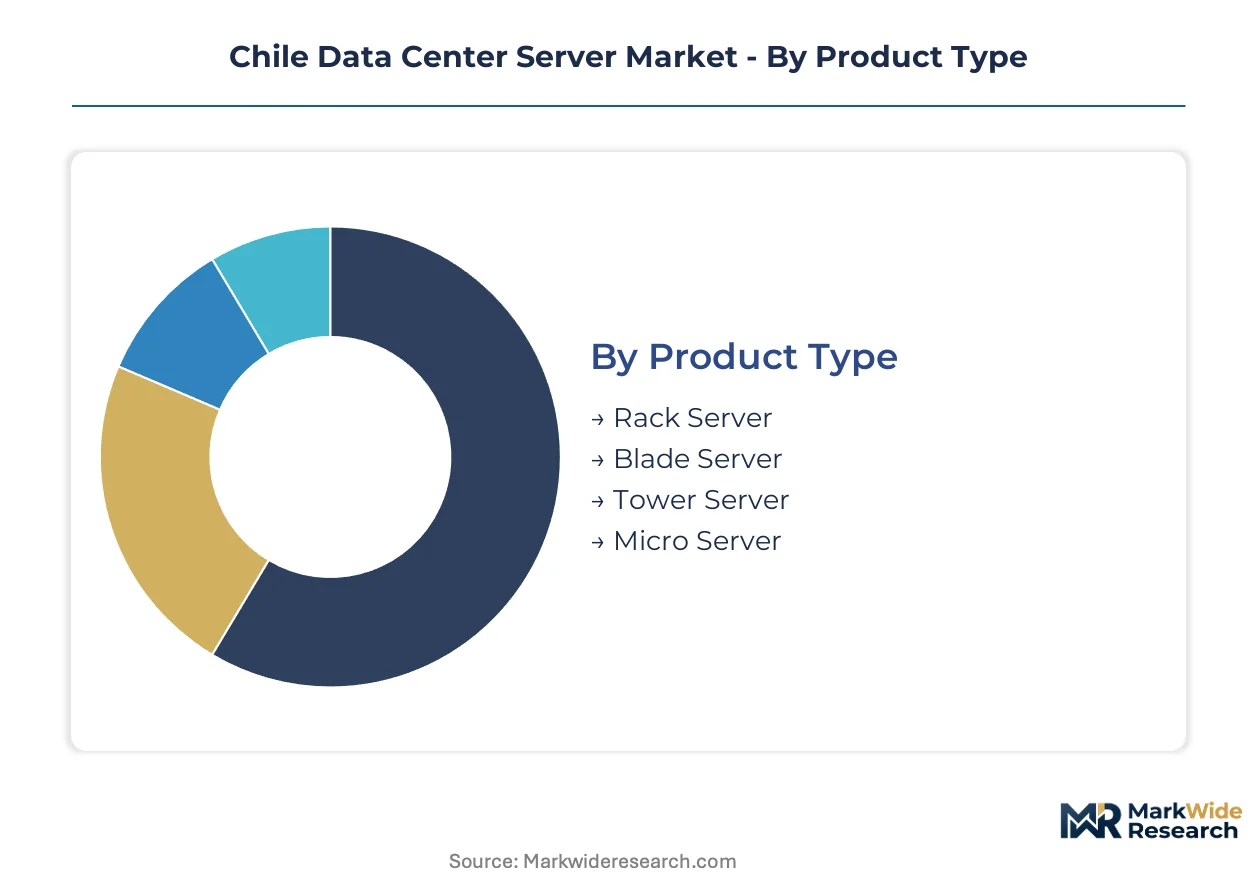
Server procurement patterns in Chile fragment sharply across workload requirements and facility ownership models. Channel economics differ materially between hyperscale cloud deployments and enterprise captive installations.
Product Type:
Channel flow varies substantially: rack and blade units move primarily through direct OEM relationships with large enterprises and colocation operators, while tower and micro servers distribute through systems integrators serving mid-market clients.
- Rack Server:Multi-socket systems in standard 42U enclosures form the backbone of Chilean data center infrastructure. Financial services operators in Santiago's metropolitan zone specify these for core banking virtualization stacks, driven by Subsecretaría de Telecomunicaciones certification requirements for payment system hardware.
- Blade Server:Chassis-integrated high-density configurations enable telecommunications carriers to consolidate 5G core network functions. Entel and Movistar deployments concentrate these in Santiago edge nodes where submarine cable landings reduce latency to sub-10ms thresholds.
- Tower Server:Standalone pedestal units serve provincial healthcare networks and municipal government offices requiring sub-10kW compute footprints without raised-floor facilities.
- Micro Server:Ultra-compact single-socket systems address edge computing nodes in Antofagasta mining corridors where dust filtration and thermal constraints limit conventional rack deployment.
Rack servers dominate installed base. Blade configurations are where expansion concentrates for telecommunications infrastructure builds.
Technology:
Application intensity determines margin structure: virtualization and cloud computing platforms generate recurring software revenue streams, while edge and big data workloads command premium hardware pricing for specialized configurations.
- Virtualization:Hypervisor-optimized server pools abstract compute resources for multi-tenant colocation environments. Bío Bío Region data center operators deploy these for retail and manufacturing clients requiring rapid workload provisioning without capital hardware ownership.
- Cloud Computing:Scalable infrastructure-as-a-service platforms rely on commodity server fleets with automated orchestration layers. AWS, Microsoft Azure, and Google Cloud expansion in Santiago drives demand for standardized rack units with 48-hour replacement service level agreements.
- Edge Computing:Distributed low-latency nodes process autonomous haulage telemetry and predictive maintenance algorithms at copper and lithium extraction sites.
- Big Data:High-memory configurations with GPU acceleration support analytics pipelines for retail banks segmenting customer transaction patterns.
Cloud computing anchors current revenue. Edge computing is climbing the fastest as mining digitization accelerates outside metropolitan zones.
End User:
Procurement sophistication tiers separate regulated financial institutions with dedicated sourcing teams from healthcare and retail operators relying on managed service intermediaries.
- Financial Services:Banks and payment processors mandate domestic server residency under central bank cybersecurity frameworks. Banco de Chile and Banco Santander Chile specify liquid-cooled rack configurations for trading floor co-location to meet sub-microsecond latency requirements.
- Telecommunications:Carriers chassis-integrate blade servers for network function virtualization, with deployment concentrated in Santiago and Valparaíso cable landing zones.
- Healthcare:Hospital networks and insurance providers deploy on-premises towers for patient record systems subject to data protection authority cross-border transfer restrictions.
- Retail:Department store chains and e-commerce operators favor hosted and managed service arrangements to avoid capital depreciation on seasonal demand fluctuations.
Financial services commands premium pricing. Retail is gaining share fastest as omnichannel transaction volumes expand domestic rack requirements.
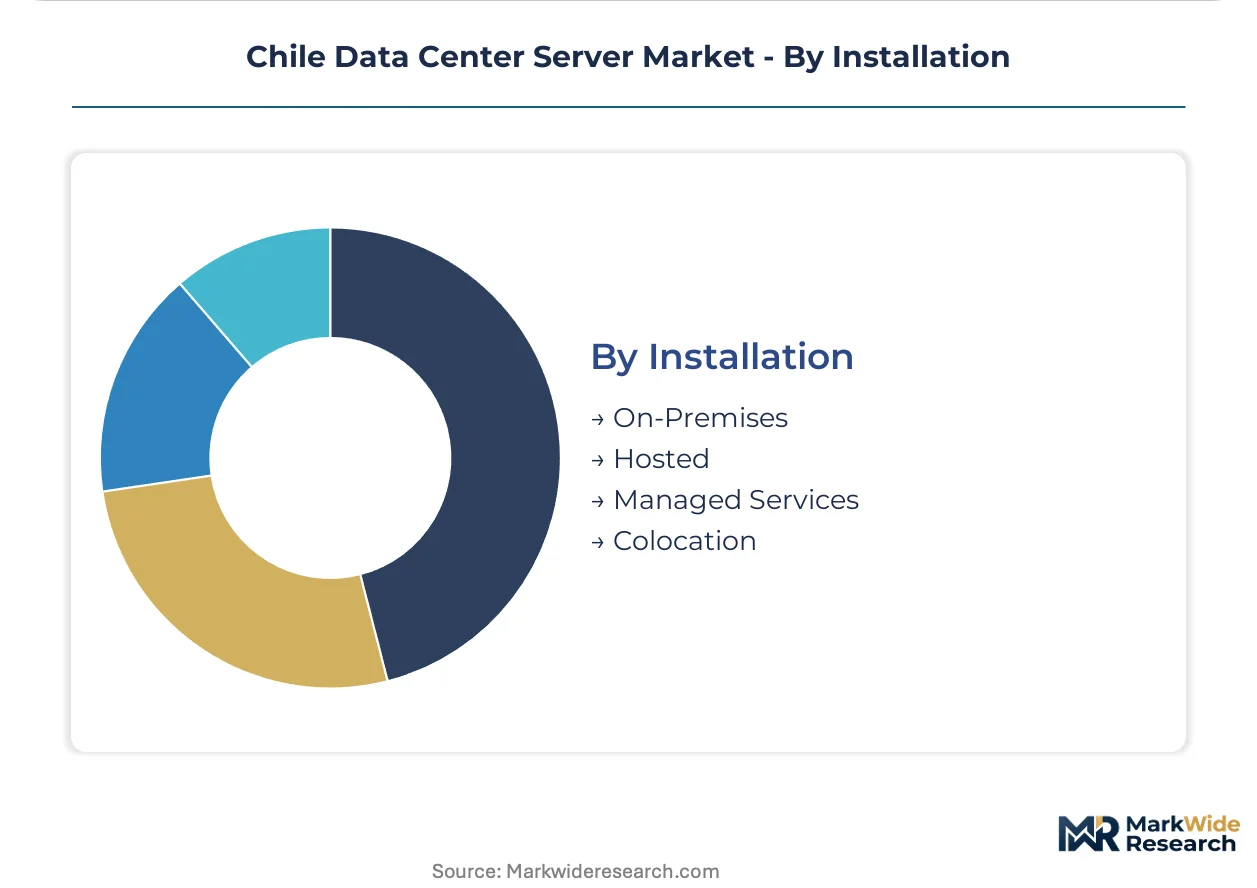
Installation:
Ownership economics bifurcate between capital-intensive on-premises deployments and operational-expense models where facility operators absorb hardware lifecycle risk.
- On-Premises:Enterprise-owned facilities in Santiago's Quilicura and Cerrillos industrial districts house custom-built server rooms with redundant substations. Mining conglomerates Antofagasta Minerals and Codelco maintain these for proprietary geological modeling workloads.
- Hosted:Single-tenant data halls within multi-client facilities provide dedicated power and cooling without real estate ownership. Regional banks in Concepción deploy these to avoid metropolitan land costs.
- Managed Services:Outsourced infrastructure operations include hardware procurement, monitoring, and maintenance for mid-market enterprises lacking specialized IT staffing.
- Colocation:Multi-tenant cabinet and cage rentals concentrate in Santiago's Pudahuel and Huechuraba districts where facility competition drives power pricing below provincial alternatives.
On-premises retains legacy installed base. Colocation is where expansion concentrates as cloud providers lease wholesale space for edge node deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Chile's server deployment zones. Santiago's metropolitan buyers prioritize latency and certification speed over unit cost. Provincial mining and logistics operators in the Bío Bío and Antofagasta regions exhibit acute price sensitivity for edge node configurations.
Santiago Metropolitan Zone
Financial services and cloud hyperscalers dominate rack procurement in Quilicura, Cerrillos, and Pudahuel districts. The Subsecretaría de Telecomunicaciones enforces infrastructure certification timelines that compress deployment windows. Liquid-cooled facilities concentrate in Huechuraba where power density requirements exceed 15kW per rack.
Bío Bío Region
Copper and lithium extraction operators deploy micro servers for autonomous haulage telemetry at Cerro Colorado and Los Bronces sites. The central bank's cybersecurity frameworks extend to mining payment systems requiring localized transaction processing. Concepción hosts emerging colocation capacity serving regional manufacturing clients.
Antofagasta Region
Port logistics and desert mining operations drive edge computing demand with sub-5ms latency requirements. Submarine cable landing investments at Antofagasta port reduce international backhaul costs for cloud edge nodes. Zaldívar and Spence mine sites prototype predictive maintenance server clusters.
Valparaíso Region
Telecommunications carriers chassis-integrate blade servers for 5G core infrastructure near Quintero cable landing stations. The data protection authority's cross-border transfer restrictions mandate domestic residency for customer data pipelines. Viña del Mar hosts carrier-neutral facilities serving Santiago overflow demand.
Chile Data Center Server Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Chile's server procurement tiers. The market structures around three distinct supplier categories: integrated systems vendors with direct-to-customer supply chains, modular architecture specialists targeting high-density configurations, and volume-driven fabricators serving standardized cloud deployments. Competitive moves center on liquid-cooling integration partnerships and renewable energy co-location agreements that reduce total cost of ownership for hyperscale clients.
Among US-based integrated systems vendors, Dell Technologies and Hewlett Packard Enterprise occupy positions serving financial services and telecommunications carriers with certified deployment timelines. Super Micro Computer Inc. represents the modular architecture archetype, specializing in configurations that reduce rack footprints for colocation operators facing Santiago's space constraints. These three exemplify the technology-cost bifurcation: integrated vendors command premium positioning through certification relationships, while the modular specialist competes on density-optimized hardware economics.
| Leading Market Players |
|---|
| Dell Technologies |
| Hewlett Packard Enterprise |
| International Business Machines Corporation |
| Cisco Systems Inc. |
| Lenovo Group Limited |
| Super Micro Computer Inc. |
| Huawei Technologies Co. Ltd. |
| Quanta Computer Inc. |
| Inspur Group |
| Others |
Pricing and Supply Chain Analysis
Hyperscale rack utilization rates above 85 percent in Santiago's metropolitan facilities create steep economies that compress unit costs for cloud providers while erecting price floors for mid-market colocation tenants lacking comparable volume scale. This concentration dynamic bifurcates procurement power between wholesale-leasing hyperscalers and captive-installation enterprises absorbing full hardware depreciation.
Pricing Analysis
After-sales service contracts and extended warranty tiers generate lifetime value multiples exceeding three times initial hardware revenue for integrated systems vendors. Chile's server market operates on a hybrid pricing structure combining capital equipment purchase with managed service overlays. Price differentiation hinges on Subsecretaría de Telecomunicaciones certification tier and liquid-cooling integration complexity. Pricing pressure stems from renewable energy co-location agreements in the Atacama Desert undercutting metropolitan power rates. Cloud hyperscalers exhibit lowest price sensitivity due to volume scale, while provincial mining operators deploying edge nodes demonstrate acute cost consciousness.
Supply Chain Analysis
Strategic stockpiling of processor inventory dominates procurement behavior among Chilean system integrators buffering against Asian manufacturing lead time volatility. Server hardware supply concentrates in Taiwan, China, and Malaysia for motherboard and chassis fabrication. Critical component dependencies include Intel and AMD processors, Samsung and SK Hynix memory modules, and Delta Electronics power supplies. Single-source vulnerability runs through advanced semiconductor lithography equipment subject to export control restrictions. Distribution feeds from Valparaíso port customs clearance through direct OEM relationships with large enterprises and systems integrator channels serving mid-market clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in edge computing deployments outside Santiago's saturated core, as mining digitization and 5G infrastructure builds create specialized workload requirements underserved by standardized cloud configurations.
For Market Incumbents: Shield installed base relationships in financial services by deepening liquid-cooling certification partnerships with Subsecretaría de Telecomunicaciones before emerging modular architecture specialists capture retrofit demand. Consolidate channel control through exclusive service contracts with Bío Bío Region colocation operators expanding capacity for manufacturing clients. For New Entrants and Emerging Players: Anchor in Antofagasta Region edge corridors where latency requirements for autonomous haulage telemetry outstrip incumbent response capabilities. Target underpenetrated mining logistics operators with dust-hardened micro server configurations. Pursue direct-to-mine-site deployment models bypassing Santiago distribution chokepoints. For Investors and Strategic Acquirers: Regional systems integrators with established Subsecretaría de Telecomunicaciones certification relationships and renewable energy co-location contracts represent the most defensible acquisition archetype. Long-term viability hinges on positioning for data sovereignty enforcement expansion across Latin American markets. Watch submarine cable landing completion timelines as inflection indicators for edge node deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid-Cooling Retrofit Partnership | Addresses Santiago's thermal constraints while capturing hyperscale rack density premiums. |
| Renewable Energy Co-location Agreement | Enables Atacama Desert power purchase agreements undercutting metropolitan electricity rates. |
| Subsecretaría de Telecomunicaciones Certification Investment | Accelerates deployment timelines for financial services clients with fixed go-live mandates. |
| Edge Node Geographic Expansion | Captures mining digitization demand in Antofagasta and Bío Bío corridors outside saturated Santiago. |
| Managed Service Platform Integration | Shifts mid-market enterprises from capital purchase to operational-expense models. |
Research Methodology
Operator-level perspectives from data center facility managers, cloud infrastructure procurement officers, telecommunications network architects, and mining operations technology directors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation drawing from Subsecretaría de Telecomunicaciones infrastructure filings, central bank cybersecurity framework disclosures, submarine cable landing project databases, and renewable energy grid interconnection records. Bottom-up server deployment tallies triangulated against top-down facility capacity estimates across Santiago, Bío Bío, Antofagasta, and Valparaíso zones.
Sensitivity analysis tested forecast robustness across power cost trajectory scenarios and import equipment lead time variations. The analytical framework segmented volume and value outputs by product type, technology deployment model, end-user industry, and installation ownership structure throughout the projection horizon. CAGRs derived from regression against macroeconomic drivers including mining sector capital expenditure cycles and cloud hyperscaler regional expansion commitments. Industry-specific inputs incorporated data protection authority enforcement intensity and central bank payment system hardware specifications.
Material uncertainties — regulatory certification timeline compression, renewable energy grid stability, and submarine cable construction delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding power purchase agreement availability and liquid-cooling mechanical contracting capacity. Revision becomes warranted when Subsecretaría de Telecomunicaciones certification backlog exceeds six months or Atacama solar grid interconnection crosses stability thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Brazil Data Center Market
Data Center Infrastructure
France Data Center Power Market
Data Center Infrastructure
South Korea Data Center Physical Security Market
Data Center Infrastructure
Mumbai Data Center Market
Data Center Infrastructure
Australia Data Center Power Market
Data Center Infrastructure
India Data Center Market
Data Center Infrastructure
Global Containerized Data Center Market
Data Center Infrastructure
Philippines Data Center Server Market
Data Center Infrastructure
Global Software-Defined Data Center Market
Data Center Infrastructure
Mexico Data Center Market
Data Center Infrastructure
Denmark Data Center Rack Market
Data Center Infrastructure
Data Center Life Cycle Services Market
Data Center Infrastructure
India Data Center Power Market
Data Center Infrastructure
United Arab Emirates Data Center Market
Data Center Infrastructure
Colocation Edge Data Center Market
Data Center Infrastructure
Middle East Data Center Market