
 Electromagnetic Simulation Software Market | 2026-2036
Electromagnetic Simulation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Electromagnetic Simulation Software Market Foresight
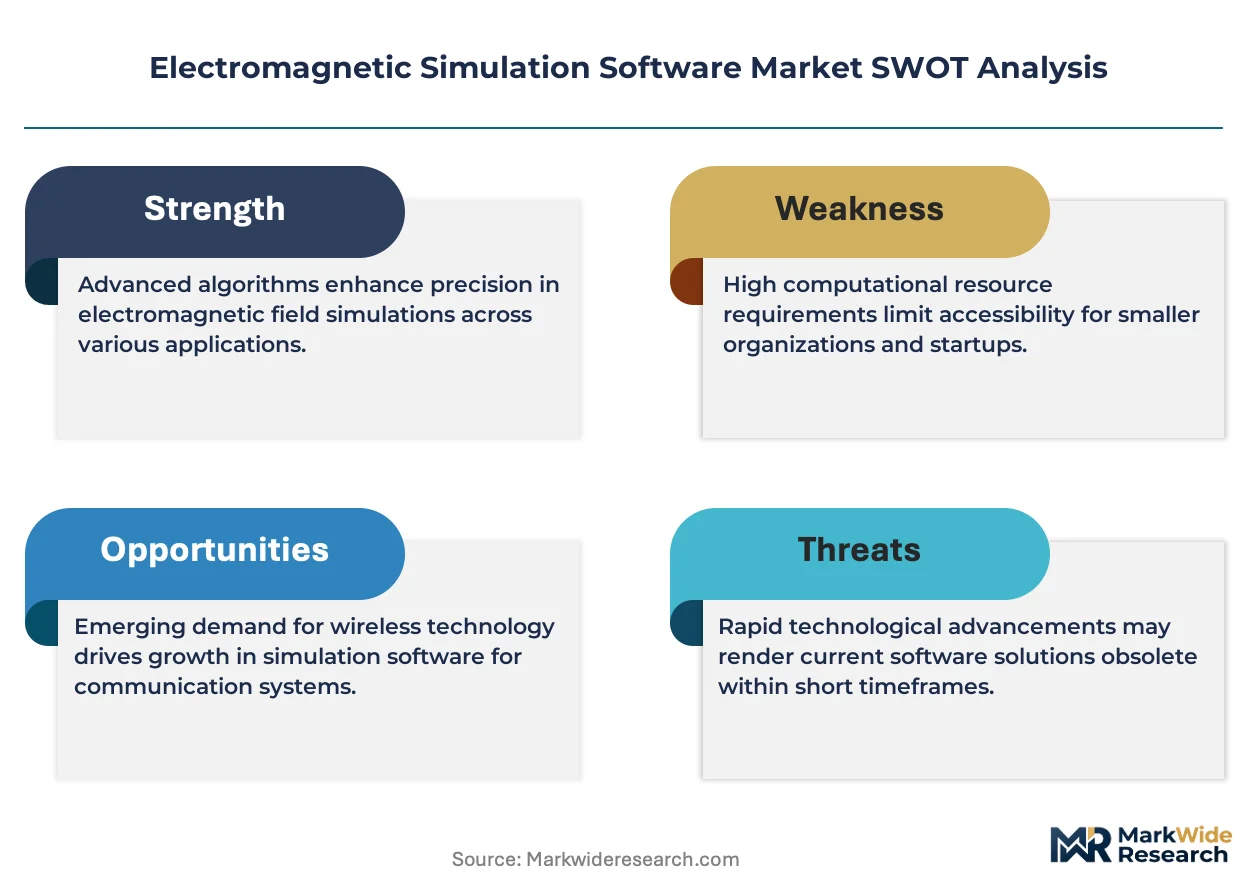
Gallium nitride is pivoting into RF power amplifier designs, displacing legacy LDMOS substrates across 5G base station and radar applications. ANSYS, Inc. leverages decades of solver architecture investment to dominate high-frequency electromagnetic analysis for defense contractors. Keysight Technologies sustains competitive positioning through tight hardware-software integration with its test instrumentation portfolio. COMSOL, Inc. differentiates via multi-physics coupling capabilities that link thermal, mechanical, and electromagnetic phenomena in single workflows.
Electromagnetic simulation software comprises computational tools that solve Maxwell's equations across finite element, finite difference time domain, or method-of-moments meshes to predict field distributions, scattering parameters, and radiation patterns in electronic systems. These platforms enable virtual prototyping of antennas, printed circuit boards, and integrated circuits before physical fabrication, compressing development cycles and reducing compliance failure risk. 3D field simulation commands the largest revenue share due to its indispensability in aerospace and automotive radar design, where geometric fidelity determines accuracy. Cloud-based deployment represents the fastest-expanding delivery mode as engineering teams distribute compute-intensive solves across elastic GPU clusters without capital-intensive on-premises infrastructure. Multi-physics simulation captures concentrated margin pools among semiconductor manufacturers thermally characterizing chip-package interactions.
The FCC enforces electromagnetic interference limits through Part 15 and Part 18 rules that mandate pre-compliance simulation for consumer electronics and industrial equipment entering the US market. The EU EMC Directive and CE marking requirements compel European automotive and telecommunications manufacturers to document electromagnetic compatibility through validated simulation prior to product registration. China's MIIT issues GB standards for wireless device certification that increasingly reference simulation-based equivalence testing. Stakeholders must monitor evolving dual-use export control classifications affecting electromagnetic solver algorithms while calibrating R&D roadmaps against shifting frequency allocations for 6G and automotive radar bands.
Market Dynamics
Gallium nitride substrate migration is compressing design validation cycles, forcing electromagnetic simulation vendors to recalibrate solver accuracy for wide-bandgap semiconductor geometries that operate at higher frequencies and power densities than legacy silicon architectures.
Growth Catalysts
- FCC Part 15 mandates:Pre-compliance simulation requirements for consumer electronics entering the US market are institutionalizing software procurement into product development workflows.
- Automotive radar proliferation:77-81 GHz frequency allocation expansions for collision avoidance systems are multiplying solver license demand among tier-one automotive suppliers.
- China telecommunications infrastructure:Domestic base station vendor consolidation is concentrating high-frequency RF design validation spend in Shenzhen and Beijing engineering centers.
Market Restraints
- GPU compute cost volatility:Cloud-based elastic cluster pricing fluctuates with semiconductor foundry capacity constraints, squeezing mid-size engineering team budgets.
- Solver algorithm export controls:Dual-use classification uncertainties around method-of-moments acceleration techniques are delaying international deployment timelines.
- Legacy LDMOS installed base:Existing radar and base station amplifier designs retain multi-year depreciation schedules that slow substrate transition investments.
Strategic Opportunities
- 6G terahertz research:Early-stage 140-300 GHz spectrum exploration is creating pre-competitive simulation tool development partnerships between national laboratories and commercial vendors.
- Multi-physics convergence:Thermal-electromagnetic coupling capabilities are opening semiconductor packaging workflows previously isolated in mechanical engineering departments.
- India PLI scheme:Production-linked incentives for telecom equipment manufacturing are seeding domestic RF design competency centers requiring localized solver deployment.
Industry Challenges
- Computational electromagnetics talent scarcity:Finite element mesh generation expertise and Maxwell's equation formulation skills command premium compensation that outpaces university program output.
- Legacy CAD integration friction:Existing mechanical design databases require geometry cleanup pipelines that consume 30-40% of project setup time before solver execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electromagnetic Simulation Software Market |
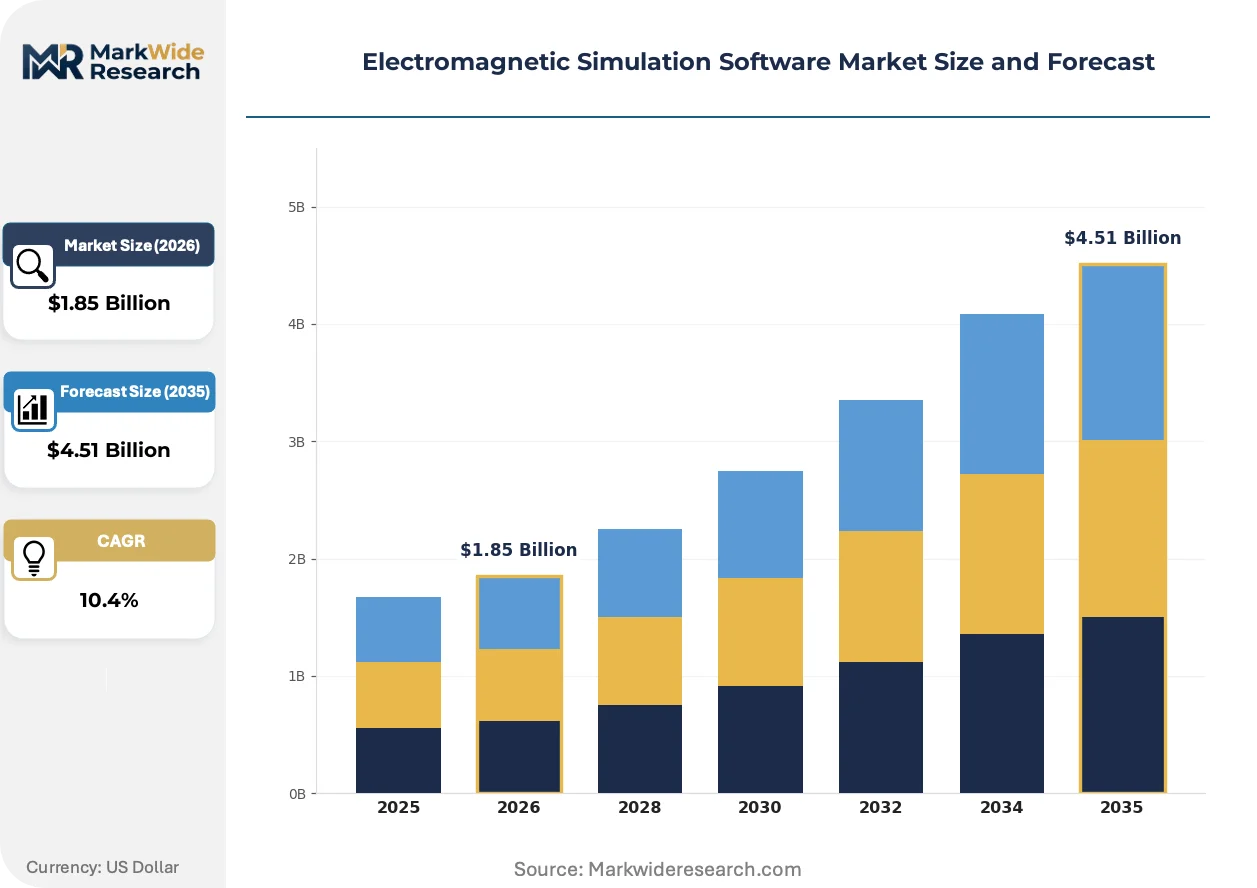
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.51 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Field Simulation, 2D Field Simulation, Circuit Simulation, Multi-Physics Simulation Application: Antenna Design, EM Compatibility, RF Component Design, Wireless Communication End User: Aerospace, Automotive, Consumer Electronics, Telecommunications Deployment: On-Premises, Cloud-Based, Hybrid, SaaS |
| Companies Covered | Altair Engineering Inc., Sonnet Software, Inc., ElectroMagneticWorks, Inc., Dassault Systèmes, COMSOL, Inc., Keysight Technologies, ANSYS, Inc., Mician GmbH, Remcom Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electromagnetic Simulation Software Market Shifts & Advancements
Artificial intelligence is penetrating electromagnetic workflow automation, compressing mesh generation and parameter sweep execution from hours to minutes while redistributing engineering labor toward design interpretation rather than computational setup.
Machine learning surrogate modeling is automating expensive full-wave electromagnetic simulations by training neural networks on sparse solver outputs, enabling automotive radar designers to explore antenna geometry spaces that were previously computationally prohibitive. Tier-one suppliers in Germany and Japan are deploying these reduced-order models for real-time optimization loops during concept phases. The technique is collapsing traditional sequential design-verification cycles into parallel exploration workflows.
The EU AI Act risk classification framework is imposing documentation requirements on simulation software used in safety-critical automotive and aerospace applications, compelling vendors to implement algorithmic transparency features and audit trail capabilities. Engineering teams must now demonstrate traceability from solver outputs to design decisions for regulatory submissions. This is most acute in German automotive supply chains where KBA type-approval processes are integrating simulation evidence standards.
Subscription-based licensing is displacing perpetual seat purchases among mid-size engineering consultancies, with usage-metered access to GPU clusters replacing capital-intensive on-premises workstation investments. Value-added resellers are pivoting toward implementation services and workflow customization rather than license margin capture. This shift is most visible in North American defense contracting where federal budget cycles previously dictated multi-year procurement patterns.
Electromagnetic Simulation Software Market Segmentation
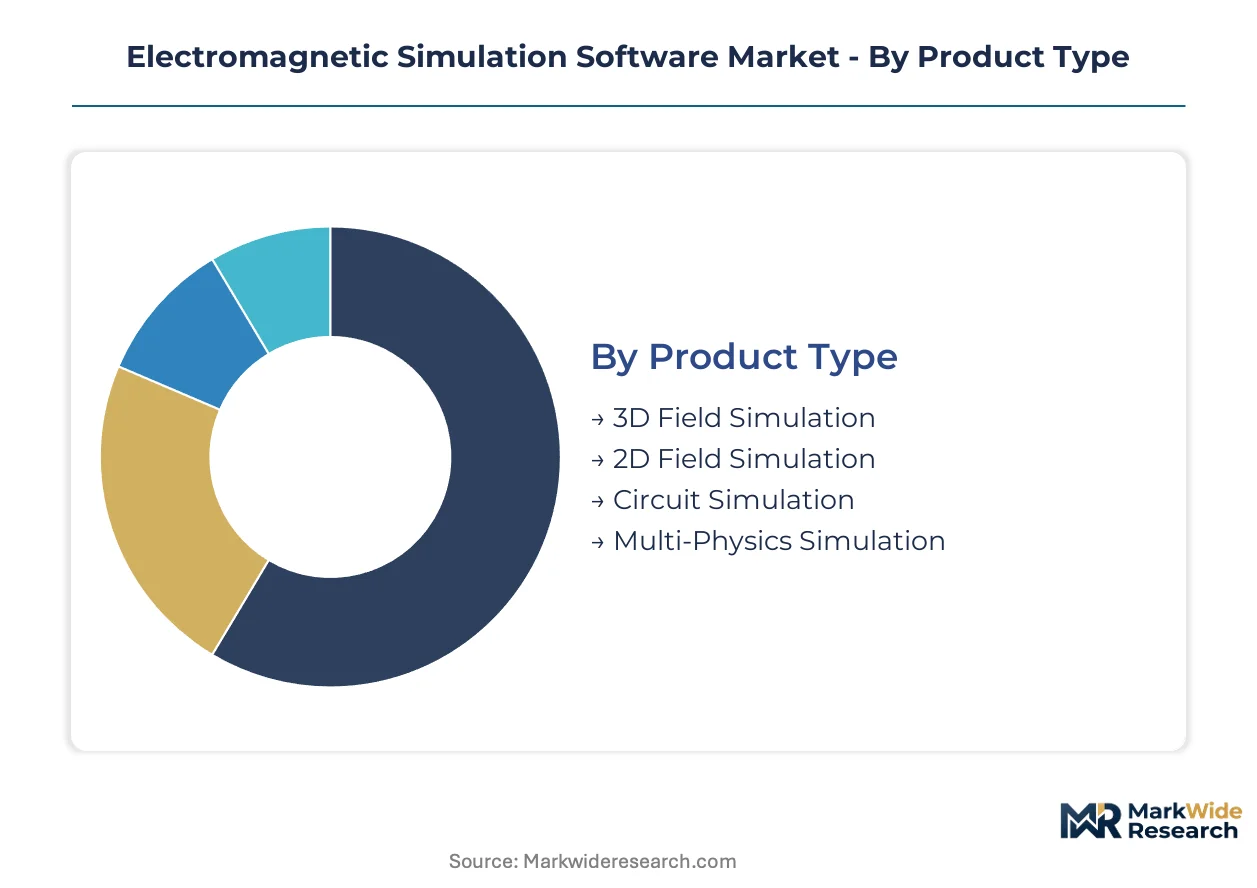
Electromagnetic simulation software segments reflect divergent computational requirements across defense, automotive, and telecommunications workflows. Solver architecture choices directly determine which engineering teams capture design validation contracts in high-frequency RF markets.
Product Type:
Supply concentration in aerospace radar and automotive antenna design has elevated 3D field simulation to dominant procurement priority among tier-one engineering departments.
- 3D Field Simulation:Full-wave Maxwell's equation solvers operating on volumetric meshes deliver geometric fidelity essential for radar cross-section analysis and millimeter-wave antenna characterization. Aerospace manufacturers in Germany and the United States anchor license demand for high-frequency scattering parameter extraction. FCC Part 15 pre-compliance mandates institutionalize procurement into product development workflows.
- Multi-Physics Simulation:Coupled thermal-electromagnetic-mechanical solvers enable semiconductor packaging workflows where chip-package interaction determines reliability. Foundries in Taiwan and South Korea drive adoption for power amplifier thermal characterization. Gallium nitride substrate migration forces solver recalibration for wide-bandgap geometries.
- 2D Field Simulation:Planar method-of-moments solvers address printed circuit board trace analysis and planar antenna arrays with reduced computational overhead.
- Circuit Simulation:SPICE-compatible electromagnetic co-simulation tools link field solvers to linear and nonlinear circuit analysis for RF front-end design.
Today's leader: 3D Field Simulation. Tomorrow's challenger: Multi-Physics Simulation.
Application:
Cost tier stratification separates enterprise-grade antenna design suites from mid-market EM compatibility tools purchased by consumer electronics consultancies.
- Antenna Design:Full-wave solvers optimize radiation patterns, impedance matching, and beam steering for 5G base stations and automotive radar modules. China's telecommunications infrastructure buildout concentrates high-frequency RF validation spend in Shenzhen engineering centers. Domestic base station vendor consolidation multiplies solver license requirements.
- RF Component Design:Power amplifier and filter simulation workflows address gallium nitride substrate geometries displacing legacy LDMOS architectures. Defense contractors in the United States prioritize wide-bandgap semiconductor modeling for next-generation radar systems. Dual-use export control uncertainties delay international deployment timelines.
- EM Compatibility:Pre-compliance simulation for FCC Part 15 and EU EMC Directive mandates reduces physical testing cycles for consumer electronics entering regulated markets.
- Wireless Communication:System-level link budget and channel modeling tools support base station coverage optimization and interference analysis.
Antenna Design commands current procurement volume. RF Component Design climbs the fastest as substrate transitions accelerate.
End User:
Customer type segmentation reveals aerospace and automotive as premium pricing anchors while telecommunications volumes scale through subscription licensing.
- Aerospace:Radar cross-section and electronic warfare simulation requirements demand classified-cleared solver deployments with specialized meshing for stealth geometries. German and United States manufacturers expand adoption of 3D field tools for defense procurement compliance.
- Automotive:77-81 GHz radar collision avoidance systems multiply solver demand among tier-one suppliers facing KBA type-approval integration of simulation evidence standards. EU AI Act documentation requirements impose algorithmic transparency mandates.
- Telecommunications:Base station RF design validation concentrates in China's domestic vendor engineering centers.
- Consumer Electronics:Pre-compliance EM simulation for FCC Part 15 and CE marking requirements institutionalizes software procurement into product development workflows.
Aerospace retains pricing power through security-cleared deployments. Automotive scales fastest via radar proliferation mandates.
Deployment:
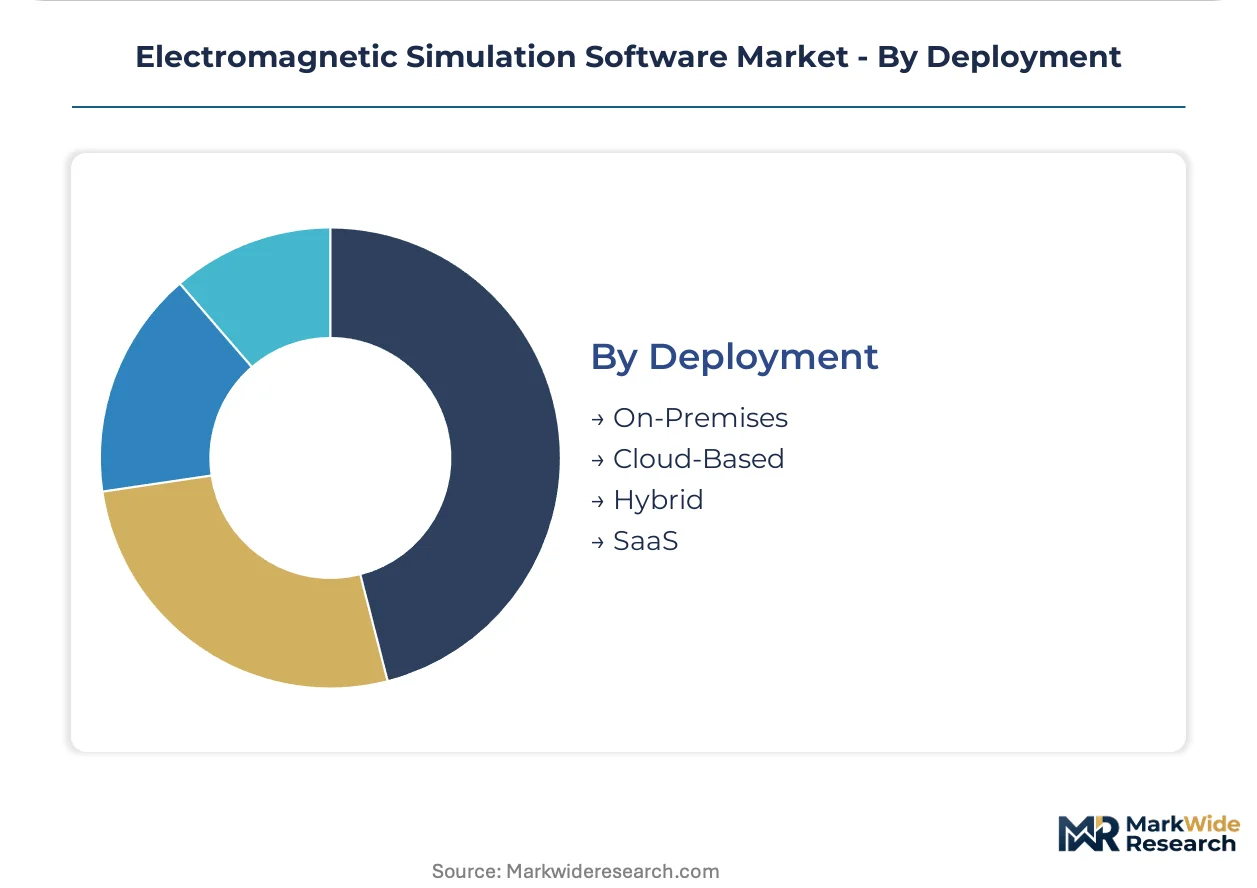
Volume distribution favors elastic compute models as engineering teams abandon capital-intensive workstation investments.
- Cloud-Based:GPU cluster elasticity enables distributed solve execution without on-premises infrastructure ownership. Mid-size consultancies in North America pivot from perpetual seats to usage-metered access. Semiconductor foundry capacity constraints introduce pricing volatility.
- SaaS:Browser-accessible solver interfaces with pre-configured workflows reduce setup expertise requirements for occasional users.
- On-Premises:Classified defense programs and data sovereignty requirements perpetuate air-gapped installations.
- Hybrid:Mixed deployments partition sensitive geometry handling on-premises while offloading parametric sweeps to cloud clusters.
Cloud-Based deployment expands most quickly. Hybrid architectures address lingering security constraints in defense workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's telecommunications engineering centers anchor solver license procurement for 5G base station validation, while German automotive suppliers and United States defense contractors concentrate high-frequency electromagnetic analysis demand across three continents.
United States
Defense contractors in Massachusetts and California drive classified-cleared solver deployments for radar cross-section analysis. FCC Part 15 mandates institutionalize pre-compliance simulation into consumer electronics workflows. Boston and Los Angeles engineering clusters expand 3D field tool adoption for electronic warfare procurement compliance.
Germany
Tier-one automotive suppliers in Stuttgart and Munich multiply solver demand for 77-81 GHz radar collision avoidance systems. KBA type-approval processes integrate simulation evidence standards under EU AI Act documentation requirements. Bavaria's engineering centers recalibrate thermal-electromagnetic coupling for gallium nitride power amplifier characterization.
China
Domestic base station vendor consolidation concentrates high-frequency RF design validation spend in Shenzhen and Beijing. MIIT GB standards for wireless device certification increasingly reference simulation-based equivalence testing. Yangtze River Delta engineering centers scale cloud-based GPU cluster access for millimeter-wave antenna development.
Japan
Automotive radar designers in Nagoya deploy machine learning surrogate models for real-time antenna geometry optimization. METI funding for 6G terahertz research seeds pre-competitive simulation tool partnerships between national laboratories and commercial vendors. Kansai region engineering teams compress design-verification cycles through parallel exploration workflows.
India
Production-linked incentives for telecom equipment manufacturing seed domestic RF design competency centers in Bengaluru and Hyderabad. TRAI spectrum allocation consultations anticipate 6G frequency bands requiring localized solver deployment. Karnataka's semiconductor packaging facilities adopt thermal-electromagnetic coupling for chip-package interaction analysis.
Electromagnetic Simulation Software Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors integrate hardware-software stacks and cloud compute elasticity. The vendor base organizes around three tiers: established multi-physics platforms with decades of solver architecture investment, test instrumentation manufacturers leveraging hardware-software synergies, and specialized high-frequency electromagnetic boutiques serving defense-aerospace niches. Portfolio diversification and technology licensing represent the two dominant competitive vectors, with incumbents extending thermal-mechanical coupling capabilities and regional players securing algorithm acceleration patents.
Within the full-wave solver tier, ANSYS, Inc. and Keysight Technologies occupy positions reflecting divergent strategic origins—one rooted in finite element method development, the other in measurement instrumentation integration. COMSOL, Inc. exemplifies the multi-physics convergence archetype, linking thermal, mechanical, and electromagnetic phenomena in unified workflows that semiconductor foundries adopt for power amplifier reliability characterization.
| Leading Market Players |
|---|
| Altair Engineering Inc. |
| Sonnet Software, Inc. |
| ElectroMagneticWorks, Inc. |
| Dassault Systèmes |
| COMSOL, Inc. |
| Keysight Technologies |
| ANSYS, Inc. |
| Mician GmbH |
| Remcom Inc. |
| Others |
Supply & Pricing Matrix
GPU cluster compute costs cascade through electromagnetic simulation software pricing tiers, with cloud-based elastic licensing absorbing foundry capacity volatility that on-premises perpetual seats once shielded. Aerospace defense contractors in the United States and Germany anchor premium pricing through classified-cleared deployments, while mid-size automotive consultancies in Stuttgart and Nagoya migrate toward usage-metered SaaS tiers that trade capital intensity for operational flexibility.
Pricing Analysis
Input-cost pass-through from semiconductor foundry pricing runs through cloud-based deployment tiers, compressing margins for vendors offering elastic GPU cluster access. Three-tier pricing structure across premium, standard, and economy levels separates aerospace security-cleared installations from automotive radar validation suites and consumer electronics pre-compliance tools. Pricing pressure stems from GPU compute cost volatility squeezing mid-size engineering team budgets. Tier-one automotive suppliers exhibit lowest price sensitivity due to KBA type-approval mandates, while consumer electronics consultancies demonstrate highest elasticity as FCC Part 15 compliance becomes commoditized.
Supply Chain Analysis
Certification and qualification gating through FCC Part 15, EU EMC Directive, and MIIT GB standards concentrates solver algorithm development in the United States, Germany, and China. Raw material dependencies span gallium nitride substrates from Taiwan and South Korea, high-performance GPU silicon from NVIDIA's foundry partners, and specialized meshing libraries from academic licensing agreements. Single-source vulnerability around method-of-moments acceleration patents creates dual-use export control exposure. Distribution runs through value-added resellers pivoting toward implementation services rather than license margin capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory demand through the EU AI Act's safety-critical documentation mandates, which institutionalize simulation evidence standards into German automotive type-approval processes.
For Market Incumbents: Extend thermal-electromagnetic coupling capabilities into semiconductor packaging workflows previously isolated in mechanical engineering departments. Acquire machine learning surrogate modeling competencies to defend against neural-network-based reduced-order model entrants. Prioritize cloud GPU cluster partnerships that buffer foundry capacity constraints threatening mid-tier pricing stability. For New Entrants and Emerging Players: Capture India PLI scheme telecom equipment manufacturing incentives by deploying localized solver infrastructure in Bengaluru and Hyderabad engineering centers. Target thermal characterization workflows at Karnataka semiconductor packaging facilities where multi-physics convergence creates white-space. Pursue academic licensing partnerships for method-of-moments acceleration algorithms to circumvent dual-use patent thickets. For Investors and Strategic Acquirers: Consolidation pressure builds where computational electromagnetics talent scarcity outpaces university program output. Long-term viability hinges on solver architecture moats capable of absorbing gallium nitride substrate transitions and 6G terahertz spectrum expansion. Target boutique high-frequency electromagnetic specialists with defense-aerospace clearance credentials. Watch for MIIT GB standard revisions referencing simulation-based equivalence testing as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Hardware-software stack unification with test instrumentation portfolios anchors Keysight Technologies' competitive positioning. |
| Strategic Partnership | Pre-competitive 6G terahertz tool development between METI-funded Japanese national laboratories and commercial vendors seeds next-generation solver architectures. |
| Acquisition of Specialist Firm | Machine learning surrogate modeling boutiques in Nagoya and Stuttgart enable real-time automotive radar optimization loops. |
| Geographic Expansion | Localized solver deployment in Shenzhen and Beijing engineering centers captures China domestic base station vendor consolidation. |
| Product Launch | Browser-accessible SaaS interfaces with pre-configured workflows reduce setup expertise barriers for occasional EM compatibility users. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with electromagnetic simulation software product managers, aerospace procurement officers at defense contractors, automotive tier-one supplier RF engineering directors, and cloud GPU cluster operations leads with secondary validation. SEC 10-K filings from ANSYS and Keysight Technologies, FCC Part 15 enforcement databases, EU EMC Directive implementation guidance, and MIIT GB standard publication records anchored bottom-up and top-down triangulation.
Segment-weighting across product type, application, end user, and deployment model dimensions structured the analytical framework over the projection horizon. Solver license revenue flows were modeled against gallium nitride substrate migration timelines and 77-81 GHz automotive radar allocation expansions. CAGRs derived from elasticity-adjusted adoption curves reflecting cloud pricing volatility and regulatory mandate compliance deadlines.
GPU foundry capacity constraints, dual-use export control reclassifications, and 6G spectrum allocation delays are the dominant revision risks. Forecasts reflect assumptions around semiconductor packaging thermal-electromagnetic coupling adoption rates and China telecommunications infrastructure buildout continuity. A model refresh is warranted upon material change in EU AI Act implementation timelines affecting safety-critical automotive simulation documentation requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Customer Experience Software Market
Software & Services
Performance Management Software Market
Software & Services
Gym Management Software Market
Software & Services
Quality Management Software Market
Software & Services
Know Your Customer Software Market
Software & Services
EDA Tools Market
Software & Services
Optical Coatings Design Software Market
Software & Services
Global Cloud Testing Market
Software & Services
Contract Abstraction Software Market
Software & Services
Collaborative Applications Market
Software & Services
Poland IT Software and Service Market
Software & Services
Sales Compensation Software Market
Software & Services
Retail Core Banking Solution Market
Software & Services
SMS Marketing Software Market
Software & Services
Global Budgeting Software Market
Software & Services
Global Church Management Software Market