
 Fixed LTE Wireless Broadband Market | 2026-2036
Fixed LTE Wireless Broadband Market Size, Share, and Industry Trends Forecast 2026-2036
Fixed LTE Wireless Broadband Market Insights
Baseband infrastructure deployment in South Korea is recalibrating supplier priorities across the fixed wireless value chain. Nokia Corporation leverages its massive MIMO portfolio to sustain leadership in carrier-grade CPE manufacturing. Huawei Technologies Co. Ltd. anchors supply chains across emerging markets with integrated macro cell and customer premise equipment offerings. Samsung Electronics competes through vertical control over modem silicon and antenna design.
Fixed LTE wireless broadband delivers high-speed internet access through stationary subscriber units operating on standardized 4G spectrum allocations, typically achieving 25–100 Mbps downstream via outdoor directional antennas with carrier aggregation. The technology serves as a fiber alternative for households and enterprises lacking wired infrastructure, with TD-LTE variants dominating unpaired spectrum deployments across Asia and Africa. Residential service types generate the largest revenue pool though commercial and industrial segments command premium pricing due to SLA-backed throughput guarantees. Private network deployments are accelerating fastest among mining operations and utility grids seeking cellular reliability without public carrier dependency.
The FCC governs spectrum auctions and device certification in the United States, directly shaping equipment vendor market access and operator rollout timelines. ETSI and 3GPP frameworks in Europe enforce interoperability mandates that constrain proprietary lock-in and accelerate modular procurement across the value chain. Stakeholders must monitor mid-band spectrum clearing progress and C-band auction outcomes to anticipate capacity expansion windows and competitive repositioning cycles.
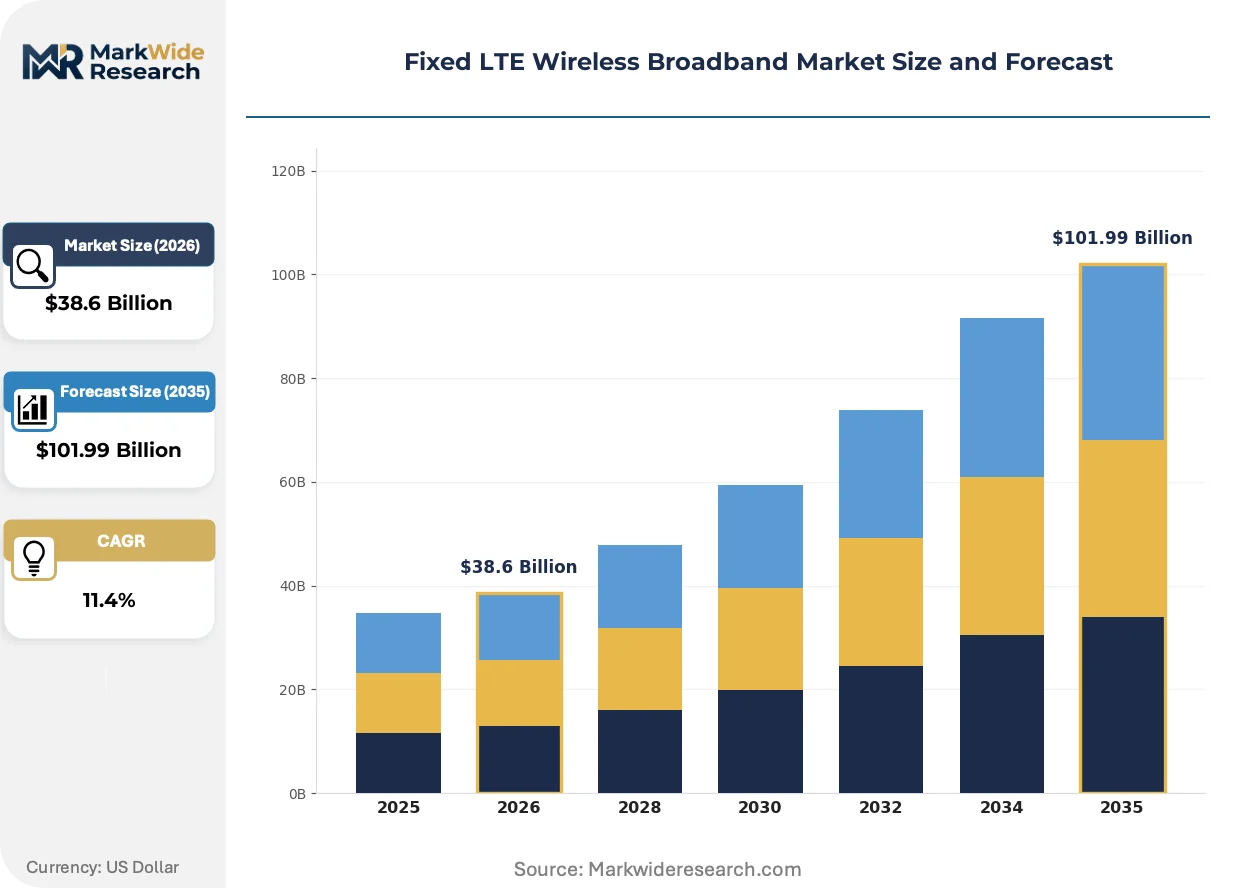
Market Dynamics
Spectrum reallocation policies by the FCC are compressing deployment timelines for fixed wireless operators while simultaneously fragmenting equipment procurement across incompatible regional band plans. This regulatory velocity is forcing infrastructure vendors to maintain parallel product SKUs for adjacent markets.
Growth Catalysts
- Mid-band spectrum clearing:The FCC's C-band auction outcomes are unlocking contiguous 100 MHz channels for carrier aggregation, enabling gigabit-class fixed wireless throughput in suburban United States markets previously served by legacy DSL.
- Rural electrification mandates:Brazil's national broadband plan prioritizes fixed wireless for Amazon basin settlements where fiber trenching faces prohibitive terrain and regulatory barriers from environmental agencies.
- Carrier aggregation evolution:TD-LTE Advanced Pro is integrating five-component carrier bonding, allowing operators in India to combine unpaired TDD spectrum blocks for symmetric upstream-downstream ratios that match enterprise SLA requirements.
Market Restraints
- Semiconductor supply concentration:Baseband chipset fabrication concentrates at TSMC's 7nm and 5nm nodes, creating single-source dependency for integrated macro cell DSPs and CPE modems.
- Line-of-sight propagation limits:Millimeter-wave and upper mid-band signals attenuate through vegetation and precipitation, restricting reliable coverage radius to 3-5 kilometers in tropical climates without dense small cell overlays.
- Right-of-way regulatory friction:Tower siting permits from municipal authorities in tier-two Indian cities impose 18-24 month approval cycles, delaying base station activation despite cleared spectrum availability.
Strategic Opportunities
- Private network deployments:Mining operations in South Africa's platinum belt are procuring dedicated TD-LTE infrastructure for autonomous haulage control, bypassing public carrier dependency and latency variability.
- Utility grid modernization:Smart metering backhaul via fixed wireless is displacing unlicensed mesh networks for distribution automation, with Brazilian utilities prioritizing cellular reliability for outage management systems.
- Convergence with satellite:Hybrid CPE terminals integrating geostationary and low-earth-orbit failover are emerging for remote enterprise sites in Australia's outback where terrestrial backhaul remains uneconomical.
Industry Challenges
- RF engineering talent scarcity:Massive MIMO beamforming optimization requires specialized expertise in 3D antenna pattern modeling, with fewer than 200 qualified engineers available across India's vendor ecosystem.
- Multi-band certification complexity:FCC equipment authorization for C-band CPE requires separate testing protocols for each regional power spectral density limit, extending time-to-market by 8-12 months for modular designs.
- Legacy copper interconnection:Incumbent wireline operators in Brazil resist colocation at central offices, forcing fixed wireless providers to construct parallel fiber backhaul from scratch.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fixed LTE Wireless Broadband Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: TD-LTE, FD-LTE, LTE-Advanced, LTE-M Service Type: Residential, Commercial, Industrial, Government Deployment Model: Private Network, Public Network, Hybrid Network, Managed Services End User: Households, Small Businesses, Large Enterprises, Educational Institutions |
| Companies Covered | Nokia Corporation, Cisco Systems Inc., AT&T Inc., Commscope Holding Company Inc., Samsung Electronics, Verizon, Huawei Technologies Co. Ltd., Zyxel Communications Corp, T-Mobile USA, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fixed LTE Wireless Broadband Market Trends and Innovations
Open RAN disaggregation is fragmenting the baseband supplier landscape while compressing hardware margins. This architectural shift enables multi-vendor interoperability but complicates system integration accountability.
Massive MIMO antenna arrays are integrating 64-element configurations with 3D beamforming algorithms for fixed wireless access. Rural electric cooperatives in the United States are adopting these systems to serve 50-100 subscriber locations per tower site. The technology is integrating spatial multiplexing gains that were previously exclusive to dense urban mobile networks into low-density deployment economics.
ETSI's FWA specifications under 3GPP Release 16 are mandating enhanced interference mitigation for unlicensed spectrum coexistence. European operators must now implement listen-before-talk protocols in 5.8 GHz bands shared with Wi-Fi and radar systems. German utilities deploying private LTE for grid automation are responding with spectrum sensing hardware that adds 15-20 percent to CPE bill-of-materials.
Enterprise procurement of fixed wireless is consolidating through managed service contracts rather than standalone connectivity purchases. Brazilian agribusiness operations are contracting system integrators for bundled CPE, installation, and SLA-backed support. This bundling is most visible in Mato Grosso soy belt operations where seasonal bandwidth spikes require flexible capacity scaling without capital ownership.
Fixed LTE Wireless Broadband Market Segmentation
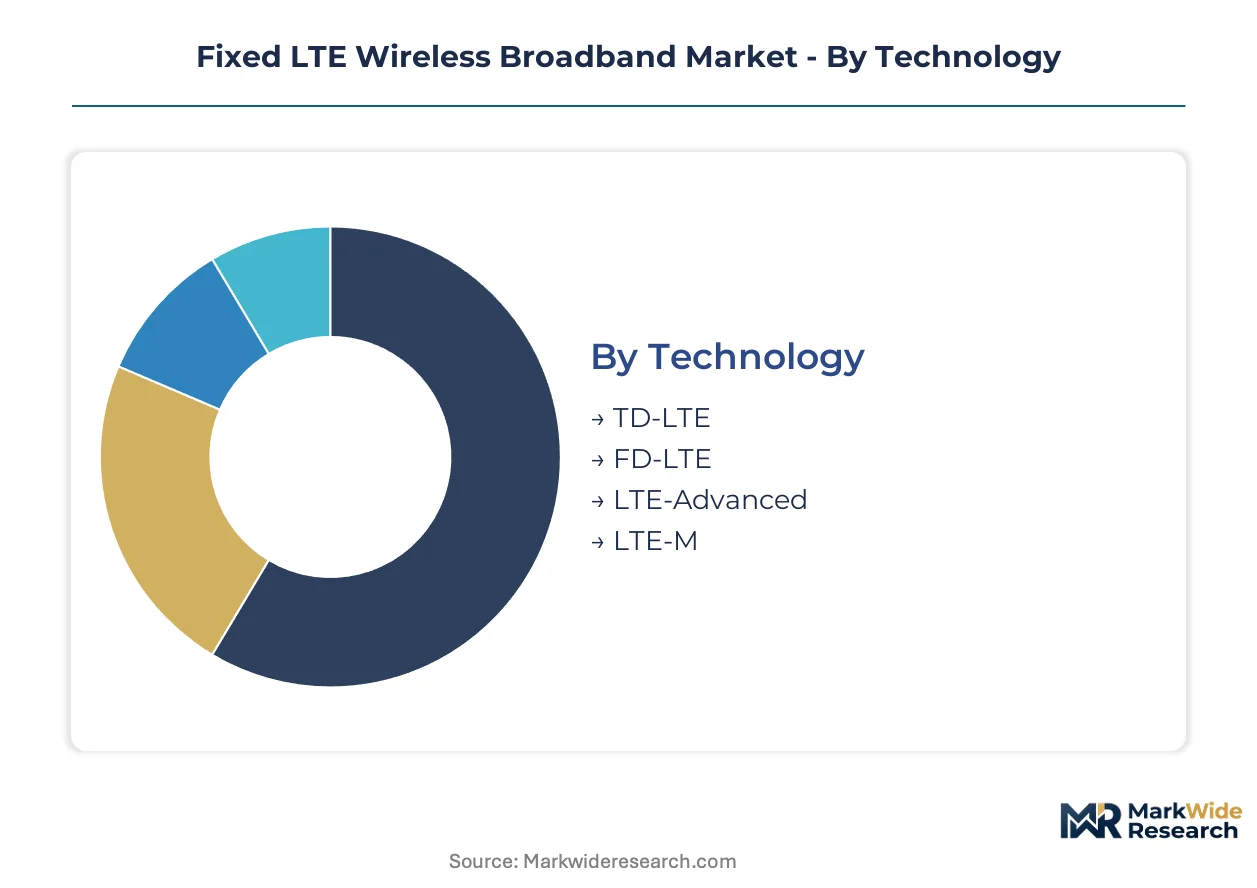
Fixed LTE wireless broadband segmentation reveals how certification requirements, spectrum licensing, and deployment economics fragment procurement patterns across subscriber types. Equipment vendors must maintain parallel product lines to address divergent regulatory burdens and performance specifications.
Technology:
FCC equipment authorization for C-band CPE requires separate testing protocols for each regional power spectral density limit, fragmenting vendor certification roadmaps across TD-LTE and FD-LTE variants. ETSI interoperability mandates under 3GPP Release 16 impose additional protocol compliance layers for European deployments.
- TD-LTE:Time-division duplexing dominates unpaired spectrum deployments across India and Brazil, enabling asymmetric throughput profiles optimized for downstream-heavy residential consumption. TRAI's spectrum allocation framework in India favors TD-LTE for its spectral efficiency in sub-3 GHz bands where paired spectrum remains scarce.
- FD-LTE:Frequency-division duplexing commands premium positioning in enterprise SLA-backed contracts across the United States, leveraging paired spectrum blocks for symmetric upstream-downstream ratios critical to cloud-based operations. FCC C-band clearing has expanded contiguous paired allocations for FD-LTE carrier aggregation.
- LTE-Advanced:Carrier aggregation and enhanced MIMO configurations support 100+ Mbps throughput tiers for suburban United States markets displacing legacy DSL infrastructure.
- LTE-M:Narrowband IoT-optimized variant serves utility smart metering backhaul in Brazil's distribution automation networks where bandwidth requirements remain modest.
TD-LTE sits at the top of the volume ranking, with LTE-Advanced climbing the fastest as operators pursue gigabit-class throughput positioning.
Service Type:
Pricing stratification across residential, commercial, and industrial tiers reflects divergent SLA structures and installation complexity rather than raw bandwidth differentials alone.
- Residential:Outdoor CPE with directional antennas delivers 25-50 Mbps downstream to households lacking fiber access, generating the largest absolute subscriber base across rural United States cooperatives and Brazilian Amazon settlements. Brazil's national broadband plan prioritizes this segment through subsidized equipment programs.
- Commercial:SLA-backed throughput guarantees with sub-50ms latency commitments command 3-4x residential ARPU multiples, concentrated in Indian tier-two city retail chains and professional services firms. Municipal right-of-way delays in Indian cities compress deployment timelines for this segment.
- Industrial:Private network deployments for autonomous haulage and process control in South African mining operations and German manufacturing facilities require dedicated spectrum and edge computing integration.
- Government:Public safety and rural school connectivity programs in the United States and Brazil specify TAA-compliant equipment with enhanced cybersecurity certifications.
Residential service sits at the top of the volume ranking, with Industrial climbing the fastest as mining and utility sectors bypass public carrier dependency.
Deployment Model:
Capital ownership preferences and operational expertise gaps drive segmentation between operator-managed infrastructure and third-party service contracts.
- Private Network:Dedicated TD-LTE infrastructure for South African platinum belt mining operations and German utility grid automation delivers cellular reliability without public carrier latency variability or roaming dependencies.
- Public Network:Standard commercial subscriptions leverage existing macro cell density, dominating Brazilian residential deployments where tower sharing economics favor incumbent mobile operators.
- Hybrid Network:Primary fixed wireless with satellite failover configurations serve remote Australian enterprise sites and Amazon basin settlements where terrestrial backhaul remains uneconomical.
- Managed Services:Bundled CPE, installation, and SLA-backed support contracts consolidate procurement for Brazilian Mato Grosso agribusiness operations with seasonal bandwidth scaling requirements.
Public Network sits at the top of the volume ranking, with Managed Services climbing the fastest as enterprise buyers outsource operational complexity.
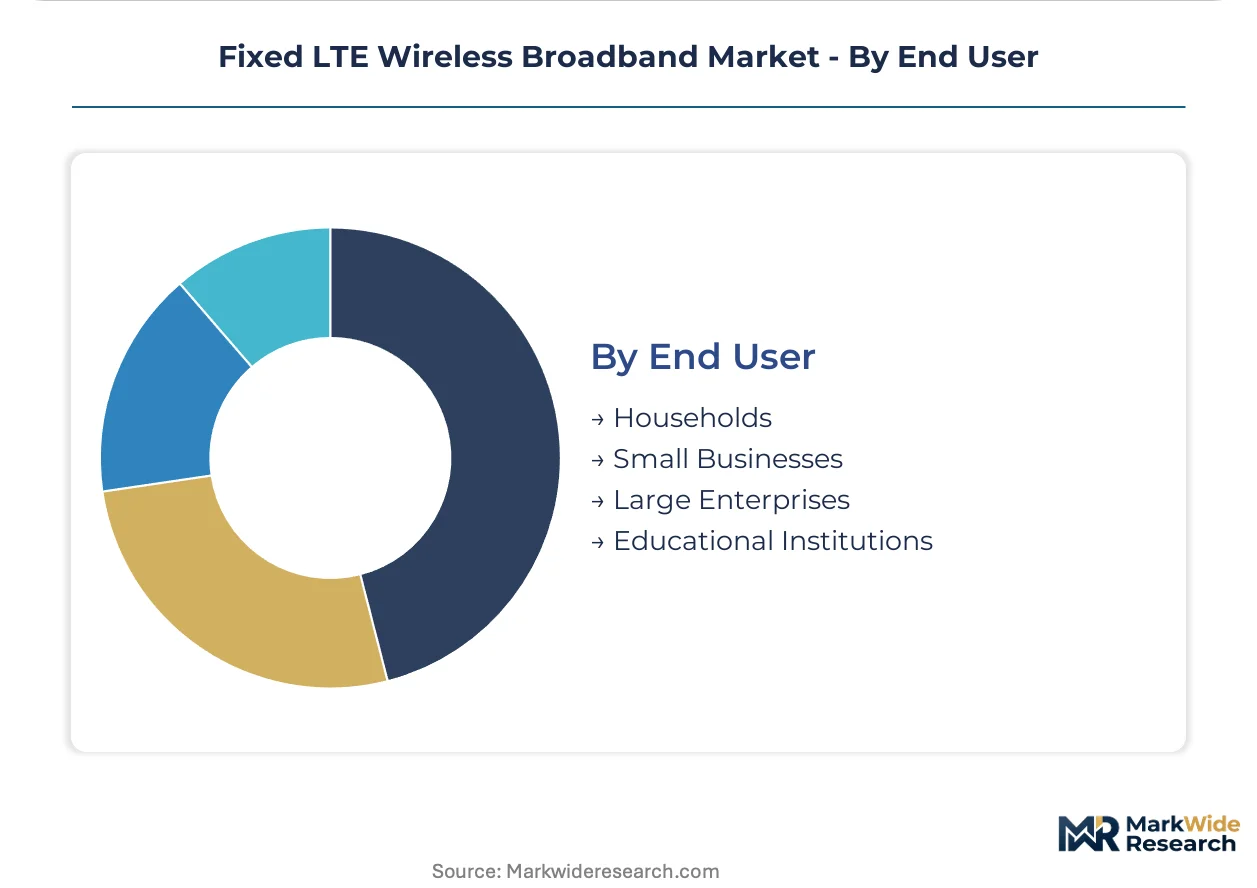
End User:
Procurement authority and technical sophistication determine whether subscribers self-install CPE or require turnkey deployment services.
- Households:Consumer-grade outdoor units with self-alignment features dominate United States rural electric cooperative deployments, where subscribers typically manage installation without technician dispatch.
- Small Businesses:Professional installation with rooftop mounting and Ethernet handoff prevails in Indian tier-two city retail and hospitality sectors lacking internal IT infrastructure.
- Large Enterprises:Multi-site contracts with centralized billing and API-driven traffic management characterize Brazilian agribusiness and German industrial conglomerate procurement patterns.
- Educational Institutions:E-rate subsidized deployments in United States rural school districts specify CIPA-compliant content filtering and extended hardware warranties.
Households sit at the top of the volume ranking, with Large Enterprises climbing the fastest as multi-site managed service contracts displace standalone connectivity purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment vendors are arbitraging regulatory compliance costs by routing certification-heavy C-band CPE production through jurisdictions with streamlined FCC mutual recognition agreements, while maintaining TD-LTE manufacturing clusters in markets with lighter type-approval burdens.
United States
Rural electric cooperatives in the Midwest and Southeast are deploying massive MIMO systems to serve subscriber clusters of 50-100 households per tower site. The FCC's C-band auction clearing has unlocked contiguous 100 MHz channels for carrier aggregation, compressing deployment timelines for fixed wireless operators in suburban markets previously dependent on legacy DSL infrastructure.
Brazil
Amazon basin settlements and Mato Grosso soy belt operations are driving managed service contract consolidation for bundled CPE and SLA-backed support. ANATEL's national broadband plan prioritizes fixed wireless for terrain-prohibitive regions where environmental agencies block fiber trenching permits.
India
Tier-two city retail chains and professional services firms in Karnataka and Telangana command 3-4x residential ARPU multiples for commercial-grade throughput guarantees. TRAI's spectrum allocation framework favors TD-LTE for spectral efficiency in sub-3 GHz bands where paired spectrum remains scarce.
South Korea
Baseband infrastructure deployment is recalibrating supplier priorities across the fixed wireless value chain, with Seoul-based operators integrating 64-element antenna configurations for 3D beamforming optimization. The country's Ministry of Science and ICT has accelerated mid-band clearing timelines to support gigabit-class fixed wireless throughput.
Germany
Industrial conglomerates in Bavaria and Baden-Württemberg are procuring private LTE networks for manufacturing automation, displacing unlicensed mesh networks with cellular reliability. ETSI's FWA specifications under 3GPP Release 16 mandate enhanced interference mitigation protocols that German utilities are addressing through spectrum sensing hardware additions.
Fixed LTE Wireless Broadband Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue private network specialization and managed service bundling as differentiation vectors. The vendor landscape exhibits moderate consolidation around integrated macro cell and CPE offerings, with fragmentation increasing at the disaggregated Open RAN layer. Three archetypes dominate: spectrum-integrated infrastructure vendors, silicon-verticulated equipment manufacturers, and carrier-affiliated service providers. Competitive repositioning occurs through strategic partnerships for tower sharing economics and portfolio diversification into satellite-hybrid terminals.
Among Nordic-origin infrastructure specialists, Nokia Corporation occupies a position exemplifying carrier-grade CPE manufacturing at scale. Samsung Electronics anchors the Korean vendor cluster through captive modem silicon and antenna design integration. Huawei Technologies Co. Ltd. represents the integrated macro cell and customer premise equipment archetype across emerging market supply chains.
| Leading Market Players |
|---|
| Nokia Corporation |
| Cisco Systems Inc. |
| AT&T Inc. |
| Commscope Holding Company Inc. |
| Samsung Electronics |
| Verizon |
| Huawei Technologies Co. Ltd. |
| Zyxel Communications Corp |
| T-Mobile USA, Inc. |
| Others |
Pricing and Supply Chain Analysis
Brazil's environmental licensing requirements for tower construction in Amazon basin settlements gate both qualified EPC contractor supply and premium-tier managed service pricing for remote fixed wireless deployments. This regulatory filter compresses vendor pools while elevating contract values for compliant operators.
Pricing Analysis
Distributor margins of 12-18 percent on CPE hardware compress final pricing flexibility for operators in India's tier-two cities. Three-tier pricing structure across carrier-grade, enterprise, and consumer CPE levels reflects FCC certification grade and after-sales bundling intensity. Cost compression in consumer-tier equipment is intensifying because of Open RAN disaggregation and multi-vendor procurement. Residential subscribers in Brazilian Amazon settlements exhibit highest price sensitivity, while South African mining operations show lowest sensitivity due to productivity-linked ROI calculations.
Supply Chain Analysis
Freight costs for massive MIMO antenna arrays from South Korea to Midwest United States rural electric cooperatives add 8-12 percent to landed equipment costs. Baseband chipset fabrication concentrates in Taiwan and South Korea, with final assembly drawing from China and Vietnam. Single-source vulnerability at TSMC's 7nm and 5nm nodes threatens integrated macro cell DSP supply continuity. Distribution runs through carrier-direct procurement for large deployments and regional systems integrators for private network installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by mining and utility sector demand-shift toward SLA-backed private networks with sub-50ms latency specifications. Premium procurement now prioritizes cellular reliability over cost minimization.
For Market Incumbents: Deploy massive MIMO manufacturing scale as the primary defensive lever against Open RAN fragmentation. Incumbents should anchor carrier-grade CPE certification pipelines at FCC and ANATEL to delay modular procurement adoption. Capacity addition in South Korea and Brazil maintains proximity to fastest-growing demand clusters. Threat from silicon-verticulated competitors like Samsung Electronics demands captive antenna design investment. For New Entrants and Emerging Players: Enter via private network specialization for autonomous haulage and grid automation applications where incumbent mobile operators lack vertical expertise. White-space targets include South African platinum belt mining operations and German Bavarian manufacturing facilities seeking cellular reliability without public carrier dependency. Most penetrable segment: utility smart metering backhaul in Brazil's distribution networks. Go-to-market angle: bundled CPE-installation-SLA contracts displacing unlicensed mesh networks. For Investors and Strategic Acquirers: Roll-up economics work for managed service integrators because enterprise procurement is consolidating through bundled contracts rather than standalone connectivity purchases. Long-term viability centers on recurring revenue streams with seasonal flexibility for agribusiness operations. Acquisition target archetype: regional systems integrators with ANATEL-licensed technician networks. Signal to watch: mid-band spectrum clearing progress in United States C-band and Indian sub-3 GHz allocations as inflection indicator for capacity expansion windows.| Strategic Initiative | Industry Significance |
|---|---|
| Spectrum Portfolio Expansion | FCC C-band auction participation unlocks contiguous 100 MHz channels for gigabit-class throughput positioning. |
| Private Network System Integration | Vertical expertise in mining automation commands 3-4x ARPU multiples over residential service tiers. |
| Managed Service Contract Bundling | Brazilian agribusiness procurement patterns favor outsourced operational complexity with seasonal scaling. |
| Open RAN Architectural Pivot | Multi-vendor interoperability mandates fragment hardware margins while enabling new entrant participation. |
| Satellite-Hybrid Terminal Development | Australian outback and Amazon basin demand integrates geostationary failover for uneconomical terrestrial backhaul. |
Research Methodology
Direct dialogue with network planning executives at rural electric cooperatives, RF engineering directors at infrastructure vendors, procurement leads at Brazilian agribusiness operations, and regulatory affairs specialists at ANATEL and FCC grounded qualitative findings. Secondary validation drew from FCC equipment authorization databases, TRAI spectrum allocation notices, 3GPP release documentation, and SEC filings of listed equipment manufacturers. Bottom-up subscriber forecasts across deployment models triangulated against top-down infrastructure spending projections.
Segmented outputs across TD-LTE and FD-LTE technology variants, residential-commercial-industrial service tiers, and private-public-hybrid deployment models populated the analytical framework across the projection horizon. CAGRs were derived from subscriber penetration curves weighted against spectrum clearing timelines and tower siting approval cycles. Key inputs included carrier aggregation evolution trajectories and massive MIMO unit cost decline curves.
Inputs from FCC and ANATEL regulatory filings were available through the study window; gaps in real-time tower activation data introduce uncertainty bands around Indian tier-two city deployment timelines. Forecasts reflect assumptions on mid-band clearing progress and semiconductor supply normalization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Telecom Wireless Data Market
Wireless Technologies
Industrial 5G Market
Wireless Technologies
5G Mmwave Technology Market
Wireless Technologies
P2P Antennas Market
Wireless Technologies
APAC Small Cell Tower Market
Wireless Technologies
5G Spectrum Market
Wireless Technologies
Global Massive MIMO Market
Wireless Technologies
Global in-Building Wireless Market
Wireless Technologies
5G Fixed Wireless Access Market
Wireless Technologies
Underwater Wireless Communication Market
Wireless Technologies
Wireless Phone Chargers Market
Wireless Technologies
Global Gi Fi Technology Market
Wireless Technologies
Wireless Microphone Market
Wireless Technologies
Wireless Communication Equipment Market
Wireless Technologies
Base Transceiver Station (BTS) Market
Wireless Technologies
Near Field Communication Market