
 Insight As a Service Application Market | 2026-2036
Insight As a Service Application Market Size, Share, and Industry Trends Forecast 2026-2036
Insight As a Service Application Market Foresight
Subscription-based delivery is decoupling analytics consumption from perpetual licensing, forcing vendors to restructure revenue recognition and customer success operations. Oracle Corporation leverages its cloud infrastructure to embed insight services within enterprise ERP workflows. IBM Corporation anchors its position through Watson-branded AI modules that sustain recurring engagement across healthcare and finance clients. Microsoft Corporation competes by extending Power BI into managed service bundles that occupy mid-market procurement budgets.
Insight As a Service Application denotes cloud-hosted analytics platforms that ingest structured and unstructured data, apply machine learning models with sub-second query latency, and deliver actionable intelligence through embedded dashboards or API endpoints. The architecture eliminates on-premise data warehouse maintenance while enabling real-time decision pipelines for revenue operations and supply chain teams. Predictive analytics leads application-type revenue as manufacturing and finance clients prioritize demand forecasting and risk scoring over retrospective reporting. API integration dominates delivery architecture because enterprises require seamless data flow between CRM systems, ERP records, and external market signals without manual extract-transform-load cycles.
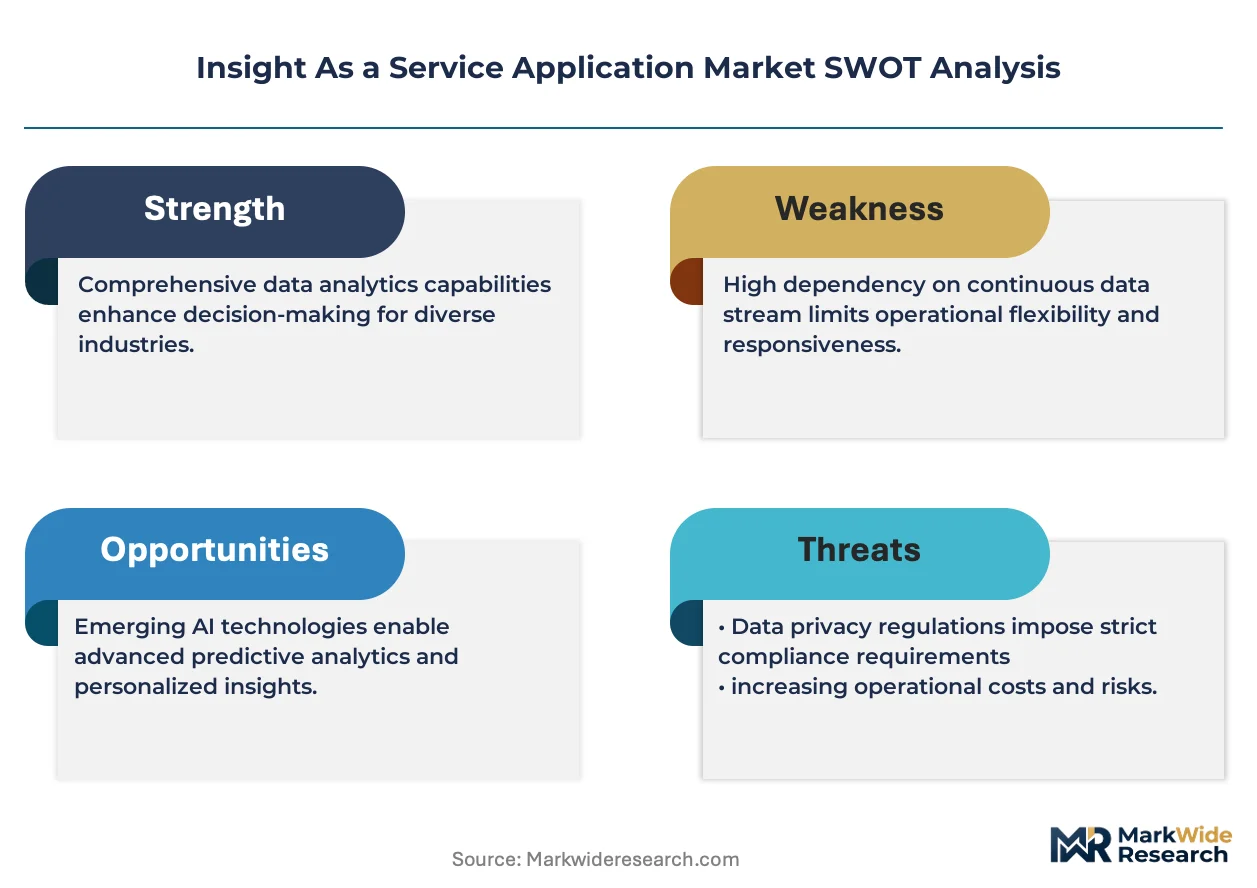
EU GDPR and the EU AI Act impose algorithmic transparency and data minimization requirements that constrain model training methodologies and cross-border data transfers. The US SEC and HIPAA frameworks in healthcare finance mandate audit trails and access controls that elevate compliance costs for multi-tenant platform architectures. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether to localize inference infrastructure or standardize on the most restrictive common denominator.
Market Dynamics
Subscription billing models are restructuring vendor economics by replacing upfront license revenue with recurring streams, forcing platform providers to rebuild customer success functions around consumption metrics and retention engineering.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements are accelerating procurement of managed analytics services that embed governance tooling, as enterprises seek pre-certified platforms to reduce internal audit burdens.
- Manufacturing demand forecasting:Discrete and process manufacturers are deploying predictive modules to compress inventory cycles and align procurement with volatile raw material availability.
- Real-time API architectures:Sub-second query latency requirements are pulling enterprises away from batch-processed on-premise warehouses toward cloud-native inference pipelines.
Market Restraints
- Cross-border data transfer friction:GDPR data residency clauses and Schrems II rulings are fragmenting cloud infrastructure deployment, forcing redundant regional instances that inflate operational overhead.
- Specialized MLOps talent scarcity:Shortages of engineers capable of productionizing transformer models at scale are extending implementation timelines and inflating professional services costs.
- Legacy ERP integration complexity:Custom connector development for SAP and Oracle on-premise installations consumes 30-40% of deployment budgets, compressing margins on mid-market contracts.
Strategic Opportunities
- Healthcare HIPAA-compliant analytics:Providers and payers are consolidating patient records into unified platforms, creating demand for managed services with pre-built audit trails and access controls.
- Edge inference deployment:Manufacturing and logistics clients are distributing model execution to factory floors and warehouse nodes, reducing latency for quality control and routing decisions.
- CSRD sustainability reporting:EU corporate sustainability disclosure rules are mandating granular emissions tracking, pulling demand for supply chain analytics that ingest Scope 3 data from tiered suppliers.
Industry Challenges
- Model drift monitoring at scale:Production teams struggle to maintain prediction accuracy as input data distributions shift, requiring continuous retraining pipelines that strain compute budgets.
- Multi-tenant security architecture:Platform engineers must isolate client data within shared infrastructure while preserving query performance, complicating encryption key management and access logging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insight As a Service Application Market |
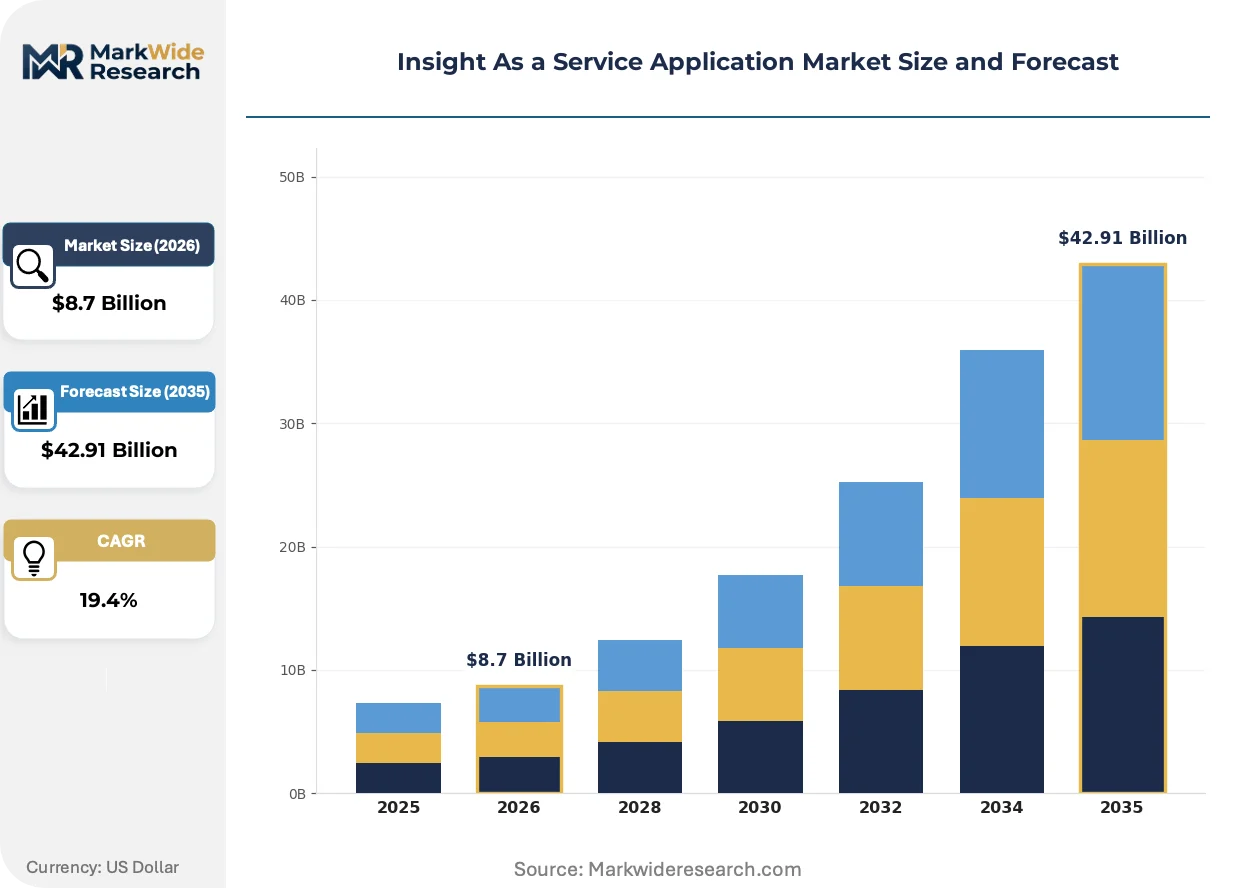
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Market Research, Customer Analytics, Predictive Analytics, Reporting Tools Delivery Model: Subscription-Based, Pay-As-You-Go, On-Premise, Managed Service End User: Healthcare, Retail, Finance, Manufacturing Integration Level: API Integration, CRM Integration, Data Warehouse Integration, Standalone Solutions |
| Companies Covered | Oracle Corporation, IBM Corporation, Accenture PLC, Dell Technologies Inc., GoodData Corporation, Capgemini SE, Microsoft Corporation, Deloitte Touche Tohmatsu India LLP, NTT DATA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insight As a Service Application Market Shifts & Advancements
Generative AI capabilities are embedding directly into analytics workflows, compressing the distance between raw data ingestion and natural language insight delivery. Three developments are restructuring competitive positioning.
Transformer-based natural language interfaces are absorbing query construction tasks previously handled by SQL specialists. Business analysts at financial services and retail firms are adopting conversational exploration tools without coding backgrounds. This capability is absorbing demand for traditional BI certification programs and compressing the premium attached to technical specialist roles.
EU AI Act risk classification tiers are mandating human-in-the-loop review for high-stakes automated decisions in credit scoring and medical diagnostics. Platform vendors are embedding explanation layers and override workflows to satisfy conformity assessments. Healthcare and finance deployments in Germany and France are prioritizing vendors with pre-submitted technical documentation packages.
Consumption-based pricing is displacing seat-based licenses as the dominant procurement structure. Enterprise buyers are negotiating contracts tied to query volume or data processed rather than named user counts. This shift is most visible among United States mid-market software firms seeking to align analytics spending with actual utilization patterns rather than headcount growth.
Insight As a Service Application Market Segmentation
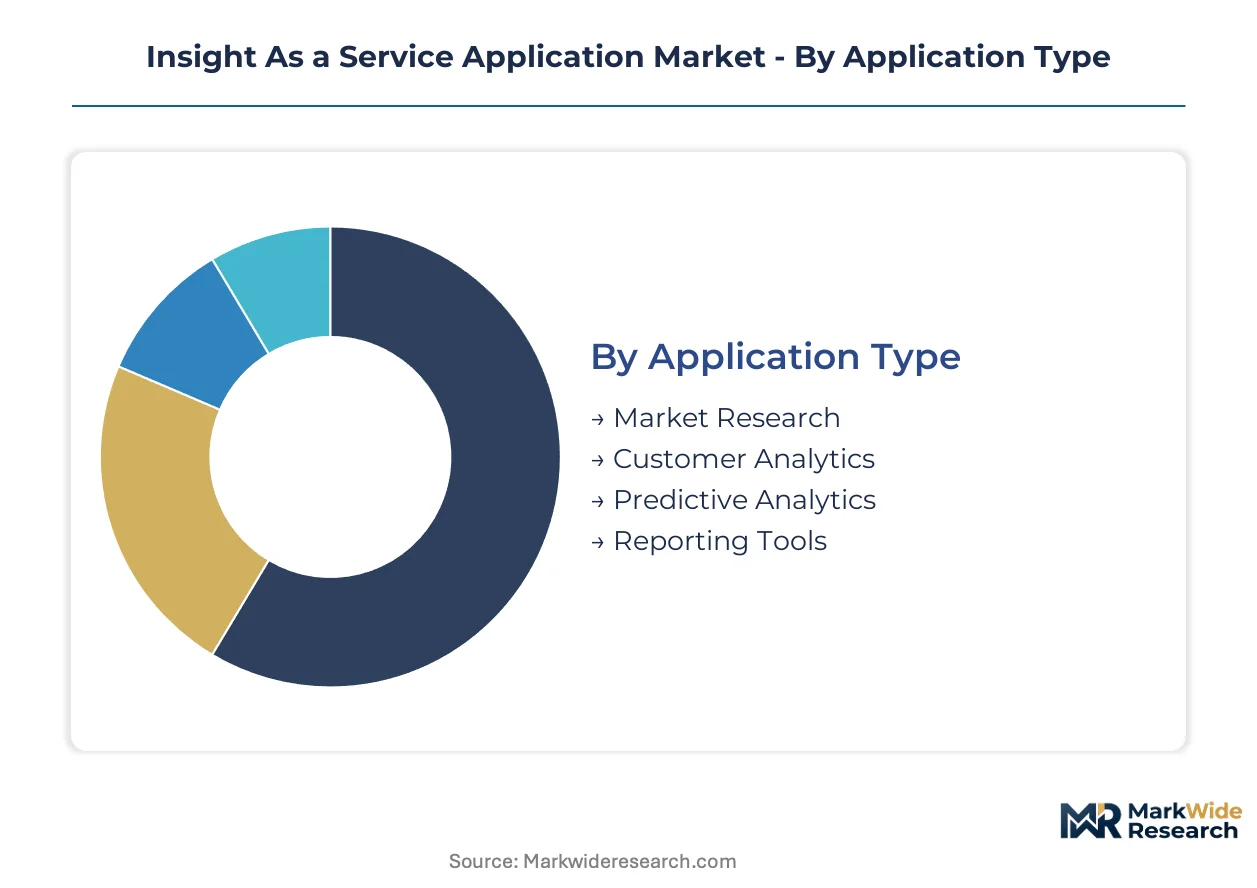
Segmentation in the Insight As a Service Application market reveals how procurement patterns split between standardized cloud subscriptions and highly customized managed deployments. Buyers trade off implementation speed against integration depth, with regulatory pressure and legacy system footprints determining which configuration dominates.
Application Type:
Predictive modules command premium pricing through specialized model development, while descriptive tools compete on deployment velocity and user accessibility.
- Predictive Analytics:Machine learning pipelines ingest historical transaction patterns and external market signals to forecast demand curves, risk exposures, and equipment failure probabilities. Manufacturing procurement teams in Germany and finance risk officers in the United States prioritize these capabilities for inventory optimization and credit scoring workflows.
- Customer Analytics:Behavioral segmentation engines unify clickstream data, purchase histories, and loyalty program records into unified customer profiles. Retail chains across France and healthcare patient engagement teams deploy these modules to personalize outreach and predict churn propensity.
- Market Research:Survey aggregation platforms with automated sentiment classification.
- Reporting Tools:Dashboard visualization systems for retrospective performance tracking.
Most installed capacity flows through Predictive Analytics. Expansion is steepest in Customer Analytics.
Delivery Model:
Revenue recognition complexity varies sharply across this spectrum, with consumption-metered contracts requiring fundamentally different customer success operations than perpetual license arrangements.
- Subscription-Based:Fixed monthly or annual fees grant unlimited access to platform capabilities within contracted tier limits, locking in predictable recurring revenue streams. United States enterprise software procurement teams favor this structure for budget forecasting, while EU buyers demand data residency clauses that fragment vendor infrastructure.
- Managed Service:Vendors assume full operational responsibility for model training, drift monitoring, and infrastructure scaling under outcome-based service level agreements. Healthcare providers in Germany and France select this option to satisfy EU AI Act conformity requirements without building internal MLOps teams.
- Pay-As-You-Go:Query-volume or data-processed billing aligned to actual utilization spikes.
- On-Premise:Licensed software deployed within client-controlled data centers for maximum sovereignty.
Subscription-Based contracts anchor vendor revenue stability. Managed Service engagements are climbing the fastest as compliance burdens intensify.
End User:
Industry-specific regulatory frameworks and data sensitivity levels create distinct procurement criteria across vertical deployments.
- Finance:Real-time risk scoring, fraud detection, and algorithmic trading analytics with SEC audit trail mandates. United States banks and insurance carriers dominate procurement volumes, prioritizing sub-second latency for transaction monitoring.
- Healthcare:Patient outcome prediction, clinical trial optimization, and operational efficiency analytics under HIPAA and GDPR constraints. German hospital networks and United States health systems drive demand for pre-certified platforms with embedded explanation layers.
- Manufacturing:Demand forecasting, predictive maintenance, and supply chain optimization modules.
- Retail:Inventory positioning, dynamic pricing, and customer lifetime value prediction engines.
Finance absorbs the largest share of platform spending. Healthcare is expanding most quickly as EU AI Act implementation deadlines approach.
Integration Level:
Technical architecture choices determine implementation timelines, with seamless data flow requirements pushing buyers toward deeper embedding strategies.
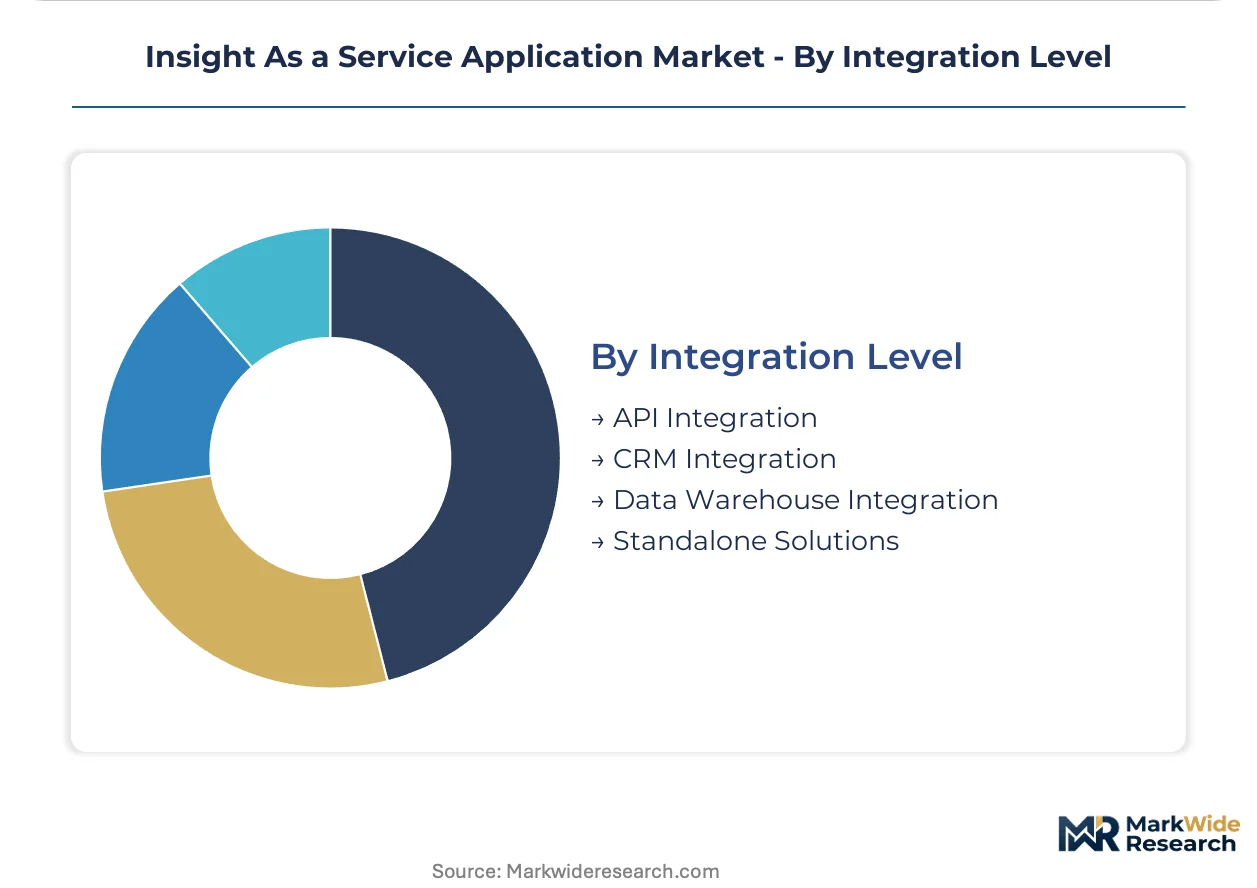
- API Integration:REST and GraphQL endpoints enable real-time data exchange between analytics platforms and operational systems without manual pipeline construction. United States mid-market software firms and German automotive suppliers prioritize this architecture to maintain ERP continuity while adding inference capabilities.
- Data Warehouse Integration:Native connectors to Snowflake, Databricks, and BigQuery environments eliminate extract-transform-load latency. Finance and healthcare data engineering teams in France and the United States select this path to preserve existing cloud data investments.
- CRM Integration:Pre-built connectors for Salesforce, HubSpot, and Microsoft Dynamics environments.
- Standalone Solutions:Self-contained platforms requiring manual data import and export processes.
API Integration carries the dominant deployment volume. Data Warehouse Integration is gaining share fastest as cloud-native data platforms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States enterprise procurement teams outpace German buyers in cloud analytics adoption velocity, yet Berlin and Munich hospital networks are closing the gap as EU AI Act deadlines approach. Regulatory fragmentation between SEC disclosure mandates and GDPR data residency clauses is forcing vendors to architect redundant regional infrastructure rather than unified global deployments.
United States
Financial services firms in New York and Chicago are deploying sub-second latency risk scoring modules for algorithmic trading and fraud detection workflows. SEC audit trail mandates elevate compliance costs for multi-tenant platform architectures. The San Francisco Bay Area enterprise software corridor concentrates vendor headquarters and early-adopter procurement budgets.
Germany
Automotive suppliers in Stuttgart and Munich are integrating predictive maintenance modules to align procurement with volatile raw material availability. EU AI Act algorithmic transparency requirements are accelerating procurement of managed analytics services with pre-certified governance tooling. The Rhine-Ruhr industrial belt hosts manufacturing clients prioritizing demand forecasting over retrospective reporting.
France
Healthcare providers in Paris and Lyon are consolidating patient records into unified platforms requiring HIPAA-equivalent audit trails and access controls. CNIL enforcement of GDPR data minimization rules constrains model training methodologies and cross-border data transfers. The Île-de-France region anchors pharmaceutical and clinical trial optimization analytics demand.
United Kingdom
London-based insurance carriers and retail chains are adopting customer analytics modules for behavioral segmentation and churn prediction. The Financial Conduct Authority's operational resilience requirements are elevating procurement scrutiny for cloud-hosted inference pipelines. The Thames Valley technology corridor hosts mid-market software firms negotiating consumption-based pricing contracts.
Japan
Manufacturing conglomerates in Tokyo and Osaka are distributing model execution to factory floors for quality control and routing decisions. METI guidelines on data sovereignty are encouraging localized inference infrastructure deployment. The Nagoya automotive cluster is prioritizing edge inference deployment over centralized cloud analytics.
Insight As a Service Application Market Competitive Landscape
Top-tier vendors anchor enterprise ERP and cloud infrastructure integration, while mid-tier specialists compete on vertical-specific compliance certifications and managed service outcomes. The vendor base stratifies across three tiers: hyperscale cloud providers with embedded analytics, global systems integrators with industry-specific solution factories, and pure-play analytics platforms with API-first architectures. Dominant competitive moves include strategic partnerships with legacy ERP vendors and geographic expansion through localized data residency infrastructure.
Among United States-based technology conglomerates, Oracle Corporation and Microsoft Corporation exemplify the hyperscale integration archetype, embedding insight services within enterprise workflow platforms. IBM Corporation represents the AI-native managed services tier, sustaining recurring engagement through Watson-branded modules. Accenture PLC and Capgemini SE occupy the systems integrator position, translating regulatory requirements into deployable governance tooling for European healthcare and finance clients.
| Leading Market Players |
|---|
| Oracle Corporation |
| IBM Corporation |
| Accenture PLC |
| Dell Technologies Inc. |
| GoodData Corporation |
| Capgemini SE |
| Microsoft Corporation |
| Deloitte Touche Tohmatsu India LLP |
| NTT DATA Corporation |
| Others |
Supply & Pricing Matrix
MLOps engineer concentration in the San Francisco Bay Area and Bangalore creates labor-cost differentials that widen pricing spreads between premium managed-service tiers and standardized API offerings. EU AI Act compliance investments in Frankfurt and Paris further stratify vendor cost structures, compressing margins on entry-level subscriptions while sustaining premium pricing for pre-certified governance bundles.
Pricing Analysis
Capacity additions in India and Eastern Europe are reshaping price floors for mid-market API integrations. Three-tier pricing structure across premium, standard, and economy levels anchors vendor revenue models, with premium tiers capturing EU AI Act pre-certification costs and dedicated inference infrastructure. Price differentiation rests on HIPAA compliance tier and sub-second latency guarantees. Cost compression in standard tiers is intensifying because hyperscaler compute pricing wars are eroding per-query margins. Mid-market software firms in the United States exhibit highest price sensitivity, while German healthcare networks tolerate premium pricing for managed-service outcomes.
Supply Chain Analysis
Single-source vulnerability sits with NVIDIA GPU supply through Taiwan Semiconductor Manufacturing and high-bandwidth memory from South Korea. Cloud infrastructure provisioning draws from United States hyperscaler regions, Irish data centers, and Singapore availability zones. Transformer model weights and training datasets hinge on proprietary vendor investments, creating captive supply dynamics. Tariff exposure on Chinese-manufactured edge inference hardware is fragmenting hardware procurement strategies. Distribution runs through direct enterprise sales teams for healthcare and finance verticals, with channel partners serving mid-market software clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Insight As a Service Application market functions as a stable compounder, with recurring subscription revenue and compliance-mandated refresh cycles generating predictable cash flow visibility across economic cycles.
For Market Incumbents: Lock in customer switching costs by embedding inference pipelines directly into SAP and Oracle ERP workflows, reducing displacement risk from API-first challengers. Invest in EU AI Act technical documentation pre-submission to capture German and French healthcare procurement windows before certification backlogs accumulate. Vertical integration into edge hardware manufacturing insulates against GPU supply volatility. For New Entrants and Emerging Players: Capture white-space in HIPAA-compliant managed services for United States regional hospital networks lacking internal MLOps capabilities. Target EU AI Act conformity assessment tooling as the most penetrable segment, selling governance automation to incumbent platforms rather than competing on raw inference performance. Pursue channel partnerships with systems integrators possessing existing healthcare and finance relationships. For Investors and Strategic Acquirers: Cloud hyperscalers with existing enterprise distribution footprints are the most active acquirer in this space, seeking vertical-specific compliance expertise to augment generic infrastructure offerings. Acquisition target archetypes include pre-certified EU AI Act compliance platforms and specialized healthcare analytics vendors with embedded explanation-layer IP. Watch for inflection when United States SEC mandates expand algorithmic transparency requirements beyond current audit trail standards, triggering compliance-driven procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification Investment | German hospital networks prioritize vendors with submitted technical documentation packages. |
| Edge Inference Infrastructure Deployment | Manufacturing clients in Japan's Nagoya automotive cluster demand factory-floor model execution. |
| HIPAA-Compliant Managed Service Launch | United States regional health systems seek outsourced MLOps without internal engineering hires. |
| API-First Architecture Expansion | Mid-market software firms in the United States prioritize seamless ERP and CRM data flow. |
| Strategic Partnership with Systems Integrators | Accenture and Capgemini translate EU regulatory requirements into deployable governance tooling. |
Research Methodology
Multiple input streams — executive interviews with platform engineering leaders, procurement officer surveys at financial services firms, and regulatory affairs consultations with EU AI Act implementation teams — were reconciled against secondary validation. CTOs at United States mid-market software companies, IT procurement officers at German automotive suppliers, healthcare CIOs in France and the United Kingdom, and MLOps platform engineers at cloud hyperscalers contributed primary perspectives. SEC disclosure filings, EU AI Act implementation guidance documents, HIPAA audit protocol databases, and hyperscaler capex announcements furnished secondary data anchors. Bottom-up deployment estimates and top-down market sizing were triangulated to constrain variance.
Data-stream reconciliation applied across the projection horizon employed segment-specific growth drivers for predictive analytics, customer analytics, and managed service delivery models. Modeled dimensions included application type complexity, integration architecture depth, end-user vertical regulatory burden, and regional cloud adoption maturity. CAGRs were derived from fitted growth curves calibrated to historical subscription revenue recognition patterns and compliance-driven procurement acceleration events. Forecast inputs incorporated EU AI Act implementation deadline effects and United States SEC algorithmic transparency rulemaking trajectories.
Regulatory delay, hyperscaler pricing volatility, and MLOps talent supply constraints are the dominant revision risks to modeled outcomes. Forecasts embed assumptions regarding compliance timeline adherence and cloud infrastructure availability zone expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Data Monetization Platform Market
Digital Solutions
Smart Process Application (SPA) Market
Digital Solutions
Product Life Cycle Management (PLM) Market
Digital Solutions
Global Genealogy Products and Services Market
Digital Solutions
Electronic Records Management Solutions Market
Digital Solutions
Manufacturing Execution System Market
Digital Solutions
End-User Computing (EUC) Market
Digital Solutions
Returnless Refund Fraud Detection Market
Digital Solutions
Smart Government Market
Digital Solutions
Global Interactive Voice Response Market
Digital Solutions
Consent Management Market
Digital Solutions
Global Client Virtualization Market
Digital Solutions
Global Inventory Optimization Software Market
Digital Solutions
Product Design and Development Services Market
Digital Solutions
Mobile Ticketing Market
Digital Solutions
Global Smart Offices Market