
 Europe Wireless Charging Market | 2026-2036
Europe Wireless Charging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Wireless Charging Market Foresight
Market Context
Germany's industrial manufacturing base is fragmenting into specialized wireless power clusters across Bavaria and Baden-Württemberg. NXP Semiconductors anchors European chipset supply through its Eindhoven design centers and automotive-qualified transmitter portfolios. Qualcomm Inc. competes by leveraging its cross-licensing architecture across resonant and inductive standards. Samsung Electronics dominates consumer-grade pad manufacturing through its Polish assembly facilities serving EU retail channels.
Technology and Segments
Europe wireless charging encompasses contactless power transfer systems operating at frequencies between 110–205 kHz for inductive architectures and 6.78 MHz for resonant implementations, eliminating conductive interfaces through magnetic field coupling between transmitter coils and receiver assemblies. Magnetic induction sustains the largest installed base across smartphone and wearable applications, while resonant induction is capturing margin pools in automotive integrations where spatial tolerance and multi-device charging justify premium positioning. Radio frequency segments occupy early-stage commercial deployment in healthcare devices and industrial sensor networks where watt-level delivery suffices.
Regulatory Environment
EMA's electromagnetic compatibility directives and the EU Green Deal's interoperability mandates shape product certification requirements and infrastructure rollout timelines across member states. CE marking under RED 2014/53/EU and emerging Ecodesign regulations govern efficiency thresholds and standby power limits for charger ecosystems. Stakeholders must monitor whether the EU AI Act's device classification framework extends to intelligent power management algorithms embedded in next-generation charging controllers.
Market Dynamics
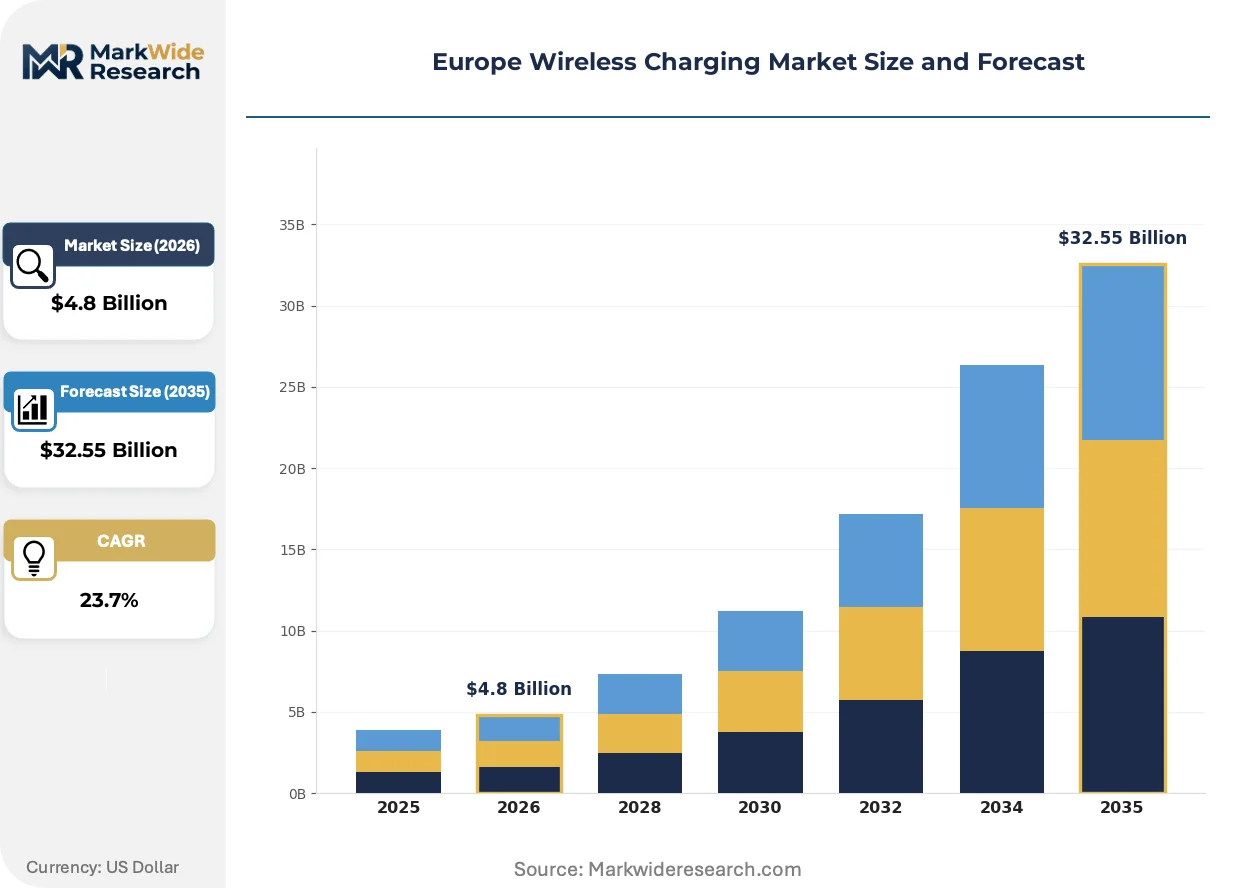
The EU Green Deal's interoperability mandates are forcing a convergence between automotive OEMs and infrastructure providers around standardized coil architectures, compressing development cycles and locking in supplier relationships before secondary markets mature.
Growth Catalysts
- EU Green Deal standardization:Mandated interoperability protocols accelerate infrastructure deployment across member states by eliminating proprietary lock-in between vehicle platforms and charging pads.
- Factory automation clusters:Bavaria and Baden-Württemberg industrial corridors are integrating inductive power transfer into automated guided vehicle fleets, creating concentrated demand for high-wattage transmitter systems.
- Magnetic resonance tolerance:Spatial freedom in coil alignment is capturing automotive design wins where multi-device cabin charging justifies premium component sourcing.
Market Restraints
- Ferrite core supply concentration:Rare-earth magnet processing capacity concentrates in Asian refining corridors, exposing European coil manufacturers to input volatility and tariff exposure.
- EMC certification friction:RED 2014/53/EU electromagnetic compatibility testing timelines extend product launch windows by six to nine months for multi-frequency architectures.
- Conductive cable substitution:High-power USB-C delivery above 100 watts retains cost advantage in consumer electronics, limiting wireless penetration in price-sensitive smartphone tiers.
Strategic Opportunities
- Polish assembly expansion:Consumer-grade manufacturing capacity in Eastern European industrial zones offers tariff-advantaged export positioning into German retail channels.
- Healthcare sensor integration:Watt-level radio frequency charging is penetrating implantable device applications where galvanic isolation eliminates infection risks from transcutaneous connectors.
- Ecodesign efficiency thresholds:Emerging standby power regulations under EU Ecodesign frameworks favor intelligent power management controllers that modulate field strength based on load detection.
Industry Challenges
- Multi-physics simulation talent:Electromagnetic-thermal-mechanical co-design expertise remains scarce across European engineering institutes, constraining rapid prototyping cycles.
- Legacy fleet retrofit complexity:Aftermarket pad installation in existing electric vehicle platforms requires chassis-level modifications that void manufacturer warranties and complicate insurance coverage.
- Cross-standard IP licensing:Patent thickets spanning Qi, PMA, and proprietary automotive protocols create royalty stacking that erodes margin pools for mid-tier chipset vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Wireless Charging Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $32.55 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Magnetic Induction, Resonant Induction, Radio Frequency, Capacitive Coupling End User: Consumer Electronics, Automotive, Industrial Equipment, Healthcare Devices Form Factor: Portable Chargers, Built-in Solutions, Vehicle Charging Pads, Desktop Stations Deployment: Public Charging Stations, Home Solutions, Commercial Installations, Automotive Integrations |
| Companies Covered | Mouser Electronics Europe, Qualcomm Inc., NXP Semiconductors, Analog Devices Inc., Samsung Electronics, WÜRTH ELEKTRONIK GMBH & CO. KG, WiTricity Corporation, Plugless, ZenS B.V, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Wireless Charging Market Shifts & Advancements
Resonant frequency architectures are compressing the traditional trade-off between spatial tolerance and power density, while regulatory pressure on standby consumption forces firmware-level intelligence into previously passive transmitter designs.
Gallium nitride power semiconductors are collapsing thermal management constraints in high-frequency inverter stages. Automotive Tier 1 suppliers are adopting GaN-based Class E amplifiers for 11 kW in-vehicle charging modules. This compression of switching losses enables passive cooling architectures that eliminate liquid loop complexity from underbody transmitter housings.
CE marking under RED 2014/53/EU is tightening electromagnetic emission thresholds for wearable-adjacent charging surfaces. The European Commission's draft revisions propose stricter limits on human exposure at 6.78 MHz resonant frequencies. Medical device manufacturers in Switzerland and Germany are pre-emptively redesigning coil geometries to maintain margin headroom against anticipated regulatory ratcheting.
Fleet procurement managers are consolidating vendor relationships around vertically integrated suppliers capable of delivering transmitter coils, power electronics, and cloud-based charge monitoring through single-source contracts. German automotive leasing subsidiaries are piloting subscription models where infrastructure costs bundle into monthly vehicle payments rather than capital expenditure line items. This shift is most visible in corporate fleet electrification programs across the Rhine-Ruhr industrial belt.
Europe Wireless Charging Market Segmentation
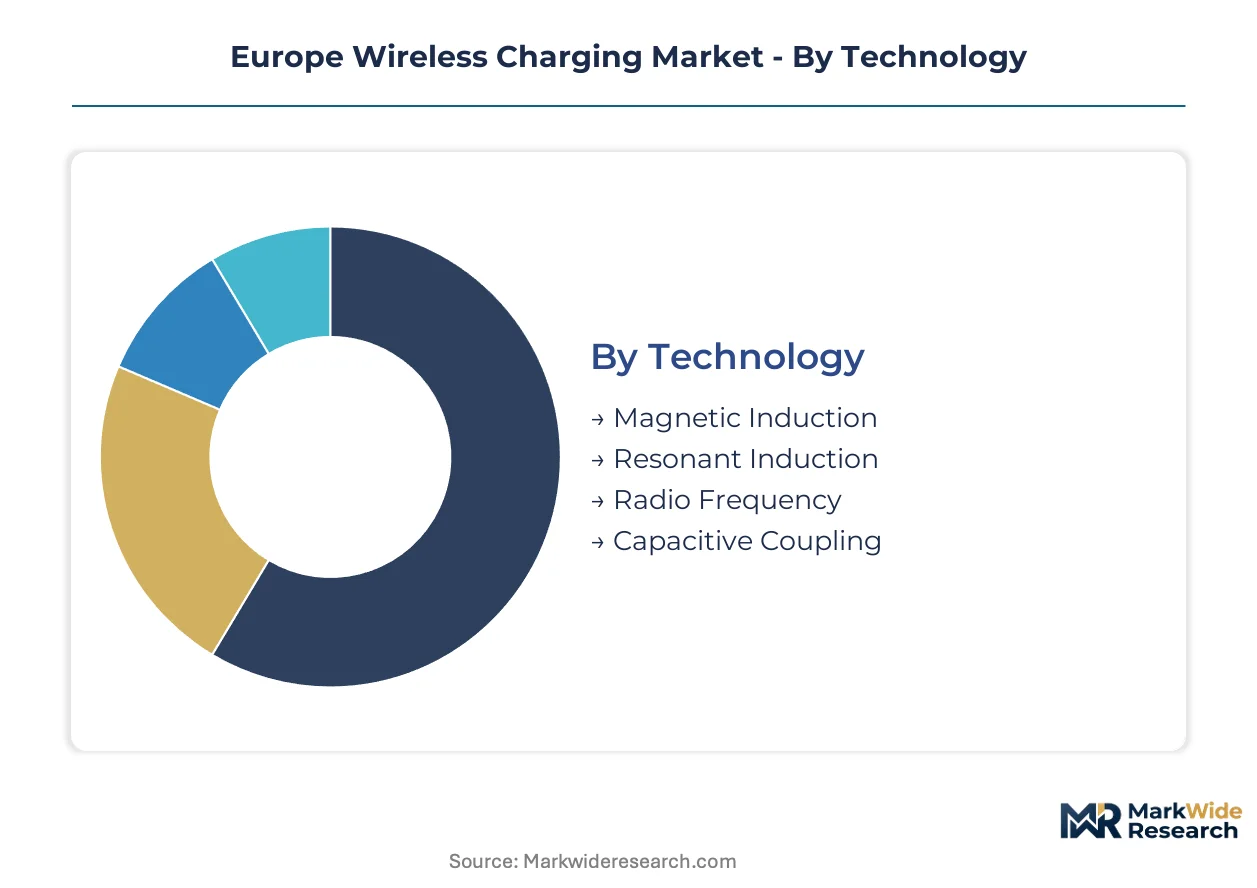
Wireless charging architectures in Europe fragment across four distinct dimensions, each with divergent refresh cycles and margin profiles. Technology selection determines electromagnetic compatibility testing burdens, while end-user concentration shapes coil specification requirements and supplier qualification timelines.
Technology:
Magnetic induction platforms turn over fastest as smartphone OEMs annualize design refreshes, whereas automotive resonant systems lock in for seven-to-ten-year vehicle platforms. Radio frequency and capacitive alternatives occupy intermediate refresh cycles tied to medical device certification and industrial sensor deployment schedules.
- Magnetic Induction:Operates at 110–205 kHz through tightly coupled transmitter-receiver coil pairs with alignment tolerances under 5mm. Smartphone and wearable demand concentrates in Poland's assembly corridors and Germany's retail distribution networks, where CE marking under RED 2014/53/EU drives six-to-nine-month certification timelines that compress product lifecycles.
- Resonant Induction:Functions at 6.78 MHz with spatial freedom extending coil alignment tolerance to 50mm, enabling through-surface power transfer. Bavarian and Baden-Württemberg automotive clusters are standardizing on this architecture for cabin-integrated multi-device charging, though Ecodesign efficiency thresholds and standby power limits force firmware-level intelligence into transmitter designs.
- Radio Frequency:Delivers watt-level power through far-field electromagnetic propagation for healthcare implantables and industrial sensors where galvanic isolation eliminates infection risks.
- Capacitive Coupling:Transfers energy through electric fields between conductive plates rather than magnetic coils, finding niche deployment in sealed underwater equipment and explosive atmosphere environments where inductive heating risks are prohibitive.
Magnetic induction anchors the volume base while resonant induction gains share at the steepest rate.
End User:
Cost tier differentiation separates consumer-grade pad manufacturing from automotive-qualified systems requiring ASIL-compliant fault management and healthcare devices demanding biocompatibility certification.
- Consumer Electronics:Smartphone, wearable, and personal audio device charging dominates unit shipments through Polish assembly facilities serving EU retail channels, though USB-C conductive delivery above 100 watts retains cost advantage in price-sensitive tiers.
- Automotive:In-vehicle cabin charging and underbody static charging pads integrate into electric vehicle platforms across German and French OEM lineups, with the EU Green Deal's interoperability mandates forcing convergence around standardized coil architectures.
- Industrial Equipment:Automated guided vehicle fleets in Rhine-Ruhr industrial corridors and factory automation cells in Bavaria deploy high-wattage transmitter systems for contactless power delivery in continuous-operation environments.
- Healthcare Devices:Implantable cardiac monitors and transcutaneous sensors in Swiss and German medical device clusters utilize isolated power transfer to eliminate connector-related infection pathways.
Consumer electronics captures the widest unit base while automotive applications command the highest average system values.
Form Factor:
Volume concentration favors portable and desktop formats for consumer replenishment, whereas built-in and vehicle-integrated solutions require chassis-level engineering collaboration with extended qualification horizons.
- Portable Chargers:Battery-integrated pads and power banks enable mobility for field service technicians and traveling professionals, with demand clustering in German business travel corridors.
- Built-in Solutions:Furniture-embedded transmitters in hospitality and office environments across Benelux and Nordic markets integrate power delivery into desk surfaces and hotel room fixtures.
- Vehicle Charging Pads:Aftermarket and OEM-installed underbody assemblies for static charging enable fleet electrification without conductive cable handling, though legacy vehicle retrofit complexity voids manufacturer warranties.
- Desktop Stations:Multi-device charging hubs for simultaneous smartphone, wearable, and earbud replenishment anchor retail channel volume through consumer electronics distributors.
Desktop stations and portable chargers dominate shipment volumes while built-in solutions expand most quickly through commercial interior renovation cycles.
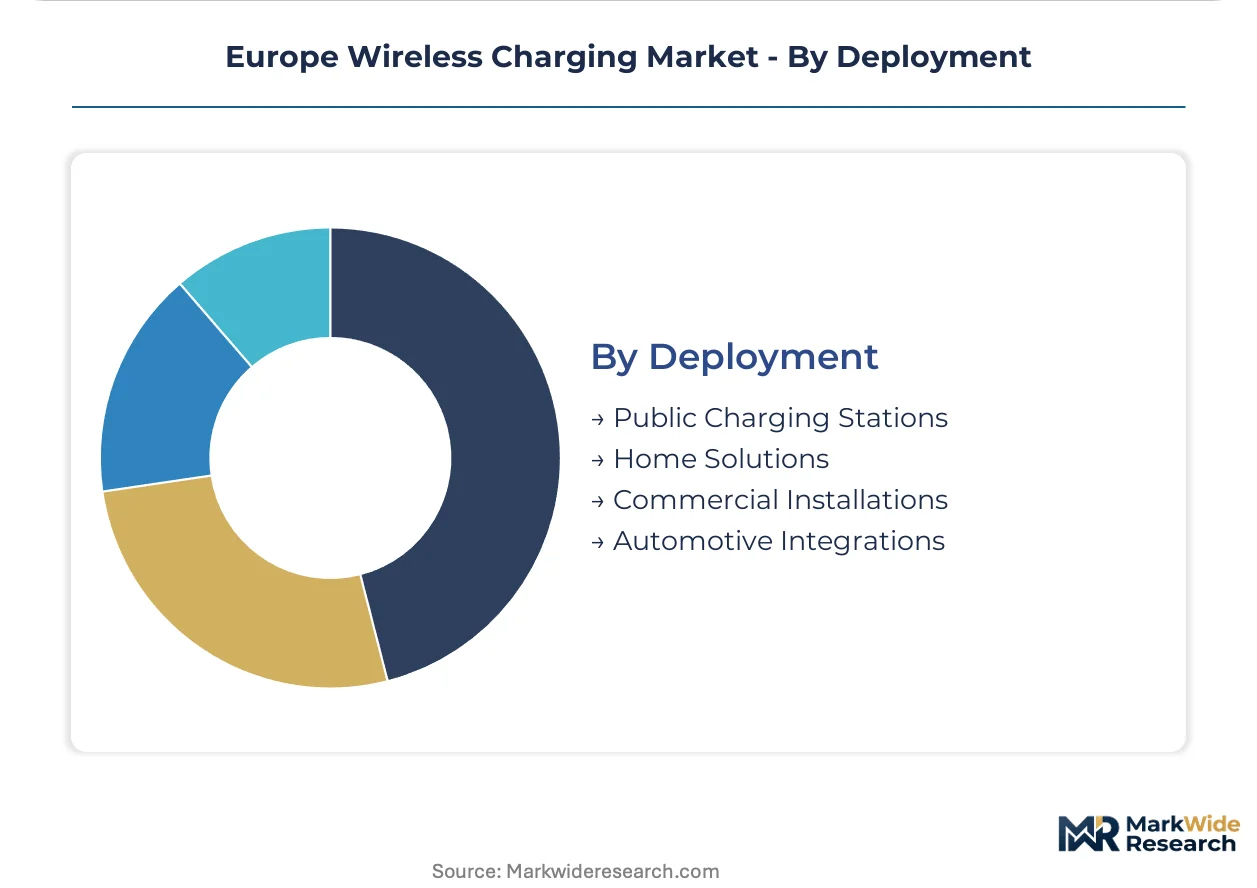
Deployment:
Customer type stratification separates individual residential procurement from corporate fleet managers consolidating around vertically integrated suppliers capable of delivering hardware and cloud monitoring through single-source contracts.
- Public Charging Stations:Street furniture and transit hub installations across German urban centers face electromagnetic compatibility scrutiny under RED 2014/53/EU with human exposure limits at 6.78 MHz frequencies.
- Home Solutions:Residential bedroom and kitchen counter deployments concentrate demand for consumer-grade pads through electronics retail channels in France and Italy.
- Commercial Installations:Corporate campus and hospitality deployments in Benelux and Nordic markets bundle infrastructure into facility management contracts with subscription-based service models.
- Automotive Integrations:Factory-installed cabin and underbody systems lock in supplier relationships before secondary markets mature, with German automotive leasing subsidiaries piloting subscription models where infrastructure costs bundle into monthly vehicle payments.
Home solutions and commercial installations split the current installed base while automotive integrations show the steepest forward trajectory tied to electric vehicle platform launches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal anchors regional standardization across member states, with KBA certification requirements and CE marking under RED 2014/53/EU shaping deployment timelines. National industrial clusters concentrate demand for automotive-qualified and consumer-grade systems.
Germany
Bavarian automotive OEMs and Baden-Württemberg factory automation fleets drive demand for high-wattage resonant systems. KBA enforces electromagnetic compatibility thresholds for underbody charging installations. The Rhine-Ruhr industrial belt hosts corporate fleet electrification programs bundling infrastructure into subscription models.
France
Paris-based automotive design centers integrate cabin-embedded charging pads into next-generation electric vehicle platforms. ANSM monitors human exposure limits at 6.78 MHz frequencies for medical-adjacent deployments. Île-de-France semiconductor research clusters advance coil geometry optimization.
Netherlands
Eindhoven anchors NXP Semiconductors' automotive-qualified transmitter design operations serving EU chipset demand. The national regulator enforces RED 2014/53/EU standby power limits on consumer electronics imports. Randstad logistics corridors distribute Polish-assembled charging hardware across Benelux retail channels.
Poland
Consumer-grade pad manufacturing clusters in Eastern European industrial zones supply tariff-advantaged export capacity into German retail networks. The national standards body aligns product certification with EU Ecodesign efficiency thresholds. Warsaw distribution hubs consolidate Samsung Electronics assembly output for EU-wide channel fulfillment.
Switzerland
Swissmedic certification requirements govern implantable medical device charging systems utilizing galvanic isolation. Zurich and Basel medical device clusters redesign coil geometries to maintain margin headroom against anticipated emission threshold revisions. Alpine precision manufacturing supports healthcare sensor integration at watt-level power delivery.
Europe Wireless Charging Market Competitive Landscape
Vertically integrated chipset vendors and specialized coil manufacturers split the market into distinct capability tiers. Consolidation pressure concentrates around automotive-qualified suppliers capable of ASIL-compliant fault management and cloud-based charge monitoring. European semiconductor design houses and Asian consumer electronics conglomerates represent the dominant archetypes. Competitive moves center on backward integration into ferrite core supply and strategic partnerships for resonant frequency IP licensing.
Within the semiconductor archetype, NXP Semiconductors and Qualcomm Inc. anchor European automotive-qualified transmitter portfolios through Eindhoven design centers and cross-licensing architectures. Samsung Electronics occupies a position in consumer-grade volume manufacturing through Polish assembly facilities. WÜRTH ELEKTRONIK GMBH & CO. KG exemplifies the specialized coil fabricator tier serving industrial automation corridors with high-wattage transmitter systems.
| Leading Market Players |
|---|
| Mouser Electronics Europe |
| Qualcomm Inc. |
| NXP Semiconductors |
| Analog Devices Inc. |
| Samsung Electronics |
| WÜRTH ELEKTRONIK GMBH & CO. KG |
| WiTricity Corporation |
| Plugless |
| ZenS B.V |
| Others |
Supply & Pricing Matrix
Eastern Polish industrial zones concentrate consumer-grade pad assembly capacity, creating tariff-advantaged export positioning that compresses margin pools for German retail channel competitors while amplifying pricing power for vertically integrated chipset vendors serving automotive-qualified systems.
Pricing Analysis
German retail channels command 15-25% premiums over Polish-sourced equivalents for identical Qi-certified pads, reflecting logistics cost layering and warranty localization rather than component differentiation. Pricing stratifies across automotive-qualified, industrial-grade, and consumer tiers, with ASIL-compliant fault management systems justifying substantial uplifts over bedroom-counter alternatives. Cost compression in consumer electronics intensifies as USB-C delivery above 100 watts retains cost advantage in price-sensitive smartphone segments. Fleet procurement managers show lowest price sensitivity, consolidating around single-source contracts bundling hardware and cloud monitoring.
Supply Chain Analysis
EU dual-use export controls and emerging technology restrictions limit gallium nitride power semiconductor flows from certain Asian refining corridors, constraining European automotive Tier 1 suppliers' access to high-frequency inverter components. Coil manufacturing draws from ferrite core processing concentrated in China and Vietnam, with rare-earth magnet refining exposing European fabricators to input volatility and tariff exposure. Single-source vulnerability concentrates in GaN wafer supply for Class E amplifier stages. Distribution runs through Randstad logistics corridors consolidating Polish assembly output for Benelux and German retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across technology standards and end-use certifications creates defendable niche positions for specialists, as EU Green Deal interoperability mandates force premature standardization that leaves residual demand for legacy protocol support and aftermarket retrofit solutions.
For Market Incumbents: Insulate automotive-qualified revenue streams through captive ferrite core supply arrangements and accelerated ASIL-D certification investment, while consolidating cloud-based charge monitoring capabilities to capture fleet subscription renewals. The threat of resonant frequency IP litigation from cross-licensing rivals demands defensive patent portfolio expansion.
For New Entrants and Emerging Players: Establish a beachhead in healthcare implantable charging systems where Swissmedic certification barriers deter consumer electronics conglomerates from vertical entry. Watt-level radio frequency delivery for transcutaneous sensors offers the most penetrable white space, with go-to-market traction through Zurich and Basel medical device clusters.
For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-annuity play because fleet electrification programs are converting capital expenditure into recurring subscription revenue. Acquisition targets should emphasize coil fabricators with electromagnetic-thermal co-design capabilities and existing KBA certification relationships. The signal to watch is German automotive leasing subsidiary pilot conversion rates from bundled infrastructure offerings.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Power Semiconductor Integration | Enables passive cooling architectures that eliminate liquid loop complexity from underbody transmitter housings. |
| Resonant Frequency IP Licensing | Resolves patent thickets spanning Qi and proprietary automotive protocols that erode mid-tier chipset vendor margins. |
| Healthcare Certification Pathway | Secures Swissmedic approval for implantable device charging systems utilizing galvanic isolation protocols. |
| Cloud Monitoring Platform Development | Captures fleet subscription revenue through single-source contracts bundling hardware and charge analytics. |
| Ecodesign Compliance Investment | Anticipates emerging EU standby power regulations favoring intelligent field-strength modulation controllers. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with automotive platform engineers, semiconductor procurement leads at Tier 1 suppliers, fleet electrification program managers, and medical device R&D directors; and secondary validation through KBA electromagnetic compatibility filings, CE marking databases under RED 2014/53/EU, EIA customs records for ferrite core trade flows, and automotive production registration data. Bottom-up transmitter coil shipment estimates triangulated against top-down electric vehicle platform launch schedules.
Forecast inputs considered technology adoption curves across magnetic induction, resonant induction, and radio frequency architectures; end-use concentration spanning consumer electronics, automotive, industrial automation, and healthcare devices; form factor evolution from portable pads to built-in furniture integration; and deployment model shifts from transactional hardware sales to subscription-based fleet services. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion across the projection horizon, with specific weighting for EU Green Deal standardization timelines and Ecodesign regulatory ratcheting.
Sensitivities concentrate around ferrite core supply disruptions, GaN semiconductor export restriction expansion, and EMC certification timeline extensions under RED 2014/53/EU draft revisions. Forecasts reflect documented assumptions regarding interoperability mandate enforcement and automotive OEM platform launch schedules. Material shifts in rare-earth magnet processing capacity allocation or 6.78 MHz human exposure threshold revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Global in-Building Wireless Market
Wireless Technologies
Industrial 5G Market
Wireless Technologies
Wi-Fi 7 Market
Wireless Technologies
Voice Over LTE (VOLTE) and Voice Over Wi-Fi Market
Wireless Technologies
Light Fidelity Market
Wireless Technologies
Global Wi-Fi 6 Market
Wireless Technologies
Global Bluetooth Beacon and Ibeacon Market
Wireless Technologies
P2P Antennas Market
Wireless Technologies
Europe Wireless Microphone Market
Wireless Technologies
Wireless Antenna Market
Wireless Technologies
Italy Fixed Wireless Access (FWA) Market
Wireless Technologies
Global Open Radio Access Network (Oran) Market
Wireless Technologies
Wireless Paging Systems Market
Wireless Technologies
Wireless Smart Home Market
Wireless Technologies
Base Transceiver Station (BTS) Market
Wireless Technologies
Voice Over Wifi Market