
 Fire Resistant Cable Materials Market | 2026-2036
Fire Resistant Cable Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Resistant Cable Materials Market Intelligence
The EU Green Deal's embodied carbon targets for construction materials is restructuring procurement criteria across European infrastructure projects. Prysmian S.p.A. leverages its integrated compounding capabilities to control mineral filler supply chains for high-temperature silicone and mica tapes. Nexans S.A. anchors its position through specialized R&D centers in France and Norway focused on ceramic-forming polymers. Sumitomo Electric Industries, Ltd. competes on manufacturing scale across Asia-Pacific utility tenders with vertically integrated halogen-free compound production.
Fire resistant cable materials comprise polymer compounds engineered with mineral fillers, ceramic precursors, and cross-linked matrices that maintain electrical continuity when exposed to temperatures exceeding 750°C for defined durations under IEC 60331 or BS 6387 test protocols. These formulations serve critical functions in power distribution, emergency circuits, and communication backbones where flame propagation must be suppressed and circuit integrity preserved during fire events. LSZH compounds command expanding share in transportation and high-occupancy construction segments where smoke toxicity regulations have displaced conventional PVC insulation. Multi-core armored constructions dominate industrial and utilities applications where mechanical protection and fire resistance must coexist, while single-core non-armored formats lead in commercial building power distribution due to installation flexibility and lower material intensity.
The EU Construction Products Regulation and CE marking requirements under the CPR framework mandate declared fire performance classes for cables installed in permanent buildings, directly shaping product development roadmaps and testing expenditures for compound suppliers. China's GB standards and India's BIS certification schemes impose comparable circuit integrity and flame spread thresholds, creating parallel compliance architectures that favor manufacturers with multi-jurisdictional testing capabilities. Stakeholders must monitor evolving harmonization between regional fire test protocols and the pace at which halogen-free formulations achieve cost parity with legacy PVC systems across price-sensitive construction markets.
Market Dynamics
EU Construction Products Regulation mandates under the CPR framework are restructuring compound development roadmaps, forcing suppliers to prioritize halogen-free formulations that maintain circuit integrity above 750°C while meeting stricter smoke toxicity thresholds across permanent building installations.
Growth Catalysts
- Urban infrastructure buildout:China's high-rise residential tower construction and India's smart city electrification programs are accelerating procurement of mineral-filled polymer compounds for emergency power circuits.
- REACH compliance migration:The EU's restriction on halogenated flame retardants is compelling cable manufacturers to reformulate with ceramic precursors and cross-linked silicone matrices.
- Data center resilience standards:Hyperscale facility operators are mandating multi-hour circuit integrity for critical communication backbones, expanding addressable demand for mica tape constructions.
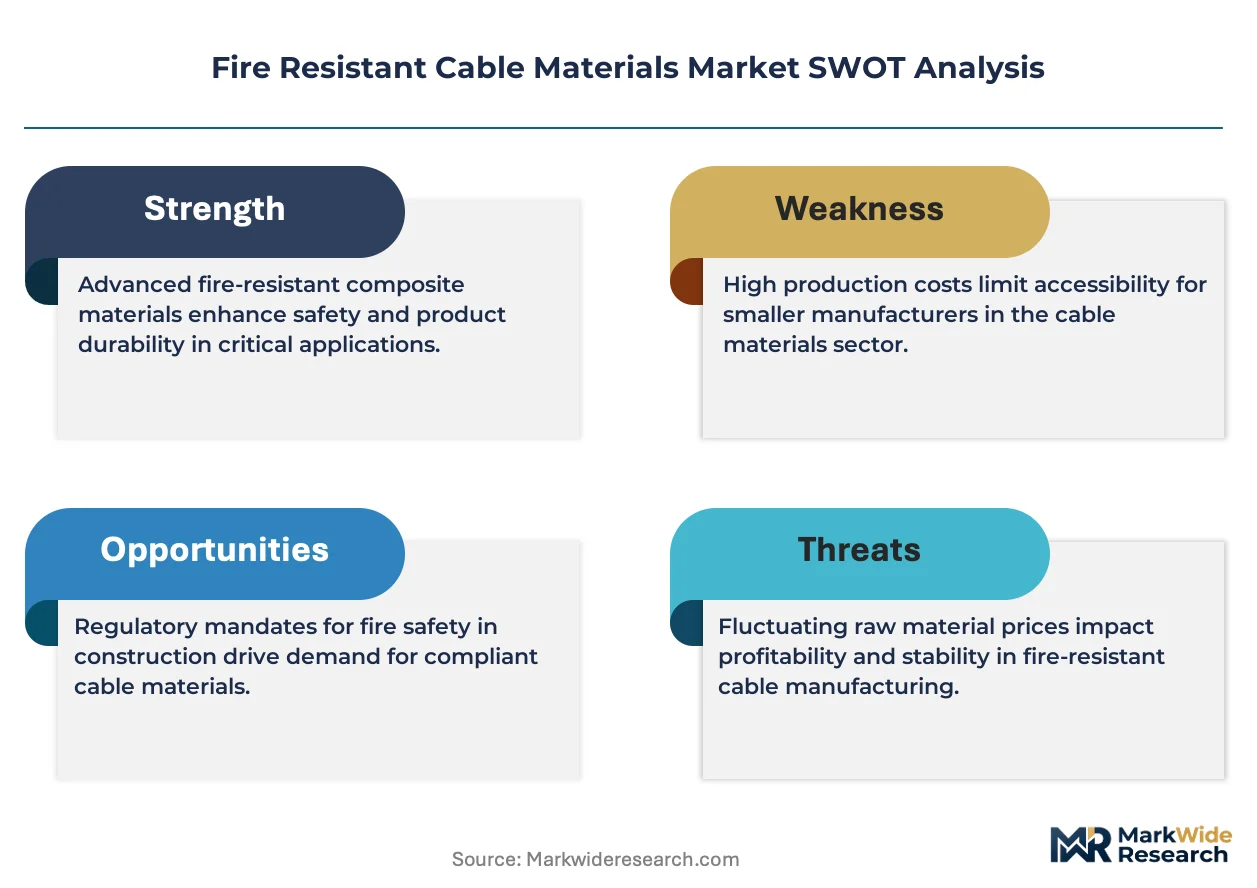
Market Restraints
- Mineral filler supply concentration:High-purity magnesium hydroxide and aluminum trihydrate processing capacity clusters in China, creating input vulnerability for European compounders.
- Technical performance ceiling:LSZH compounds still exhibit inferior mechanical flexibility versus PVC at sub-zero temperatures, limiting outdoor utility deployment in Nordic climates.
- Cost structure asymmetry:Halogen-free formulations command 15-40% raw material premiums over legacy PVC systems, compressing margins in price-sensitive Southeast Asian construction tenders.
Strategic Opportunities
- UAE and Saudi Arabia megaprojects:NEOM and Qiddiya developments are importing EU-equivalent fire performance standards, creating premium positioning for CPR-tested compound suppliers.
- Rail electrification corridors:India's Dedicated Freight Corridor and Indonesia's Java high-speed rail are specifying low-smoke zero-halogen cables for tunnel safety compliance.
- Ceramic-forming polymer convergence:Integration of silicone-based ceramifiable layers with conventional EPR insulation is enabling thinner-wall constructions without sacrificing fire resistance ratings.
Industry Challenges
- Multi-jurisdictional certification timelines:Securing parallel IEC 60331, BS 6387, and GB/T 19216 approvals extends product launch cycles by 18-24 months for new compound platforms.
- Compounding technician scarcity:Formulation expertise in high-temperature mineral dispersion and cross-linking chemistry concentrates among aging specialists in Germany and Japan.
- Legacy cable inventory displacement:Contractors face write-down pressure from PVC-insulated stockpiles as Singapore and UAE authorities retroactively tighten fire code enforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Resistant Cable Materials Market |
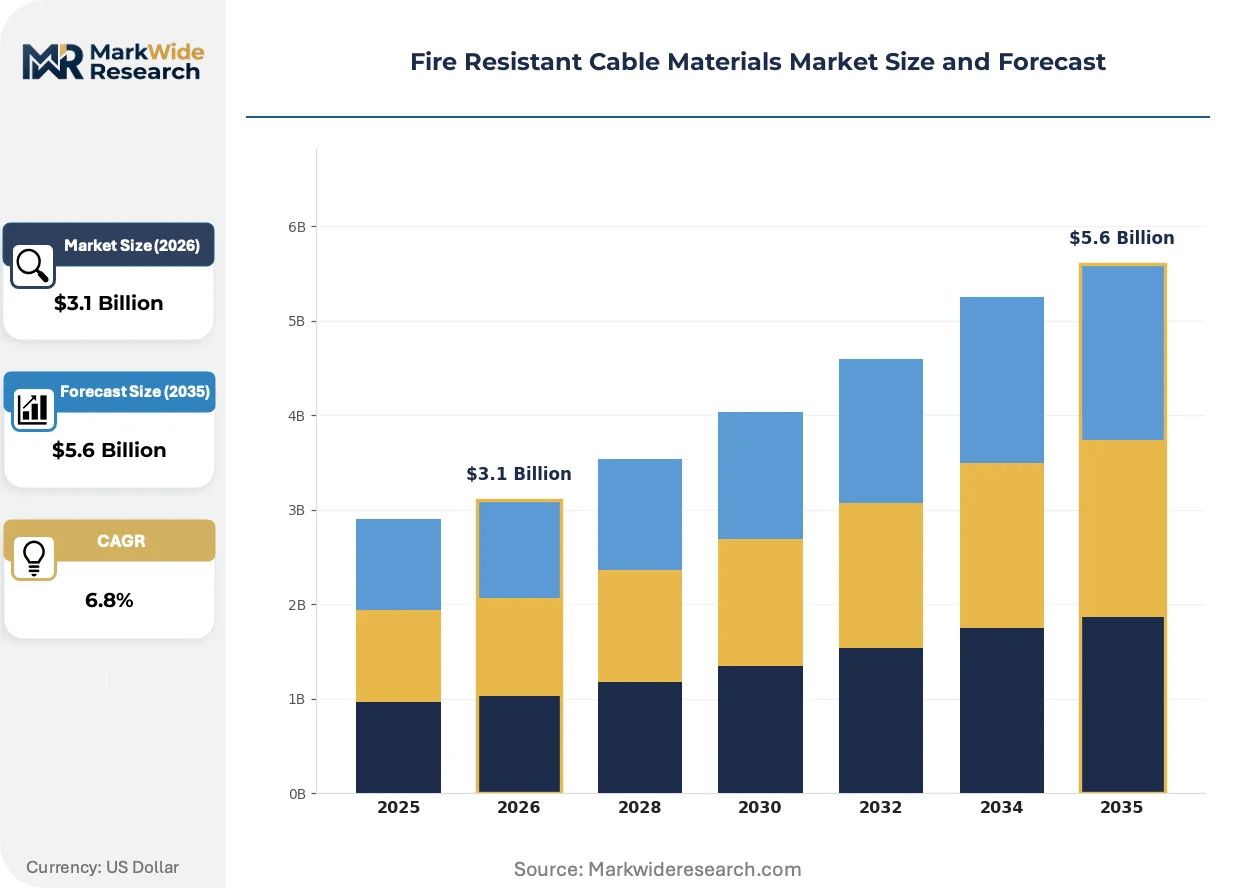
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.6 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: XLPE, PVC, LSZH, Halogen-Free Construction Type: Single-Core, Multi-Core, Armored, Non-Armored End User: Construction, Industrial, Transportation, Utilities Application: Power Distribution, Communication, Fire Alarm, Lighting |
| Companies Covered | LS Cable & System Ltd., Sumitomo Electric Industries, Ltd., Prysmian S.p.A., LEONI AG, Furukawa Electric Co., Ltd., Nexans S.A., Southwire Company, LLC, Polycab India Limited, NKT A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Resistant Cable Materials Market Strategic Shifts & Innovations
Formulation chemistry is pivoting from additive-based flame suppression toward intrinsic material architectures that ceramify under thermal stress, while procurement patterns favor suppliers with captive mineral filler processing and multi-standard testing capabilities.
Distributed ceramic-forming polymer systems integrate silicone-based precursors directly into ethylene-propylene rubber matrices rather than relying on external mica tape wrapping. Data center operators and high-occupancy building specifiers are adopting these constructions for installation flexibility in confined cable trays. This integration is decentralizing manufacturing value from specialized tape laminators toward integrated compounders with in-house ceramification expertise.
The EU Green Deal's embodied carbon targets for construction materials are extending to cable procurement criteria, pressuring suppliers to document cradle-to-gate emissions for mineral fillers and polymer feedstocks. Compounders with verified low-carbon magnesium hydroxide supply chains are securing preferred supplier status on French and German infrastructure tenders. LSZH cable categories are capturing share fastest in Nordic markets where national building codes now reference CPR fire performance classes explicitly.
Specification authority is migrating from general contractors toward fire safety engineering consultants who mandate third-party witnessed testing beyond minimum code requirements. This credential-driven selection is compressing the viable supplier base to manufacturers with permanent testing furnace infrastructure in multiple geographies. The shift is most pronounced in Singapore and UAE commercial developments where insurance underwriters influence material approval workflows.
Fire Resistant Cable Materials Market Segmentation
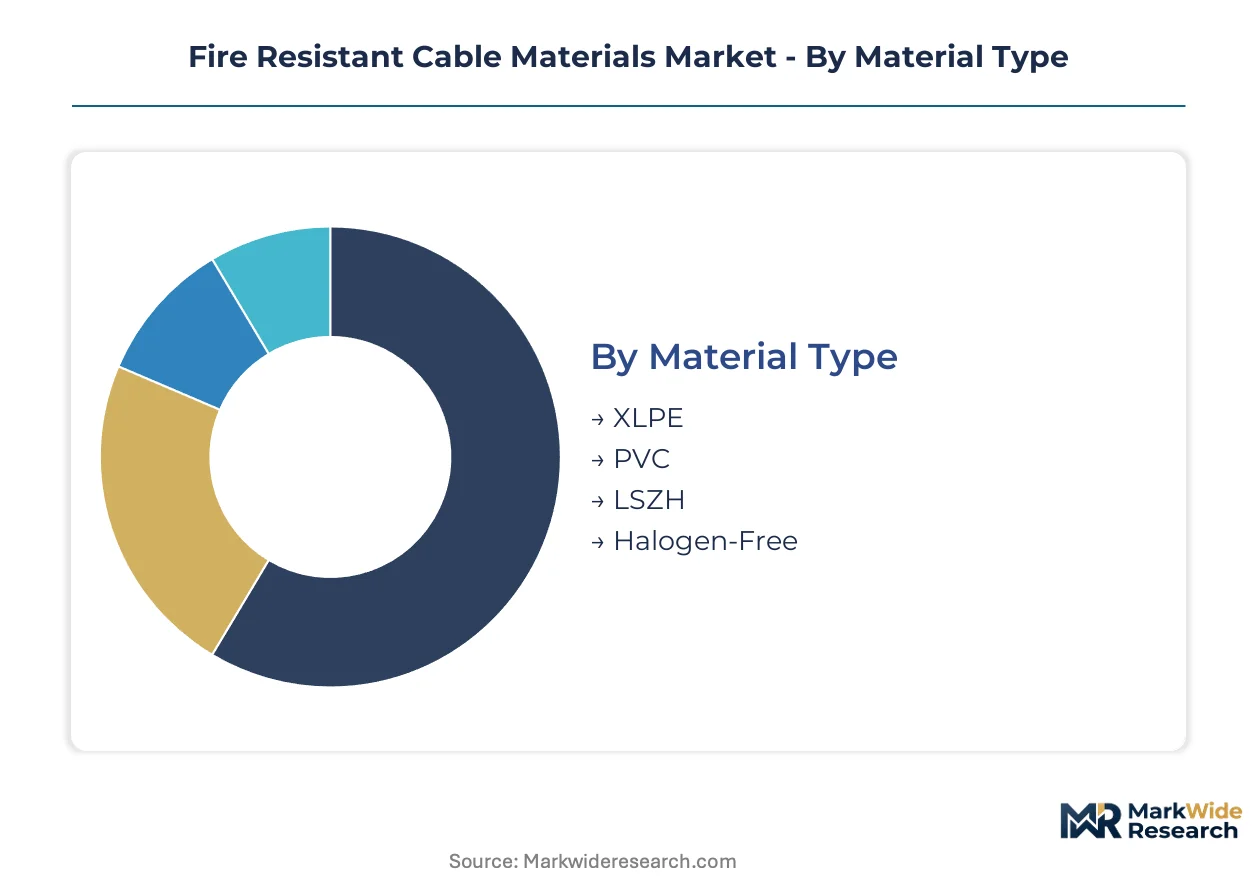
Fire resistant cable materials exhibit distinct performance profiles across formulation chemistry and physical construction. Procurement decisions hinge on balancing regulatory compliance thresholds against installation constraints and total system cost.
Material Type:
Standardization dominates commodity-grade specifications while custom compounding secures premium positioning in high-integrity installations.
- XLPE:Cross-linked polyethylene delivers superior thermal stability through three-dimensional molecular bonding, maintaining dielectric properties up to 250°C continuous operation. Demand concentrates in European utility grid modernization where ECHA REACH restrictions on halogenated additives have accelerated migration from PVC-insulated legacy stock. German distribution network operators specify XLPE for underground feeder circuits requiring 90-minute circuit integrity.
- LSZH:Low-smoke zero-halogen compounds incorporate aluminum trihydrate and magnesium hydroxide fillers that suppress smoke opacity below 60% during IEC 61034 testing. Procurement is accelerating across Singapore's Mass Rapid Transit expansion and Dubai's high-rise residential clusters where MOHAP fire safety directives mandate enhanced evacuation visibility. The formulation commands price premiums of 15-40% versus conventional insulation.
- PVC:Polyvinyl chloride remains entrenched in price-sensitive Southeast Asian construction tenders despite declining share in regulated European markets.
- Halogen-Free:Ceramic-forming polymer systems ceramify under thermal stress to maintain conductor protection without halogenated flame retardants.
Most installed capacity flows through XLPE compounds. Expansion is steepest in LSZH formulations.
Construction Type:
Mechanical protection requirements drive specification divergence between confined-space commercial installations and exposed industrial environments.
- Multi-Core:Bundled conductor configurations integrate power, control, and communication functions within unified sheathing systems. Demand is concentrating in India's smart city electrification programs and China's data center complexes where cable tray density constraints favor consolidated routing. BIS certification requirements for multi-core fire resistant cables have tightened compound selection criteria for suppliers targeting Indian infrastructure tenders.
- Armored:Steel wire or tape reinforcement provides mechanical protection against impact and rodent damage while maintaining fire resistance ratings. Procurement accelerates across Saudi Arabia's NEOM linear city development and Indonesian mining operations where buried cable runs face excavation hazards. The construction commands 25-35% material cost premiums over non-armored equivalents.
- Single-Core:Individual conductor format enables flexible routing in congested commercial building risers.
- Non-Armored:Lightweight sheathing reduces material intensity and installation labor for indoor power distribution.
Multi-core constructions dominate current procurement volumes. Armored formats are gaining share fastest in Middle Eastern megaprojects.
End User:
Regulatory stringency varies sharply across customer categories, with transportation and high-occupancy construction facing the most prescriptive material mandates.
- Construction:High-rise residential and commercial tower developments specify fire resistant cables for emergency power, fire alarm, and smoke extraction circuits. China's GB 31247 standard and UAE Civil Defense codes mandate 90-minute circuit integrity for vertical riser installations. Urban infrastructure buildout in Mumbai and Jakarta is accelerating demand for halogen-free compounds in mixed-use developments.
- Transportation:Rail electrification and tunnel safety requirements impose low-smoke toxicity thresholds that exclude conventional PVC insulation. India's Dedicated Freight Corridor and Indonesia's Java high-speed rail specify LSZH cables for tunnel sections exceeding 500 meters. European ECE R118 regulations for rolling stock further tighten smoke density limits.
- Industrial:Petrochemical and heavy manufacturing facilities prioritize mechanical durability alongside fire resistance.
- Utilities:Grid operators balance capital efficiency against regulatory compliance in transmission and distribution networks.
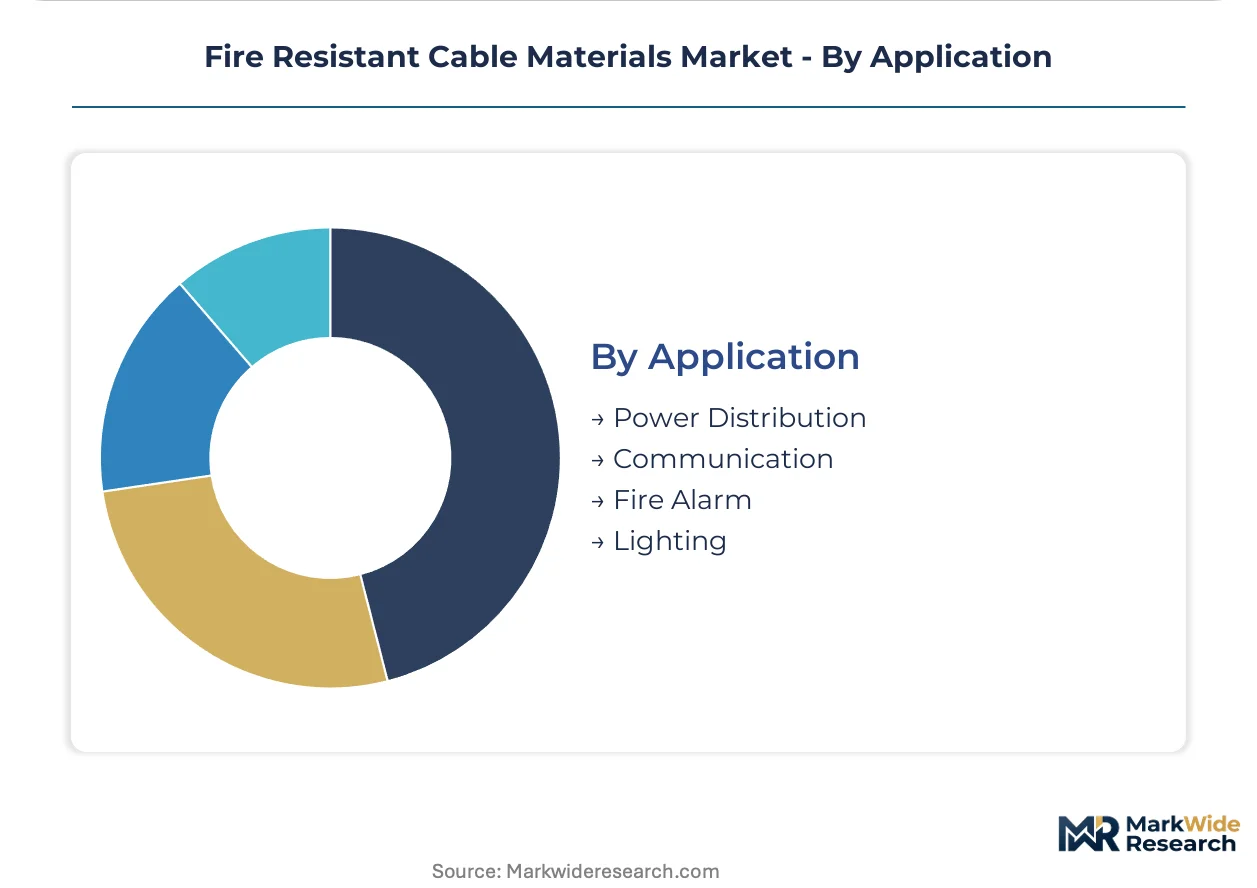
Construction sector procurement represents the largest volume channel. Transportation applications are expanding most quickly.
Application:
Mission-criticality determines specification grade, with communication backbones and fire safety circuits commanding premium material selections.
- Power Distribution:Primary electrical feed circuits require sustained current carrying capacity during fire events to maintain emergency systems operation. Data center operators in Frankfurt and Singapore specify mica tape or ceramifiable silicone constructions achieving 180-minute circuit integrity for main switchgear connections. Utility procurement in France and Germany increasingly references EU Green Deal embodied carbon criteria.
- Communication:Fiber optic and copper data cables must preserve signal transmission for emergency response coordination. Hyperscale facility operators mandate multi-hour integrity standards exceeding baseline building code requirements. Third-party witnessed testing under BS 6387 Category CWZ protocols has become a de facto procurement filter.
- Fire Alarm:Detection and notification circuits prioritize low-smoke emission to maintain visibility during evacuation.
- Lighting:Emergency illumination circuits balance cost efficiency against minimum compliance thresholds.
Power distribution applications absorb the majority of compound volume. Communication infrastructure represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fire resistant cable materials trace their industrial lineage to post-war European reconstruction, when German and British electrical manufacturers first standardized mineral-filled compounds for underground power networks. This technical foundation migrated to Asia-Pacific through Japanese industrial partnerships in the 1970s, then proliferated through Chinese state infrastructure programs from the 1990s onward.
China
Urban infrastructure buildout across high-rise residential towers and data center complexes drives procurement of halogen-free compounds. GB 31247 standards mandate 90-minute circuit integrity for vertical riser installations in permanent buildings. Shanghai and Beijing clusters concentrate domestic compound manufacturing capacity serving both local utilities and export markets.
Germany
Distribution network operators specify XLPE-insulated cables for underground feeder circuits requiring extended fire resistance. ECHA REACH restrictions on halogenated flame retardants accelerate reformulation toward ceramic precursors and cross-linked silicone matrices. Industrial compounders in North Rhine-Westphalia maintain captive mineral filler processing for high-temperature applications.
India
Smart city electrification programs and high-rise commercial developments accelerate demand for multi-core fire resistant constructions. BIS certification schemes impose circuit integrity thresholds comparable to European CPR frameworks. Mumbai and Delhi-NCR construction corridors specify LSZH compounds for mixed-use developments under tightened municipal fire codes.
United Arab Emirates
NEOM and Qiddiya megaprojects import EU-equivalent fire performance standards for premium infrastructure segments. MOHAP fire safety directives mandate enhanced smoke toxicity thresholds across high-occupancy buildings. Dubai's high-rise residential clusters represent concentrated demand for low-smoke zero-halogen cable procurement.
United States
Data center resilience standards from hyperscale facility operators mandate multi-hour circuit integrity for critical communication backbones. NFPA 70 National Electrical Code references fire resistance ratings for emergency power circuits in high-occupancy structures. Northern Virginia and Dallas-Fort Worth data center corridors concentrate specification authority among fire safety engineering consultants.
Fire Resistant Cable Materials Market Key Industry Players
Capital-heavy producers compete with asset-light designers across divergent capability requirements in mineral filler processing and multi-standard testing infrastructure. The vendor base stratifies between integrated compounders with captive raw material supply and specialized cable manufacturers sourcing formulations externally. Three archetypes dominate: European integrated compounders with in-house ceramification expertise, Asia-Pacific scale manufacturers serving utility tender markets, and regional specialists focused on certification-intensive premium segments. Competitive positioning hinges on backward integration into high-purity magnesium hydroxide supply chains and permanent testing furnace infrastructure across multiple jurisdictions.
Among European integrated producers, Prysmian S.p.A. and Nexans S.A. occupy positions anchored by captive mineral filler processing capabilities and multi-jurisdictional testing infrastructure. Sumitomo Electric Industries, Ltd. represents the Asia-Pacific scale archetype with vertically integrated halogen-free compound production serving regional utility procurement. These three exemplify the divergence between formulation-integrated and sourcing-dependent competitive models.
| Leading Market Players |
|---|
| LS Cable & System Ltd. |
| Sumitomo Electric Industries, Ltd. |
| Prysmian S.p.A. |
| LEONI AG |
| Furukawa Electric Co., Ltd. |
| Nexans S.A. |
| Southwire Company, LLC |
| Polycab India Limited |
| NKT A/S |
| Others |
Cost & Logistics Intelligence
EU Green Deal embodied carbon targets gate qualified supply and premium-tier pricing access, as compounders with verified low-carbon mineral filler chains secure preferred status on French and German infrastructure tenders while legacy PVC suppliers face margin compression from compliance exclusion.
Pricing Analysis
Three-tier pricing structure across premium CPR-tested, standard multi-jurisdictional, and economy domestic-grade levels stratifies procurement by certification depth and testing witnessed status. Price differentiation hinges on GB/T 19216 versus BS 6387 Category CWZ certification tier and captive magnesium hydroxide supply. Cost compression in economy-grade LSZH compounds intensifies because Chinese mineral filler exports face European carbon border scrutiny. Southeast Asian contractors exhibit highest price sensitivity; hyperscale data center operators show least.
Supply Chain Analysis
Compounding technician scarcity in North Rhine-Westphalia and aging specialist cohorts in Japan constrain formulation throughput for high-temperature mineral dispersion. Geographic supply concentration centers on China for high-purity magnesium hydroxide and aluminum trihydrate, Germany for XLPE compounding, and India for multi-core cable sheathing. Raw material dependencies draw from ceramic precursor silicones, cross-linking peroxides, and mica tape substrates. Single-source vulnerability in Chinese mineral processing creates input disruption risk. Distribution runs through authorized electrical distributors serving contractor specification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fire resistant cable materials constitute a late-cycle quality story as procurement authority migrates toward fire safety engineering consultants mandating third-party witnessed testing beyond minimum code thresholds.
For Market Incumbents: Acquire permanent multi-jurisdictional testing furnace infrastructure to defend specification authority against emerging asset-light designers. Consolidate backward integration into high-purity magnesium hydroxide supply chains before REACH restrictions deepen. Certification investment in parallel IEC 60331 and GB/T 19216 approvals extends product launch cycles but locks out competitors lacking capital intensity. For New Entrants and Emerging Players: Launch via direct specification relationships with fire safety engineering consultants in Singapore and UAE commercial developments. Target India's Dedicated Freight Corridor and Indonesia's Java high-speed rail for LSZH cable penetration where incumbent presence remains thin. White-space exists in ceramifiable silicone layer integration for thinner-wall constructions. For Investors and Strategic Acquirers: Roll-up economics work for regional specialists with captive testing infrastructure because multi-jurisdictional certification timelines create acquisition premiums for time-compressed market entry. Long-term viability centers on compounders with verified low-carbon supply chains and permanent furnace assets across three-plus geographies. Watch for EU carbon border adjustment mechanism implementation as inflection signal for mineral filler sourcing advantage.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Filler Processing | Captive magnesium hydroxide supply secures margin stability against Chinese export volatility under EU carbon border rules. |
| Multi-Jurisdictional Testing Infrastructure Expansion | Permanent IEC 60331 and BS 6387 furnace assets in France, Germany, and UAE compress competitor qualification timelines. |
| Ceramifiable Polymer R&D Partnership | Silicone-based precursor integration with EPR matrices enables thinner-wall constructions for data center cable tray density constraints. |
| Long-Term Supply Agreement with Hyperscale Data Center Operators | Multi-hour circuit integrity commitments from Frankfurt and Singapore facility operators anchor premium-tier volume visibility. |
| Green Certification Program for Embodied Carbon Documentation | Cradle-to-gate emissions verification aligns procurement criteria with EU Green Deal construction material mandates. |
Research Approach
Multiple input streams — compounder technical directors, cable manufacturer procurement leads, fire safety engineering consultants, and mineral filler processing plant managers — were reconciled against customs trade data, BIS certification registries, SEC 10-K filings from listed cable producers, and EU Construction Products Regulation technical documentation. Bottom-up volume estimates from individual compounder capacity and top-down demand calibration from construction permit data were triangulated to cross-validate market sizing.
Data-stream reconciliation across material type, construction format, end-user sector, and application criticality informed the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by regional regulatory enforcement intensity and infrastructure investment pipelines. Forecast inputs incorporated GB 31247 adoption curves in China, CPR fire class migration in Europe, and data center resilience standard tightening from hyperscale facility operators.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH restriction expansion or Chinese mineral export licensing disruption. Material deviation in EU carbon border adjustment mechanism implementation timelines or BIS certification scheme acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Global High Temperature Insulation Materials Market
Insulation Materials
UK Industrial Insulation Market
Insulation Materials
Thermal Tapes Market
Insulation Materials
Insulation Boards Market
Insulation Materials
Phase Change Thermal Interface Materials Market
Insulation Materials
Industrial Insulation Market
Insulation Materials
Recyclable Thermal Insulation Packs Market
Insulation Materials
High Temperature Insulation Market
Insulation Materials
Global Pipe Insulation Market
Insulation Materials
Global Insulation Materials Market
Insulation Materials
Phenolic Insulation Market
Insulation Materials
Flame-Retardant Foams and Insulation Market
Insulation Materials
Expanded Perlite Market
Insulation Materials
Dielectric Fluid Market
Insulation Materials
Thermal Conductive Polymer Materials Market
Insulation Materials
Global Industrial Insulators Market