
 Thermal Tapes Market | 2026-2036
Thermal Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Tapes Market Analytics
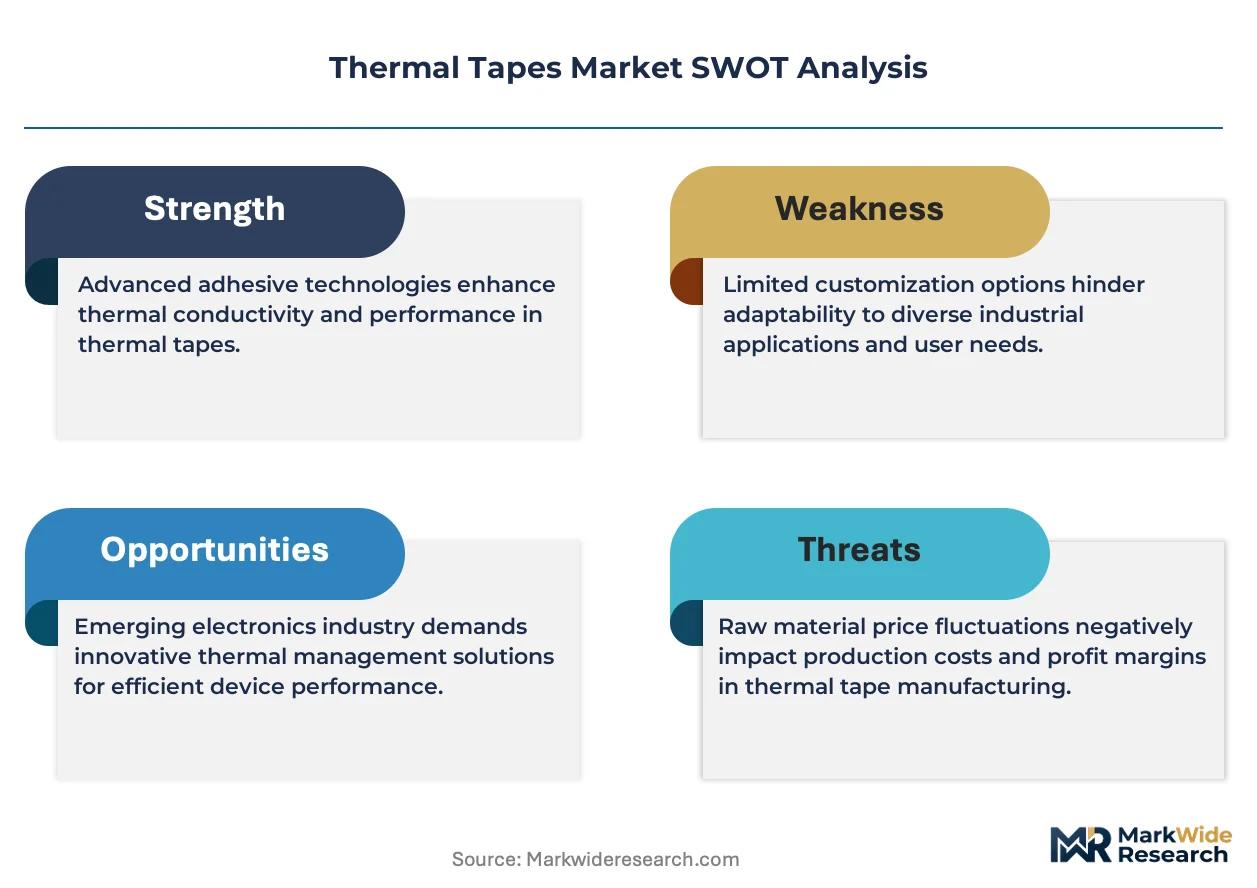
REACH compliance is pivoting European suppliers toward halogen-free adhesive formulations. 3M leverages its fluoropolymer expertise to sustain premium positioning in aerospace-grade tapes. Nitto Denko anchors Asian electronics supply chains through polyimide specialization. DuPont competes on material science depth with aromatic polymer backbones that tolerate sustained thermal cycling.
Thermal tapes are pressure-sensitive adhesive constructions, typically 25–250 micrometers thick, engineered to conduct or insulate heat while maintaining dielectric integrity between bonded substrates. They function as thermal interface materials in electronic assemblies, battery packs, and climate-control systems where mechanical fastening would compromise heat transfer or electrical isolation. Polyimide tapes command the highest margin pools due to their 180°C continuous service temperature and Kapton-class reliability in semiconductor fabrication. Silicone adhesives represent the fastest-expanding chemistry segment as electric vehicle battery module assembly shifts toward softer, conformable thermal pathways. Acrylic formulations remain the volume leader in HVAC and appliance applications where cost sensitivity outweighs extreme temperature demands.
The EPA regulates volatile organic compound emissions from adhesive manufacturing under Clean Air Act Title V, pushing U.S. producers toward solventless coating technologies. Japan's METI enforces JIS standards for electrical insulating materials that govern export eligibility for Japanese automotive OEMs. OEMs and tier-one contractors must monitor evolving F-Gas Regulation phase-down schedules in Europe, as hydrofluorocarbon restrictions cascade into refrigerant system designs that redefine tape specification requirements. Stakeholders should calibrate R&D portfolios against the divergence between regional chemical compliance regimes rather than assuming convergent global standards.
Market Dynamics
Electric vehicle battery pack architectures are driving thermal tape specification intensity upward as cell-to-pack designs eliminate module housings and demand conformable thermal interface materials that compensate for substrate warpage across larger bonding surfaces.
Growth Catalysts
- EU F-Gas Regulation phase-down:Refrigerant system redesigns across European HVAC OEMs are triggering specification updates for compressor and heat exchanger bonding tapes that tolerate new working fluid chemistries.
- Semiconductor fabrication scaling:Advanced packaging nodes below 7nm are expanding polyimide tape consumption for temporary wafer bonding and die-attach applications in Taiwan and South Korea fabs.
- Silicone adhesive chemistry:Softer, thermally conductive silicone formulations are displacing acrylics in EV battery module assembly where vibration damping and thermal cycling tolerance outweigh cost considerations.
Market Restraints
- Fluoropolymer feedstock concentration:PTFE and PVDF resin supply concentrates among a handful of chemical conglomerates, exposing tape converters to price volatility and allocation risk during semiconductor demand surges.
- REACH SVHC disclosure thresholds:European downstream users face documentation burdens for adhesive formulations containing candidate list substances, slowing new product qualification cycles.
- Phase-change materials:Melting-alloy thermal interface materials are capturing share in high-performance computing where thermal resistance targets below 0.1 K·cm²/W exceed tape capabilities.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor and component assembly are attracting tape distributors to establish local slitting and converting operations near Chennai and Bengaluru clusters.
- Solid-state battery commercialization:Oxide and sulfide electrolyte cell designs require dielectric thermal management solutions that tolerate higher operating voltages than incumbent liquid-electrolyte systems.
- Direct-to-fab distributor models:Tape converters are bypassing traditional electronics distributors to secure qualified supplier status with automotive tier-ones, capturing margin and specification influence.
Industry Challenges
- Adhesive formulator talent scarcity:Compound development expertise in silicone thermal conductivity optimization concentrates among aging specialists in Japan and Germany, constraining R&D velocity at mid-tier converters.
- Automotive PPAP timeline compression:EV platform launch cadences are squeezing tape qualification from 18-month cycles toward 9-month windows, straining validation laboratory capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Tapes Market |
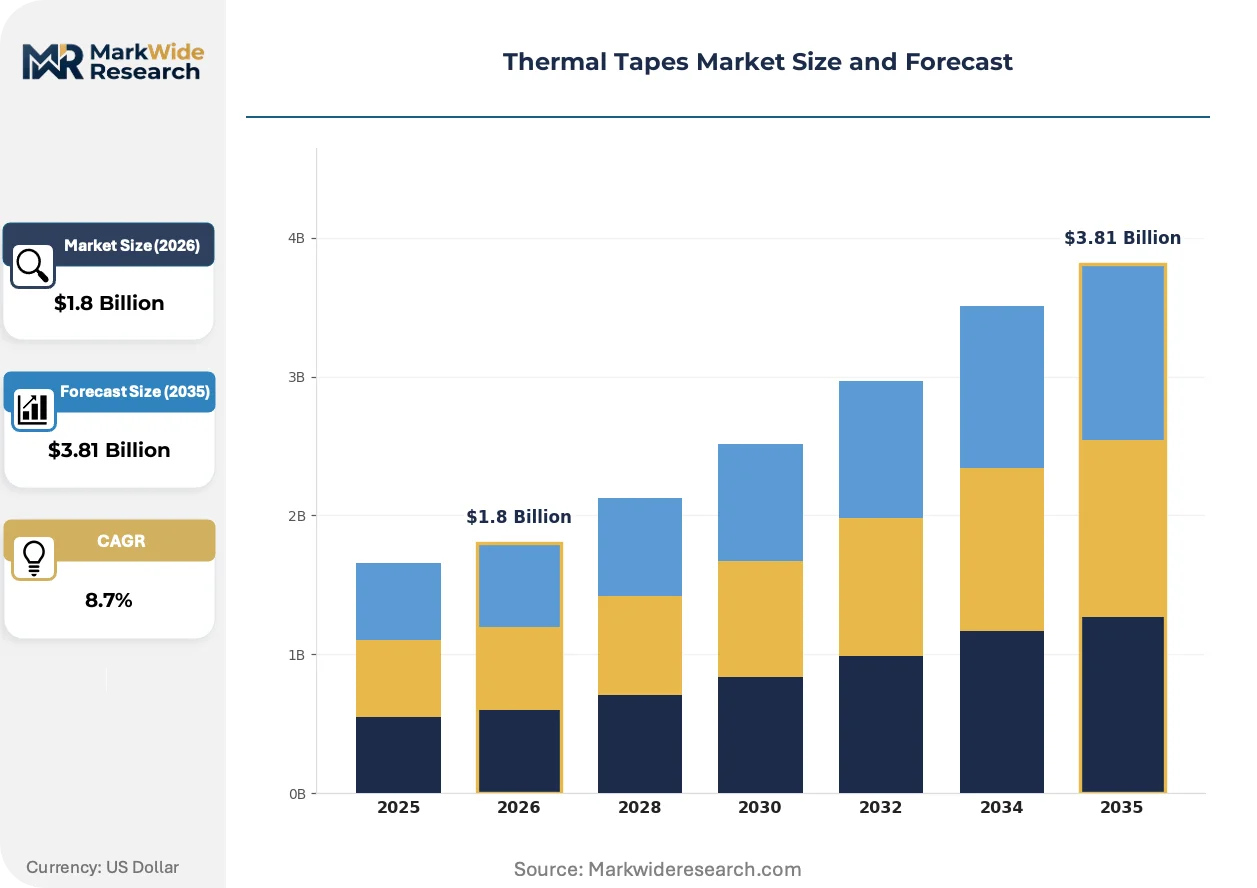
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double-Sided, Silicone, Acrylic, Polyimide Application: Electronics, Automotive, HVAC, Aerospace End User: Manufacturers, OEMs, Contractors, Distributors Size: Thin Film, Thick Film, Custom Size, Standard Roll |
| Companies Covered | 3M, DuPont, Nitto Denko Corporation, Avery Dennison Corporation, tesa SE, Scapa Industrial, Lintec Corporation, PI Advanced Materials Co., Ltd., Kaneka Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Tapes Market Evolving Landscape
Material science convergence with battery chemistry evolution is redefining thermal tape performance thresholds, while regulatory chemical restrictions and procurement centralization are reshaping competitive access routes.
Phase-change adhesive architectures are expanding into electric vehicle battery packs where gap-filling requirements between irregular cell surfaces and cooling plates exceed conventional solid tape conformability. Automotive thermal engineers specify these materials for modules above 400V where dielectric withstand and thermal impedance must coexist. The technology is expanding into second-life battery refurbishment operations where substrate condition variability demands adaptive bonding solutions.
EPA Clean Air Act Title V enforcement is accelerating solventless coating line investments among North American tape manufacturers, eliminating toluene and xylene emissions from acrylic adhesive deposition. Convertors face capital expenditure thresholds of several million dollars per production line to achieve compliance. Pressure-sensitive adhesive tape categories serving HVAC and appliance markets bear the steepest cost adjustment burden given thinner margin structures compared to electronics-grade specialty tapes.
Centralized procurement consortiums among German automotive OEMs are consolidating thermal interface material specifications across multiple platform programs, reducing qualified supplier lists from dozens to single-digit approved vendors. Tier-one battery pack assemblers must now navigate direct negotiation with OEM material engineering teams rather than decentralized plant-level purchasing. This concentration is most pronounced in Stuttgart and Munich headquarters operations where Volkswagen, BMW, and Mercedes-Benz coordinate thermal management strategy.
Thermal Tapes Market Segmentation
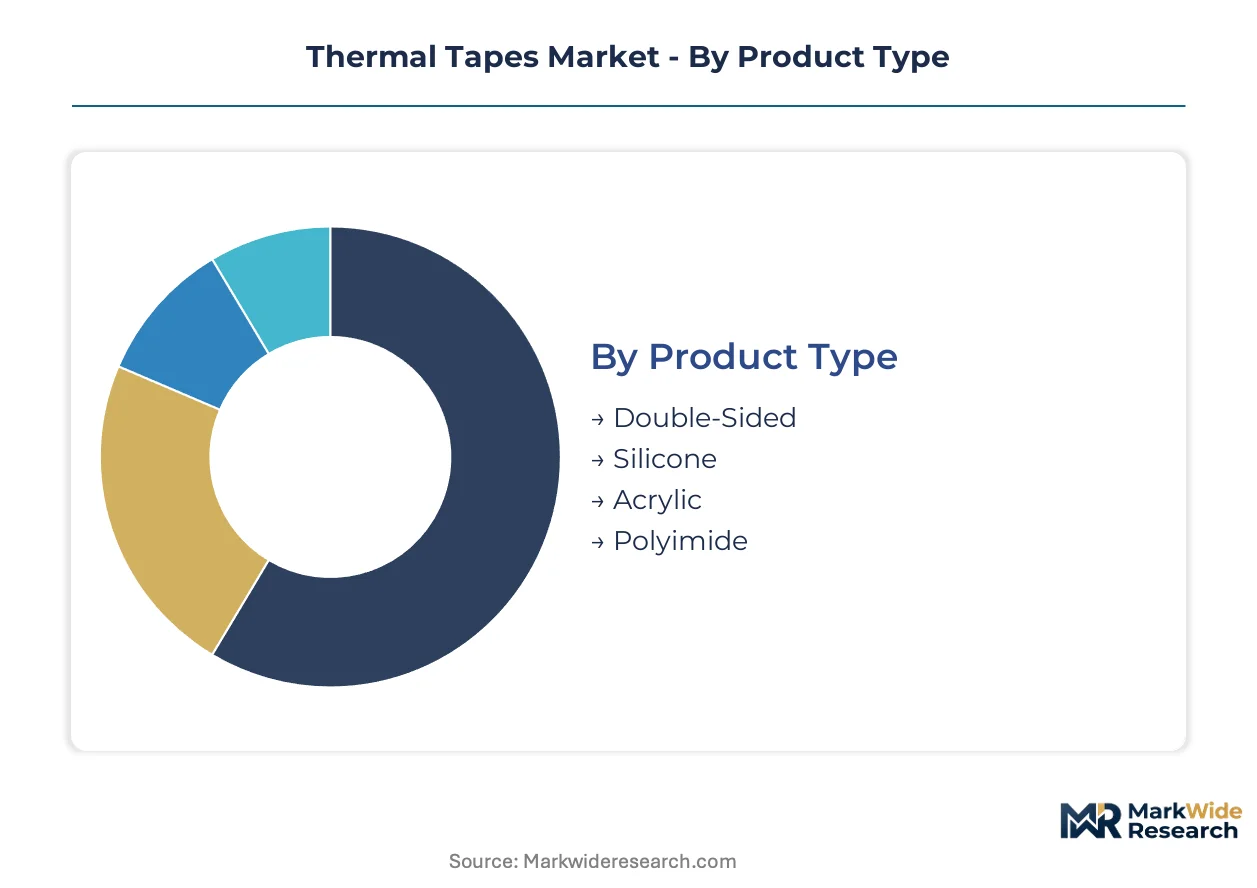
Thermal tape specification intensity varies dramatically across bonding geometries, adhesive chemistries, and end-use thermal cycling requirements. Procurement patterns diverge between electronics fabs demanding dielectric precision and automotive assemblers prioritizing conformability over extreme temperature tolerance.
Product Type:
Capital deployment for coating lines and adhesive compounding facilities concentrates most heavily in silicone and polyimide production, where solventless deposition and cleanroom slitting demand multimillion-dollar infrastructure commitments.
- Double-Sided:Pressure-sensitive adhesive layers on both faces enable substrate bonding without mechanical fasteners in battery module assembly. EV manufacturers in Germany and Japan specify these constructions for cell-to-pack architectures where thermal impedance and electrical isolation must coexist across irregular surfaces.
- Silicone:Soft, thermally conductive formulations displace acrylics in electric vehicle battery modules where vibration damping and thermal cycling tolerance outweigh cost considerations. METI-certified Japanese compounders anchor global supply for automotive OEM qualification programs.
- Acrylic:Cost-optimized chemistry dominates HVAC and appliance bonding applications where service temperatures remain below 120°C. EPA Title V compliance pressures North American converters toward solventless coating retrofits.
- Polyimide:Kapton-class backbones tolerate 180°C continuous exposure in semiconductor wafer processing. Taiwan and South Korea fabs consume premium grades for temporary bonding and die-attach operations.
Most installed capacity flows through acrylic formulations serving appliance and climate-control OEMs. Expansion is steepest in silicone adhesive production as battery pack architectures eliminate module housings and demand softer thermal interface materials.
Application:
Application selection dictates regulatory exposure, with aerospace and automotive segments subject to the most stringent qualification protocols and documentation burdens.
- Electronics:Semiconductor fabrication and consumer device assembly drive specification intensity for thin-film dielectric tapes. Advanced packaging nodes below 7nm expand polyimide consumption for temporary wafer bonding in Taiwan fabs.
- Automotive:Battery thermal management and power electronics cooling dominate procurement volumes as electric vehicle platforms multiply. EU F-Gas Regulation phase-downs force refrigerant system redesigns that cascade into compressor bonding tape specifications.
- HVAC:Heat exchanger and compressor sealing applications favor cost-efficient acrylic formulations. European OEMs face compressed qualification timelines as hydrofluorocarbon restrictions accelerate equipment redesign cycles.
- Aerospace:Fluoropolymer-backed tapes command premium positioning for engine compartment and avionics thermal shielding. 3M leverages decades of fluorochemical expertise to defend specification control with Boeing and Airbus tier-one suppliers.
Electronics applications absorb the highest unit margins per square meter. Automotive demand is climbing the fastest as cell-to-pack battery architectures multiply bonding surface area per vehicle.
End User:
Procurement centralization among German automotive OEMs has compressed qualified supplier lists from dozens to single-digit approved vendors, reshaping competitive access for each end-user category.
- Manufacturers:Electronics component and battery cell producers specify raw tape materials for in-house converting operations. Chennai and Bengaluru clusters attract distributor investments under India's PLI scheme incentives.
- OEMs:Volkswagen, BMW, and Mercedes-Benz headquarters operations coordinate thermal management strategy across platform programs. Direct negotiation with material engineering teams has replaced decentralized plant-level purchasing.
- Contractors:Tier-one battery pack assemblers and HVAC installation specialists demand slitting and die-cutting services with rapid turnaround. Validation laboratory capacity strains under nine-month PPAP timeline compression.
- Distributors:Traditional electronics distributors face bypass threats as tape converters secure direct qualified supplier status with automotive tier-ones. Margin capture and specification influence shift toward specialized converters.
OEM procurement concentration in Stuttgart and Munich anchors volume commitments. Contractor demand is expanding most quickly as battery pack assembly outsourcing accelerates.
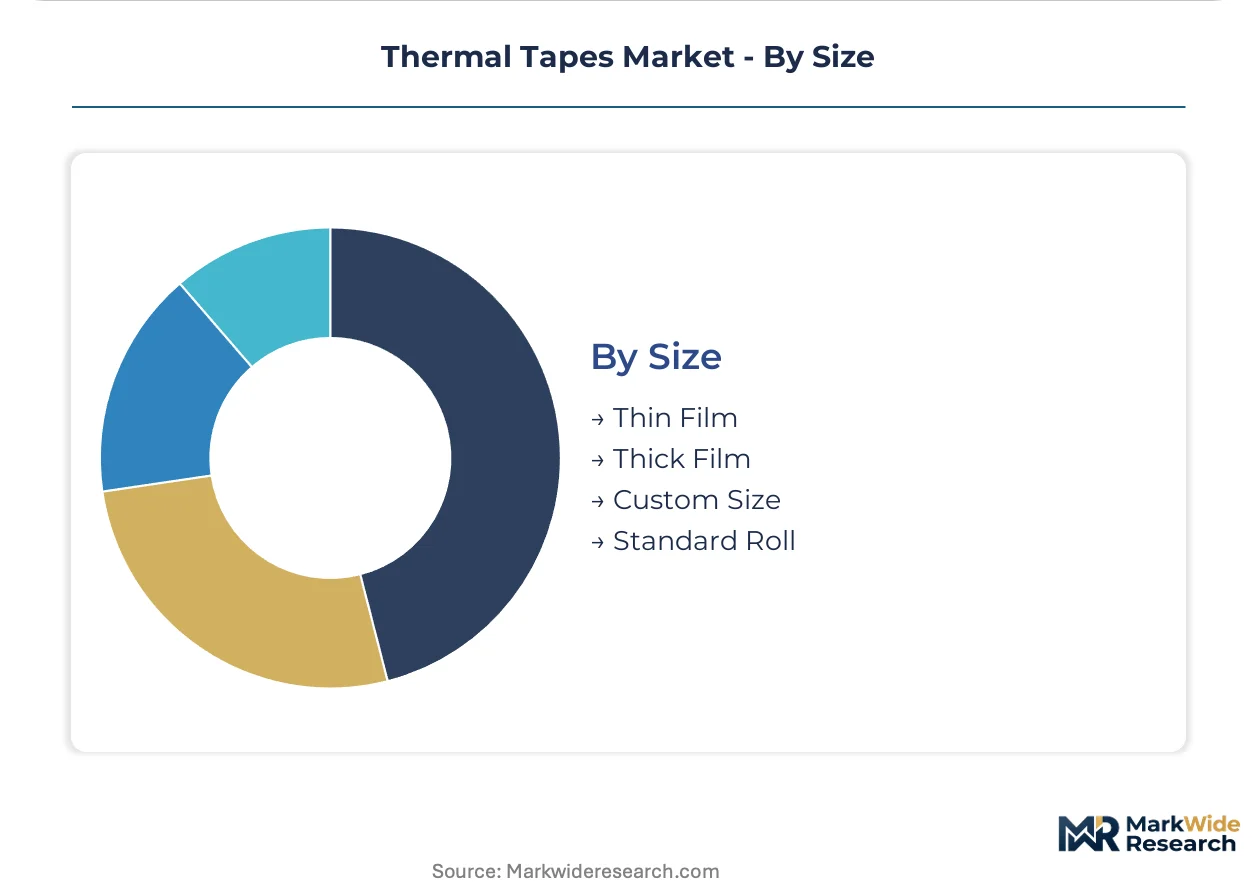
Size:
Thickness and format selection determines capital equipment requirements, with thin-film precision slitting and custom die-cutting demanding specialized infrastructure.
- Thin Film:25–75 micrometer constructions serve semiconductor temporary bonding and compact electronics thermal management. Cleanroom slitting lines require substantial capital investment for particle control.
- Thick Film:150–250 micrometer tapes provide gap-filling compliance in battery modules with substrate warpage. Automotive specifications increasingly favor these constructions for cell-to-pack bonding.
- Custom Size:Die-cut shapes and kit configurations reduce assembly labor for tier-one battery pack contractors. Converters invest in rotary and laser cutting capacity to capture specification influence.
- Standard Roll:Bulk formats serve HVAC and appliance manufacturers with high-volume, low-mix procurement patterns. Cost sensitivity in these segments resists premium adhesive chemistries.
Standard roll formats move the highest absolute volume through climate-control and appliance supply chains. Custom size configurations are gaining share fastest as battery pack assembly complexity increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thermal tape manufacturing scaled from post-war Japanese electronics fabrication and German automotive supplier clusters, with contemporary demand concentrating where semiconductor and battery assembly infrastructure has concentrated over three decades.
United States
Electric vehicle battery plants in Michigan and Tennessee drive silicone adhesive procurement for cell-to-pack thermal management. EPA Clean Air Act Title V enforcement accelerates solventless coating line investments among domestic converters. Austin and Phoenix semiconductor fabs expand polyimide tape consumption for advanced packaging nodes.
Germany
Automotive OEM headquarters in Stuttgart and Munich centralize thermal interface material specifications across platform programs. EU F-Gas Regulation phase-down forces refrigerant system redesigns that cascade into compressor bonding tape requirements. Bavarian industrial corridors anchor European distribution infrastructure for electronics-grade specialty tapes.
Japan
Semiconductor fabrication and automotive electronics sustain premium polyimide and silicone formulation demand. METI enforces JIS standards for electrical insulating materials that govern export eligibility for domestic OEMs. Osaka and Nagoya industrial basins concentrate adhesive compounding expertise among established chemical specialists.
South Korea
Memory and logic foundries in Suwon and Pyeongtaek expand temporary wafer bonding tape consumption below 7nm packaging nodes. Domestic battery cell producers specify conformable thermal interface materials for cylindrical and prismatic cell formats. Government semiconductor support programs attract tape converter investments for local slitting operations.
China
Domestic electric vehicle production scales thermal tape specification intensity across battery module and pack assembly lines. MIIT governs standards for electronic component materials that shape procurement requirements for both domestic and export-oriented manufacturers. Yangtze River Delta and Pearl River Delta clusters concentrate converting capacity near consumer electronics and automotive tier-one suppliers.
Thermal Tapes Market Competitive Landscape
The competitive structure tilts toward diversified materials conglomerates with fluoropolymer and aromatic polymer expertise. Tier-one automotive qualification programs favor suppliers with decade-long validation histories and captive resin supply arrangements. Strategic archetypes include vertically integrated chemical majors, specialized adhesive compounders, and regional converting specialists. Capacity expansion and direct-to-OEM distributor bypass represent the dominant competitive moves reshaping channel access.
Among diversified materials conglomerates, 3M and DuPont exemplify archetypes defending specification control through fluorochemical and aromatic polymer expertise respectively. Nitto Denko Corporation occupies a position within the specialized adhesive compounder tier, anchoring Asian electronics supply chains through polyimide formulation depth. These three entities represent the competitive anchors around which mid-tier converters and regional specialists coordinate qualification and distribution strategies.
| Leading Market Players |
|---|
| 3M |
| DuPont |
| Nitto Denko Corporation |
| Avery Dennison Corporation |
| tesa SE |
| Scapa Industrial |
| Lintec Corporation |
| PI Advanced Materials Co., Ltd. |
| Kaneka Corporation |
| Others |
Value Network & Pricing Analysis
Solventless coating line retrofits across North American converters simultaneously inflate capital expenditure thresholds and consolidate production among well-capitalized players capable of absorbing multimillion-dollar compliance costs. This technological transition compresses margin structures for acrylic formulations serving HVAC markets while widening spreads for electronics-grade specialty tapes where dielectric precision commands premium positioning.
Pricing Analysis
Raw tape supply and slitting services operate as unbundled procurement categories, with OEMs increasingly separating material specification from converting operations. Three-tier pricing structure across premium, standard, and economy levels separates aerospace fluoropolymer grades from automotive silicone formulations and appliance acrylics. Price differentiation centers on certification tier and volume scale, with JIS-certified Japanese compounders extracting substantial premiums over uncertified alternatives. Cost compression in standard-grade acrylics is intensifying because EPA Title V compliance burdens concentrate among thinner-margin segments. HVAC and appliance manufacturers exhibit highest price sensitivity, while semiconductor fabs demonstrate least elasticity given qualification lock-in risks.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale battery pack assembler demand, bypassing traditional electronics distributors that historically intermediated tape procurement. PTFE and PVDF resin supply concentrates in the United States, Germany, and Japan, drawing from fluorochemical feedstocks controlled by a handful of chemical conglomerates. Adhesive formulation expertise rests on aromatic polymer backbones from DuPont and silicone compounding know-how from Japanese specialists. Single-source vulnerability around fluoropolymer resins exposes converters to allocation risk during semiconductor demand surges. Distribution runs through qualified supplier programs governed by automotive OEM material engineering teams rather than decentralized plant-level purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in silicone adhesive segments where EV battery thermal management specifications outpace cost-down pressures, and in polyimide grades where semiconductor fabrication scaling sustains premium pricing power.
For Market Incumbents: Anchor specification control through captive resin supply arrangements with fluoropolymer producers, insulating against allocation risk during demand surges. Deepen JIS and REACH certification portfolios to defend qualified supplier status against mid-tier converters attempting direct-to-OEM bypass. Prioritize capacity addition in South Korea and Taiwan to capture advanced packaging node demand below 7nm.
For New Entrants and Emerging Players: Begin with India's PLI scheme corridors near Chennai and Bengaluru, where semiconductor assembly incentives attract tape distribution investments without incumbent qualification legacy requirements. Target solid-state battery thermal management as the most penetrable application, where oxide and sulfide electrolyte designs demand dielectric solutions absent established supplier relationships. Pursue direct qualification with automotive tier-ones rather than distributor channel dependence.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier converters with solventless coating infrastructure already deployed, offering EPA compliance arbitrage against competitors facing retrofit capital calls. Long-term viability favors adhesive compounders with demonstrated automotive PPAP completion histories and aging specialist talent retention. Watch silicone thermal conductivity optimization patent filings as inflection indicator for R&D velocity shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Resin Supply | Captive PTFE sourcing from Chemours or Daikin insulates converters against semiconductor demand surge allocation risk. |
| Solventless Coating Line Deployment | EPA Title V compliance in Michigan and Tennessee secures continued access to automotive OEM procurement programs. |
| JIS Certification Investment | METI standard compliance unlocks export eligibility for Japanese automotive OEM thermal management specifications. |
| Direct-to-OEM Distribution Bypass | Qualified supplier status with Stuttgart and Munich headquarters operations captures margin from electronics distributors. |
| Solid-State Battery Thermal Interface Development | Oxide and sulfide electrolyte cell designs require dielectric tapes tolerating higher operating voltages than incumbent systems. |
Research Methodology
Coverage spans the United States, Germany, Japan, South Korea, and China, with primary inputs from each market. Primary interviews with adhesive compounders, automotive OEM material engineers, semiconductor fab procurement managers, and tape converting operators combined with secondary validation from EPA enforcement records, METI JIS standard documentation, EU F-Gas Regulation phase-down schedules, and SEC filings from diversified materials conglomerates. Bottom-up and top-down triangulation cross-checked installed coating capacity against end-use demand segmentation.
Rate-of-change decomposition separated volume growth from price trajectory across adhesive chemistry tiers and application segments. The analytical framework modeled product type, application, end user, and regional production hub dimensions throughout the forecast period. CAGRs derived from regression analysis against electric vehicle production forecasts and semiconductor wafer start projections, with cross-validation against historical tape consumption intensity per battery pack and per square meter of fab cleanroom space.
Several conditions sit outside the modeled scope, including potential REACH SVHC list expansions that could disqualify incumbent formulations, and breakthrough phase-change material thermal resistance achievements below tape capabilities. Forecasts reflect assumptions around continued F-Gas Regulation enforcement and automotive platform electrification commitments. Periodic stress-testing of base assumptions against regulatory acceleration or battery chemistry discontinuities is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Insulation Products Market
Insulation Materials
Global Fire Protection Materials Market
Insulation Materials
OEM Insulation Market
Insulation Materials
North America Extruded Polystyrene (XPS) Insulation Material Market
Insulation Materials
North America Industrial Insulation Market
Insulation Materials
Extruded Polystyrene (XPS) Insulation Material Market
Insulation Materials
Insulation Boards Market
Insulation Materials
Asia-Pacific Insulation Materials Market
Insulation Materials
Polyisocyanurate Insulation Market
Insulation Materials
Seismic Reinforcement Materials Market
Insulation Materials
Global High-Performance Insulation Market
Insulation Materials
Global Calcium Silicate Insulation Market
Insulation Materials
North America Expanded Polypropylene Foam Market
Insulation Materials
North America Flexible Foam Market
Insulation Materials
Microencapsulated Paraffin Phase Change Materials Market
Insulation Materials
Low Smoke Halogen Free Flame Retardant Polypropylene (PP) Market