
 Wind Power Bolts Market | 2026-2036
Wind Power Bolts Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Power Bolts Market Insights
Offshore wind farm operators are unwinding procurement concentration from onshore contractors as monopile and floating foundation projects multiply. Dokka Fasteners leverages its Nordic manufacturing base to supply corrosion-resistant bolting systems for North Sea installations. Stanley Black & Decker sustains broad distribution reach across multiple turbine OEM supply chains. Finework (HuNan) New Energy Technology anchors production near China's expanding offshore wind belt in Jiangsu and Guangdong provinces.
Wind power bolts are high-tensile threaded fasteners engineered to secure structural joints in wind turbine towers, nacelles, and substructures, typically manufactured to property classes 8.8 through 12.9 with hot-dip galvanizing or zinc-flake coating for corrosion resistance exceeding 1,000 hours in salt spray testing. Carbon steel dominates material selection for tower flanges and base plates where cost efficiency governs, while alloy steel commands premium positioning in drivetrain and blade root connections subject to cyclic fatigue loading. Application segmentation reveals turbine assembly as the most mature demand pool, with foundation installation representing the fastest-expanding segment as offshore water depths increase and gravity-based structures require specialized anchor bolt arrays.
FERC renewable energy credit frameworks in the United States, EU Green Deal industrial policy under REACH chemical compliance, and China's GB standards enforced by SAMR collectively tighten material traceability and mechanical testing protocols for structural fasteners in renewable energy applications. The EU AI Act and CSRD disclosure requirements are extending supply chain documentation obligations to tier-two bolt manufacturers serving European wind OEMs. Stakeholders must monitor evolving certification thresholds for hydrogen embrittlement resistance as turbine manufacturers qualify next-generation bolt coatings for 25-year offshore design lives.
Market Dynamics
Offshore turbine scaling toward 15MW+ capacities is forcing bolt specification upgrades across foundation, tower, and drivetrain assemblies. Monopile and floating substructure proliferation is redirecting procurement volumes from onshore contractors to specialized marine fastener suppliers with North Sea and coastal China manufacturing footprints.
Growth Catalysts
- EU Green Deal industrial policy:REACH chemical compliance and extended producer responsibility mandates are accelerating certified fastener replacement cycles in European wind OEM supply chains.
- Floating foundation proliferation:Tension-leg and semi-submersible platforms require specialized anchor bolt arrays with 25-year corrosion resistance ratings, expanding addressable hardware scope.
- China's dual carbon goals:Jiangsu and Guangdong provincial governments are fast-tracking offshore wind auctions that specify GB-standard high-tensile fasteners for turbine assembly.
Market Restraints
- Alloy steel price volatility:Nickel and molybdenum input costs swing 15-40% quarterly, compressing margin predictability for 12.9-grade bolt manufacturers serving drivetrain applications.
- Coastal China supply concentration:Over 60% of hot-dip galvanizing capacity clusters within 200km of Ningbo-Zhoushan port, creating single-point vulnerability for corrosion-coated bolt supply.
- Hydrogen embrittlement susceptibility:High-strength steels above 10.9 property class face performance degradation in subsea cathodic protection environments, limiting coating qualification pathways.
Strategic Opportunities
- US Gulf Coast offshore belt:Louisiana and Texas lease auctions under FERC renewable credit frameworks are activating demand for hurricane-rated foundation bolts with enhanced fatigue performance.
- Blade root connection upgrade cycles:Retrofit demand from 2-3MW turbine fleets reaching mid-life service intervals creates aftermarket pull for improved preload retention systems.
- Digital thread integration:RFID-embedded fasteners with full material traceability align with EU AI Act supply chain documentation requirements for tier-two component suppliers.
Industry Challenges
- Multiaxial fatigue testing capacity:Specialized laboratories capable of simulating 25-year offshore loading spectra are concentrated in Germany and Norway, creating certification bottlenecks for new market entrants.
- Coating qualification timelines:Salt spray testing protocols exceeding 1,000 hours extend product development cycles 18-24 months, delaying revenue recognition for next-generation corrosion-resistant formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Power Bolts Market |
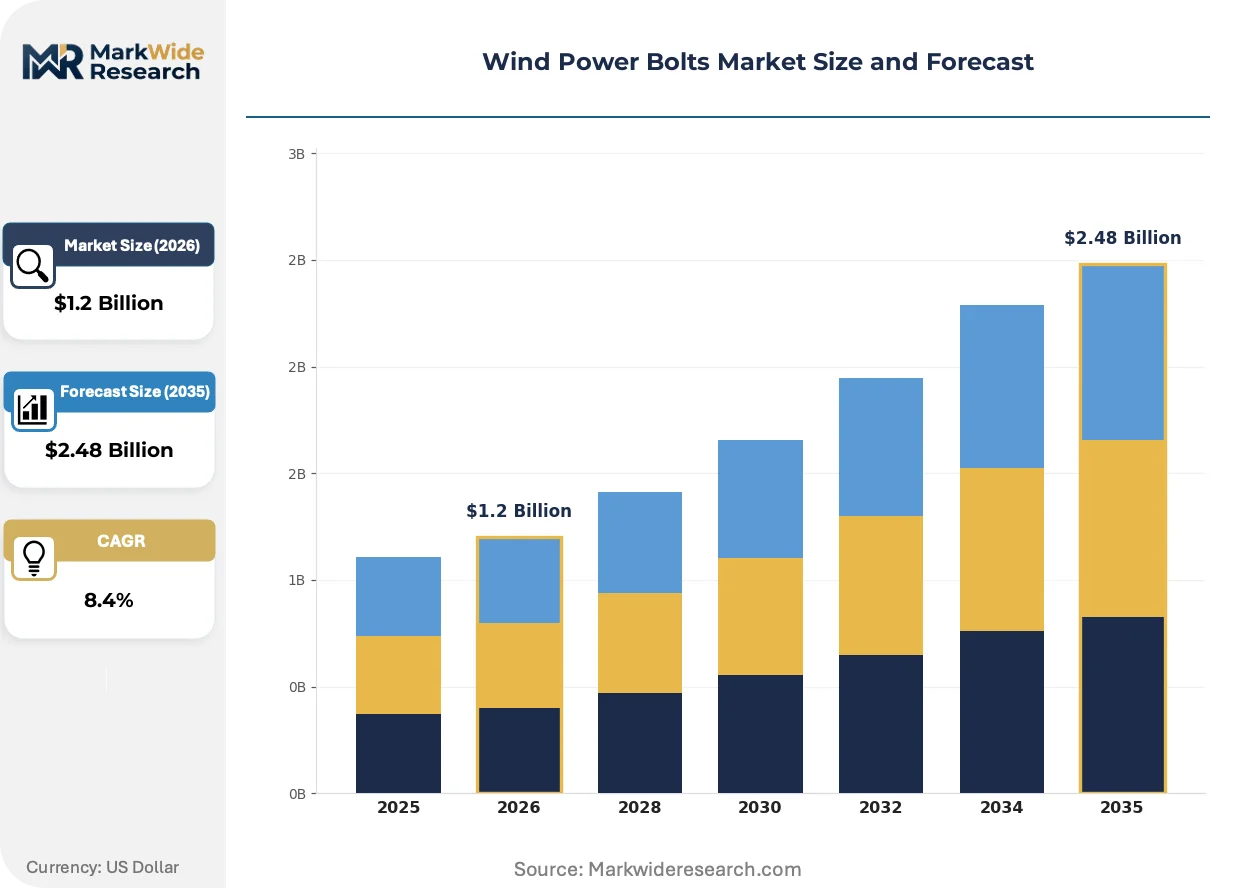
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Strength Bolts, Tension Control Bolts, Anchor Bolts, Screws Material: Carbon Steel, Stainless Steel, Alloy Steel, Aluminum Application: Turbine Assembly, Tower Construction, Foundation Installation, Maintenance End User: OEM Manufacturers, Wind Farm Operators, Contractors, Maintenance Providers |
| Companies Covered | Dokka Fasteners, Stanley Black & Decker, Dyson Corp., Finework (HuNan) New Energy Technology, ITH Bolting Technology, Mudge Fasteners, Beck Industries, August Friedberg GmbH, Ningbo Ningli High-Strength Fastener, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Power Bolts Market Trends and Innovations
Material science advances and regulatory disclosure mandates are compressing traditional fastener procurement cycles while elevating performance certification requirements. Three developments are restructuring competitive positioning among bolt manufacturers and their turbine OEM customers.
Zinc-flake coating systems with aluminum-rich formulations are supplanting conventional hot-dip galvanizing for subsea applications. Ørsted and Equinor procurement specifications now specify these coatings for monopile flange connections exposed to North Sea splash zones. The shift is compressing qualified supplier lists to manufacturers with in-house coating lines and third-party ISO 12944 validation.
EU CSRD disclosure requirements and the EU AI Act are extending supply chain documentation obligations to tier-two bolt manufacturers serving Vestas and Siemens Gamesa. Mechanical testing protocols must now include full material traceability from steel mill through heat treatment. German turbine OEMs are responding by consolidating supplier panels to vendors with integrated quality management systems.
Direct contracting between offshore wind farm operators and specialized fastener manufacturers is disrupting traditional OEM-mediated procurement channels. Copenhagen Infrastructure Partners and Ocean Winds are establishing preferred supplier agreements with Nordic bolting specialists for foundation installation phases. The pattern is most visible in North Sea markets where floating platform projects require application-engineered anchor systems beyond standard catalog specifications.
Wind Power Bolts Market Segmentation
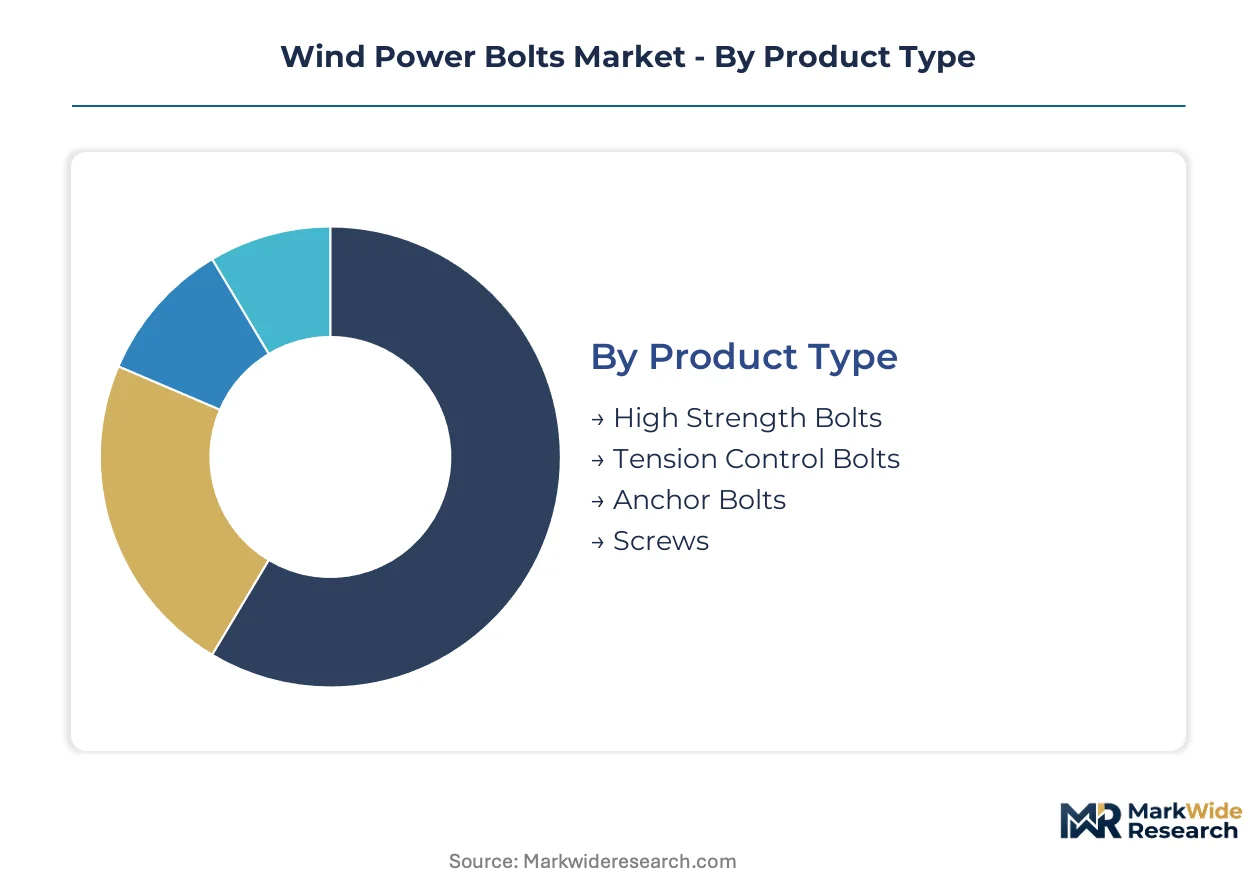
Wind power bolt procurement channels diverge sharply by application criticality and volume scale. Specialized marine fastener suppliers capture foundation work through direct operator contracts, while standard turbine assembly bolts flow via OEM-mediated supply chains with stricter certification tiers.
Product Type:
Channel mix splits between catalog-standard items for onshore turbine assembly and application-engineered systems for offshore foundations requiring third-party validation.
- High Strength Bolts:Property classes 10.9 and 12.9 dominate tower flange and nacelle connections. Jiangsu and Guangdong offshore wind auctions in China are specifying these grades for monopile transition pieces, compressing qualified supplier lists to manufacturers with in-house heat treatment.
- Anchor Bolts:Cast-in and post-installed arrays secure gravity-based and floating substructures. Tension-leg platform projects in the North Sea are driving procurement toward specialized marine fastener suppliers with 25-year corrosion resistance validation.
- Tension Control Bolts:Preload retention systems for blade root connections. Mid-life retrofit demand from 2-3MW turbine fleets creates aftermarket pull.
- Screws:Secondary fastening for electrical enclosures and auxiliary systems. Standard catalog distribution through industrial supply houses.
By volume, High Strength Bolts leads. By growth pace, Anchor Bolts is climbing the fastest.
Material:
Cost tier stratification separates commodity carbon grades from premium alloy specifications subject to nickel and molybdenum price swings.
- Carbon Steel:Property classes 8.8 and 10.9 anchor tower construction where cost efficiency governs. Hot-dip galvanizing capacity clusters within 200km of Ningbo-Zhoushan port, creating single-point vulnerability for coated supply.
- Alloy Steel:Nickel-chromium-molybdenum formulations command premium positioning in drivetrain and blade root connections. Quarterly input cost volatility of 15-40% compresses margin predictability for manufacturers.
- Stainless Steel:Duplex grades for splash zone exposure. REACH chemical compliance under EU Green Deal policy tightens substitution pathways.
- Aluminum:Lightweight fastening for nacelle interior systems. Limited penetration due to galvanic corrosion concerns with steel structures.
Carbon Steel dominates unit shipments. Alloy Steel captures the steepest value expansion trajectory as turbine capacities scale.
Application:
Maturity gradient runs from established turbine assembly protocols to emerging foundation engineering requirements.
- Foundation Installation:Monopile and floating substructure proliferation redirects procurement from onshore contractors to marine specialists. FERC renewable credit frameworks in Louisiana and Texas are activating demand for hurricane-rated systems.
- Turbine Assembly:Mature demand pool with consolidated OEM supplier panels. GB standards enforced by SAMR in China and EU AI Act documentation requirements are elevating tier-two manufacturer qualification thresholds.
- Tower Construction:Flange connection bolting for tubular steel and hybrid structures. Standardized specifications limit differentiation.
- Maintenance:Aftermarket replacement and preload monitoring services. Digital thread integration with RFID-embedded fasteners aligns with CSRD disclosure requirements.
Turbine Assembly holds installed base dominance. Foundation Installation is gaining share fastest as offshore water depths increase.
End User:
Customer type determines contract structure, with direct operator engagement disrupting traditional OEM mediation for critical subsea applications.
- Wind Farm Operators:Copenhagen Infrastructure Partners and Ocean Winds are establishing preferred supplier agreements with Nordic bolting specialists. Direct contracting for floating platform anchor systems bypasses standard OEM channels.
- OEM Manufacturers:Vestas and Siemens Gamesa are consolidating supplier panels to vendors with integrated quality management systems covering full material traceability.
- Contractors:Foundation installation specialists for onshore and near-shore projects. Price-sensitive procurement with shorter qualification cycles.
- Maintenance Providers:Service contractors for blade root connection upgrade cycles. Retrofit demand creates pull for improved preload retention systems.
OEM Manufacturers anchor current volume. Wind Farm Operators are expanding procurement scope most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ningbo-Zhoushan port complex anchors Asia-Pacific supply flows for corrosion-coated fasteners, while North Sea offshore lease auctions and US Gulf Coast lease rounds concentrate demand generation in three distinct manufacturing corridors.
China
Jiangsu and Guangdong provincial governments are fast-tracking offshore wind auctions that specify GB-standard high-tensile fasteners for turbine assembly. SAMR enforces material traceability protocols that compress qualified supplier lists to manufacturers with integrated heat treatment capabilities. The Yangtze River Delta manufacturing belt around Ningbo hosts over 60% of regional hot-dip galvanizing capacity, creating dense clustering for coated bolt production serving domestic and export markets.
Germany
North Sea floating platform projects are redirecting procurement volumes from onshore contractors to specialized marine fastener suppliers. The EU Green Deal and REACH chemical compliance mandates accelerate certified fastener replacement cycles in Vestas and Siemens Gamesa supply chains. Hamburg and Bremerhaven port infrastructure supports logistics for monopile transition piece bolting systems destined for Baltic and North Sea installations.
United States
Louisiana and Texas lease auctions under FERC renewable credit frameworks are activating demand for hurricane-rated foundation bolts with enhanced fatigue performance. OSHA structural fastening standards and Buy America provisions elevate domestic manufacturing requirements for federally subsidized wind projects. The Gulf Coast fabrication corridor from Corpus Christi to Lake Charles is attracting coating specialists to serve emerging offshore installation demand.
Norway
Equinor and Ocean Winds floating platform developments require specialized anchor bolt arrays with 25-year corrosion resistance validation. Norwegian multiaxial fatigue testing laboratories concentrate certification capacity for offshore loading spectrum simulation. Stavanger and Bergen industrial zones host Nordic bolting specialists establishing preferred supplier agreements directly with wind farm operators.
United Kingdom
Dogger Bank and Hornsea-scale offshore projects are consolidating procurement through direct operator contracts bypassing traditional OEM channels. The EU AI Act and CSRD disclosure requirements extend supply chain documentation obligations to tier-two bolt manufacturers serving European turbine OEMs. Hull and Grimsby manufacturing bases support installation logistics for North Sea foundation systems.
Wind Power Bolts Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and certification depth. The vendor base organizes into three tiers: integrated multinational tool conglomerates with broad distribution reach, regional heat-treatment specialists with OEM panel positions, and marine-focused fabricators capturing direct operator contracts for offshore foundations. Strategic moves concentrate on coating line vertical integration and preferred supplier agreement capture with floating platform developers.
Within the Nordic specialist tier, Dokka Fasteners exemplifies the marine-focused archetype with North Sea manufacturing positioning. Stanley Black & Decker represents the scale-driven multinational pattern with cross-industrial distribution infrastructure. Finework (HuNan) New Energy Technology anchors the China-based regional specialist category with Yangtze River Delta production concentration.
| Leading Market Players |
|---|
| Dokka Fasteners |
| Stanley Black & Decker |
| Dyson Corp. |
| Finework (HuNan) New Energy Technology |
| ITH Bolting Technology |
| Mudge Fasteners |
| Beck Industries |
| August Friedberg GmbH |
| Ningbo Ningli High-Strength Fastener |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four-month coating qualification timelines compress pricing power for new market entrants while concentrating procurement leverage with established suppliers holding validated ISO 12944 certifications. This lead-time structure reinforces tiered pricing stratification across the value chain, where marine fastener specialists with in-house zinc-flake lines command premium positioning against commodity carbon steel distributors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs transaction dynamics. Premium tier captures 12.9-grade alloy steel bolts for drivetrain applications with full material traceability; standard tier covers 10.9-grade carbon steel tower flanges; economy tier serves secondary electrical enclosure fastening. Price differentiation hinges on certification depth and corrosion resistance ratings, with nickel-molybdenum input cost volatility intensifying margin compression in alloy grades. Contractors represent the most price-sensitive buyer archetype, while offshore wind farm operators absorb premium positioning for 25-year validated anchor systems.
Supply Chain Analysis
Strategic stockpiling of high-tensile steel feedstock dominates over just-in-time approaches given 15-40% quarterly alloy price swings and coating capacity bottlenecks. Manufacturing gravity centers on China, Germany, and Norway, with the Ningbo-Zhoushan corridor anchoring hot-dip galvanizing output. Raw material dependencies draw from nickel-chromium-molybdenum alloy formulations, carbon steel billets, and zinc-aluminum coating chemistries. Single-point vulnerability concentrates in coastal China galvanizing clusters within 200km of Ningbo-Zhoushan port. Distribution runs through direct operator contracts for foundation systems and OEM-mediated channels for turbine assembly bolts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon fiber composite fastening systems and adhesive bonding technologies pose credible substitution threats that incumbent bolt manufacturers must neutralize through performance differentiation and certification depth.
For Market Incumbents: Fortify market position by deepening backward integration into captive zinc-flake coating lines and securing preferred supplier agreements with floating platform developers. Dokka Fasteners and Nordic specialists demonstrate the defensive value of North Sea manufacturing footprints with 25-year corrosion validation. Counter composite substitution threats by embedding RFID traceability that satisfies EU AI Act documentation requirements. For New Entrants and Emerging Players: Lead with digital thread integration capabilities as the most penetrable wedge against established supplier panels. The US Gulf Coast offshore belt offers white-space opportunity as Louisiana and Texas lease auctions activate demand for hurricane-rated foundation systems without entrenched incumbent relationships. Position through direct contracting with Copenhagen Infrastructure Partners-style operators bypassing traditional OEM mediation. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with dormant fastener divisions lacking offshore wind certification depth. Long-term viability hinges on coating line ownership and multiaxial fatigue testing access. Watch for inflection when FERC renewable credit frameworks trigger accelerated US Gulf Coast procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Line Vertical Integration | In-house zinc-flake production compresses ISO 12944 validation timelines for North Sea suppliers. |
| Preferred Supplier Agreement Capture | Direct contracts with Ocean Winds and Copenhagen Infrastructure Partners bypass OEM procurement channels. |
| RFID-Enabled Traceability Deployment | Embedded fasteners satisfy EU AI Act supply chain documentation mandates for Vestas and Siemens Gamesa panels. |
| Multiaxial Fatigue Testing Investment | German and Norwegian laboratory access removes certification bottlenecks for 25-year offshore loading spectra. |
| US Gulf Coast Manufacturing Footprint | Lake Charles to Corpus Christi positioning captures FERC-subsidized demand for hurricane-rated foundation bolts. |
Research Methodology
A standing panel of foundation installation contractors, turbine OEM procurement directors, marine fastener quality managers, and offshore wind project developers provided ongoing calibration across primary interview cycles. Secondary validation drew from FERC renewable credit filings, EU Green Deal policy documentation, SAMR GB standard enforcement records, and SEC disclosures from listed industrial conglomerates with fastener divisions. Bottom-up shipment estimates from coating line operators and top-down demand modeling from offshore lease auction pipelines were triangulated for consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across product grade tier, application criticality, end-user contract structure, and regional regulatory cluster. CAGRs were derived from installation pipeline visibility and replacement cycle analysis. Forecast inputs incorporated alloy steel price trajectory assumptions and floating platform adoption curves.
Forecasts assume regulatory continuity in FERC credit frameworks, EU REACH compliance mandates, and SAMR material traceability enforcement; material policy shifts would require re-modeling. Hydrogen embrittlement susceptibility in high-strength steels and coating qualification timeline extensions represent specific revision triggers. Revision becomes warranted when nickel-molybdenum input cost volatility exceeds historical bands or when floating platform procurement accelerates beyond modeled penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Global Wind Automation Market
Wind Energy Systems
Wind Power Couplings Market
Wind Energy Systems
Wind Turbine Lenses Market
Wind Energy Systems
Offshore Wind Tower Market
Wind Energy Systems
India Wind Industry Market
Wind Energy Systems
Canada Wind Energy Market
Wind Energy Systems
Wind Turbine Shaft Market
Wind Energy Systems
North America Wind Power Equipment Market
Wind Energy Systems
Wind Turbine Nacelle Market
Wind Energy Systems
Taiwan Wind Energy Market
Wind Energy Systems
Wind Power Market
Wind Energy Systems
Asia-Pacific Wind Power Equipment Market
Wind Energy Systems
Wind Turbine Tower Market
Wind Energy Systems
Wind Tower Market
Wind Energy Systems
Germany Wind Energy Market
Wind Energy Systems
Denmark Wind Energy Market