
 Europe Direct Drive Wind Turbine Market | 2026-2036
Europe Direct Drive Wind Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Direct Drive Wind Turbine Market Foresight
The EU Green Deal is consolidating the cost-of-entry calculus for turbine suppliers serving European waters. ENERCON GmbH anchors onshore deployment across Northern Germany with established permanent magnet generator supply chains. Siemens Gamesa Renewable Energy SA dominates offshore direct drive installations through integrated nacelle manufacturing in Denmark. VENSYS Energy AG specializes in gearless drivetrain technology for medium-scale projects, competing on generator efficiency metrics.
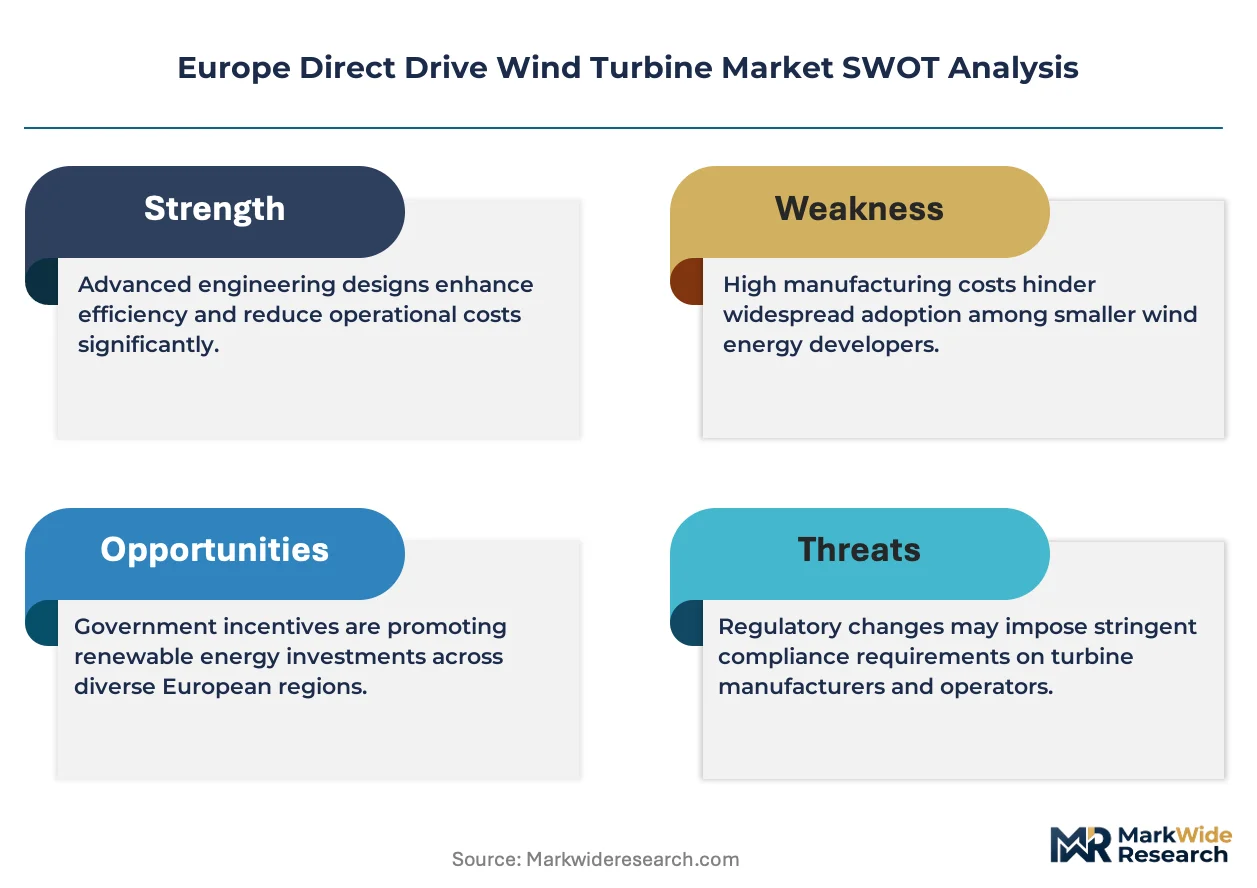
A direct drive wind turbine eliminates the gearbox between rotor and generator, instead coupling blades directly to a low-speed multi-pole ring generator typically rated above 3 MW for commercial utility applications. Permanent magnet synchronous generators dominate offshore configurations due to higher torque density and reduced maintenance intervals compared with electrically-excited alternatives. Onshore applications favor asynchronous direct drive designs where grid-forming capabilities and lower rare-earth dependency offset weight penalties. Utility-scale installations command the largest revenue pool, though repowering retrofits of aging Danish and Spanish fleets represent the fastest-growing installation type as operators seek to preserve grid connection rights.
EMA guidelines on generator bearing lubricant biodegradability, CE marking for nacelle electrical assemblies, and the EU F-Gas Regulation on SF6-insulated switchgear collectively shape product certification timelines and component sourcing rules for European OEMs. National regulators in Germany, Denmark, and the Netherlands layer marine spatial planning requirements onto turbine type certification, extending lead times for offshore variants. Stakeholders must monitor forthcoming EU Critical Raw Materials Act implementation to assess magnet supply security against domestic content mandates.
Market Dynamics
EU domestic content mandates under REPowerEU are restructuring supplier qualification criteria, forcing turbine OEMs to reconfigure permanent magnet sourcing and nacelle assembly footprints across the North Sea corridor.
Growth Catalysts
- Offshore lease auctions:Germany, Denmark, and the United Kingdom are awarding seabed rights exclusively to projects specifying direct drive platforms above 10 MW, locking in technology preferences for the 2026-2035 development cycle.
- EU F-Gas Regulation:Phase-down schedules for SF6-insulated switchgear are accelerating demand for vacuum-interrupter alternatives that integrate more naturally with direct drive electrical architectures.
- Permanent magnet generators:Advances in dysprosium-terbium reduction chemistry are cutting rare-earth mass per MW while preserving torque density, improving project economics for offshore developers.
Market Restraints
- Rare-earth supply concentration:Magnet raw material processing clusters in a single non-European jurisdiction create exposure to export licensing disruptions that European OEMs cannot hedge through inventory alone.
- Generator bearing technical limitation:Low-speed multi-pole ring generators impose static load ratings that constrain rotor diameter scaling beyond 15 MW without splitting the drivetrain into multiple generator units.
- Marine spatial planning friction:Netherlands and Belgian regulators are extending environmental impact assessment timelines for offshore arrays, stretching project development cycles and compressing supplier payment schedules.
Strategic Opportunities
- Polish Baltic development:Emerging offshore zones in Polish waters lack established supplier relationships, creating first-mover positioning for direct drive OEMs willing to localize nacelle assembly.
- Repowering retrofit applications:Aging onshore fleets in Spain and Portugal face grid connection expiry, opening conversion opportunities where direct drive replacements preserve permitting rights.
- EU Critical Raw Materials Act:Magnet recycling mandates and strategic stockpile provisions will favor OEMs with documented circular supply chains for permanent magnet recovery.
Industry Challenges
- Generator winding skill scarcity:Low-speed multi-pole ring generators require specialized copper coil forming expertise that European vocational pipelines have not scaled to match installation targets.
- Type certification timeline compression: DNV and TÜV Rheinland are extending offshore turbine certification protocols to cover integrated power electronics, adding 8-14 months to product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Direct Drive Wind Turbine Market |
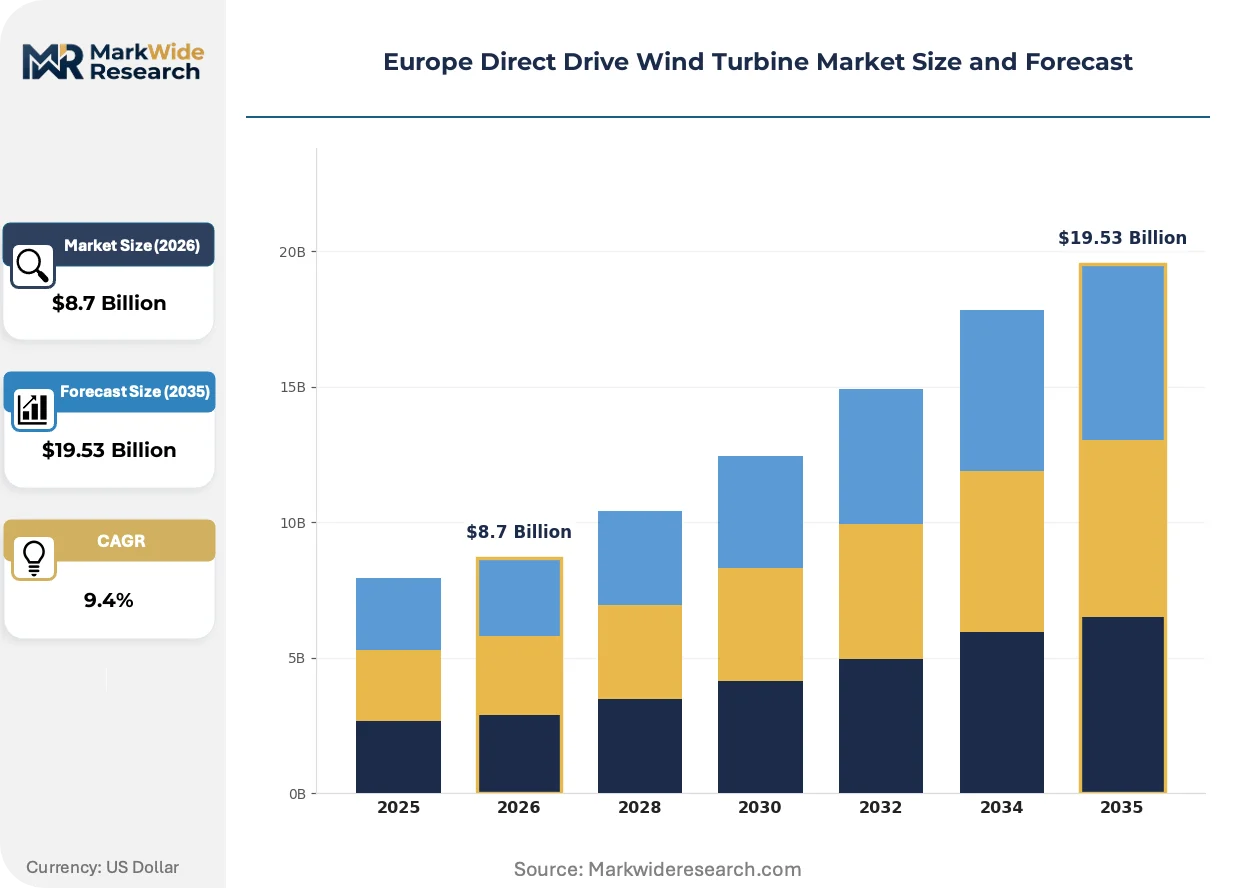
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
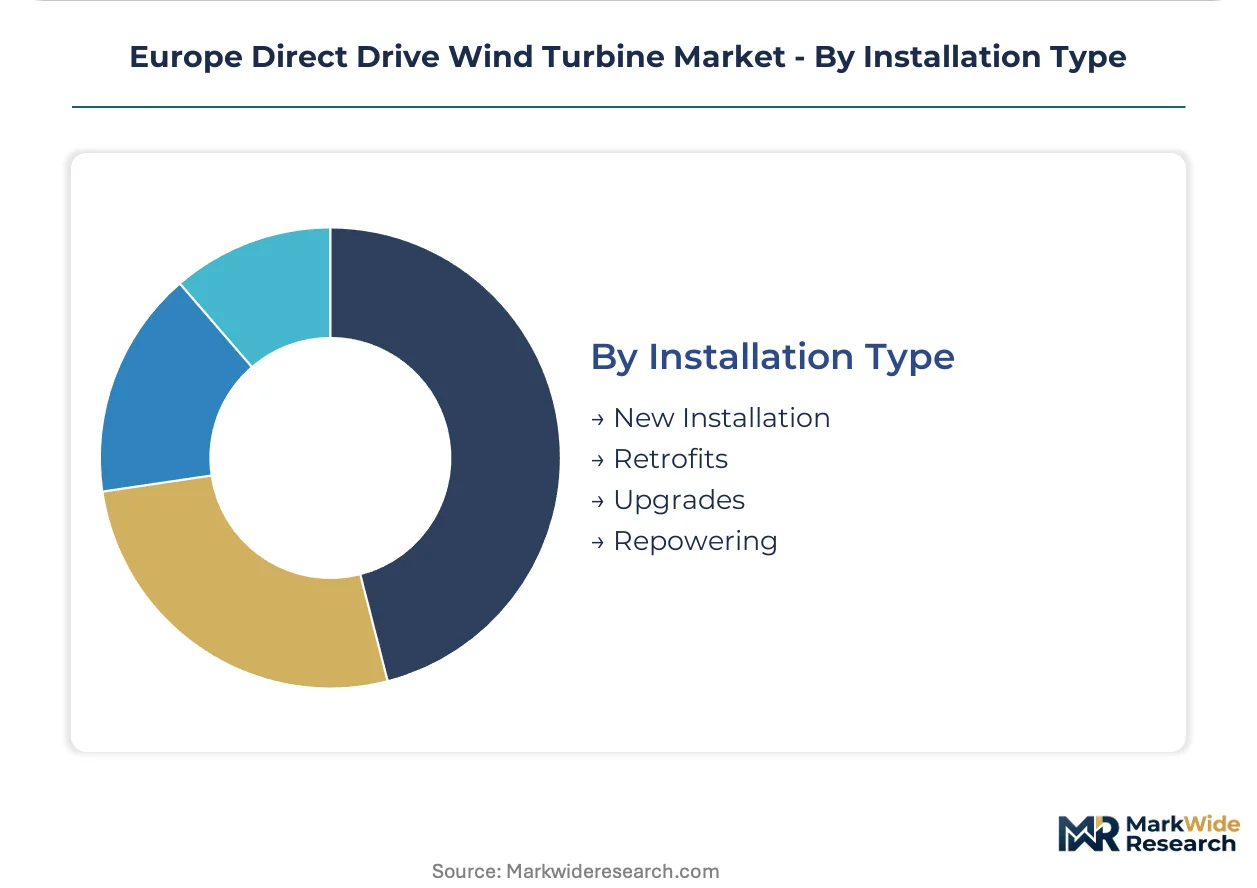
| Segmentation | Technology: Permanent Magnet, Synchronous, Asynchronous, Direct Drive Application: Onshore, Offshore, Utility-Scale, Distributed Generation End User: Energy Producers, Utility Companies, Independent Power Producers, Government Agencies Installation Type: New Installation, Retrofits, Upgrades, Repowering |
| Companies Covered | Emergya Wind Technologies B.V, VENSYS Energy AG, Siemens Gamesa Renewable Energy SA, Nordex SE, Northern Power Systems, ENERCON GmbH, ABB Ltd, GE Vernova, Leitner AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Direct Drive Wind Turbine Market Shifts & Advancements
Direct drive architectures are converging with power electronics integration and grid-forming controls, compressing the boundary between mechanical drivetrain design and electrical system architecture.
Air-cooled permanent magnet generators are electrifying thermal management strategies for offshore nacelles. Developers in the German Bight are specifying these units to eliminate seawater cooling loops and their associated corrosion risks. This electrification is collapsing maintenance intervals from semi-annual to biennial schedules, reshaping service contract economics.
EMA guidelines on biodegradable lubricants are mandating formulation changes for generator bearings and pitch systems. OEMs serving Danish waters must now submit biodegradability certifications alongside mechanical test reports. Offshore variants face the tightest compliance windows, with some suppliers accelerating synthetic ester adoption by 18 months to secure type approval.
Utility offtakers are unbundling turbine supply from installation and long-term service agreements. Danish and German developers are now procuring direct drive units through separate RFPs from balance-of-plant contractors, fragmenting vendor relationships. This unbundling is most pronounced in the United Kingdom, where CfD auction structures favor developers who optimize component sourcing across multiple specialist suppliers.
Europe Direct Drive Wind Turbine Market Segmentation
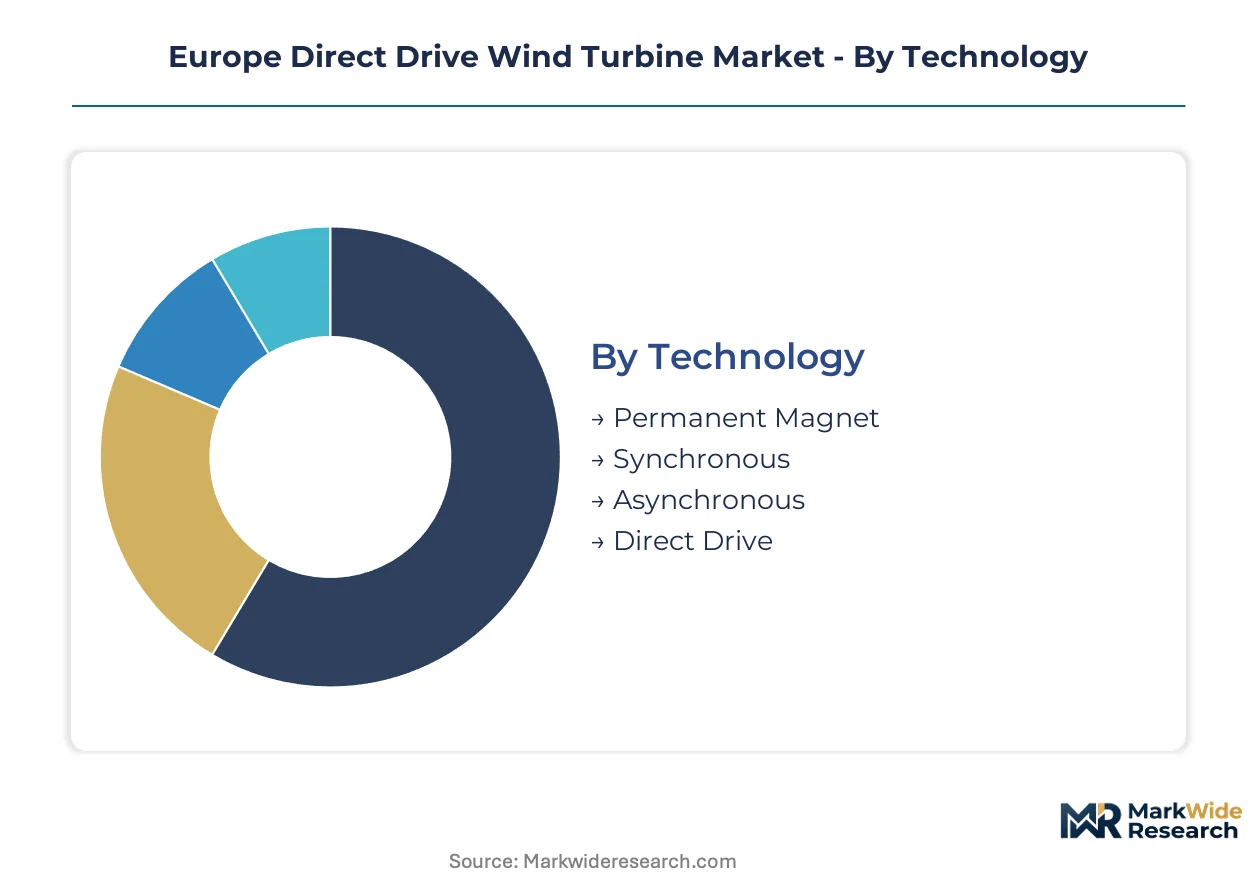
Direct drive turbine procurement patterns diverge sharply across technology architectures and deployment contexts. European developers select generator configurations based on grid connection constraints, marine spatial licensing, and domestic content compliance timelines.
Technology:
Buyers differentiate on magnet supply security, grid-forming capability, and rare-earth exposure rather than upfront capital cost alone.
- Permanent Magnet:Multi-pole ring generators employing neodymium-dysprosium-terbium alloys deliver torque density above 15 kNm/m³ for offshore platforms above 10 MW. North Sea developers in Germany and Denmark specify these units exclusively for lease auctions mandating high-capacity direct drive configurations, though magnet processing concentration outside Europe creates licensing exposure that OEMs address through strategic inventory and recycling partnerships.
- Synchronous:Grid-forming synchronous direct drive generators enable black-start capability and inertia provision for weak grid connections in rural Scotland and Iberian peninsula sites. Spanish repowering projects favor these units where existing substations lack synchronous condenser upgrades.
- Asynchronous:Squirrel-cage induction generators eliminate rare-earth dependency entirely, trading torque density for supply chain resilience.
- Direct Drive:Gearless architectures as a technical class encompass the above variants, unified by elimination of gearbox maintenance and associated offshore service vessel requirements.
Volume sits with Permanent Magnet; growth tilts toward Synchronous as grid code requirements stiffen.
Application:
Site conditions and permitting economics determine platform scale more than technology readiness.
- Offshore:Fixed-bottom and floating installations in the German Bight, Danish North Sea, and UK Dogger Bank zone deploy units rated 12-15 MW with air-cooled nacelles eliminating seawater corrosion loops. Lease auction structures in these waters now specify minimum capacity thresholds that only direct drive architectures satisfy.
- Onshore:Northern German plain installations and Spanish plateau repowering sites favor 3-5 MW units with asynchronous generators where grid connection rights are grandfathered.
- Utility-Scale:Projects above 50 MW aggregate capacity dominate procurement volume through CfD mechanisms and corporate PPA aggregation.
- Distributed Generation:Industrial self-consumption and agricultural cooperative installations below 10 MW aggregate capacity fill interconnection queue gaps in Poland and Romania.
Revenue concentrates in Offshore; capacity additions expand most quickly in Distributed Generation where queue access is unconstrained.
End User:
Risk tolerance and balance sheet capacity separate procurement strategies more than technical specifications.
- Energy Producers:Integrated oil majors and former utilities with North Sea oil platform decommissioning expertise leverage existing marine logistics for offshore development.
- Utility Companies:RWE, Ørsted, and SSE specify direct drive platforms through multi-turbine framework agreements with 15-year service unbundling.
- Independent Power Producers:Project finance-dependent developers optimize turbine selection for CfD auction scoring and lender technical due diligence requirements.
- Government Agencies:State-owned enterprises in Poland and Baltic states anchor emerging market creation through offtake guarantees and grid buildout commitments.
Procurement volume clusters with Utility Companies; deal flow is climbing fastest among Government Agencies in Polish and Baltic waters.
Installation Type:
Grid connection rights and permitting timelines create divergent project economics across greenfield and brownfield contexts.
- New Installation:Greenfield developments in emerging Polish and Baltic offshore zones require full environmental impact assessment and seabed survey cycles extending development timelines.
- Retrofits:Nacelle replacements on existing tower and foundation infrastructure preserve permitting while upgrading yield.
- Upgrades:Control system and blade extension modifications on mid-life fleets in Germany and Spain extend asset life without full repowering.
- Repowering:Complete turbine replacement at aging Danish and Spanish onshore sites preserves grid connection rights expiring under original permits, with direct drive units replacing 1990s-era geared machines while maintaining tip height and noise envelopes.
Project pipelines favor New Installation; steepest expansion trajectory belongs to Repowering as connection rights face expiry deadlines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Direct drive turbine procurement clusters along the North Sea corridor where lease auctions and grid connection queues favor high-capacity platforms. Germany, Denmark, and the United Kingdom dominate installation volumes, while Poland and the Baltic states emerge as new demand centers.
Germany
The German Bight hosts the continent's densest concentration of offshore direct drive deployment, with developers specifying 12-15 MW air-cooled units to eliminate seawater corrosion risks. The Federal Maritime and Hydrographic Agency enforces stringent marine spatial planning requirements that extend environmental impact assessment timelines. Cuxhaven and Bremerhaven anchor nacelle assembly clusters where ENERCON GmbH maintains permanent magnet generator supply chains.
Denmark
Danish North Sea lease zones mandate minimum capacity thresholds that only direct drive architectures satisfy, locking in technology preferences through 2035. The Danish Energy Agency coordinates grid connection queues with seabed rights auctions to compress development cycles. Esbjerg hosts integrated manufacturing facilities where Siemens Gamesa Renewable Energy SA dominates offshore direct drive installations.
United Kingdom
The Dogger Bank zone drives demand for 14-15 MW platforms through Contract for Difference mechanisms that favor optimized component sourcing. The Offshore Petroleum Regulator for Environment and Decommissioning layers consent requirements onto turbine type certification. Hull and Aberdeen harbor clusters support installation logistics for utility-scale arrays.
Poland
Polish Baltic waters lack established supplier relationships, creating first-mover positioning for OEMs willing to localize nacelle assembly. The Polish Energy Regulatory Office administers offshore wind auctions with domestic content requirements mirroring REPowerEU mandates. Gdańsk and Szczecin industrial zones attract nacelle manufacturing investments from entrants seeking unconstrained queue access.
Spain
Spanish plateau repowering sites favor 3-5 MW asynchronous generators where grid connection rights are grandfathered from 1990s-era permits. The Ministry for the Ecological Transition administers renewable energy auction schemes with accelerated timelines for brownfield replacements. Zaragoza and Castile-La Mancha host retrofit clusters where aging geared machines face replacement deadlines.
Europe Direct Drive Wind Turbine Market Competitive Landscape
German producers anchor the integrated nacelle tier; Danish specialists hold offshore installation density. The vendor base concentrates around three OEMs with permanent magnet supply chain control, while component suppliers and regional assemblers populate fragmented downstream tiers. Strategic archetypes include integrated drivetrain manufacturers, generator winding specialists, and power electronics integrators. Capacity expansion and magnet recycling partnerships constitute the dominant competitive moves as domestic content mandates tighten.
Among Germany-based fabricators, ENERCON GmbH and Nordex SE occupy positions within the onshore direct drive tier, while Siemens Gamesa Renewable Energy SA exemplifies the integrated offshore architecture archetype. VENSYS Energy AG represents the gearless drivetrain specialist segment competing on generator efficiency metrics. These companies illustrate how European OEMs are restructuring permanent magnet sourcing and nacelle assembly footprints to satisfy REPowerEU qualification criteria across the North Sea corridor.
| Leading Market Players |
|---|
| Emergya Wind Technologies B.V |
| VENSYS Energy AG |
| Siemens Gamesa Renewable Energy SA |
| Nordex SE |
| Northern Power Systems |
| ENERCON GmbH |
| ABB Ltd |
| GE Vernova |
| Leitner AG |
| Others |
Supply & Pricing Matrix
Permanent magnet versus asynchronous generator architectures split European procurement into distinct value tiers, with rare-earth dependency premiums commanding higher unit economics while supply chain localization mandates reshape component sourcing footprints across the North Sea corridor.
Pricing Analysis
Volume procurement concentrates with utility-scale offshore developers while margin capture tilts toward specialized generator winding houses serving repowering retrofits. Price differentiation separates air-cooled permanent magnet platforms from asynchronous alternatives through magnet supply security premiums and grid-forming capability certifications. Cost compression in the asynchronous tier intensifies as Polish and Baltic developers prioritize rare-earth-free configurations for domestic content compliance. Independent power producers exhibit highest price sensitivity given project finance constraints, whereas integrated oil majors absorb premiums for supply chain traceability.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from RWE and Ørsted, while regional assemblers serve distributed generation through fabricators in Poland and Romania. Magnet raw material processing draws from China, with secondary sourcing from Vietnam and Malaysia emerging under EU Critical Raw Materials Act pressure. Rare-earth concentrate dependency creates single-source vulnerability that OEMs address through strategic inventory and recycling partnerships. Distribution runs through Bremerhaven and Esbjerg port clusters for offshore nacelle assembly, with Cuxhaven anchoring permanent magnet generator supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal and REPowerEU domestic content mandates erect a cost-of-compliance barrier that favors incumbent OEMs with established European nacelle assembly footprints over import-dependent challengers.
For Market Incumbents: Extend magnet recycling capabilities through documented circular supply chains that satisfy forthcoming EU Critical Raw Materials Act provisions. Deepen backward integration into generator bearing lubricant formulation to meet EMA biodegradability guidelines without supplier dependency. Lock in Cuxhaven and Esbjerg capacity additions before Polish Baltic auction timelines compress available labor pools.
For New Entrants and Emerging Players: Enter via Polish Baltic waters where established supplier relationships remain absent and domestic content requirements create first-mover positioning for localized nacelle assembly. Target distributed generation interconnection queues in Romania and Poland where utility-scale developers face grid access constraints. Pursue generator winding specialization as a service model for repowering retrofits rather than competing on integrated platform supply.
For Investors and Strategic Acquirers: Re-rating potential sits with generator winding specialists given grid-forming synchronous architecture demand from Iberian repowering projects and Scottish weak-grid connections. Monitor DNV and TÜV Rheinland certification queue lengths as an inflection signal for product launch velocity and working capital intensity across the analysis window.
| Strategic Initiative | Industry Significance |
|---|---|
| Magnet Recycling Partnership | Circular supply chain documentation satisfies EU Critical Raw Materials Act compliance ahead of mandate implementation. |
| Air-Cooled Generator Scale-Up | Elimination of seawater corrosion loops extends maintenance intervals and reshapes service contract economics for German Bight developers. |
| Polish Nacelle Assembly Localization | First-mover positioning in Baltic waters captures domestic content premiums under REPowerEU qualification criteria. |
| Generator Winding Vocational Pipeline | Copper coil forming expertise scarcity constrains installation targets and creates captive labor advantages for early investors. |
| Biodegradable Lubricant Certification | EMA guideline compliance accelerates synthetic ester adoption and tightens type approval windows for Danish waters. |
Research Methodology
European Wind Energy Association statistics, EIA country energy profiles, and IEA renewable technology roadmaps formed the secondary backbone, supplemented by customs data on permanent magnet imports and offshore lease auction disclosures. Primary fieldwork incorporated structured interviews with utility planning officers at RWE and Ørsted, IPP project developers active in Polish Baltic waters, EPC contractors specializing in North Sea installation logistics, and grid operators managing connection queues across Germany and Denmark. Bottom-up installation forecasts triangulated against top-down capacity targets from national renewable energy action plans.
Bottom-up modeling tracked individual project pipelines through CfD auction mechanisms and corporate PPA aggregations, while top-down validation stress-tested against REPowerEU capacity installation corridors. Segmentation dimensions encompassed generator technology architecture, deployment context across offshore and onshore sites, end-user risk tolerance profiles, and installation type from greenfield development through repowering retrofit. CAGRs derived from unit economics modeling incorporating magnet price volatility scenarios and domestic content compliance cost curves.
Revisions become necessary when rare-earth export licensing disruptions materialize, when marine spatial planning timelines extend beyond modeled development cycles, or when grid connection queue prioritization rules shift unexpectedly. Forecasts reflect assumptions regarding magnet recycling technology maturation and vocational training pipeline scaling. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Europe Large Wind Turbine Market
Wind Energy Systems
Europe Small Wind Turbine Market
Wind Energy Systems
Wind Speed Alarm Market
Wind Energy Systems
Wind Turbine Pitch System Sales Market
Wind Energy Systems
Wind Power Bolts Market
Wind Energy Systems
Greece Wind Energy Market
Wind Energy Systems
Global Small Wind Market
Wind Energy Systems
Taiwan Wind Energy Market
Wind Energy Systems
Wind Blades NDT Market
Wind Energy Systems
Offshore Wind Turbine Blade Leading-Edge Defect Inspection Equipment Market
Wind Energy Systems
Wind Turbine Operation and Maintenance Market
Wind Energy Systems
Chile Wind Energy Market
Wind Energy Systems
New Zealand Wind Energy Market
Wind Energy Systems
Wind Tower Market
Wind Energy Systems
Wind Turbine Blades Market
Wind Energy Systems
Asia-Pacific Wind Power Equipment Market