
 Ecuador Wind Energy Market | 2026-2036
Ecuador Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Ecuador Wind Energy Market Foresight
Horizontal-axis turbine technology is fragmenting into modular, transport-optimized configurations suited to Ecuador's narrow mountain roads and dispersed grid nodes. Siemens Gamesa Renewable Energy leverages its nacelle assembly footprint in Latin America to reduce logistics costs for Andean projects. Vestas Wind Systems anchors its regional service network through long-term operations contracts with local utilities. CELEC EP competes as the state-owned offtaker and project partner, controlling transmission access for most wind developments.
Ecuador wind energy encompasses electricity generation from aerodynamic rotor systems converting kinetic wind flux into grid-synchronized AC power, with typical installations employing doubly-fed induction generators or direct-drive permanent magnet alternators rated between 1.5 MW and 3.5 MW for high-altitude air density conditions. Onshore turbines dominate current capacity additions due to lower civil works requirements and established EPC supply chains, while hybrid systems pairing wind with photovoltaic arrays represent the fastest-growing configuration as developers seek to flatten generation profiles and optimize grid connection utilization. Horizontal-axis technology leads by installed base, though direct-drive architectures gain share where gearbox maintenance logistics prove prohibitive in remote terrain.
Ecuador's Ministry of Energy and Non-Renewable Natural Resources governs concession licensing and power purchase agreements, while the National Electricity Regulator (ARCONEL) sets grid codes and tariff structures that determine project bankability. The central bank's green credit line and the country's adherence to ISO 14001 environmental management standards shape developer compliance costs and financing access. Stakeholders must monitor transmission expansion timelines in the Sierra region and evolving auction mechanisms that could shift offtaker risk allocation.
Market Dynamics
Grid-scale utility procurement is compressing project development timelines in Ecuador's wind sector, as CELEC EP accelerates offtake contracting to meet Andean highlands electrification targets. This structural shift is reshaping developer capital allocation and equipment sourcing strategies.
Growth Catalysts
- Ministry of Energy Permitting Reforms:Streamlined concession licensing for renewable projects reduces administrative delays in Loja Province and adjacent Andean corridors.
- Hybrid System Economics:Wind-photovoltaic pairing flattens generation profiles and maximizes grid connection utilization rates for Sierra region developers.
- Green Credit Facility:Ecuador's central bank dedicated lending line improves project bankability and reduces weighted average cost of capital for qualifying installations.
Market Restraints
- Geographic Supply Concentration:Nacelle and blade manufacturing capacity clusters in Brazil and Argentina, exposing projects to cross-border logistics bottlenecks and currency fluctuation risk.
- Transmission Access Constraints:CELEC EP's monopoly over Sierra region grid infrastructure creates queue delays for independent power producers seeking interconnection agreements.
- Air Density Technical Limitation:High-altitude turbine derating requirements reduce nameplate capacity factors below sea-level benchmarks, compressing revenue projections for Andean installations.
Strategic Opportunities
- Emerging Coastal Zones:Unexploited wind resources in Manabí and Esmeraldas provinces offer lower turbulence intensity and superior capacity factors compared to high-altitude sites.
- Direct-Drive Technology Convergence:Permanent magnet alternators paired with modular transport configurations eliminate gearbox maintenance requirements in remote terrain.
- ARCONEL Auction Mechanism Evolution:Competitive bidding reforms under consideration could reallocate offtaker risk and attract international equity participation.
Industry Challenges
- Specialized Technician Scarcity:Ecuador's vocational training infrastructure produces insufficient certified wind turbine service personnel for remote Andean operations and maintenance.
- ISO 14001 Compliance Complexity:Environmental management certification timelines for Andean projects extend due to biodiversity impact assessments and indigenous consultation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ecuador Wind Energy Market |
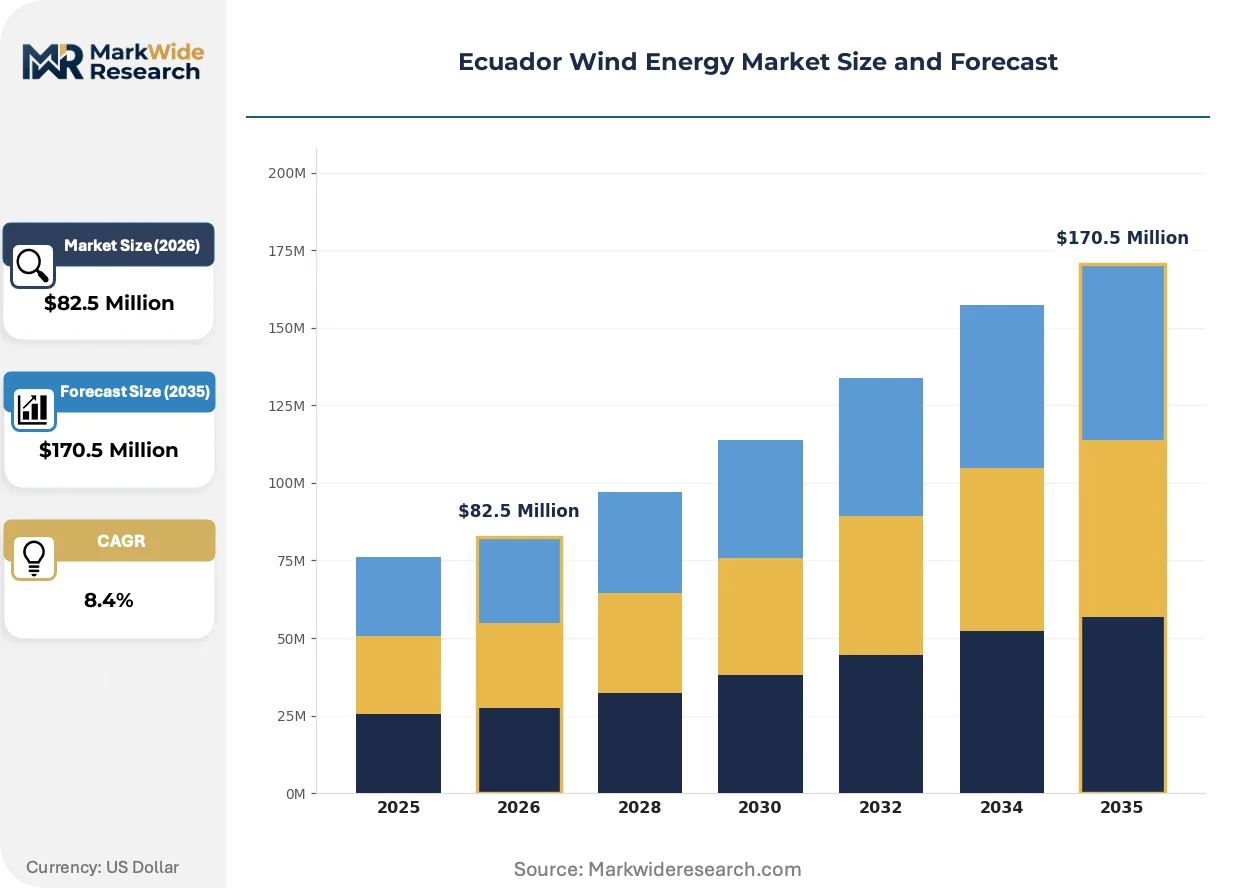
| Market Size in 2026 | $82.5 Million |
| Market Size in 2035 | $170.5 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Onshore Turbines, Offshore Turbines, Hybrid Systems, Small Wind Systems Technology: Vertical Axis, Horizontal Axis, Ducted Wind Turbines, Direct Drive Installation: Coastal, Mountainous, Urban, Rural End User: Utilities, Independent Power Producers, Commercial Users, Residential Customers |
| Companies Covered | Neoen SA, Siemens Gamesa Renewable Energy, Goldwind International Holdings (HK) Ltd, Vestas Wind Systems, Xinjiang Goldwind Science & Technology Co. Ltd, CELEC EP, Total Eren SA, Nordex Group, EDP Renovaveis SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ecuador Wind Energy Market Shifts & Advancements
Transport-optimized turbine configurations are disrupting traditional equipment procurement patterns in Ecuador's wind sector. Developers now prioritize modular nacelle designs that accommodate narrow mountain road constraints.
Horizontal-axis turbine technology is collapsing traditional gearbox-reliant architectures as direct-drive permanent magnet systems gain share in Loja Province installations. Remote Andean utilities are specifying these configurations to eliminate lubrication maintenance cycles. The shift is compressing operational expenditure budgets and extending turbine availability guarantees.
ARCONEL's evolving grid code standards are mandating enhanced frequency response capabilities for new wind interconnectors. Projects must now demonstrate synthetic inertia provision and voltage ride-through performance. Sierra region developers are retrofitting power converter specifications to meet these technical requirements ahead of commissioning deadlines.
Utility procurement teams are unbundling long-term service agreements from initial equipment supply contracts. CELEC EP and provincial distributors now negotiate operations and maintenance separately, enabling competitive tendering for post-warranty service provision. This behavioral shift is most pronounced in Loja and Azuay provinces where multi-project portfolios create scale economies for specialized service providers.
Ecuador Wind Energy Market Segmentation
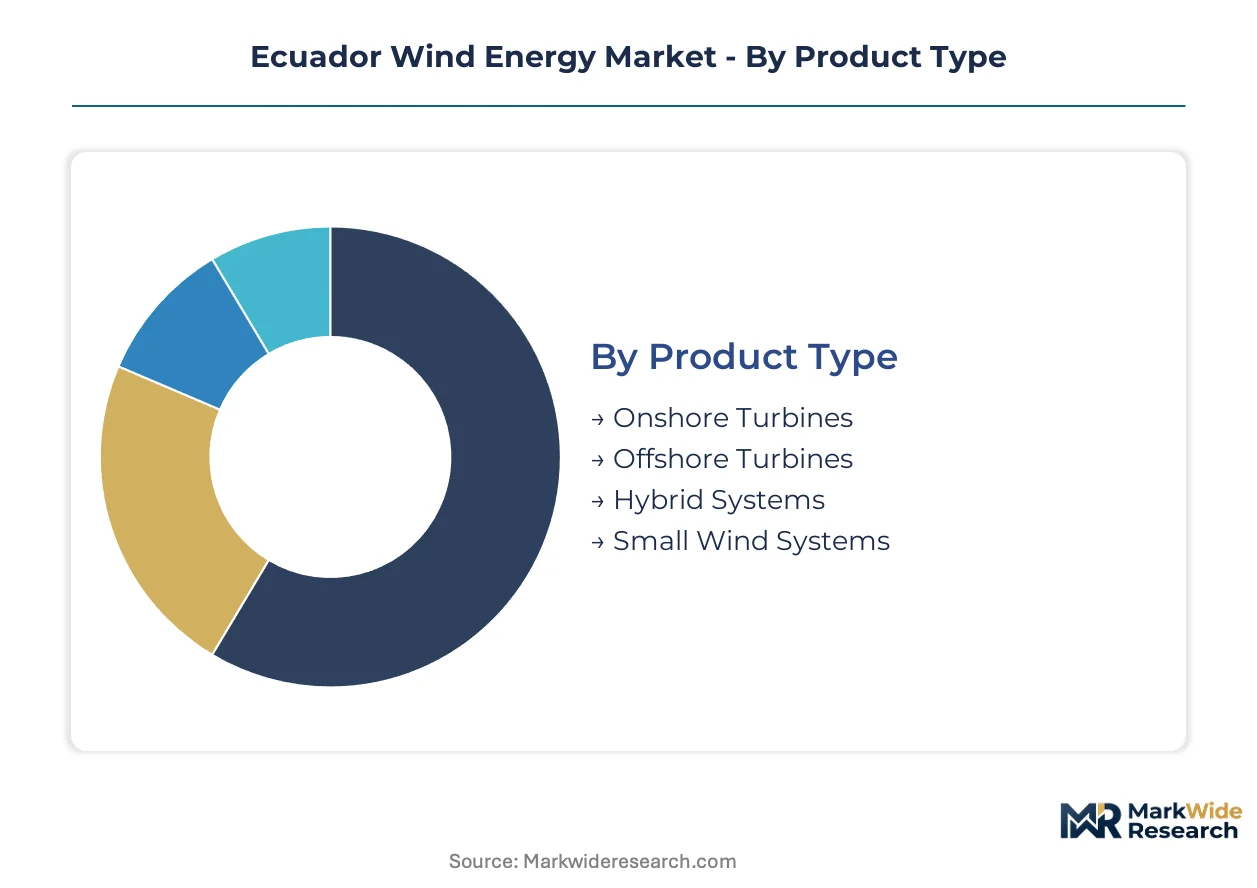
Ecuador's wind energy market segments across four critical dimensions that determine project economics, technology selection, and regulatory pathways. Understanding these divisions reveals where capital is concentrating and which configurations offer viable returns under Andean conditions.
Product Type:
Cost tier differentiation in turbine procurement separates grid-scale developments from distributed generation opportunities across Ecuador's Sierra and coastal zones.
- Onshore Turbines:Large-scale horizontal-axis units rated 1.5 MW to 3.5 MW dominate CELEC EP utility procurement. Loja Province developers favor these for established EPC supply chains and lower civil works requirements compared to alternative configurations.
- Hybrid Systems:Wind-photovoltaic pairing flattens generation profiles and maximizes grid connection utilization rates. Sierra region independent power producers are rotating into this configuration fastest as ARCONEL interconnection queues tighten.
- Offshore Turbines:No operational capacity exists; Esmeraldas and Manabí coastal studies remain pre-feasibility.
- Small Wind Systems:Sub-100 kW units serve isolated rural electrification programs in Azuay province.
Onshore turbines hold installed capacity. Hybrid systems are rotating up the share rankings.
Technology:
Application suitability drives technology selection, with terrain accessibility and maintenance logistics determining architecture preference.
- Horizontal Axis:Doubly-fed induction generators and direct-drive permanent magnet alternators constitute the dominant installed base. CELEC EP specifications favor these for grid synchronization stability under ARCONEL frequency response mandates.
- Direct Drive:Permanent magnet alternators eliminate gearbox maintenance cycles. Remote Andean utilities in Loja and Chimborazo specify these where lubrication service logistics prove prohibitive.
- Vertical Axis:Darrieus and Savonius configurations occupy niche urban demonstration projects in Quito metropolitan zone.
- Ducted Wind Turbines:Shrouded augmentor designs remain experimental; no commercial deployments operate.
Horizontal axis technology anchors current capacity. Direct drive architectures are rotating up the share rankings.
Installation:
Geography dictates wind resource quality, grid access economics, and transport logistics for equipment delivery.
- Mountainous:Andean highlands above 2,500 meters in Loja, Azuay, and Chimborazo provinces concentrate developer interest. High-altitude air density derating reduces nameplate capacity factors, compressing revenue projections for these installations.
- Coastal:Lower turbulence intensity in Manabí and Esmeraldas offers superior capacity factors versus high-altitude sites. Transmission infrastructure gaps currently constrain development timelines.
- Rural:Dispersed grid nodes in Sierra region provinces accommodate small-scale independent power producer interconnections.
- Urban:Building-integrated and rooftop configurations face zoning restrictions under municipal ordinances.
Mountainous installations hold installed capacity. Coastal zones are rotating up the share rankings.
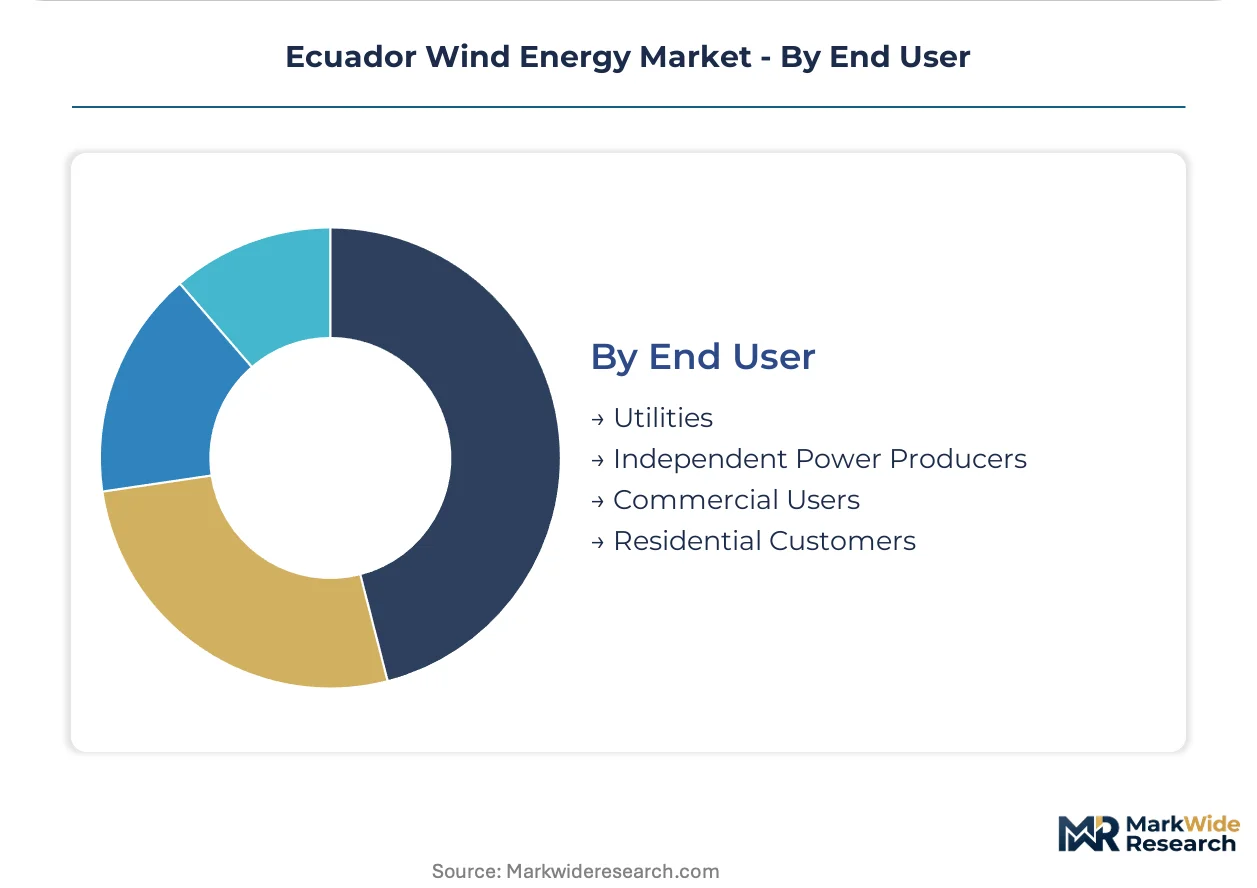
End User:
Customer type determines offtake structure, financing access, and regulatory compliance burden.
- Utilities:CELEC EP serves as primary offtaker through state-controlled power purchase agreements. The state-owned entity controls transmission access for most wind developments, creating queue dependencies for independent projects.
- Independent Power Producers:Private developers negotiate bilateral contracts with provincial distributors. Green credit line access from Ecuador's central bank improves project bankability for qualifying installations.
- Commercial Users:Corporate offtake agreements remain nascent; industrial consumers in Guayaquil manufacturing corridor evaluate direct procurement.
- Residential Customers:Net metering frameworks support distributed generation; penetration limited by grid code complexity.
Utility offtake holds installed capacity. Independent power producers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CELEC EP dominates offtake contracting across Ecuador's Sierra region, while provincial distributors in Azuay and Loja compete for independent power producer interconnections. Transmission access queues shape developer capital allocation toward grid-adjacent Andean corridors.
Loja Province
High-altitude wind resources above 2,500 meters attract concentrated developer interest despite air density derating effects on turbine output. The Ministry of Energy and Non-Renewable Natural Resources has streamlined concession licensing specifically for renewable projects in this corridor. Siemens Gamesa Renewable Energy and Vestas Wind Systems maintain active equipment procurement relationships with utilities serving the Loja-Azuay interconnection zone.
Azuay Province
Hybrid wind-photovoltaic configurations dominate new capacity additions as developers seek to flatten generation profiles and maximize grid connection utilization rates. ARCONEL's evolving grid code standards mandate enhanced frequency response capabilities for interconnectors in this province. The provincial capital Cuenca anchors service provider clustering for Andean wind operations and maintenance.
Chimborazo Province
Remote terrain accessibility challenges drive specification preference for direct-drive permanent magnet alternators that eliminate gearbox maintenance cycles. The central bank's green credit line improves project bankability for qualifying installations in this corridor. Riobamba serves as the logistical hub for modular nacelle transport into high-altitude installation sites.
Manabí Province
Unexploited coastal wind resources offer lower turbulence intensity and superior capacity factors compared to high-altitude Sierra sites. Transmission infrastructure gaps currently constrain development timelines despite resource quality advantages. Portoviejo and Manta represent emerging concentration points for pre-feasibility studies and coastal grid expansion planning.
Esmeraldas Province
Pre-feasibility studies for coastal wind development remain active as developers evaluate grid connection economics against Sierra region alternatives. CELEC EP's transmission access monopoly creates queue dependencies for independent projects in this zone. The city of Esmeraldas anchors northern coastal electrification planning and potential future interconnection infrastructure.
Ecuador Wind Energy Market Competitive Landscape
Channel-controlling players compete with product-specialist players for positioning in Ecuador's wind energy procurement landscape. CELEC EP's monopoly over Sierra region transmission infrastructure creates queue dependencies that shape developer equipment sourcing decisions. Three strategic archetypes dominate: state-controlled offtakers controlling interconnection access, global turbine OEMs with Latin American assembly footprints, and hybrid-focused independent power producers optimizing generation profiles. Competitive moves concentrate on long-term service agreement unbundling and modular transport configuration development.
Among global turbine OEMs with regional presence, Siemens Gamesa Renewable Energy, Vestas Wind Systems, and Goldwind International Holdings occupy positions representing distinct technology and service archetypes. Siemens Gamesa leverages Latin American nacelle assembly capabilities to reduce logistics costs for Andean projects. Vestas anchors regional service network positioning through operations contract relationships with Ecuadorian utilities. Goldwind represents the Chinese manufacturer archetype competing on modular direct-drive configurations suited to remote terrain maintenance constraints.
| Leading Market Players |
|---|
| Neoen SA |
| Siemens Gamesa Renewable Energy |
| Goldwind International Holdings (HK) Ltd |
| Vestas Wind Systems |
| Xinjiang Goldwind Science & Technology Co. Ltd |
| CELEC EP |
| Total Eren SA |
| Nordex Group |
| EDP Renovaveis SA |
| Others |
Supply & Pricing Matrix
The Guayaquil-Quito freight corridor's narrow mountain pass constraints amplify logistics premiums for nacelle deliveries, concentrating pricing power with OEMs possessing Latin American assembly footprints while forcing developers toward modular transport configurations that compress installation cost differentials across Sierra region projects.
Pricing Analysis
Cost-plus contracts indexed to steel and rare earth price benchmarks dominate CELEC EP utility procurement, with Siemens Gamesa and Vestas anchoring premium tiers through long-term service bundling while Goldwind competes on direct-drive standard configurations. Price differentiation rests on gearbox versus gearless architecture and ARCONEL grid code certification tier. Cost compression in the standard tier is intensifying as Chinese manufacturers expand modular nacelle offerings. Independent power producers exhibit highest price sensitivity due to green credit line collateral requirements, while state utilities prioritize availability guarantees over unit economics.
Supply Chain Analysis
Tariff exposure between Brazil and Ecuador dominates supply chain risk assessment for blade and tower imports, with nacelle assembly capacity clustering in Brazil, Argentina, and China creating currency fluctuation vulnerabilities for Andean project budgets. Raw material dependencies center on neodymium permanent magnets, carbon fiber composites, and high-grade steel forgings. Single-source vulnerability concentrates in gearbox components from European suppliers. Distribution runs through CELEC EP-controlled transmission queues, with provincial distributors managing last-mile interconnection logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ecuador's wind sector represents early-cycle expansion as Ministry of Energy permitting reforms compress development timelines and hybrid system adoption accelerates across Sierra region portfolios.
For Market Incumbents: Pre-empt modular direct-drive technology displacement by anchoring service network density in Loja and Azuay provinces before Goldwind scales regional technician training. Defend position against independent power producer vertical integration into hybrid EPC capabilities by locking multi-project O&M contracts with provincial distributors. CELEC EP transmission queue control remains the priority lever for margin protection.
For New Entrants and Emerging Players: Build out coastal wind development capabilities in Manabí and Esmeraldas ahead of transmission infrastructure expansion, as unexploited capacity factors there exceed Andean benchmarks. Target independent power producer segment penetration through green credit line facilitation partnerships with Ecuador's central bank. White-space concentration in direct-drive permanent magnet service specialization offers the most penetrable entry angle.
For Investors and Strategic Acquirers: Hybrid-focused independent power producers with secured ARCONEL interconnection queue positions represent the most attractive acquisition archetype for long-horizon exposure. Monitor CELEC EP auction mechanism evolution announcements as the inflection signal for offtaker risk reallocation and international equity participation thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Nacelle Transport Optimization | Reduces logistics costs for Siemens Gamesa and Vestas serving narrow Andean mountain roads. |
| Direct-Drive Technology Licensing | Goldwind's permanent magnet alternator configurations eliminate gearbox maintenance in remote Chimborazo terrain. |
| Hybrid Wind-Photovoltaic Development | Flattened generation profiles maximize grid connection utilization rates under ARCONEL interconnection queues. |
| Green Credit Line Facility Access | Ecuador's central bank dedicated lending improves project bankability for qualifying independent power producers. |
| Long-Term Service Agreement Unbundling | CELEC EP and provincial distributors now competitively tender post-warranty O&M separately from equipment supply. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with utility planning officers at CELEC EP, independent power producer project developers, EPC contractors serving Andean terrain, and grid operators managing Sierra region interconnection queues. Secondary validation drew from ARCONEL regulatory filings, Ministry of Energy concession licensing databases, central bank green credit facility disclosures, and customs import data for turbine component trade flows. Bottom-up project pipeline aggregation was triangulated against top-down capacity installation tracking.
Calibration against historical capacity addition patterns and announced project development timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include technology architecture, installation geography, end-user type, and project scale tier. CAGRs were derived from regression analysis of capacity deployment trajectories against regulatory milestone schedules and financing availability indicators. Forecast inputs incorporated ARCONEL grid code evolution scenarios and transmission expansion timeline probabilities.
Stress conditions across currency fluctuation bands, rare earth price volatility, and CELEC EP queue delay distributions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding Ministry of Energy permitting reform sustainability and green credit line facility continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Latin America Wind Turbine Market
Wind Energy Systems
Europe Small Wind Turbine Market
Wind Energy Systems
Norway Wind Energy Market
Wind Energy Systems
Wind Services Market
Wind Energy Systems
Wind Cones Market
Wind Energy Systems
Wind Speed Alarm Market
Wind Energy Systems
Wind Power Composite Market
Wind Energy Systems
Wind Blades NDT Market
Wind Energy Systems
Wind Power Converter Systems Market
Wind Energy Systems
Wind Energy Foundation Market
Wind Energy Systems
Canada Wind Energy Market
Wind Energy Systems
Wind Turbine Tower Market
Wind Energy Systems
Wind Turbine Pitch System Sales Market
Wind Energy Systems
Wind Turbine Pitch Systems Market
Wind Energy Systems
Global Offshore Wind Market
Wind Energy Systems
Japan Wind Energy Market