
 Europe Wind Power Market | 2026-2036
Europe Wind Power Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Wind Power Market Foresight
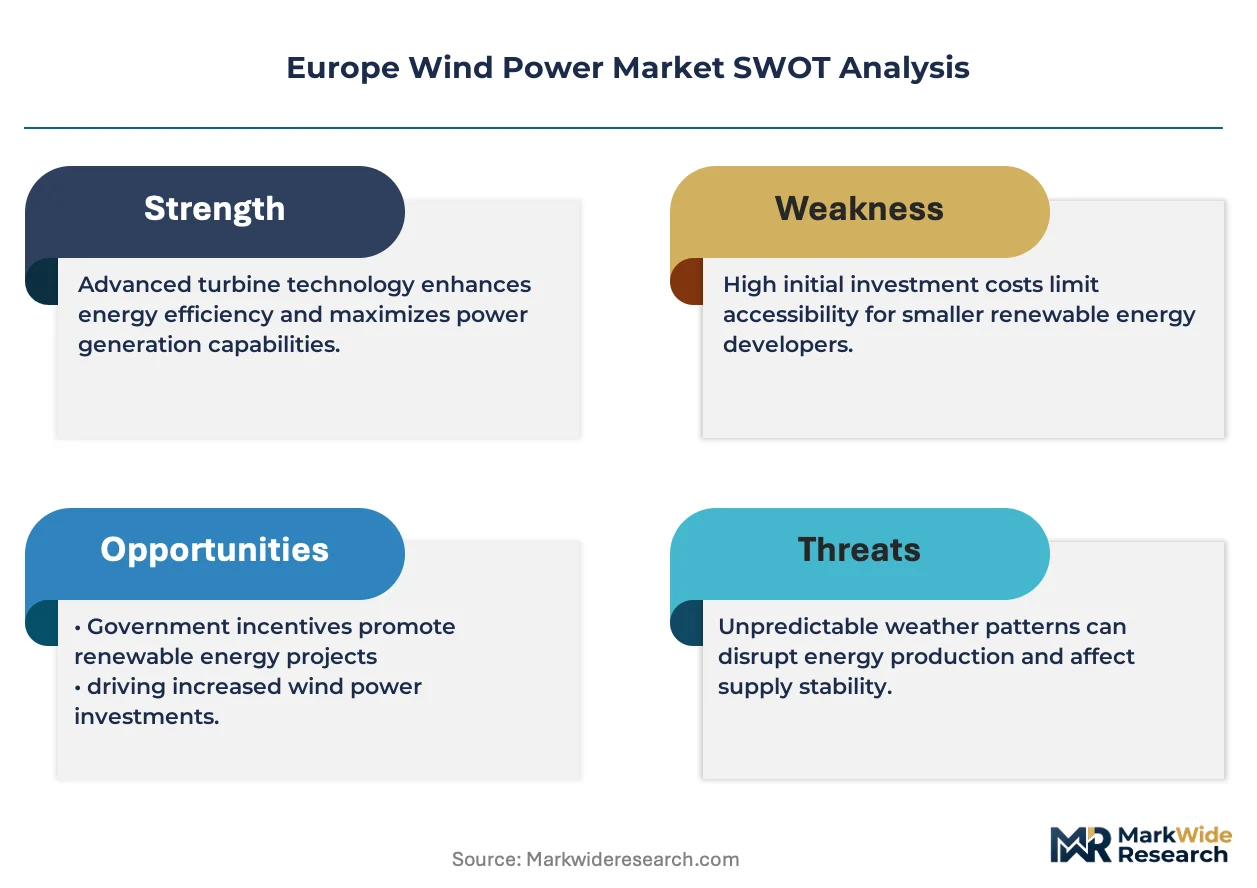
A shortage of certified offshore installation vessels and specialized turbine technicians is unwinding project timelines across the North Sea basin. Orsted AS leverages its Danish project pipeline and proprietary operations platform to sustain first-mover margins in offshore zones. Vestas Wind Systems AS anchors onshore manufacturing scale in Spain and Denmark, while Siemens Gamesa Renewable Energy competes through direct-drive offshore technology leadership.
Europe wind power encompasses electricity generation systems converting kinetic wind energy through horizontal-axis turbines with rotor diameters exceeding 220 meters for offshore units, delivering rated capacities from 15 MW upward to utility grids. Onshore technology dominates installed base economics, yet offshore deployment commands premium development margins due to higher capacity factors and seabed leasing scarcity. Utility-scale deployment attracts institutional capital pools, while distributed generation segments face interconnection queue bottlenecks. Independent power producers and government agencies represent contrasting end-user procurement profiles, with the former prioritizing merchant price exposure and the latter mandating local content requirements.
The EU Green Deal and REPowerEU framework shape national auction design and grid connection priority, while ECHA chemical compliance and CE marking govern turbine material standards and nacelle component market access. Germany's Federal Network Agency and the UK's Crown Estate wield direct influence over lease allocation and revenue cap mechanisms. Stakeholders must monitor seabed auction schedules against vessel delivery constraints to calibrate capital deployment timing.
Market Dynamics
Offshore wind deployment is reshaping European power markets through seabed scarcity and vessel bottlenecks that compress project timelines and inflate development premiums. The collision between REPowerEU targets and finite installation capacity creates a structural auction dynamic where lease access trumps turbine economics.
Growth Catalysts
- REPowerEU framework:The EU's emergency response to energy security mandates accelerated permitting timelines and grid connection priority for renewable projects across member states.
- German seabed leasing:The Federal Network Agency's auction rounds for North Sea zones attract utility capital through 20-year revenue certainty mechanisms.
- 15 MW turbine platforms:Next-generation offshore units with 220-meter rotors unlock capacity factors above 50% in North Sea wind regimes.
Market Restraints
- Installation vessel shortage:The North Sea basin operates with fewer than 15 certified jack-up vessels capable of handling 15 MW+ turbine components.
- Copper and rare earth dependency:Direct-drive permanent magnet generators rely on neodymium supply chains concentrated in Chinese processing facilities.
- Grid interconnection queues:Ten-year connection timelines in the United Kingdom and Germany strand consented projects without dispatch certainty.
Strategic Opportunities
- Baltic Sea expansion:Poland and Lithuania offer untapped seabed with lower vessel competition and shallower water depths reducing foundation costs.
- Power-to-X integration:Offshore wind sites paired with electrolyzer platforms capture premium green hydrogen offtake from German industrial clusters.
- Floating foundation trials:Demonstration projects in Portugal and Norway validate semi-submersible designs for water depths exceeding 60 meters.
Industry Challenges
- Certified technician scarcity:GWO safety training capacity constraints limit workforce scaling for turbine commissioning and blade repair operations.
- CE marking complexity:ECHA chemical compliance for blade composites and nacelle electronics extends component qualification timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Wind Power Market |
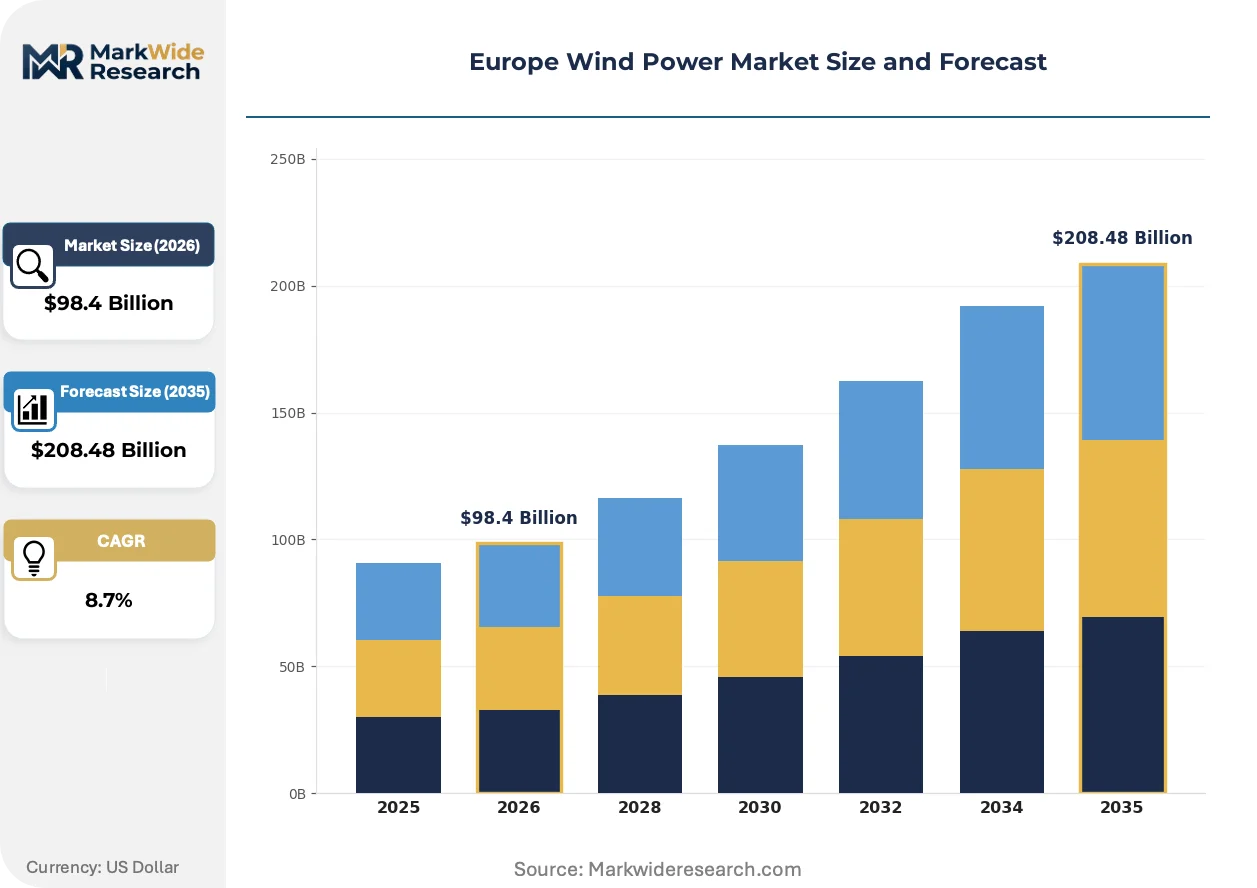
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $208.48 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Onshore, Offshore, Vertical Axis, Horizontal Axis Deployment: Utility Scale, Distributed Generation, Hybrid, Offshore Farms Application: Electricity Generation, Grid Support, Community Projects, Commercial Ventures End User: Utilities, Independent Power Producers, Industrial Users, Government Agencies |
| Companies Covered | Orsted AS, Vestas Wind Systems AS, Siemens Gamesa Renewable Energy, EDF SA, Acciona Energia SA, Nordex, GE Vernova, E.ON SE, Enercon, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Wind Power Market Shifts & Advancements
Turbine scaling and digital operations platforms are compressing levelized cost trajectories while regulatory pressure on supply chain provenance reshapes procurement standards across European utilities.
Direct-drive generator architectures is supplanting geared drivetrains in offshore applications above 12 MW. Orsted and RWE are specifying permanent magnet systems for 90% of new North Sea orders. This technology is supplanting conventional gearbox maintenance schedules and reducing nacelle weight by 15-20 tonnes.
The EU Green Deal's carbon border adjustment mechanism imposes embodied carbon disclosure requirements on imported steel and cement for turbine foundations. Danish and Dutch developers now mandate Environmental Product Declarations from sub-suppliers. German offshore projects face the strictest verification thresholds, driving backward integration into domestic steel sourcing.
Utility procurement teams are consolidating supplier panels from twelve to four preferred turbine OEMs per seabed zone. Long-term service agreements now bundle availability guarantees with predictive maintenance algorithms. This concentration is most visible in United Kingdom Round 4 and 5 auctions, where five developers submitted bids specifying single-source turbine supply.
Europe Wind Power Market Segmentation
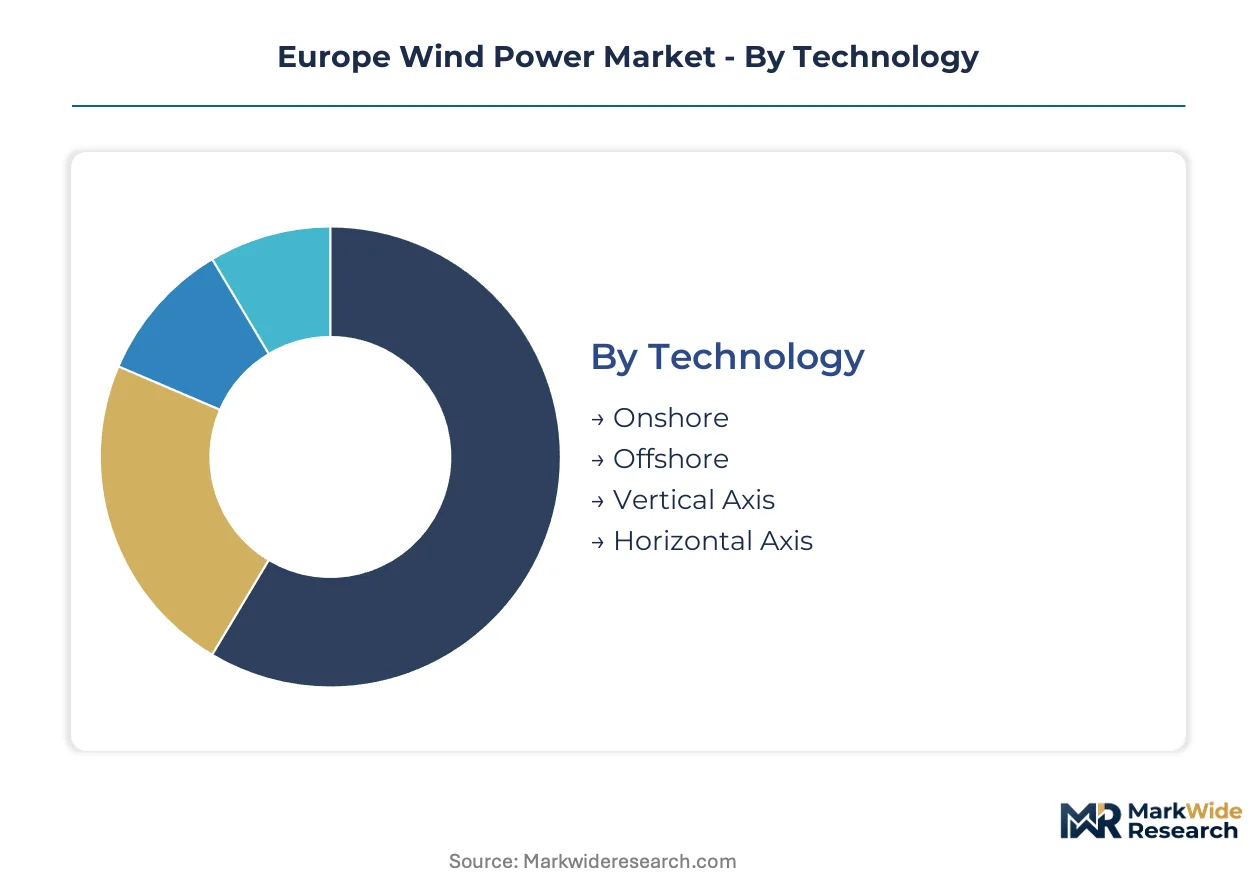
Technology and deployment configurations in European wind power map directly to regulatory incentive tiers and seabed access regimes. Understanding these segment boundaries reveals where capital allocation meets policy-driven revenue certainty mechanisms across member states.
Technology:
EU Green Deal funding thresholds and ECHA material compliance requirements create divergent qualification burdens across turbine architectures.
- Onshore:Horizontal-axis turbines with 3-6 MW ratings dominate installed capacity economics across Spain and Germany. German Federal Network Agency auctions prioritize repowering of aging fleets, while Spanish developers exploit streamlined environmental permitting for brownfield sites.
- Offshore:15 MW+ horizontal-axis units with 220-meter rotors unlock capacity factors exceeding 50% in North Sea wind regimes. UK Crown Estate lease rounds and Danish Energy Agency seabed allocations concentrate developer capital in zones with 20-year revenue mechanisms.
- Vertical Axis:Darrieus and Savonius designs serve distributed urban applications where noise and visual impact constraints block conventional installations.
- Horizontal Axis:Upwind three-blade configurations constitute the engineering standard for utility-scale deployment across all European climatic zones.
Established volume favors onshore; emerging adoption favors offshore.
Deployment:
Grid connection priority under REPowerEU creates tiered dispatch certainty that stratifies investment returns across scale categories.
- Utility Scale:Projects exceeding 100 MW capacity access priority interconnection queues and long-term power purchase agreements. German and UK transmission system operators mandate synchronous condenser capabilities for grid stability services.
- Offshore Farms:Seabed leasing in Danish, German, and UK waters commands premium development margins due to 50-year asset lifespans and scarcity of installation vessel capacity.
- Distributed Generation:Sub-5 MW installations face interconnection bottlenecks in France and Italy despite streamlined permitting under EU renewable energy directives.
- Hybrid:Co-located solar and battery storage configurations optimize land use constraints in Southern European markets with high solar irradiance.
Capital deployment concentrates in utility scale; regulatory tailwinds accelerate offshore farms.
Application:
Revenue model differentiation separates merchant-exposed generation from regulated tariff mechanisms across European power markets.
- Electricity Generation:Baseload and peak power supply to wholesale markets and bilateral offtake contracts. Nordic pool price exposure attracts financial investors seeking merchant risk premiums.
- Grid Support:Frequency regulation, voltage control, and black-start capabilities commanded by transmission system operators in Germany and the Netherlands.
- Community Projects:Citizen-owned cooperatives in Denmark and Germany leverage local content requirements and preferential feed-in tariffs.
- Commercial Ventures:Corporate power purchase agreements from industrial clusters seeking Scope 2 emissions reductions.
Wholesale market integration dominates electricity generation; sustainability mandates expand commercial ventures.
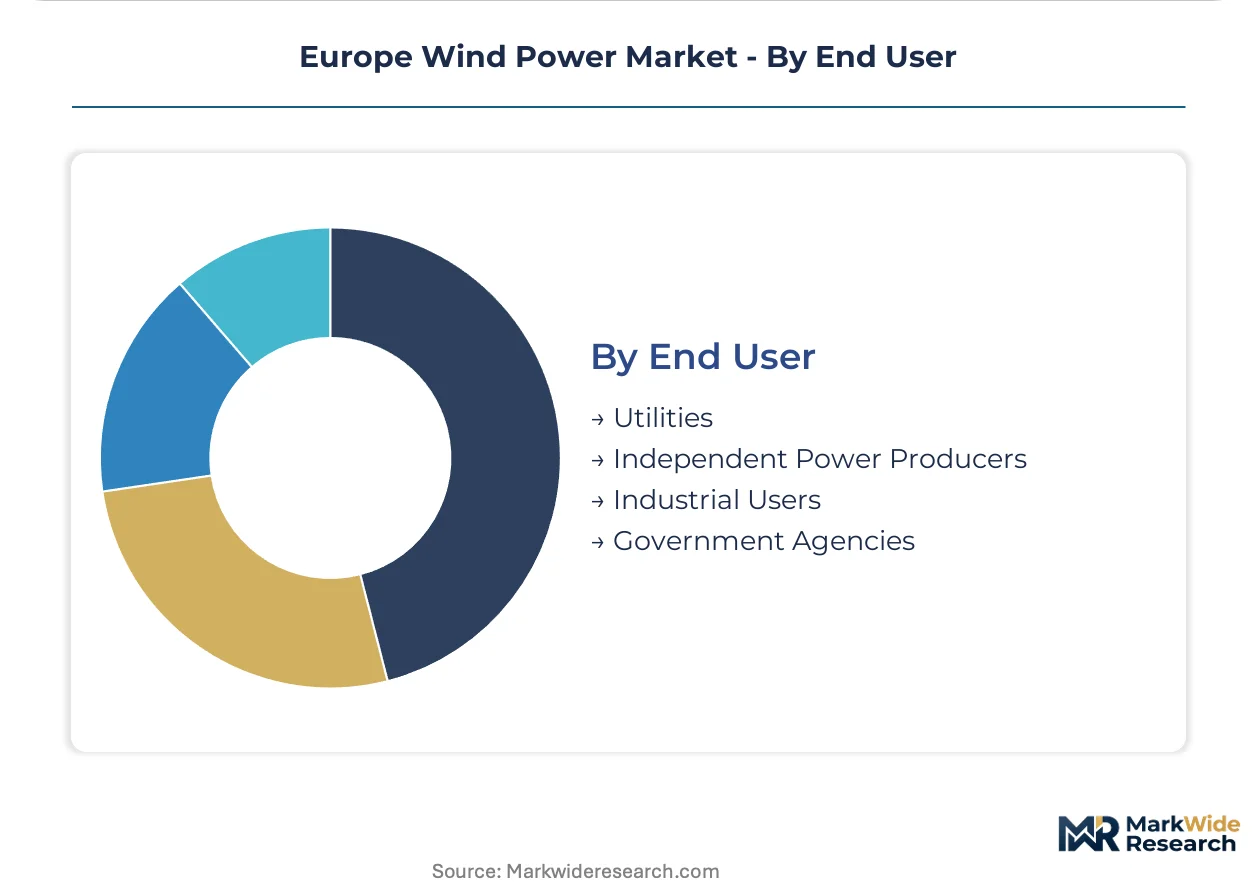
End User:
Procurement sophistication and risk tolerance separate institutional capital pools from public-sector procurement frameworks.
- Utilities:Vertically integrated operators like Orsted and RWE deploy balance-sheet capacity across multi-gigawatt development pipelines. German utilities prioritize offshore exposure for portfolio decarbonization targets.
- Independent Power Producers:Financial sponsors and infrastructure funds seek merchant price exposure and development-to-core monetization strategies.
- Industrial Users:Aluminum smelters and chemical manufacturers in Norway and Germany contract directly for green power offtake.
- Government Agencies:State-owned enterprises in France and Poland execute national energy security mandates through direct procurement.
Balance-sheet scale favors utilities; risk-return optimization attracts independent power producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal anchors deployment trajectories across member states, with national regulators calibrating auction design to vessel availability and grid connection timelines. Member state divergence in permitting speed and seabed access creates tiered investment climates that stratify developer capital allocation.
Germany
North Sea seabed leasing rounds by the Federal Network Agency attract utility capital through 20-year revenue certainty mechanisms. The Onshore Wind Energy Act mandates streamlined permitting for repowering aging fleets. Industrial clusters in Lower Saxony and Schleswig-Holstein host turbine component fabrication and port staging infrastructure for installation vessels.
United Kingdom
The Crown Estate's Round 4 and 5 lease allocations concentrate developer bidding around single-source turbine supply commitments. Contracts for Difference auctions prioritize projects with synchronous condenser capabilities for grid stability services. Scottish waters host floating foundation trials validating semi-submersible designs for water depths exceeding 60 meters.
Denmark
The Danish Energy Agency allocates seabed through tender rounds that reward early-mover developers with proprietary operations platforms. Local content requirements under EU renewable energy directives strengthen community-owned cooperative participation. Copenhagen and Esbjerg anchor installation vessel homeporting and blade manufacturing supply chains.
Spain
Streamlined environmental permitting for brownfield onshore sites accelerates repowering of aging 2-3 MW turbine fleets. The national integrated energy and climate plan mandates 50 GW wind capacity by 2030. Aragon and Castile-La Mancha host utility-scale developments exploiting high wind resource corridors with lower land use competition.
Poland
Baltic Sea seabed auctions offer untapped development potential with shallower water depths reducing foundation costs compared to North Sea zones. The Offshore Wind Act establishes grid connection priority and CfD mechanisms for first-mover projects. Port infrastructure expansion in Gdańsk and Świnoujście targets installation vessel servicing and nacelle component staging.
Europe Wind Power Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European wind power market. The vendor base concentrates around vertically integrated utilities with development pipelines and specialized turbine OEMs with manufacturing scale. Three archetypes dominate: balance-sheet-backed developers securing seabed leases, direct-drive technology specialists, and repowering-focused onshore manufacturers. Competitive moves center on long-term service agreement bundling and backward integration into domestic steel sourcing for foundation supply.
Among Danish and German developers, Orsted AS and E.ON SE exemplify the integrated utility archetype combining project origination with proprietary operations platforms. Vestas Wind Systems AS and Siemens Gamesa Renewable Energy occupy positions as turbine technology anchors, with the former representing onshore manufacturing scale and the latter direct-drive offshore specialization. These four entities collectively illustrate how European wind power competition stratifies between lease-access developers and component-scale manufacturers.
| Leading Market Players |
|---|
| Orsted AS |
| Vestas Wind Systems AS |
| Siemens Gamesa Renewable Energy |
| EDF SA |
| Acciona Energia SA |
| Nordex |
| GE Vernova |
| E.ON SE |
| Enercon |
| Others |
Supply & Pricing Matrix
EU Green Deal carbon border adjustment mechanisms gate both turbine component market access and price differentiation across European wind power procurement. ECHA chemical compliance for blade composites and nacelle electronics extends qualification timelines while German and Danish developers mandate Environmental Product Declarations that stratify supplier tiers.
Pricing Analysis
German North Sea projects command 15-25% development premiums over Baltic Sea equivalents due to Federal Network Agency revenue certainty mechanisms and scarcer seabed allocation. Contract structures stratify across availability-guaranteed long-term service agreements, merchant-exposed merchant offtake, and regulated feed-in tariffs. Cost compression in onshore repowering segments intensifies as Spanish and German auction designs prioritize lowest-cost bids. Independent power producers exhibit highest price sensitivity due to merchant risk exposure, while utility balance-sheet developers absorb premium pricing for operational certainty.
Supply Chain Analysis
Installation vessel component lead times now stretch 36-48 months, constraining project sequencing across the North Sea basin. Manufacturing concentrates in Denmark, Spain, and Germany for nacelle assembly and blade fabrication, while rare earth processing for direct-drive generators draws from Chinese facilities. Single-source vulnerability in neodymium supply chains creates tariff exposure risk under evolving EU-China trade frameworks. Distribution runs through port staging infrastructure at Esbjerg, Cuxhaven, and Hull, with specialized heavy-lift capabilities determining downstream access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe wind power is cycling through a vessel-constrained expansion phase where installation capacity rather than turbine economics limits deployment velocity. REPowerEU grid connection priority and accelerated permitting timelines provide the cyclical uplift.
For Market Incumbents: Secure long-term vessel charter agreements before 2027 delivery windows close, locking in installation capacity that emerging competitors cannot replicate. Deepen backward integration into domestic steel sourcing for foundation supply to meet German carbon border adjustment thresholds. Orsted and RWE demonstrate this path through proprietary operations platforms and captive fabrication capacity.
For New Entrants and Emerging Players: Anchor in Polish and Lithuanian Baltic Sea zones where shallower water depths reduce foundation costs and vessel competition remains thinner than North Sea corridors. Target community-owned cooperative structures in Denmark where local content requirements create procurement preferences. Differentiate through floating foundation demonstration capabilities for water depths exceeding 60 meters.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across offshore farm development as 15 MW turbine platforms and specialized installation vessels concentrate deployment scale. Long-term viability favors vertically integrated developers with multi-gigawatt pipelines and proprietary O&M platforms over pure-play turbine OEMs. Monitor seabed auction schedule density against vessel delivery constraints as the inflection signal for capital deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Installation Vessel Long-term Charter | Locks in scarce jack-up capacity ahead of 2027 delivery windows across North Sea zones. |
| Domestic Steel Backward Integration | Secures Environmental Product Declaration compliance for German carbon border adjustment thresholds. |
| Floating Foundation Demonstration | Validates semi-submersible designs for Portuguese and Norwegian water depths exceeding 60 meters. |
| Power-to-X Electrolyzer Integration | Captures green hydrogen offtake from German industrial clusters seeking Scope 2 reductions. |
| Predictive Maintenance Platform Licensing | Bundles availability guarantees with digital operations for UK Round 4 and 5 auction bids. |
Research Methodology
Desk research of EU regulatory filings, seabed auction databases, and ECHA chemical compliance registries preceded structured interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Secondary validation drew from Crown Estate lease round documentation, Federal Network Agency auction results, and IEA renewable deployment tracking. Bottom-up project pipeline aggregation triangulated against top-down member state capacity targets.
Variance decomposition across technology, deployment scale, and regulatory framework segments shaped analytical framework construction over the projection horizon. Modeled dimensions span onshore-offshore technology split, utility scale versus distributed generation capacity tiers, and national auction design clusters. CAGRs derived from seabed allocation schedules, vessel delivery constraints, and grid connection queue progression. Forecast inputs incorporated REPowerEU permitting acceleration timelines and ECHA material compliance phase-in curves.
Decision-makers should treat outputs as directional under sustained REPowerEU implementation and vessel supply normalization assumptions; material deviation in either would warrant model refresh. Specific risks include Chinese rare earth export restrictions, prolonged UK grid interconnection delays, and Baltic Sea seabed environmental challenges. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Power Market
Wind Energy Systems
France Wind Energy Market
Wind Energy Systems
Medium-Speed Permanent Magnet Wind Turbine Generator System Market
Wind Energy Systems
Wind Turbine Pitch Systems Market
Wind Energy Systems
Double-Fed Wind Turbine Market
Wind Energy Systems
Wind Turbine Forged Tower Flange Market
Wind Energy Systems
India Wind Industry Market
Wind Energy Systems
Quiet Wind Turbine Market
Wind Energy Systems
Wind Blades NDT Market
Wind Energy Systems
Wind Turbine Brakes Market
Wind Energy Systems
Wind Tower Market
Wind Energy Systems
Offshore Wind Turbine Blade Leading-Edge Defect Inspection Equipment Market
Wind Energy Systems
Netherlands Wind Energy Market
Wind Energy Systems
Wind Turbine Yaw and Pitch Gearbox Market
Wind Energy Systems
Offshore Wind Cable Market
Wind Energy Systems
South America Wind Power Market