
 Peru Wind Energy Market | 2026-2036
Peru Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Peru Wind Energy Market Analytics
Turnkey-to-split procurement is hardening as the dominant configuration pattern across Peruvian wind development. Grenergy Renovables SL leverages its European engineering pedigree to compete for engineering-procurement-construction contracts. Enel Green Power S.p.A. anchors the installed base through operational dominance in southern Peru. Engie Energía Perú differentiates via hybrid system integration with existing thermal assets.
Peru wind energy encompasses the generation of electrical power through aerodynamic conversion of kinetic wind energy by rotor-driven generators, with modern onshore turbines typically rated between 2.5 MW and 4.5 MW and hub heights exceeding 80 meters to capture stronger, more consistent wind streams above ground-level friction layers. Horizontal axis turbines dominate utility-scale deployment due to higher aerodynamic efficiency and proven reliability in coastal wind regimes, while vertical axis configurations occupy niche remote energy supply roles where omnidirectional wind capture reduces mechanical complexity. Application segmentation shows utility-scale projects commanding capital deployment volumes, whereas distributed generation segments sustain faster development timelines by bypassing transmission congestion in the southern mining belt.
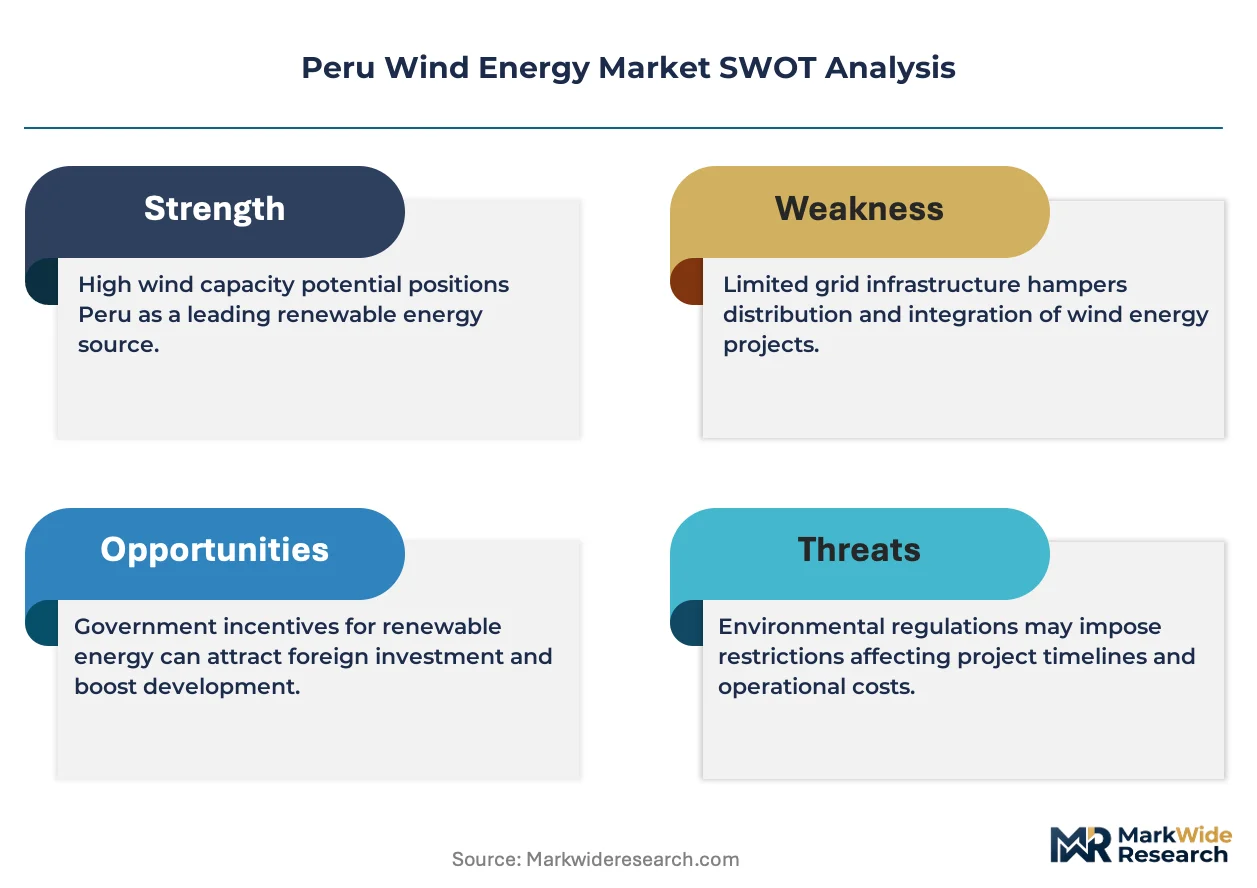
OSINERGMIN regulates grid access tariffs and dispatch priority for renewable generators under Peru's renewable energy law framework, while the Ministry of Energy and Mines sets capacity auction schedules that directly determine project pipeline visibility. Environmental certification through the national environmental certification system (SEIA) shapes site feasibility timelines and mitigation costs for coastal and Andean installations. Stakeholders must monitor auction design evolution and transmission expansion commitments to assess project bankability beyond current pipeline visibility.
Market Dynamics
OSINERGMIN's renewable energy auction framework is compressing project development timelines while concentrating capital deployment along Peru's coastal wind corridors, forcing developers to secure transmission access ahead of site certification.
Growth Catalysts
- OSINERGMIN Auction Rules:The regulator's capacity auction schedule creates pipeline visibility that enables long-term power purchase agreements with mining and industrial offtakers in the Andean region.
- Coastal Wind Resource Quality:The Ica and Lambayeque corridors offer capacity factors exceeding regional averages, attracting utility-scale investment from international developers seeking bankable sites.
- Mining Electrification Mandates:Peruvian mining operators face diesel cost volatility and carbon disclosure pressures, driving demand for firm renewable power at remote Andean extraction sites.
Market Restraints
- Transmission Bottlenecks:Grid congestion in southern Peru limits dispatch capacity for new wind farms, requiring costly transmission expansion commitments before project financial close.
- SEIA Certification Delays:Peru's national environmental certification system imposes multi-year timelines for coastal and highland sites, extending pre-construction periods and carrying costs.
- Geographic Concentration Risk:Project development clusters in two coastal corridors, creating competition for finite grid connection capacity and skilled construction labor pools.
Strategic Opportunities
- Hybrid System Integration:Wind-solar-battery configurations at mining sites in southern Peru offer dispatchable renewable power that displaces diesel generation in remote locations.
- Andean Distributed Generation:Smaller-scale turbines bypass transmission constraints by serving isolated mining camps and agricultural processing facilities in the southern highlands.
- Green Hydrogen Feedstock:Peru's renewable energy law amendments may enable wind-powered electrolysis projects targeting export markets and domestic ammonia production.
Industry Challenges
- Grid Integration Expertise Gap:Local engineering capacity for variable renewable integration with Peru's isolated grid zones remains insufficient for accelerated deployment timelines.
- Equipment Logistics Complexity:Turbine component transport from Pacific ports to Andean sites requires specialized heavy-haul infrastructure that is underdeveloped in mountain corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peru Wind Energy Market |
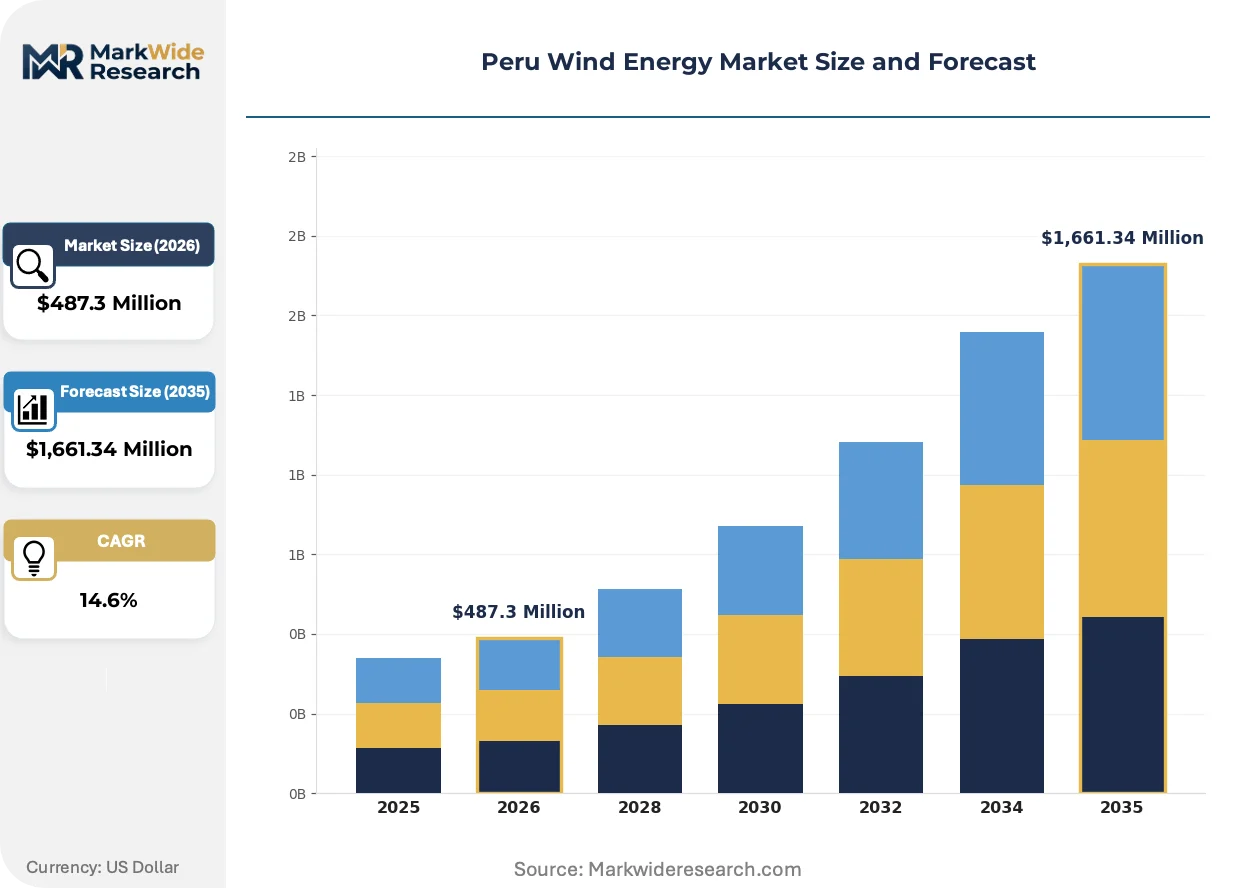
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,661.34 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Axis Turbines, Vertical Axis Turbines, Offshore Turbines, Onshore Turbines Application: Utility Scale, Distributed Generation, Hybrid Systems, Remote Energy Supply End User: Government, Private Sector, Energy Providers, Industrial Users Installation Type: Ground-Mounted, Roof-Mounted, Floating, Integrated |
| Companies Covered | Grenergy Renovables SL, Orygen Perú, Enel Green Power S.p.A., Engie Energía Perú, Kallpa Generación, ContourGlobal PLC, Acciona, S.A., Fenix Power, Cobra Group PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peru Wind Energy Market Evolving Landscape
Peru's wind sector is experiencing rapid technology adaptation as auction pressure and mining demand reshape equipment specifications and project architectures.
Advanced turbine control systems is automating blade pitch and yaw optimization to maximize capture in Peru's variable coastal wind regimes. Mining operators with 24-hour power requirements are adopting these systems fastest, seeking to minimize curtailment and maximize offtake volumes. This automation is compressing the performance gap between established European turbine platforms and newer Asian entrants in Peruvian procurement evaluations.
OSINERGMIN's dispatch priority rules for renewable generators are altering merchant revenue calculations for wind farm developers. The regulation guarantees grid access but exposes projects to spot price volatility during high-renewable penetration hours. Utility-scale projects in the Ica corridor are responding by pursuing hybrid configurations that shift output to peak price periods.
Turnkey contracting is displacing split procurement as the dominant development model among international entrants. European engineering firms with Andean experience are capturing engineering-procurement-construction mandates that local developers previously fragmented across multiple contractors. This consolidation is most visible in southern Peru where mining-linked projects demand single-point accountability for schedule and performance guarantees.
Peru Wind Energy Market Segmentation
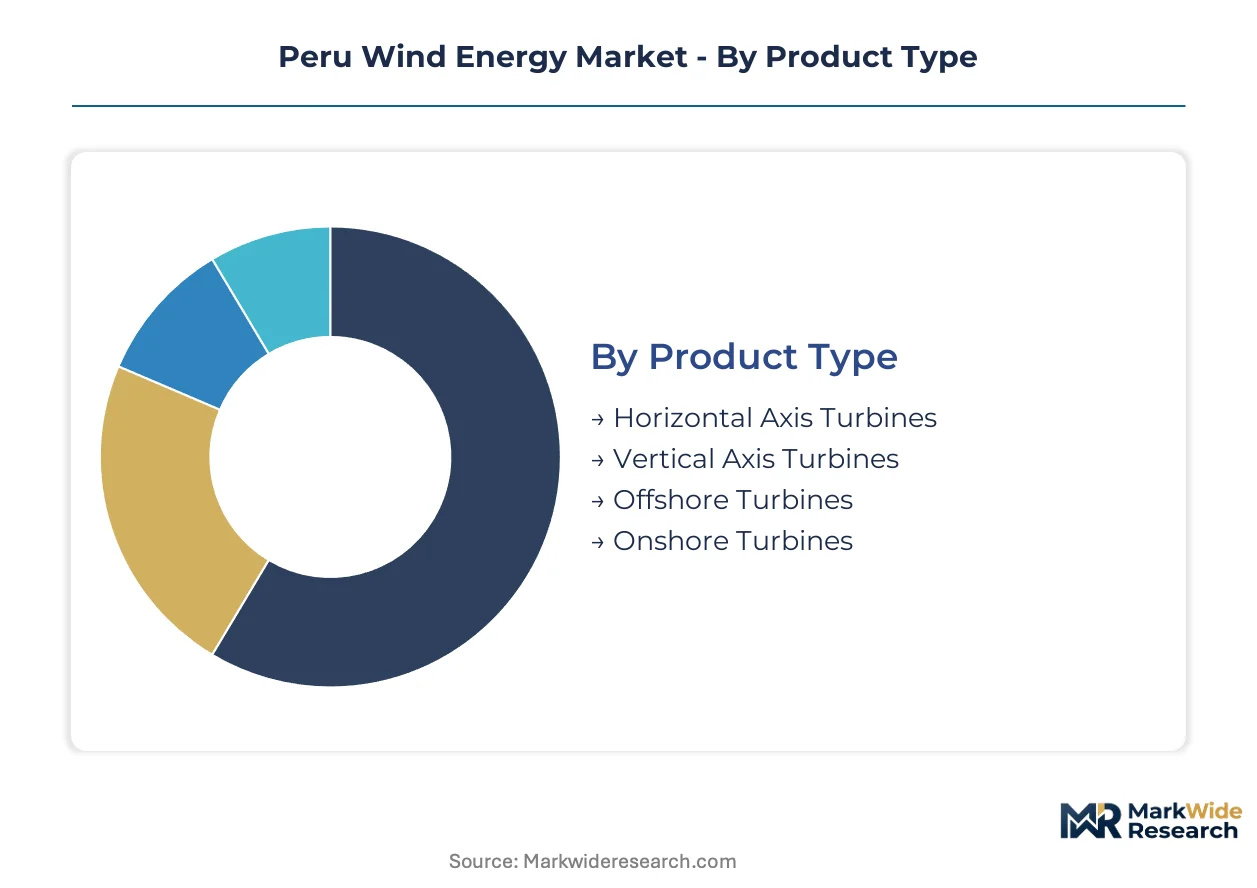
Peru's wind energy segmentation reflects the tension between utility-scale coastal development and distributed solutions for mining electrification. Auction rules and transmission constraints reshape how buyers evaluate equipment specifications and installation approaches.
Product Type:
Buyers prioritize aerodynamic efficiency and proven reliability in coastal wind regimes when selecting turbine configurations.
- Horizontal Axis Turbines:These configurations dominate utility-scale deployment through higher aerodynamic efficiency and rotor-driven generator optimization. OSINERGMIN auction winners in the Ica corridor specify these units for their capacity factor advantages and established maintenance protocols.
- Onshore Turbines:Modern units rated between 2.5 MW and 4.5 MW with hub heights exceeding 80 meters capture stronger wind streams above ground-level friction layers. The Lambayeque corridor attracts these installations where flat coastal terrain reduces foundation complexity and grid connection costs.
- Vertical Axis Turbines:Omnidirectional wind capture reduces mechanical complexity for remote mining camps in the southern Andes.
- Offshore Turbines:Pacific coastal depth gradients limit near-term deployment despite strong marine wind resources.
Horizontal axis turbines lead on scale; onshore turbines lead on momentum in auction-driven procurement.
Application:
Capital deployment volume concentrates where transmission access and offtake certainty align.
- Utility Scale:Projects commanding the largest capital volumes concentrate in the Ica and Lambayeque coastal corridors where wind resource quality attracts international developers. These installations require SEIA certification and secured grid connection before financial close.
- Hybrid Systems:Wind-solar-battery configurations at mining sites in southern Peru offer dispatchable renewable power that displaces diesel generation. Engie Energía Perú differentiates through thermal asset integration in these configurations.
- Distributed Generation:Smaller-scale development timelines bypass transmission congestion in the southern mining belt.
- Remote Energy Supply:Isolated Andean extraction sites drive demand for self-contained generation without grid dependency.
Utility scale leads on scale; hybrid systems lead on momentum in mining-linked procurement.
End User:
Procurement authority shifts between public auction mechanisms and private offtake negotiations.
- Industrial Users:Mining operators in the Peruvian Andes expanding wind-powered electrification to reduce diesel dependence represent the most visible demand concentration. These buyers require 24-hour power and prioritize automation systems that minimize curtailment.
- Energy Providers:Utility-scale developers competing in OSINERGMIN auctions secure long-term power purchase agreements that reshape project bankability calculations.
- Private Sector:Agricultural processors and manufacturing facilities in coastal zones seek renewable energy certificates.
- Government:Public procurement for rural electrification programs drives smaller-scale installations in highland communities.
Industrial users lead on scale; energy providers lead on momentum in auction pipeline development.
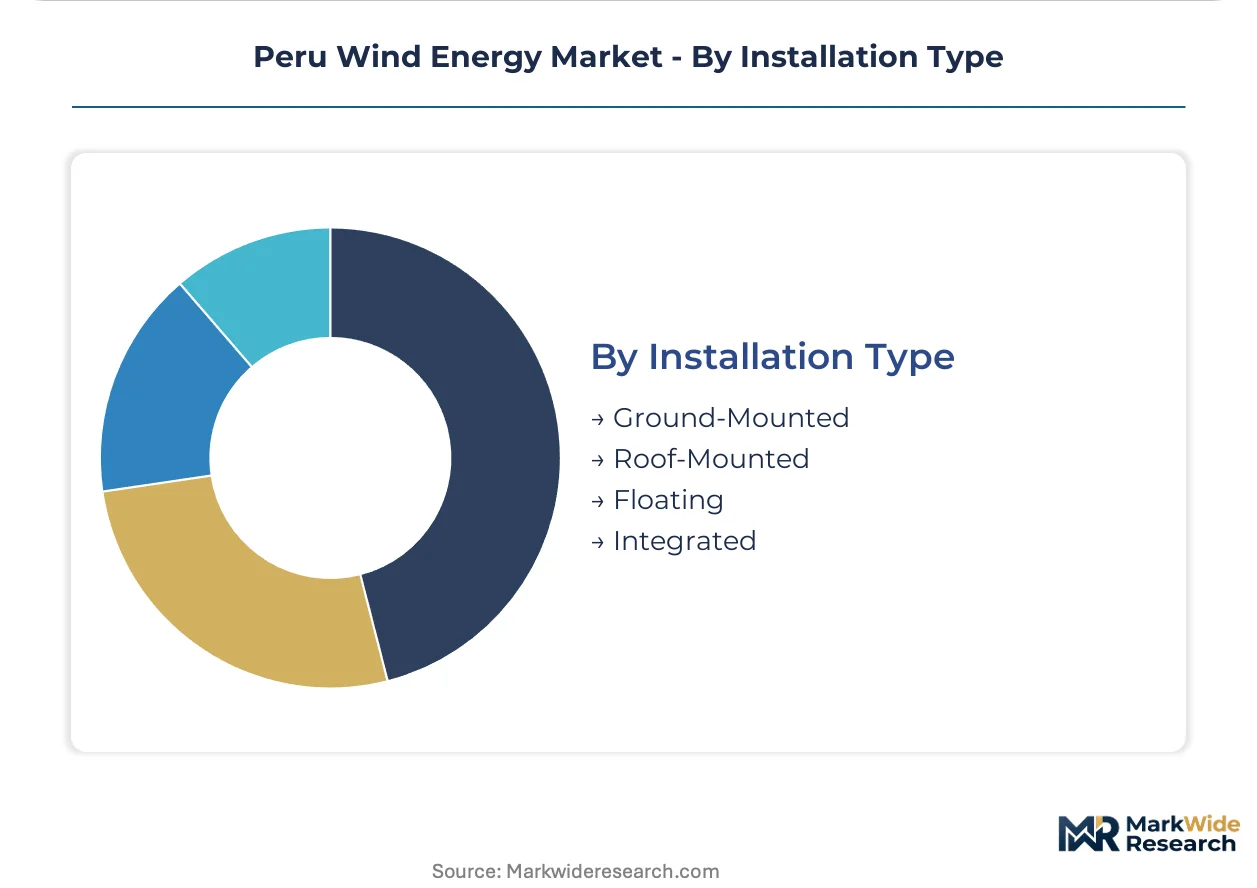
Installation Type:
Foundation and mounting decisions follow terrain constraints from coastal plains to Andean elevations.
- Ground-Mounted:Standard foundation systems dominate the Ica and Lambayeque corridors where flat coastal terrain simplifies civil works. These installations support the largest turbine ratings and enable streamlined heavy-haul logistics from Pacific ports.
- Integrated:Hybrid system architectures combine wind generation with solar arrays and battery storage at mining sites. These configurations require single-point accountability for performance guarantees that turnkey contractors like Grenergy Renovables provide.
- Roof-Mounted:Limited application for small-scale agricultural processing facilities in coastal agricultural zones.
- Floating:Pacific coastal depth profiles restrict near-term deployment despite theoretical wind resource advantages.
Ground-mounted leads on scale; integrated installations lead on momentum in hybrid system adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peru's wind energy sector traces its modern origins to coastal pilot projects in the early 2000s that demonstrated capacity factors exceeding regional benchmarks. OSINERGMIN's auction framework subsequently concentrated development in identifiable geographic corridors with verified wind resources.
Ica Corridor
Paracas wind farms anchor Peru's largest operational capacity with consistent coastal wind streams. OSINERGMIN's 2022 renewable energy auction allocated significant capacity to this zone. The Paracas-Nazca sub-region hosts multiple utility-scale installations serving mining offtakers through dedicated transmission lines.
Lambayeque Region
Flat terrain near Chiclayo reduces civil works complexity for turbine foundations. Peru's Ministry of Energy and Mines designated this northern corridor for accelerated environmental permitting under streamlined SEIA protocols. The Olmos irrigation district periphery attracts hybrid wind-solar proposals from international developers.
Arequipa and Moquegua
Southern mining electrification demand concentrates in the Andean highlands above these coastal departments. Distributed generation projects bypass grid congestion by serving isolated copper extraction sites. Tacna's border proximity creates logistics advantages for equipment import from Chilean ports.
Ancash and La Libertad
Central coastal wind mapping identifies untapped resource zones between established corridors. Regional governments in Huaraz and Trujillo promote renewable industrial parks to attract energy-intensive processing facilities. The Huarmey-Casma coastal strip awaits transmission expansion commitments from the national grid operator.
Peru Wind Energy Market Competitive Landscape
The competitive structure tilts toward European engineering specialists with Andean project experience. Turnkey contracting dominance concentrates accountability among a handful of international firms capable of performance guarantees. Two strategic archetypes define the field: auction-optimized utility-scale developers and mining-integrated hybrid system providers. Competitive moves center on transmission access pre-positioning and hybrid technology partnerships that secure dispatchable renewable contracts.
Among Spanish-origin renewable developers, Grenergy Renovables SL and Acciona, S.A. represent the engineering-procurement-construction archetype with European project pedigrees. Italian utility-backed Enel Green Power S.p.A. anchors the operational base through southern Peru installations. French multinational Engie Energía Perú exemplifies the hybrid integration specialist, positioning around thermal asset coordination capabilities. These three occupy distinct competitive vectors without direct overlap in procurement positioning.
| Leading Market Players |
|---|
| Grenergy Renovables SL |
| Orygen Perú |
| Enel Green Power S.p.A. |
| Engie Energía Perú |
| Kallpa Generación |
| ContourGlobal PLC |
| Acciona, S.A. |
| Fenix Power |
| Cobra Group PLC |
| Others |
Value Network & Pricing Analysis
Mining operators' 24-hour power requirements and automation system mandates are forcing turbine suppliers to bundle advanced control software with hardware, compressing margins on base equipment while creating premium pricing tiers for integrated performance guarantees. This demand-side specification shift concentrates pricing power among European engineering firms capable of single-point accountability, while Asian manufacturers compete on stripped-down unit economics.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates Peruvian wind procurement, with differentiation driven by turbine automation grade and after-sales service bundling. Premium tiers command substantial markups for mining-linked projects requiring guaranteed availability, while standard configurations serve auction-driven utility developers with tighter capital constraints. Cost compression in economy tiers is intensifying because Chinese manufacturers are penetrating coastal corridor auctions with simplified control architectures. Mining operators show least price sensitivity due to diesel displacement economics, whereas agricultural offtakers in coastal zones exhibit highest sensitivity to upfront capital outlays.
Supply Chain Analysis
Single-source vulnerability sits with Chinese gearbox and generator component suppliers who anchor tier-one turbine manufacturing. Nacelle assembly draws from Spain, Denmark, and China, while blade production rests on German resin systems and Brazilian fiberglass supply. Logistics chokepoints at Pacific port-to-Andean heavy-haul corridors create delivery risk for oversized tower sections. Distribution runs through EPC contractors with established Andean construction experience rather than direct manufacturer-to-developer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peru's wind market has transitioned into a late-cycle quality phase where mining electrification mandates reward premium specifications over lowest-bid procurement. This demand-shift toward automated, dispatchable renewable systems favors suppliers with integrated hybrid capabilities.
For Market Incumbents: Anticipate margin compression from Chinese turbine entrants by deepening backward integration into blade manufacturing and securing captive tower fabrication capacity in northern Peru. Reinforce position through SEIA certification expertise that accelerates project timelines for mining offtakers. The priority lever sits with transmission access pre-positioning ahead of auction announcements. For New Entrants and Emerging Players: Capture white-space in Andean distributed generation below 10 MW, where grid bypass requirements and diesel displacement economics create penetrable demand. The southern mining belt around Arequipa offers fastest development timelines without transmission queue competition. A go-to-market angle through equipment leasing rather than capital sale reduces buyer upfront burden. For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid system integrators possessing thermal coordination capabilities and existing mining relationships. Long-term viability hinges on exposure to firm renewable power contracts rather than merchant spot price exposure. Watch OSINERGMIN auction design evolution as the inflection signal for pipeline visibility and bankability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid System Integration | Wind-solar-battery configurations at mining sites displace diesel and command premium tariffs. |
| Transmission Access Pre-positioning | Early grid connection commitments in Ica and Lambayeque corridors secure auction-winning positions. |
| Turnkey EPC Consolidation | Single-point accountability contracts reduce developer risk and accelerate financial close timelines. |
| Andean Distributed Generation | Smaller turbines bypass grid congestion and serve isolated extraction sites with faster permitting. |
| Green Certification Investment | SEIA expertise differentiation compresses pre-construction periods and reduces carrying costs. |
Research Methodology
Coverage spans coastal wind corridors and Andean mining regions, with primary inputs from each zone combined with secondary validation. Interviews with IPP project developers, EPC contractors, utility planning officers, and mining energy procurement leads informed demand-side assessments. Secondary sources include OSINERGMIN auction records, SEIA certification databases, Ministry of Energy and Mines policy filings, and transmission expansion plans from the national grid operator. Bottom-up project pipeline analysis triangulates against top-down capacity auction forecasts.
Granularity-level modeling disaggregates volume and value across turbine configuration, project scale tier, end-use application, and regional grid type throughout the forecast period. CAGRs derive from auction schedule visibility, mining electrification commitment timelines, and transmission expansion phasing. Industry-specific inputs incorporate capacity factor assumptions by corridor, diesel price volatility impacts on mining offtake willingness-to-pay, and SEIA certification duration distributions.
Auction schedule delays, transmission expansion slippage, and mining commodity price cycles are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about regulatory continuity and offtake contract structures. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Offshore Wind Turbine Blade Leading-Edge Defect Inspection Equipment Market
Wind Energy Systems
Thailand Wind Energy Market
Wind Energy Systems
Global Wind Automation Market
Wind Energy Systems
Wind Turbine Scrap Market
Wind Energy Systems
Wind Turbine Pitch Systems Market
Wind Energy Systems
Asia-Pacific Large Wind Turbine Market
Wind Energy Systems
Wind Cones Market
Wind Energy Systems
Medium-Speed Permanent Magnet Wind Turbine Generator System Market
Wind Energy Systems
Wind Turbine Yaw and Pitch Gearbox Market
Wind Energy Systems
Poland Wind Energy Market
Wind Energy Systems
Europe Wind Power Equipment Market
Wind Energy Systems
Europe Direct Drive Wind Turbine Market
Wind Energy Systems
South Korea Wind Energy Market
Wind Energy Systems
Wind Turbine Control System Market
Wind Energy Systems
Europe Wind Power Market
Wind Energy Systems
Middle-East and Africa Wind Power Market