
 Wind Cones Market | 2026-2036
Wind Cones Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Cones Market Insights
Maintenance-as-a-service contracts for LED illumination modules is rebalancing how airport operators procure wind cone systems, shifting capital expenditure into operational budgets over multi-year horizons. ADB SAFEGATE leverages its airfield lighting integration expertise to bundle wind cones within broader runway visual range portfolios. Holland Aviation BV sustains manufacturing depth through in-house fabrication of corrosion-resistant frames for coastal installations. Carmanah Technologies Corp. differentiates via solar-powered autonomy, eliminating trenching and grid-connection costs at remote airfields.
A wind cone, or windsock, is a tapered fabric tube mounted on a swivel mast that indicates wind direction and relative velocity through its inflation angle and orientation, typically constructed with nylon fabric or PVC over aluminum or stainless steel framing and sized per ICAO Annex 14 specifications for visibility range and angular response. Its primary purpose is to provide pilots, port operators, and site personnel with immediate visual wind data for safe takeoff, landing, docking, and hazardous material handling decisions. Heavy-duty wind cones lead material selection where salt-laden coastal environments accelerate degradation, while retractable wind cones command attention from military airbases requiring rapid airfield denial capabilities. Lightweight nylon fabric variants occupy the fastest-growing position among renewable energy developers deploying temporary meteorological masts for wind resource assessment campaigns.
FAA Advisory Circular 150/5345-27D governs US airfield wind cone photometric and structural standards, while EASA CS-ADR-DSN harmonizes European requirements through binding certification specifications that manufacturers must satisfy for market access. India's BIS certification and DGFT import monitoring create compliance layers for foreign suppliers targeting the Airports Authority of India's procurement cycles. Stakeholders must monitor how evolving ICAO climate-resilience guidelines recast material specifications and expected service lifetimes across installed bases.
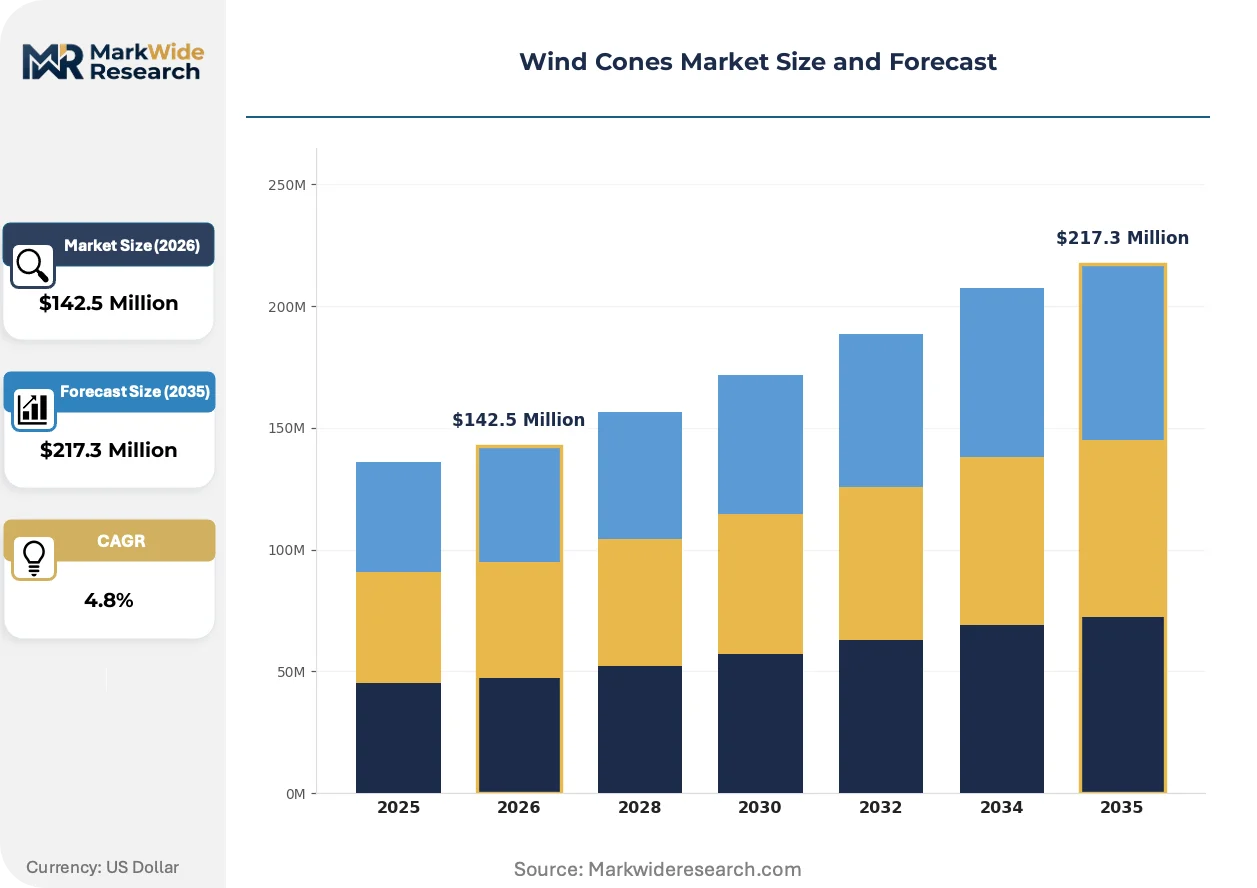
Market Dynamics
LED-integrated wind cone systems are compressing maintenance cycles and redirecting airport capital budgets toward operational expenditure models, fundamentally restructuring procurement relationships between airfield operators and equipment suppliers.
Growth Catalysts
- ICAO Annex 14 Visibility Mandates:International standards for angular response and visibility range are compelling airfield upgrades across developing aviation markets, particularly where legacy fabric systems no longer meet photometric thresholds.
- India Federal Infrastructure Programs:The Airports Authority of India's regional airfield modernization initiative is generating concentrated demand for corrosion-resistant coastal-grade wind cones at secondary and tertiary facilities.
- Solar Autonomy Integration:Photovoltaic-powered illumination modules are eliminating trenching and grid-connection requirements, unlocking deployment at remote airfields previously deemed uneconomical for electrified systems.
Market Restraints
- Aluminum and Stainless Steel Input Volatility:Frame fabrication costs fluctuate with base metal commodity markets, compressing margins for manufacturers lacking long-term supply agreements with mills.
- Coastal Manufacturing Concentration:Corrosion-resistant frame production clusters in low-lying coastal zones, exposing supply chains to salt-air degradation risks and climate-related disruption.
- FAA-EASA Certification Divergence:Separate photometric and structural approval pathways for US and European markets create redundant testing burdens and timeline extensions for cross-border suppliers.
Strategic Opportunities
- Renewable Energy Meteorological Campaigns:Wind resource assessment developers are adopting lightweight nylon fabric variants for temporary masts, creating volume demand outside traditional aviation channels.
- Maintenance-as-a-Service Contracts:LED module subscription models allow operators to shift capital expenditure into multi-year operational budgets, opening recurring revenue streams for equipment vendors.
- Southeast Asia Regulatory Expansion:Civil aviation authorities across Thailand, Indonesia, and Vietnam are expanding runway safety equipment mandates, creating compliance-driven replacement cycles at underpenetrated facilities.
Industry Challenges
- Photometric Calibration Expertise Gap:Field service networks lack sufficient technicians trained in LED intensity verification and angular response measurement, delaying commissioning timelines.
- Legacy System Integration Friction:Retrofitting LED-illuminated wind cones into existing airfield lighting control systems requires proprietary protocol adapters and extended commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Cones Market |
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $217.3 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Wind Cones, Heavy-Duty Wind Cones, Compact Wind Cones, Retractable Wind Cones, Lightweight Wind Cones Material: Aluminum, PVC, Stainless Steel, Fiberglass, Nylon Fabric, Polycarbonate Application: Aviation Airfields, Marine Ports, Industrial Sites, Weather Stations, Military Airbases, Renewable Energy Facilities Customer Type: Air Traffic Controllers, Port Authorities, Site Managers, Meteorological Agencies, Defense Contractors, Energy Developers |
| Companies Covered | AVIMAR S.r.l., Windsock Company, Airport Lighting Company, Flight Light Inc., Holland Aviation BV, Avlite Systems, ADB SAFEGATE, Carmanah Technologies Corp., Hughey & Phillips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Cones Market Trends and Innovations
Active consolidation around solid-state illumination and autonomous power systems is compressing the installed base of legacy incandescent wind cones while opening new deployment contexts beyond traditional airfield boundaries.
Solid-state LED illumination is consolidating market share across commercial and military airfields by eliminating filament degradation and reducing relamping frequency from months to years. Airport operators in salt-laden coastal environments are prioritizing sealed LED modules over open-incandescent designs. This consolidation is compressing the addressable market for replacement lamp suppliers while expanding margins for integrated system vendors.
EASA CS-ADR-DSN certification specifications are harmonizing European airfield equipment standards, reducing fragmentation between national aviation authorities. Manufacturers must now satisfy binding design specifications rather than navigating voluntary guidance documents. LED-integrated wind cones with embedded photometric monitoring are capturing preference in EASA-regulated markets where continuous compliance verification is becoming standard.
Service-based contracting is displacing outright equipment purchase across mid-sized regional airports seeking budget predictability. Multi-year illumination module subscriptions bundle hardware, installation, and preventive maintenance into single operational line items. This pattern is most visible in India's Airports Authority procurement cycles, where federal infrastructure programs favor expenditure smoothing over capital spikes.
Wind Cones Market Segmentation
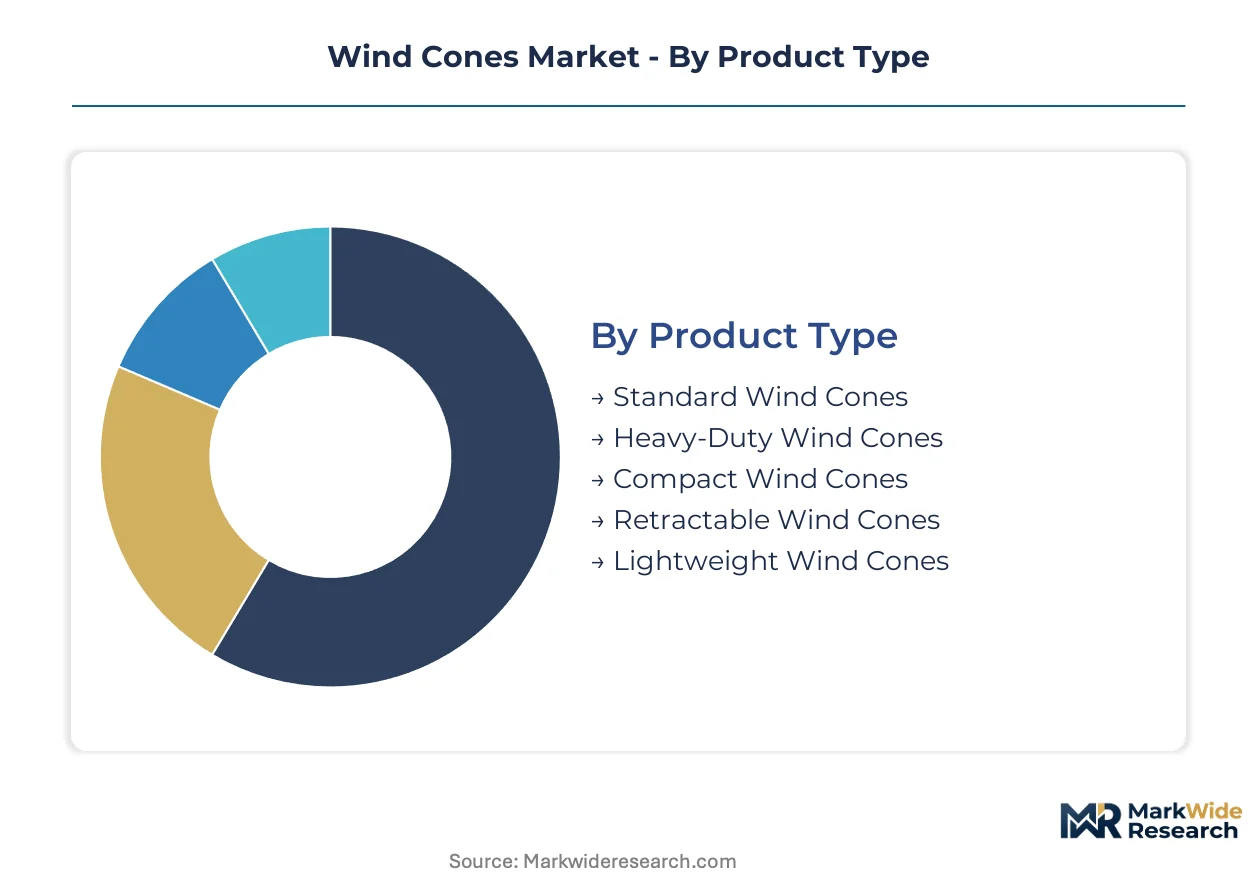
Wind cone procurement patterns diverge sharply across aviation, maritime, and industrial contexts, with material selection and form factor decisions driven by exposure severity, mobility requirements, and regulatory compliance burdens rather than unit economics alone.
Product Type:
Supply concentration tilts toward heavy-duty variants as coastal airfield operators prioritize corrosion resistance over first-cost savings.
- Standard Wind Cones:Conventional nylon fabric over aluminum framing satisfies ICAO Annex 14 visibility specifications at commercial airfields. Demand clusters at secondary facilities in India undergoing Airports Authority modernization where federal infrastructure programs favor proven designs.
- Heavy-Duty Wind Cones:Reinforced stainless steel frames with sealed LED modules withstand salt-laden coastal environments. Southeast Asian civil aviation authorities specify these for runway safety equipment mandates at exposed facilities.
- Compact Wind Cones:Reduced-diameter designs for heliport and droneport installations where space constraints limit mast height.
- Retractable Wind Cones:Swivel-mounted systems with rapid-deployment mechanisms serve military airbases requiring airfield denial capabilities.
- Lightweight Wind Cones:Minimal nylon fabric variants deploy on temporary meteorological masts for renewable energy resource assessment campaigns.
Today's leader: Heavy-Duty Wind Cones. Tomorrow's challenger: Lightweight Wind Cones.
Material:
Cost tier stratification separates premium stainless steel from economy PVC alternatives, with mid-tier aluminum dominating volume procurement.
- Aluminum:Standard framing material balancing weight and structural integrity for permanent airfield installations. India's DGFT import monitoring shapes procurement cycles for foreign suppliers targeting Airports Authority tenders.
- PVC:Molded housings for compact and temporary deployments where corrosion resistance exceeds strength requirements.
- Stainless Steel:Coastal-grade fabrication resists salt-air degradation at marine ports and exposed airfields. Holland Aviation BV maintains in-house production of corrosion-resistant frames for this specification tier.
- Fiberglass:Non-conductive masts for lightning-sensitive installations at fuel storage and chemical handling facilities.
- Nylon Fabric:High-visibility orange or red woven material meeting ICAO photometric response standards for angular wind indication.
- Polycarbonate:Impact-resistant lensing for LED illumination modules in high-vibration environments.
Stainless steel commands margin premiums at the coast; aluminum retains volume dominance inland.
Application:
Application-driven specification divergence creates distinct vendor qualification pathways, with aviation certification requirements filtering supplier participation.
- Aviation Airfields:FAA Advisory Circular 150/5345-27D and EASA CS-ADR-DSN govern photometric and structural standards for commercial and military runways. LED-integrated systems are displacing incandescent installations across EASA-regulated markets.
- Marine Ports:Salt-exposed dockside installations demand sealed illumination and corrosion-resistant framing. Port authorities specify heavy-duty variants with extended service intervals.
- Industrial Sites:Chemical plants and refineries deploy wind cones for hazardous material handling decisions, often integrating with site-wide meteorological networks.
- Weather Stations:National meteorological agencies require calibrated angular response for research-grade wind measurement.
- Military Airbases:Rapid airfield denial capabilities drive retractable wind cone procurement with electromagnetic interference hardening.
- Renewable Energy Facilities:Temporary meteorological masts for wind resource assessment favor lightweight nylon fabric variants, expanding fastest outside traditional aviation channels.
Aviation retains procurement value concentration; renewable energy is climbing the fastest.
Customer Type:
Customer procurement maturity separates subscription-ready airport operators from capital-budget-constrained site managers.
- Air Traffic Controllers:FAA and EASA-regulated facilities drive specification compliance and LED upgrade cycles. Maintenance-as-a-service contracts are restructuring procurement toward operational expenditure models.
- Port Authorities:Coastal corrosion exposure prioritizes sealed LED modules and stainless steel framing over first-cost minimization.
- Site Managers:Industrial facility operators integrate wind cones with broader environmental monitoring systems, often lacking dedicated aviation expertise.
- Meteorological Agencies:Research-grade calibration requirements filter supplier qualification to specialized vendors with photometric verification capabilities.
- Defense Contractors:Military procurement specifications emphasize rapid deployment and electromagnetic compatibility.
- Energy Developers:Renewable project developers deploy temporary lightweight systems for wind resource campaigns, creating volume demand with minimal service infrastructure expectations.
Air traffic controllers anchor current revenue; energy developers represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India generates concentrated procurement volume through federal airfield modernization, while the United States sustains steady replacement demand through FAA-mandated photometric upgrades at aging facilities.
United States
FAA Advisory Circular 150/5345-27D governs photometric and structural standards for commercial and military airfields. The FAA mandates angular response and visibility range specifications that compel LED upgrades at legacy installations. Dallas-Fort Worth and Atlanta Hartsfield-Jackson anchor demand concentration where major hub operators pursue maintenance-as-a-service contracts.
India
The Airports Authority of India's regional airfield modernization initiative drives procurement of corrosion-resistant coastal-grade wind cones. India's BIS certification and DGFT import monitoring create compliance layers for foreign suppliers targeting federal tenders. Secondary and tertiary facilities in Maharashtra and Gujarat concentrate demand where infrastructure programs favor proven designs.
Germany
EASA CS-ADR-DSN harmonizes European requirements through binding certification specifications for market access. German airport operators prioritize sealed LED modules over open-incandescent designs in salt-laden North Sea coastal environments. Frankfurt and Munich anchor procurement concentration where continuous compliance verification is becoming standard.
Thailand
Civil aviation authorities are expanding runway safety equipment mandates at underpenetrated facilities. National regulations align with ICAO Annex 14 visibility standards while accommodating tropical humidity exposure in material specifications. Bangkok Suvarnabhumi and Phuket International concentrate procurement where coastal corrosion accelerates replacement cycles.
United Arab Emirates
Dubai and Abu Dhabi anchor demand for heavy-duty variants with extended service intervals in extreme heat and salt-air conditions. Port authorities specify sealed illumination and corrosion-resistant framing over first-cost minimization. Jebel Ali and Khalifa Port clusters drive maritime procurement where dockside exposure demands premium material selection.
Wind Cones Market Competitive Landscape
Top-tier vendors anchor integrated airfield lighting portfolios, while mid-tier specialists concentrate on material fabrication or autonomous power modules. The vendor base stratifies across three functional tiers: full-system integrators, component fabricators with in-house corrosion-resistant production, and solar-autonomy specialists eliminating grid-connection requirements. Competitive positioning hinges on certification breadth and multi-year service contract penetration.
Among European fabricators, Holland Aviation BV exemplifies the coastal-grade specialist archetype through its manufacturing depth, while ADB SAFEGATE occupies a position as a full-system integrator bundling wind cones within broader runway visual range portfolios. Carmanah Technologies Corp. represents the solar-autonomy vector, eliminating trenching costs at remote installations.
| Leading Market Players |
|---|
| AVIMAR S.r.l. |
| Windsock Company |
| Airport Lighting Company |
| Flight Light Inc. |
| Holland Aviation BV |
| Avlite Systems |
| ADB SAFEGATE |
| Carmanah Technologies Corp. |
| Hughey & Phillips |
| Others |
Pricing and Supply Chain Analysis
Federal infrastructure programs in India mandating corrosion-resistant coastal-grade specifications are forcing supply base adjustments toward stainless steel fabrication, compressing margins for aluminum-dependent vendors while elevating price floors for premium tier offerings.
Pricing Analysis
Capacity additions in Southeast Asia are reshaping price floors for standard aluminum-framed wind cones as regional manufacturers scale output for civil aviation authority mandates. Three-tier pricing structure across premium, standard, and economy levels separates sealed LED-integrated systems from incandescent legacy units and temporary nylon fabric variants. Cost compression in the standard tier is intensifying because of aluminum commodity volatility and import duty layering under India's DGFT monitoring. Energy developers deploying temporary meteorological masts exhibit highest price sensitivity, while coastal port authorities prioritize corrosion resistance over first-cost minimization.
Supply Chain Analysis
Direct-to-airport procurement channels handle concentrated demand from India's Airports Authority modernization initiative, while distributor networks serve fragmented industrial site managers. Frame fabrication concentrates in the Netherlands, India, and China, with corrosion-resistant stainless steel production anchored in coastal European facilities. Supply chains draw from aluminum mill contracts, LED module suppliers, and nylon textile weavers. Single-source vulnerability in sealed LED illumination modules creates procurement risk for buyers seeking EASA CS-ADR-DSN certification compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ICAO Annex 14 visibility mandate expansions across Southeast Asia generate sustained compliance-driven replacement cycles regardless of aviation traffic growth trajectories.
For Market Incumbents: Extend service-based contracting penetration among India's Airports Authority procurement cycles to lock in multi-year operational expenditure relationships before federal infrastructure program completion. Deepen in-house fabrication of corrosion-resistant frames to defend margin position against aluminum price volatility and coastal manufacturing disruption risks. For New Entrants and Emerging Players: Renewable energy developers represent the most penetrable demand channel, with lightweight nylon fabric variants for temporary meteorological masts requiring minimal certification burden and offering volume scale outside aviation regulatory complexity. Pursue direct OEM partnerships with wind resource assessment equipment suppliers to bypass established airfield lighting distribution networks. For Investors and Strategic Acquirers: Asymmetric upside sits with solar-autonomy specialists possessing photovoltaic-integrated illumination modules that eliminate trenching costs at remote airfields. Long-term viability favors vendors with EASA and FAA dual-certification breadth capable of serving fragmented regulatory environments. Monitor LED module subscription contract penetration rates as the inflection indicator for operational expenditure model maturation.| Strategic Initiative | Industry Significance |
|---|---|
| LED Module Subscription Launch | Transforms capital expenditure into recurring revenue streams aligned with India's Airports Authority procurement preferences. |
| Corrosion-Resistant Frame Backward Integration | Captures margin premiums in salt-laden coastal environments where Holland Aviation BV currently dominates. |
| Solar Autonomy Certification Investment | Unlocks remote airfield deployments previously uneconomical for grid-connected systems under FAA Advisory Circular standards. |
| Renewable Energy Channel Partnership | Establishes volume foothold in fastest-expanding application segment for temporary meteorological mast installations. |
| EASA-FAA Dual Certification Pathway | Eliminates redundant testing burdens and timeline extensions that constrain cross-border supplier participation. |
Research Methodology
Multiple input streams — primary interviews with airfield lighting procurement officers, air traffic control facility managers, and LED module service technicians, alongside secondary validation through FAA Advisory Circular documentation, EASA CS-ADR-DSN certification records, and India's BIS regulatory filings — were reconciled using bottom-up installation base assessments and top-down aviation infrastructure spending analysis.
Data-stream reconciliation across product type, material grade, application context, and customer procurement maturity dimensions informed the analytical framework throughout the projection horizon. CAGRs were derived from segment-level demand build-ups incorporating airfield modernization program timelines, regulatory mandate phase-in schedules, and renewable energy deployment trajectories for wind resource assessment campaigns.
Revisions become necessary when ICAO climate-resilience guidelines recast material specifications, when aluminum or stainless steel commodity markets experience sustained dislocation, or when civil aviation authorities accelerate runway safety equipment mandate timelines beyond modeled compliance cycles. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Global Wind LIDAR Market
Wind Energy Systems
Offshore Wind Tower Market
Wind Energy Systems
Drone Wind Turbine Blade Inspection Market
Wind Energy Systems
Boat Wind Turbine Market
Wind Energy Systems
Lubricants for Wind Turbine Market
Wind Energy Systems
Offshore Wind Anchoring Market
Wind Energy Systems
Double-Fed Wind Turbine Market
Wind Energy Systems
Asia-Pacific Wind Power Equipment Market
Wind Energy Systems
Taiwan Wind Energy Market
Wind Energy Systems
Asia-Pacific Wind Power Market
Wind Energy Systems
United Kingdom Renewable Energy Market
Wind Energy Systems
Wind Energy Foundation Market
Wind Energy Systems
Middle-East and Africa Wind Power Market
Wind Energy Systems
Japan Wind Energy Market
Wind Energy Systems
Wind Turbine Cables Market
Wind Energy Systems
North America Wind Power Equipment Market