
 Wind Turbine Cables Market | 2026-2036
Wind Turbine Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Cables Market Analytics
The capital-intensity divergence between integrated manufacturers and component assemblers is bifurcating competitive dynamics in wind turbine cables. Prysmian Group leverages captive submarine cable-laying vessels to control installation scheduling and margin capture. Hengtong Group anchors its position through backward integration into copper smelting and specialty polymer compounding. NKT differentiates via high-voltage DC extrusion expertise for long-distance offshore transmission corridors.
Wind turbine cables are engineered electrical conductors designed to transmit power, control signals, and data across turbine nacelles, towers, and grid interconnection points, typically employing cross-linked polyethylene insulation rated for torsional flexure and salt-fog environments. Their primary purpose is maintaining electrical integrity across dynamic mechanical loads while minimizing resistive losses in generation-to-grid pathways. Power cables occupy the dominant value pool given escalating offshore turbine ratings, while submarine installation methods represent the fastest-growing dimension as floating wind platforms proliferate. Fiber optic cables command premium positioning for condition monitoring and turbine-to-shore SCADA networks, though copper conductor material still sustains the largest volume footprint across onshore repowering cycles.
The EU Green Deal and F-Gas Regulation constrain fluorinated gas use in cable insulation manufacturing, redirecting formulation investments toward halogen-free flame-retardant compounds. China's GB standards and MIIT directives mandate localized testing certification for high-voltage cable imports, shaping market access conditions for non-domestic suppliers. ISO and IEC standards govern submarine cable fatigue testing protocols, creating compliance thresholds that filter qualified bidders in offshore tenders. Stakeholders must monitor raw material pass-through mechanisms and qualification timeline compression as turbine OEMs consolidate supplier panels.
Market Dynamics
Offshore wind turbine ratings are scaling past 15 MW, forcing cable manufacturers to reconcile higher current densities with submarine fatigue requirements while EU F-Gas Regulation and China's dual carbon goals simultaneously constrain insulation chemistry options.
Growth Catalysts
- Offshore wind farm procurement waves:Developers in the North Sea basin and China's coastal provinces are tendering multi-gigawatt projects requiring kilometer-scale submarine cable arrays.
- EU Green Deal material mandates:The regulation's circular economy provisions for electrical infrastructure are accelerating halogen-free sheathing compound qualification timelines.
- Cross-linked polyethylene insulation:Advances in torsional-flexure-rated formulations are extending cable service life in floating platform applications.
Market Restraints
- Copper price volatility:Conductor material accounts for substantial bill-of-materials exposure, with smelter capacity concentration in Chile and Peru amplifying input cost swings.
- Submarine cable-laying vessel scarcity:Qualified installation fleets number fewer than two dozen globally, creating scheduling bottlenecks for offshore project commissioning.
- High-voltage DC extrusion technical thresholds:Few manufacturers possess validated 320 kV+ extrusion capability, filtering tender participation for long-distance transmission corridors.
Strategic Opportunities
- Floating wind platform emergence:Dynamic cable systems for tension-leg and semi-submersible foundations represent uncaptured value pools as pre-commercial projects scale in Portugal and Japan.
- Condition monitoring fiber integration:Turbine-to-shore SCADA networks are creating demand for hybrid power-communication cable architectures.
- Onshore repowering retrofit cycles:Aging European and North American wind fleets are reaching end-of-design-life, triggering replacement demand for medium-voltage array cables.
Industry Challenges
- Submarine fatigue testing certification:ISO and IEC protocol compliance requires 12-18 month qualification timelines that compress against turbine OEM supplier panel consolidation schedules.
- Specialized polymer compounding talent:Formulation chemists with salt-fog and torsional-load expertise remain concentrated among incumbent manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Cables Market |
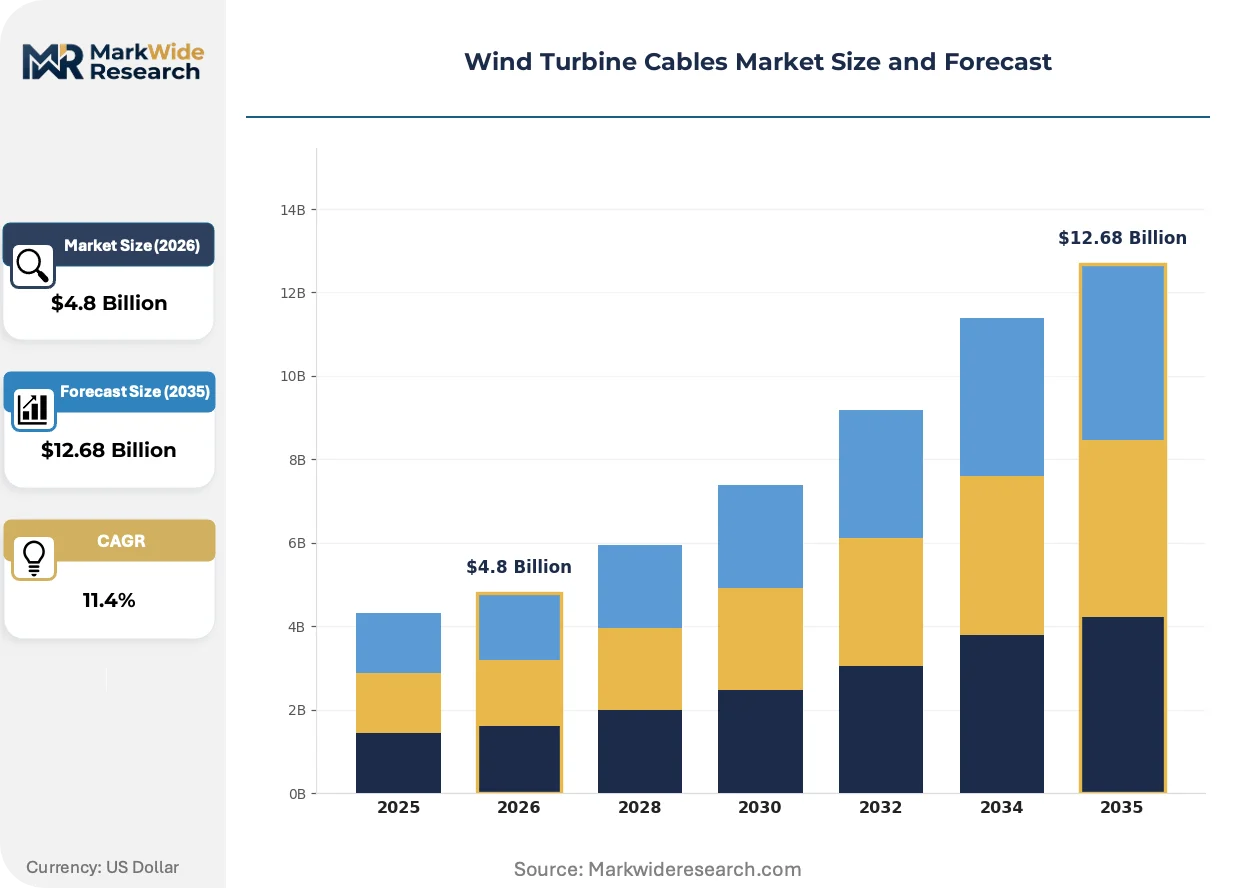
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
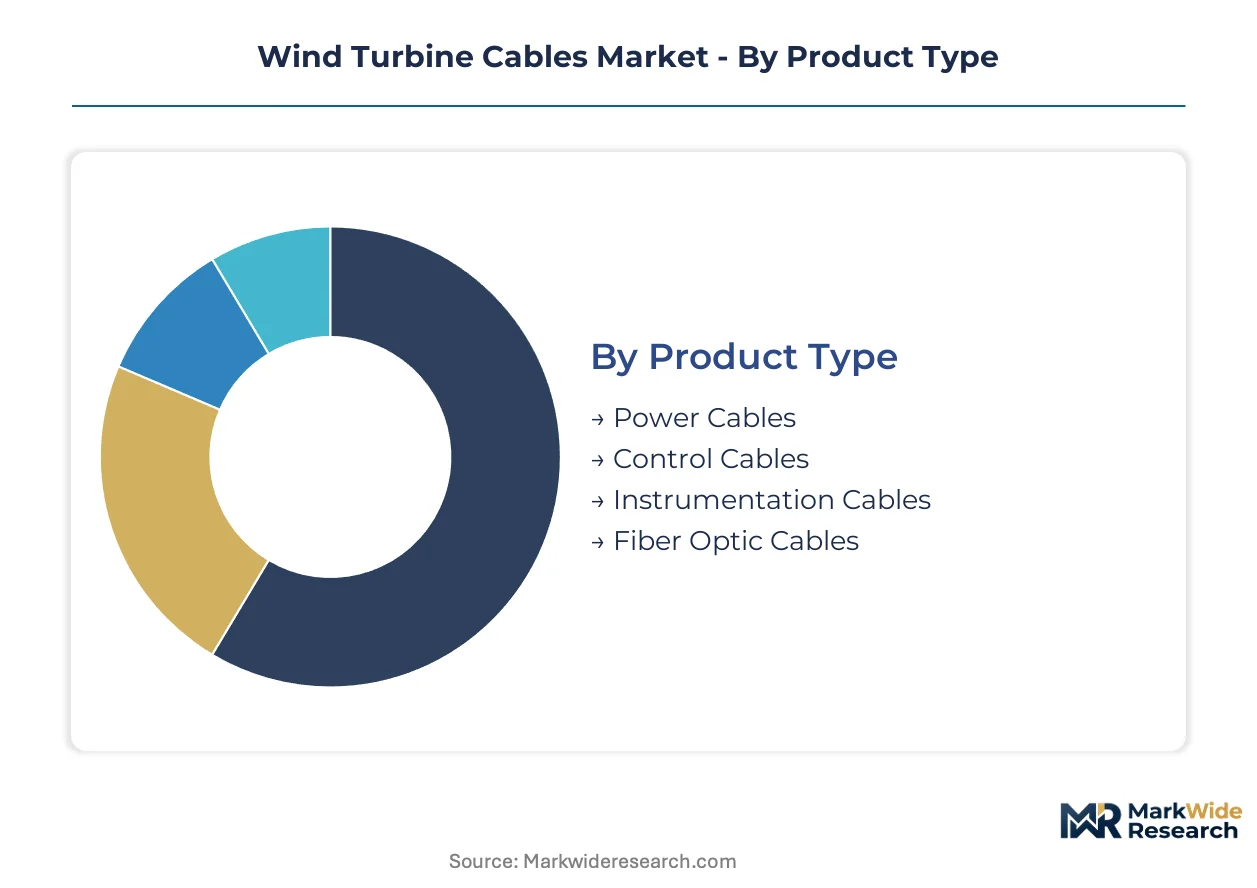
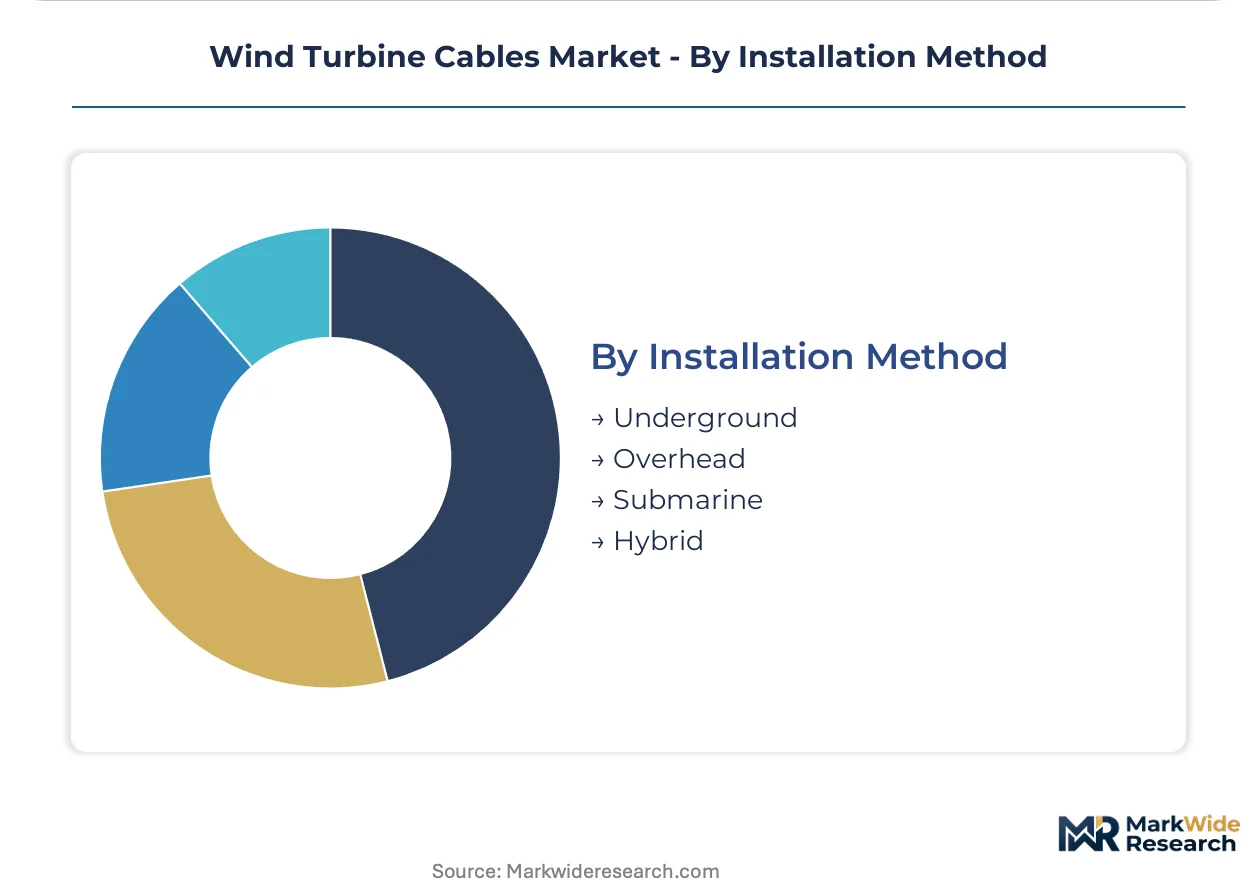
| Segmentation | Product Type: Power Cables, Control Cables, Instrumentation Cables, Fiber Optic Cables Material: Copper, Aluminum, Polyethylene, Rubber Insulation Type: Low Voltage, Medium Voltage, High Voltage, Weather-Resistant Installation Method: Underground, Overhead, Submarine, Hybrid |
| Companies Covered | LS Cable & System, Furukawa Electric, Nexans, ZTT Group, JDR Cable Systems, Prysmian Group, Sumitomo Electric Industries, Hengtong Group, NKT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Cables Market Evolving Landscape
Material science and installation methodology are diverging simultaneously as manufacturers confront incompatible pressures: higher electrical ratings demand thicker insulation, while submarine handling requires thinner, more flexible constructions.
Dynamic cable systems for floating wind platforms are fragmenting the traditional submarine cable market. These specialized conductors incorporate bend stiffeners and buoyancy modules to accommodate platform motion. Offshore developers in Portugal, Japan, and Scotland are piloting configurations at 66 kV and 132 kV ratings. The technology is fragmenting procurement patterns by requiring integrated mechanical-electrical design capabilities that discrete cable suppliers rarely possess.
EU F-Gas Regulation bans are redirecting formulation investments toward halogen-free flame-retardant compounds. The regulation's phase-down schedule for fluorinated gases used in insulation manufacturing is compressing R&D timelines for alternative chemistries. Submarine-rated cable sheathing faces the tightest constraints, as offshore salt-fog environments previously relied on fluoropolymer protection.
Buyer concentration among consolidated turbine OEMs is compressing supplier qualification windows. Vestas, Siemens Gamesa, and Goldwind are reducing approved vendor lists to three-to-five cable suppliers per region. This consolidation is forcing mid-tier manufacturers to absorb certification costs for OEM-specific testing protocols, particularly in China where GB standards and MIIT directives mandate localized testing certification for high-voltage imports.
Wind Turbine Cables Market Segmentation
Wind turbine cable procurement patterns diverge sharply across electrical rating tiers and environmental exposure levels. Manufacturers must align extrusion capacity and compound formulation expertise against specific installation stresses rather than pursuing universal product platforms.
Product Type:
Power cables face limited substitution threat given escalating offshore turbine ratings, while control and instrumentation cables confront hybrid fiber-power architectures that consolidate functionality.
- Power Cables:These conductors employ cross-linked polyethylene insulation rated for torsional flexure and salt-fog environments, transmitting bulk generation from nacelle to grid interconnection. Demand concentrates in China's coastal provinces and the North Sea basin as developers tender multi-gigawatt offshore arrays requiring kilometer-scale submarine installations.
- Fiber Optic Cables:Glass fiber conductors integrated with power cores enable turbine-to-shore SCADA networks and real-time condition monitoring. Portugal and Japan's floating wind pilots are accelerating procurement of hybrid power-communication architectures that displace discrete copper control lines.
- Control Cables:Low-voltage copper conductors manage pitch systems, yaw drives, and safety circuits within turbine nacelles.
- Instrumentation Cables:Shielded pairs transmit sensor data for vibration, temperature, and oil condition monitoring across tower assemblies.
Power cables retain volume leadership; fiber optic cables hold the steepest expansion curve.
Material:
Cost tier stratification separates conductor metals from sheathing compounds, with copper commanding premium positioning against aluminum substitution in high-reliability offshore applications.
- Copper:High-conductivity electrolytic copper dominates offshore and high-voltage segments where resistive losses directly impact project economics. Smelter capacity concentration in Chile and Peru amplifies input cost volatility, forcing manufacturers to maintain hedge positions or backward integration into cathode procurement.
- Polyethylene:Cross-linked formulations provide the dominant insulation matrix for submarine-rated power cables, with halogen-free flame-retardant variants gaining share under EU F-Gas Regulation constraints.
- Aluminum:Lower-density conductor material penetrates onshore array cabling where span lengths and installation labor dominate project costs.
- Rubber:Ethylene-propylene-diene monomer compounds serve nacelle-internal flexible connections requiring extreme temperature cycling resistance.
Copper sustains revenue concentration; polyethylene formulations are expanding most quickly as halogen-free qualification accelerates.
Insulation Type:
Application voltage determines extrusion equipment requirements and qualification timelines, with high-voltage DC capability filtering tender participation for long-distance offshore transmission corridors.
- High Voltage:Extruded insulation systems at 66 kV, 132 kV, and 320 kV+ ratings serve inter-array and export cables for offshore wind farms. Few manufacturers possess validated 320 kV+ extrusion capability, creating supply concentration for North Sea and East Asian projects.
- Medium Voltage:33 kV to 66 kV ratings dominate inter-turbine array cabling in both onshore repowering and fixed-bottom offshore installations.
- Low Voltage:Nacelle-internal and tower wiring applications where flexibility and termination speed outweigh dielectric thickness optimization.
- Weather-Resistant:Specialized sheathing compounds for extreme temperature, UV, and abrasion exposure in desert and arctic onshore installations.
High voltage systems capture premium pricing; medium voltage maintains shipment volume leadership across replacement cycles.
Installation Method:
Geographic deployment patterns favor submarine methods in coastal provinces and the North Sea, while onshore markets split between underground burial and overhead collector systems.
- Submarine:Qualified cable-laying vessels number fewer than two dozen globally, creating scheduling bottlenecks for project commissioning. Prysmian Group and NKT leverage captive fleets to control installation timing and margin capture in Denmark, Germany, and United Kingdom tenders.
- Underground:Direct-buried medium-voltage arrays dominate onshore wind farm construction in agricultural and residential buffer zones.
- Overhead:Lattice tower suspension systems persist in remote terrain where excavation costs exceed conductor material premiums.
- Hybrid:Combined submarine-terrestrial routes for island-connected wind farms and coastal marsh crossings.
Underground methods retain volume leadership; submarine installation claims the steepest expansion trajectory as floating platforms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's coastal provinces exhibit the highest price sensitivity due to intense domestic competition, while North Sea developers prioritize technical qualification and installation reliability over unit cost.
China
Provincial governments in Jiangsu and Fujian are tendering multi-gigawatt offshore arrays that strain qualified cable-laying vessel availability. MIIT directives mandate localized testing certification for high-voltage imports, filtering market access for non-domestic suppliers. Qingdao and Shanghai anchor manufacturing clusters where state-owned fabricators are scaling 320 kV extrusion capacity.
Germany
North Sea lease rounds require kilometer-scale submarine cable arrays connecting clusters of 15 MW+ turbines. The EU F-Gas Regulation bans fluorinated insulation gases, compressing reformulation timelines for halogen-free alternatives. Rostock and Bremen host cable-laying vessel fleets that control installation scheduling for Danish and UK cross-border projects.
United Kingdom
Crown Estate leasing rounds are accelerating floating wind pilots in Scottish waters requiring dynamic cable systems. The Contracts for Difference scheme underwrites project economics that absorb premium pricing for qualified submarine installations. Aberdeen and Hull concentrate installation service providers and turbine marshaling infrastructure.
Denmark
Energy Island projects in the Baltic and North Seas mandate high-voltage DC corridors spanning hundreds of kilometers. National grid operator Energinet is procuring extruded insulation systems at 320 kV+ ratings that filter supplier participation. Esbjerg functions as the primary cable marshaling port for German and Dutch offshore zones.
Japan
METI feed-in tariff revisions are unlocking floating wind demonstration projects off Kyushu and Hokkaido. Domestic content requirements under the Green Transformation policy favor cable procurement from local joint ventures. Nagasaki and Yokohama host manufacturing facilities serving tension-leg platform pilot programs.
Wind Turbine Cables Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that lacks captive installation assets or backward integration into conductor smelting. Prysmian Group and NKT control cable-laying vessel fleets that capture margin through installation timing certainty. Hengtong Group anchors supply security through in-house copper cathode procurement. Competitive moves concentrate on M&A for polymer compounding expertise and strategic partnerships with turbine OEMs to compress qualification timelines.
Among European-integrated manufacturers, Prysmian Group and NKT exemplify the vessel-captive archetype that commands scheduling priority in North Sea tenders. Hengtong Group represents the vertically integrated Asian model combining smelter access with high-voltage extrusion capacity. Nexans occupies a position between these poles with extrusion expertise but without captive marine installation assets. Specialist fabricators like JDR Cable Systems and ZTT Group sit within the project-specific tier, anchoring regional procurement relationships without global vessel networks.
| Leading Market Players |
|---|
| LS Cable & System |
| Furukawa Electric |
| Nexans |
| ZTT Group |
| JDR Cable Systems |
| Prysmian Group |
| Sumitomo Electric Industries |
| Hengtong Group |
| NKT |
| Others |
Value Network & Pricing Analysis
EU F-Gas Regulation phase-down schedules gate both submarine cable qualification timelines and price differentiation across insulation chemistry tiers, compressing reformulation investments while filtering suppliers capable of halogen-free compound validation.
Pricing Analysis
Installation service bundling drives lifetime value capture more than cable unit economics alone. Three-tier pricing structure across premium, standard, and economy levels separates vessel-captive integrators from extrusion-only fabricators and regional assemblers. Price differentiation rests on ISO/IEC fatigue certification status and captive cable-laying fleet access. Cost compression in standard-tier array cabling intensifies as Chinese state-owned fabricators scale 320 kV capacity. Offshore developers in the North Sea basin exhibit lowest price sensitivity; onshore repowering contractors in agricultural zones show highest.
Supply Chain Analysis
Strategic copper cathode stockpiling dominates over just-in-time conductor procurement given smelter concentration volatility. Manufacturing gravity centers on China, Germany, and Italy for extrusion systems; Chile and Peru anchor upstream cathode supply. Raw material dependencies span electrolytic copper, cross-linked polyethylene compounds, and specialized marine-grade sheathing polymers. Single-source vulnerability concentrates in qualified cable-laying vessel fleets numbering fewer than two dozen globally. Distribution runs through turbine OEM-approved vendor panels with compressed qualification windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wind turbine cable procurement is recovering from cyclical vessel capacity constraints as floating wind platform tenders accelerate project backlogs.
For Market Incumbents: Secure captive cable-laying vessel scheduling priority through long-term charter agreements with North Sea port operators. Deepen backward integration into copper smelting or specialty polymer compounding to offset cathode price volatility. Defend against emerging Chinese state-owned fabricators by accelerating halogen-free compound qualification ahead of EU F-Gas ban deadlines. For New Entrants and Emerging Players: Dynamic cable system engineering services represent an under-served layer where incumbents lack integrated mechanical-electrical design capabilities. Penetrate Portugal and Japan floating wind pilot programs through partnerships with tension-leg platform developers. Pursue OEM-specific testing certification under China's GB standards to unlock coastal province procurement access. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed cable-laying service providers facing vessel replacement capex cliffs. Five-to-ten year viability hinges on floating wind commercialization velocity rather than fixed-bottom offshore saturation. Monitor 320 kV+ extrusion qualification announcements as inflection indicators for supplier consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Cable-Laying Vessel Acquisition | Prysmian Group and NKT control installation scheduling through captive fleets in Danish and German waters. |
| Halogen-Free Compound Qualification | EU F-Gas Regulation bans are redirecting R&D investments toward flame-retardant sheathing alternatives. |
| Copper Smelter Backward Integration | Hengtong Group anchors supply security through in-house cathode procurement from Chilean concentrate. |
| Dynamic Cable System Partnerships | Scotland and Japan floating pilots require integrated bend-stiffener and buoyancy module capabilities. |
| OEM Panel Consolidation Defense | Vestas and Siemens Gamesa are reducing approved vendors to three-to-five suppliers per region. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with offshore wind farm developers, cable-laying vessel operators, polymer formulation chemists, and turbine OEM procurement directors. Secondary validation drew from IEC standard documentation, EU F-Gas Regulation filings, MIIT directive publications, and customs trade data for copper cathode flows. Bottom-up project pipeline aggregation was triangulated against top-down manufacturer capacity disclosures.
Across the analysis window, volume and value outputs reflect segmentation by product type, material composition, insulation voltage rating, and installation method. CAGRs were derived from project-level procurement schedules and manufacturer order backlogs. Forecast inputs incorporated cable-laying vessel fleet utilization rates and 320 kV+ extrusion capacity commissioning timelines.
Forecasts assume regulatory continuity in EU F-Gas phase-down schedules and China's dual carbon enforcement; material policy shifts would require re-modeling. Revision becomes warranted when floating wind platform tender volumes cross commercial-scale thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Europe Wind Power Market
Wind Energy Systems
Dual Rotor Wind Turbine Market
Wind Energy Systems
Wind Cones Market
Wind Energy Systems
Offshore Wind Anchoring Market
Wind Energy Systems
Sweden Wind Energy Market
Wind Energy Systems
Europe Small Wind Turbine Market
Wind Energy Systems
South Korea Wind Energy Market
Wind Energy Systems
Global Marine Wind Turbine Market
Wind Energy Systems
Asia-Pacific Large Wind Turbine Market
Wind Energy Systems
Wind Services Market
Wind Energy Systems
Drone Wind Turbine Blade Inspection Market
Wind Energy Systems
Asia-Pacific Wind Power Equipment Market
Wind Energy Systems
Denmark Wind Energy Market
Wind Energy Systems
Wind Speed Alarm Market
Wind Energy Systems
Offshore Wind Cable Market
Wind Energy Systems
Australia Wind Energy Market