
 Wind Energy Equipment Market | 2026-2036
Wind Energy Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Energy Equipment Market Outlook
Chinese turbine manufacturers is expanding blade and nacelle output to meet domestic offshore installation targets. Vestas Wind Systems leverages its global service network to sustain recurring revenue from long-term operations contracts. Siemens Gamesa Renewable Energy anchors European offshore supply through specialized direct-drive platforms. Goldwind competes aggressively on cost while extending its vertical reach into rare-earth permanent magnet supply.
Wind energy equipment encompasses the mechanical and electrical systems that convert kinetic wind energy into grid-ready electricity, including towers rated for 100+ meter hub heights, carbon-fiber-reinforced polymer blades exceeding 80 meters in length, and power conversion assemblies with reactive power control capability. Turbines dominate capital allocation within the product type dimension, while offshore technology captures the fastest expansion trajectory due to higher capacity factors and fewer land-use constraints. Horizontal axis designs occupy the overwhelming majority of installed capacity, though vertical axis configurations retain niche appeal in distributed urban applications.
The EU Green Deal and F-Gas Regulation constrain refrigerant and insulation choices in generator cooling systems, while the IRA in the United States creates domestic content bonuses that redirect supply chain geography. China's MIIT enforces GB standards for grid-code compliance that effectively filter non-domestic equipment from national tenders. Stakeholders must monitor how divergent local-content rules across Washington, Brussels, and Beijing fragment formerly global procurement strategies.
Market Dynamics
Offshore wind turbine scaling is compressing unit economics while straining port infrastructure and heavy-lift vessel availability across Northern Europe and East Asia. Manufacturers now face a structural squeeze between 15+ MW platform development costs and the limited installation windows imposed by seasonal weather constraints.
Growth Catalysts
- US IRA domestic content bonuses:The Inflation Reduction Act's additive manufacturing credits are redirecting nacelle assembly and blade molding capacity toward American coastal states. Developers now structure procurement to capture full incentive stacks.
- Direct-drive generator platforms:Rare-earth permanent magnet architectures eliminate gearbox maintenance burdens and reduce offshore servicing frequency. Siemens Gamesa and Chinese competitors are converging on this topology for 10+ MW units.
- China's MIIT grid-code enforcement:GB standards for fault-ride-through and reactive power capability filter non-compliant equipment from national tenders. Domestic manufacturers capture volume through technical compliance rather than price alone.
Market Restraints
- Neodymium-dysprosium supply concentration:Rare-earth magnet production clusters in China's Inner Mongolia and Jiangxi provinces. Western turbine builders face input cost volatility and geopolitical exposure for direct-drive platforms.
- F-Gas Regulation refrigerant constraints:The EU's phasedown of hydrofluorocarbons limits cooling system options for generator thermal management. Equipment redesigns extend certification timelines for European offshore projects.
- Intermittency-driven grid integration costs:High wind penetration strains transmission balancing reserves. Developers in Germany and Spain absorb incremental grid reinforcement expenses that erode project returns.
Strategic Opportunities
- Floating foundation technology maturation:Semi-submersible and tension-leg platforms unlock deep-water sites off California, Japan, and France where fixed-bottom installation proves uneconomic. Supply chains for dynamic cables and station-keeping systems remain underdeveloped.
- Repowering of 2000s-era onshore fleets:Early German and Danish installations face blade fatigue and gearbox obsolescence. Site owners evaluate 3-4 MW turbine replacements against greenfield development timelines.
- Green hydrogen offtake integration:Electrolyzer co-location at offshore wind hubs converts curtailed generation into ammonia or e-fuels. Denmark's Energy Island concept and Dutch hydrogen corridor planning anchor pilot demand.
Industry Challenges
- Composite blade recycling infrastructure gaps:Thermoset carbon-fiber and glass-fiber laminates resist mechanical or chemical separation. Landfill diversion mandates in Germany and the Netherlands outpace viable pyrolysis or solvolysis capacity deployment.
- Installation vessel bottlenecks:Jones Act requirements in US waters and specialized heavy-lift jack-up scarcity in Europe compress project execution windows. Charter rates for 1,500+ tonne crane vessels have tripled since 2020.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Energy Equipment Market |
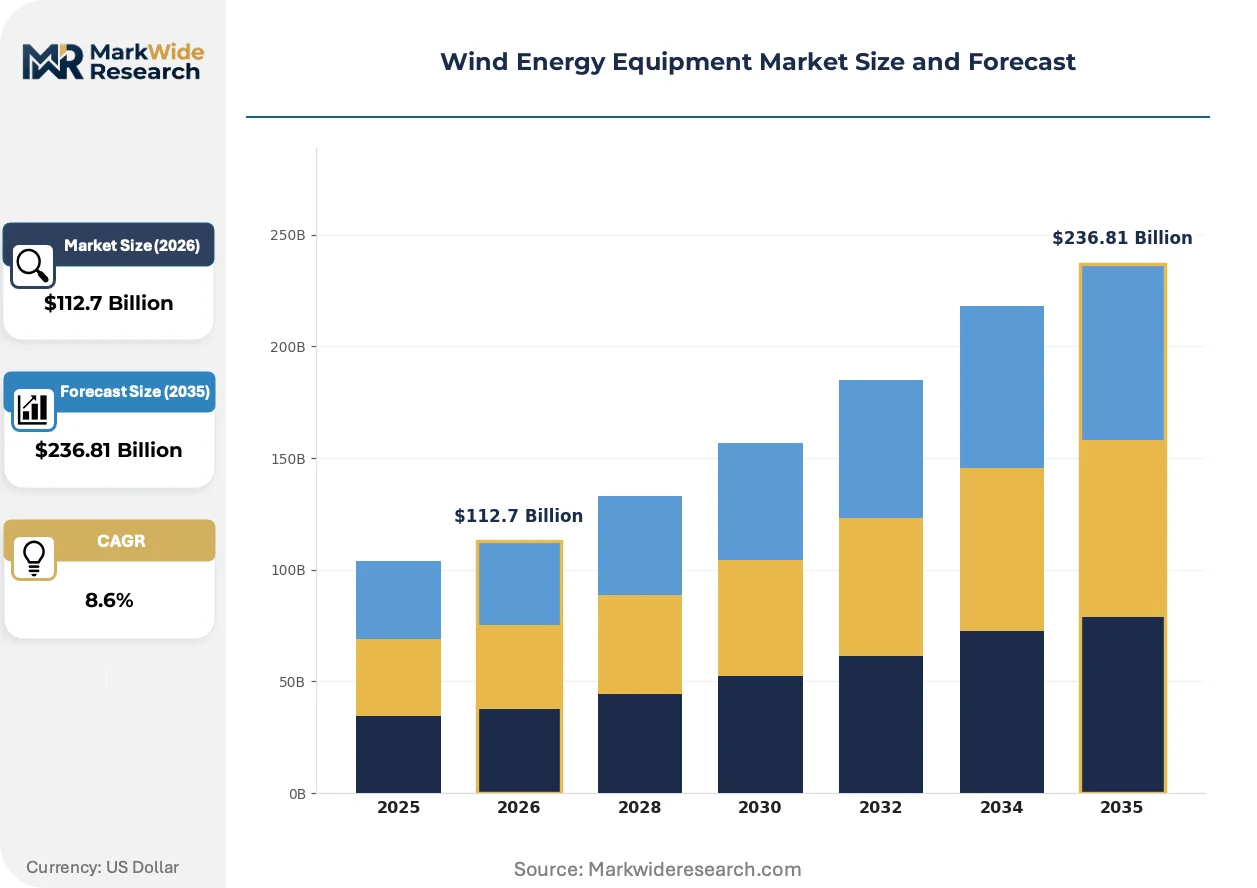
| Market Size in 2026 | $112.7 Billion |
| Market Size in 2035 | $236.81 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Turbines, Blades, Gearboxes, Control Systems Technology: Horizontal Axis, Vertical Axis, Offshore, Onshore End User: Utility Companies, Independent Power Producers, Government, Commercial Users Installation: Ground Mount, Roof Mount, Floating, Integrated Systems |
| Companies Covered | Vestas Wind Systems, Siemens Gamesa Renewable Energy, Goldwind, General Electric, Nordex SE, Enercon GmbH, Shanghai Electric, ABB, Suzlon Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Energy Equipment Market Strategic Shifts
Blade aerodynamics and control systems are converging with aviation composite methods and power electronics to push capacity factors above 50% for offshore installations. Material science advances now enable 100+ meter rotors that were structurally infeasible a decade prior.
Segmented blade manufacturing is expanding into the 80+ meter class as transport constraints force inland producers toward modular assembly. Vestas and LM Wind Power now bond blade root sections at portside facilities rather than moving complete structures over road networks. This distributed production model is compressing logistics costs for land-constrained markets.
The EU F-Gas Regulation's refrigerant phasedown is forcing generator cooling system redesigns toward air-cooled or dielectric fluid alternatives. Equipment suppliers face extended type-certification timelines as notified bodies validate thermal performance under revised IEC 60034 standards. Offshore nacelles above 8 MW rating feel the constraint most acutely given heat rejection requirements.
Utility procurement committees now unbundle operations contracts from turbine supply agreements to benchmark service pricing across independent providers. European energy majors like Ørsted and RWE tender multi-site O&M separately from initial CAPEX, compressing incumbent OEM service margins. This contract separation is most visible in the UK Round 4 and German auction rounds where 15-year service terms face competitive rebidding.
Wind Energy Equipment Market Segmentation
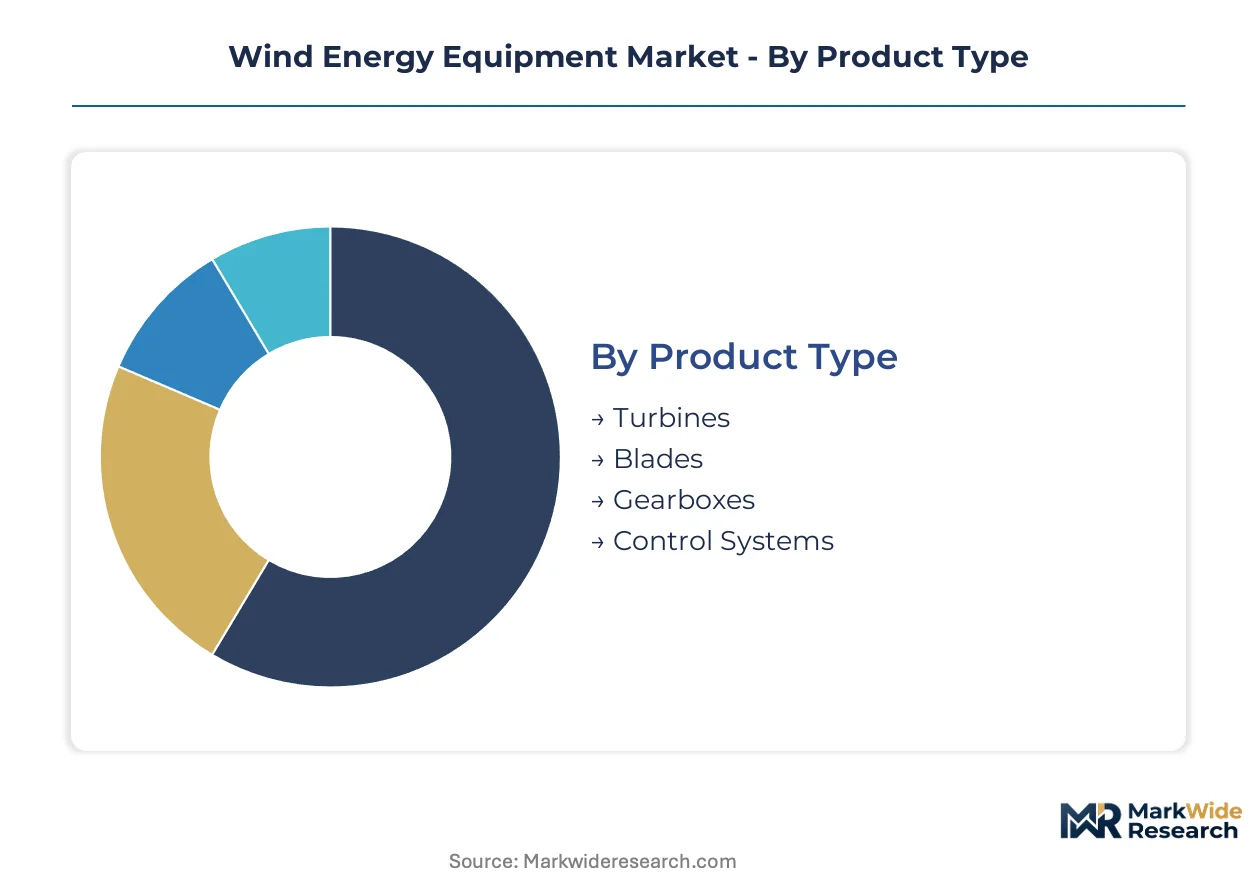
Equipment segmentation in wind energy determines procurement complexity, certification pathways, and lifecycle cost structures. Developers align segment selection with site constraints, grid requirements, and financing terms.
Product Type:
Type certification under IEC 61400-1 demands distinct test regimes for each equipment category, with offshore-rated turbines facing extended load-case validation.
- Turbines:Complete nacelle assemblies integrating rotor, drivetrain, and power electronics. Demand clusters in coastal provinces of China where MIIT enforces GB grid-code compliance for 10+ MW platforms. Certification timelines stretch 18-24 months for offshore variants.
- Blades:Carbon-fiber-reinforced polymer structures exceeding 80 meters in contemporary designs. European manufacturers bond segmented root sections at portside facilities to bypass road transport limits. IEC 61400-23 blade testing mandates full-scale fatigue validation.
- Gearboxes:Planetary and parallel-shaft speed increasers for medium-speed generator architectures. Onshore repowering projects in Germany sustain aftermarket demand despite direct-drive displacement in offshore.
- Control Systems:Pitch, yaw, and power electronics governing turbine response. Grid-forming inverters face emerging IEEE 1547-2018 compliance requirements in US interconnection queues.
Leading the category by volume: Turbines. Growing fastest: Blades.
Technology:
Technology choice dictates foundation design, maintenance access, and capacity factor expectations across project finance structures.
- Horizontal Axis:Upwind rotor configurations capturing 99% of installed capacity. Danish and Chinese developers dominate procurement of 15+ MW offshore variants requiring specialized heavy-lift vessels.
- Vertical Axis:Darrieus and H-rotor designs for distributed urban installations. Niche demand in Tokyo and Barcelona where building-integrated configurations bypass height restrictions.
- Offshore:Fixed-bottom and floating platforms in water depths exceeding 60 meters. Semi-submersible foundations unlock California and Japanese deep-water sites where fixed installation proves uneconomic.
- Onshore:Hub heights above 150 meters accessing stronger wind regimes. Repowering of 2000s-era German and Danish fleets drives replacement demand for 3-4 MW units.
Dominating capacity additions: Horizontal Axis. Expanding most quickly: Offshore.
End User:
End-user category shapes contract structures, risk allocation, and O&M unbundling trends in contemporary procurement.
- Utility Companies:Vertically integrated generators with captive balance-sheet capacity. Ørsted and RWE tender multi-site O&M separately from turbine supply in UK Round 4 auctions.
- Independent Power Producers:Project-financed developers selling output under long-term PPAs. Tax equity partnerships in US markets structure around IRA domestic content bonus capture.
- Government:State-owned enterprises anchoring national renewable targets. China's state-backed developers filter procurement toward GB-compliant domestic equipment.
- Commercial Users:Corporate offtakers securing behind-the-meter or virtual PPA arrangements. Data center operators in Virginia and Iowa drive distributed procurement.
Capturing largest procurement volume: Utility Companies. Gaining share fastest: Independent Power Producers.
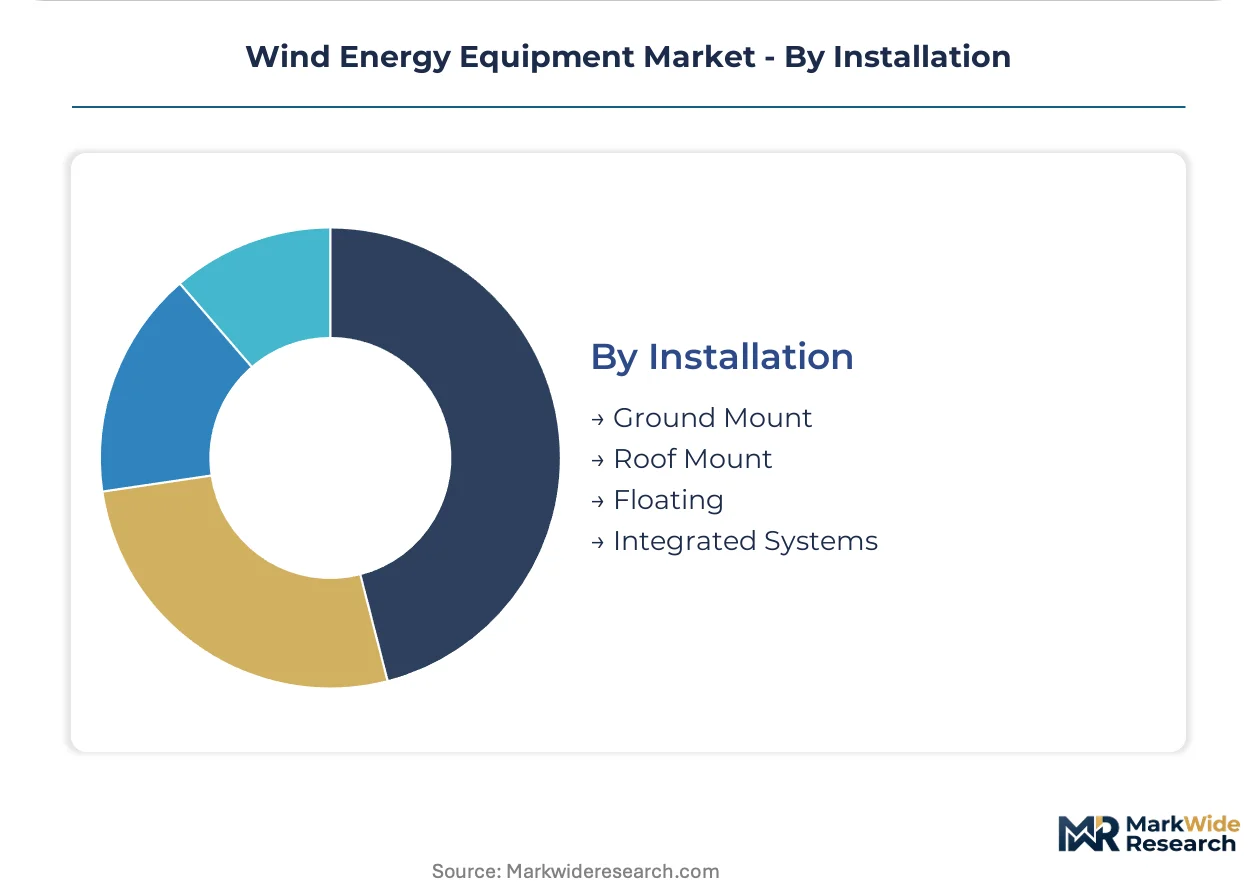
Installation:
Installation method constrains logistics, foundation cost, and site flexibility across terrain and water depth variations.
- Ground Mount:Tubular steel towers on reinforced concrete foundations. US Great Plains developers optimize for 80-140 meter hub heights with geotechnical site classes dictating embedment depth.
- Roof Mount:Small-scale urban turbines on commercial and industrial buildings. Tokyo's building codes and Barcelona's superblock planning enable distributed deployment.
- Floating:Semi-submersible and tension-leg platforms for depths beyond 60 meters. Dynamic cable supply chains remain underdeveloped for Celtic Sea and California lease areas.
- Integrated Systems:Co-located electrolyzer or storage configurations. Denmark's Energy Island concept anchors pilot hydrogen offtake demand.
Accounting for dominant deployment: Ground Mount. Steepest expansion trajectory: Floating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Inner Mongolia's rare-earth deposits anchor magnet supply for direct-drive generators. Jiangxi province concentrates dysprosium processing. These feedstock localities shape manufacturing geography across three continents.
United States
Developers in Texas and Iowa accelerate onshore procurement to capture IRA domestic content bonuses. FERC interconnection reforms compress queue timelines for Great Plains projects. Port infrastructure in New Bedford and Corpus Christi anchors nacelle assembly expansion.
China
MIIT enforces GB grid-code compliance that filters non-domestic equipment from national tenders. State-backed developers in Jiangsu and Guangdong provinces drive 10+ MW offshore installation targets. Yangtze River Delta clusters blade molding capacity for export markets.
Germany
Repowering demand from 2000s-era fleets sustains onshore turbine replacement cycles. The EU F-Gas Regulation constrains generator cooling system refrigerant choices. Hamburg and Bremerhaven anchor heavy-lift vessel chartering for North Sea offshore construction.
United Kingdom
Round 4 auction rounds unbundle O&M contracts from turbine supply agreements. Ørsted and RWE tender multi-site service terms separately from CAPEX procurement. Scottish waters host floating foundation pilots for deep-water lease areas.
Japan
METI offshore wind auctions unlock capacity factors above 50% for Kyushu and Hokkaido projects. Semi-submersible platform technology maturation targets depths beyond 60 meters. Nagasaki shipyards adapt heavy-lift capabilities for domestic installation fleets.
Wind Energy Equipment Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue floating foundation and hydrogen integration adjacencies. The vendor base stratifies across three capability tiers: full-platform OEMs, component specialists, and regional assemblers. Archetypes include rare-earth-integrated verticalists, service-network sustainers, and port-proximate fabricators. Capacity expansion and strategic partnerships dominate competitive moves as installation vessel scarcity compresses project windows.
Among Danish-origin full-platform OEMs, Vestas Wind Systems exemplifies the service-network sustainer archetype through long-term operations contract positioning. Siemens Gamesa Renewable Energy anchors European offshore supply specialization. Goldwind occupies the rare-earth-integrated verticalist tier with backward magnet supply control. These three represent distinct strategic postures within a market where technical compliance and logistics proximity increasingly determine procurement outcomes.
| Leading Market Players |
|---|
| Vestas Wind Systems |
| Siemens Gamesa Renewable Energy |
| Goldwind |
| General Electric |
| Nordex SE |
| Enercon GmbH |
| Shanghai Electric |
| ABB |
| Suzlon Energy |
| Others |
Value Chain & Pricing Dynamics
The EU F-Gas Regulation's refrigerant phasedown gates qualified supply for generator cooling systems while segmenting premium-tier pricing for compliant nacelle assemblies. OEMs bearing extended IEC 60034 certification timelines capture pricing power, whereas non-compliant suppliers face exclusion from European offshore tenders.
Pricing Analysis
Warranty and service-bundling unbundling reshapes contract structures as Ørsted and RWE tender multi-site O&M separately from turbine supply in UK Round 4 auctions. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and after-sales service depth. Cost compression in standard-tier onshore units intensifies because Chinese manufacturers compete aggressively on nacelle assembly. Independent Power Producers demonstrate highest price sensitivity, while Utility Companies absorbing long-term O&M premiums show lowest.
Supply Chain Analysis
Reverse-logistics infrastructure for blade end-of-life remains underdeveloped as thermoset carbon-fiber laminates resist pyrolysis separation. Supply concentrates in China for rare-earth magnet processing, Germany for gearbox precision manufacturing, and Denmark for nacelle assembly. Raw material flows draw from Inner Mongolia neodymium deposits, Jiangxi dysprosium refineries, and carbon-fiber precursor from Japan and the United States. Single-source vulnerability in heavy-lift vessel chartering compresses installation windows. Distribution runs through port-proximate bonding facilities for segmented blade root sections.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wind energy equipment has become a vertical-integration race. Players pursue backward integration into rare-earth permanent magnet supply to secure direct-drive generator cost structures.
For Market Incumbents: Anchor service-network density in offshore lease areas before independent O&M providers capture multi-site contracts. Siemens Gamesa and Vestas should extend port-proximate nacelle assembly capacity to compress installation vessel charter exposure. Defend against Goldwind's rare-earth-integrated verticalist model by locking long-term magnet offtake with Jiangxi processors.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in floating foundation technology offers white-space entry. Target semi-submersible platform engineering for California and Japanese deep-water sites where fixed-bottom installation proves uneconomic. Pursue electrolyzer co-location partnerships at offshore wind hubs to capture green hydrogen offtake demand.
For Investors and Strategic Acquirers: FERC interconnection queue reform acceleration is the leading indicator that US project development timelines will compress, improving developer returns. Five-to-ten year viability favors port-proximate fabricators with Jones Act-compliant assembly capabilities. Monitor charter rate trends for 1,500+ tonne crane vessels as inflection signal for installation bottleneck severity.
| Strategic Initiative | Industry Significance |
|---|---|
| Port-Proximate Nacelle Assembly | IRA domestic content bonus capture redirects capacity toward New Bedford and Corpus Christi. |
| Rare-Earth Magnet Backward Integration | Goldwind's Jiangxi supply control eliminates geopolitical exposure for direct-drive platforms. |
| Floating Foundation Technology Licensing | Semi-submersible patents unlock California and Japanese deep-water lease areas. |
| Multi-Site O&M Contract Unbundling | Ørsted and RWE tender service terms separately from CAPEX procurement in UK Round 4. |
| Green Hydrogen offtake Integration | Denmark's Energy Island concept anchors pilot electrolyzer co-location demand. |
Study Parameters
Document review covered EIA generation data, IEA renewable technology reports, FERC interconnection filings, and MIIT GB standard documentation, complemented by interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Bottom-up turbine order aggregation from project development databases was cross-referenced against top-down national installation targets. Primary fieldwork with heavy-lift vessel operators and blade molding facility managers validated logistics cost assumptions.
Historical installation trajectories were cross-referenced against panel input from OEM procurement executives to anchor growth assumptions across the analysis window. Segmentation modeling incorporated product type, technology topology, end-user contract structure, and installation method dimensions. CAGRs were derived from unit economics compression curves and policy incentive phase-in schedules. Forecast inputs included port infrastructure capacity buildout timelines and rare-earth magnet price volatility bands.
Inputs from EIA, IEA, and FERC were available through the study window; gaps in floating foundation pilot performance data introduce uncertainty bands for deep-water cost assumptions. Forecasts reflect documented assumptions regarding IRA domestic content bonus continuity and EU F-Gas Regulation enforcement intensity. Practitioners should monitor Jones Act vessel construction progress and Jiangxi rare-earth processing export licensing for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Blades NDT Market
Wind Energy Systems
Wind Energy Market
Wind Energy Systems
Peru Wind Energy Market
Wind Energy Systems
Wind Turbine Scrap Market
Wind Energy Systems
Steel Wind Tower Market
Wind Energy Systems
Europe Direct Drive Wind Turbine Market
Wind Energy Systems
Offshore Wind Turbine Blade Leading-Edge Defect Inspection Equipment Market
Wind Energy Systems
Floating Wind Power Market
Wind Energy Systems
Wind Turbine Control System Market
Wind Energy Systems
India Wind Energy Market
Wind Energy Systems
Asia-Pacific Wind Power Market
Wind Energy Systems
Wind Turbine Decommissioning Market
Wind Energy Systems
Wind Turbine Gearbox Vibration and Condition Monitoring Test Platforms Market
Wind Energy Systems
United Kingdom Renewable Energy Market
Wind Energy Systems
Europe Wind Power Market
Wind Energy Systems
Wind Power Forgings Market