
 East Europe Renewable Energy Market | 2026-2036
East Europe Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
East Europe Renewable Energy Market Foresight
Polysilicon is expanding its share in photovoltaic module supply as crystalline silicon wafers displace thin-film alternatives across East European project pipelines. Vestas Wind Systems A/S leverages its turbine servicing network to sustain aftermarket revenue across Poland and Romania. Enel Green Power S.p.A. anchors greenfield development through its operational scale in Bulgaria and Greece. Hanwha Q Cells Co., Ltd. differentiates via n-type TOPCon cell efficiency gains that improve yield-per-watt in suboptimal irradiance zones.
East Europe renewable energy encompasses power generation systems harnessing solar irradiance, wind kinetic energy, biomass combustion, and hydroelectric head to produce electricity with near-zero operational emissions, typically utilizing turbine-generator sets with 25-40 year asset lifespans and inverter efficiencies exceeding 98%. The technology dimension spans solar, wind, biomass, and hydro, with onshore wind holding mature installed capacity across the Carpathian corridor while utility-scale solar claims the fastest capacity addition rates. Grid-tied applications dominate financing structures, though distributed generation segments attract commercial-industrial offtakers seeking behind-the-meter supply security.
The EU Green Deal and REPowerEU framework shape capacity auctions and cross-border interconnection targets, while national regulators in Poland and Romania implement Contracts-for-Difference mechanisms that de-risk developer returns. ECHA chemical compliance and REACH substance restrictions govern solar panel end-of-life protocols and biomass fuel quality standards. Stakeholders must monitor auction clearing prices and grid queue congestion as the primary signals for project viability and capital allocation timing.
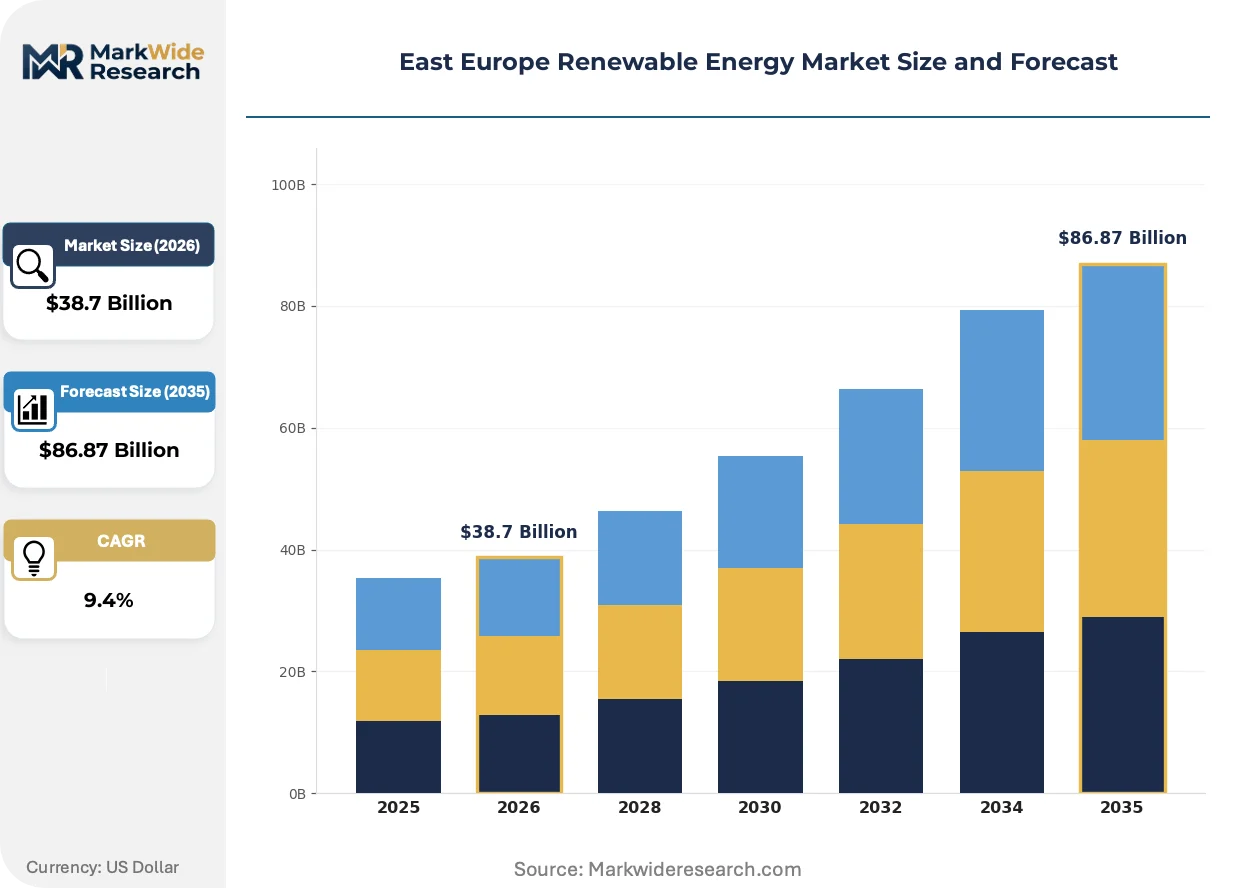
Market Dynamics
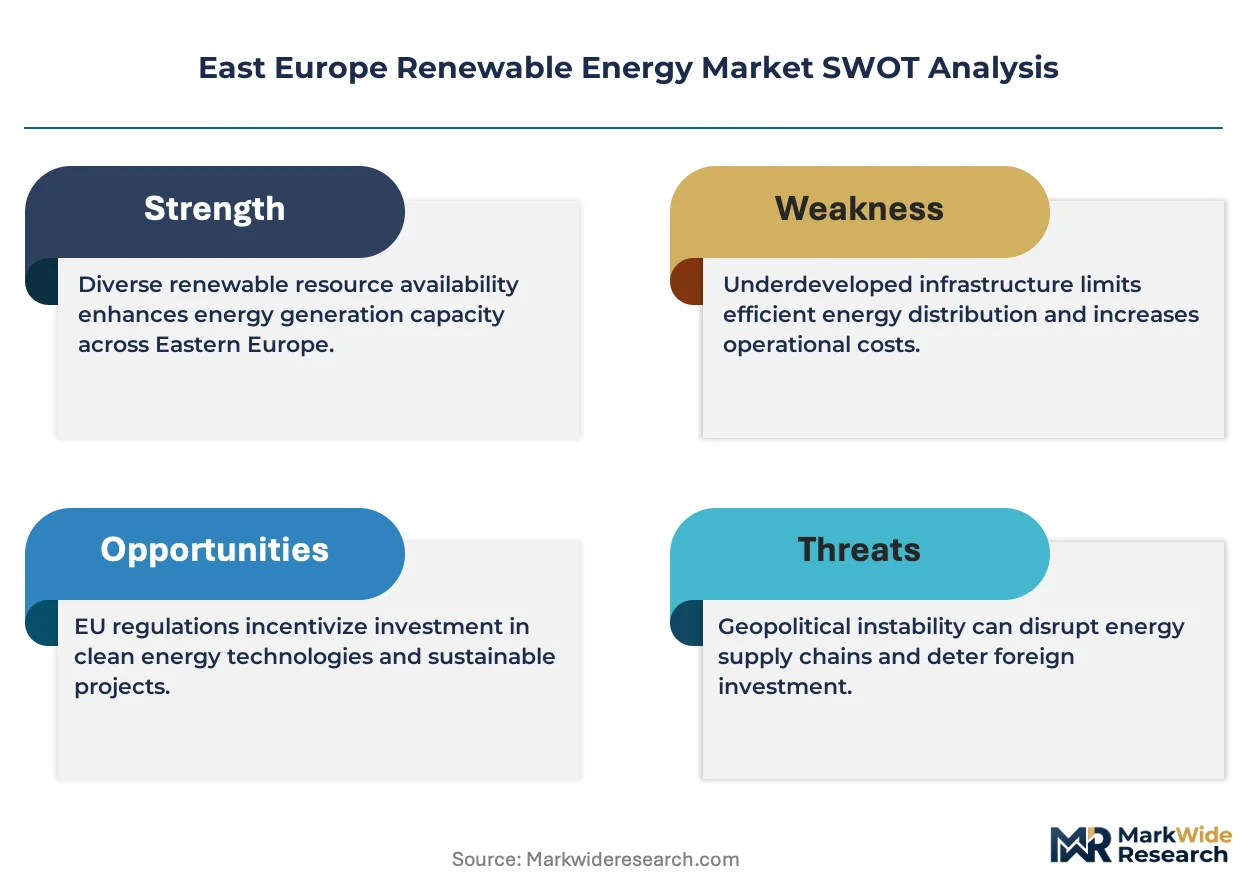
Grid interconnection bottlenecks across Poland and Romania are forcing developers toward hybrid solar-plus-storage configurations that bypass transmission queue congestion and capture higher merchant margins.
Growth Catalysts
- REPowerEU framework:The EU's accelerated renewable targets and hydrogen bank financing de-risk capital deployment for greenfield projects across Bulgaria and Greece.
- Industrial manufacturing procurement:Polish automotive and Romanian steel facilities are signing long-term power purchase agreements to hedge against volatile natural gas pricing.
- Polysilicon supply localization:Crystalline silicon wafer production expansion in the Czech Republic and Hungary shortens module delivery lead times for regional developers.
Market Restraints
- Copper and rare earth price volatility:Turbine generator sets and power electronics remain exposed to concentrated Chinese processing capacity for neodymium and dysprosium.
- Grid queue congestion:Romania's Transelectrica and Poland's PSE face 18-24 month connection timelines for utility-scale projects in high-resource zones.
- Biomass fuel quality variance:Inconsistent agricultural residue moisture content and ash composition limit combustion efficiency in Balkan district heating systems.
Strategic Opportunities
- Green hydrogen pilot corridors:Bulgaria's Black Sea port infrastructure and Greece's DESFA pipeline network enable export-oriented electrolyzer deployment.
- Distributed commercial generation:Behind-the-meter solar installations for Hungarian food processing and Slovak automotive suppliers bypass grid interconnection delays.
- EU Carbon Border Adjustment Mechanism:The CBAM creates cost pressure on imported aluminum and cement that accelerates on-site renewable adoption for energy-intensive exporters.
Industry Challenges
- HVDC converter station commissioning:Specialized technician shortages delay synchronization of Romania's 400 kV corridor upgrades with neighboring grids.
- Module recycling compliance:ECHA's evolving substance restrictions and national extended producer responsibility schemes impose unproven end-of-life cost structures on solar asset owners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | East Europe Renewable Energy Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar, Wind, Biomass, Hydro End User: Residential, Commercial, Industrial, Government Service Type: Installation, Maintenance, Consulting, Financing Application: Grid-Tied, Off-Grid, Hybrid, Distributed Generation |
| Companies Covered | Federal Hydro-Generating Co RusHydro PAO, Vestas Wind Systems A/S, Enel Green Power S.p.A., NOTUS Energy GmbH, SGS SA, Wärtsilä Oyj Abp, Hanwha Q Cells Co., Ltd., Schneider Electric SE, C&C Energy SRL, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
East Europe Renewable Energy Market Shifts & Advancements
Technology convergence between power electronics and grid-forming inverters is compressing system integration timelines while enabling higher renewable penetration rates without synchronous generation backup.
n-type TOPCon cell architecture is overtaking p-type PERC dominance across East European utility-scale procurement. Polish and Romanian developers specify TOPCon modules for their superior temperature coefficient and bifaciality gains in suboptimal irradiance conditions. The technology is overtaking thin-film alternatives in distributed commercial segments where roof space constraints maximize yield-per-watt economics.
The EU Green Deal's delegated acts on renewable energy deployment tighten sustainability criteria for biomass feedstocks and solar panel carbon footprint declarations. Industrial offtakers in Hungary and Slovakia now require module supply chain documentation that traces polysilicon origin and manufacturing energy intensity. Project finance institutions are embedding these compliance timelines into construction loan covenants, accelerating supplier certification investments.
Aggregated power purchase agreements are consolidating procurement for mid-sized manufacturing clusters in Poland's Silesian industrial belt. Energy service companies are underwriting behind-the-meter solar and battery installations in exchange for long-term energy management contracts that guarantee price ceilings. This model is displacing traditional utility supply arrangements for Romanian textile and automotive component suppliers seeking budget predictability.
East Europe Renewable Energy Market Segmentation
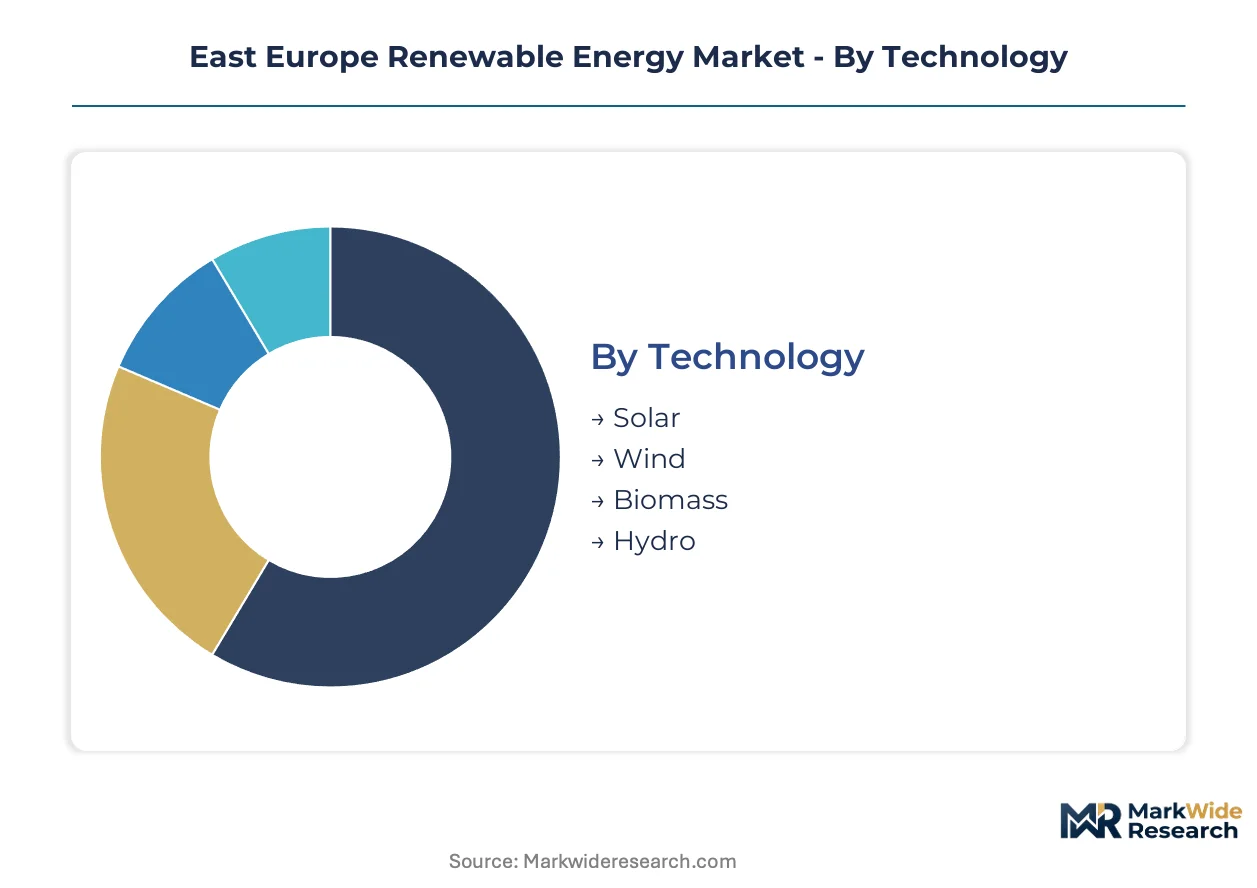
Technology choices in East Europe reflect resource endowment and grid infrastructure maturity. End-user procurement patterns diverge sharply between state-backed auctions and private offtake. Service providers must align capabilities with the region's hybrid project surge and distributed generation pivot.
Technology:
Supply concentration in turbine manufacturing and polysilicon refining shapes technology deployment economics across Poland and Romania.
- Solar:Crystalline silicon modules dominate procurement, with n-type TOPCon cells displacing p-type PERC in utility-scale tenders. Polish developers in the Lublin corridor and Romanian projects in the Black Sea hinterland prioritize bifacial panels for yield-per-watt optimization under variable irradiance.
- Wind:Onshore turbines anchor installed capacity across the Carpathian belt, where Vestas and Siemens Gamesa service networks sustain aftermarket revenue. Grid queue congestion in high-resource zones is forcing repowering investments at 15-year-old sites rather than greenfield expansion.
- Biomass:Agricultural residue combustion supplies district heating in Balkan municipalities. Inconsistent fuel quality and ECHA emissions compliance limit scaling beyond captive industrial heat applications.
- Hydro:Run-of-river installations in Bulgaria's Rhodope foothills provide baseload complement to variable solar and wind. Small-scale projects under 10 MW face environmental permitting delays that extend development timelines.
Today's leader: Solar. Tomorrow's challenger: Wind repowering.
End User:
Cost tier stratification separates price-sensitive residential adopters from industrial offtakers seeking long-term hedge structures.
- Residential:Rooftop solar deployments concentrate in Hungarian suburbs and Czech exurbs, driven by net metering tariffs and green mortgage incentives. Battery attachment rates remain below commercial segments due to payback period sensitivity.
- Commercial:Behind-the-meter installations for Slovak automotive suppliers and Polish food processors bypass grid interconnection queues. Energy service companies underwrite capex in exchange for 10-15 year energy management contracts.
- Industrial:Steel and aluminum producers in Romania's Galati corridor and Poland's Silesian belt sign aggregated power purchase agreements to satisfy EU Carbon Border Adjustment Mechanism compliance. Procurement teams require module supply chain documentation tracing polysilicon origin.
- Government:State-owned utilities in Bulgaria and Greece administer Contracts-for-Difference auctions that set clearing prices for utility-scale deployment. Ministries of energy prioritize cross-border interconnector synchronization over pure generation subsidies.
Industrial procurement commands premium pricing for bankable offtake structures. Commercial distributed generation is climbing fastest.
Service Type:
Margin compression in commoditized installation is pushing providers toward integrated financing and long-term asset management.
- Installation:EPC contractors face skilled technician shortages for HVDC converter station commissioning. Romanian and Polish grid synchronization projects compete for the same specialized labor pool.
- Maintenance:Turbine servicing networks generate recurring revenue for OEMs with established East European presence. Predictive analytics contracts are displacing time-based maintenance schedules.
- Consulting:Permitting advisory and grid queue navigation support developer returns in congested zones. Regulatory compliance services expand with ECHA substance restriction evolution.
- Financing:Green bonds and EU hydrogen bank facilities de-risk capital deployment for electrolyzer corridors. Project finance institutions embed supply chain documentation requirements into construction loan covenants.
Financing services capture the widest margins. Installation is commoditizing fastest.
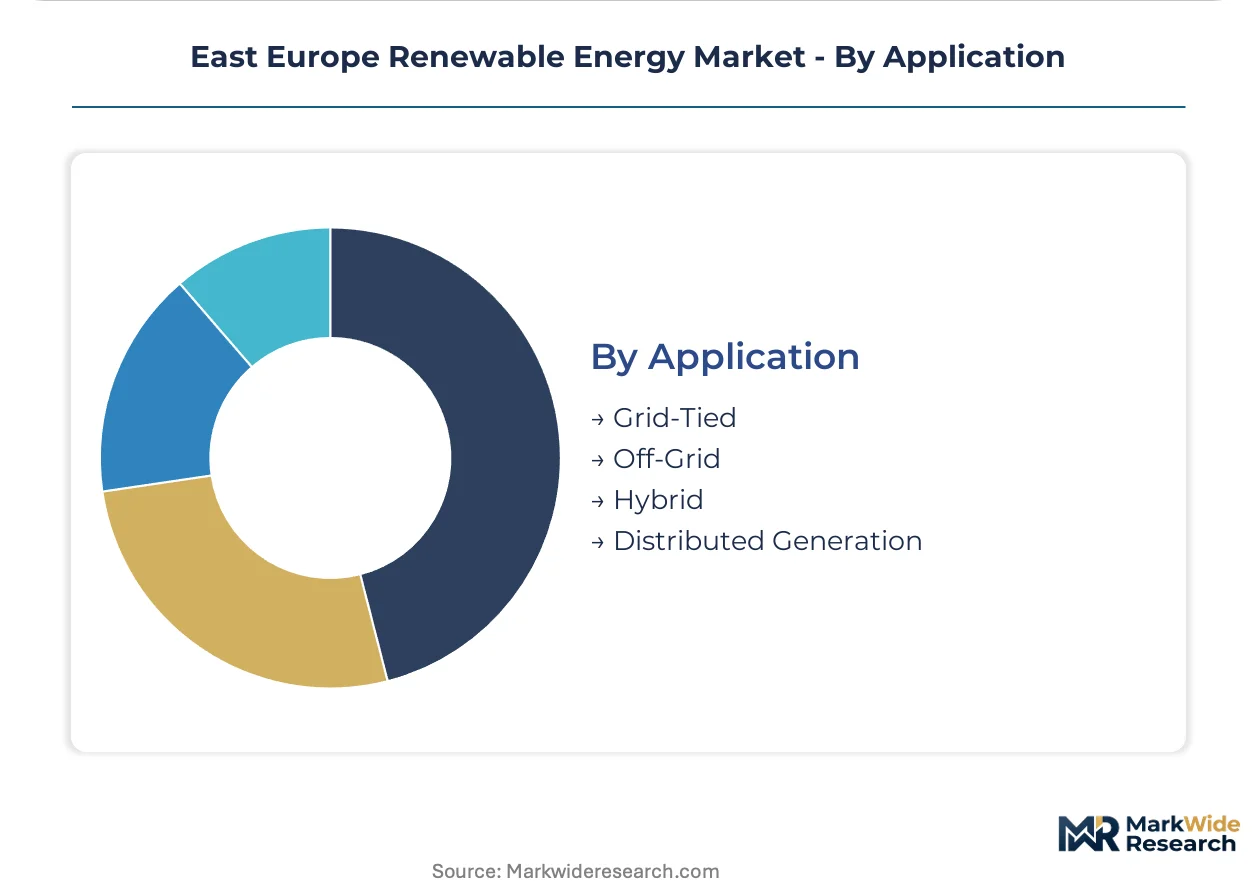
Application:
Geography dictates application choice, with grid-tied projects clustering near transmission infrastructure and off-grid solutions penetrating remote industrial sites.
- Grid-Tied:Utility-scale solar and wind connect through Poland's PSE and Romania's Transelectrica networks. Auction mechanisms allocate connection capacity, creating 18-24 month queues in high-resource zones.
- Off-Grid:Remote industrial facilities in Bulgaria's mining districts and Greek island resorts deploy diesel-solar hybrid systems. Battery storage sizing determines economic viability against grid extension costs.
- Hybrid:Solar-plus-storage configurations bypass transmission congestion and capture merchant margin upside. Polish developers pair midday solar generation with evening peak pricing arbitrage.
- Distributed Generation:Commercial-industrial behind-the-meter supply secures budget predictability for Romanian textile and automotive component exporters facing CBAM compliance pressure.
Grid-tied deployment holds current volume leadership. Hybrid configurations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland's Silesian industrial belt drives procurement velocity across East Europe as manufacturers confront EU Carbon Border Adjustment Mechanism compliance deadlines and volatile natural gas pricing.
Poland
Steel and automotive clusters in Katowice and Krakow sign aggregated power purchase agreements to hedge energy costs. The Contracts-for-Difference mechanism administered by the Energy Regulatory Office sets auction clearing prices that de-risk developer returns. Utility-scale solar corridors in the Lublin region attract capital as grid interconnection queues extend to 24 months.
Romania
Aluminum smelters in the Galati corridor and Constanta port industrial zone procure bankable offtake structures. Transelectrica faces synchronization delays for 400 kV corridor upgrades with neighboring Bulgarian and Hungarian grids. Onshore wind repowering investments concentrate in the Carpathian foothills where 15-year-old turbine sites bypass greenfield permitting.
Bulgaria
Black Sea port infrastructure enables export-oriented green hydrogen pilot deployment backed by EU hydrogen bank facilities. Run-of-river hydro installations in the Rhodope foothills provide baseload complement to variable solar generation. The Ministry of Energy prioritizes cross-border interconnector synchronization over pure generation subsidies.
Hungary
Food processing and automotive component suppliers in the Budapest-Szekesfehervar industrial axis deploy behind-the-meter solar to bypass grid queue congestion. Net metering tariffs and green mortgage incentives accelerate suburban rooftop installations. ECHA chemical compliance requirements shape module supply chain documentation for industrial offtakers.
Greece
The DESFA pipeline network anchors electrolyzer corridors targeting export markets. Island resorts and remote mining districts deploy diesel-solar hybrid systems where grid extension costs exceed battery storage economics. Enel Green Power's operational scale sustains greenfield development momentum despite permitting delays for small-scale hydro projects under 10 MW.
East Europe Renewable Energy Market Competitive Landscape
Global majors compete with regional champions across turbine servicing networks and module supply chain localization. The vendor base stratifies into three tiers: integrated European utilities with auction execution capabilities, Asian module manufacturers with n-type cell efficiency advantages, and specialized regional developers with permitting advisory expertise. Strategic moves center on hybrid project configuration capabilities and long-term asset management contracts that displace traditional EPC arrangements.
Among European-based integrated utilities, Enel Green Power S.p.A. and Vestas Wind Systems A/S exemplify distinct competitive positions. Enel Green Power anchors greenfield development through operational scale in Bulgaria and Greece, while Vestas leverages its turbine servicing network to sustain aftermarket revenue across Poland and Romania. Hanwha Q Cells Co., Ltd. represents the Asian module manufacturing archetype, differentiating via n-type TOPCon cell efficiency gains. NOTUS Energy GmbH and C&C Energy SRL occupy positions within the specialized regional developer tier, navigating grid queue congestion and permitting complexity.
| Leading Market Players |
|---|
| Federal Hydro-Generating Co RusHydro PAO |
| Vestas Wind Systems A/S |
| Enel Green Power S.p.A. |
| NOTUS Energy GmbH |
| SGS SA |
| Wärtsilä Oyj Abp |
| Hanwha Q Cells Co., Ltd. |
| Schneider Electric SE |
| C&C Energy SRL |
| Others |
Supply & Pricing Matrix
Industrial offtakers in Poland's Silesian belt and Romania's Galati corridor anchor the dominant contract-based long-term offtake pricing model, with aggregated power purchase agreements locking in cost predictability against volatile natural gas benchmarks. Their procurement concentration forces developers toward bankable structures that de-risk capital deployment through fixed-price tenors and supply chain documentation requirements.
Pricing Analysis
Input-cost pass-through from polysilicon and rare earth processing drives module and turbine pricing volatility across East European project pipelines. Pricing stratifies across premium n-type TOPCon modules with full supply chain traceability, standard p-type PERC units for utility-scale tenders, and economy thin-film alternatives in distributed commercial segments. Cost compression in standard-tier crystalline silicon is intensifying as Czech and Hungarian wafer localization shortens delivery lead times. Residential rooftop adopters in Hungarian suburbs exhibit highest price sensitivity due to payback period thresholds, while industrial aluminum and steel producers accept premium pricing for CBAM-compliant bankable offtake structures.
Supply Chain Analysis
Freight cost escalation from Asia-Europe container routes and Black Sea corridor disruptions is compressing margins for module importers serving Polish and Romanian developers. Manufacturing concentration in China for polysilicon refining and Vietnam for cell assembly feeds East European procurement, with neodymium and dysprosium processing concentrated in Chinese facilities. Single-source vulnerability in rare earth magnet supply for turbine generator sets poses structural risk for Carpathian wind repowering timelines. Distribution runs through EPC contractor networks with established grid queue navigation capabilities, bypassing direct developer-procurement relationships in congested interconnection zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
East Europe renewable energy offers margin expansion through n-type cell efficiency premiums and localized polysilicon supply that compresses logistics exposure. Industrial offtaker procurement concentration supports pricing power for bankable offtake structures.
For Market Incumbents: To counter grid queue congestion eroding project returns, Vestas and Enel Green Power should deepen service network density in Poland and Romania while securing backward integration into Czech polysilicon supply. Captive wafer sourcing shortens module delivery timelines and insulates against Asia-Europe freight volatility. For New Entrants and Emerging Players: Enter via behind-the-meter commercial solar installations for Slovak automotive suppliers and Hungarian food processors, where grid interconnection bypass commands merchant margin premiums. The most penetrable segment is distributed generation with energy service company financing, using 10-15 year energy management contracts that displace traditional utility supply arrangements. For Investors and Strategic Acquirers: Integrated European utilities with auction execution capabilities are the most active acquirer in this space, consolidating regional developers with permitting advisory expertise and hybrid project pipelines. Long-term viability centers on electrolyzer corridor positioning for hydrogen export through Bulgaria's Black Sea ports and Greece's DESFA network. The signal to monitor is Contracts-for-Difference auction clearing prices in Warsaw and Bucharest as inflection indicators for capital allocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Solar-Plus-Storage Deployment | Polish developers capture evening peak pricing arbitrage while bypassing Transelectrica queue congestion. |
| n-Type TOPCon Cell Manufacturing Localization | Czech and Hungarian wafer expansion shortens module delivery lead times for regional project pipelines. |
| Green Hydrogen Electrolyzer Corridor Development | Bulgaria's Black Sea ports and Greece's DESFA network enable export-oriented hydrogen bank financing. |
| Turbine Repowering Investment | Romanian Carpathian sites bypass greenfield permitting delays while leveraging existing grid infrastructure. |
| Behind-the-Meter Energy Service Contracts | Slovak automotive suppliers secure budget predictability through 10-15 year energy management agreements. |
Research Methodology
Multiple input streams — primary interviews with IPP project developers, EPC contractors, and utility planning officers; secondary validation through EIA data, IEA reports, and project development databases; plus regulatory filing analysis — were reconciled through bottom-up capacity addition modeling and top-down policy target triangulation. Stakeholder conversations spanned Warsaw, Bucharest, and Sofia, with secondary sources including FERC-equivalent grid operator disclosures and EU hydrogen bank facility documentation.
Historical capacity deployment patterns were cross-referenced against expert panel inputs on auction clearing price trajectories and interconnection queue timelines. The analytical framework segmented by fuel source, generation capacity tier, and regulatory framework across the projection horizon. CAGRs were derived from installed capacity buildout curves and merchant margin sensitivity to natural gas price volatility, with technology cost curves for n-type cell manufacturing feeding module price forecasts.
Inputs from grid operators and ministry energy planners were available through the study window; gaps in real-time auction clearing data and electrolyzer project financing terms introduce uncertainty bands around hydrogen corridor timing. Forecasts reflect modeled assumptions on EU Green Deal delegated act implementation and REPowerEU funding disbursement velocity. Stakeholders should weight assumptions against their own operating context and regulatory compliance timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
PV Water Heater Market
Renewable Energy
Solar Traffic Light Market
Renewable Energy
Solar Farm Market
Renewable Energy
Point Absorber Market
Renewable Energy
Renewable Energy Enclosures Market
Renewable Energy
Algeria Renewable Energy Market
Renewable Energy
Philippines Renewable Energy Market
Renewable Energy
Renewable Energy Certificate Market
Renewable Energy
Green Power Market
Renewable Energy
Biomethane Certificate Trading Platform Market
Renewable Energy
Renewable Energy Policy Fit Analysis Market
Renewable Energy
Denmark Renewable Energy Market
Renewable Energy
Renewable Heating Market
Renewable Energy
Solar Showers Market
Renewable Energy
Global Solar Home Lighting Market
Renewable Energy
Solar Chimney Market