
 Hybrid Solar Wind System Market | 2026-2036
Hybrid Solar Wind System Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Solar Wind System Market Analysis
The EU Green Deal is expanding the cost-of-entry calculus for hybrid system manufacturers targeting European deployment. Siemens Gamesa Renewable Energy leverages its turbine engineering heritage to anchor large-scale hybrid projects across multiple continents. General Electric competes through integrated power electronics that merge solar inverters with wind converter platforms. Supernova Technologies specializes in compact residential hybrid kits that occupy the distributed generation niche with simplified installation protocols.
A hybrid solar wind system combines photovoltaic arrays with horizontal or vertical axis wind turbines, battery storage, and unified power conditioning electronics into a single dispatchable generation asset typically rated from kilowatts to multi-megawatts. The primary purpose is to flatten renewable output variability and extend capacity factor beyond what either source achieves independently. Grid-tied configurations dominate installed capacity where interconnection standards permit, while off-grid and microgrid segments capture the fastest growth in islanded industrial and remote location applications. Solar panels and battery components concentrate margin pools as crystalline silicon module prices compress and lithium-ion storage becomes the dominant cost stack in new installations.
The EPA enforces emissions benchmarks that indirectly elevate hybrid renewables against diesel backup in US industrial settings, while India's CEA mandates renewable purchase obligations that utilities satisfy partly through hybrid wind-solar parks. ISO 61400 standards for wind turbine design and IEC 61215 for photovoltaic module qualification create product certification barriers that filter non-compliant suppliers from tender participation. Stakeholders must monitor how evolving grid codes in priority markets redefine frequency response requirements for hybrid assets and whether storage duration mandates shift component procurement strategies.
Market Dynamics
India's PLI scheme for domestic solar and wind component manufacturing is redirecting supply chains toward localized production, compressing import dependency and reshaping procurement geography for hybrid renewable assets.
Growth Catalysts
- Sub-Saharan Africa Grid Instability:Unreliable grid infrastructure across Nigeria, Kenya, and Ghana pushes commercial users toward self-contained hybrid systems for mining and telecom operations.
- CEA Renewable Purchase Obligations:India's Central Electricity Authority mandates that utilities satisfy renewable targets partly through hybrid wind-solar parks, creating tender-driven demand.
- Lithium-Ion Storage Cost Curves:Declining battery pack economics enable longer-duration hybrid configurations that flatten renewable output variability.
Market Restraints
- Polysilicon Supply Concentration:Crystalline silicon module production clusters in Xinjiang and Sichuan provinces create geopolitical and logistics risk for solar-wind hybrid developers.
- ISO 61400 Certification Barriers:Wind turbine design standards filter non-compliant suppliers from tender participation, elevating engineering costs for smaller entrants.
- Diesel Backup Substitution Threat:Mature genset infrastructure and established fuel supply chains in remote industrial sites delay hybrid adoption where capex constraints dominate.
Strategic Opportunities
- India Domestic Manufacturing:PLI incentives for solar cells, modules, and wind turbine components create captive supply advantages for localized hybrid system assembly.
- Green Hydrogen Integration:Converging electrolyzer loads with hybrid renewable generation enables round-the-clock hydrogen production at remote industrial clusters.
- EU Green Deal Carbon Border Adjustments:The carbon border mechanism elevates hybrid renewables against fossil backup for European industrial offtakers seeking scope compliance.
Industry Challenges
- Power Electronics Integration Complexity:Unified inverter-converter architectures for solar-wind-battery coordination require scarce firmware and grid-code expertise.
- IEC 61215 Certification Timelines:Photovoltaic module qualification protocols extend product launch cycles, compressing competitive response windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Solar Wind System Market |
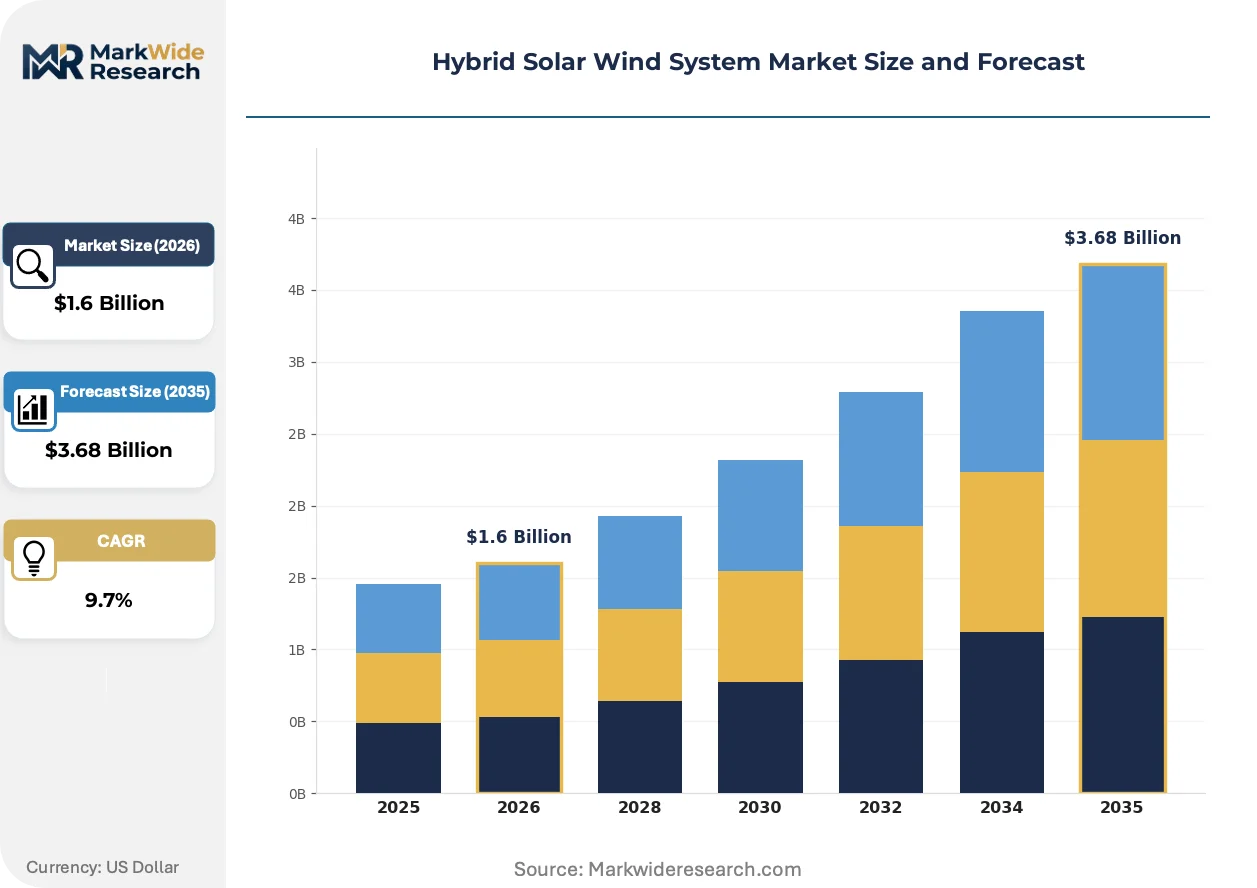
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $3.68 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Grid-Tied, Off-Grid, Microgrid, Hybrid Systems Application: Residential, Commercial, Industrial, Remote Locations Component: Inverters, Turbines, Batteries, Solar Panels End User: Utilities, Agricultural Sector, Defense, Others |
| Companies Covered | Siemens Gamesa Renewable Energy, General Electric, Blue Pacific Solar Product, Inc., Alpha Windmills, ReGen Powertech, Supernova Technologies, UNITRON Energy System Pvt. Ltd., Zenith Solar Systems, Alternate Energy Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Solar Wind System Market Emerging Trajectories
Technology convergence between photovoltaic arrays and advanced wind turbine architectures is compressing system footprints and enabling modular deployment models that bypass traditional utility interconnection queues.
Vertical-axis wind turbines paired with bifacial solar panels are rewriting the economics of distributed hybrid generation. Remote mining operators in Australia and Chile deploy these integrated units to displace diesel fuel consumption. The technology is compressing payback periods below conventional separate-system installations.
The EU Green Deal's expanding cost-of-entry calculus is elevating hybrid system specifications for European deployment. Manufacturers must now document embedded carbon and circularity credentials to participate in tender processes. Nordic utilities are responding by mandating extended producer responsibility clauses in procurement contracts.
Industrial offtakers are consolidating vendor relationships around integrated hybrid providers that bundle engineering, storage, and long-term service. Equipment distributors in Sub-Saharan Africa are ceding ground to direct manufacturer-to-project-developer contracting. This channel compression is most visible across Nigerian and Kenyan commercial and industrial segments where capital efficiency dictates single-source accountability.
Hybrid Solar Wind System Market Segmentation
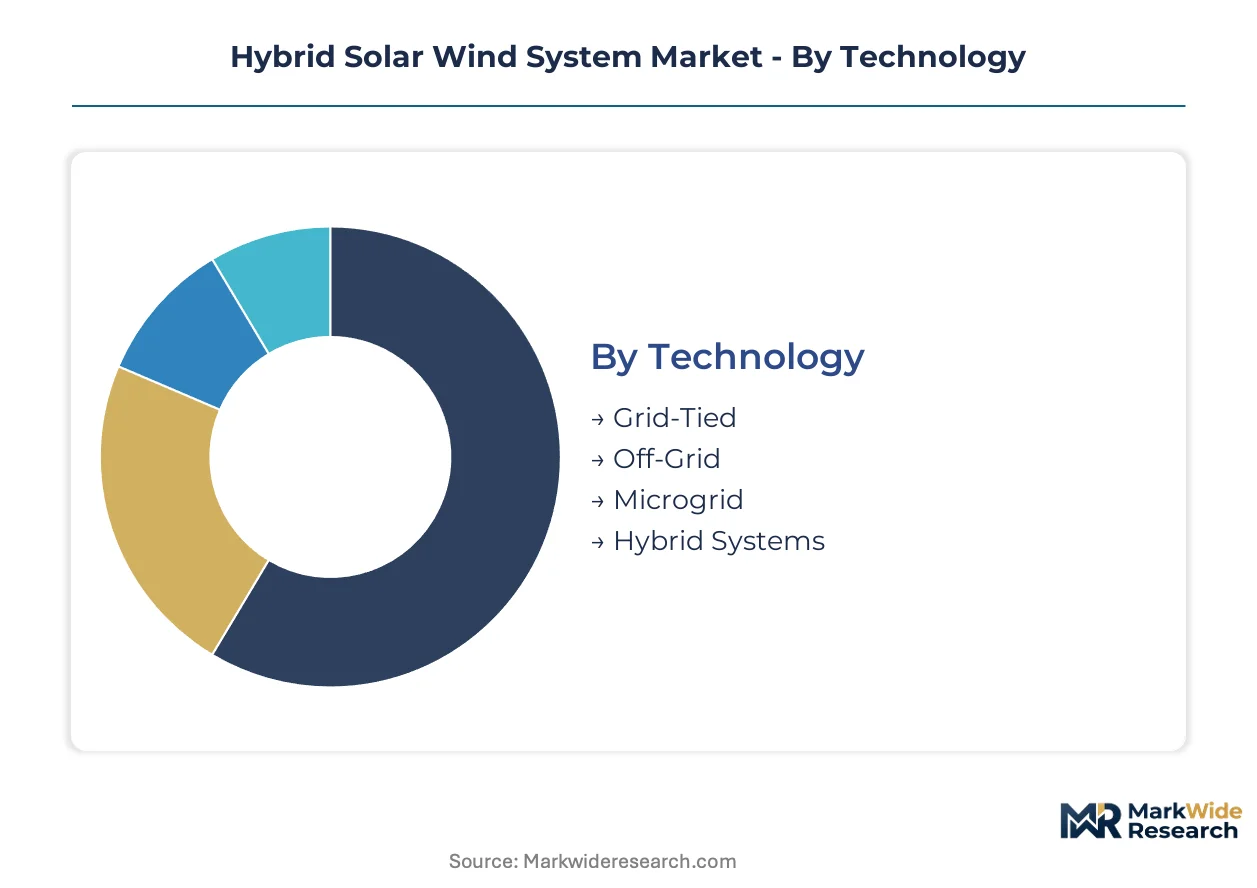
Technology architecture determines dispatch capability and revenue model for hybrid solar wind deployments. Application context drives component sizing and storage duration requirements. End user procurement patterns shape whether systems integrate with existing infrastructure or operate as islanded assets.
Technology:
System topology dictates interconnection standards, storage integration depth, and operational autonomy levels across deployment scenarios.
- Grid-Tied:Configurations synchronize with utility frequency standards to export surplus generation and import during renewable shortfalls. Indian utilities under CEA renewable purchase obligations procure these systems to satisfy hybrid wind-solar park mandates. Grid-Tied leads on scale; Microgrid leads on momentum.
- Off-Grid:Islanded architectures integrate battery storage and diesel backup for complete energy autonomy without utility interconnection. Nigerian mining operators and Ghanaian telecom towers favor these units where grid extension proves uneconomical.
- Microgrid:Localized generation networks serving multiple loads with intelligent load management and peer-to-peer energy trading capabilities. Chilean remote industrial clusters deploy these to aggregate multiple hybrid assets into dispatchable clusters.
- Hybrid Systems:Integrated solar-wind-battery platforms with unified power conditioning electronics and single-point control interfaces. Australian off-grid stations specify these for simplified procurement and single-vendor accountability.
Grid-Tied dominates installed capacity; Microgrid configurations expand most quickly in islanded industrial applications.
Application:
Load profile intensity and reliability requirements segment procurement specifications across customer archetypes.
- Residential:Distributed generation kits rated 5-20kW serving single-family homes with net metering or complete autonomy. Kenyan rural electrification programs subsidize these units where grid penetration remains below 30%.
- Commercial:Mid-scale systems 50kW-2MW powering retail, hospitality, and office facilities with peak shaving and backup functions. South African shopping centers deploy these to mitigate load shedding frequency.
- Industrial:Heavy-load configurations 2-50MW with high-capacity factor requirements and 24/7 operational mandates. Remote Australian iron ore mines specify these to displace diesel fuel consumption exceeding 10 million liters annually.
- Remote Locations:Self-contained units designed for minimal maintenance access and extreme climate resilience. Chilean copper extraction sites and Saudi Aramco desert facilities represent core demand concentration.
Industrial applications command the highest average system ratings; Remote Locations gain share fastest as extraction industries electrify.
Component:
Cost stack concentration and supply chain geography differentiate margin capture across the bill of materials.
- Inverters:Power electronics converting variable DC output from solar arrays and wind turbines to grid-synchronous AC with MPPT and frequency regulation functions. India's PLI scheme incentivizes domestic manufacturing of these units to reduce import dependency.
- Turbines:Horizontal and vertical axis wind generators capturing kinetic energy with rotor diameters scaling from residential 1-meter units to utility-scale 120-meter machines. ISO 61400 certification requirements filter non-compliant suppliers from tender participation.
- Batteries:Lithium-ion storage systems providing ramp rate control, frequency regulation, and multi-hour discharge duration. Declining pack economics enable longer-duration configurations that flatten renewable output variability.
- Solar Panels:Crystalline silicon photovoltaic modules comprising the largest surface area and capital cost share in hybrid installations. Polysilicon supply concentration in Xinjiang and Sichuan provinces creates geopolitical and logistics risk for developers.
Solar Panels represent the largest cost component; Batteries capture the steepest expansion trajectory as duration requirements lengthen.
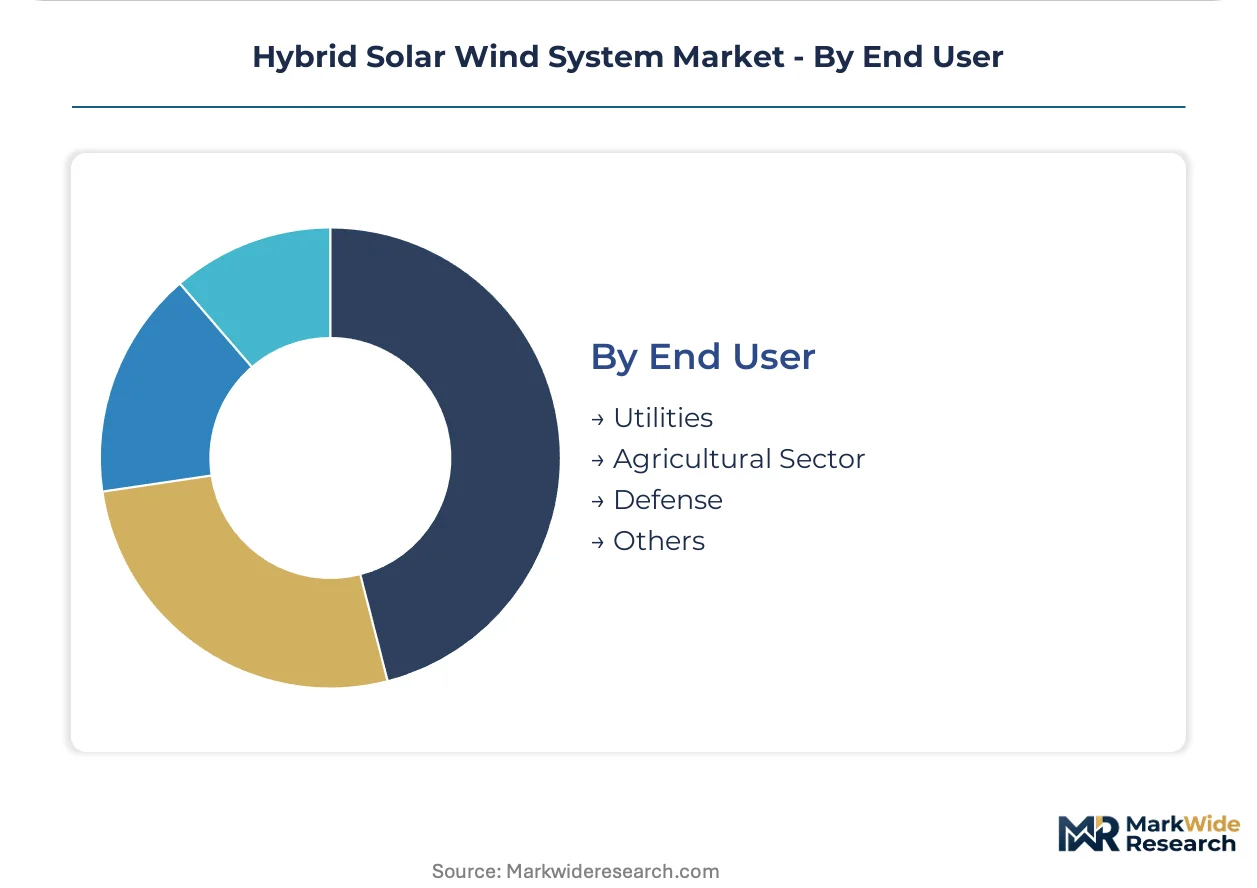
End User:
Procurement sophistication and financing capacity determine whether deployments proceed through tender, direct negotiation, or subsidy programs.
- Utilities:Centralized power purchasers issuing competitive tenders for hybrid wind-solar parks with grid integration obligations. Indian state distribution companies dominate this segment under CEA-mandated renewable purchase obligations.
- Agricultural Sector:Irrigation pumping and cold chain operators seeking tariff reduction and supply reliability. Kenyan flower exporters and Chilean vineyard operators deploy these systems to secure power quality for processing facilities.
- Defense:Military installations requiring energy security, electromagnetic resilience, and operational autonomy from civilian grid infrastructure. Forward operating bases in remote theaters specify containerized hybrid units with rapid deployment protocols.
- Others:Telecommunications towers, healthcare facilities, and educational institutions with specialized reliability requirements. Nigerian MTN and Airtel tower portfolios represent significant aggregate demand.
Utilities lead on procurement volume; Defense contracts expand most quickly amid base electrification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Germany and India anchor hybrid system development, while procurement gravity shifts toward Sub-Saharan Africa and South American mining corridors where grid instability and diesel displacement create urgent demand.
India
Domestic manufacturing capacity expansion under the PLI scheme compresses import dependency for solar cells, modules, and wind turbine components. The CEA mandates renewable purchase obligations that utilities satisfy through hybrid wind-solar park tenders. Gujarat and Tamil Nadu industrial corridors concentrate assembly operations for localized hybrid system production.
United States
Remote mining operators in Nevada and Arizona deploy off-grid hybrid units to displace diesel consumption exceeding ten million liters annually at single sites. The EPA enforces emissions benchmarks that elevate hybrid renewables against fossil backup in industrial settings. Texas and California grid interconnection queues push developers toward microgrid configurations that bypass utility approval timelines.
Germany
Nordic utilities mandate extended producer responsibility clauses in procurement contracts, filtering suppliers without circularity documentation. The EU Green Deal's carbon border adjustment mechanism elevates hybrid system specifications for European industrial offtakers. Bavaria and North Rhine-Westphalia host engineering centers where turbine and inverter firmware development concentrates.
Australia
Iron ore mines in Western Australia specify industrial-scale hybrid systems to secure 24/7 operational autonomy from grid infrastructure. National renewable energy targets accelerate tender issuance for remote industrial electrification. Pilbara region extraction clusters represent the densest concentration of diesel displacement projects across the Southern Hemisphere.
Chile
Copper extraction sites in the Atacama Desert deploy containerized hybrid units with rapid deployment protocols for minimal maintenance access. Mining sector electrification mandates compress payback period requirements below conventional separate-system installations. Antofagasta and Calama industrial zones anchor procurement demand for extreme climate resilience specifications.
Hybrid Solar Wind System Market Vendor Landscape
The competitive structure tilts toward diversified industrial conglomerates with turbine engineering heritage and power electronics integration capabilities. Siemens Gamesa Renewable Energy and General Electric anchor the premium tier through multi-continent project deployment. Three archetypes dominate: turbine-heritage industrials, integrated power electronics specialists, and compact residential kit providers. Capacity expansion in India and strategic partnerships for storage integration represent the dominant competitive moves across the vendor base.
Within the turbine-heritage tier, Siemens Gamesa Renewable Energy exemplifies large-scale hybrid project anchoring across multiple continents. General Electric occupies a position merging solar inverters with wind converter platforms through integrated power electronics. Supernova Technologies represents the distributed generation niche with simplified installation protocols for residential applications. UNITRON Energy System Pvt. Ltd. and ReGen Powertech sit within the India-based manufacturing tier capitalizing on PLI scheme localization advantages. Blue Pacific Solar Product, Inc. and Alpha Windmills anchor regional supply positions in North American distributed markets.
| Leading Market Players |
|---|
| Siemens Gamesa Renewable Energy |
| General Electric |
| Blue Pacific Solar Product, Inc. |
| Alpha Windmills |
| ReGen Powertech |
| Supernova Technologies |
| UNITRON Energy System Pvt. Ltd. |
| Zenith Solar Systems |
| Alternate Energy Company |
| Others |
Supply Flow & Price Mechanics
India's PLI scheme for domestic solar and wind component manufacturing is redirecting supply chains toward localized production, compressing import dependency and reshaping procurement geography for hybrid renewable assets.
Pricing Analysis
Bundled engineering-procurement-construction contracts versus unbundled component sourcing splits the pricing landscape for hybrid solar wind systems. Three-tier pricing structure across premium, standard, and economy levels reflects certification tier, with ISO 61400-compliant turbines commanding substantial premiums over uncertified alternatives. Cost compression in residential kits is intensifying because crystalline silicon module prices continue compressing and lithium-ion storage economics enable longer-duration configurations at lower price points. Mining operators in remote locations exhibit the lowest price sensitivity due to diesel displacement economics, while agricultural irrigation users in Kenya and Ghana demonstrate acute sensitivity to upfront capital requirements.
Supply Chain Analysis
Freight costs from Xinjiang and Sichuan provinces to Indian assembly hubs and African deployment sites represent a structural cost layer that localized manufacturing under India's PLI scheme is designed to erode. Polysilicon supply concentrates in China, wind turbine nacelle assembly clusters in Germany and India, and lithium-ion cell production draws from South Korea and Japan. Raw material dependencies span polysilicon ingots, rare-earth magnets for turbine generators, and lithium carbonate for battery cathodes. Single-source vulnerability in polysilicon refining creates exposure to geopolitical disruption. Distribution runs through direct manufacturer-to-project-developer contracting in Sub-Saharan Africa, bypassing traditional equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hybrid solar wind system market functions as a regulatory compounder where India's CEA renewable purchase obligations and the EU Green Deal carbon border mechanism create durable demand tailwinds through mandated procurement and compliance-driven substitution.
For Market Incumbents: Cement turbine engineering heritage advantages by deepening firmware expertise for unified inverter-converter architectures, addressing the power electronics integration complexity that filters smaller entrants. Fortify position through captive battery supply agreements with Korean or Japanese cell manufacturers, neutralizing the lithium-ion storage cost curve pressure that threatens margin capture. Prioritize certification maintenance for ISO 61400 and IEC 61215 standards to preserve tender participation eligibility as grid codes evolve.
For New Entrants and Emerging Players: Regional EPC contractors in Nigeria and Kenya represent the most accessible channel partners for penetrating Sub-Saharan Africa's fastest-growing microgrid segment. Target containerized hybrid units for Chilean copper extraction sites where rapid deployment protocols and minimal maintenance access specifications create white-space opportunity. Pursue green hydrogen integration partnerships with Australian iron ore miners to anchor electrolyzer load contracts alongside generation assets.
For Investors and Strategic Acquirers: Asymmetric upside sits with India-based manufacturing specialists possessing PLI scheme accreditation and localized component assembly capabilities. Long-term viability rests on exposure to markets with structural grid instability and diesel displacement economics rather than discretionary renewable adoption. Acquisition focus should center on firms with integrated power electronics firmware stacks and existing CEA tender track records. Watch for inflection in frequency response requirement shifts within evolving grid codes that would favor hybrid assets with advanced storage duration configurations.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Manufacturing Capacity Buildout | India's PLI scheme compresses import dependency for solar cells and wind turbine components. |
| Power Purchase Agreement Structuring | Long-term offtake contracts with Nigerian mining operators de-risk project finance for remote deployments. |
| Technology Licensing for Vertical Turbines | Vertical-axis wind turbine patents enable footprint reduction for Australian distributed generation applications. |
| Vertical Integration into Battery Storage | In-house lithium-ion pack assembly captures margin pools as duration requirements lengthen across industrial configurations. |
| Green Certification Program Alignment | EU Green Deal circularity documentation enables tender participation for Nordic utility procurement. |
Methodological Framework
Bottom-up industrial offtake modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and mining sector energy managers were combined with secondary validation from EIA data, IEA renewable energy reports, FERC interconnection filings, and Indian CEA tender databases. Triangulation between deployment volume estimates and component production data ensures consistency across the analysis window.
Historical trendline analysis of installed hybrid capacity, technology cost curves, and regulatory mandate implementation timelines informs the projection framework. Segmentation dimensions modeled include system topology, application intensity, component cost stack concentration, and end-user procurement sophistication. CAGRs were derived from slope analysis of technology adoption curves and policy-driven demand inflection points. Key forecast inputs span lithium-ion battery pack economics, polysilicon supply availability, and evolving grid code frequency response requirements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical disruption in polysilicon supply, abrupt shifts in storage chemistry economics, and regulatory modifications to renewable purchase obligation structures. Forecasts reflect assumptions regarding continued PLI scheme execution, stable freight cost trajectories, and incremental grid code harmonization. A model refresh is warranted upon material change in India's domestic manufacturing incentive structure or EU carbon border adjustment implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Israel Renewable Energy Market
Renewable Energy
Saudi Arabia Renewable Energy Market
Renewable Energy
Offshore Wind Energy Infrastructure Market
Renewable Energy
North Africa Renewable Energy Market
Renewable Energy
Solar Home Lights Market
Renewable Energy
United States Renewable Energy Market
Renewable Energy
Mexico Renewable Energy Market
Renewable Energy
Biogas Plant Market
Renewable Energy
Drones in Renewable Energy Market
Renewable Energy
Global Artificial Photosynthesis Market
Renewable Energy
Russian Federation Renewable Energy Market
Renewable Energy
Australia Renewable Energy Market
Renewable Energy
Nigeria Renewable Energy Market
Renewable Energy
Solar Thermal Water Heater Market
Renewable Energy
Renewable Energy Contractor Market
Renewable Energy
Solar Chair Market