
 Wind Turbine Inspection Services Market | 2026-2036
Wind Turbine Inspection Services Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Inspection Services Market Outlook
China's offshore wind build-out is reconfiguring service demand patterns across Asia-Pacific. Intertek Group Plc leverages its marine certification heritage to anchor large-scale inspection programs along China's eastern seaboard. Vestas Wind Systems A/S competes through integrated service agreements that extend turbine availability guarantees. Mistras Group differentiates via specialized ultrasonic testing capabilities for composite blade integrity assessment.
Wind turbine inspection services encompass non-destructive evaluation of rotor blades, towers, nacelles, and foundations using acoustic emission, thermographic imaging, and aerial drone platforms to detect subsurface delamination, corrosion, and structural fatigue before operational failure occurs. Drone inspection technology leads deployment growth due to reduced technician risk and faster turnaround on offshore assets, while predictive maintenance service types capture expanding margin pools as operators shift from scheduled to condition-based intervention models. Thermographic inspection remains concentrated in gearbox and electrical component monitoring where heat signature anomalies predict bearing failures months in advance.
EASA maintains stringent aerial work platform standards that shape drone operator certification requirements across European wind farms. China's MIIT enforces GB standards for offshore equipment inspection frequency that directly mandate third-party service engagement. The US FAA governs beyond-visual-line-of-sight drone operations that constrain inspection automation potential in domestic wind corridors. Stakeholders must weigh regulatory divergence against platform standardization economics when scaling multi-continent service portfolios.
Market Dynamics
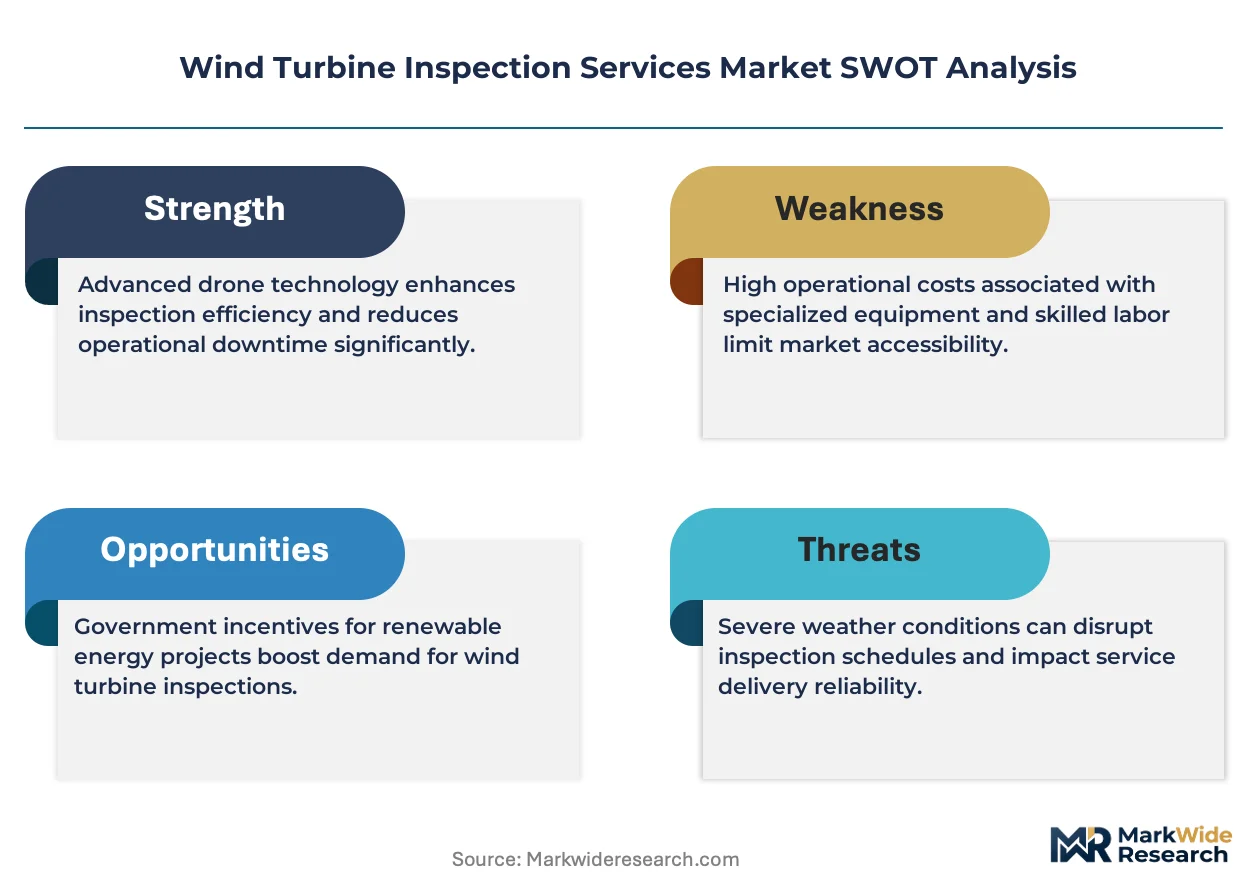
Drone-based inspection platforms are compressing service timelines and eliminating technician exposure risks across offshore wind portfolios, while predictive maintenance algorithms restructure contract economics away from scheduled interventions.
Growth Catalysts
- GB Standards Mandate:China's MIIT-enforced offshore equipment inspection frequency rules compel third-party service engagement across eastern seaboard installations.
- Composite Ultrasonic Testing:Advanced subsurface delamination detection extends blade operational life and unlocks end-of-warranty assessment revenue streams.
- Offshore Fleet Expansion:Northern European operators are enlarging service contracts to cover proliferating turbine counts in the North Sea and Baltic corridors.
Market Restraints
- Technician Certification Bottlenecks:EASA aerial work platform standards create prolonged drone operator qualification timelines that throttle deployment velocity.
- Equipment Capital Intensity:Thermographic imaging systems and acoustic emission sensors demand substantial upfront investment before contract profitability materializes.
- Regulatory Fragmentation:Divergent FAA beyond-visual-line-of-sight constraints versus EASA frameworks complicate platform standardization across multi-continent service portfolios.
Strategic Opportunities
- German Aging Infrastructure:Systematic end-of-warranty assessment requirements across aging onshore installations generate concentrated demand for blade integrity evaluation.
- Drone-Thermography Convergence:Integrated aerial platforms combining thermal imaging with high-resolution visual capture enable single-pass comprehensive asset evaluation.
- Condition-Based Contracting:Availability guarantee structures displace time-based maintenance schedules and capture expanded margin pools through performance risk transfer.
Industry Challenges
- Specialized Technician Scarcity:Rope-access technicians face displacement while drone pilot certification programs lag operational demand curves.
- Legacy System Integration:Predictive maintenance platforms require data architecture overhauls that prolong implementation timelines at established wind farm operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Inspection Services Market |
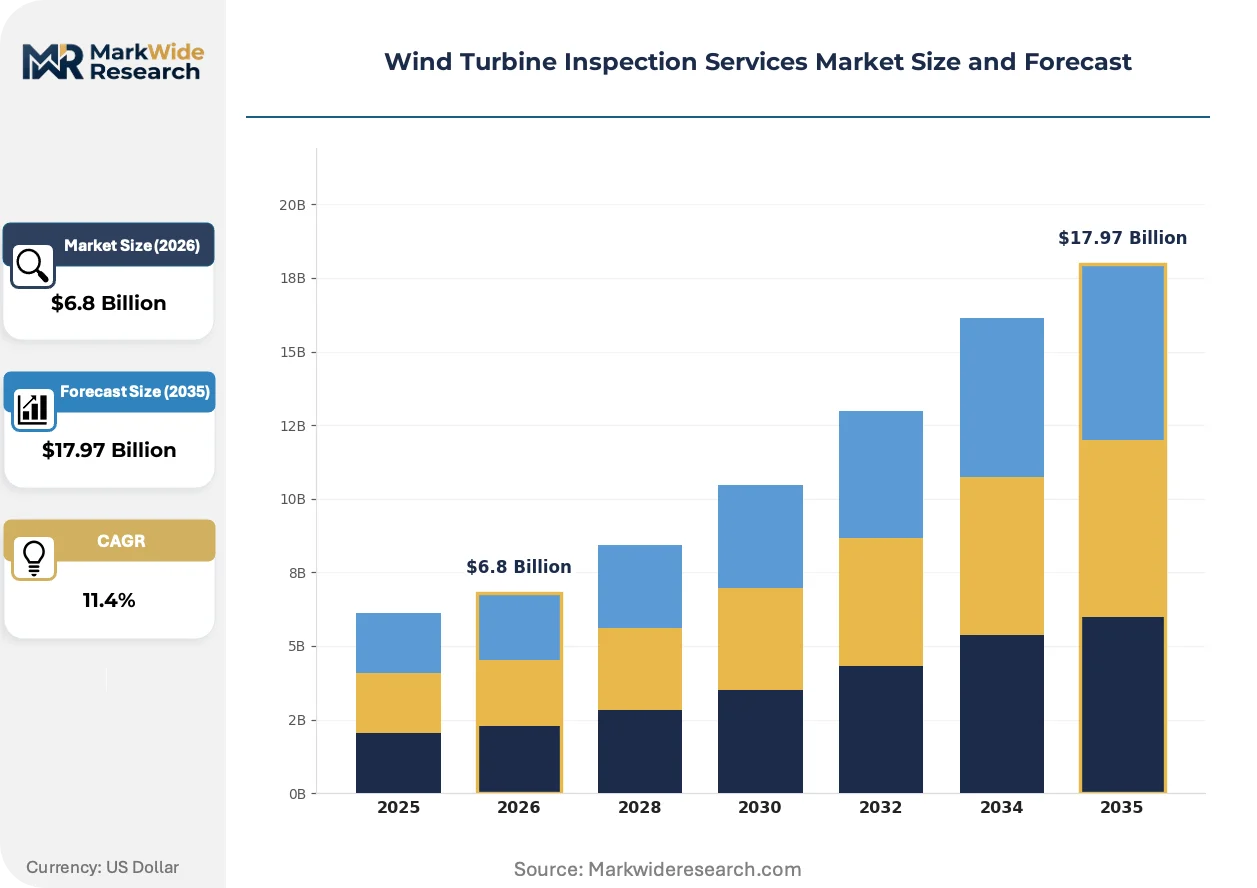
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Inspection Technology: Drone Inspection, Ultrasonic Testing, Thermographic Inspection, Visual Inspection Service Type: Preventive Maintenance, Predictive Maintenance, Emergency Repair, Compliance Inspection End User: Utility Companies, Independent Power Producers, Asset Managers, Manufacturers Delivery Model: On-Site Services, Remote Monitoring, Annual Contracts, Pay-Per-Use |
| Companies Covered | Intertek Group Plc, Mistras Group, Vestas Wind Systems A/S, UL International GmbH, Deutsche Windtechnik AG, Siemens Gamesa Renewable Energy, DNV AS, Swire Renewable Energy A/S, SGS SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Inspection Services Market Strategic Shifts
Inspection methodologies are pivoting from reactive damage assessment toward preemptive failure prediction, compressing intervention windows and restructuring service provider value propositions around uptime guarantees rather than defect detection.
Autonomous drone swarms equipped with machine-vision algorithms are rendering obsolete manual blade walk-downs and rope-access techniques for offshore rotor evaluation. Offshore wind farm operators in the North Sea corridor are deploying these systems at accelerating frequency to reduce turbine downtime during inspection windows. The structural consequence is a collapse in per-turbine inspection labor hours and a compression of contractor margins on traditional access-based services.
REACH chemical substance restrictions and the EU Green Deal sustainability disclosure requirements are mandating detailed material traceability for composite blade components across European wind installations. Industrial consequence includes heightened documentation burdens for inspection service providers documenting repair material provenance. Offshore segments in German and Danish waters face the most acute compliance pressure, driving consolidation toward certified contractors with established supply chain audit capabilities.
Service procurement is unbundling from original equipment manufacturer maintenance packages as independent inspection specialists demonstrate superior defect detection rates. Asset owners in China's coastal provinces are disaggregating blade evaluation from turbine supply agreements and contracting directly with drone-based specialists. This pattern is most pronounced in Shandong and Jiangsu provinces where provincial energy authorities prioritize local service provider participation in offshore development zones.
Wind Turbine Inspection Services Market Segmentation
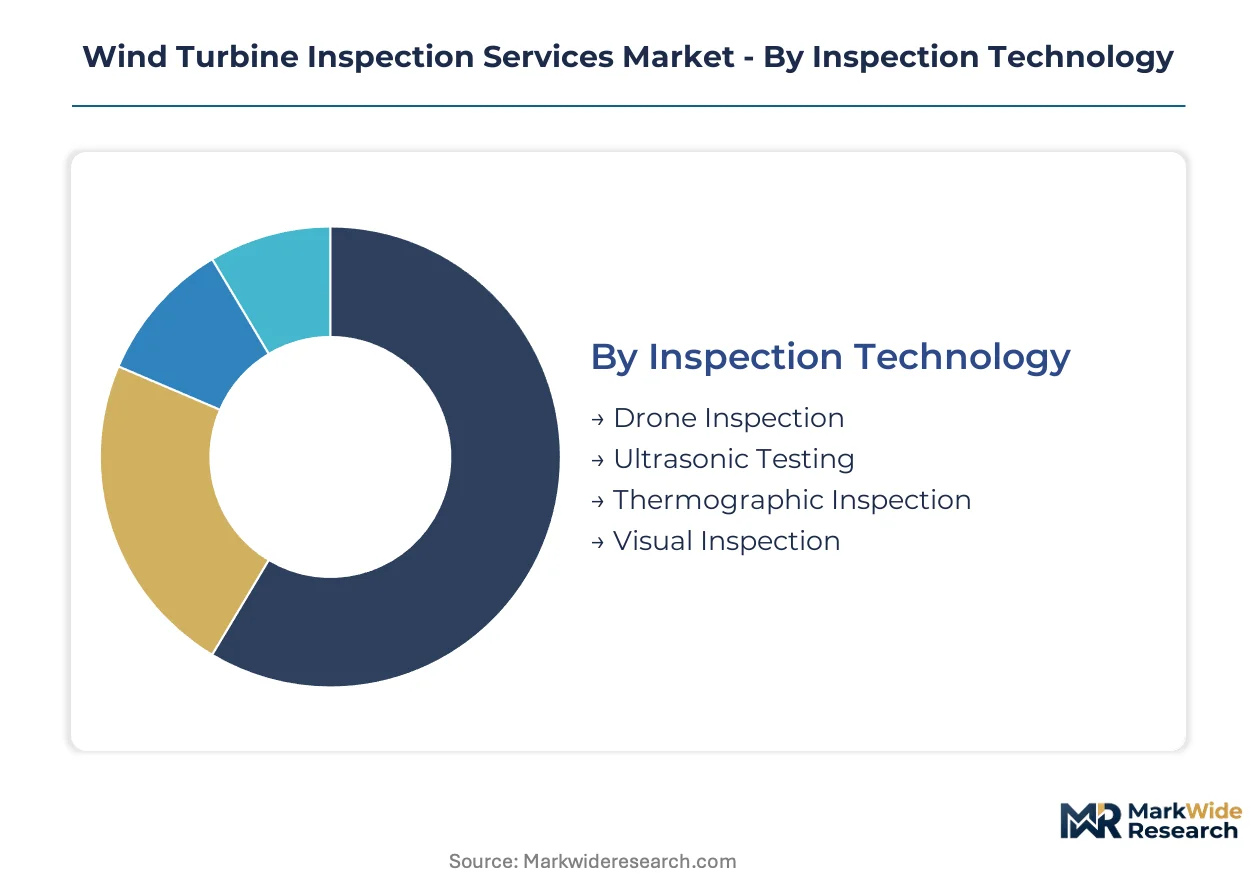
Wind turbine inspection services fragment across four operational dimensions that reshape procurement economics. Technology selection determines labor intensity and technician risk exposure. Service type governs contract structure and margin capture. Delivery model alignment separates integrated operators from specialized vendors.
Inspection Technology:
Cost tier differentiation separates capital-intensive autonomous platforms from labor-dependent manual methods.
- Drone Inspection:Aerial platforms equipped with high-resolution cameras and LiDAR sensors eliminate rope-access requirements. Northern European offshore operators in the North Sea corridor deploy these systems to compress inspection windows and reduce turbine downtime. EASA aerial work platform standards govern operator certification and constrain deployment velocity.
- Ultrasonic Testing:Subsurface acoustic wave propagation detects delamination and voids within composite blade laminates. German onshore operators facing end-of-warranty assessments rely on this method for structural integrity verification. Mistras Group anchors specialized capability in this segment.
- Thermographic Inspection:Infrared imaging identifies heat signature anomalies in electrical components and gearbox bearings.
- Visual Inspection:Manual blade walk-downs and rope-access techniques persist for damage confirmation.
Drone inspection holds installed capacity. Ultrasonic testing is rotating up the share rankings.
Service Type:
Application purpose distinguishes scheduled intervention from condition-triggered response.
- Predictive Maintenance:Machine-learning algorithms processing sensor data forecast component failures months before operational impact. Availability guarantee structures transfer performance risk to service providers and expand margin pools. Vestas Wind Systems A/S competes through integrated agreements embedding this capability.
- Preventive Maintenance:Calendar-based component replacement and lubrication regimes dominate legacy operator procurement. Aging onshore installations in Germany sustain concentrated demand for systematic blade integrity programs.
- Emergency Repair:Unscheduled defect remediation following storm damage or operational anomaly detection.
- Compliance Inspection:Regulatory-mandated assessments under China's MIIT GB standards and EASA directives.
Predictive maintenance is gaining share fastest. Preventive maintenance retains contract volume concentration.
End User:
Customer type determines procurement sophistication and contract duration preferences.
- Utility Companies:Vertically integrated electricity generators with captive turbine fleets and established maintenance infrastructure. These operators unbundle inspection from OEM service packages and contract directly with drone-based specialists in China's Shandong and Jiangsu provinces.
- Independent Power Producers:Financial investors owning dispersed wind assets across multiple geographies. Asset managers in this category prioritize standardized reporting formats and multi-site service agreements.
- Asset Managers:Third-party portfolio operators managing turbines on behalf of institutional investors.
- Manufacturers:Turbine OEMs offering extended warranty and service contracts.
Utility companies anchor procurement volume. Independent power producers are climbing the fastest in contract sophistication.
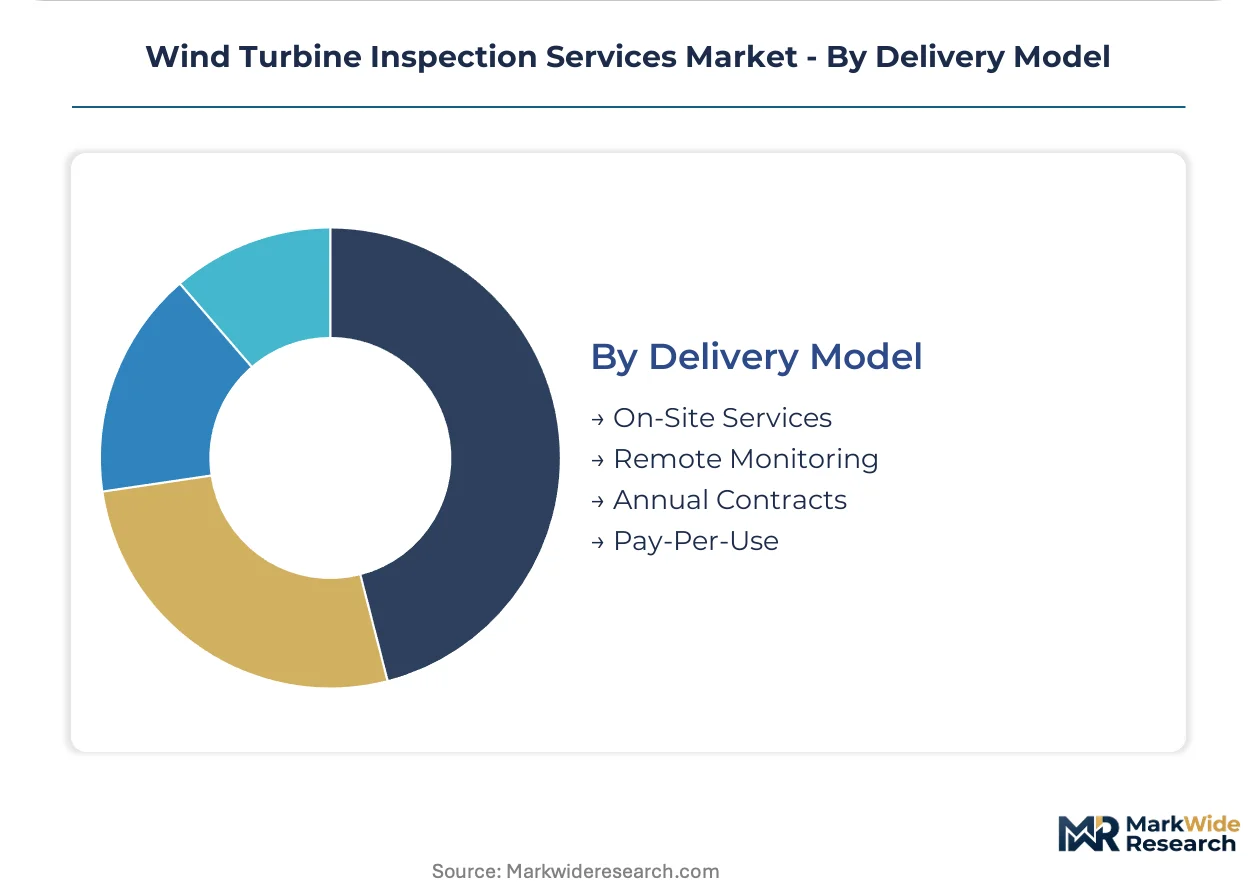
Delivery Model:
Volume commitment structure separates recurring revenue relationships from transactional engagement.
- Annual Contracts:Multi-year service agreements with fixed inspection frequencies and bundled technology deployment. Northern European offshore operators enlarge these contracts to cover proliferating turbine counts in Baltic corridors.
- Remote Monitoring:Continuous sensor data transmission enabling centralized diagnostic assessment. This model demands data architecture overhauls that prolong implementation timelines at established operators.
- On-Site Services:Technician dispatch for physical inspection and repair execution.
- Pay-Per-Use:Transactional pricing for ad-hoc inspection requests without volume commitment.
Annual contracts dominate revenue stability. Remote monitoring shows the steepest expansion trajectory as predictive platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Service provider networks cluster where turbine density and regulatory stringency intersect. Germany, China, the United Kingdom, the United States, and Denmark concentrate contract volumes and shape procurement standards that diffuse to secondary markets.
Germany
Aging onshore installations drive systematic end-of-warranty blade assessments across Lower Saxony and Brandenburg. EASA aerial work platform standards govern drone operator certification and constrain deployment velocity. Hamburg anchors specialized ultrasonic testing capacity serving North Sea offshore corridors.
China
Provincial build-outs in Shandong and Jiangsu reconfigure Asia-Pacific service demand. MIIT-enforced GB standards mandate third-party inspection frequency across eastern seaboard installations. Yangtze River Delta clusters host emerging drone-based specialists displacing OEM-integrated service packages.
United Kingdom
North Sea offshore expansion enlarges multi-year service contracts covering proliferating turbine counts. The country's national aviation regulator constrains beyond-visual-line-of-sight drone operations that limit inspection automation. Scottish waters concentrate floating wind pilot projects requiring adapted inspection protocols.
United States
Great Plains wind corridors sustain preventive maintenance contract volume for utility-scale fleets. FAA beyond-visual-line-of-sight regulations fragment platform standardization against European frameworks. Texas and Iowa anchor technician training programs addressing rope-access displacement.
Denmark
Baltic Sea offshore proliferation drives condition-based contracting structures transferring performance risk to service providers. EU Green Deal sustainability disclosure requirements mandate material traceability documentation for composite blade repairs. Copenhagen clusters certification specialists with established supply chain audit capabilities.
Wind Turbine Inspection Services Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in testing and sensor supply. The vendor base organizes around three strategic archetypes: diversified testing conglomerates with marine certification heritage, turbine OEMs embedding inspection within availability guarantee structures, and specialized non-destructive evaluation firms with composite blade expertise. Dominant competitive moves include strategic partnerships bridging regulatory jurisdictions and technology licensing agreements accelerating drone-thermography convergence.
Within the diversified testing tier, Intertek Group Plc and SGS SA exemplify geographic footprint strategies leveraging marine certification heritage across multiple regulatory jurisdictions. Mistras Group occupies a position among specialized non-destructive evaluation providers, representing the ultrasonic testing archetype for subsurface blade integrity assessment.
| Leading Market Players |
|---|
| Intertek Group Plc |
| Mistras Group |
| Vestas Wind Systems A/S |
| UL International GmbH |
| Deutsche Windtechnik AG |
| Siemens Gamesa Renewable Energy |
| DNV AS |
| Swire Renewable Energy A/S |
| SGS SA |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on German ultrasonic testing equipment creates pricing tier spreads that widen as EASA certification requirements harden, while supply chain shape bends toward drone sensor manufacturers in China and Denmark to offset equipment capital intensity.
Pricing Analysis
EASA aerial work platform standards dictate the pricing tier structure across European wind corridors, separating certified drone operators from uncertified competitors. Three-tier pricing structure across premium, standard, and economy levels reflects operator certification grade, inspection technology bundling, and volume commitment scale. Cost compression in the economy tier is intensifying because provincial energy authorities in Shandong and Jiangsu prioritize local service provider participation. Independent power producers exhibit highest price sensitivity due to dispersed asset portfolios, while utility companies with captive fleets accept premium pricing for availability guarantees.
Supply Chain Analysis
Specialized drone manufacturers in China, Denmark, and Germany hold contract-manufacturing capacity for aerial inspection platforms serving offshore wind operators. The supply chain draws from lithium-polymer battery producers in South Korea, thermal imaging sensor fabricators in the United States, and composite blade repair material suppliers in Germany. Single-source vulnerability concentrates in EASA-certified training providers that throttle technician pipeline expansion. Distribution runs through multi-year service agreements with annual contract structures dominating revenue stability for platform integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wind turbine inspection services sit in early-cycle expansion as drone-thermography convergence accelerates adoption beyond Northern European offshore corridors into Asia-Pacific build-outs.
For Market Incumbents: Pre-empt displacement by rope-access technician scarcity through accelerated drone pilot certification program scaling in Texas and Iowa training clusters. Anchor defensive positioning via backward integration into thermal imaging sensor supply to capture equipment margin pools and reduce third-party dependency. The priority lever rests on securing EASA regulatory compliance documentation ahead of competitor filings. For New Entrants and Emerging Players: China's Jiangsu province offers underpenetrated demand density where provincial energy authorities disaggregate blade evaluation from OEM service packages. White-space targets concentrate in ultrasonic testing specialization for end-of-warranty assessments across German Lower Saxony installations. Go-to-market execution should leverage direct contracting with utility companies bypassing turbine manufacturer maintenance bundles. For Investors and Strategic Acquirers: The market sits at a platform-consolidation phase that favors specialized non-destructive evaluation firms with composite blade expertise over diversified testing conglomerates. Long-term viability hinges on predictive maintenance algorithm development capabilities transferring performance risk to service providers. Acquisition target archetypes include drone-based inspection specialists with established EASA operator certification pipelines. Monitor FAA beyond-visual-line-of-sight regulatory relaxation as inflection signal for domestic automation scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Drone-Thermography Platform Convergence | Integrated aerial systems enable single-pass comprehensive asset evaluation for North Sea operators. |
| EASA Operator Certification Investment | Certified training pipelines constrain competitor deployment velocity across European wind corridors. |
| Predictive Maintenance Algorithm Development | Machine-learning platforms transfer performance risk and expand margin pools through availability guarantees. |
| Backward Integration into Sensor Supply | In-house thermal imaging production captures equipment margins and reduces third-party dependency. |
| Direct Utility Contracting in China | Provincial energy authorities in Shandong and Jiangsu prioritize local service provider participation. |
Study Parameters
Initial hypotheses were tested against primary input from wind farm operations directors, drone platform engineers, EASA certification specialists, and utility procurement managers and refined through secondary validation against EIA wind capacity data, IEA renewable energy reports, FERC interconnection filings, and turbine OEM service disclosure documents. Bottom-up segmentation modeling triangulated against top-down market sizing across inspection technology, service type, and delivery model dimensions.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling adoption curves for drone inspection platforms against technician certification pipeline constraints. Segmentation dimensions included inspection technology tier, service contract structure, end-user procurement sophistication, and regional regulatory framework clustering. CAGRs were derived from installed turbine fleet expansion rates and inspection frequency mandates, with specific inputs from MIIT GB standards enforcement timelines and EASA aerial work platform directive implementation phases.
The forecast holds incumbent behavior within observed patterns; aggressive moves by autonomous drone swarm developers or relaxed FAA beyond-visual-line-of-sight regulations would shift outcomes materially. Quarterly review of technician certification completion rates, provincial offshore wind auction announcements in China, and EASA regulatory amendment proposals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Solar Panel Mounting Structure Market
Renewable Energy
Renewable Energy Inverters Market
Renewable Energy
Spain Renewable Energy Market
Renewable Energy
Solar District Heating Market
Renewable Energy
Solar Showers Market
Renewable Energy
Offshore Wind Energy Infrastructure Market
Renewable Energy
China Wind Energy Market
Renewable Energy
Biomethane Certificate Trading Platform Market
Renewable Energy
Zimbabwe Renewable Energy Market
Renewable Energy
Hybrid Solar Wind Diesel Market
Renewable Energy
Denmark Renewable Energy Market
Renewable Energy
Wind Turbine Inspection Drones Market
Renewable Energy
North Africa Renewable Energy Market
Renewable Energy
Japan Renewable Energy Market
Renewable Energy
Solar Tree Market
Renewable Energy
Rectenna Market