
 Renewable Energy Sources Market | 2026-2036
Renewable Energy Sources Market Size, Share, and Industry Trends Forecast 2026-2036
Renewable Energy Sources Market Insights
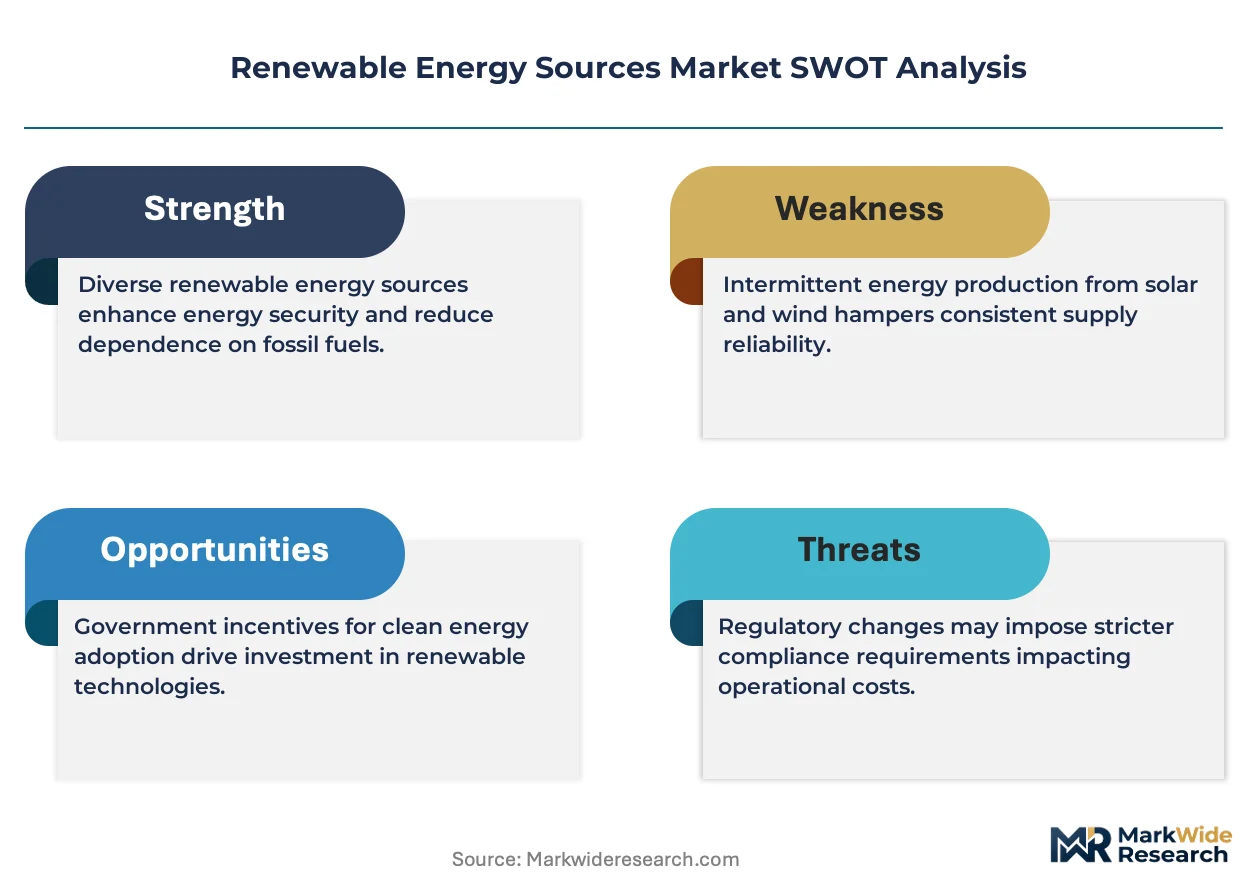
Project finance and green bond structures is rewriting competitive access in renewable energy deployment, allowing developers without utility balance sheets to bid at scale. NextEra Energy leverages its regulated utility cash flows to self-finance gigawatt-scale pipelines. Vestas Wind Systems anchors its competitiveness through blade manufacturing scale and service contract density across offshore zones.
Renewable energy sources encompass naturally replenishing flows—solar irradiance, wind kinetic energy, hydropower potential, and geothermal heat—captured through engineered conversion systems with operational lifespans typically spanning 25–30 years. These installations displace fossil thermal generation by feeding electrons or thermal energy into grids, industrial processes, and transport fuel cycles. Solar photovoltaics dominates capacity additions due to module cost compression and distributed deployment flexibility, while concentrated solar power with molten salt storage captures premium value in markets with high peak demand. Offshore wind turbines command elevated capital intensity but deliver capacity factors exceeding 50% in North Sea and East Asian lease areas.
FERC Order 2023 interconnection reforms in the United States compress queue timelines for solar and wind projects, while EU Green Deal taxonomy criteria restrict institutional capital to assets meeting stringent sustainability thresholds. China's National Energy Administration enforces grid parity mandates that phase out feed-in tariffs and expose developers to merchant price risk. Stakeholders must track which regulatory jurisdictions are shifting from subsidy-dependent procurement to competitive auction and merchant frameworks.
Market Dynamics
Utility-scale solar procurement by data center operators is compressing development timelines and forcing developers to restructure project finance around offtake certainty rather than merchant price exposure.
Growth Catalysts
- IRA Tax Credits:The Inflation Reduction Act's production and investment tax credits redirect institutional capital toward domestic solar and battery co-location projects in the United States.
- Data Center Load Growth:Hyperscale cloud operators in Northern Virginia, Dallas, and Phoenix are contracting gigawatt-scale renewable portfolios to match 24/7 carbon-free energy targets.
- EU Green Deal Taxonomy:Institutional investors across the European Union must deploy capital into assets meeting stringent sustainability thresholds, funneling pension and insurance funds into verified renewable infrastructure.
Market Restraints
- Polysilicon Supply Concentration:Xinjiang-based polysilicon refiners supply over 40% of global solar-grade silicon, exposing module manufacturers to forced labor scrutiny and supply disruption risk.
- Interconnection Queue Backlogs:FERC Order 2023 reforms aim to compress timelines, yet regional transmission organizations still face multi-year queues for solar and wind projects seeking grid access.
- Grid Parity Mandates:China's National Energy Administration has phased out feed-in tariffs, exposing developers to merchant price volatility without the price floor that previously underwrote project finance.
Strategic Opportunities
- India Manufacturing Scale-Up:Production-linked incentive schemes are attracting module and cell manufacturing investments in Gujarat and Tamil Nadu to serve domestic demand and export markets.
- Offshore Wind Lease Rounds:Bureau of Ocean Energy Management auctions in the Gulf of Mexico and Pacific Northwest open new capacity zones with capacity factors exceeding 50%.
- Green Hydrogen Integration:Electrolyzer deployments paired with curtailed renewable generation in Brazil's Northeast are creating synthetic fuel export corridors to European industrial offtakers.
Industry Challenges
- Grid Synchronization Expertise:Project developers face acute shortages of power systems engineers capable of modeling inverter-based resource stability and harmonic distortion for utility interconnection studies.
- Equipment Certification Delays:IEC 61400 and IEEE 1547 compliance testing backlogs at accredited laboratories are extending project commissioning schedules by six to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renewable Energy Sources Market |
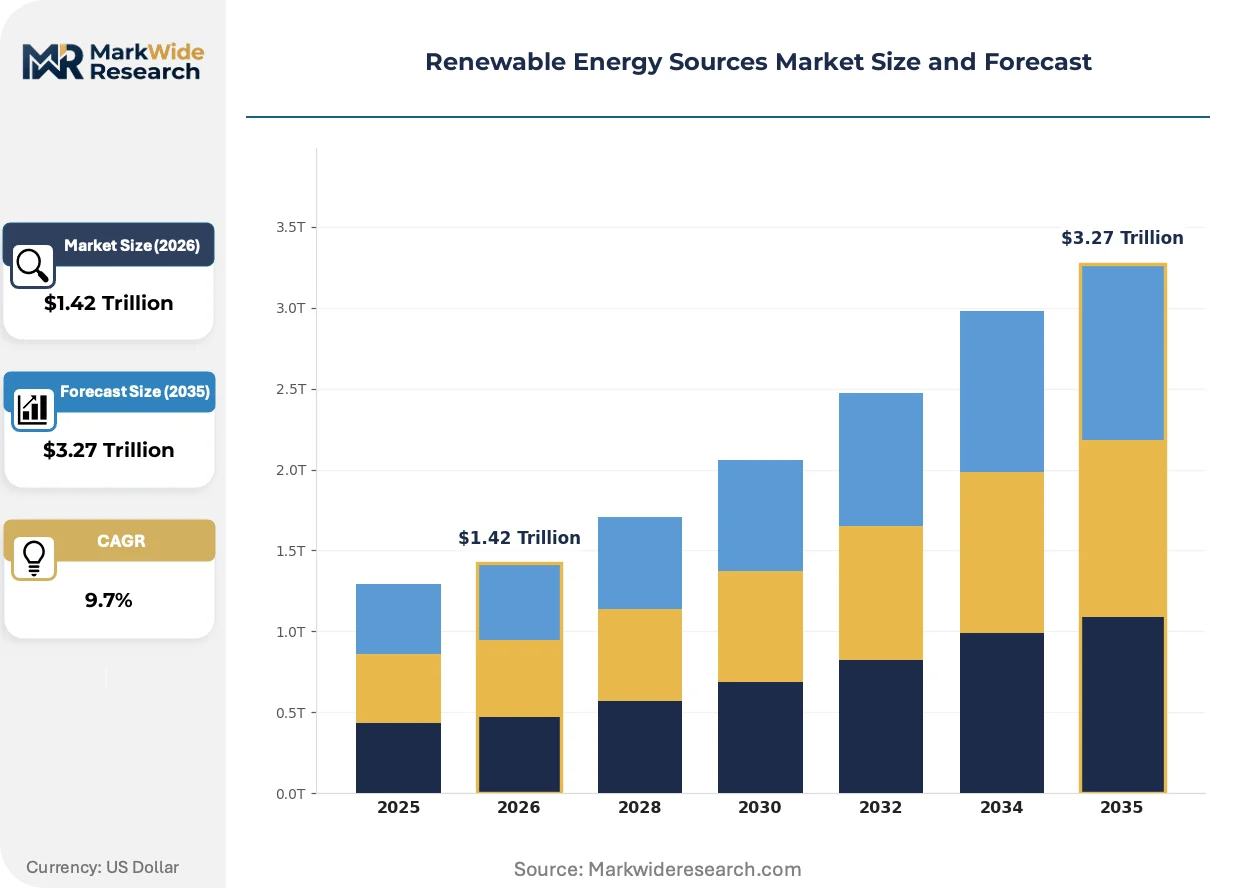
| Market Size in 2026 | $1.42 Trillion |
| Market Size in 2035 | $3.27 Trillion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Type: Solar, Wind, Hydropower, Geothermal Application: Electricity Generation, Heating, Transportation, Off-Grid Systems End User: Industrial, Residential, Commercial, Agricultural Technology: Photovoltaics, Concentrated Solar Power, Wind Turbines, Biomass |
| Companies Covered | NextEra Energy, GE Vernova, ACWA Power, Sungrow Power Supply, Iberdrola, Vestas Wind Systems, Brookfield Renewable Partners, Adani Green Energy, China Three Gorges Renewables, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renewable Energy Sources Market Trends and Innovations
Digital twin platforms and predictive analytics are compressing operational expenditure curves across wind and solar fleets, while policy frameworks in major economies harden around domestic content requirements.
Artificial intelligence-driven predictive maintenance software is digitizing turbine and inverter performance optimization. Asset operators in the North Sea and Texas Panhandle are deploying machine learning models to forecast component failure and dispatch maintenance crews before downtime events. This capability is digitizing service contract structures toward availability guarantees and away from time-and-material billing.
The EU Green Deal's Carbon Border Adjustment Mechanism is tightening embodied emissions standards for imported solar modules and steel towers. European project developers must now document supply chain carbon intensity or face tariff penalties, forcing procurement teams to audit Chinese and Southeast Asian manufacturing partners. Offshore wind foundation fabricators in Denmark and the Netherlands are accelerating decarbonization of steel sourcing to maintain contract eligibility.
Corporate offtakers are abandoning annual renewable energy credit matching in favor of 24/7 carbon-free energy contracting. Data center and semiconductor manufacturers in Arizona, Taiwan, and Ireland now require hourly generation-load matching rather than annual net-zero claims. This behavioral shift is driving investment in battery storage and geothermal baseload to complement intermittent solar and wind resources in markets with the most aggressive sustainability procurement teams.
Renewable Energy Sources Market Segmentation
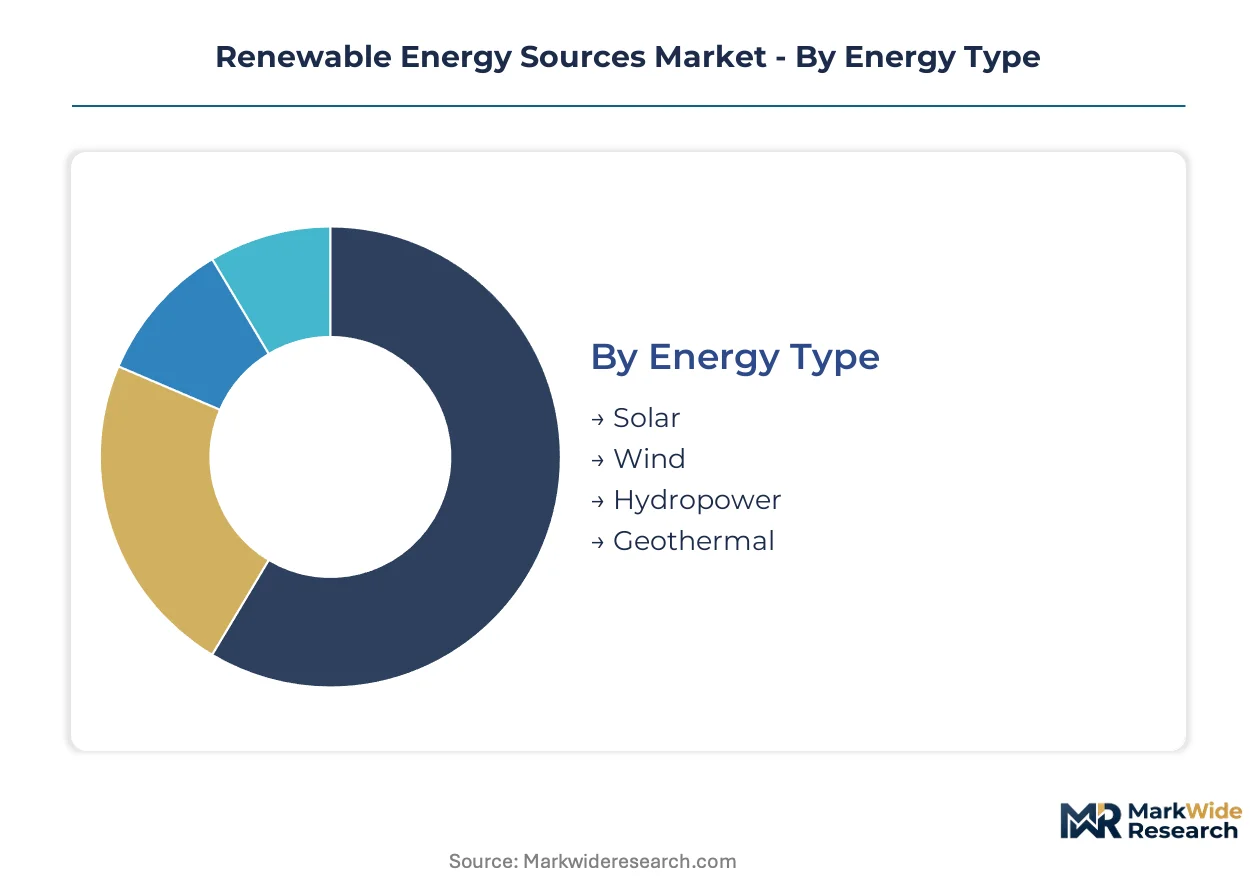
Segmentation in renewable energy markets determines capital allocation efficiency, technology procurement strategies, and regulatory compliance pathways. Developers, investors, and grid operators use these dimensions to match resource characteristics with load profiles and policy incentives.
Energy Type:
Mature baseload technologies coexist with emerging variable resources across the deployment spectrum.
- Solar:Photovoltaic modules convert sunlight directly to electricity through semiconductor junctions, achieving module efficiencies above 22% in monocrystalline formats. Utility-scale deployments in Arizona, Gujarat, and Spain concentrate procurement volume; IRA production tax credits and India's PLI scheme accelerate manufacturing localization.
- Wind:Horizontal-axis turbines extract kinetic energy through aerodynamic blade profiles, with offshore variants reaching nameplate capacities above 15 MW. North Sea lease areas and Texas Panhandle clusters anchor demand; grid interconnection queue reforms in the United States and EU permitting streamlining compress development timelines.
- Hydropower:Run-of-river and reservoir configurations provide dispatchable renewable capacity with lifespans exceeding 50 years. Brazil, Norway, and China's southwestern provinces maintain installed bases; environmental licensing requirements constrain greenfield expansion in most OECD jurisdictions.
- Geothermal:Binary cycle and flash steam plants exploit subsurface heat gradients, delivering baseload capacity factors above 90%. Iceland, Kenya, and Indonesia's volcanic zones concentrate operational capacity; exploration risk and drilling costs limit deployment outside geologically active regions.
Solar handles the majority of throughput; geothermal is the fastest mover on share as corporate offtakers seek 24/7 carbon-free matching.
Application:
End-use requirements shape technology selection, storage co-location decisions, and grid integration complexity.
- Electricity Generation:Grid-connected solar, wind, and hydro installations feed transmission networks at voltage levels from distribution to ultra-high voltage. Data center operators in Northern Virginia and semiconductor fabs in Taiwan contract gigawatt-scale portfolios; FERC Order 2023 interconnection reforms aim to compress queue timelines.
- Heating:Solar thermal collectors and geothermal heat pumps displace fossil fuel combustion in residential and industrial thermal loads. Denmark's district heating networks and China's building efficiency mandates concentrate deployment; seasonal storage integration remains technically challenging.
- Transportation:Renewable electricity powers battery electric vehicles and electrolyzer-fed hydrogen supply chains. Norway's EV charging infrastructure and Germany's hydrogen core grid anchor demand; EU Green Deal taxonomy criteria restrict institutional capital to verified low-carbon pathways.
- Off-Grid Systems:Standalone solar-battery microgrids serve remote industrial sites and rural electrification programs. Mining operations in Western Australia and island communities in Indonesia concentrate procurement; diesel displacement economics drive payback calculations without grid parity considerations.
Electricity generation absorbs the dominant share of capital deployment; off-grid systems are expanding most quickly as remote industrial loads seek energy autonomy.
End User:
Customer scale and load predictability determine project finance structures and offtake contract terms.
- Industrial:Continuous manufacturing loads require firm renewable supply with high capacity factor matching. Steel producers in Sweden and chemical complexes in the Netherlands contract for baseload geothermal and offshore wind; 24/7 carbon-free energy procurement replaces annual REC matching.
- Residential:Distributed solar and heat pump installations serve single-family and multi-unit buildings. Australia's rooftop solar penetration and Germany's building energy renovation programs concentrate volume; net metering policy revisions in California and Spain alter self-consumption economics.
- Commercial:Office buildings, retail chains, and logistics facilities procure renewable electricity through direct PPAs and green tariff programs. Hyperscale cloud operators in Dublin and Singapore drive demand for hourly generation-load matching; sustainability disclosure requirements under EU CSRD mandate supply chain verification.
- Agricultural:Irrigation pumping, grain drying, and livestock operations consume dispersed thermal and electrical loads. Solar-powered irrigation in India's Punjab and Haryana states and biogas digesters in Germany's livestock regions anchor deployment; feed-in tariff phase-outs expose developers to merchant price risk.
Industrial offtakers command the largest transaction sizes; agricultural applications are gaining share fastest as distributed generation economics improve.
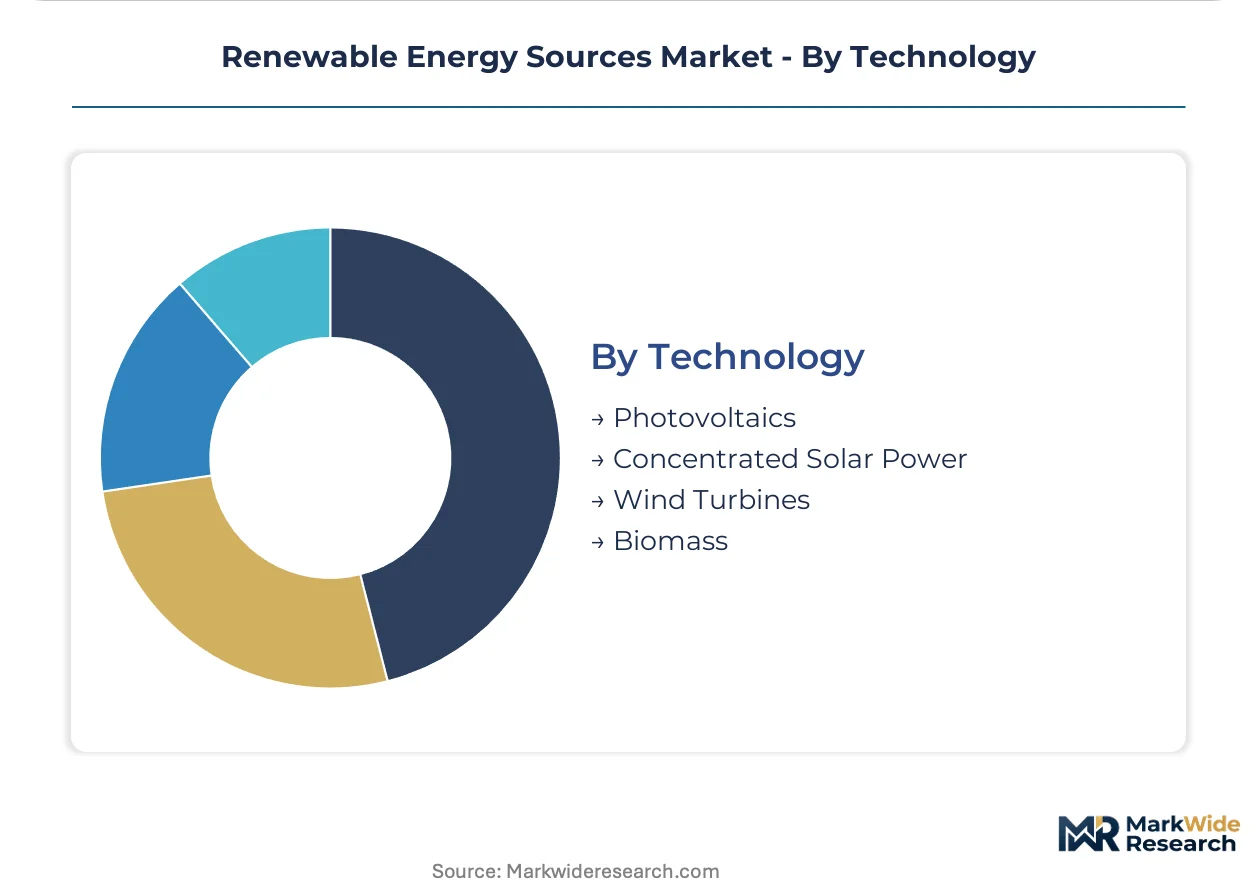
Technology:
Conversion system architectures differentiate on efficiency, cost trajectory, and integration complexity.
- Photovoltaics:Crystalline silicon cells dominate module production, with perovskite tandem architectures approaching commercialization. Chinese manufacturers in Jiangsu and Anhui provinces control wafer and cell capacity; EU Carbon Border Adjustment Mechanism forces supply chain carbon intensity documentation.
- Concentrated Solar Power:Parabolic trough and power tower configurations with molten salt storage deliver dispatchable thermal electricity. Morocco's Noor complex and Chile's Atacama Desert installations anchor operational capacity; high capital intensity and water consumption constraints limit greenfield development.
- Wind Turbines:Onshore and offshore variants scale rotor diameters and hub heights to capture higher wind resource layers. Vestas and Siemens Gamesa assembly facilities in Denmark and Spain serve European demand; blade recycling regulations under EU Waste Framework Directive shape end-of-life liabilities.
- Biomass:Combustion, gasification, and anaerobic digestion convert organic feedstocks to electricity, heat, or transport fuels. Finland's forest industry residues and Brazil's sugarcane bagasse anchor feedstock supply; sustainability certification under EU Renewable Energy Directive restricts eligible feedstocks.
Photovoltaics captures the dominant share of capacity additions; concentrated solar power shows the steepest expansion trajectory as storage-integrated dispatchable resources attract premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in renewable energy equipment are shifting as domestic manufacturing incentives in India, the United States, and the European Union reduce import dependence on Chinese solar modules and wind components. Capital deployment now tracks regulatory jurisdictions offering production-linked subsidies and carbon border protections.
United States
Data center load growth in Northern Virginia and Dallas-Fort Worth is compressing utility-scale solar development timelines. FERC Order 2023 interconnection reforms aim to reduce queue backlogs for solar and wind projects seeking grid access. Arizona's solar manufacturing corridor is attracting module and cell investments to serve domestic procurement mandates under IRA domestic content rules.
China
Grid parity mandates from the National Energy Administration have eliminated feed-in tariffs, exposing developers to merchant price volatility. Xinjiang-based polysilicon refiners supply over 40% of global solar-grade silicon, concentrating upstream supply. Jiangsu and Anhui provinces host wafer and cell manufacturing clusters that feed both domestic installations and export markets.
India
Production-linked incentive schemes are attracting module and cell manufacturing to Gujarat and Tamil Nadu to serve domestic demand and Southeast Asian export markets. The Central Electricity Authority enforces renewable purchase obligations on distribution companies. Rajasthan and Karnataka host gigawatt-scale solar parks that anchor utility-scale deployment.
Germany
EU Green Deal taxonomy criteria restrict institutional capital to assets meeting stringent sustainability thresholds, funneling pension funds into verified renewable infrastructure. The Carbon Border Adjustment Mechanism is tightening embodied emissions standards for imported solar modules. Offshore wind foundation fabricators in northern ports are accelerating steel decarbonization to maintain contract eligibility.
Brazil
Electrolyzer deployments paired with curtailed wind generation in the Northeast are creating synthetic fuel export corridors to European industrial offtakers. The national development bank provides concessional financing for renewable hybrid projects. Ceará and Rio Grande do Norte concentrate wind and solar resources with capacity factors supporting green hydrogen economics.
Renewable Energy Sources Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: regulated utilities leveraging balance sheet capacity to self-finance gigawatt-scale pipelines, independent power producers accessing institutional capital through green bond structures, and equipment manufacturers anchoring competitiveness through manufacturing scale and service contract density. Competitive moves center on backward integration into polysilicon and rare earth supply chains and geographic expansion into markets with domestic content requirements.
Within the utility-led archetype, NextEra Energy exemplifies regulated cash flow deployment into renewable pipelines, while Iberdrola occupies a comparable position in European markets. Among equipment specialists, Vestas Wind Systems represents the manufacturing-scale archetype with offshore service density, and Sungrow Power Supply anchors the power electronics segment. These entities illustrate how capital structure and manufacturing positioning determine competitive access to procurement opportunities.
| Leading Market Players |
|---|
| NextEra Energy |
| GE Vernova |
| ACWA Power |
| Sungrow Power Supply |
| Iberdrola |
| Vestas Wind Systems |
| Brookfield Renewable Partners |
| Adani Green Energy |
| China Three Gorges Renewables |
| Others |
Pricing and Supply Chain Analysis
Xinjiang polysilicon dependency determines both module pricing spreads and supply chain configuration across solar deployment. The EU Carbon Border Adjustment Mechanism and IRA domestic content rules force procurement teams to audit tier-1 versus tier-2 supplier carbon intensity, widening price differentials between compliant and non-compliant module sources.
Pricing Analysis
Industrial OEM buyers anchor long-term offtake contracting as the dominant pricing structure in utility-scale renewable procurement. Price differentiation rests on certification tier—UL 1703 versus IEC 61215 compliance—and volume scale with annual procurement thresholds above 500 MW unlocking standard-tier discounts. Cost compression in module manufacturing is intensifying because Chinese cell producers are expanding PERC and TOPCon capacity in Jiangsu and Anhui. Data center operators demonstrate the least price sensitivity due to 24/7 carbon-free energy mandates, while agricultural distributed generation buyers face acute budget constraints under feed-in tariff phase-outs.
Supply Chain Analysis
Polysilicon feedstock draws from Xinjiang, Inner Mongolia, and Yunnan provinces in China, with metallurgical-grade silicon sourcing from Brazil and Norway. Solar-grade polysilicon, high-purity quartz crucibles, and silver paste metallization pastes constitute critical input dependencies. Single-source vulnerability concentrates in Xinjiang-based polysilicon refiners supplying over 40% of global solar-grade silicon. Distribution runs through module assembly clusters in Vietnam, Thailand, and India serving markets with domestic content requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among hyperscale data center operators contracting gigawatt-scale renewable portfolios, fragmenting developer margins across smaller offtakers unable to match procurement scale.
For Market Incumbents: Harden balance sheet capacity against merchant price exposure by locking in 15-20 year power purchase agreements with investment-grade corporate offtakers. Prioritize backward integration into polysilicon refining and inverter manufacturing to capture margin compression from Chinese module imports facing CBAM tariffs. The threat of grid parity mandates eliminating price floors requires defensive positioning in markets with renewable purchase obligations. For New Entrants and Emerging Players: Southeast Asian module assembly underpenetration offers white-space expansion for cell and wafer producers seeking to bypass US and EU tariff exposure. Target India's production-linked incentive schemes in Gujarat and Tamil Nadu for manufacturing localization serving domestic renewable purchase obligations. A go-to-market angle anchored in carbon intensity documentation compliance addresses EU Green Deal taxonomy eligibility requirements. For Investors and Strategic Acquirers: FERC Order 2023 interconnection queue reforms reshape the acquisition landscape by compressing development timelines for grid-ready solar and wind assets. Long-term viability favors developers with secured interconnection agreements and offtake contracts in markets transitioning from subsidy-dependent procurement to competitive auction frameworks. Acquisition target archetypes include independent power producers with contracted pipelines in Northern Virginia and Texas. The signal to watch is queue position advancement rates at regional transmission organizations as an inflection indicator for development velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Content Manufacturing Scale-Up | IRA production tax credits and EU CBAM compliance requirements incentivize module assembly in Arizona and northern European ports. |
| 24/7 Carbon-Free Energy Contracting | Data center operators in Northern Virginia and semiconductor fabs in Taiwan now require hourly generation-load matching. |
| Offshore Wind Lease Acquisition | Bureau of Ocean Energy Management auctions in the Gulf of Mexico open capacity zones with capacity factors exceeding 50%. |
| Green Hydrogen Electrolyzer Deployment | Curtailed wind generation in Brazil's Northeast creates synthetic fuel export corridors to European industrial offtakers. |
| Grid Interconnection Queue Positioning | FERC Order 2023 reforms compress timelines for solar and wind projects seeking transmission access in RTO markets. |
Research Methodology
Operator-level perspectives from utility planning officers, IPP project developers, EPC contractors, and grid operators anchored the qualitative base for this analysis. Primary interviews combined with secondary validation from EIA data, IEA reports, FERC filings, and project development databases established supply-side and demand-side triangulation. Bottom-up capacity addition modeling and top-down policy impact assessment were cross-referenced for convergence.
Scenario-bracketing around IRA tax credit permanence, EU CBAM enforcement timing, and China's grid parity mandate acceleration bounded the analytical framework. Segmentation dimensions modeled span fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs were derived from installed base growth rates, capacity factor assumptions, and levelized cost of energy trajectories across the projection horizon. Forecast inputs incorporated polysilicon supply elasticity, interconnection queue velocity, and corporate procurement contract tenor distributions.
Practitioners should monitor tariff enforcement actions, interconnection reform implementation, and feed-in tariff phase-out schedules for early signals of forecast revision. Forecasts reflect assumptions regarding policy continuity, technology cost curves, and commodity price stability. Quarterly review of queue position advancement rates, module import volumes, and corporate PPA announcement velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Variable Renewable Energy Market
Renewable Energy
Iran Renewable Energy Market
Renewable Energy
Solar Chair Market
Renewable Energy
South Africa Distributed Solar Energy Market
Renewable Energy
Net-Zero Energy Buildings Market
Renewable Energy
Hydrokinetic Converters Market
Renewable Energy
Asia-Pacific Renewable Energy Market
Renewable Energy
Wave Energy Market
Renewable Energy
Green Power Market
Renewable Energy
Global Renewable Energy Market
Renewable Energy
Nigeria Renewable Energy Market
Renewable Energy
Republic of Ireland Renewable Energy Market
Renewable Energy
North Europe Renewable Energy Market
Renewable Energy
China Solar Photovoltaic Market
Renewable Energy
Solar Thermal Water Heater Market
Renewable Energy
Portugal Renewable Energy Market