
 Netherlands Renewable Energy Market | 2026-2036
Netherlands Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Renewable Energy Market Foresight
North Sea offshore wind build-out is reconfiguring Dutch generation geography. Siemens AG anchors turbine supply chains through its European offshore manufacturing footprint. Vattenfall AB competes in project development with operational assets across the Dutch continental shelf. Orsted AS extends its offshore expertise into Dutch waters through construction partnerships and long-term power purchase agreements.
Netherlands renewable energy encompasses solar photovoltaic, onshore and offshore wind, biomass conversion, and small-scale hydropower systems integrated into a densely populated, grid-constrained territory. Offshore wind dominates capacity additions due to favorable shallow-water geology and high capacity factors exceeding those of North Sea neighbors. Solar installations concentrate in residential and commercial rooftop segments where distributed generation bypasses transmission bottlenecks. Utility companies represent the primary end user category, aggregating output through TenneT's high-voltage network and contracting long-term supply to industrial offtakers.
The Netherlands Enterprise Agency (RVO) administers subsidy schemes including SDE++ that steer investment toward cost-competitive technologies. EU Green Deal targets and the national Climate Agreement bind sectoral emission reductions, forcing industrial users toward power purchase agreements and on-site renewable installations. Grid operators face regulatory pressure from the Dutch Authority for Consumers and Markets to accelerate connection timelines. Stakeholders must monitor whether offshore wind auction design and hydrogen co-location requirements reshape project economics faster than supply chain capacity can respond.
Market Dynamics
The EU Green Deal's binding emission targets are forcing Dutch industrial clusters toward electrification and renewable power purchase agreements faster than grid expansion can accommodate.
Growth Catalysts
- SDE++ Subsidy Scheme:The Netherlands Enterprise Agency steers capital toward cost-competitive offshore wind and green hydrogen through auction-based support mechanisms.
- Industrial Cluster Electrification:Rotterdam's port and refining complex procures clean power through long-term contracts to meet Climate Agreement mandates.
- North Sea Shallow-Water Geology:Favorable seabed conditions enable high-capacity-factor offshore installations with lower foundation costs than deeper neighboring waters.
Market Restraints
- Grid Connection Queues:The Dutch Authority for Consumers and Markets pressures TenneT to accelerate timelines, yet transmission bottlenecks persist in densely populated western provinces.
- Offshore Supply Concentration:Specialized vessel availability and turbine component fabrication concentrate in a handful of North Sea port facilities.
- Intermittency Management Costs:Battery storage and demand-response systems add capital intensity that erodes project returns without co-located hydrogen offtake.
Strategic Opportunities
- Green Hydrogen Co-Location:Electrolyzer deployment at offshore wind sites creates synthetic fuel export potential to German industrial users.
- Agrivoltaic Expansion:Dual-use solar installations on agricultural land in Gelderland and Overijssel bypass rooftop saturation in urban cores.
- Corporate PPA Aggregation:Energy-as-a-service platforms bundle SME demand to access utility-scale renewable supply previously reserved for large offtakers.
Industry Challenges
- Marine Engineering Talent Scarcity:Specialized offshore construction and subsea cable installation skills command premium wages across the North Sea basin.
- Permitting Timeline Compression:Environmental impact assessments for North Sea sites face scrutiny from fisheries and defense stakeholders.
- Legacy Gas Infrastructure Stranding:Groningen field decommissioning and grid reconfiguration require coordinated asset retirement planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Renewable Energy Market |
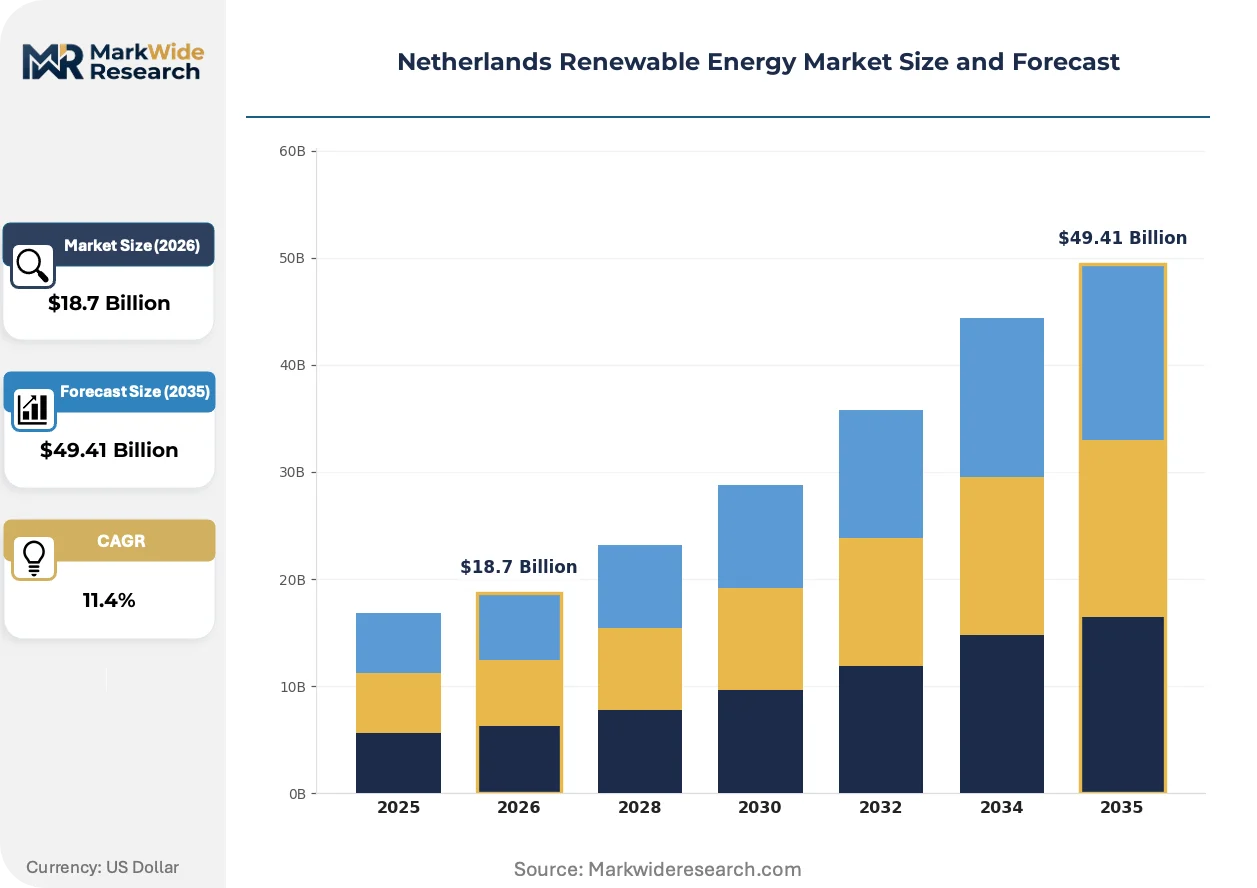
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar, Wind, Biomass, Hydropower Application: Residential, Commercial, Industrial, Transportation End User: Utility Companies, Private Consumers, Government, NGOs Service Type: Installation, Maintenance, Consulting, Financing |
| Companies Covered | Siemens AG, Sunstroom Engineering BV, Vattenfall AB, Statkraft AS, Shell Renewables & Energy Solutions, Orsted AS, TenneT Holding BV, Eneco Groep NV, RWE AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Renewable Energy Market Shifts & Advancements
Technology convergence between offshore generation and hydrogen production is redefining project economics. Regulatory pressure on industrial emissions accelerates demand-side transformation. Digitalization of asset management reshapes operational cost structures.
Floating offshore wind platforms are hybridizing with electrolyzer systems to produce hydrogen at sea, eliminating costly cable runs to shore. Port of Rotterdam developers pilot integrated designs where turbine power feeds directly to offshore conversion units. This architecture compresses transmission infrastructure requirements while opening deeper North Sea zones previously uneconomical for fixed-bottom foundations.
The EU Green Deal's Fit for 55 package tightens emission caps on Dutch heavy industry through the revised Emissions Trading System. Steel and chemical producers in IJmuiden and Moerdijk face carbon border adjustment exposure on exports. These facilities respond with power purchase agreement commitments that outstrip current renewable supply, pulling forward auction schedules and grid investment timelines.
Corporate buyers now aggregate demand through specialized procurement platforms rather than contracting directly with developers. Mid-sized manufacturers in Eindhoven's high-tech cluster access offshore wind supply through intermediaries that pool fragmented load. This channel shift concentrates buyer negotiating power while displacing traditional utility intermediaries in the western Randstad conurbation.
Netherlands Renewable Energy Market Segmentation
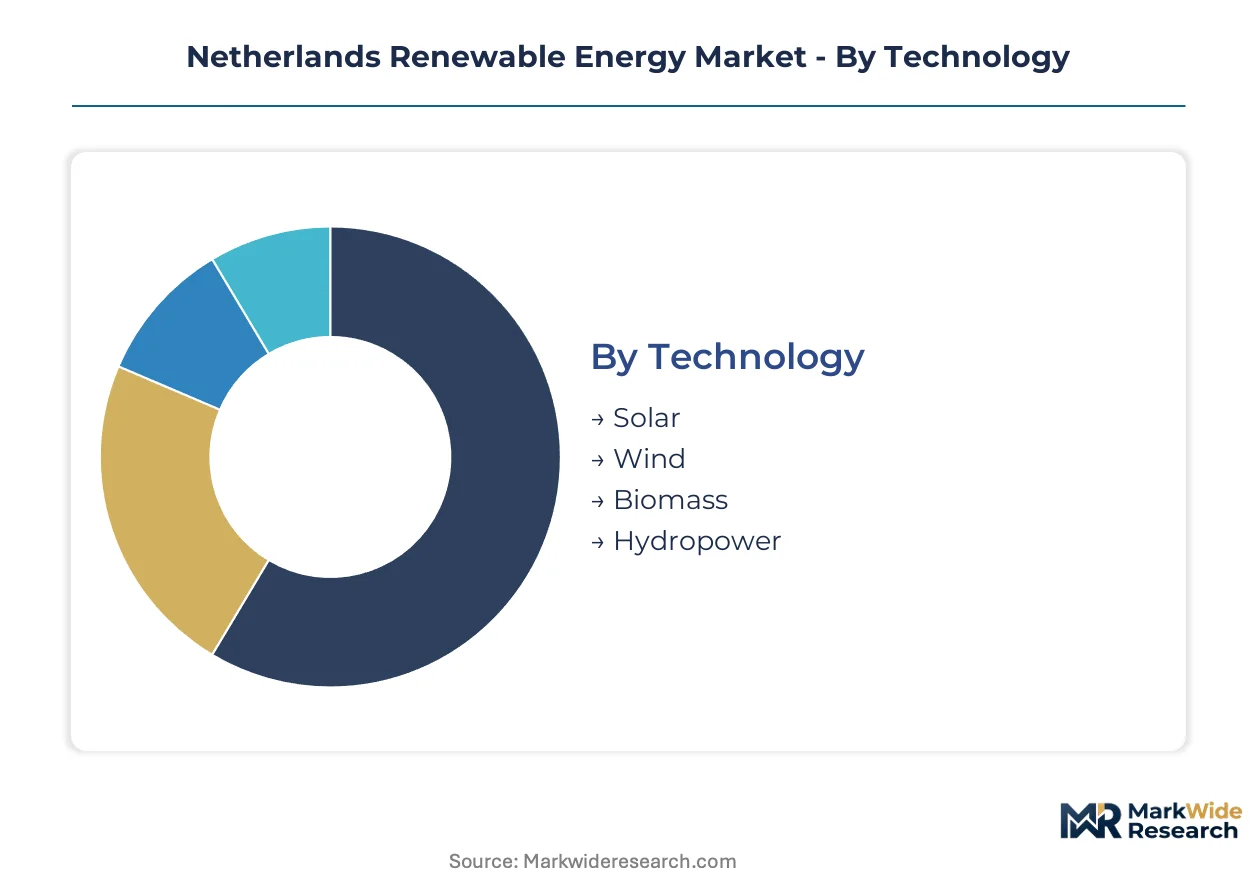
Dutch renewable energy segments exhibit divergent capital cycles. Offshore wind and utility-scale solar demand decade-long development timelines. Distributed residential solar and consulting services turn over in months. Understanding these velocity differences shapes procurement strategy and investment sequencing.
Technology:
Wind assets cycle slowest due to marine construction windows and grid connection queues. Solar panels turnover fastest as rooftop permitting streamlines. Biomass and hydropower occupy intermediate positions constrained by feedstock logistics and environmental licensing.
- Solar:Photovoltaic modules dominate distributed generation across Dutch rooftops and agrivoltaic installations. Residential demand concentrates in Randstad urban cores where grid congestion makes self-consumption economically attractive against rising retail tariffs.
- Wind:Offshore turbines anchor capacity additions through shallow-water North Sea developments. Rotterdam-Europoort industrial clusters procure output through long-term power purchase agreements to satisfy EU Green Deal emission mandates.
- Biomass:Organic waste conversion and agricultural residue processing supply combined heat and power systems. Feedstock availability limits expansion in Gelderland and Overijssel provinces.
- Hydropower:Small-scale run-of-river installations operate in Limburg and eastern border regions. Minimal untapped resource constrains meaningful capacity growth.
Wind dominates installed base. Solar is where expansion concentrates.
Application:
Industrial offtakers command largest contract values but slowest procurement cycles. Residential adoption accelerates through simplified net-metering frameworks. Commercial and transportation segments split between facility-level investment and fleet electrification infrastructure.
- Residential:Rooftop photovoltaic systems and small-scale battery storage address household electricity demand. SDE++ subsidy eligibility drives installation decisions in owner-occupied housing stock.
- Commercial:Mid-sized enterprises in Eindhoven's high-tech manufacturing corridor aggregate demand through energy-as-a-service platforms. These procurement intermediaries bypass traditional utility channels to access offshore wind supply.
- Industrial:Rotterdam port refining and chemical complexes electrify process heat and motive power. Climate Agreement binding targets force accelerated renewable power purchase agreement commitments.
- Transportation:Electric vehicle charging infrastructure and green hydrogen refueling stations expand along A15 and A2 motorway corridors. Fleet operators face zero-emission zone deadlines in Amsterdam and Utrecht.
Industrial applications anchor contract value. Residential installations are climbing the fastest.
End User:
Utility companies consolidate long-duration assets requiring grid integration expertise. Private consumers fragment across income brackets and housing tenure types. Government and NGO procurement concentrates on demonstration projects and social housing retrofits.
- Utility Companies:TenneT and regional network operators aggregate generation through high-voltage transmission infrastructure. These entities manage offshore wind grid connection queues and balancing responsibilities.
- Private Consumers:Homeowners and small businesses purchase distributed solar through installer networks. Financing availability and property ownership status segment this category sharply.
- Government:National and municipal entities procure renewable supply for public buildings and street lighting. RVO subsidy administration creates procurement coordination role.
- NGOs:Environmental organizations and cooperative associations develop community-owned wind and solar assets. These structures prioritize local participation over commercial returns.
Utility companies dominate installed base. Private consumers are gaining share fastest.
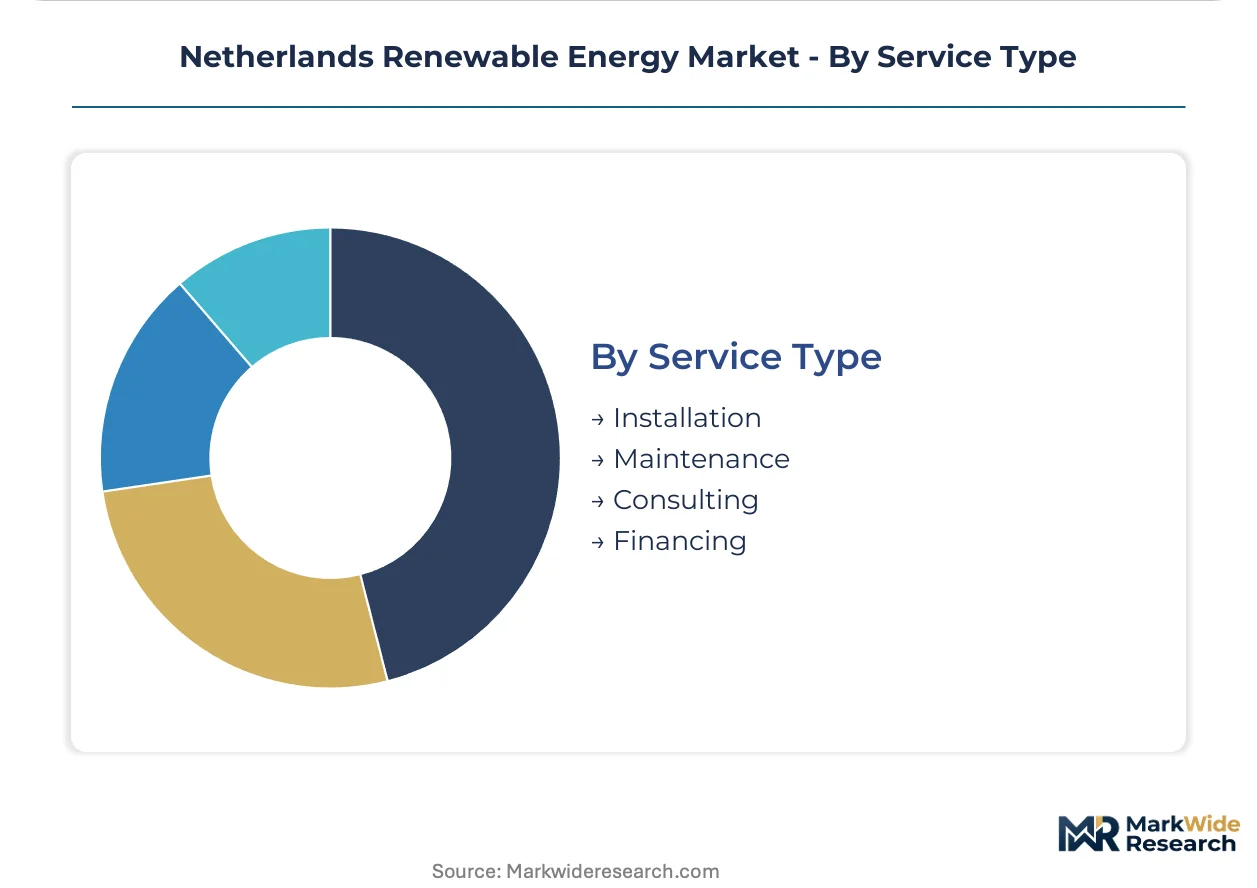
Service Type:
Installation services exhibit highest revenue volatility tied to subsidy auction schedules. Maintenance contracts generate recurring revenue streams extending across asset lifetimes. Consulting and financing occupy advisory positions with lower capital intensity.
- Installation:Engineering, procurement, and construction contractors deploy offshore foundations and onshore electrical infrastructure. North Sea vessel availability and specialized labor scarcity constrain throughput.
- Maintenance:Operations and service providers manage turbine availability and solar performance ratios. Long-term service agreements lock in revenue across twenty-year asset lifetimes.
- Consulting:Technical advisors and environmental assessors navigate permitting processes for Dutch Authority for Consumers and Markets and provincial regulators. Marine ecology and defense stakeholder coordination consumes timeline.
- Financing:Project finance institutions and green bond arrangers structure capital stacks for offshore wind development. SDE++ auction outcomes determine debt sizing and equity return thresholds.
Installation commands peak revenue years. Maintenance offers steadiest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Netherlands Authority for Consumers and Markets pressures TenneT to accelerate grid connection timelines across the country's western provinces. Dutch industrial clusters in Rotterdam and Eindhoven anchor renewable power procurement. The EU Green Deal and national Climate Agreement bind sectoral emission reductions across heavy industry.
Randstad
Rotterdam's port and refining complex electrifies process heat through long-term power purchase agreements. The SDE++ subsidy scheme steers capital toward offshore wind and green hydrogen auctions. TenneT manages high-voltage transmission infrastructure connecting North Sea generation to industrial offtakers in the Europoort cluster.
Brabant
Eindhoven's high-tech manufacturing corridor aggregates SME demand through energy-as-a-service platforms. The Climate Agreement mandates accelerate renewable procurement commitments from mid-sized enterprises. Philips and ASML supply chain facilities contract bundled offshore wind supply through specialized procurement intermediaries.
Northern Netherlands
Groningen's legacy gas field decommissioning requires coordinated grid reconfiguration toward renewable integration. The national government programs offshore wind auction rounds targeting shallow-water North Sea zones. Eemshaven port facilities concentrate turbine component fabrication and specialized vessel availability for marine construction.
Netherlands Renewable Energy Market Competitive Landscape
Integrated energy conglomerates and specialized offshore developers split the market between capital-intensive generation assets and nimble project pipelines. Siemens AG anchors turbine supply chains through European offshore manufacturing footprints. Vattenfall AB and Orsted AS compete in project development with operational assets across the Dutch continental shelf. Dominant competitive moves include strategic partnerships for hydrogen co-location and capacity expansion in North Sea shallow-water zones.
Within the integrated utility tier, RWE AG and Statkraft AS occupy positions spanning generation, trading, and industrial offtake contracting. Shell Renewables & Energy Solutions exemplifies oil-major pivot strategies toward electrons and molecules. Specialized developers including Sunstroom Engineering BV sit within the distributed solar segment, serving residential and commercial rooftop markets where permitting streamlines faster than offshore timelines. TenneT Holding BV anchors transmission infrastructure as the regulated monopoly operator, while Eneco Groep NV represents regional utility consolidation in retail and distributed energy services.
| Leading Market Players |
|---|
| Siemens AG |
| Sunstroom Engineering BV |
| Vattenfall AB |
| Statkraft AS |
| Shell Renewables & Energy Solutions |
| Orsted AS |
| TenneT Holding BV |
| Eneco Groep NV |
| RWE AG |
| Others |
Supply & Pricing Matrix
North Sea port infrastructure concentration in Denmark, Germany, and the Netherlands concentrates turbine component fabrication and specialized vessel availability, anchoring margin pools with EPC contractors and marine logistics operators rather than project developers or offtakers. This geographic chokepoint transmits cost volatility directly into Dutch offshore wind auction bids through foundation steel and inter-array cable pricing.
Pricing Analysis
Contract-based long-term offtake structures dominate Dutch renewable procurement, with industrial clusters in Rotterdam and Eindhoven locking in fifteen to twenty-year power purchase agreements. Price differentiation rests on volume scale and SDE++ subsidy tier eligibility, with utility-scale offtakers commanding lower per-MWh rates than fragmented SME demand aggregated through energy-as-a-service platforms. Pricing pressure stems from TenneT grid connection queue delays that extend project development timelines and inflate carrying costs. Mid-sized manufacturers exhibit highest price sensitivity due to limited balance-sheet capacity for long-term contract commitments.
Supply Chain Analysis
Monopile steel fabrication draws from Denmark, Spain, and Poland, while turbine nacelle assembly concentrates in Germany and Denmark. Rare-earth magnet supply for direct-drive generators rests on Chinese processing capacity. Single-source vulnerability pervades heavy-lift vessel availability, with only a handful of North Sea ports capable of marshaling jack-up installation units. Distribution runs through Rotterdam-Europoort and Eemshaven port facilities, where component staging and pre-assembly compress logistics timelines for Dutch continental shelf deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Dutch industrial clusters as Rotterdam port authorities and Eindhoven high-tech manufacturers consolidate procurement through specialized energy-as-a-service platforms. This aggregation displaces traditional utility intermediaries and compresses developer margins.
For Market Incumbents: Build regulatory relationship moats through early engagement with the Netherlands Enterprise Agency on SDE++ auction design and hydrogen co-location requirements. Siemens AG and Vestas-style OEMs should anchor capacity expansion in Eemshaven port zones to secure vessel access windows. The threat of Chinese turbine manufacturers entering European offshore markets via Baltic Sea demonstration projects demands accelerated service capability investment.
For New Entrants and Emerging Players: Pursue agrivoltaic development in Gelderland and Overijssel provinces where agricultural land availability and streamlined provincial permitting create faster deployment timelines than saturated Randstad rooftop markets. Target SME demand aggregation through digital procurement platforms that bypass incumbent utility channels. A direct-to-industrial-offtaker sales model with SDE++ auction participation support offers the clearest go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across floating offshore wind and hydrogen co-location sub-segments as foundation costs and electrolyzer capex stack. Long-term viability over the next decade hinges on successful technology convergence at scale. Acquisition targets should display operational offshore assets with contracted offtake rather than pre-construction pipelines. The signal to watch is TenneT grid connection timeline announcements, which indicate whether project completion schedules align with industrial PPA commencement dates.
| Strategic Initiative | Industry Significance |
|---|---|
| Offshore Wind Capacity Buildout | Rotterdam-Europoort industrial clusters secure contracted renewable supply to meet Climate Agreement mandates. |
| Green Hydrogen Co-Location | Electrolyzer deployment at North Sea sites creates synthetic fuel export pathways to German chemical users. |
| Backward Integration into Foundation Steel | EPC contractors secure monopile supply commitments through European fabrication partnerships, reducing vessel waiting costs. |
| Power Purchase Agreement Aggregation | Energy-as-a-service platforms bundle fragmented SME demand to access utility-scale offshore wind contracts. |
| Grid Connection Queue Acceleration | Pressure from the Dutch Authority for Consumers and Markets forces TenneT infrastructure investment timeline compression. |
Research Methodology
Desk research of IEA renewable energy databases, TenneT transmission planning documents, and SDE++ auction records preceded structured interviews with offshore wind project developers, EPC contractors, utility procurement officers, and industrial energy managers. Secondary validation drew from EU Green Deal policy filings, North Sea port authority infrastructure reports, and the Netherlands Enterprise Agency subsidy disbursement data. Bottom-up project pipeline aggregation and top-down national capacity targets were triangulated to establish market sizing.
Assumptions regarding SDE++ auction schedule continuity, TenneT grid expansion timelines, and industrial emission reduction compliance pathways were held fixed across the projection horizon, while technology cost curves and marine construction productivity were varied. Segmentation modeling incorporated technology type, application category, end-user archetype, and regional grid constraint severity. CAGRs were derived from weighted average auction price trajectories and announced project development timelines, with electrolyzer cost learning curves and floating foundation maturation serving as key technology inputs.
Macroeconomic conditions sit as an overlay; deviation in eurozone interest rate policy, steel commodity pricing, or EU carbon border adjustment implementation would shift the trajectory. Forecasts reflect these assumptions and acknowledge that marine permitting delays or North Sea fisheries stakeholder litigation could compress development velocity. Cross-checking against IEA Netherlands renewable energy outlooks and TenneT official network development plans is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Solar Autoclave Market
Renewable Energy
Uzbekistan Renewable Energy Market
Renewable Energy
East Europe Renewable Energy Market
Renewable Energy
Algeria Renewable Energy Market
Renewable Energy
North America Solar Tracker Market
Renewable Energy
Renewable Naphtha Market
Renewable Energy
Nigeria Renewable Energy Market
Renewable Energy
Turkey Renewable Energy Market
Renewable Energy
Austria Renewable Energy Market
Renewable Energy
Solar Chimney Market
Renewable Energy
East Asia Renewable Energy Market
Renewable Energy
Solar Balloon Market
Renewable Energy
United States Renewable Energy Market
Renewable Energy
Romania Power Market
Renewable Energy
South Korea Renewable Energy Market
Renewable Energy
China Wind Power Market