
 Renewable Energy Enclosures Market | 2026-2036
Renewable Energy Enclosures Market Size, Share, and Industry Trends Forecast 2026-2036
Renewable Energy Enclosures Market Insights
Chinese steel-fabrication clusters is repositioning global supply dynamics for renewable energy enclosures. Rittal leverages its European manufacturing footprint to serve utility-scale solar farms across Germany and Spain. Schneider Electric anchors its position through integrated power-distribution software bundled with thermal enclosure systems. Siemens competes on IEC-certified designs that streamline grid-connection approvals in multiple jurisdictions.
Renewable energy enclosures are engineered housings that protect power-electronics, battery cells, and distribution equipment from environmental degradation, thermal runaway, and electromagnetic interference, typically fabricated from galvanized steel or aluminum alloys with IP55+ ingress protection and active ventilation or liquid-cooling integration. Their primary purpose is to extend equipment lifespan and ensure safety compliance in outdoor installations exposed to temperature extremes, moisture, and particulate contamination. Battery Storage enclosures command premium margins due to fire-suppression and thermal-management complexity, while Solar Inverter housings represent the highest volume segment driven by utility-scale photovoltaic deployment. Steel dominates material selection for ground-mounted utility installations, though Aluminum gains share in rooftop and wall-mounted commercial applications where weight reduction matters.
FERC Order 2222 in the United States enables distributed energy resource aggregation, directly expanding addressable demand for grid-interactive enclosure systems that house bidirectional power electronics. The EU Green Deal and CE marking requirements under the Low Voltage Directive constrain market access to enclosure designs meeting electromagnetic compatibility and material-recovery standards. Stakeholders must monitor evolving fire-code amendments for lithium-ion battery installations, as these regulations will determine whether passive or active thermal-management enclosure architectures become the default specification.
Market Dynamics
Utility-scale battery storage deployment in Texas and California is compressing thermal-management enclosure lead times and forcing suppliers to pre-certify designs against evolving fire codes before project bidding.
Growth Catalysts
- NEMA 3R and 4X certification requirements:North American utilities now mandate these ingress protection standards for outdoor inverter housings, disqualifying uncertified fabricators from bidding on federally subsidized solar projects under the IRA production tax credit framework.
- Lithium-ion thermal runaway containment:Battery storage enclosures with integrated fire-suppression and liquid-cooling are commanding procurement priority as California's Title 24 building standards tighten safety specifications for grid-scale installations.
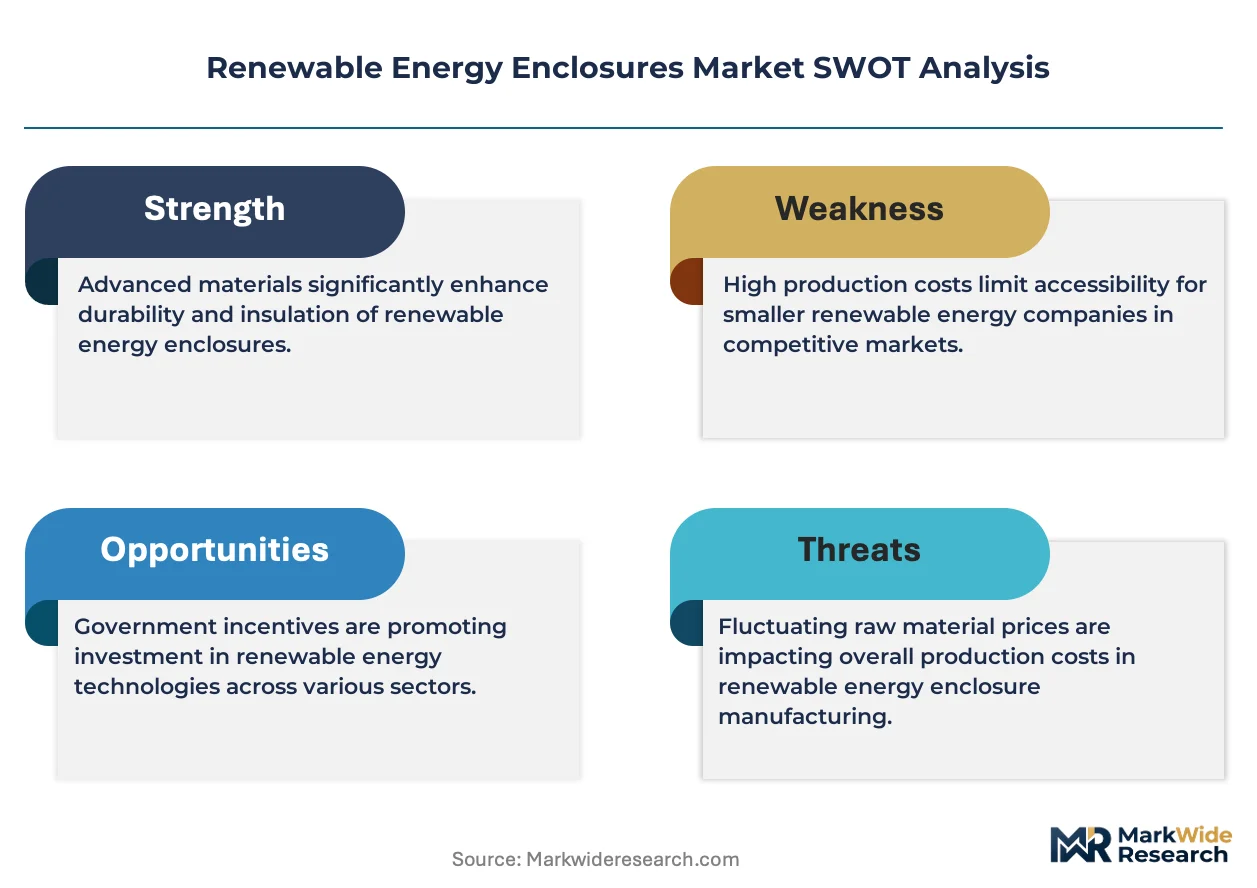
- Chinese steel-fabrication clusters:Concentrated capacity in Jiangsu and Shandong provinces is compressing raw material costs for galvanized enclosure shells, enabling price-competitive exports to European solar developers.
Market Restraints
- Aluminum alloy price volatility:Rooftop commercial installations face margin pressure from London Metal Exchange aluminum fluctuations, forcing fabricators to absorb cost swings or lose wall-mounted projects to steel alternatives.
- IEC 61439-2 compliance timelines:European low-voltage switchgear standards require 12-18 month certification cycles for power-distribution enclosures, freezing new entrants out of German utility tenders until approvals clear.
- Passive cooling architecture limitations:Desert solar farms in Nevada and Arizona are rejecting natural-convection designs above 50°C ambient, mandating active ventilation that adds cost and maintenance burden.
Strategic Opportunities
- India's PLI scheme for solar manufacturing:Domestic content requirements for photovoltaic components are creating captive demand for locally fabricated inverter enclosures in Gujarat and Rajasthan manufacturing hubs.
- FERC Order 2222 aggregation infrastructure:Distributed energy resource interconnection rules in the United States are spawning demand for compact bidirectional power-electronics housings that grid operators can deploy at substation edge nodes.
- Hydrogen electrolyzer integration:Converging power-to-gas projects in Spain and Denmark are specifying enclosures that simultaneously house rectifiers, inverters, and hydrogen safety systems, opening a new specification category.
Industry Challenges
- Computational fluid dynamics modeling talent:Thermal simulation expertise for optimizing enclosure airflow is concentrated among automotive and aerospace engineers, creating recruitment competition that delays design cycles.
- IP55 to IP66 upgrade certification costs:Sealing validation for dust-tight marine-grade enclosures requires third-party testing fees that strain mid-tier fabricators serving offshore wind markets in the North Sea.
- Legacy SCADA integration complexity:Grid-interactive enclosures must communicate with decades-old utility control systems, forcing custom protocol gateways that extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renewable Energy Enclosures Market |
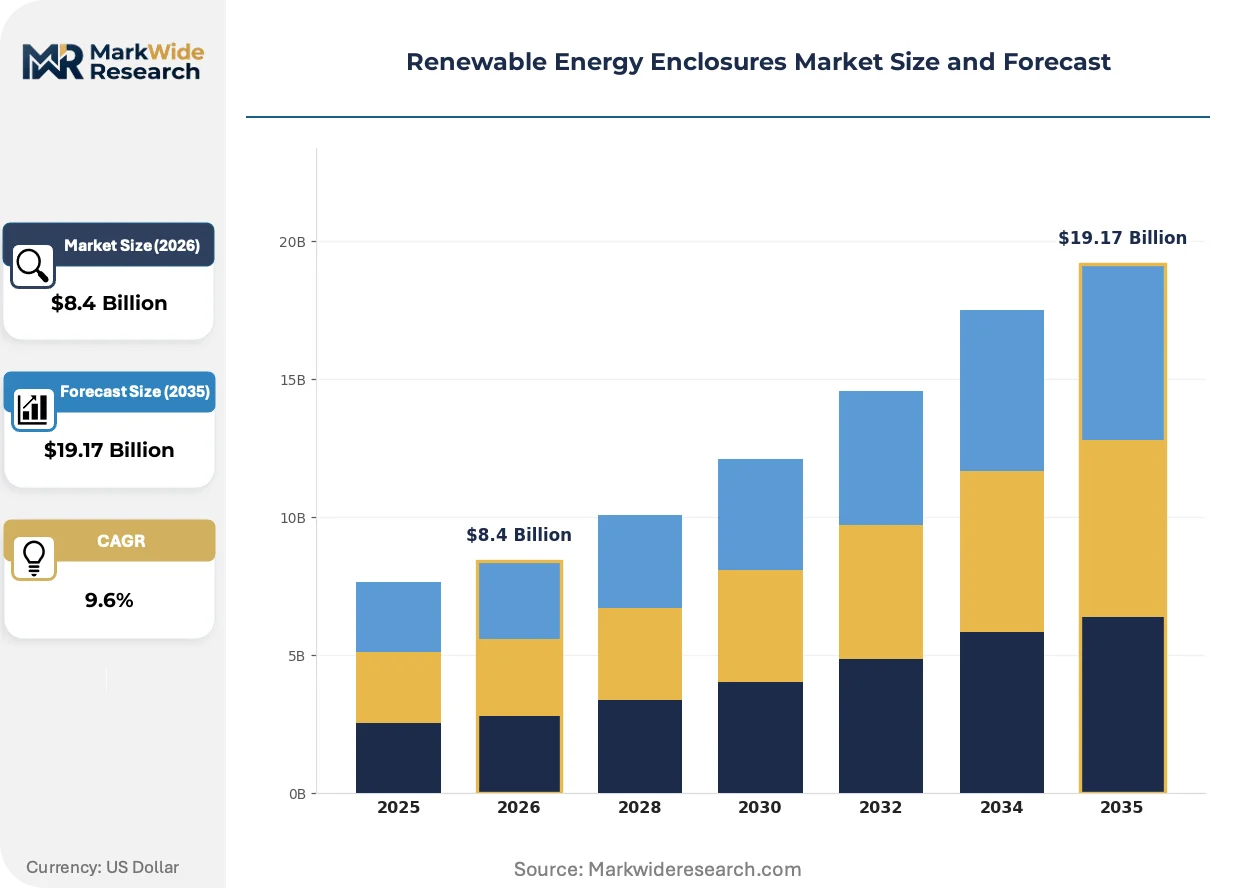
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.17 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Storage, Solar Inverters, Power Distribution Units, Enclosure Systems Material: Steel, Aluminum, Polycarbonate, Composite Materials Installation: Ground Mounted, Wall Mounted, Portable, Integrated Systems End User: Utilities, Commercial Buildings, Residential, Industrial Applications |
| Companies Covered | Rittal, Schneider Electric, Eaton, ABB, Pentair, Emerson, Hubbell, Siemens, nVent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renewable Energy Enclosures Market Trends and Innovations
Liquid-cooled thermal architectures are displacing air-cooled designs in high-density battery enclosures, while digital twin simulation is compressing prototyping cycles. Regulatory pressure on fire safety is accelerating passive-to-active cooling transitions.
Phase-change material thermal buffering is electrifying enclosure temperature management by absorbing peak heat loads during battery charge cycles. Texas utility-scale developers are adopting these systems fastest, driven by 100°F summer ambient conditions. The technology is electrifying competitive positioning for fabricators who can integrate paraffin-based cooling without expanding enclosure footprint.
EU F-Gas Regulation restrictions on hydrofluorocarbon refrigerants are forcing enclosure suppliers to specify CO2 or propane-based cooling circuits for European battery storage projects. Industrial consequence includes redesign of compressor systems and safety venting. German and Spanish utility EPCs are responding by pre-qualifying only suppliers with EU-approved alternative refrigerant portfolios.
Buyer consolidation among independent power producers is compressing supplier lists to tier-one fabricators with multi-site service networks. Long-term service agreements now bundle enclosure maintenance with inverter warranties, displacing spot procurement. This pattern is most visible in California and Texas where NextEra and AES dominate project development.
Renewable Energy Enclosures Market Segmentation
Segmentation in renewable energy enclosures reveals how thermal management requirements, structural loads, and regulatory compliance vary sharply across deployment contexts. Procurement specifications diverge materially between utility-scale battery farms and distributed commercial solar, driving distinct supplier capabilities and certification investments.
Product Type:
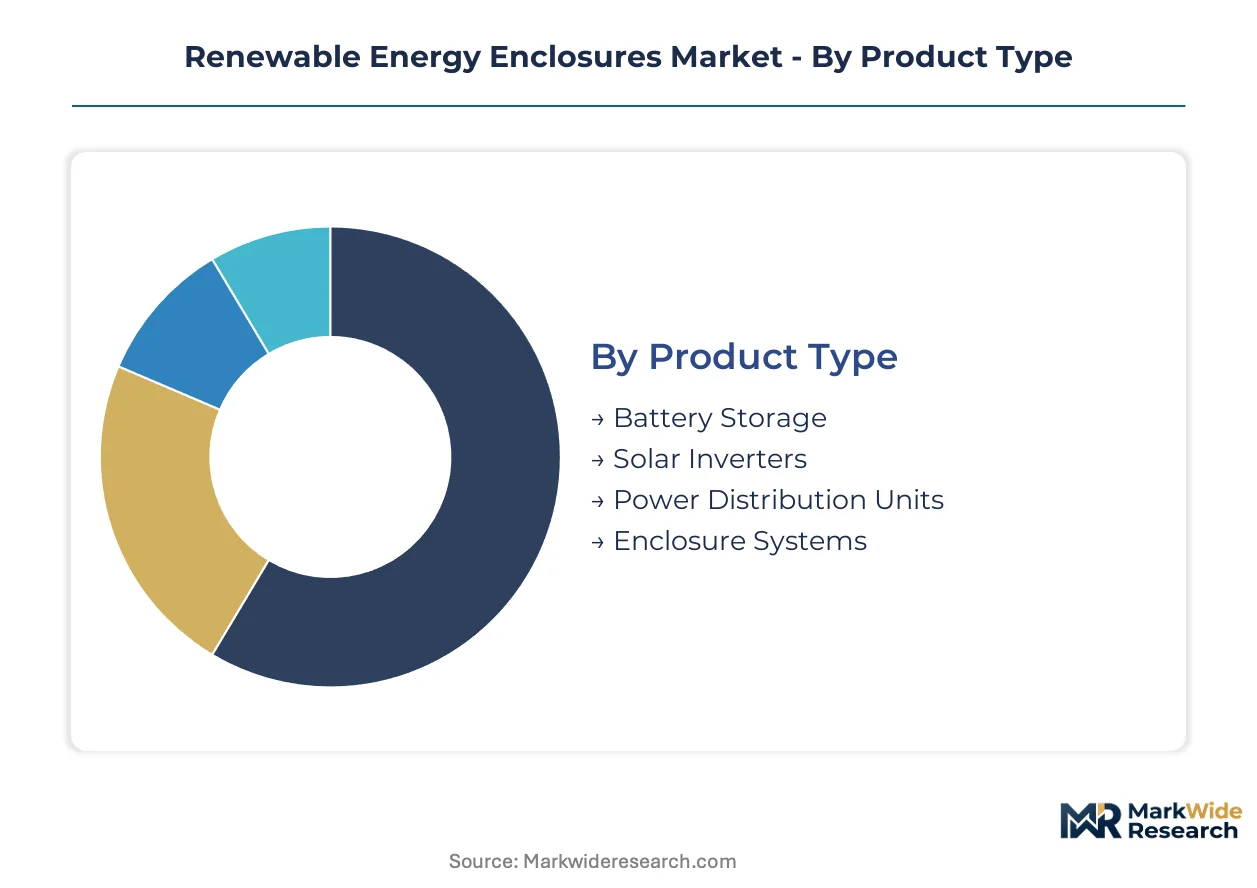
Standardization dominates high-volume inverter housings, while battery storage enclosures demand bespoke thermal and fire-safety engineering.
- Battery Storage:These enclosures integrate liquid-cooling circuits, fire-suppression systems, and thermal runaway containment barriers. Demand concentrates in Texas and California utility-scale projects where Title 24 and evolving fire codes mandate active safety architectures. Premium margins reflect certification complexity and thermal simulation requirements.
- Solar Inverters:Galvanized steel housings with NEMA 3R or 4X ingress protection constitute the highest shipment volumes. Procurement flows through German and Spanish utility-scale solar farms where IEC-certified designs streamline grid-connection approvals.
- Power Distribution Units:Low-voltage switchgear enclosures serving grid interconnection points.
- Enclosure Systems:Integrated housing solutions combining multiple power-electronics functions.
Most installed capacity flows through Solar Inverters. Expansion is steepest in Battery Storage.
Material:
Cost tier and weight constraints split procurement between heavy-duty utility installations and commercial rooftop applications.
- Steel:Hot-dip galvanized carbon steel dominates ground-mounted utility installations for structural rigidity and cost efficiency. Chinese fabrication clusters in Jiangsu and Shandong provinces supply competitive shell components to European developers.
- Aluminum:Extruded aluminum alloys enable weight reduction critical for wall-mounted commercial and residential rooftops. London Metal Exchange price volatility pressures fabricator margins on these projects.
- Polycarbonate:UV-stabilized thermoplastic housings for lightweight, corrosion-resistant applications.
- Composite Materials:Fiber-reinforced polymer enclosures for specialized marine or chemical-exposure environments.
Steel commands the greatest installed base. Aluminum is gaining share fastest in commercial distributed generation.
Installation:
Volume scale and service accessibility determine whether fixed or mobile deployment architectures prevail.
- Ground Mounted:Concrete-pad installations housing utility-scale inverters and battery containers. Desert solar farms in Nevada and Arizona reject passive cooling designs above 50°C ambient, mandating active ventilation.
- Wall Mounted:Commercial building facades and electrical rooms where aluminum weight reduction matters. California commercial developers favor these for distributed solar retrofits.
- Portable:Skid-mounted or containerized systems for temporary or mobile power applications.
- Integrated Systems:Factory-assembled power-electronics skids reducing field commissioning time.
Ground Mounted absorbs the majority of megawatt-scale deployments. Wall Mounted is climbing the fastest as commercial rooftop solar accelerates.
End User:
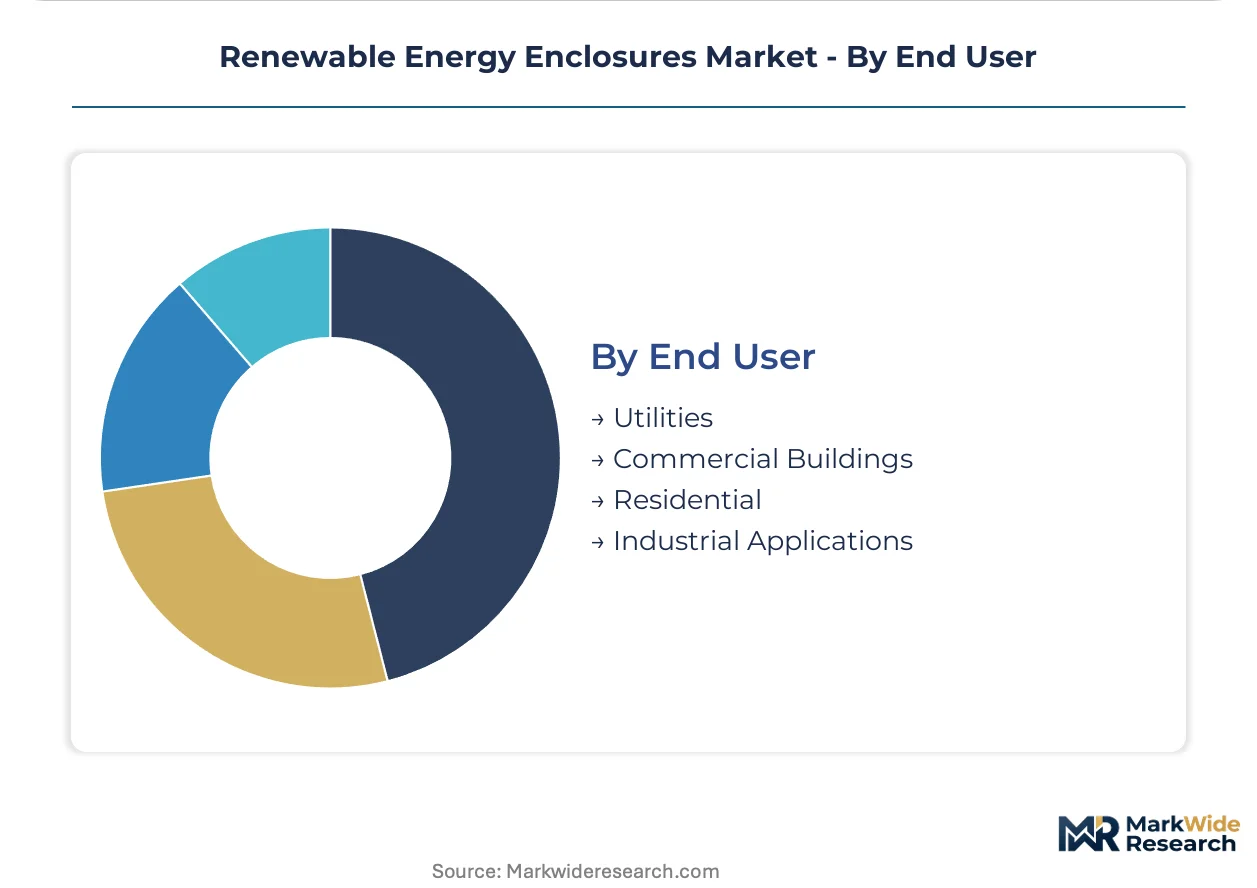
Customer type dictates procurement scale, service contract structures, and regulatory compliance intensity.
- Utilities:Investor-owned and public utilities drive bulk procurement with multi-site service requirements. NextEra and AES in California and Texas now bundle long-term enclosure maintenance with inverter warranties, compressing supplier lists to tier-one fabricators.
- Commercial Buildings:Corporate offtakers and property developers specifying distributed solar and storage. FERC Order 2222 aggregation rules expand addressable demand for grid-interactive bidirectional power-electronics housings.
- Residential:Single-family and small multi-family installations with standardized product requirements.
- Industrial Applications:Manufacturing facilities and data centers with high-reliability power infrastructure needs.
Utilities represent the largest revenue pool. Commercial Buildings show the steepest expansion trajectory behind corporate renewable procurement commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's steel-fabrication clusters compress enclosure shell costs while Germany's IEC certification requirements reshape supplier qualification criteria across Europe. Demand concentrates in utility-scale battery storage projects across Texas and California, grid modernization spending in Germany and Spain, and solar manufacturing hubs in India.
United States
Utility-scale battery storage deployment in Texas and California accelerates procurement of thermally managed enclosures with fire-suppression integration. FERC Order 2222 enables distributed energy resource aggregation, expanding demand for grid-interactive bidirectional power-electronics housings. California's Title 24 building standards tighten safety specifications, forcing suppliers to pre-certify designs before project bidding.
Germany
Utility-scale solar farms across Germany and Spain drive high-volume demand for IEC-certified inverter housings that streamline grid-connection approvals. EU F-Gas Regulation restrictions on hydrofluorocarbon refrigerants force enclosure suppliers to specify CO2 or propane-based cooling circuits. Rittal leverages its European manufacturing footprint to serve these installations.
China
Concentrated steel-fabrication capacity in Jiangsu and Shandong provinces enables price-competitive exports of galvanized enclosure shells to European solar developers. Domestic renewable capacity additions sustain captive demand for locally fabricated power-electronics housings. Chinese producers anchor the cost-competitive tier of global supply.
India
The PLI scheme for solar manufacturing creates captive demand for locally fabricated inverter enclosures in Gujarat and Rajasthan manufacturing hubs. Domestic content requirements for photovoltaic components force procurement shifts toward indigenous fabrication. These hubs concentrate assembly operations for both domestic deployment and regional export.
Spain
Converging power-to-gas projects in Spain and Denmark specify enclosures that simultaneously house rectifiers, inverters, and hydrogen safety systems. EU Green Deal and CE marking requirements under the Low Voltage Directive constrain market access to designs meeting electromagnetic compatibility standards. Spanish utility EPCs pre-qualify only suppliers with EU-approved alternative refrigerant portfolios.
Renewable Energy Enclosures Market Competitive Landscape
Chinese producers anchor one tier; European specialists hold certification-driven positions in premium utility-scale segments. The vendor base splits between scale-driven steel fabricators serving high-volume solar inverter demand and thermal-engineering specialists capturing battery storage premiums. Two strategic archetypes dominate: integrated power-distribution conglomerates bundling software with enclosure systems, and pure-play thermal-management fabricators competing on fire-safety certification. Competitive moves concentrate on multi-site service network expansion and long-term maintenance agreement bundling.
Among Germany-based fabricators, Rittal and Siemens occupy positions within the European certification-focused tier. Schneider Electric exemplifies the integrated conglomerate archetype through bundled power-distribution software offerings. These three companies represent distinct competitive vectors: Rittal anchors manufacturing footprint advantages, Siemens competes on IEC-certified design standardization, and Schneider Electric leverages software-integration differentiation.
| Leading Market Players |
|---|
| Rittal |
| Schneider Electric |
| Eaton |
| ABB |
| Pentair |
| Emerson |
| Hubbell |
| Siemens |
| nVent |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between IEC-certified thermal-management systems and uncertified commodity steel shells splits procurement economics across utility-scale and commercial rooftop segments. This bifurcation channels premium margins toward German and Spanish fabricators holding CE marking under the Low Voltage Directive while compressing returns for Jiangsu and Shandong producers supplying standardized inverter housings.
Pricing Analysis
Distributor margins on battery storage enclosures absorb certification and fire-safety engineering costs before reaching utility EPCs in Texas and California. Three-tier pricing structure across NEMA 4X-certified premium, IEC-standard mid-tier, and uncertified economy levels reflects thermal simulation investment and active cooling integration. Cost compression in steel-shell commodity tiers intensifies because Chinese fabrication clusters export at thin margins. Commercial rooftop developers in California exhibit highest price sensitivity, while utility procurement teams prioritize fire-code compliance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from NextEra and AES procurement teams mandate qualified backup suppliers for thermally managed battery enclosures across multi-site deployments. Manufacturing gravity centers on China for galvanized steel shells, Germany for IEC-certified power-distribution housings, and India for PLI-scheme solar inverter enclosures. Raw material dependencies span London Metal Exchange aluminum for rooftop applications, hot-dip galvanized carbon steel from Jiangsu mills, and CO2-based refrigerants for EU F-Gas Regulation compliance. Single-source vulnerability concentrates in thermal simulation engineering talent drawn from automotive and aerospace sectors. Distribution runs through EPC contractors bundling enclosure procurement with inverter and battery system awards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Chinese steel-fabrication cost advantages clash with European certification premiums, rewarding suppliers who bridge both cost structures through modular design platforms.
For Market Incumbents: Cement multi-site service network density across Texas and California utility corridors before buyer consolidation freezes supplier lists. Acquire thermal simulation engineering capability from automotive or aerospace sectors to defend against recruitment competition delaying design cycles. Pre-certify liquid-cooled architectures against evolving California Title 24 amendments to lock out uncertified competitors from federally subsidized IRA projects.
For New Entrants and Emerging Players: Capture India's PLI-scheme solar manufacturing hubs in Gujarat and Rajasthan where domestic content requirements force procurement shifts toward indigenous fabrication. Target hydrogen electrolyzer integration specifications in Spain and Denmark where converging power-to-gas projects specify novel enclosure categories without entrenched incumbent relationships. Lead with CO2-based cooling circuit engineering to bypass EU F-Gas Regulation barriers blocking hydrofluorocarbon-dependent suppliers.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier fabricators face IP55-to-IP66 upgrade certification costs straining balance sheets serving North Sea offshore wind markets. Five-to-ten year viability favors suppliers bundling long-term maintenance agreements with inverter warranties, displacing spot procurement. Target acquisition archetype: pure-play thermal-management fabricators holding California fire-code pre-certification. Signal to monitor: amendments to lithium-ion battery installation codes determining passive versus active cooling architecture defaults.
| Strategic Initiative | Industry Significance |
|---|---|
| Fire-Code Pre-Certification Investment | California Title 24 compliance locks in utility-scale procurement eligibility before project bidding opens. |
| Multi-Site Service Network Expansion | NextEra and AES bundling requirements compress supplier lists to tier-one fabricators with geographic coverage. |
| Alternative Refrigerant Portfolio Development | EU F-Gas Regulation restrictions force CO2 and propane-based cooling circuit specifications for European battery storage. |
| Thermal Simulation Engineering Acquisition | Automotive and aerospace talent scarcity delays enclosure design cycles without captive CFD modeling capability. |
| Domestic Content Alignment in India | PLI scheme requirements in Gujarat and Rajasthan manufacturing hubs redirect procurement toward indigenous fabrication. |
Research Methodology
Multiple input streams — structured interviews with utility planning officers and IPP project developers, EPC contractor procurement data, and FERC interconnection filings — were reconciled against secondary validation from EIA deployment statistics, IEA renewable capacity reports, and California Title 24 regulatory documentation. Primary fieldwork captured enclosure specification trends from grid operators in Texas and California, thermal engineering directors at battery storage integrators, and steel fabrication procurement leads in Jiangsu and Shandong provinces. Bottom-up project pipeline aggregation triangulated against top-down market sizing from customs trade data and utility CAPEX disclosures.
Data-stream reconciliation across product type, material grade, installation architecture, and end-user procurement scale produced volume and value estimates across the projection horizon. Segmentation dimensions modeled include thermal management intensity, ingress protection certification tier, and regional regulatory framework clustering. CAGRs were derived from deployment trajectory analysis against grid modernization spending patterns. Industry-specific forecast inputs incorporated FERC Order 2222 aggregation infrastructure buildout timelines and EU F-Gas Regulation compliance transition curves.
Regulatory amendment velocity, raw material price volatility, and thermal engineering labor market tightness are the dominant revision risks to modeled deployment schedules. Deviation in California fire-code amendment timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
West Europe Renewable Energy Market
Renewable Energy
Romania Power Market
Renewable Energy
Norway Renewable Energy Market
Renewable Energy
Germany Renewable Energy Market
Renewable Energy
Net-Zero Energy Buildings Market
Renewable Energy
Canada Renewable Energy Market
Renewable Energy
Japan Renewable Energy Market
Renewable Energy
Europe Biomethane Market
Renewable Energy
China Renewable Energy Market
Renewable Energy
Wave Energy Converter Market
Renewable Energy
Tidal Energy Generation Systems Market
Renewable Energy
Wind Turbine Foundation Market
Renewable Energy
Hybrid Solar Wind System Market
Renewable Energy
Romania Solar Energy Market
Renewable Energy
Renewable Naphtha Market
Renewable Energy
Africa Solar E-Bike Market