
 North America Wind Power Equipment Market | 2026-2036
North America Wind Power Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Wind Power Equipment Market Analytics
Multi-sourcing of blade and tower components is hardening across the supply base as OEMs reduce exposure to single-country dependencies. GE Vernova anchors domestic nacelle assembly capacity across multiple US manufacturing sites. Vestas Wind Systems leverages its Colorado blade facility to sustain proximity advantages for utility-scale developers. Siemens Gamesa Renewable Energy competes through specialized offshore direct-drive platforms targeting Atlantic projects.
North America wind power equipment encompasses the complete mechanical and electrical infrastructure required to convert kinetic wind energy into grid-synchronous electricity, including rotor assemblies exceeding 100 meters in diameter, pitch control systems, and power conversion electronics rated for variable frequency operation. The primary purpose spans utility-scale generation, distributed commercial supply, and emerging hybrid configurations paired with battery storage. Turbines and blades capture the dominant share of capital allocation, while offshore technology represents the fastest-expanding dimension as water-depth capabilities advance. Gearboxes face structural pressure from direct-drive alternatives, which eliminate intermediate mechanical stages and reduce maintenance intervals for remote maritime installations.
The Federal Aviation Administration coordinates airspace clearance for turbine height exemptions, while the Environmental Protection Agency oversees avian impact mitigation protocols that shape siting timelines. The Inflation Reduction Act's domestic content bonus credits are redirecting capital toward US-based forging and casting operations. State public utility commissions in Texas, Iowa, and California administer interconnection queues that determine project commercialization sequencing. Stakeholders must monitor transmission buildout commitments against equipment manufacturing lead times to avoid stranded capacity scenarios.
Market Dynamics
Offshore turbine scaling is compressing supply chain lead times while forcing port infrastructure investments along the US Atlantic seaboard and Gulf Coast. The Federal Aviation Administration's height exemption protocols and the Inflation Reduction Act's domestic content bonus credits are simultaneously constraining siting flexibility and redirecting forging capacity toward US-based operations.
Growth Catalysts
- Production Tax Credit Extensions:The Inflation Reduction Act's multi-year credit certainty is locking in utility procurement commitments for projects reaching financial close through 2032. Developers are accelerating offtake negotiations to secure qualifying construction timelines.
- Blade Manufacturing Proximity:Colorado and Texas blade facilities are reducing transport costs for utility-scale developers targeting central US wind corridors. Regional hub concentration is compressing logistics expenditure as a share of installed capital.
- Floating Foundation Advancement:Water-depth capabilities exceeding 60 meters are unlocking lease areas off California and Maine previously classified as uneconomical. Atlantic seaboard states are advancing port readiness assessments for assembly and staging operations.
Market Restraints
- Rare Earth Magnet Concentration:Direct-drive offshore platforms depend on neodymium supply chains concentrated in Chinese processing facilities. Tariff exposure and export licensing unpredictability are elevating input cost volatility for nacelle assembly.
- Interconnection Queue Congestion:State public utility commissions in Texas, Iowa, and California are administering backlogs exceeding three years for transmission access. Stranded project pipelines are freezing capital deployment timelines independent of equipment availability.
- Avian Impact Mitigation:The Environmental Protection Agency's seasonal siting restrictions and radar-activated curtailment systems are extending permitting durations for migratory corridor projects. Biological opinion delays are adding 12-18 months to commercialization schedules.
Strategic Opportunities
- Hybrid Storage Pairing:Battery co-location configurations are emerging as procurement differentiators for utility offtakers seeking firm capacity attributes. Developers are bundling turbine supply with integrated storage engineering to capture capacity market premiums.
- Gulf Coast Port Infrastructure:Louisiana and Texas deepwater facilities are positioning for floating foundation assembly serving Atlantic and Pacific lease areas. Multi-purpose heavy-lift terminals are attracting OEM staging investments ahead of federal lease auctions.
- Direct-Drive Platform Specialization:Gearbox elimination is reducing maintenance vessel requirements for remote maritime installations. Service providers are reconfiguring offshore logistics around lower-frequency component replacement cycles.
Industry Challenges
- Maritime Installation Vessel Scarcity:Jones Act-compliant heavy-lift jack-up vessels face construction backlogs extending through 2027. Project developers are competing for limited US-flagged capacity or accepting foreign vessel cost premiums.
- Composite Blade Recycling Infrastructure:Thermoset resin recovery technologies remain pre-commercial at scale, creating end-of-life liability exposure for utility asset owners. Landfill diversion mandates in California and Washington are accelerating circular economy pilot investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Wind Power Equipment Market |
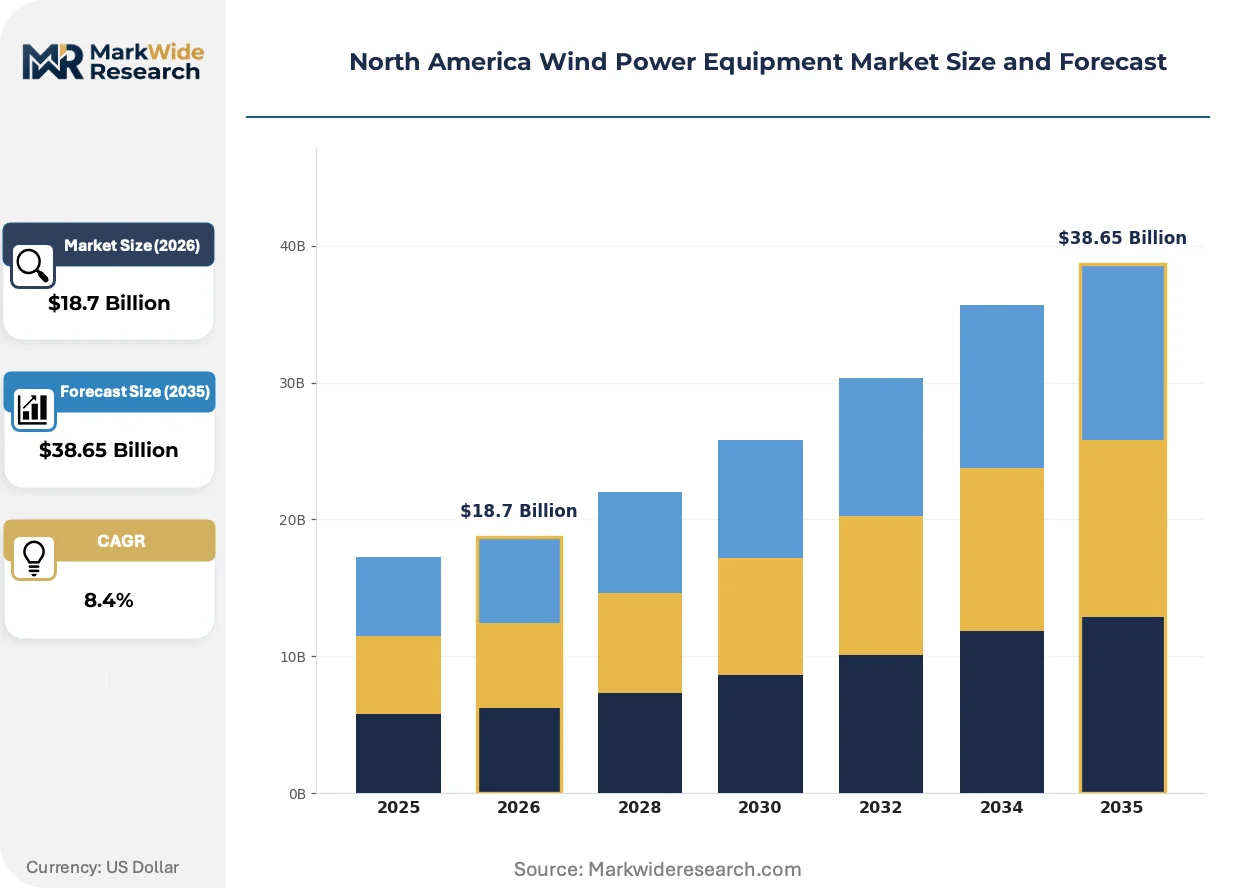
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Turbines, Gearboxes, Generators, Blades Technology: Horizontal Axis, Vertical Axis, Offshore, Onshore Installation Type: Utility Scale, Distributed Generation, Hybrid Systems, Microgrids End User: Utilities, Independent Power Producers, Commercial, Residential |
| Companies Covered | GE Vernova, Vestas Wind Systems, Siemens Gamesa Renewable Energy, TPI Composites, LM Wind Power, Nordex, Arcosa Wind Towers, NextEra Energy, Ørsted, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Wind Power Equipment Market Evolving Landscape
Digital twin deployment is compressing operational expenditure forecasting accuracy while predictive maintenance algorithms are reshaping service contract structures. Equipment manufacturers are embedding sensor arrays directly into blade laminates and drivetrain housings to capture real-time structural load data.
Advanced pitch control systems are automating turbine response to grid frequency events and wake steering optimization. Siemens Gamesa and GE Vernova are integrating machine learning modules into blade pitch actuators for real-time aerodynamic adjustment. US independent power producers are demanding this capability as a standard procurement specification for new offtake agreements.
The Inflation Reduction Act's domestic content bonus credits are redirecting capital toward US-based forging and casting operations. Equipment suppliers are qualifying alternative steel and aluminum sources to meet 40% domestic content thresholds for maximum credit capture. Nacelle assembly facilities in South Carolina and Florida are expanding to integrate previously imported subcomponents.
Utility procurement teams are consolidating supplier relationships around integrated turbine-service packages rather than equipment-only transactions. Developers are negotiating 15-20 year service extensions at financial close to lock in operational cost predictability. Texas and Oklahoma utility-scale projects are leading this contracting evolution, with integrated procurement now representing the majority of new capacity awards.
North America Wind Power Equipment Market Segmentation
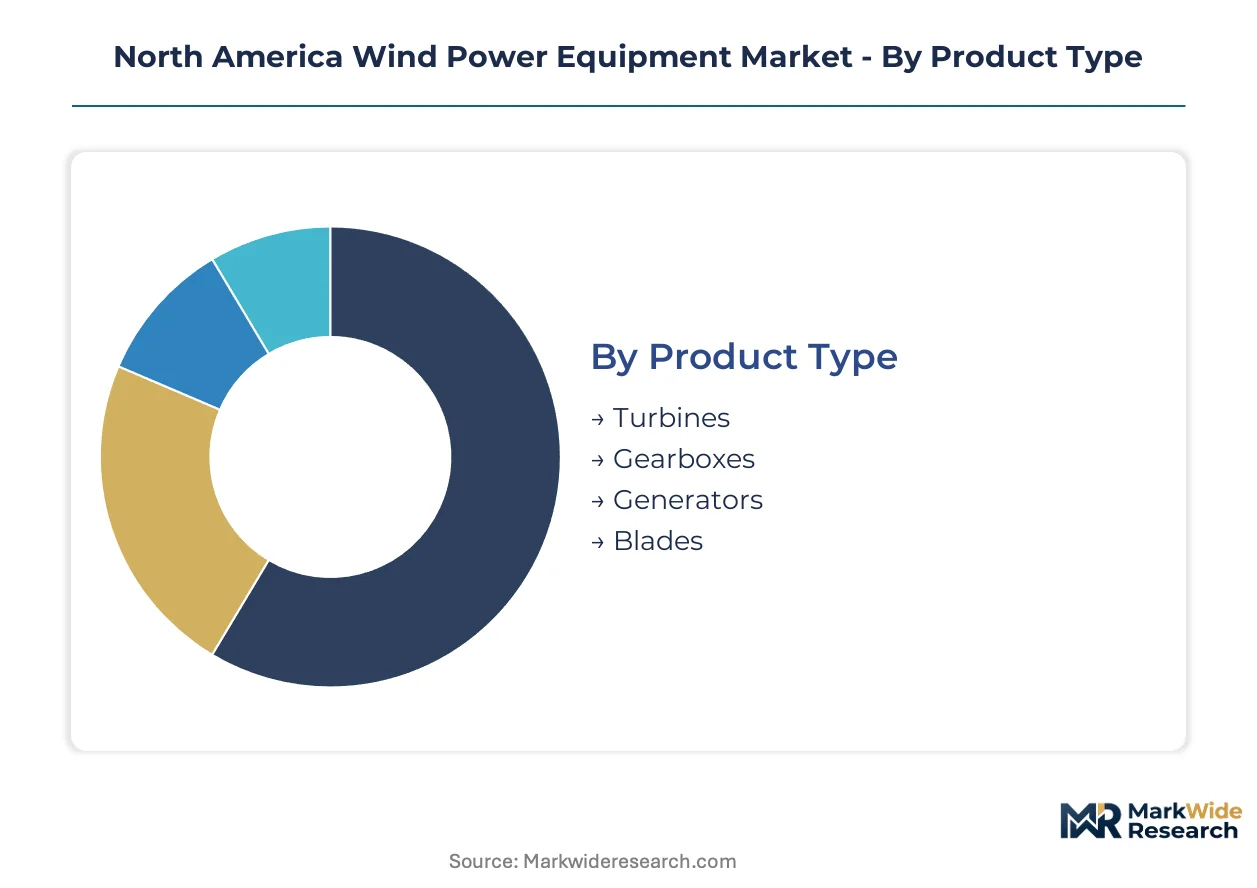
Equipment segmentation in North American wind power reveals distinct procurement patterns across turbine configurations and installation scales. Utility buyers prioritize technology bundles that optimize capacity factors against transmission interconnection costs, while distributed developers seek modular systems with streamlined permitting pathways.
Product Type:
Capital allocation decisions hinge on component lifecycle durability and supply chain proximity to project sites.
- Turbines:Complete rotor-nacelle assemblies integrating drivetrain, hub, and pitch control systems. Demand clusters along the US Gulf Coast and Atlantic seaboard where offshore-capable platforms require specialized foundation interfaces and maritime logistics coordination.
- Blades:Glass-fiber and carbon-fiber composite structures exceeding 100 meters in length for utility-scale applications. Colorado and Texas manufacturing facilities are capturing procurement preference from central US developers seeking to compress transport expenditure and damage risk during overland haul.
- Gearboxes:Multi-stage speed increasers connecting rotor to generator. Direct-drive alternatives are displacing conventional geared architectures in offshore specifications where maintenance vessel access carries premium cost.
- Generators:Doubly-fed induction and permanent magnet synchronous units rated for variable frequency operation. The Inflation Reduction Act's domestic content thresholds are redirecting sourcing toward US-based winding and lamination facilities.
Turbines lead on scale; blades lead on momentum.
Technology:
Site conditions and water depth dictate rotor orientation and foundation selection across procurement portfolios.
- Offshore:Fixed-bottom and floating foundation systems targeting water depths from 30 to 200 meters. Atlantic lease areas off Massachusetts and New Jersey are driving nacelle assembly investments at South Carolina and Florida facilities.
- Onshore:Land-based turbines optimized for hub heights between 80 and 160 meters. Texas, Iowa, and Oklahoma project pipelines are concentrating demand for high-capacity factor configurations with advanced wake steering capabilities.
- Horizontal Axis:Upwind rotor configurations dominating utility-scale deployment. FAA height exemption protocols constrain maximum tip elevation, compressing design flexibility for tall tower applications in migratory corridors.
- Vertical Axis:Darrieus and Savonius architectures for distributed urban and commercial rooftops. Limited penetration reflects lower aerodynamic efficiency and higher unit cost per rated kilowatt.
Onshore installations dominate cumulative capacity; offshore platforms are climbing the fastest.
Installation Type:
Grid interconnection scale and regulatory jurisdiction shape developer technology bundling strategies.
- Utility Scale:Projects exceeding 100 MW with dedicated transmission infrastructure. FERC interconnection queues and state PUC sequencing determine commercialization timelines independent of equipment manufacturing lead times.
- Distributed Generation:Commercial and industrial behind-the-meter installations from 100 kW to 5 MW. Accelerated permitting pathways under streamlined environmental review are compressing development cycles relative to utility-scale counterparts.
- Hybrid Systems:Co-located wind and battery storage configurations capturing capacity market premiums. ERCOT and CAISO grid operators are driving procurement specifications for firm capacity attributes.
- Microgrids:Islanded or weak-grid connected systems with integrated control architecture. Alaska and remote Canadian territories represent concentrated demand for cold-climate rated components with black-start capability.
Utility scale leads on scale; hybrid systems lead on momentum.
End User:
Counterparty credit quality and offtake duration structure equipment financing and service contract terms.
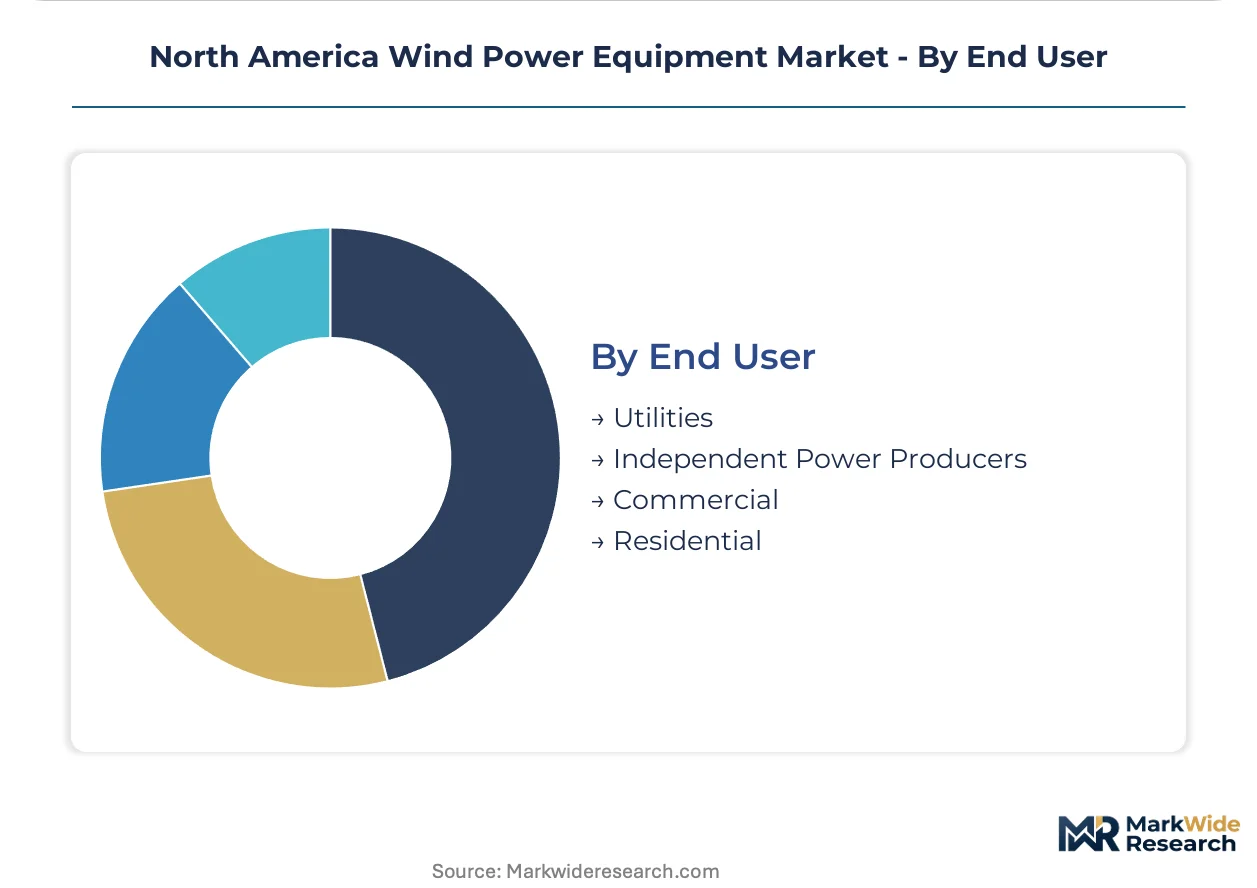
- Utilities:Investor-owned and public power entities with regulated rate-base treatment. Integrated turbine-service packages spanning 15-20 years are displacing equipment-only procurement in Texas and Oklahoma markets.
- Independent Power Producers:Merchant and contracted developers selling to wholesale markets or under corporate PPAs. Financial close deadlines tied to Inflation Reduction Act credit qualification are accelerating construction timelines.
- Commercial:Corporate offtakers with renewable energy credit requirements and carbon reduction commitments. Virtual and physical PPAs are expanding addressable market beyond traditional utility procurement.
- Residential:Small-scale distributed systems typically below 100 kW. Limited penetration in North America reflects zoning restrictions, aesthetic opposition, and unfavorable economics relative to utility-scale alternatives.
Utilities lead on scale; independent power producers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Gulf Coast industrial corridor anchors North American wind power equipment demand through offshore-capable nacelle assembly and blade manufacturing concentration. Port infrastructure investments at Corpus Christi and Lake Charles are staging floating foundation components for Atlantic lease area deployment.
United States
Texas and Iowa utility-scale pipelines drive demand for high-capacity factor turbine configurations with advanced wake steering. The Federal Aviation Administration coordinates height exemption protocols that constrain tall tower siting in migratory corridors. South Carolina nacelle facilities are expanding to integrate previously imported subcomponents under Inflation Reduction Act domestic content thresholds.
Canada
Ontario and Quebec procurement programs concentrate demand for cold-climate rated drivetrain components with extended temperature operating ranges. Environment and Climate Change Canada administers migratory bird impact assessments that extend permitting timelines for prairie corridor projects. Alberta wind corridors are attracting blade logistics hubs to reduce overland transport expenditure from US manufacturing centers.
Mexico
Baja California and Oaxaca wind resource zones sustain demand for utility-scale horizontal axis configurations with grid-stabilizing power electronics. The Comisión Reguladora de Energía oversees interconnection queue administration for merchant and contracted developers. Monterrey industrial clusters are positioning for tower forging capacity to serve cross-border equipment procurement from Texas and California developers.
North America Wind Power Equipment Market Competitive Landscape
Global majors compete with regional champions across foundation logistics and port staging capabilities. The market structure consolidates around integrated turbine-service packages rather than equipment-only transactions, compressing vendor counts at the utility procurement tier. Three archetypes dominate: full-system OEMs with domestic assembly footprints, specialized blade and tower fabricators, and offshore project developers with captive equipment sourcing. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms position for Inflation Reduction Act credit qualification timelines.
Among full-system OEMs, GE Vernova, Vestas Wind Systems, and Siemens Gamesa Renewable Energy exemplify the integrated manufacturing archetype with US-based nacelle and blade facilities. These companies occupy positions within the premium-tier equipment segment where domestic content compliance determines credit capture eligibility. Their manufacturing footprints anchor regional supply chain clustering around Colorado blade facilities and South Carolina assembly operations.
| Leading Market Players |
|---|
| GE Vernova |
| Vestas Wind Systems |
| Siemens Gamesa Renewable Energy |
| TPI Composites |
| LM Wind Power |
| Nordex |
| Arcosa Wind Towers |
| NextEra Energy |
| Ørsted |
| Others |
Value Network & Pricing Analysis
Domestic content bonus credits under the Inflation Reduction Act gate qualified supply access and premium-tier pricing for turbine OEMs. Developers seeking maximum credit capture must source 40% domestic content, compressing qualified supplier pools and elevating pricing power for compliant manufacturers.
Pricing Analysis
Input-cost pass-through from rare earth magnet and steel forging inputs is compressing margins for direct-drive offshore platforms. Pricing stratifies across premium, standard, and economy tiers based on domestic content qualification and integrated service bundling. Cost compression in the standard tier is intensifying because of interconnection queue delays freezing capital deployment. Independent power producers exhibit highest price sensitivity, while regulated utilities prioritize credit-eligible supply over unit cost.
Supply Chain Analysis
UL and IEC certification requirements for grid-synchronous power electronics gate qualified supplier participation in utility procurement. Manufacturing concentrates in the United States, Denmark, and Spain for nacelle assembly and blade fabrication. Supply chains draw from Chinese rare earth processing, German precision gearing, and domestic steel forging. Tariff exposure on magnet inputs creates single-source vulnerability for offshore direct-drive specifications. Distribution runs through OEM-direct contracting with integrated 15-20 year service packages displacing equipment-only transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America wind power equipment market functions as a geographic-arbitrage play between US Gulf Coast assembly costs and Atlantic seaboard port infrastructure premiums. The Inflation Reduction Act's domestic content thresholds create a regulatory wedge favoring South Carolina and Texas manufacturing over imported alternatives.
For Market Incumbents: Deepen captive blade and tower forging capacity to defend against emerging Chinese OEM entrants qualifying US-based facilities. Anchor nacelle assembly in South Carolina and Florida to maximize domestic content credit capture. Lock in 20-year service extensions at financial close to freeze out equipment-only competitors. For New Entrants and Emerging Players: Floating foundation engineering expertise offers a technology-first wedge into California and Maine lease areas previously uneconomical at water depths exceeding 60 meters. Target hybrid storage integration as the most penetrable procurement specification, bundling battery co-location with turbine supply to capture ERCOT and CAISO capacity market premiums. For Investors and Strategic Acquirers: Roll-up economics work for specialized offshore logistics providers because Jones Act vessel scarcity creates captive demand for US-flagged heavy-lift capacity. Acquire platform-agnostic service firms with Gulf Coast port access. Watch federal lease auction timing as the inflection indicator for equipment procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Content Compliance Investment | South Carolina nacelle facilities expand to integrate previously imported subcomponents under IRA thresholds. |
| Floating Foundation Port Infrastructure | Louisiana heavy-lift terminals attract OEM staging investments ahead of Atlantic lease auctions. |
| Integrated Service Package Extension | Texas utility-scale projects lead 15-20 year turbine-service bundling to lock operational cost predictability. |
| Direct-Drive Platform Specialization | Gearbox elimination reduces maintenance vessel requirements for remote maritime installations off California. |
| Hybrid Storage Co-Location Engineering | Battery pairing captures capacity market premiums under ERCOT and CAISO procurement specifications. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market. The research combines structured interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators with secondary validation from EIA data, FERC filings, IEA reports, and project development databases. Bottom-up equipment procurement tracking triangulates against top-down generation capacity forecasts.
Granularity-level modeling captures technology segmentation at the turbine configuration level, installation type at the project scale tier, and end-user archetype at the counterparty credit quality dimension. CAGRs derive from equipment manufacturing lead time analysis against transmission buildout commitments. Forecast inputs include interconnection queue administration patterns, domestic content qualification timelines, and port infrastructure readiness assessments.
The model holds under stable IRA credit policy and Jones Act enforcement; deviation in tariff regimes or rare earth export licensing would shift manufacturing location decisions. Forecasts reflect assumptions on lease auction sequencing, FAA height exemption processing timelines, and avian impact mitigation protocol consistency. A model refresh is warranted upon material change in federal offshore wind lease schedules or domestic content threshold adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Turbine Forged Tower Flange Market
Wind Energy Systems
United States Wind Energy Market
Wind Energy Systems
Global Small Wind Power Market
Wind Energy Systems
Wind Turbine Pitch and Yaw Control System Market
Wind Energy Systems
Italy Wind Energy Market
Wind Energy Systems
Global Wind Power Equipment Market
Wind Energy Systems
Medium-Speed Permanent Magnet Wind Turbine Generator System Market
Wind Energy Systems
Wind Turbine Shaft Market
Wind Energy Systems
Taiwan Wind Energy Market
Wind Energy Systems
Asia-Pacific Wind Power Market
Wind Energy Systems
Europe Wind Power Market
Wind Energy Systems
Wind Turbine Gearbox Market
Wind Energy Systems
Small Scale Single and Multi-Rotor Wind Turbine Market
Wind Energy Systems
Wind Energy Rescue System Market
Wind Energy Systems
Denmark Wind Energy Market
Wind Energy Systems
Wind Turbine Pitch Systems Market