
 Wind Turbine Drivetrain Market | 2026-2036
Wind Turbine Drivetrain Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Drivetrain Market Analytics
A shortage of certified drivetrain technicians and gearbox metallurgists is redrawing where manufacturing capacity can expand. Siemens Gamesa Renewable Energy leverages its European service footprint to sustain long-term maintenance contracts. GE Vernova anchors North American supply through vertically integrated nacelle assembly. Vestas Wind Systems A/S dominates aftermarket parts logistics across multiple continents.
A wind turbine drivetrain transmits mechanical torque from the rotor hub to the electrical generator, typically operating at input speeds below 20 RPM and output speeds exceeding 1,500 RPM through planetary or parallel shaft gearing stages, with direct drive systems eliminating the gearbox entirely by using annular generators. The primary purpose is to convert variable aerodynamic energy into grid-synchronous electrical power while managing torque spikes, fatigue loads, and drivetrain damping across decades of operation. Gearbox configurations retain cost advantages in onshore applications where weight constraints relax, while direct drive systems capture margin pools in offshore settings where reliability premiums outweigh capital intensity. Hybrid systems are gaining traction as OEMs balance the efficiency of geared stages against the maintenance simplicity of permanent-magnet generators.
The EU Green Deal and F-Gas Regulation constrain hydraulic drivetrain cooling systems and refrigerant choices across European installations. China's GB standards and MIIT efficiency mandates shape nacelle import requirements and domestic procurement rules. Stakeholders must monitor how IEC 61400 design certification revisions and emerging national content requirements in the United States, India, and Brazil will alter supplier qualification timelines and factory location decisions.
Market Dynamics
Direct drive and hybrid drivetrain architectures are compressing the addressable market for conventional multi-stage gearboxes as offshore wind farm developers prioritize reliability premiums over capital efficiency. This technology rotation redistributes manufacturing value toward permanent-magnet supply chains and away from precision-forged gearing capacity concentrated in traditional industrial clusters.
Growth Catalysts
- EU Green Deal efficiency mandates:The European Commission's tightening recyclability requirements for nacelle components accelerate OEM redesign cycles toward modular drivetrain architectures that simplify end-of-life material recovery.
- China's coastal province clustering:Jiangsu and Guangdong provincial governments bundle grid connection priority with domestic content thresholds, concentrating assembly capacity near Shanghai and Shenzhen port infrastructure.
- Hybrid system technology maturation:The convergence of medium-speed permanent-magnet generators with single-stage epicyclic gearing captures efficiency gains from both direct drive and conventional geared approaches.
Market Restraints
- Rare earth magnet supply concentration:Dysprosium and neodymium processing capacity concentrates in China's Inner Mongolia and Jiangxi provinces, exposing generator manufacturers to export quota volatility and geopolitical friction.
- GB standards compliance costs:China's MIIT efficiency testing protocols for nacelle imports impose extended certification timelines that delay European and North American supplier market entry by 12-18 months.
- Subsea cable integration complexity:Offshore direct drive turbines require specialized high-voltage slip rings and transformer integration that eliminates the gearbox maintenance advantage in floating platform applications.
Strategic Opportunities
- India's offshore lease round expansion:The Ministry of New and Renewable Energy's 2024 seabed allocation framework creates first-mover positioning for drivetrain suppliers establishing Chennai and Mumbai service depots.
- F-Gas Regulation refrigerant transition:The European Union's phasedown of hydrofluorocarbon cooling systems forces hydraulic drivetrain redesign toward dielectric fluid or air-cooled thermal management, opening patent white space.
- Digital twin predictive maintenance convergence:Vibration sensor arrays and physics-based degradation models enable unbundled service contracts that separate drivetrain O&M from turbine OEM captive arrangements.
Industry Challenges
- Certified gearbox metallurgist scarcity:Case-hardening and planetary carrier fatigue analysis expertise concentrates among aging specialists in Denmark and Germany, constraining quality assurance capacity for new manufacturing entrants.
- IEC 61400-4 design certification timeline compression:Revised gearbox load measurement requirements extend type certification testing by 8-12 months, delaying project financing close for turbine platforms awaiting drivetrain qualification.
- Legacy SCADA integration friction:Retrofitting condition monitoring systems onto operating fleets requires protocol translation between proprietary OEM data architectures and independent service provider analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Drivetrain Market |
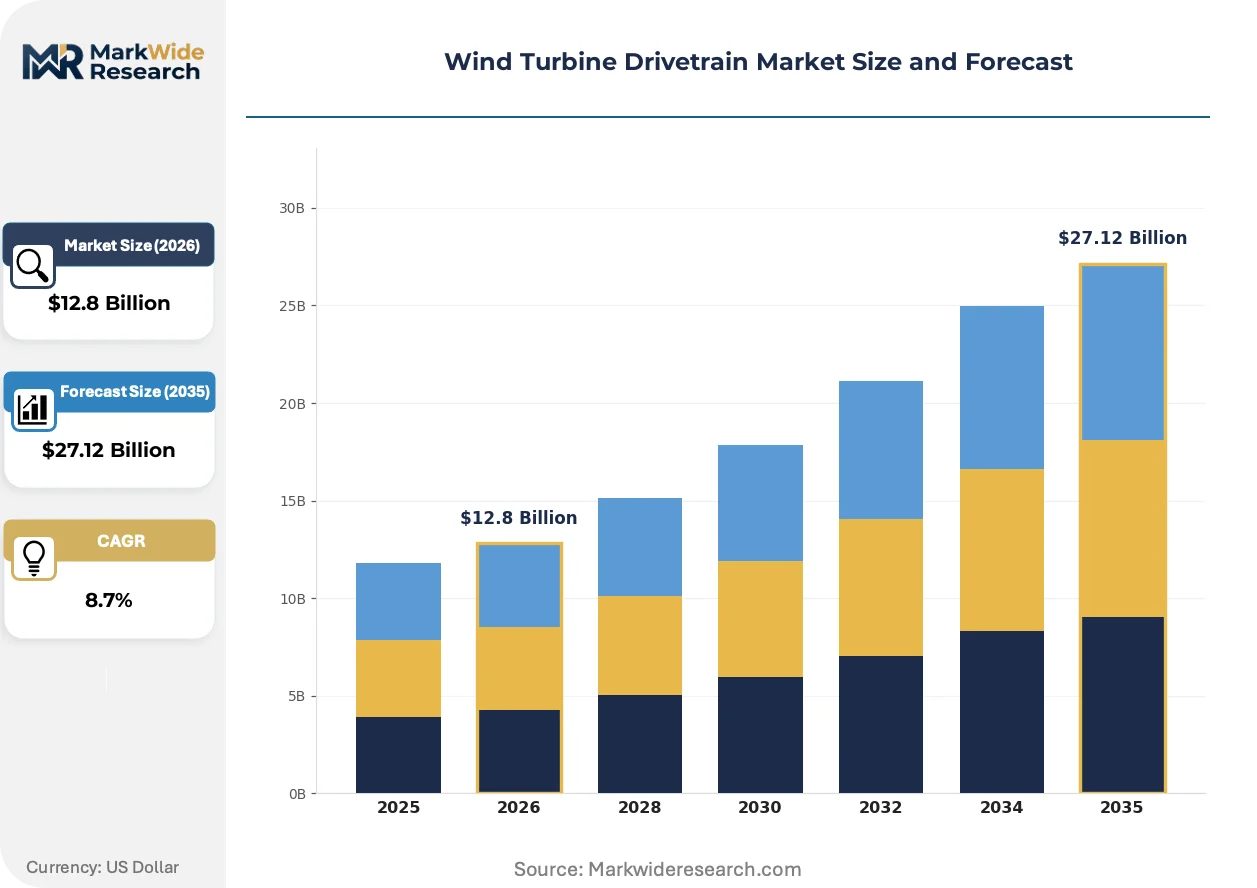
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gearbox, Direct Drive, Hybrid System, Control System Application: Onshore, Offshore, Small Scale, Large Scale End User: Utilities, Independent Power Producers, Government, Corporations Technology: Mechanical, Electrical, Hydraulic, Magnetic |
| Companies Covered | GE Vernova, Nordex SE, Vestas Wind Systems A/S, Envision Energy, Mingyang Smart Energy, Siemens Gamesa Renewable Energy, ENERCON GmbH, Dongfang Electric Corporation, Goldwind, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Drivetrain Market Evolving Landscape
Advanced materials and digitalization are restructuring how drivetrain performance is validated, financed, and maintained across the project lifecycle. These shifts compress traditional supplier hierarchies while elevating specialized component and software providers.
Permanent-magnet direct drive generators are fragmenting the conventional gearbox-dominated supply landscape by eliminating lubrication systems and high-speed bearings from offshore nacelle designs. Danish and German project developers now specify direct drive architectures for water depths exceeding 40 meters where maintenance vessel access is constrained. This technology rotation compresses addressable volume for precision gearing manufacturers while expanding generator winding and power electronics assembly capacity.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is forcing hydraulic cooling system redesign across European offshore installations. OEMs must substitute dielectric fluids or air-cooled architectures for traditional gearbox thermal management, extending engineering validation cycles by 6-9 months. German North Sea projects face the most acute compliance pressure given their concentration of 5-8 MW geared turbines commissioned under earlier cooling specifications.
Buyer consolidation among utility-scale offshore developers is compressing supplier negotiation leverage and fragmenting aftermarket service relationships. Ørsted, RWE, and Equinor now unbundle drivetrain maintenance from turbine OEM contracts, directly tendering gearbox overhaul and generator rewinding to specialized service providers. This disintermediation is most visible in the UK and Netherlands where operational fleets exceed 5 GW and independent service infrastructure achieves scale economics.
Wind Turbine Drivetrain Market Segmentation
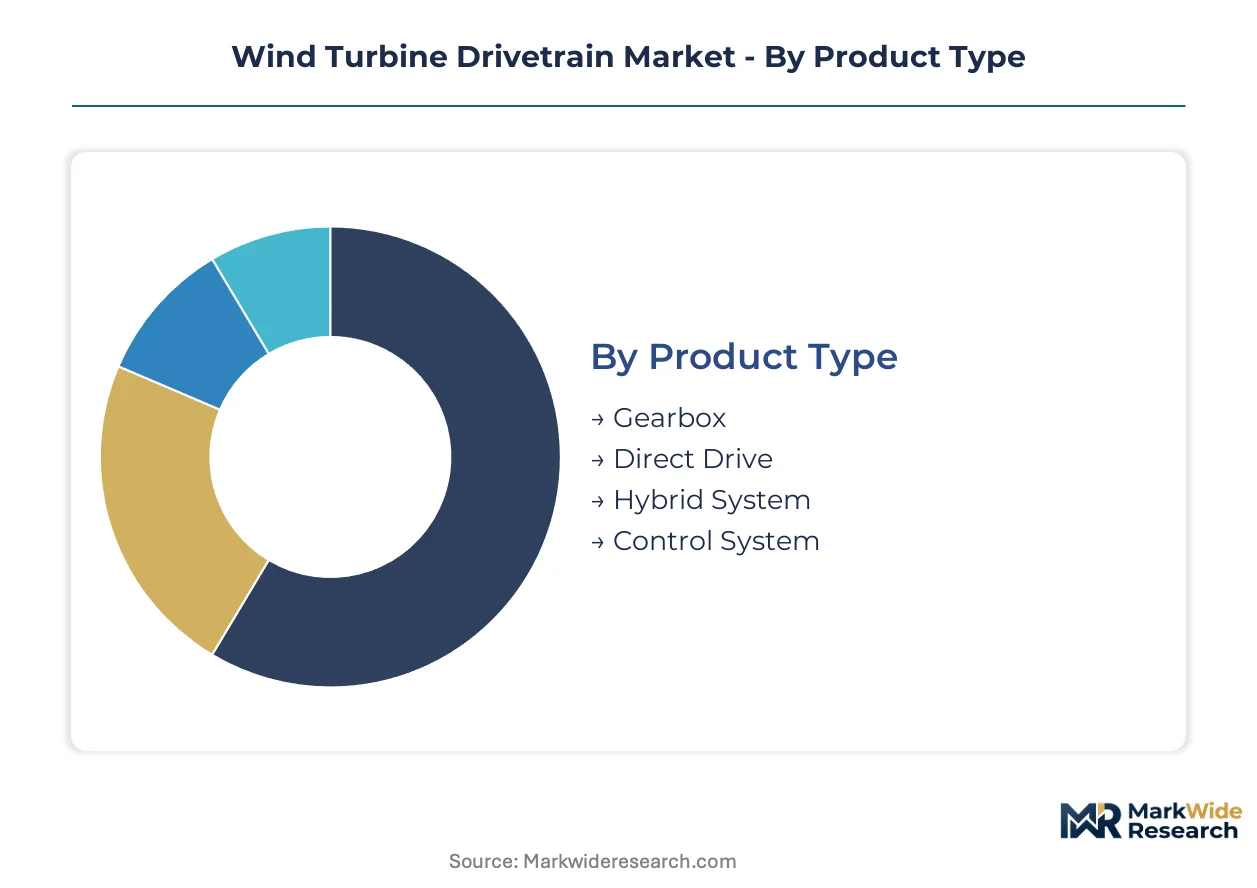
Drivetrain segmentation reveals how technology choices cascade through procurement, financing, and operational risk allocation. Product architecture and deployment setting together determine which suppliers capture margin and which face commoditization pressure.
Product Type:
Margin pools concentrate in architectures that reduce offshore maintenance exposure and simplify long-term service contracts.
- Direct Drive:Annular generators eliminate gearbox lubrication and high-speed bearing systems entirely. Water depths exceeding 40 meters in the Danish and German North Sea now mandate this architecture where vessel access windows narrow.
- Hybrid System:Single-stage epicyclic gearing paired with medium-speed permanent-magnet generators splits efficiency gains against reliability tradeoffs. China's Jiangsu province procurement specifications increasingly favor this configuration for coastal installations balancing capital efficiency with operational uptime.
- Gearbox:Multi-stage planetary and parallel shaft systems retain cost advantages where weight constraints relax.
- Control System:Power electronics and converter assemblies manage grid synchronization and variable load response.
The dominant share belongs to gearbox configurations, while hybrid systems are closing the gap fastest.
Application:
Deployment setting determines maintenance infrastructure requirements and financing risk premiums.
- Offshore:Subsea cable integration and floating platform dynamics impose specialized high-voltage slip ring and transformer requirements. UK and Netherlands operational fleets exceeding 5 GW now drive unbundled service contracts separating drivetrain maintenance from turbine OEM arrangements.
- Onshore:Ground-level crane access and established service road networks permit conventional geared architectures. Germany's inland wind corridors continue specifying multi-stage gearboxes where terrain and grid connection costs dominate project economics.
- Large Scale:Utility-scale procurement concentrates buyer leverage and compresses supplier margins.
- Small Scale:Distributed generation applications face distinct interconnection standards and permitting pathways.
Offshore applications command premium pricing, while onshore deployments maintain volume leadership.
End User:
Procurement sophistication varies sharply across buyer categories, shaping contract structures and aftermarket capture.
- Utilities:Vertically integrated grid operators deploy long-dated power purchase agreements that internalize drivetrain lifecycle costs. Ørsted, RWE, and Equinor now tender gearbox overhaul and generator rewinding directly to specialized service providers.
- Independent Power Producers:Project finance structures impose strict operation and maintenance reserve requirements that favor drivetrain architectures with predictable degradation curves.
- Corporations:Renewable energy certificate procurement and direct power purchase agreements drive demand for dispatchable generation profiles.
- Government:Public ownership models in China and select European markets concentrate procurement through state-owned grid enterprises.
Utilities capture the largest addressable spend, though independent power producers are expanding their procurement footprint most aggressively.
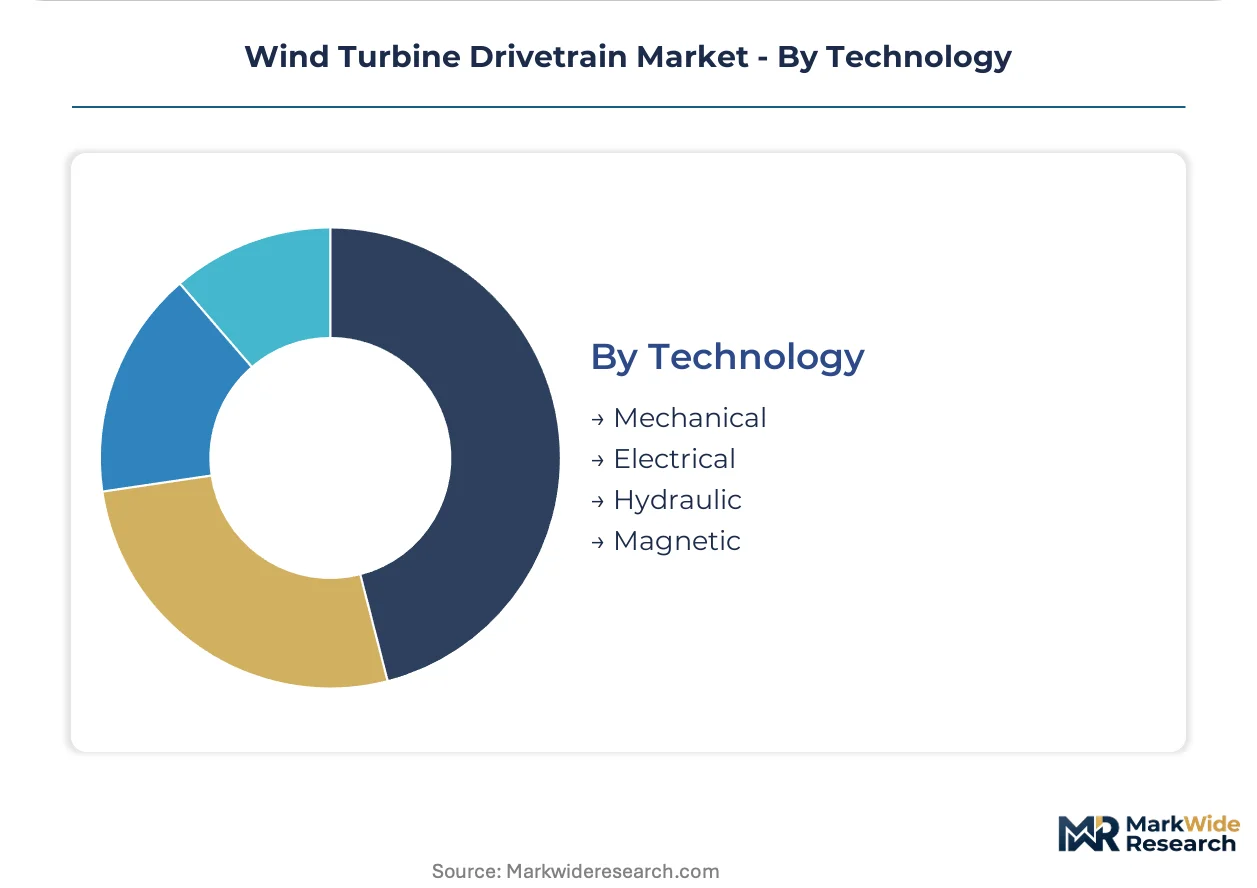
Technology:
Thermal management and torque transmission mechanisms determine regulatory exposure and materials sourcing risk.
- Magnetic:Permanent-magnet generators depend on dysprosium and neodymium supply chains concentrated in China's Inner Mongolia and Jiangxi provinces. The EU F-Gas Regulation's refrigerant phasedown accelerates magnetic system adoption as hydraulic cooling faces redesign pressure.
- Mechanical:Precision-forged gearing and case-hardened bearing races require specialized metallurgical expertise concentrated among aging specialists in Denmark and Germany.
- Electrical:Power electronics and converter assemblies manage variable frequency output to grid-synchronous power.
- Hydraulic:Traditional cooling and pitch control systems face extended engineering validation cycles as dielectric fluid substitutions replace hydrofluorocarbon refrigerants.
Magnetic technology is gaining share fastest in offshore specifications, while mechanical systems retain dominance in onshore installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT efficiency mandates and GB standards compliance protocols anchor procurement patterns across China's coastal manufacturing clusters. The EU Green Deal's recyclability requirements and F-Gas Regulation refrigerant phasedown reshape European offshore specifications. Project developers in the United States navigate FERC interconnection queues and domestic content thresholds under the Inflation Reduction Act.
China
Jiangsu and Guangdong provincial governments bundle grid connection priority with domestic content thresholds for offshore lease allocations. MIIT efficiency testing protocols for nacelle imports impose extended certification timelines that delay European supplier market entry. Assembly capacity concentrates near Shanghai and Shenzhen port infrastructure to serve coastal province clustering.
Germany
The North Sea basin spanning Denmark, Germany, and the Netherlands drives direct drive architecture specifications for water depths exceeding 40 meters. The EU F-Gas Regulation's hydrofluorocarbon phasedown forces hydraulic cooling system redesign across operational fleets. German North Sea projects face acute compliance pressure given their concentration of 5-8 MW geared turbines commissioned under earlier cooling specifications.
United States
The Inflation Reduction Act's domestic content bonuses and FERC interconnection queue reforms accelerate East Coast offshore lease development. GE Vernova anchors North American supply through vertically integrated nacelle assembly in northeastern manufacturing corridors. State renewable portfolio standards in California, New York, and Massachusetts tighten efficiency mandates for utility-scale procurement.
Denmark
Danish project developers now specify direct drive architectures for constrained maintenance vessel access windows in deeper North Sea waters. The EU Green Deal's tightening recyclability requirements accelerate OEM redesign cycles toward modular drivetrain architectures. Copenhagen and Aarhus host specialized gearbox metallurgist expertise concentrated among aging specialists in planetary carrier fatigue analysis.
India
The Ministry of New and Renewable Energy's 2024 seabed allocation framework creates first-mover positioning for drivetrain suppliers establishing Chennai and Mumbai service depots. Central Electricity Authority grid codes and state-level open access regulations shape interconnection standards for coastal wind corridors. Gujarat and Tamil Nadu concentrate early offshore development activity near existing port infrastructure.
Wind Turbine Drivetrain Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the drivetrain supply landscape. Vertically integrated turbine OEMs capture premium pricing in offshore specifications where reliability premiums outweigh capital intensity. Independent gearbox specialists and generator winding houses occupy mid-tier positions serving aftermarket overhaul demand. The dominant competitive moves involve unbundled service contract tenders that separate drivetrain O&M from turbine OEM captive arrangements, plus strategic partnerships for permanent-magnet supply chain security.
Among European-headquartered OEMs with integrated drivetrain capabilities, Siemens Gamesa Renewable Energy and Vestas Wind Systems A/S exemplify the vertically integrated archetype, while GE Vernova represents the North American integrated model. ENERCON GmbH occupies a distinct position as a German GmbH-structured specialist in direct drive generator architectures. These three entities anchor different geographic and technology vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| GE Vernova |
| Nordex SE |
| Vestas Wind Systems A/S |
| Envision Energy |
| Mingyang Smart Energy |
| Siemens Gamesa Renewable Energy |
| ENERCON GmbH |
| Dongfang Electric Corporation |
| Goldwind |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between offshore developers and drivetrain OEMs lock in rare earth magnet supply access while capping price volatility for permanent-magnet generators. These contracts bundle component procurement with service obligations across decades of turbine operation, compressing spot market exposure for critical inputs.
Pricing Analysis
North Sea basin projects command 15-25% premiums over Chinese coastal installations due to IEC 61400-4 certification requirements and specialized subsea cable integration. Three-tier pricing structure across premium, standard, and economy levels separates direct drive architectures from hybrid systems and conventional gearboxes. Cost compression in gearbox configurations is intensifying because buyer consolidation among utilities concentrates negotiation leverage. Independent power producers exhibit highest price sensitivity, while vertically integrated utilities absorb lifecycle premiums for reliability guarantees.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam trade lane elevate inbound logistics costs for European nacelle assembly operations. Rare earth processing concentrates in China's Inner Mongolia and Jiangxi provinces, precision forging capacity clusters in Germany and Denmark, and power electronics assembly localizes near Shenzhen and Shanghai. Dysprosium, neodymium, and specialized bearing steel constitute critical input dependencies. Single-source vulnerability in magnet supply chains exposes generator manufacturers to export quota volatility. Distribution runs through port-centric manufacturing clusters serving coastal wind corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technology rotation toward direct drive and hybrid architectures fragments incumbent supplier hierarchies, creating entry niches for specialized component providers and independent service operators.
For Market Incumbents: Shield permanent-magnet supply relationships through backward integration into rare earth processing partnerships or long-term offtake contracts with Chinese refiners. Deepen aftermarket capture by unbundling drivetrain maintenance from turbine OEM captive arrangements, responding to utility tender patterns in the UK and Netherlands. Prioritize IEC 61400-4 certification investment to compress qualification timelines against emerging competitors.
For New Entrants and Emerging Players: Independent gearbox overhaul capacity in the North Sea basin represents the most penetrable service-layer gap, as aging specialist metallurgists retire from Danish and German precision-forging clusters. Target Chennai and Mumbai depot establishment for India's offshore lease round positioning. Pursue direct utility contracting relationships that bypass turbine OEM intermediation, leveraging digital twin predictive maintenance capabilities as differentiation.
For Investors and Strategic Acquirers: Specialized generator winding houses with permanent-magnet expertise and established port-proximate facilities offer the strongest acquisition target archetype for portfolio exposure to offshore buildout. Long-term viability hinges on technology-agnostic service capabilities spanning direct drive, hybrid, and legacy gearbox architectures. Monitor F-Gas Regulation compliance timelines as inflection indicator for thermal management redesign demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Permanent-Magnet Supply Security Partnership | Long-term dysprosium and neodymium offtake agreements with Chinese processors reduce generator cost volatility. |
| Independent Service Depot Expansion | Chennai and Mumbai facility investments capture India's seabed allocation framework first-mover positioning. |
| Dielectric Fluid Thermal Management Transition | F-Gas Regulation compliance redesign opens patent white space for hydraulic drivetrain cooling substitution. |
| Digital Twin Predictive Maintenance Platform | Vibration sensor arrays and physics-based degradation models enable unbundled O&M contract capture from OEMs. |
| IEC 61400-4 Certification Acceleration | Compressed gearbox load measurement testing timelines reduce project financing delays for turbine platforms. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with nacelle OEM procurement directors, offshore project developers, gearbox metallurgists, and independent service operators; and secondary validation through IEC certification databases, MIIT efficiency testing protocols, EU Green Deal implementation documents, and customs trade records for rare earth magnet flows. Bottom-up segmentation modeling triangulated against top-down market sizing from installed capacity projections and drivetrain replacement cycles.
Across the analysis window, the forecast framework disaggregated volume and value by product architecture, deployment setting, and end-user procurement sophistication. CAGRs derived from technology penetration curves for direct drive adoption in offshore specifications, hybrid system maturation in Chinese coastal provinces, and gearbox retention in onshore corridors. Input assumptions incorporated GB standards compliance timelines, F-Gas Regulation phasedown schedules, and domestic content threshold evolution under the Inflation Reduction Act.
Forecasts assume regulatory continuity in EU Green Deal implementation, MIIT efficiency mandate enforcement, and IRA domestic content bonus structures; material policy shifts would require re-modeling. Rare earth export quota volatility, subsea cable integration complexity, and certified technician scarcity constitute specific risk factors that could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Mexico Power EPC Market
Power
Asia-Pacific Package Substation Market
Power
Smart PV Inverters Market
Power
Water Turbine Market
Power
Asia-Pacific Alternating Current (AC) Drive Market
Power
Temporary Load Bank Rental Market
Power
Canada Thermal Power Market
Power
High Voltage DC Power System Market
Power
Asia-Pacific Power Market
Power
North America Micro CHP Market
Power
Distributed Buoyancy Modules Market
Power
Russian Federation Power Market
Power
Power Purchase Agreement Market
Power
India Uninterruptible Power Supply (UPS) Market
Power
Japan Uninterrupted Power Supply (UPS) Market
Power
Modified Sine Wave Home Inverters Market