
 Chile Wind Energy Market | 2026-2036
Chile Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Wind Energy Market Outlook
Market Context
Chile's wind corridor from Biobío to Magallanes is fragmenting as developers target distinct resource profiles and grid access points. Enel Green Power Chile leverages its transmission partnerships to secure priority dispatch in the Sistema Interconectado Central. Acciona Energía anchors its position through integrated development across onshore sites with high capacity factors. Mainstream Renewable Power competes by specializing in hybrid wind-solar configurations that reduce intermittency penalties.
Technology and Segments
Chile wind energy encompasses the conversion of kinetic atmospheric energy into electrical power through turbine-generator systems, with modern installations typically operating at hub heights of 80-120 meters to capture stronger, more consistent wind streams above surface friction layers. The technology serves primarily to displace fossil generation in Chile's mining-dominated electricity demand profile and to satisfy corporate renewable energy procurement commitments. Onshore installations dominate current capacity, though the Above 10 MW turbine class is capturing developer attention as economies of scale intensify for utility-scale projects. Independent Power Producers represent the fastest-expanding end user category as merchant and contracted offtake structures proliferate beyond traditional utility procurement.
Regulatory Environment
Chile's Ministry of Energy and the National Electric Coordinator shape market access through transmission planning mandates and renewable dispatch prioritization rules under the country's decarbonization framework. The Superintendency of the Environment enforces environmental impact assessments that lengthen project timelines but standardize biodiversity mitigation practices across the Patagonian and Atacama zones. Stakeholders must monitor transmission queue reforms and carbon border adjustment preparations in key export markets to align project development with evolving commercial and compliance requirements.
Market Dynamics
Chile's wind energy sector is restructuring around transmission queue reforms that prioritize renewable dispatch, forcing developers to secure grid access before turbine procurement and reshaping capital allocation across the Atacama-to-Patagonia corridor.
Growth Catalysts
- Mining Electrification Mandates:Copper and lithium producers in Antofagasta and Tarapacá regions are procuring firm renewable supply contracts to displace diesel generation and meet Scope 3 commitments.
- Transmission Integration Priority:The National Electric Coordinator's renewable dispatch rules under Chile's decarbonization framework grant preferential grid access to wind projects with firming capacity or storage co-location.
- Corporate PPA Proliferation:Power purchase agreements from data centers, desalination plants, and industrial facilities in Coquimbo and Valparaíso are creating merchant offtake structures independent of regulated utility tariffs.
Market Restraints
- Grid Congestion in Northern Zones:The Sistema Interconectado Norte Grande faces saturation at substations serving Calama and Mejillones, delaying project energization regardless of generation readiness.
- Environmental Permitting Duration:The Superintendency of the Environment's biodiversity mitigation requirements for Patagonian steppe and Andean condor habitats extend development timelines by 18-36 months.
- Steel and Rare Earth Input Volatility:Turbine tower and permanent magnet supply chains concentrate in China, exposing Chilean developers to freight cost swings and export license uncertainty.
Strategic Opportunities
- Hybrid Wind-Solar Configurations:Complementary generation profiles in Atacama Desert sites allow shared transmission infrastructure and reduced firming costs versus standalone wind.
- Green Hydrogen Offtake Integration:Electrolyzer projects in Magallanes and Antofagasta are contracting baseload wind supply for ammonia and e-fuel export production.
- Distribution Network Deferral:Distributed wind installations below 10 MW in Biobío and Maule agricultural zones relieve rural substation loading and qualify for accelerated interconnection.
Industry Challenges
- Specialized Technician Scarcity:Blade repair, high-voltage terminations, and SCADA commissioning skills concentrate in Santiago, requiring relocation premiums for remote site staffing.
- Community Land-Use Negotiations:Indigenous consultation requirements under Chile's Indigenous Consultation Law for energy projects create procedural uncertainty and social license timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Wind Energy Market |
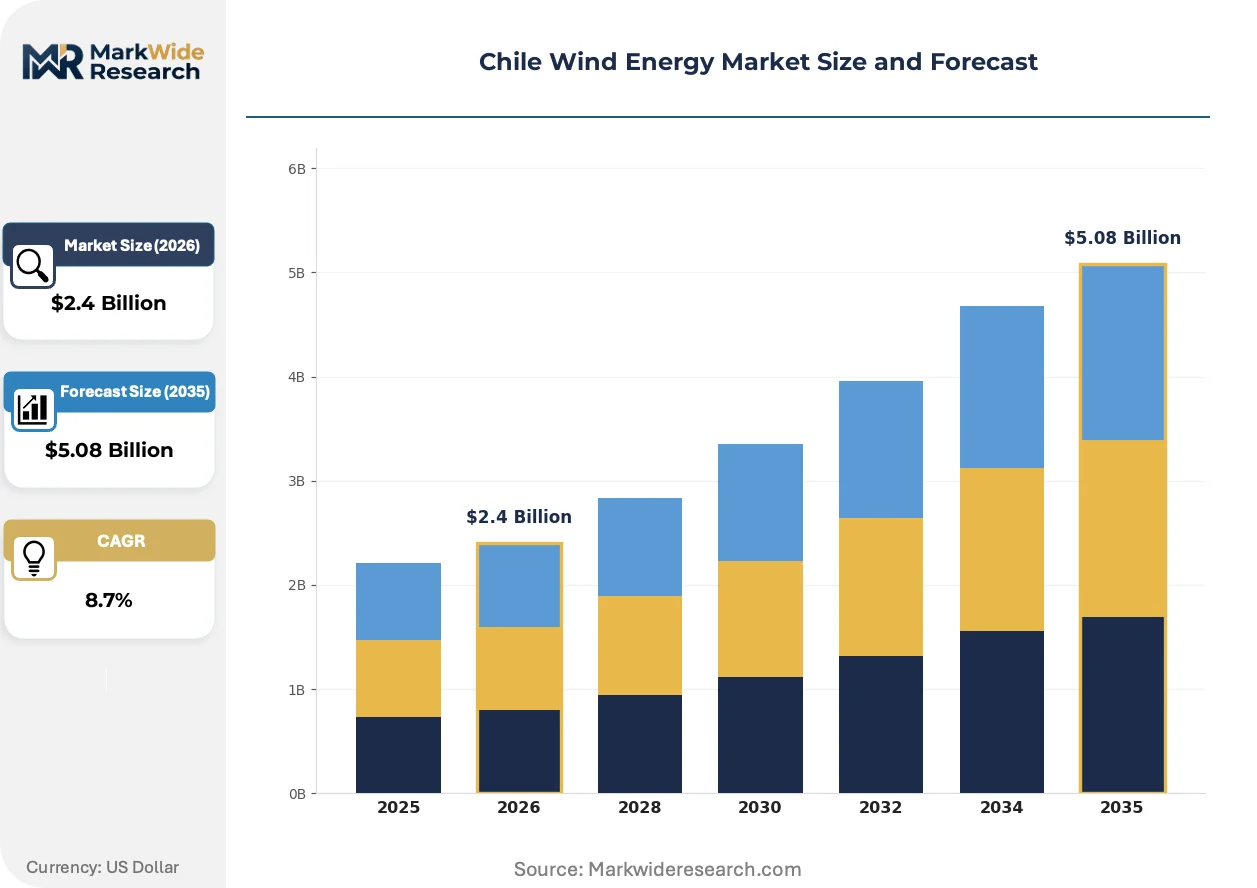
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Horizontal Axis, Vertical Axis, Offshore, Onshore End User: Utilities, Independent Power Producers, Corporates, Agriculture Installation: New Build, Retrofit, Replacement, Upgrade Capacity: Below 1 MW, 1-5 MW, 5-10 MW, Above 10 MW |
| Companies Covered | Acciona Energía, Repsol, Enel Green Power Chile, Ørsted, Goldwind, Colbún S.A., Mainstream Renewable Power, Électricité de France, AES Andes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Wind Energy Market Strategic Shifts
Digital infrastructure is compressing operational decision cycles across Chile's wind fleet, while regulatory pressure on grid stability accelerates technology convergence between generation and storage systems.
Advanced turbine control systems is virtualizing maintenance scheduling and performance optimization across Chile's growing fleet. Remote monitoring platforms aggregate vibration, thermal, and power curve data from turbines in the Atacama and Magallanes regions. Independent power producers and utility operators are adopting these systems to reduce unplanned outage duration and extend component life cycles.
Chile's Ministry of Energy has tightened grid code requirements for fault ride-through capability and frequency response, mandating that new wind installations demonstrate synthetic inertia provision or paired storage. This regulatory pressure is accelerating retrofit investments at operating facilities and biasing new procurement toward turbines with advanced power electronics. Developers in the Sistema Interconectado Central are responding by specifying full converter architectures and grid-forming inverters.
Long-term service agreements are unbundling from original equipment supply, with Chilean asset owners now contracting blade inspection, gearbox overhaul, and drivetrain replacement through third-party specialists. This disaggregation reduces capitalized maintenance reserves and transfers performance risk to service providers with regional execution capability. The trend is most visible among merchant wind farms in Coquimbo and Biobío that lack utility balance-sheet backing for captive service teams.
Chile Wind Energy Market Segmentation
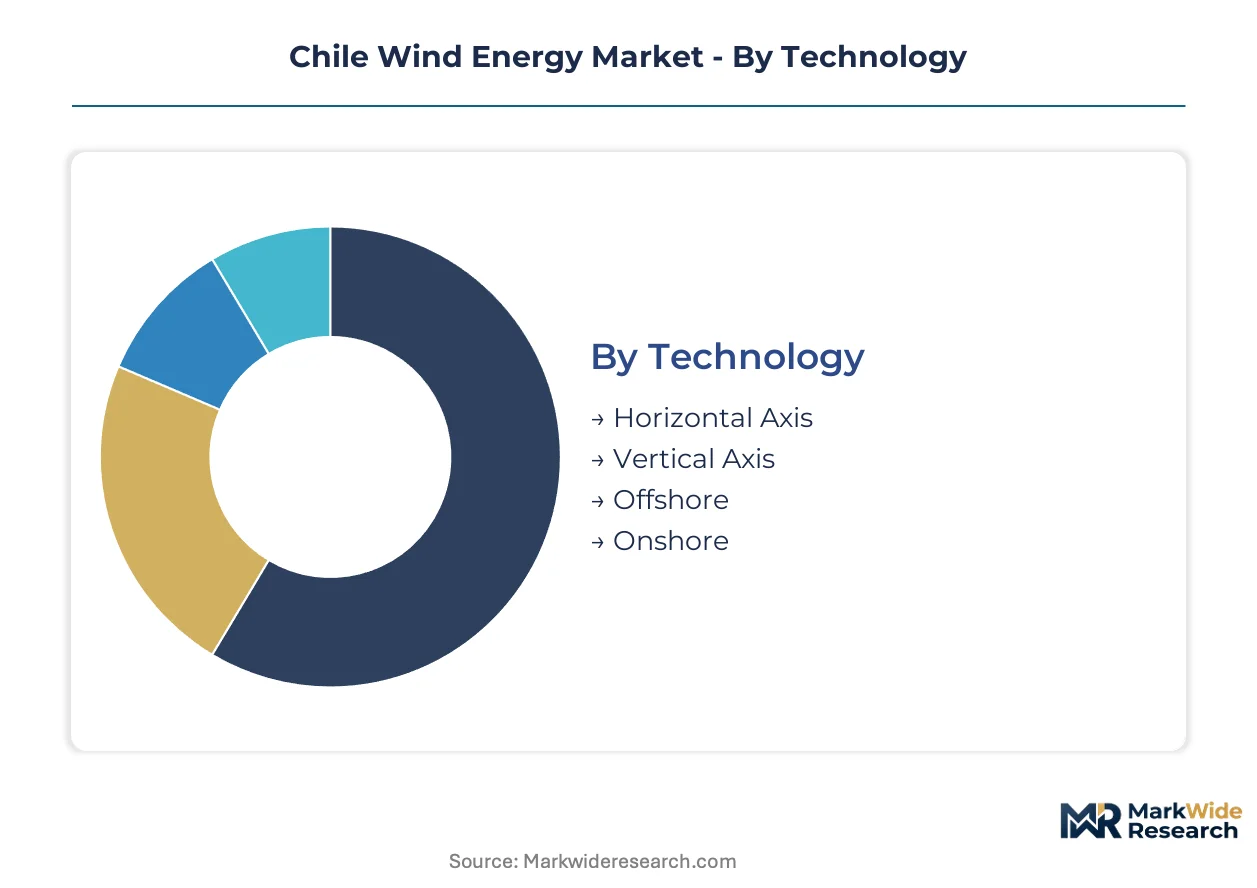
Chile's wind energy market fragments across four critical dimensions that determine project economics, grid integration requirements, and customer procurement patterns. Understanding these segment boundaries reveals how developers allocate capital between merchant and contracted revenue streams, and where technology choices align with specific resource zones.
Technology:
Horizontal axis turbines dominate utility-scale deployment, while vertical axis configurations serve niche distributed applications where maintenance access constraints favor simpler drivetrain architectures.
- Horizontal Axis:Three-blade upwind configurations with variable pitch control capture the strongest wind resources in Atacama and Magallanes corridors. Mining offtakers in Antofagasta specify these units for capacity factors exceeding 45 percent at 100-meter hub heights.
- Vertical Axis:Darrieus and Savonius designs operate effectively in turbulent wind regimes near agricultural installations in Maule and Biobío. Farmers select these systems for lower noise signatures and reduced bird strike risks near livestock operations.
- Offshore:Floating platform concepts are advancing through feasibility studies for deep-water sites off Valparaíso and Coquimbo. The Ministry of Energy's marine spatial planning process will determine lease auction timing.
- Onshore:Conventional tower-mounted installations represent the overwhelming majority of Chile's operating fleet, with projects concentrated in the Sistema Interconectado Central and Sistema Interconectado Norte Grande transmission zones.
The dominant share belongs to Horizontal Axis, while Offshore is closing the gap fastest through early-stage environmental permitting.
End User:
Customer type determines financing structures, with merchant exposure varying sharply between regulated utilities and corporate offtakers seeking renewable energy certificates.
- Utilities:State-controlled distributors and generation companies procure wind capacity through regulated auction mechanisms. Their procurement prioritizes firm capacity contributions and grid stability services over pure energy volume.
- Independent Power Producers:Merchant developers in Coquimbo and Valparaíso regions structure bilateral contracts with industrial customers. These entities are expanding most quickly as transmission queue reforms enable direct market access.
- Corporates:Copper miners and lithium producers in Tarapacá execute virtual and sleeved PPAs to meet Science Based Targets initiative commitments. Data centers in Santiago's suburbs represent emerging demand concentration.
- Agriculture:Grape producers and dairy operations in O'Higgins deploy sub-megawatt turbines to offset irrigation pumping loads. These installations qualify for simplified interconnection under distribution network deferral programs.
Independent Power Producers command the largest development pipeline, though Corporates are gaining share fastest through mining electrification mandates.
Installation:
Project lifecycle stage dictates equipment sourcing strategies and labor mobilization requirements across Chile's fragmented development timeline.
- New Build:Greenfield developments in Atacama Desert corridors require complete civil works, including access roads and substation construction. These projects face the longest environmental permitting durations.
- Retrofit:Repowering campaigns at aging wind farms in Biobío replace first-generation turbines with larger rotor diameters. Existing grid infrastructure reduces interconnection costs versus greenfield alternatives.
- Replacement:Component-level swaps of gearboxes and generators extend asset life at facilities approaching original design limits. Specialist contractors from Santiago execute these campaigns during low-wind seasons.
- Upgrade:Control system and blade extension modifications improve output at operating facilities without full turbine replacement. These investments respond to tightened grid code requirements for frequency response capability.
New Build absorbs the majority of capital deployment, while Retrofit is climbing the fastest as early projects reach repowering age.
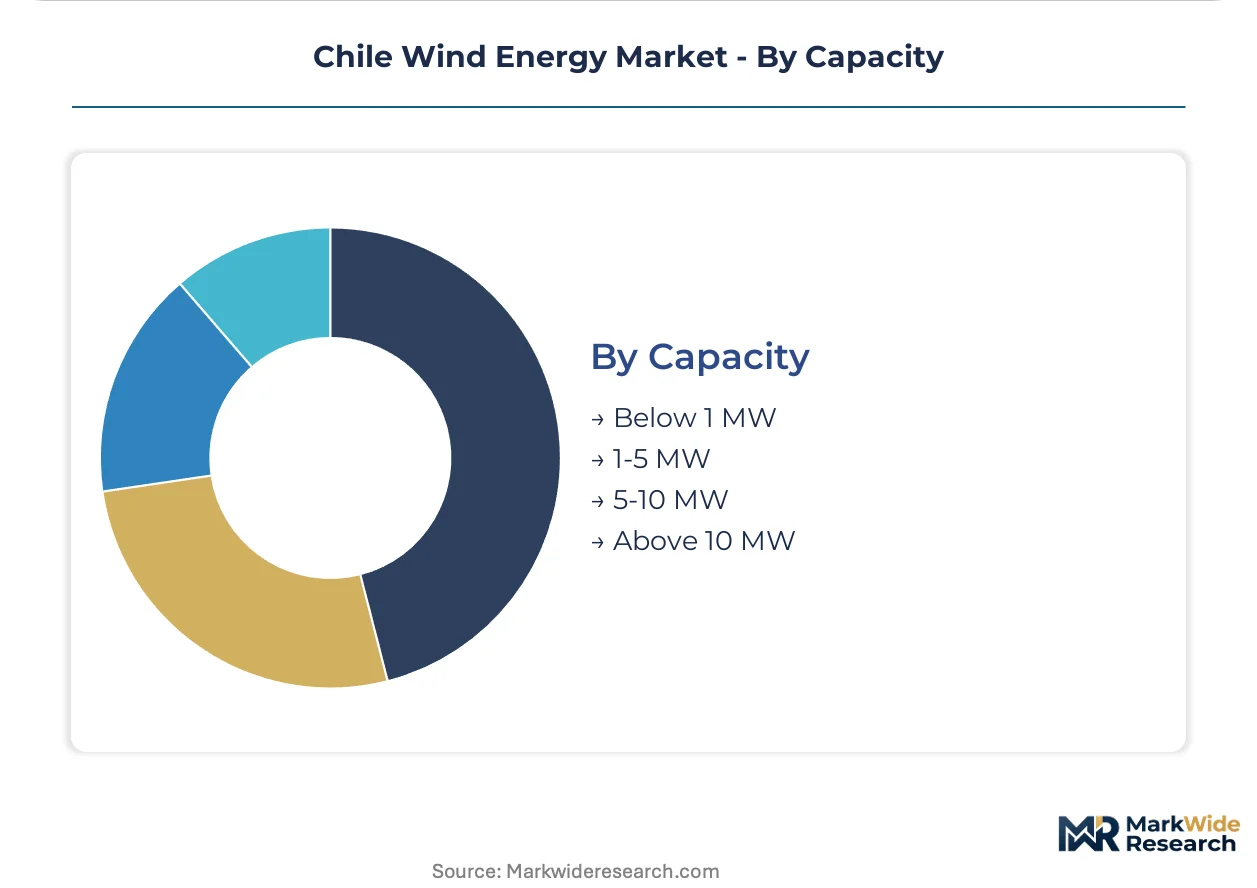
Capacity:
Turbine scale determines transmission voltage levels and maintenance contract structures, with Chile's grid code favoring larger units that can provide synthetic inertia services.
- Below 1 MW:Distributed units serve agricultural and rural industrial loads in Maule and O'Higgins. These installations bypass transmission queue congestion through distribution network connection.
- 1-5 MW:Mid-scale turbines populate hybrid wind-solar configurations in Atacama where shared infrastructure improves project returns. Developers specify these units for sites with moderate wind shear profiles.
- 5-10 MW:Large onshore machines are gaining share as hub heights increase to 140 meters and rotor diameters exceed 150 meters. These units optimize energy capture in Patagonian corridors with high wind variability.
- Above 10 MW:Next-generation turbines target the Sistema Interconectado Norte Grande where mining offtakers demand maximum unit output per interconnection point. These machines require specialized transport logistics through Andean passes.
Above 10 MW is capturing the steepest expansion trajectory, though 5-10 MW retains the largest installed base in current operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Sistema Interconectado Central transmission backbone underwrites Chile's wind corridor from Biobío to Magallanes, while the Sistema Interconectado Norte Grande unlocks Atacama Desert resources for mining electrification.
Atacama Desert Corridor
Copper and lithium producers in Antofagasta and Tarapacá regions execute firm renewable supply contracts to displace diesel generation. The National Electric Coordinator's renewable dispatch prioritization rules grant preferential grid access to projects with storage co-location. Calama and Mejillones industrial clusters concentrate electrolyzer projects contracting baseload wind for green hydrogen export production.
Magallanes Region
Patagonian wind resources with capacity factors exceeding 45 percent attract utility-scale developers targeting merchant export markets. The Superintendency of the Environment enforces biodiversity mitigation requirements for Andean condor habitats that extend timelines. Punta Arenas anchors port infrastructure for turbine component logistics through the Strait of Magellan.
Coquimbo and Valparaíso
Data centers and desalination plants in La Serena and Greater Valparaíso create corporate PPA demand independent of regulated utility tariffs. Distribution network deferral programs accelerate interconnection for distributed installations below 10 MW. The Ministry of Energy's marine spatial planning process advances floating offshore feasibility studies off Valparaíso.
Biobío and Maule
Agricultural operations in Concepción and Talca deploy sub-megawatt turbines to offset irrigation pumping loads through simplified interconnection pathways. Retrofit campaigns at aging wind farms replace first-generation turbines with larger rotor diameters. Existing grid infrastructure reduces interconnection costs versus greenfield alternatives in these central valley zones.
O'Higgins Region
Grape producers and dairy operations in Rancagua qualify for accelerated distribution network connection under rural deferral programs. The Indigenous Consultation Law creates procedural requirements for energy projects on Mapuche community lands. San Fernando clusters agricultural load centers where lower noise signature turbines reduce livestock disruption risks.
Chile Wind Energy Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying towers, blades, and power electronics to Chilean developers. The market structures around three distinct tiers: utility-affiliated generators with transmission partnerships, merchant independent power producers with corporate offtake expertise, and equipment suppliers capturing economies of scale in the Above 10 MW turbine class. Dominant competitive moves include strategic partnerships for grid access priority and portfolio diversification into hybrid wind-solar configurations.
Among European-headquartered renewable developers, Ørsted and Électricité de France exemplify the integrated platform archetype combining project development with long-term asset ownership. Mainstream Renewable Power occupies a position within the merchant specialist tier, structuring bilateral contracts with industrial customers across Coquimbo and Valparaíso. These three entities represent contrasting approaches to Chile's transmission queue reforms: utility-scale platform depth versus agile corporate PPA origination.
| Leading Market Players |
|---|
| Acciona Energía |
| Repsol |
| Enel Green Power Chile |
| Ørsted |
| Goldwind |
| Colbún S.A. |
| Mainstream Renewable Power |
| Électricité de France |
| AES Andes |
| Others |
Value Chain & Pricing Dynamics
The Strait of Magellan shipping corridor anchors turbine component logistics costs, concentrating supply-side leverage among developers with bonded warehouse arrangements in Punta Arenas and transmitting freight cost differentials into interconnection queue positioning across the Sistema Interconectado Central and Norte Grande zones.
Pricing Analysis
Volume-discount tiering structures separate Above 10 MW turbine procurement from sub-5 MW distributed installations, with mining offtakers in Antofagasta capturing scale premiums through multi-project master supply agreements while agricultural buyers in Maule face standard list pricing without term flexibility. Price differentiation hinges on hub height specifications and grid-forming inverter bundling, with integrated storage configurations commanding margin premiums over pure generation assets. Cost compression in the mid-scale 1-5 MW segment is intensifying because Chinese tower manufacturers are absorbing freight volatility to maintain Chilean market share. Corporate PPA offtakers exhibit lowest price sensitivity due to Science Based Targets initiative compliance premiums, while utility procurement through regulated auctions drives hardest bargain terms.
Supply Chain Analysis
Supplier-financing facilities from Chinese equipment manufacturers extend payment terms to 24 months for Chilean independent power producers, easing working capital constraints during construction phases but tethering project economics to yuan-denominated credit exposure. Manufacturing concentrates in China, Spain, and Denmark for nacelle assembly and blade fabrication, while permanent magnet supply draws from Chinese rare earth processing and Vietnamese magnet finishing facilities. Raw material dependencies span steel plate for towers, balsa and carbon fiber for blades, and copper winding for generators. Single-source vulnerability concentrates in permanent magnet supply chains subject to export license uncertainty. Distribution runs through Punta Arenas port infrastructure with overland trucking through Andean passes to Atacama sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
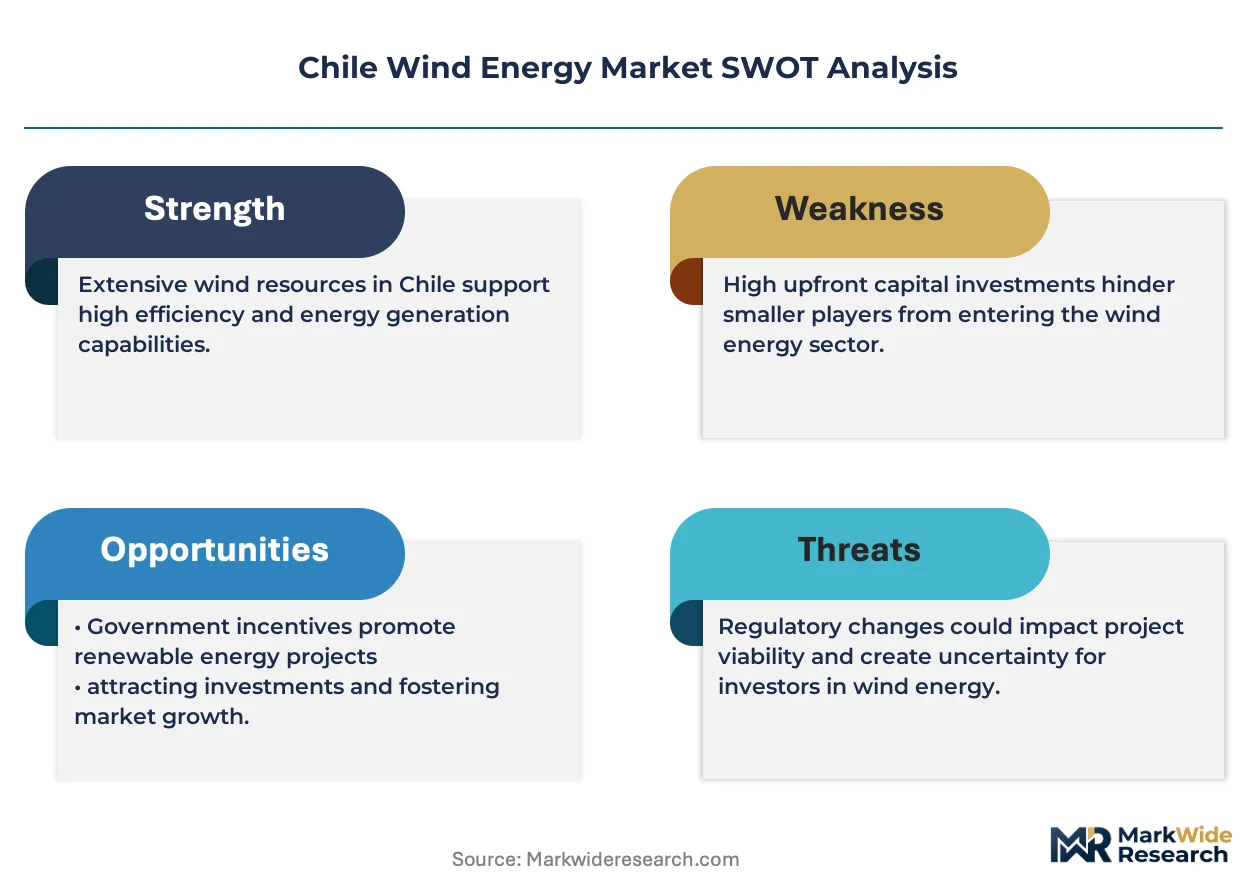
Chile's wind energy market functions as a defensive-moat arena where transmission queue priority operates as a network effect, entrenching early movers with secured grid access positions against latecomers facing interconnection delays regardless of technology cost competitiveness.
For Market Incumbents: Entrench queue positions by accelerating storage co-location investments that satisfy National Electric Coordinator renewable dispatch prioritization rules, while backward integration into O&M service capabilities captures recurring revenue streams as first-generation assets in Biobío reach repowering age. The threat of hybrid wind-solar configurations from merchant specialists like Mainstream Renewable Power demands response through portfolio diversification into complementary generation profiles. For New Entrants and Emerging Players: Pursue distributed installation opportunities below 10 MW in O'Higgins and Maule agricultural zones where simplified interconnection pathways bypass transmission queue congestion, and where grape producers and dairy operations seek irrigation load offset without utility tariff exposure. The most penetrable segment lies in corporate PPA origination for data centers and desalination plants in Coquimbo and Valparaíso, with go-to-market execution through direct bilateral contracting rather than regulated auction participation. For Investors and Strategic Acquirers: Merchant independent power producers with contracted offtake pipelines and secured environmental permits represent the priority acquisition archetype, offering cash flow visibility without utility balance sheet dependence. Long-term viability over the coming decade rests on electrolyzer offtake integration for green hydrogen export production. The signal to monitor is Ministry of Energy marine spatial planning progress for floating offshore lease auctions off Valparaíso and Coquimbo.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Wind-Solar Configuration | Complementary generation profiles in Atacama reduce firming costs and shared transmission infrastructure improves project returns. |
| Storage Co-location Investment | National Electric Coordinator dispatch prioritization rules grant preferential grid access to projects with paired battery systems. |
| Green Hydrogen Offtake Contracting | Electrolyzer projects in Magallanes and Antofagasta contract baseload wind supply for ammonia and e-fuel export production. |
| Retrofit Campaign Execution | Repowering aging Biobío wind farms with larger rotor diameters reduces interconnection costs versus greenfield alternatives. |
| Third-Party Service Unbundling | Independent blade inspection and gearbox overhaul contracts transfer performance risk to regional execution specialists. |
Study Parameters
A standing panel of utility planning officers, independent power producer project developers, EPC contractors, and National Electric Coordinator transmission planners provided ongoing calibration against secondary validation from EIA data, IEA renewable energy reports, Chilean Ministry of Energy regulatory filings, and project development database tracking. Primary interviews with grid operators and fuel supply specialists combined with customs records and SEC filings from listed equipment manufacturers enabled bottom-up installation tracking and top-down market sizing triangulation.
Scenario-bracketing framed demand projections across the analysis window, modeling capacity deployment by turbine scale tier, project lifecycle stage, end-user category, and regional grid type within the Sistema Interconectado Central and Norte Grande zones. CAGRs derived from regression analysis against mining electrification mandates, corporate PPA proliferation rates, and transmission queue reform implementation timelines. Industry-specific forecast inputs incorporated electrolyzer project announcements and marine spatial planning progress for floating offshore feasibility.
Sensitivities concentrate around transmission queue reform implementation pace, environmental permitting duration variability under Superintendency of the Environment protocols, and permanent magnet export license stability from Chinese suppliers. Forecasts reflect documented assumptions regarding mining sector electrification commitment durability and grid code requirement evolution. Macroeconomic deviation in copper and lithium pricing, regulatory shift in Indigenous Consultation Law enforcement, or technological breakthrough in floating offshore platform economics would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Offshore Wind Anchoring Market
Wind Energy Systems
Wind Turbine Pitch Systems Market
Wind Energy Systems
Offshore Wind Turbine Blade Leading-Edge Defect Inspection Equipment Market
Wind Energy Systems
Wind Power Market
Wind Energy Systems
Europe Direct Drive Wind Turbine Market
Wind Energy Systems
Wind Turbine Scrap Market
Wind Energy Systems
Wind Cones Market
Wind Energy Systems
Multi-Rotor Wind Turbine Market
Wind Energy Systems
Quiet Wind Turbine Market
Wind Energy Systems
Sweden Wind Energy Market
Wind Energy Systems
Offshore Wind Cable Market
Wind Energy Systems
Wind Turbine Market
Wind Energy Systems
Global Wind LIDAR Market
Wind Energy Systems
Wind Power Hubcap Market
Wind Energy Systems
Germany Wind Energy Market
Wind Energy Systems
Asia-Pacific Wind Power Equipment Market