
 Germany Renewable Energy Market | 2026-2036
Germany Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Renewable Energy Market Foresight
Industrial power procurement is broadening as German manufacturing clusters from chemicals to automotive seek long-term renewable supply contracts. RWE AG leverages its offshore wind pipeline in the North Sea to anchor utility-scale generation positions. Siemens Energy sustains turbine technology leadership through high-capacity onshore platforms. Nordex competes aggressively in the German wind repowering segment with next-generation rotor systems.
Germany renewable energy encompasses electricity and heat generation from solar radiation, wind kinetic energy, biomass combustion, hydropower flow, geothermal heat, and ocean tidal forces, typically converted through photovoltaic cells with module efficiencies exceeding 20 percent or horizontal-axis wind turbines with hub heights surpassing 150 meters to feed into the national 50 Hz alternating current grid. Photovoltaic installations dominate capacity additions across residential rooftops and agrivoltaic arrays, while offshore wind claims the deepest margin pools due to higher capacity factors and long-term power purchase agreements. Heat pump technology is expanding fastest in the application sector as building retrofits accelerate under federal efficiency mandates.
The Federal Network Agency (Bundesnetzagentur) administers auction mechanisms under the Renewable Energy Sources Act (EEG), while KBA certifies electric vehicle charging infrastructure that integrates with renewable supply, and the EU Green Deal's Fit for 55 framework tightens national emission budgets. These regulatory layers shape project finance timelines, equipment standards, and grid connection priorities across German states. Stakeholders must monitor auction price floors, hydrogen pipeline conversion timelines, and municipal permitting backlogs to align capital deployment with policy trajectories.
Market Dynamics
The EEG 2023 revision and the German Onshore Wind Act are compressing permitting timelines from years to months, fundamentally altering how capital deploys across photovoltaic and onshore wind project pipelines.
Growth Catalysts
- Industrial Power Purchase Agreements:Chemical and automotive manufacturing clusters in North Rhine-Westphalia and Lower Saxony are signing decade-long renewable supply contracts, anchoring project finance for new capacity.
- EEG Auction Mechanisms:The Federal Network Agency's competitive bidding rounds for solar and onshore wind are driving cost discovery and accelerating grid-parity project economics.
- Agrivoltaic Arrays:Dual-use solar installations on agricultural land in Brandenburg and Saxony-Anhalt are expanding deployable surface area without competing for dedicated solar zones.
Market Restraints
- Grid Connection Queues:Transmission system operators in northern Germany face backlogs for offshore wind hookups, delaying revenue recognition for North Sea projects.
- Polysilicon Supply Concentration:Module manufacturers depend on concentrated upstream refining capacity outside Europe, exposing project developers to input cost volatility and supply interruption risk.
- Heat Pump Retrofit Complexity:Building stock in older urban cores requires distribution system overhauls that technical installation crews struggle to execute at federal efficiency mandate pace.
Strategic Opportunities
- Hydrogen Pipeline Conversion:The SoutH2 corridor initiative to repurpose natural gas infrastructure for hydrogen transport opens offtake pathways for electrolyzer-linked offshore wind.
- Bavarian Solar-Plus-Storage:Residential and commercial hybrid installations in southern Germany remain underpenetrated relative to technical potential, offering white-space for integrated system providers.
- Wind Repowering:Aging turbine fleets in Schleswig-Holstein built in the 2000s now qualify for streamlined replacement permits under accelerated decommissioning rules.
Industry Challenges
- Skilled Technician Shortage:High-voltage cable installation and offshore maintenance operations lack certified personnel, constraining buildout velocity for North Sea arrays.
- Municipal Permitting Variance:Bavarian and Baden-Württemberg local authorities apply divergent aesthetic and noise standards, fragmenting project approval timelines despite federal streamlining.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Renewable Energy Market |
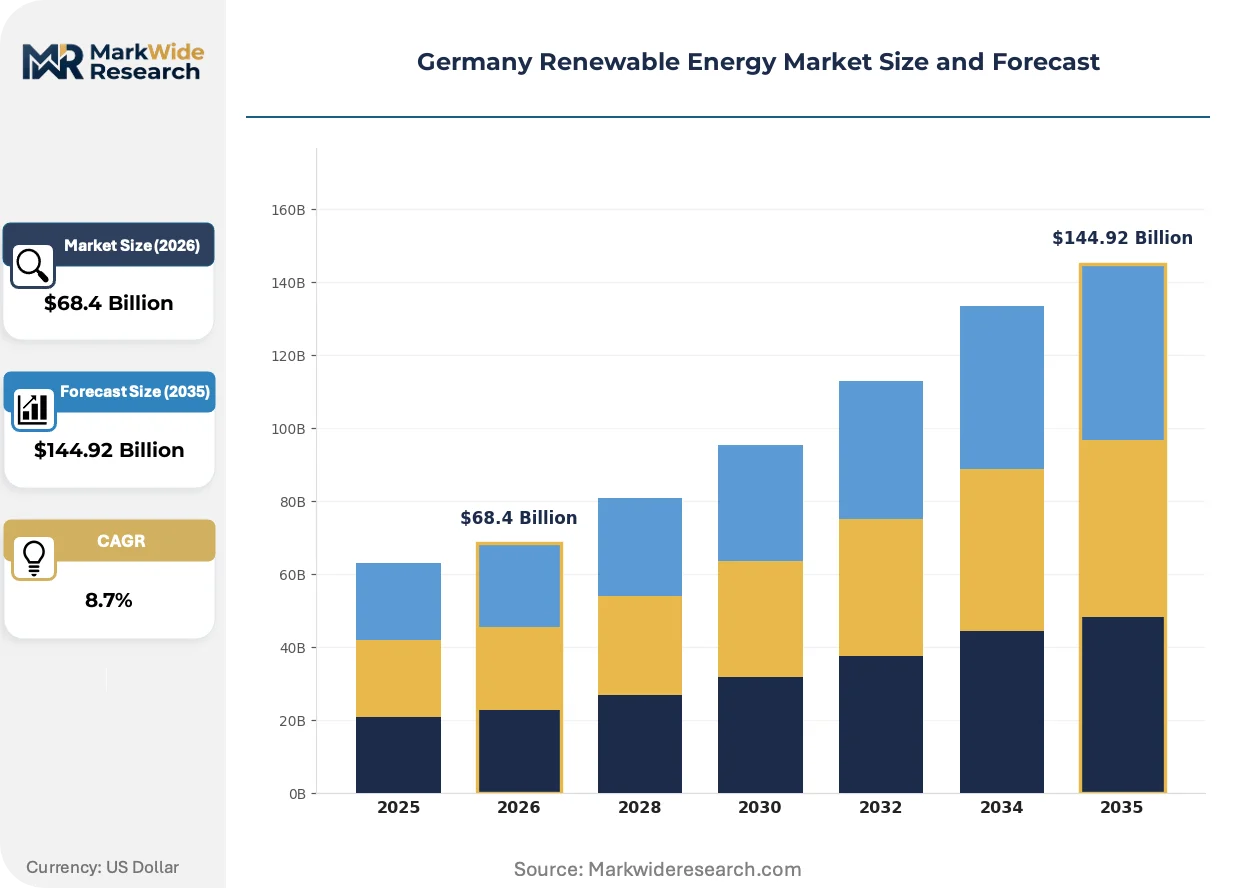
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Source: Solar, Wind, Biomass, Hydropower, Geothermal, Ocean Technology Type: Photovoltaic, Concentrated Solar Power, Onshore Wind, Offshore Wind, Anaerobic Digestion, Heat Pumps Application Sector: Residential, Commercial, Agricultural, Transportation, Public Infrastructure, Military End User: Utility Providers, Independent Power Producers, Municipal Corporations, Industrial Enterprises, Energy Cooperatives, Research Institutions |
| Companies Covered | RWE AG, EnBW Energie Baden-Württemberg AG, BayWa r.e. AG, ABO Energy, E.ON SE, Vattenfall GmbH, Ørsted A/S, Siemens Energy, Nordex, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Renewable Energy Market Shifts & Advancements
Technology convergence between generation assets and digital grid management is compressing the traditional separation between power production and system balancing services.
Agrivoltaic technology is electrifying rural land-use economics by enabling simultaneous crop cultivation and electricity generation. Farmers in Lower Saxony and Mecklenburg-Vorpommern are leasing acreage to energy developers at rates exceeding traditional agricultural returns. This dual-output model is electrifying capital allocation toward previously marginal land categories.
The EU Green Deal's Fit for 55 framework tightens national emission budgets and accelerates renewable deployment mandates across member states. German project developers must now align auction bidding strategies with hydrogen offtake timelines and industrial decarbonization contracts. Bavarian solar developers are responding by bundling generation assets with behind-the-meter storage to capture capacity market premiums.
Corporate buyers are consolidating renewable procurement through aggregated power purchase agreements rather than individual project contracts. Mid-sized manufacturers without balance-sheet scale for direct offtake are joining buyer consortia facilitated by energy advisory firms. This pooling behavior is most visible in Baden-Württemberg's automotive supplier cluster, where tier-two component producers seek supply security without bearing standalone project development risk.
Germany Renewable Energy Market Segmentation
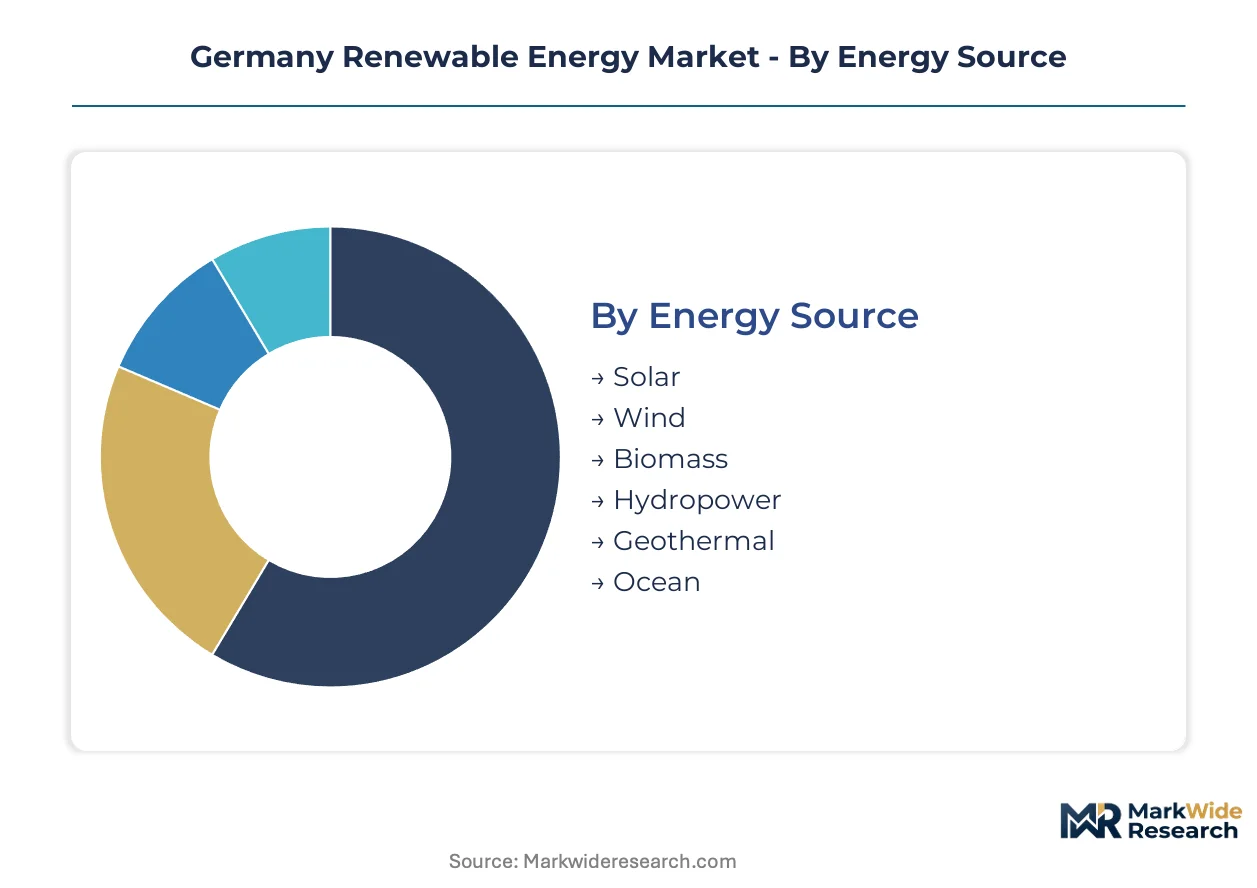
German renewable energy deployment fragments across generation technologies, application contexts, and procurement structures. Each segmentation axis reveals distinct capital deployment patterns, regulatory exposure profiles, and margin architectures that shape competitive positioning.
Energy Source:
Standardization dominates solar and wind through mature equipment supply chains, while biomass and geothermal retain customization requirements for site-specific feedstock or reservoir conditions.
- Solar:Photovoltaic cells with module efficiencies exceeding 20 percent anchor residential rooftop and agrivoltaic arrays across Brandenburg and Saxony-Anhalt. Bavarian commercial installations are bundling generation with behind-the-meter storage to capture capacity market premiums under federal efficiency mandates.
- Wind:Horizontal-axis turbines with hub heights surpassing 150 meters feed into the national 50 Hz grid. North Sea offshore arrays claim the deepest margin pools due to higher capacity factors and long-term power purchase agreements with industrial offtakers in Lower Saxony.
- Biomass:Combustion and anaerobic digestion systems process agricultural residues and organic waste streams. Rural energy cooperatives in Mecklenburg-Vorpommern operate distributed biogas plants under EEG feed-in tariff structures.
- Hydropower:Run-of-river installations in Alpine regions of Bavaria and Baden-Württemberg provide dispatchable baseload capacity.
- Geothermal:Deep drilling projects in the Upper Rhine Graben extract thermal energy for district heating networks.
- Ocean:Tidal and wave energy pilots in the North Sea remain pre-commercial with limited grid connection pathways.
Leading the category by volume: Solar. Growing fastest: Wind.
Technology Type:
Cost tier separation differentiates mass-deployable photovoltaic modules from specialized concentrated solar and offshore wind platforms requiring bespoke foundation engineering.
- Photovoltaic:Silicon-based panels dominate capacity additions through standardized manufacturing at scale. Residential installations across Germany exceed commercial ground-mount economics when factoring in avoided grid fees.
- Concentrated Solar Power:Mirror-based thermal generation with molten salt storage addresses industrial process heat demand. Technical potential concentrates in southern states with higher direct normal irradiance.
- Onshore Wind:High-capacity turbine platforms from Siemens Energy and Nordex compete in repowering aging fleets. Accelerated permitting under the German Onshore Wind Act compresses project timelines from years to months.
- Offshore Wind:Fixed-bottom and floating foundations in the North Sea require specialized installation vessels. RWE AG leverages pipeline depth to anchor utility-scale generation positions.
- Anaerobic Digestion:Biogas upgrading to biomethane integrates with existing natural gas infrastructure. Agricultural feedstock supply chains in Lower Saxony sustain plant economics.
- Heat Pumps:Building retrofit mandates in older urban cores drive fastest application sector expansion. Technical installation crews struggle to execute distribution system overhauls at federal efficiency mandate pace.
Photovoltaic claims the largest installed base. Heat pumps are climbing the fastest.
Application Sector:
Customer type fragmentation spans regulated utilities, unregulated independent power producers, municipal entities, and industrial self-consumers with divergent risk appetites and contracting structures.
- Residential:Rooftop solar-plus-storage hybrids in Bavaria and Baden-Württemberg remain underpenetrated relative to technical potential. Federal subsidies through KfW development bank reduce capital barriers.
- Commercial:Mid-sized manufacturers without balance-sheet scale for direct offtake join buyer consortia. Aggregated power purchase agreements pool demand across Baden-Württemberg's automotive supplier cluster.
- Agricultural:Agrivoltaic dual-use installations enable simultaneous crop cultivation and electricity generation. Farmers in Lower Saxony lease acreage to energy developers at rates exceeding traditional agricultural returns.
- Transportation:Electric vehicle charging infrastructure certified by KBA integrates with renewable supply. Grid connection priorities favor high-utilization corridors.
- Public Infrastructure:Municipal corporations procure renewable capacity through EEG auction mechanisms administered by the Federal Network Agency.
- Military:Bundeswehr installations seek supply security through behind-the-meter generation and islanding capability.
Commercial applications lead by project count. Agricultural deployment is gaining share fastest.
End User:
Procurement authority concentration varies from centralized utility procurement to fragmented cooperative ownership structures with divergent governance and investment horizons.
- Utility Providers:Transmission system operators manage grid connection queues for offshore wind hookups in northern Germany. Revenue recognition delays constrain North Sea project finance.
- Independent Power Producers:Unregulated developers bid into Federal Network Agency auctions for solar and onshore wind capacity. Cost discovery drives grid-parity project economics.
- Municipal Corporations:Stadtwerke combine generation ownership with distribution network operation. Local permitting backlogs fragment approval timelines despite federal streamlining.
- Industrial Enterprises:Chemical and automotive manufacturing clusters in North Rhine-Westphalia sign decade-long renewable supply contracts. Project finance for new capacity anchors on these offtake commitments.
- Energy Cooperatives:Citizen-owned projects in Schleswig-Holstein repower aging turbine fleets under streamlined replacement permits. Democratic governance structures extend investment decision timelines.
- Research Institutions:Fraunhofer and university laboratories pilot electrolyzer-linked offshore wind for hydrogen production. SoutH2 corridor initiative opens offtake pathways for converted natural gas infrastructure.
Utility providers hold the largest contracted capacity. Industrial enterprises are expanding procurement most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Renewable generation capacity concentrates in northern coastal states while consumption demand pulls from southern industrial corridors, creating transmission investment imperatives across the German grid.
North Rhine-Westphalia
Chemical manufacturing clusters in the Ruhr region anchor industrial power purchase agreements for offshore wind supply. The EEG 2023 auction mechanisms administered by the Federal Network Agency accelerate project finance timelines for new capacity. RWE AG leverages its generation portfolio to serve long-term offtake contracts with BASF and Bayer facilities in Leverkusen and Ludwigshafen.
Lower Saxony
Automotive supplier networks and Volkswagen's Wolfsburg headquarters drive renewable procurement through aggregated buyer consortia. The German Onshore Wind Act streamlines permitting for repowering aging turbine fleets in the Emsland region. Agrivoltaic dual-use installations expand across agricultural acreage in Oldenburg and Göttingen districts at lease rates exceeding traditional crop returns.
Bavaria
Residential solar-plus-storage hybrids remain underpenetrated relative to technical potential across Munich and Nuremberg metropolitan areas. KfW development bank subsidies reduce capital barriers for distributed generation adoption. Municipal permitting variance fragments approval timelines despite federal streamlining, with local authorities applying divergent aesthetic standards to rooftop installations.
Baden-Württemberg
Premium automotive manufacturers and tier-two component producers seek supply security through corporate renewable procurement. The EU Green Deal's Fit for 55 framework tightens emission budgets for industrial facilities in Stuttgart and Karlsruhe. Siemens Energy sustains turbine technology leadership through high-capacity onshore platforms serving repowering demand in the Black Forest region.
Schleswig-Holstein
Offshore wind pipeline development in the North Sea claims the deepest margin pools due to higher capacity factors. Grid connection queues at transmission system operators delay revenue recognition for projects in the Heligoland Bight. Citizen-owned energy cooperatives repower aging turbine fleets built in the 2000s under streamlined replacement permits.
Germany Renewable Energy Market Competitive Landscape
Top-tier vendors anchor utility-scale generation and turbine manufacturing, while mid-tier developers and regional installers compete on project origination speed and local permitting relationships. The market structure stratifies across integrated energy majors, specialized renewable developers, and equipment manufacturers with divergent margin architectures. Strategic archetypes include offshore wind pipeline holders, onshore repowering specialists, and solar-plus-storage system integrators. Competitive moves concentrate on auction bidding discipline and strategic partnerships for hydrogen offtake pathways.
Among Germany-based integrated utilities, RWE AG and E.ON SE occupy positions spanning generation ownership, grid operation, and retail supply. Siemens Energy and Nordex exemplify equipment manufacturing archetypes with distinct technology focus areas. Ørsted A/S represents the offshore wind pure-play model with North Sea development expertise. These named entities anchor industry-level competitive dynamics without implying specific strategic actions or market share positions.
| Leading Market Players |
|---|
| RWE AG |
| EnBW Energie Baden-Württemberg AG |
| BayWa r.e. AG |
| ABO Energy |
| E.ON SE |
| Vattenfall GmbH |
| Ørsted A/S |
| Siemens Energy |
| Nordex |
| Others |
Supply & Pricing Matrix
Polysilicon refining costs cascade through photovoltaic module pricing tiers, with upstream concentration in China feeding into German project developers facing contract-based long-term offtake negotiations against volatile spot market alternatives.
Pricing Analysis
Cost-down pressure on utility-scale solar accelerates because polysilicon supply bottlenecks compress developer margins while industrial offtakers in North Rhine-Westphalia lock in decade-long power purchase agreements at fixed rates. Three-tier pricing structure across premium certified, standard utility-grade, and economy residential modules differentiates by IEC certification level and after-sales warranty bundling. Municipal corporations exhibit highest price sensitivity due to budget constraint transparency, while automotive clusters in Baden-Württemberg prioritize supply security over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from German transmission system operators require module manufacturers to qualify polysilicon suppliers across China, Germany, and Norway to mitigate single-source vulnerability. Upstream ingot and wafer production draws from concentrated Asian refining capacity, while inverter and mounting hardware rest on European fabrication networks. Tariff exposure on Chinese photovoltaic components threatens project economics. Distribution runs through EPC contractors bundling engineering, procurement, and construction services for utility-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
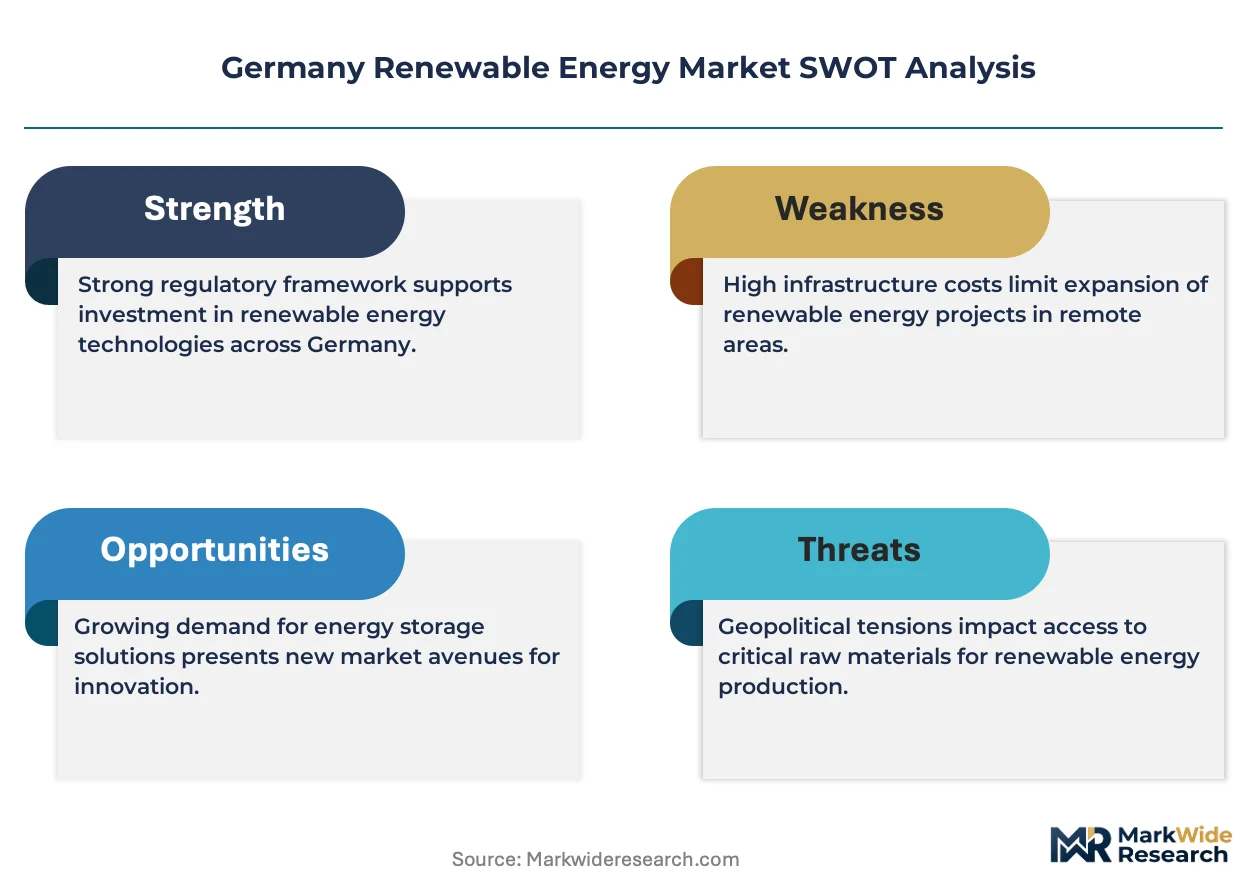
The EEG 2023 revision erects a cost-of-compliance barrier that favors developers with established Bundenetzagentur auction bidding expertise and streamlined permitting capabilities, locking out undercapitalized entrants.
For Market Incumbents: Hedge against polysilicon price volatility through backward integration into European wafer sourcing or long-term supply contracts with Norwegian metallurgical-grade silicon producers. Reinforce grid connection queue positions at northern transmission system operators to defend revenue recognition timelines against emerging offshore wind pure-plays. Prioritize electrolyzer-linked project pipelines for hydrogen offtake through SoutH2 corridor participation. For New Entrants and Emerging Players: Launch via agrivoltaic development partnerships in Brandenburg and Saxony-Anhalt, where dual-use land economics face lower municipal permitting variance than rooftop solar in Bavaria. Target residential solar-plus-storage hybrids in southern Germany as the most penetrable white-space segment. Pursue aggregated power purchase agreement consortia for mid-sized automotive suppliers lacking standalone balance-sheet scale. For Investors and Strategic Acquirers: Federal Network Agency auction clearance rates below reserve price floors are the leading indicator that capital deployment discipline is tightening and distressed asset opportunities will emerge. Frame long-term viability around hydrogen pipeline conversion timelines and industrial decarbonization contract anchoring. Monitor skilled technician certification bottlenecks as the signal for buildout velocity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Offshore Wind Capacity Buildout | RWE AG leverages North Sea pipeline depth to anchor utility-scale generation positions for industrial offtakers. |
| Power Purchase Agreement Expansion | Chemical clusters in North Rhine-Westphalia sign decade-long contracts that compress project finance risk premiums. |
| Technology Licensing Partnership | Siemens Energy sustains turbine leadership through high-capacity platform deployments in Black Forest repowering zones. |
| Vertical Integration into Storage | Bavarian developers bundle behind-the-meter batteries to capture capacity market premiums under federal mandates. |
| Green Certification Program | KBA-certified charging infrastructure integrates renewable supply with electric vehicle grid connection priorities. |
Research Methodology
Multi-period observation of Bundenetzagentur auction clearing prices, EEG feed-in tariff revisions, and municipal permitting approval timelines anchored the trend analysis, supplemented by interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Secondary validation drew from EIA data, IEA renewable deployment reports, FERC-style regulatory filings, and European project development databases. Bottom-up capacity addition modeling triangulated against top-down national emission budget targets under EU Green Deal frameworks.
Input-output matrices mapped generation capacity by fuel source, project scale tier, and regional grid type across the projection horizon. CAGRs derived from regression analysis of historical auction price discovery and equipment cost curves. Forecast inputs incorporated hydrogen pipeline conversion timelines and industrial power purchase agreement signing velocity as demand-side drivers.
Policy reversal on EEG auction mechanisms, polysilicon trade restriction escalation, and offshore wind installation vessel availability constraints are the dominant revision risks to the outlook. Deviation in municipal permitting streamlining implementation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
South Korea Renewable Energy Market
Renewable Energy
Canada Renewable Energy Market
Renewable Energy
Belarus Renewable Energy Market
Renewable Energy
Renewable Naphtha Market
Renewable Energy
Saudi Arabia Renewable Energy Market
Renewable Energy
Ethiopia Renewable Energy Market
Renewable Energy
Solar Balloon Market
Renewable Energy
Renewable Energy Policy Fit Analysis Market
Renewable Energy
Biogas Plant Market
Renewable Energy
Hydrokinetic Converters Market
Renewable Energy
Asia-Pacific Renewable Energy Market
Renewable Energy
Europe Renewable Energy Market
Renewable Energy
Austria Renewable Energy Market
Renewable Energy
Wind Turbine Automation Market
Renewable Energy
Southeast Asia Renewable Energy Market
Renewable Energy
Solar Bicycle Shed Market