
 Europe Ocean Power Market | 2026-2036
Europe Ocean Power Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ocean Power Market Analytics
Aftermarket service revenue is fragmenting across installation, maintenance, and engineering contracts as project developers seek to lock in long-term operational cash flows. Ørsted A/S leverages its offshore wind service infrastructure to cross-skill technicians for tidal array upkeep. Orbital Marine Power anchors its competitive position through proprietary nacelle refurbishment capabilities at its Orkney base. SIMEC Atlantis Energy competes by offering integrated engineering-to-operations packages that reduce client interface complexity.
Europe ocean power encompasses the extraction of kinetic and thermal energy from marine environments through tidal barrages, point absorbers, oscillating water columns, and ocean thermal energy conversion systems, typically operating at water depths of 20-50 meters for wave devices and requiring seabed anchoring rated to 2-3 meter-per-second current velocities, primarily serving grid-connected electricity generation and niche desalination applications. Tidal energy leads installed capacity due to predictable resource availability and mature turbine designs, while wave energy represents the fastest-expanding technology segment as survivability engineering improves and levelized cost trajectories steepen. Marine current energy occupies a narrower margin pool concentrated in demonstration-to-commercial transition projects, with ocean thermal energy conversion remaining geographically constrained to southern European latitudes where surface-to-deepwater temperature differentials exceed 20°C.
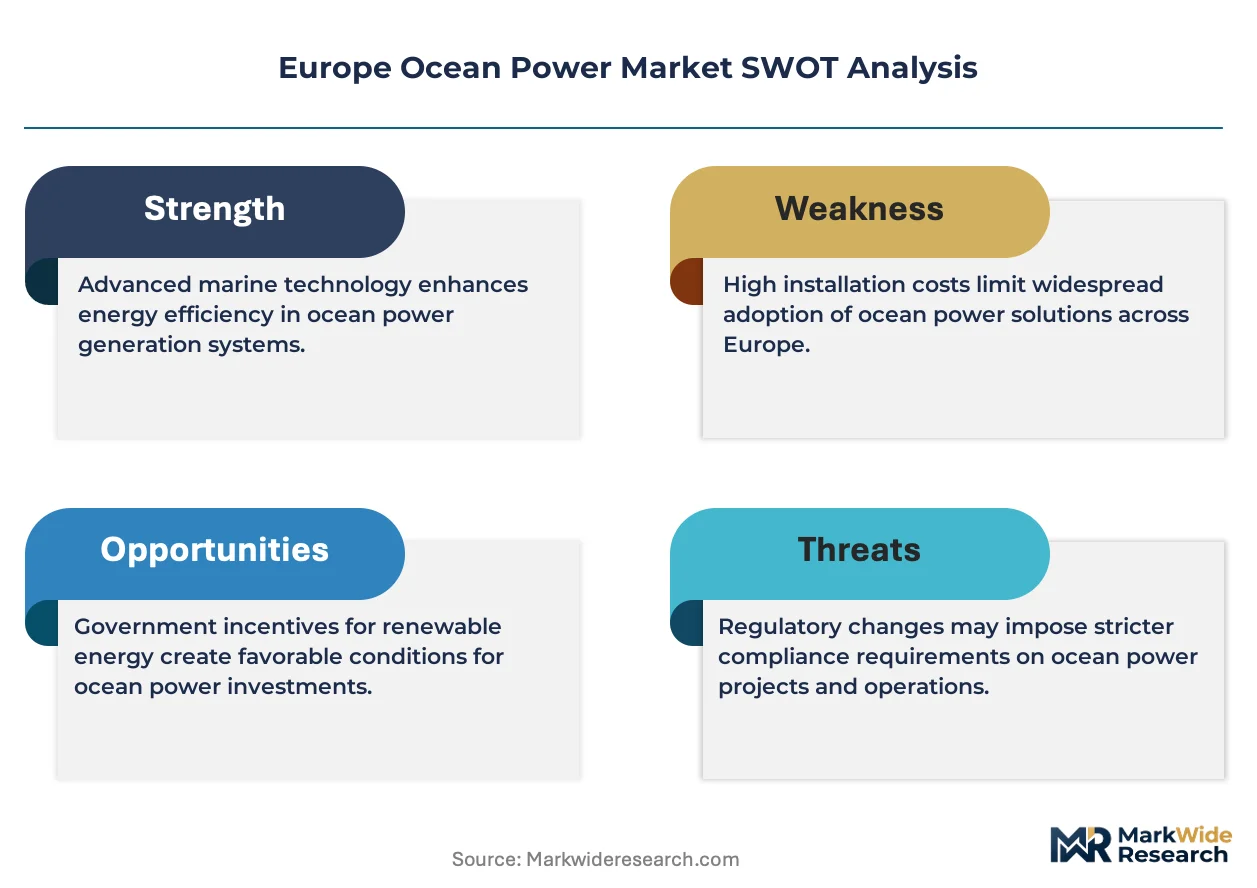
The EU Green Deal's marine renewable targets, the F-Gas Regulation's restrictions on high-global-warming-potential insulating media, and ECHA's REACH compliance requirements for anti-corrosion coatings collectively shape equipment specifications and project permitting timelines across European member states. The European Marine Energy Centre's test protocols and OSPAR Convention environmental assessments further condition technology qualification pathways and site licensing. Stakeholders must monitor how national maritime spatial planning allocations interact with offshore wind lease rounds to secure priority ocean energy zones before seabed constraints harden.
Market Dynamics
Offshore grid interconnection mandates across Scottish, Portuguese, and French territorial waters are forcing converter station redesigns and reshaping procurement timelines for tidal array developers.
Growth Catalysts
- EU Green Deal marine renewable targets:Binding national capacity quotas under the 2030 climate framework are compelling utility procurement of wave and tidal demonstration projects.
- F-Gas Regulation phase-down:Restrictions on fluorinated insulating gases in high-voltage equipment are accelerating demand for SF6-free converter technologies in subsea cable systems.
- Scottish territorial water resource concentration:Predictable tidal stream velocities exceeding 2.5 meters per second in the Pentland Firth corridor are anchoring MeyGen-scale commercial deployments.
Market Restraints
- Seabed anchoring cost volatility:Steel mooring chain and gravity base fabrication input costs fluctuate with North Sea offshore wind demand cycles.
- Specialized vessel supply concentration:Heavy-lift jack-up availability concentrates among North Sea offshore wind contractors, creating installation window bottlenecks.
- OSPAR Convention environmental assessment timelines:Marine mammal impact studies and benthic habitat surveys extend site licensing by 18-36 months in sensitive Scottish waters.
Strategic Opportunities
- Portuguese Atlantic wave energy zone allocation:Unleased seabed parcels off northern Portugal offer first-mover positioning ahead of Spanish and Irish lease rounds.
- Desalination co-location applications:Island municipalities in Greece and Cyprus are evaluating ocean thermal energy conversion for dual electricity-freshwater output.
- CSRD sustainability disclosure mandates:Corporate reporting requirements on Scope 3 emissions are creating preference pull for marine renewable power purchase agreements.
Industry Challenges
- Subsea electrical technician scarcity:Cross-training programs from offshore wind cannot scale fast enough to meet tidal array O&M crewing needs.
- Type certification timeline compression:European Marine Energy Centre test protocols and IEC 62600-2 standards require 24-48 month validation cycles before commercial financing.
- Anti-corrosion coating REACH compliance:ECHA restrictions on biocidal hull treatments are forcing reformulation of tidal turbine nacelle protective systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ocean Power Market |
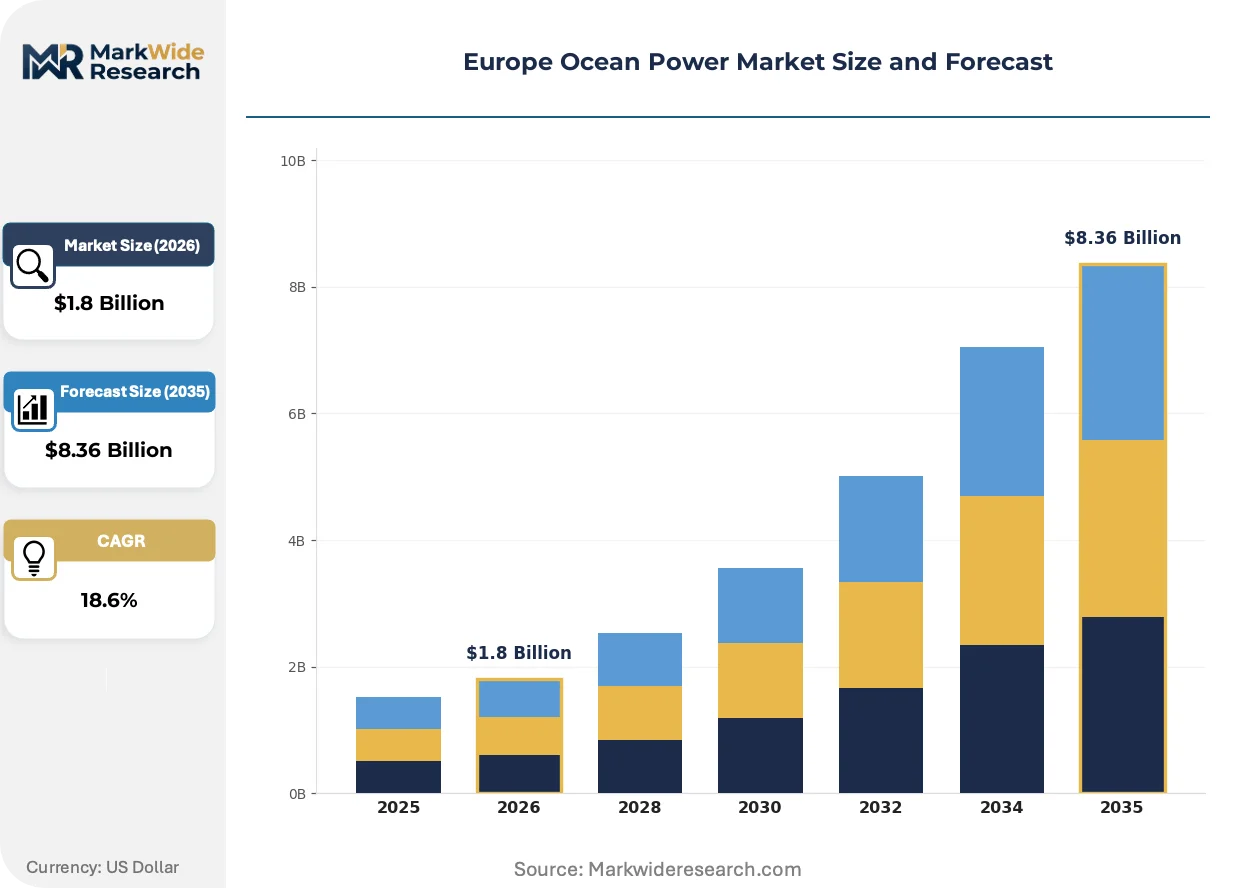
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Tidal Energy, Wave Energy, Ocean Thermal Energy Conversion, Marine Current Energy Application: Electricity Generation, Desalination, Water Pumping, Aquaculture End User: Utilities, Marine Operators, Research Institutions, Government Bodies Service Type: Installation, Maintenance, Consulting, Engineering |
| Companies Covered | Ørsted A/S, Orbital Marine Power, SIMEC Atlantis Energy, Corpower Ocean, 40South Energy, Carnegie Clean Energy, Eco Wave Power Global AB, Ocean Power Technologies Inc., MeyGen, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ocean Power Market Evolving Landscape
Tidal turbine drivetrain architectures and subsea cable insulation chemistries are undergoing rapid revision as developers target 25-year operational lifespans in corrosive North Atlantic conditions.
Direct-drive permanent magnet generators are eliminating gearbox failure modes in tidal stream turbines. Scottish array operators are specifying these units for 1.5 MW+ nacelles to reduce maintenance vessel calls. Gearbox-dependent designs are rendering obsolete for new-build projects in high-velocity current zones.
The F-Gas Regulation's 2014/517/EU amendment tightens SF6 leak thresholds for high-voltage switchgear. Converter station OEMs are trialing vacuum-interruption and clean-air insulation for 66 kV+ subsea platforms. French transmission system operators are most affected, rewriting procurement specifications for cross-channel interconnector projects.
Utility offtake agreements now bundle 15-year service contracts with initial equipment supply. Developers are locking in operational cash flows rather than competing on capital cost alone. This contractual unbundling is most visible in Scottish waters, where MeyGen-phase procurement templates are spreading to Orkney and Shetland test sites.
Europe Ocean Power Market Segmentation
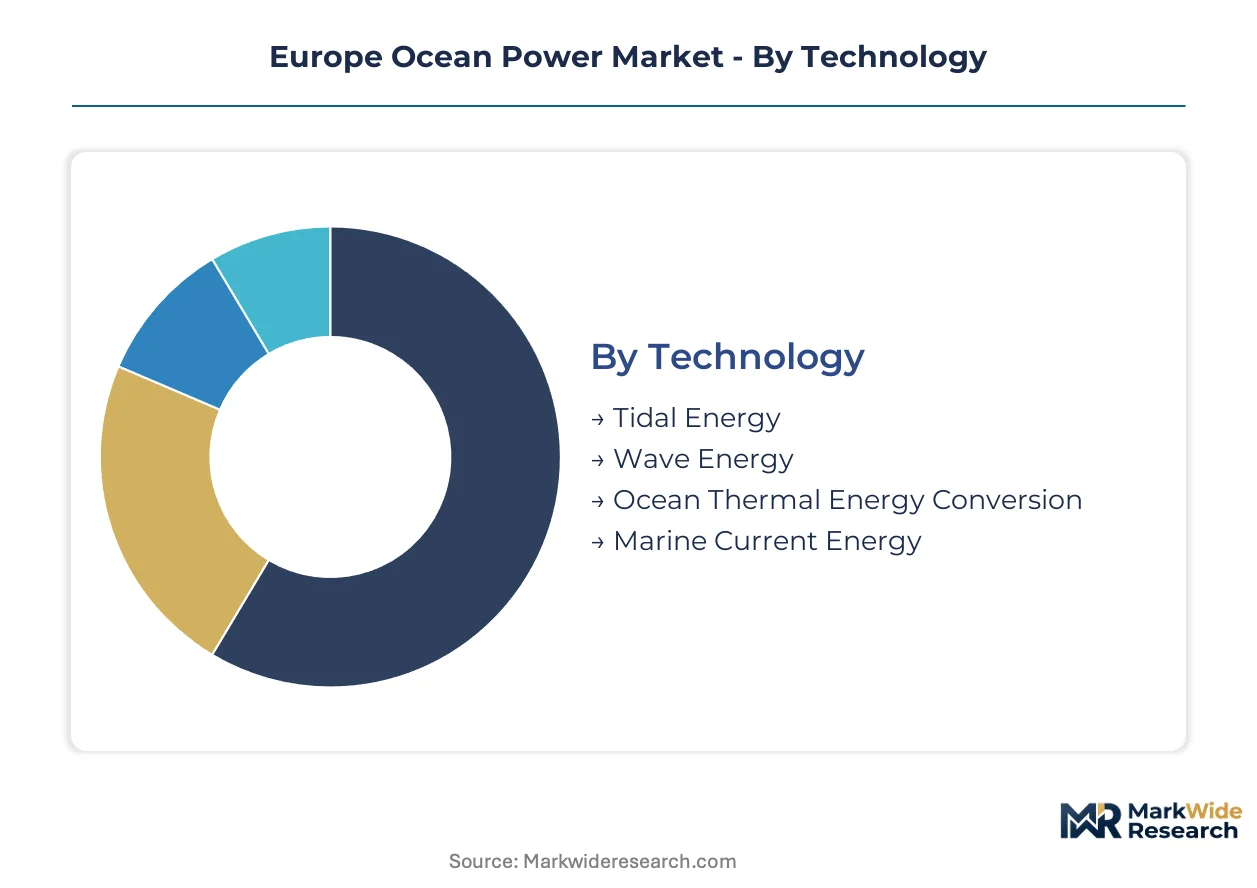
Technology-to-service linkages in European ocean power require granular segmentation to capture how tidal array hardware specifications cascade into specialized O&M contracts and regulatory compliance pathways. Each dimension reveals distinct margin pools and capability requirements that reshape competitive positioning across the value chain.
Technology:
Maturity spectra separate commercially deployable systems from demonstration-phase alternatives, with direct implications for financing structures and equipment procurement cycles.
- Tidal Energy:Horizontal-axis turbines mounted on seabed gravity bases or floating platforms extract kinetic energy from predictable tidal streams. Scottish territorial waters concentrate procurement, where MeyGen-phase deployments and Pentland Firth resource density anchor utility-scale offtake agreements.
- Wave Energy:Point absorbers, oscillating water columns, and attenuator architectures convert surface motion to electricity. Northern Portugal and Atlantic France concentrate project pipelines, as survivability engineering improvements and reduced levelized cost trajectories accelerate developer interest.
- Ocean Thermal Energy Conversion:Rankine cycle systems exploit surface-to-deepwater temperature differentials exceeding 20°C. Southern European latitudes in Greece and Cyprus host feasibility studies for dual electricity-desalination output.
- Marine Current Energy:Submerged turbines target lower-velocity currents outside tidal stream zones. Demonstration-to-commercial transition projects in French coastal waters occupy narrower margin pools pending IEC 62600-2 certification completion.
Tidal Energy handles the majority of throughput; Wave Energy is the fastest mover on share.
Application:
Revenue concentration tilts toward grid-connected generation, while niche applications create differentiation opportunities for technology providers with flexible system architectures.
- Electricity Generation:Grid-connected tidal and wave arrays feed transmission infrastructure through subsea export cables. Scottish and Portuguese procurement concentrates utility-scale capacity additions under EU Green Deal binding quotas.
- Desalination:Ocean thermal energy conversion and wave-powered reverse osmosis systems target island municipalities with constrained freshwater access. Greek and Cypriot coastal authorities evaluate co-location economics.
- Water Pumping:Tidal barrage and lagoon systems enable estuarine water management. French and British coastal engineering studies examine flood defense synergies.
- Aquaculture:Integrated multi-trophic systems leverage wave and current energy for offshore farm operations. Norwegian and Scottish marine operators pilot hybrid platforms combining generation with fish farming infrastructure.
Electricity Generation commands the dominant revenue position; Desalination is expanding most quickly as water stress intensifies across Mediterranean coastal zones.
End User:
Procurement authority fragments across balance-sheet-backed utilities, specialized marine contractors, and public research funders with divergent risk appetites and contract structures.
- Utilities:Vertically integrated power companies underwrite tidal array deployments through 15-25 year power purchase agreements. ScottishPower and EDP Renovaveis anchor European procurement volumes.
- Marine Operators:Offshore wind developers cross-skill installation fleets and service infrastructure for ocean power projects. Ørsted A/S and SIMEC Atlantis Energy leverage North Sea vessel networks.
- Research Institutions:Universities and national laboratories validate device performance at test berths. European Marine Energy Centre in Orkney and SEM-REV in France condition technology qualification pathways.
- Government Bodies:National maritime agencies allocate seabed leases and enforce OSPAR Convention environmental assessments. Marine Scotland and Portuguese Directorate-General for Maritime Policy shape site licensing timelines.
Utilities commit the largest capital allocations; Research Institutions are gaining procurement influence as certification requirements tighten.
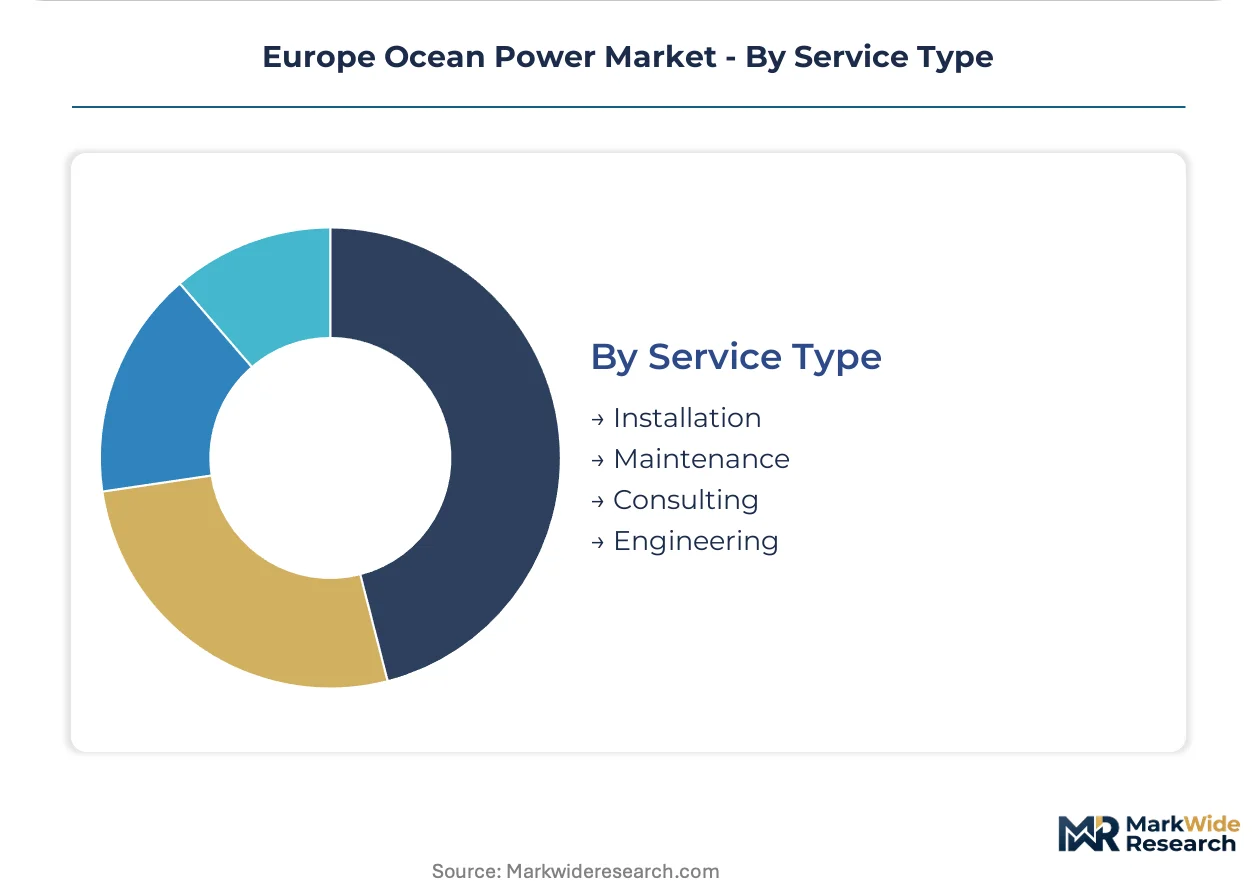
Service Type:
Contract unbundling is fragmenting integrated EPC arrangements into specialized installation, maintenance, and engineering packages that lock in long-term operational cash flows.
- Installation:Heavy-lift jack-up vessels position gravity bases and turbine nacelles in water depths of 20-50 meters. North Sea offshore wind contractors command premium day-rates during constrained weather windows.
- Maintenance:Subsea electrical technicians perform nacelle refurbishment and cable integrity inspections. Orbital Marine Power's Orkney base anchors proprietary refurbishment capabilities for tidal stream assets.
- Consulting:Environmental impact assessments and maritime spatial planning advisory support project permitting. OSPAR Convention compliance studies and benthic habitat surveys extend licensing timelines.
- Engineering:Front-end design and type certification management bridge demonstration to commercial financing. European Marine Energy Centre test protocols and IEC 62600-2 standards require 24-48 month validation cycles.
Installation absorbs the largest project cost share; Maintenance is climbing the fastest as operational fleets expand and service contracts lengthen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scottish waters prioritize tidal stream velocity harvesting, while Portuguese and French coastlines favor wave energy survivability engineering, creating divergent equipment procurement patterns across European seabed lease zones.
United Kingdom
The Pentland Firth corridor anchors MeyGen-phase commercial deployments with tidal velocities exceeding 2.5 meters per second. Marine Scotland enforces OSPAR Convention environmental assessments that extend site licensing timelines by 18-36 months. Orkney hosts the European Marine Energy Centre test berths where Orbital Marine Power operates proprietary nacelle refurbishment capabilities.
Portugal
Northern Atlantic wave energy zones offer first-mover positioning ahead of Spanish lease rounds. The Portuguese Directorate-General for Maritime Policy allocates unleased seabed parcels under EU Green Deal marine renewable targets. The Aguçadoura test site conditions technology qualification pathways for point absorber architectures.
France
Cross-channel interconnector projects drive SF6-free converter technology procurement for 66 kV+ subsea platforms. The F-Gas Regulation's 2014/517/EU amendment tightens leak thresholds for high-voltage switchgear. SEM-REV in Brittany validates device performance for Atlantic wave energy demonstration projects.
Ireland
Western seabed resource mapping identifies marine current energy sites outside tidal stream zones. The country's maritime spatial planning allocations interact with offshore wind lease rounds to secure priority ocean energy zones. Galway Bay hosts demonstration-to-commercial transition projects pending IEC 62600-2 certification completion.
Norway
Hybrid platforms combine generation with fish farming infrastructure in integrated multi-trophic aquaculture systems. The Norwegian Environment Agency coordinates OSPAR Convention compliance for subsea cable installations. Trondheim research clusters validate ocean thermal energy conversion feasibility studies for northern latitude adaptations.
Europe Ocean Power Market Competitive Landscape
Capability concentration sits with specialized marine energy developers; scale advantage sits with offshore wind incumbents cross-skilling installation fleets. The vendor base separates into three tiers: vertically integrated array operators, component specialists with proprietary refurbishment capabilities, and research-to-commercial engineering houses. Competitive moves center on 15-year service contract bundling and cross-sector technician training programs rather than capital cost competition alone.
Among Danish and Scottish developers, Ørsted A/S represents the offshore wind incumbent archetype leveraging North Sea vessel networks, while Orbital Marine Power exemplifies the specialized developer tier with captive Orkney-based service infrastructure. SIMEC Atlantis Energy occupies the integrated engineering-to-operations position, reducing client interface complexity through bundled procurement templates.
| Leading Market Players |
|---|
| Ørsted A/S |
| Orbital Marine Power |
| SIMEC Atlantis Energy |
| Corpower Ocean |
| 40South Energy |
| Carnegie Clean Energy |
| Eco Wave Power Global AB |
| Ocean Power Technologies Inc. |
| MeyGen |
| Others |
Value Network & Pricing Analysis
Heavy-lift jack-up vessel undercapacity in the North Sea during peak offshore wind installation seasons compresses tidal array deployment windows and elevates charter rates for ocean power contractors. This utilization squeeze forces developers to lock in multi-year vessel contracts at premium pricing, while converter station OEMs absorb margin pressure from F-Gas Regulation compliance costs.
Pricing Analysis
Long-term offtake agreements with bundled 15-year service contracts dominate European ocean power procurement, displacing capital-cost-only competition. Price differentiation hinges on IEC 62600-2 certification tier and gravity base fabrication quality grade, with certified arrays commanding substantial premiums over demonstration-phase alternatives. Pricing pressure stems from steel mooring chain cost volatility tracking offshore wind demand cycles. Utilities exhibit lowest price sensitivity given balance-sheet backing, while marine contractors face acute margin compression from specialized vessel scarcity.
Supply Chain Analysis
Export control regimes on permanent magnet rare earth elements constrain drivetrain sourcing from China, forcing Scottish and Danish developers toward Japanese and German magnet suppliers. Gravity base fabrication draws from Spanish and Portuguese steel foundries, while subsea cable insulation compounds rest on Belgian and Dutch chemical manufacturers. Single-source vulnerability concentrates in heavy-lift jack-up vessels anchored to North Sea offshore wind contractors. Distribution runs through EPC consortiums integrating turbine supply, installation, and long-term O&M under unified contracting structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe ocean power is entering a cyclical upswing driven by EU Green Deal binding capacity quotas compelling utility procurement commitments. This regulatory floor underwrites project financeability and stabilizes developer cash flow visibility across the deployment pipeline.
For Market Incumbents: Harden competitive moats through captive nacelle refurbishment infrastructure at Orkney-scale service bases, insulating against offshore wind incumbents cross-skilling technician pools. Deepen backward integration into gravity base steel fabrication to neutralize mooring chain cost volatility. Prioritize IEC 62600-2 certification investment ahead of MeyGen-phase procurement template standardization.
For New Entrants and Emerging Players: Northern Portuguese Atlantic wave energy zones offer underpenetrated seabed allocations ahead of Spanish lease round competition. Target desalination co-location applications in Greek and Cypriot island municipalities where dual electricity-freshwater output commands premium offtake terms. Pursue research institution partnerships for European Marine Energy Centre test berth access as qualification pathway acceleration.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized marine energy developers with proprietary service infrastructure rather than offshore wind incumbents lacking tidal-specific capabilities. The 5-10 year viability window favors integrated engineering-to-operations platforms reducing client interface complexity. Monitor OSPAR Convention environmental assessment timeline compression as inflection signal for site licensing velocity acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| SF6-Free Converter Technology Deployment | French transmission operators rewrite procurement specifications under F-Gas Regulation tightening. |
| Long-Term Service Contract Bundling | Scottish developers lock operational cash flows through 15-year O&M agreements with utilities. |
| Orkney-Base Nacelle Refurbishment Captivity | Orbital Marine Power anchors proprietary maintenance capabilities reducing third-party vessel dependence. |
| Portuguese Atlantic Zone First-Mover Positioning | Unleased seabed parcels off northern Portugal precede competitive Spanish lease allocations. |
| Direct-Drive Permanent Magnet Generator Specification | Scottish array operators eliminate gearbox failure modes in high-velocity Pentland Firth corridors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU marine renewable policy filings, EMEC test protocol documentation, and OSPAR Convention assessment records. Utility planning officers, tidal array project developers, subsea cable EPC contractors, and converter station OEM technical directors contributed structured interviews. Bottom-up project pipeline enumeration triangulates against top-down EU Green Deal capacity quota allocation models.
Forecast inputs span technology maturity spectra, seabed lease allocation velocity, and vessel availability constraints across the projection horizon. Segmentation dimensions include tidal versus wave versus ocean thermal energy conversion systems, grid-connected versus desalination application splits, and utility versus marine operator versus research institution procurement authority. CAGRs derive from installation cost trajectory modeling and levelized cost reduction curves indexed to IEC certification completion rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by offshore wind majors acquiring specialized marine energy developers would shift outcomes. Material shifts in F-Gas Regulation enforcement intensity or OSPAR Convention environmental assessment timeline compression would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Green Renewable Energy Market
Renewable Energy
Renewable Energy MRO Market
Renewable Energy
Denmark Renewable Energy Market
Renewable Energy
Malaysia Renewable Energy Market
Renewable Energy
Renewable Energy Cable Market
Renewable Energy
Europe IoT in Renewable Energy Market
Renewable Energy
South Africa Rooftop Solar Market
Renewable Energy
Solar Drying System Market
Renewable Energy
Biogas Plant Market
Renewable Energy
Wave Energy Converter Market
Renewable Energy
Europe Biomethane Market
Renewable Energy
Solar Navigation Light Market
Renewable Energy
Wind Turbine Inspection Drones Market
Renewable Energy
Global Artificial Photosynthesis Market
Renewable Energy
Offshore Wind Energy Infrastructure Market
Renewable Energy
Net-Zero Energy Buildings Market