
 Singapore Renewable Energy Market | 2026-2036
Singapore Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Renewable Energy Market Analytics
Project finance structures with long-term offtake agreements is narrowing the competitive field to developers with balance-sheet depth and sovereign-linked credit profiles. Sembcorp Industries leverages its integrated utilities platform to anchor large-scale solar and regional power import projects. Vena Energy sustains a pure-play renewable development model across Southeast Asian markets from its Singapore headquarters. Keppel competes through engineering capabilities that extend from offshore infrastructure into floating solar and energy storage systems.
Singapore renewable energy encompasses electricity generation from solar photovoltaic, wind, biomass, and emerging marine sources within a city-state constrained by land scarcity and no indigenous fossil fuel reserves. Photovoltaic systems dominate installed capacity, with module efficiency thresholds above 20% now standard for utility-scale deployments that feed into the national grid managed by SP Group. Solar technology captures the majority of capital deployment given rooftop saturation programs and floating installations on reservoirs, while grid-tied system architecture leads application volumes due to the city-state's dense urban infrastructure and limited off-grid use cases. Biomass and tidal segments occupy niche positions where waste-to-energy integration and coastal demonstration projects create specialized margin pools.
Singapore's Energy Market Authority governs grid access rules and licensing frameworks that determine which generation assets qualify for dispatch priority, while the National Environment Agency enforces carbon tax compliance that elevates the cost baseline for fossil-fired power and redirects industrial load toward renewable offtake. The Building and Construction Authority mandates Green Mark standards that embed photovoltaic readiness into new commercial developments, effectively pre-wiring demand for distributed solar systems. Stakeholders must monitor how the regulatory trajectory for cross-border power imports from Indonesia and Australia reshapes project economics and developer selection criteria for the next wave of capacity additions.
Market Dynamics
Cross-border electricity imports are restructuring Singapore's generation mix as the Energy Market Authority accelerates licensing frameworks for regional power corridors, forcing developers to secure sovereign-backed offtake structures ahead of domestic solar saturation.
Growth Catalysts
- Carbon Tax Escalation:Singapore's progressive carbon tax regime elevates fossil-fired power costs above renewable parity thresholds, redirecting industrial load toward clean electricity contracts.
- Data Center Load Expansion:Hyperscale facility operators in Tuas and Changi North are executing 15-25 year power purchase agreements that underwrite utility-scale solar and import project finance.
- Floating Photovoltaic Deployment:Reservoir-based solar installations on Tengeh and Bedok reservoirs unlock land-constrained capacity additions through modular marine engineering.
Market Restraints
- Land Scarcity Premium:Industrial rooftop saturation and reservoir capacity limits constrain domestic solar expansion beyond 2030 without territorial expansion.
- Import Infrastructure Lag:Subsea cable commissioning timelines for Indonesia and Australia corridors extend 5-7 years, creating supply gaps before 2032.
- Biomass Feedstock Constraints:Limited agricultural waste streams and competing waste-to-energy incineration demand restrict organic fuel supply chains.
Strategic Opportunities
- Jurong Island Industrial Cluster:Petrochemical and refining complexes present concentrated demand for 24/7 renewable supply through hybrid solar-storage-import configurations.
- Green Hydrogen Export Hub:Port infrastructure and regional renewable import access position Singapore as an ASEAN hydrogen trading and bunkering node.
- Building-Integrated Photovoltaics:The Building and Construction Authority's Green Mark Platinum mandates are embedding solar-ready design into commercial developments exceeding 2,000 square meters.
Industry Challenges
- Grid Integration Complexity:Variable solar injection and asynchronous import flows require SP Group to deploy advanced inverter and battery coordination systems.
- Specialized EPC Talent Scarcity:Floating solar marine engineering and high-voltage direct current cable installation expertise command premium wages across Southeast Asian labor markets.
- Permitting Timeline Compression:Environmental impact assessments for reservoir deployments and cross-border interconnection licenses extend development cycles beyond investor return thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Renewable Energy Market |
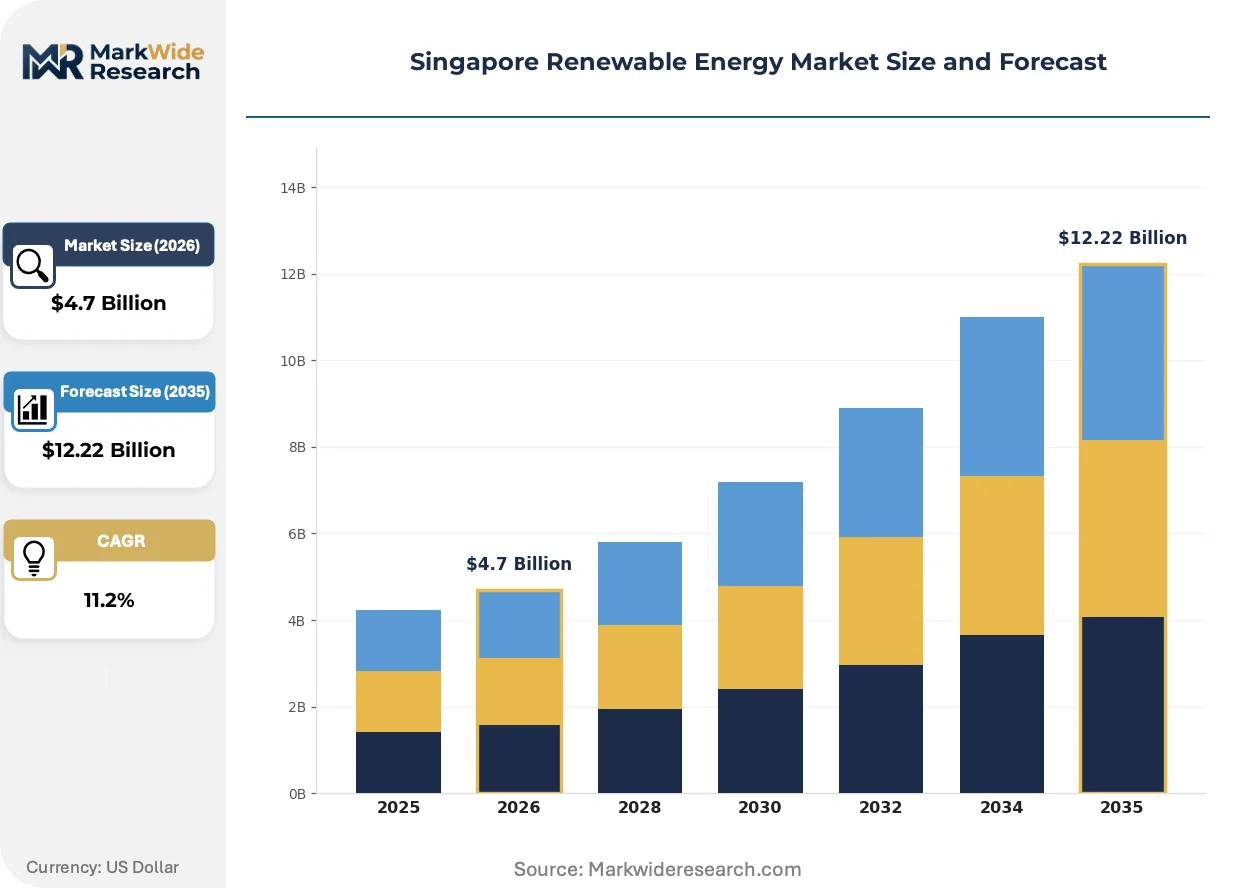
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.22 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar, Wind, Biomass, Hydropower Application: Residential, Commercial, Industrial, Utilities Energy Source: Geothermal, Tidal, Fermentation, Others System Type: Grid-Tied, Off-Grid, Hybrid, Microgrid |
| Companies Covered | Vena Energy, EDP Renewables APAC, Sunseap Group, GE Vernova, Maxeon Solar Technologies, Sembcorp Industries, Keppel, EnerMech, SP Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Renewable Energy Market Evolving Landscape
Distributed energy resource management platforms are converging with artificial intelligence forecasting to transform how Singapore balances intermittent renewable supply against concentrated industrial demand.
Digital twin technology is virtualizing power plant operations across Singapore's solar fleet, enabling SP Group and Sembcorp to simulate shading losses, inverter degradation, and predictive maintenance schedules before physical intervention. Commercial and industrial offtakers are subscribing to these virtualized performance guarantees, transferring operational risk from balance sheets to technology vendors.
Singapore's Energy Market Authority is tightening licensing conditions for generation companies to include cybersecurity standards aligned with IEC 62351 protocols, mandating encrypted SCADA communications and incident response frameworks. Grid-connected assets must demonstrate resilience against coordinated attacks before receiving dispatch priority, compressing compliance timelines for developers with legacy control systems.
Aggregated virtual power plant models are displacing traditional utility-scale procurement as commercial estate managers pool rooftop solar, battery storage, and flexible load into dispatchable blocks. This aggregation is concentrating buyer power among facility management platforms and disintermediating direct generator relationships for mid-sized industrial consumers across the Jurong and Tuas corridors.
Singapore Renewable Energy Market Segmentation
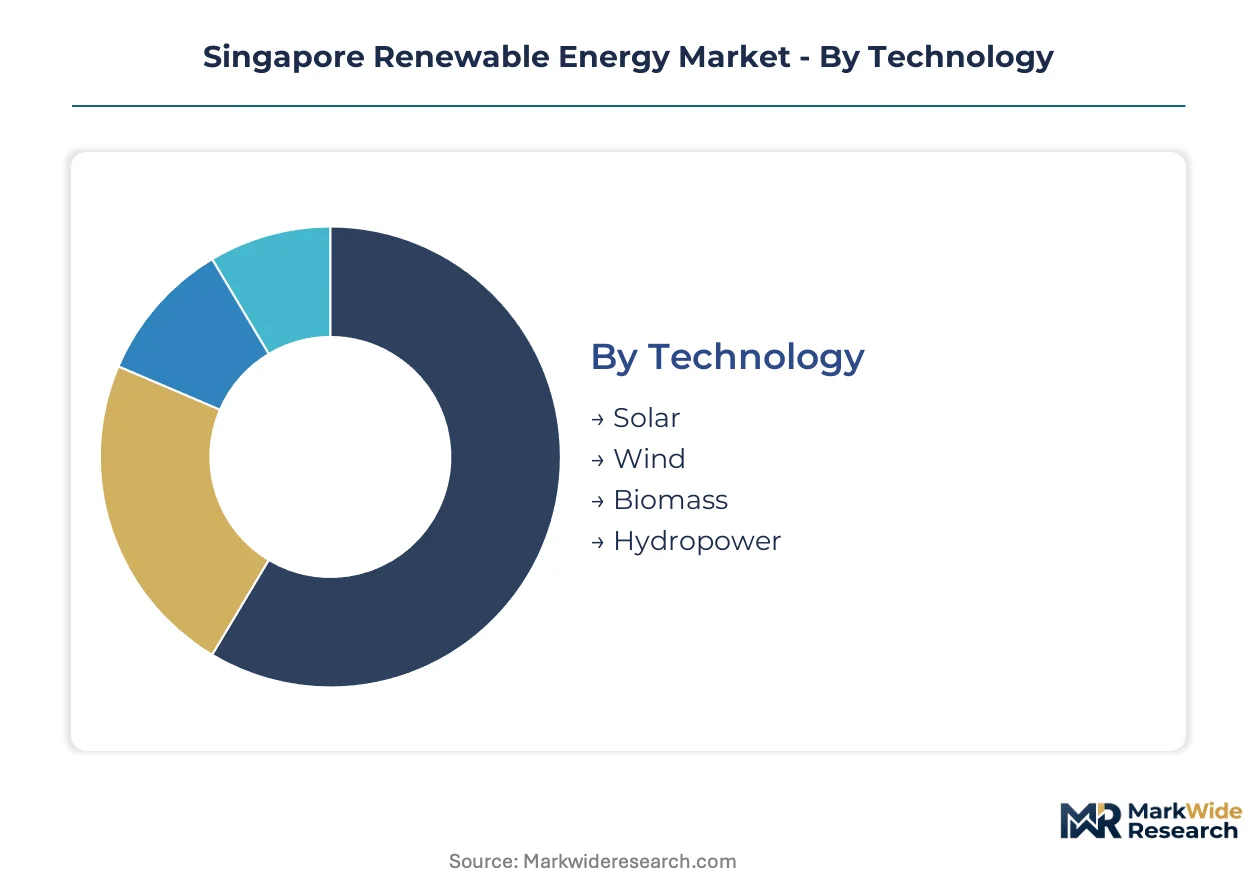
Singapore's renewable energy segmentation reflects land constraints and grid infrastructure realities. Technology choices concentrate on deployable solutions within dense urban boundaries, while application patterns track industrial decarbonization mandates.
Technology:
Mature photovoltaic systems dominate deployment, while emerging marine and waste-to-energy technologies occupy specialized niches requiring distinct regulatory pathways.
- Solar:Photovoltaic modules exceeding 20% conversion efficiency anchor utility-scale arrays on industrial rooftops and floating reservoir installations. Jurong Island petrochemical complexes and Tuas data centers drive procurement volumes under long-term power purchase agreements.
- Wind:Small-scale urban turbines and future offshore floating platforms face technical hurdles in low-wind-speed equatorial conditions. The Energy Market Authority's regional import frameworks redirect wind investment toward cross-border corridors rather than domestic generation.
- Biomass:Waste-to-energy incineration competes for limited organic feedstock streams against circular economy mandates.
- Hydropower:Absent indigenous river systems; relevant only via imported hydroelectricity from regional neighbors.
Solar handles the majority of throughput; Wind is the fastest mover on share through import-linked indirect access.
Application:
Cost tier differentiation separates premium 24/7 renewable contracts from standard grid-tied installations.
- Industrial:Petrochemical, semiconductor, and data center operators execute 15-25 year power purchase agreements that underwrite project finance. Jurong Island and Tuas corridors concentrate demand for hybrid solar-storage-import configurations meeting baseload requirements.
- Commercial:Green Mark Platinum mandates embed photovoltaic readiness into developments exceeding 2,000 square meters. Facility management platforms aggregate distributed assets into virtual power plants.
- Utilities:SP Group manages grid integration of variable solar injection and asynchronous import flows through advanced inverter coordination.
- Residential:HDB rooftop programs and private estate installations face saturation limits without territorial expansion.
Industrial contracts command premium pricing; Commercial aggregation models are expanding most quickly as facility managers pool assets.
Energy Source:
Volume concentration favors proven generation assets, while experimental marine technologies occupy demonstration-scale positions.
- Tidal:Coastal demonstration projects test kinetic energy extraction in Singapore Strait currents.
- Geothermal:Absent viable subsurface heat resources in granitic basement geology.
- Fermentation:Biogas from food waste streams integrates with waste-to-energy infrastructure.
- Others:Emerging ocean thermal and salinity gradient technologies remain pre-commercial.
Fermentation handles available organic throughput; Tidal projects are gaining share fastest through marine engineering trials.
System Type:
Customer type determines architecture selection, with grid-dependent industrial users dominating procurement.
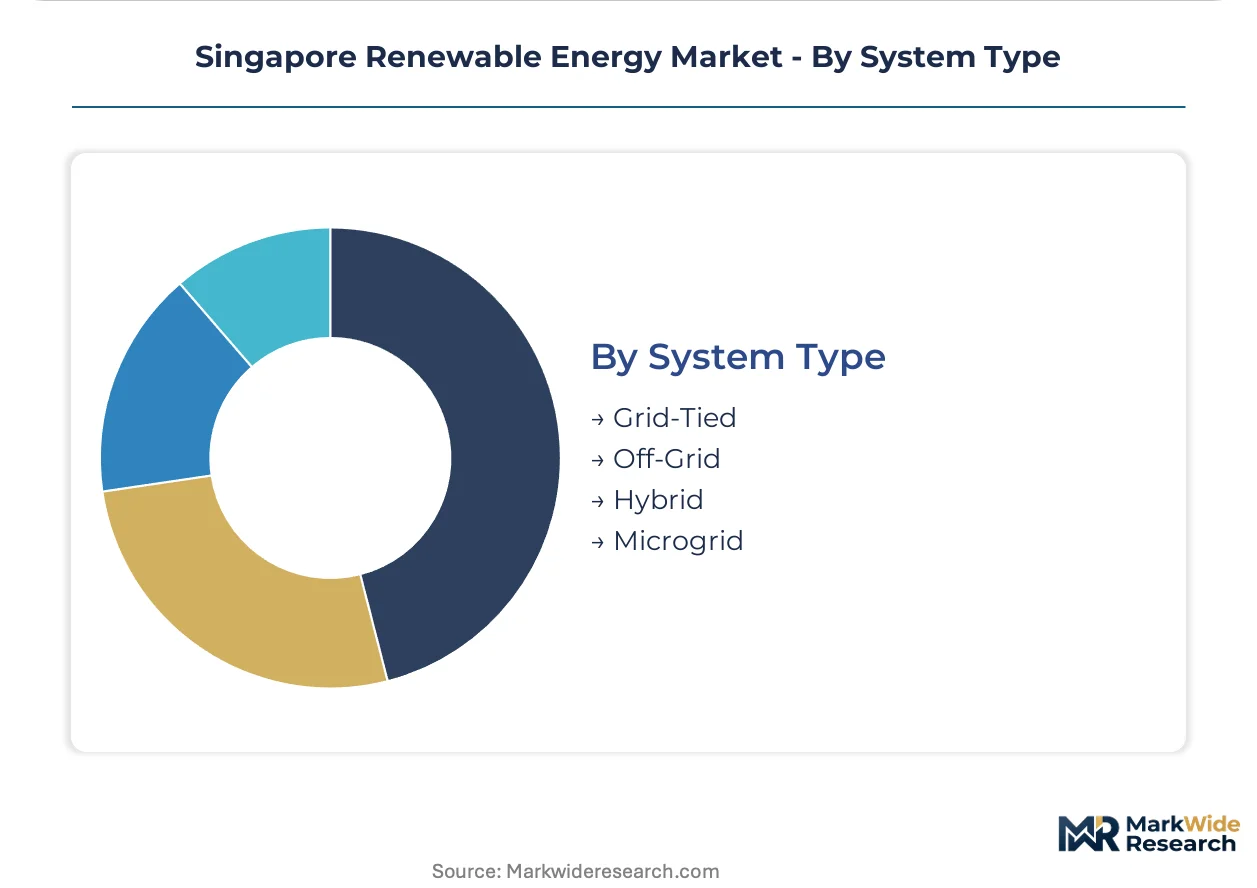
- Grid-Tied:National grid integration through SP Group infrastructure enables net metering and renewable energy certificate issuance. Dense urban infrastructure makes this the default configuration for commercial and industrial deployments.
- Hybrid:Battery-solar combinations address intermittency for 24/7 industrial loads. Jurong Island petrochemical complexes require storage-buffered supply during import corridor commissioning gaps.
- Microgrid:Sentosa and offshore island applications demonstrate islanding capability for resilience.
- Off-Grid:Negligible applicability given universal grid access and land scarcity preventing remote installations.
Grid-Tied systems handle the dominant share of connections; Hybrid configurations are climbing the fastest as storage costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's renewable energy expansion depends on cross-border electricity imports to overcome land constraints, with regional power corridors from Indonesia and Australia reshaping supply security calculations for industrial offtakers.
Indonesia
Indonesian solar and geothermal projects in Batam and Sumatra feed subsea cable corridors to Singapore under bilateral government-to-government frameworks. The country's national energy regulator coordinates licensing for these export-oriented generation assets. Batam industrial zones host concentrated solar farm development serving Singapore's baseload requirements.
Australia
Australian solar and wind resources in Northern Territory and Queensland anchor the Australia-Asia PowerLink corridor targeting Singapore offtake. The country's Clean Energy Regulator certifies renewable export credits qualifying for Singapore's carbon tax compliance. Darwin port infrastructure supports high-voltage direct current cable assembly for the subsea route.
Malaysia
Malaysian Peninsula solar installations in Johor and Malacca supply cross-border capacity through existing interconnection infrastructure. The country's Sustainable Energy Development Authority administers feed-in tariffs attracting Singapore-linked investment. Iskandar Malaysia economic zone concentrates photovoltaic manufacturing serving regional project pipelines.
Vietnam
Vietnamese offshore wind development in Binh Thuan and Ninh Thuan provinces targets future export corridors to Singapore under ASEAN Power Grid coordination. The country's Ministry of Industry and Trade negotiates power purchase frameworks with Singapore's Energy Market Authority. Phu My industrial complex hosts turbine component fabrication for regional deployment.
Thailand
Thai solar and biomass resources in the Northeast and Central regions contribute to regional grid integration studies with Singapore. The country's Energy Regulatory Commission aligns technical standards with Singapore's import licensing requirements. Map Ta Phut industrial estate explores hydrogen export potential leveraging existing petrochemical infrastructure.
Singapore Renewable Energy Market Competitive Landscape
On the supply side, the industry is consolidating around integrated utilities with sovereign-linked balance sheets and specialized renewable developers with regional development capabilities. Three strategic archetypes dominate: diversified conglomerates leveraging legacy infrastructure assets, pure-play renewable developers with Southeast Asian project pipelines, and engineering specialists converting offshore capabilities into floating solar and storage systems. Competitive moves center on securing long-term offtake agreements with data center and petrochemical operators, and assembling cross-border import consortiums with Indonesian and Australian partners.
Within the integrated utilities tier, Sembcorp Industries and Keppel anchor project finance structures through their balance-sheet depth and existing relationships with Jurong Island industrial complexes. Vena Energy occupies a pure-play development position, sustaining regional renewable pipelines from its Singapore headquarters across multiple Southeast Asian markets. These three entities exemplify the capability requirements for competing under Singapore's regulatory framework, where sovereign-linked credit profiles and specialized engineering competencies determine developer selection for utility-scale deployments.
| Leading Market Players |
|---|
| Vena Energy |
| EDP Renewables APAC |
| Sunseap Group |
| GE Vernova |
| Maxeon Solar Technologies |
| Sembcorp Industries |
| Keppel |
| EnerMech |
| SP Group |
| Others |
Value Network & Pricing Analysis
Reservoir saturation at Tengeh and Bedok is compressing domestic solar deployment timelines, forcing developers toward cross-border import projects where sovereign-backed offtake structures command premium pricing power against industrial buyers.
Pricing Analysis
Industrial OEM buyers anchor Singapore's renewable pricing structure around 15-25 year power purchase agreements with data center and petrochemical operators. Pricing stratifies across premium 24/7 renewable contracts, standard grid-tied solar installations, and economy-tier intermittent supply arrangements differentiated by certification grade under Green Mark Platinum standards and volume scale commitments. Cost compression in standard-tier domestic solar is intensifying because reservoir capacity limits constrain new project development, while pricing softness in import-linked premium tiers reflects 5-7 year subsea cable commissioning lags. Data center operators demonstrate lowest price sensitivity given carbon tax compliance mandates, whereas mid-sized commercial offtakers exhibit highest sensitivity as virtual power plant aggregation disintermediates direct generator relationships.
Supply Chain Analysis
Export control regimes on high-voltage direct current cable technology and advanced inverter systems limit equipment flows into Southeast Asian project pipelines, elongating procurement cycles for Singapore-linked developments. Module supply concentrates in China, South Korea, and Vietnam, while floating solar marine engineering expertise draws from Norway and Denmark. Polysilicon, semiconductor-grade silicon wafers, and ethylene-vinyl acetate encapsulant films constitute critical input dependencies. Single-source vulnerability runs through Chinese polysilicon refining capacity given concentration in Xinjiang-linked supply chains. Distribution runs through EPC consortiums assembling integrated solar-storage-import packages for Jurong Island and Tuas corridor deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's renewable energy market operates as a defensive-moat structure where regulatory entrenchment through Energy Market Authority licensing frameworks creates durable competitive barriers against unqualified developers.
For Market Incumbents: Entrench position by deepening sovereign-linked balance sheet capacity to underwrite cross-border import project finance ahead of 2032 supply gaps, and secure exclusive engineering partnerships with Indonesian and Australian corridor developers before permitting timelines compress further. Emerging pure-play developers with regional pipelines represent the primary competitive threat. Backward integration into floating solar marine engineering capabilities offers the strongest defensive lever against specialized EPC talent scarcity. For New Entrants and Emerging Players: Pursue building-integrated photovoltaics deployment for commercial developments exceeding 2,000 square meters under Green Mark Platinum mandates, where incumbent utilities maintain weaker presence compared to utility-scale segments. Jurong Island hybrid solar-storage configurations present the most penetrable white space given 24/7 baseload requirements that incumbent integrated utilities struggle to fulfill during import corridor commissioning gaps. Channel partnerships with facility management platforms aggregating virtual power plants offer the clearest go-to-market angle for mid-sized commercial offtakers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among developers with long-term offtake portfolios anchored by data center and petrochemical operators, positioning these archetypes for superior cash flow visibility across the analysis window. Acquisition targets should prioritize pure-play renewable developers with Southeast Asian project pipelines and existing Energy Market Authority licensing relationships rather than diversified conglomerates with legacy fossil exposure. The signal to watch is acceleration in Australia-Asia PowerLink corridor permitting approvals, which would inflect capital deployment timelines for import-linked premium-tier supply.| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Border Import Consortium Formation | Sovereign-backed offtake structures with Indonesia and Australia secure baseload supply before domestic solar saturation. |
| Floating Solar Marine Engineering Capability Buildout | Reservoir-based installations on Tengeh and Bedok unlock land-constrained capacity additions through specialized EPC expertise. |
| Virtual Power Plant Platform Integration | Facility management aggregation of distributed rooftop solar and battery assets concentrates buyer power across commercial estates. |
| Green Hydrogen Export Infrastructure Partnership | Port and petrochemical infrastructure positions Singapore as ASEAN hydrogen trading node leveraging regional renewable imports. |
| Grid-Scale Battery Storage Technology Licensing | Advanced inverter coordination systems address variable solar injection and asynchronous import flows for SP Group integration. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility planning officers at SP Group, IPP project developers with regional pipelines, EPC contractors specializing in floating solar marine engineering, and grid operators managing cross-border interconnection studies. Secondary validation drew from Energy Market Authority licensing frameworks, IEA renewable energy outlooks, FERC-style regulatory filings, and project development databases tracking Southeast Asian capacity pipelines. Bottom-up project economics modeling and top-down market sizing triangulation were cross-referenced to ensure consistency.
Calibration against historical deployment trajectories informed the analytical framework across the projection horizon. Segmentation dimensions modeled include technology type, application tier, energy source category, and system architecture, with additional granularity on regulatory framework distinctions between domestic solar and import-linked supply. CAGRs were derived from capacity addition run rates and offtake contract pricing trends. Industry-specific forecast inputs incorporated carbon tax escalation schedules and cross-border cable commissioning timelines without year-specific references.
Sensitivities concentrate around subsea cable permitting delays, polysilicon supply chain disruptions, and floating solar environmental impact assessment outcomes that could compress or extend development cycles. Forecasts reflect documented assumptions regarding sovereign credit backing for import projects and technology cost decline curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Africa Solar E-Bike Market
Renewable Energy
Solar Farm Market
Renewable Energy
East Asia Renewable Energy Market
Renewable Energy
China Wind Energy Market
Renewable Energy
Global Artificial Photosynthesis Market
Renewable Energy
North Africa Renewable Energy Market
Renewable Energy
Malaysia Renewable Energy Market
Renewable Energy
Romania Power Market
Renewable Energy
China Solar Energy Market
Renewable Energy
Europe Solar Tracker Market
Renewable Energy
Italy Renewable Energy Market
Renewable Energy
Offshore Wind Energy Infrastructure Market
Renewable Energy
Global BIPV Glass Market
Renewable Energy
South Africa Rooftop Solar Market
Renewable Energy
Switzerland Renewable Energy Market
Renewable Energy
Botswana Renewable Energy Market