
 Philippines Renewable Energy Market | 2026-2036
Philippines Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Renewable Energy Market Analytics
Philippine utility-scale solar farm development is hardening as domestic independent power producers race to meet offtake deadlines. ACEN Corporation leverages its integrated development platform across multiple islands to secure long-term power purchase agreements. Aboitiz Power Corporation anchors its portfolio with run-of-river hydropower assets that provide baseload stability to island grids. Energy Development Corporation specializes in geothermal extraction, drawing on decades of technical expertise in volcanic terrain resource mapping.
Philippines renewable energy encompasses electricity generation systems that harness solar irradiance, wind currents, organic matter combustion, and water flow kinetic energy through photovoltaic cells with typical conversion efficiencies of 18-22%, horizontal-axis wind turbines rated at 2-3 MW, anaerobic digesters producing biogas with 50-70% methane content, and low-head hydroelectric installations. These systems primarily displace imported coal and diesel generation across an archipelago where fuel transport costs inflate delivered power prices. Solar power captures the majority of new investment flows due to declining module costs and streamlined permitting under the Green Energy Auction Program. Wind energy competes favorably in northern Luzon corridor sites with consistent trade wind regimes. Hydropower retains structural importance as the only renewable source capable of providing spinning reserves and frequency regulation to the National Grid Corporation of the Philippines transmission network.
The Department of Energy administers the Renewable Portfolio Standard requiring distribution utilities to source 35% of supply from eligible renewables by 2030, while the Energy Regulatory Commission sets feed-in tariff ceilings and net metering rules that shape project finance structures. The Board of Investments extends income tax holidays and duty exemptions on imported equipment under the Renewable Energy Act of 2008. Stakeholders must track auction schedule releases and transmission capacity allocation decisions to time capital deployment effectively.
Market Dynamics
The Renewable Portfolio Standard mandate from the Department of Energy is compressing procurement timelines for distribution utilities, forcing accelerated capital deployment into solar and geothermal capacity ahead of the 2030 compliance deadline.
Growth Catalysts
- Green Energy Auction Program:The Department of Energy's competitive bidding mechanism streamlines permitting for utility-scale solar projects, reducing interconnection queue delays that previously stretched 18-24 months.
- Commercial and industrial rooftop solar:Metro Manila manufacturing facilities and Cebu business process outsourcing campuses are installing behind-the-meter photovoltaic systems to hedge against volatile wholesale electricity spot market prices.
- Geothermal resource expansion:Volcanic terrain mapping advances in Leyte and Negros islands are unlocking previously unclassified high-enthalpy reservoirs for baseload renewable generation.
Market Restraints
- Polysilicon supply concentration:Philippine solar developers remain exposed to Chinese ingot and wafer pricing volatility, with module imports comprising over 90% of project equipment costs.
- Transmission congestion:The National Grid Corporation of the Philippines lacks sufficient substation capacity in northern Luzon to absorb planned wind farm interconnections, forcing curtailment risk onto project sponsors.
- Diesel generator substitution economics:Remote island grids in Mindanao and Palawan retain dual-fuel backup systems due to solar-plus-storage capital requirements exceeding diesel operating costs at current battery prices.
Strategic Opportunities
- Mindanao electrification gap:The southern island's 68% household electrification rate lags national averages, creating concentrated demand for distributed renewable microgrids in off-grid municipalities.
- Run-of-river hydropower rehabilitation:Aging infrastructure in the Cordillera Administrative Region presents retrofit opportunities for automated turbine control systems and sediment management technologies.
- Net metering aggregation:The Energy Regulatory Commission's revised rules enable condominium associations and industrial parks to pool rooftop generation credits, unlocking multi-tenant solar deployment models previously blocked by single-meter restrictions.
Industry Challenges
- Grid code compliance engineering:Project developers face extended commissioning timelines as the National Grid Corporation of the Philippines enforces revised fault ride-through standards for inverter-based renewable resources.
- Geothermal drilling expertise scarcity:Specialized directional drilling contractors with volcanic formation experience command premium day rates, constraining exploration program scalability for independent power producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Renewable Energy Market |
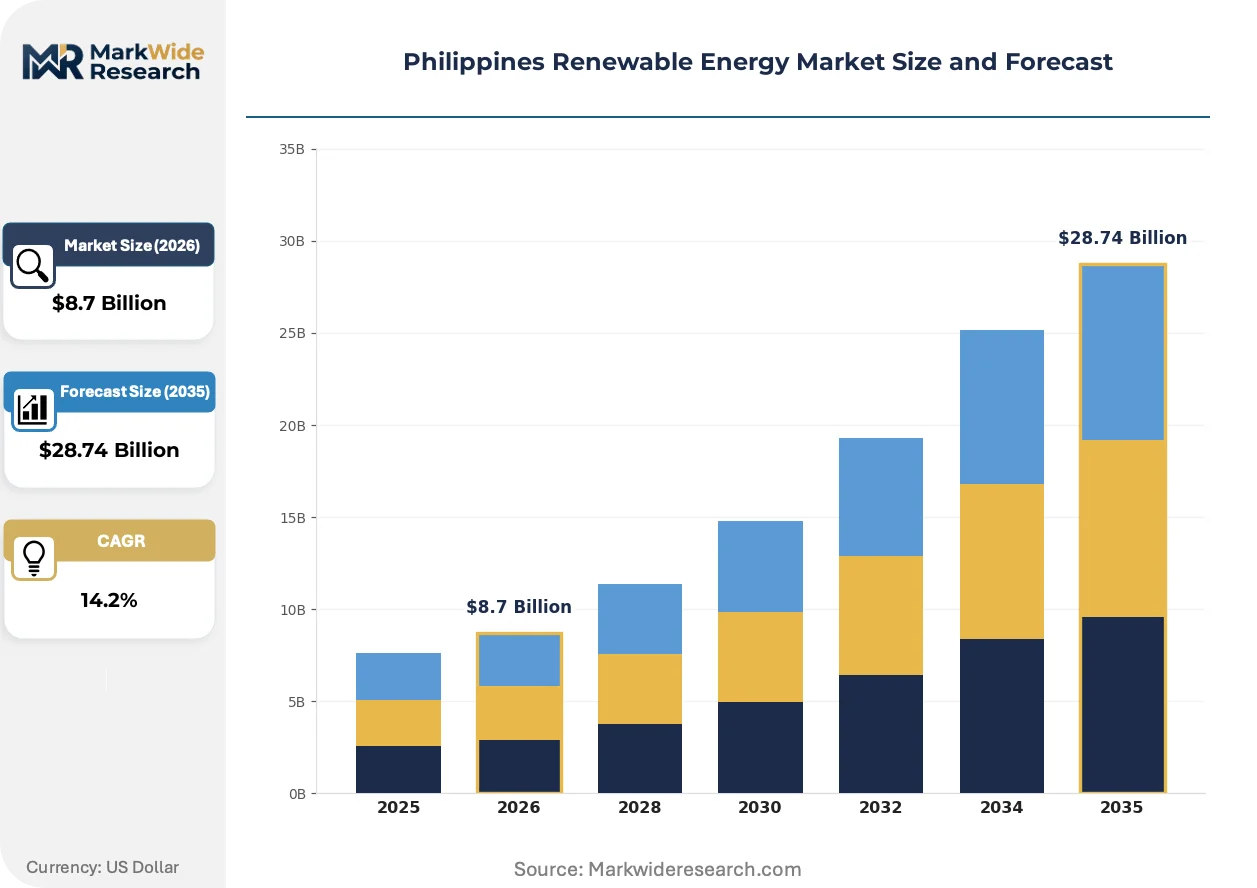
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Power, Wind Energy, Biomass, Hydropower Technology: Photovoltaic Systems, Wind Turbines, Biofuel Conversion, Hydroelectric Plants End User: Residential, Commercial, Industrial, Agricultural Installation: On-Grid, Off-Grid, Hybrid Systems, Small Scale |
| Companies Covered | ACEN Corporation, Aboitiz Power Corporation, Energy Development Corporation, Citicore Renewable Energy Corporation, First Gen Corporation, Solar Philippines Power Project Holdings Inc., Vena Energy, Terra Solar Philippines, Alternergy Holdings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Renewable Energy Market Evolving Landscape
Bifacial photovoltaic module technology is penetrating the Philippine utility-scale segment as developers seek yield optimization on fixed-tilt installations where land constraints limit tracking system deployment.
Agrivoltaic arrays are absorbing marginal agricultural land in Central Luzon rice-growing regions, allowing farmers to maintain staple crop production beneath elevated panel structures while securing secondary electricity revenue streams. The Department of Agriculture is piloting standardized lease frameworks to accelerate land-use dualization. This configuration is compressing traditional land competition tensions between food security and energy security objectives.
The Energy Regulatory Commission's feed-in tariff ceiling adjustments are forcing independent power producers toward merchant power purchase agreement structures. Commercial and industrial offtakers in the Philippine Economic Zone Authority enclaves now dominate long-term contract negotiations. Solar developers are responding with 10-15 year tenor offerings backed by international development finance institution guarantees rather than traditional utility offtake.
Corporate renewable energy procurement through the Green Energy Option Program is displacing traditional utility supply arrangements for multinational manufacturing affiliates. Food and beverage processors in Laguna Technopark and semiconductor fabricators in Cavite are executing direct bilateral contracts with solar farm operators. This behavioral shift is most visible in export-oriented zones where parent companies enforce Scope 2 emissions reduction targets through centralized supply chain mandates.
Philippines Renewable Energy Market Segmentation
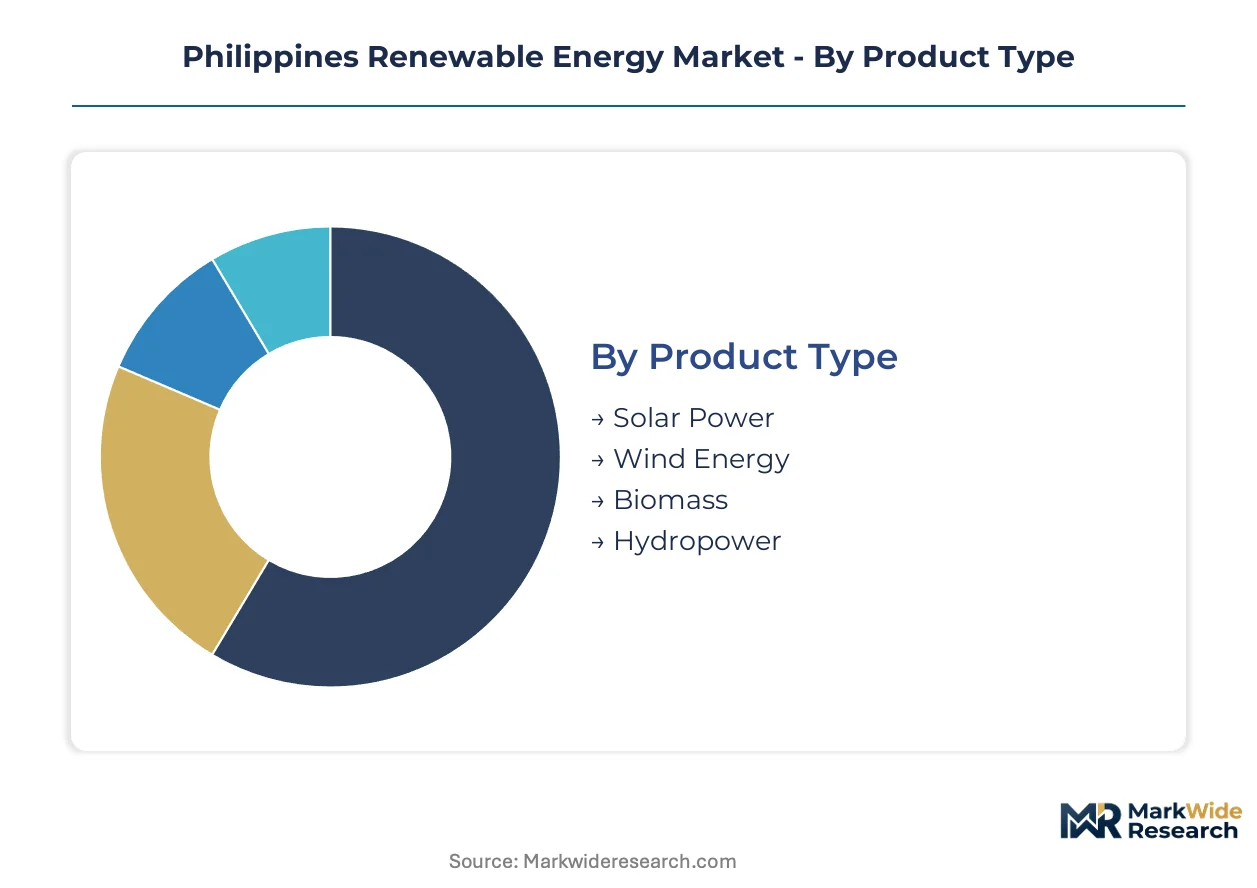
Segmentation reveals how the Philippines Renewable Energy Market stratifies across technology readiness, grid connectivity economics, and customer procurement sophistication. Each dimension carries distinct regulatory overlays from the Department of Energy and the Energy Regulatory Commission that shape capital deployment timing.
Product Type:
Solar Power and Wind Energy carry the heaviest certification burden under the Green Energy Auction Program's technical eligibility requirements, while Biomass and Hydropower face additional environmental compliance from the Department of Environment and Natural Resources.
- Solar Power:Photovoltaic arrays with 18-22% conversion efficiency dominate new capacity additions. Metro Manila commercial buyers and Cebu industrial campuses are scaling rooftop procurement to hedge volatile wholesale electricity spot market prices under the Renewable Portfolio Standard mandate.
- Wind Energy:Horizontal-axis turbines rated at 2-3 MW extract kinetic energy from consistent trade wind regimes. Northern Luzon corridor sites attract developer concentration despite National Grid Corporation of the Philippines transmission congestion forcing curtailment risk onto project sponsors.
- Biomass:Anaerobic digesters producing biogas with 50-70% methane content serve agricultural processing clusters.
- Hydropower:Low-head installations provide spinning reserves and frequency regulation to island grids.
Solar Power sits at the top of the volume ranking, with Wind Energy climbing the fastest.
Technology:
Cost tier separation distinguishes these segments, with Photovoltaic Systems and Wind Turbines occupying premium capital intensity brackets while Biofuel Conversion and Hydroelectric Plants spread across mid-range and economy tiers based on project scale.
- Photovoltaic Systems:Fixed-tilt configurations prevail where land constraints limit tracking deployment. Bifacial module penetration is accelerating yield optimization across Luzon island grid interconnection applications.
- Wind Turbines:Horizontal-axis designs rated 2-3 MW anchor northern Luzon developments. Trade wind consistency in the corridor supports capacity factor performance that competes with geothermal baseload economics.
- Biofuel Conversion:Agricultural residue processing serves provincial milling operations.
- Hydroelectric Plants:Run-of-river designs dominate Cordillera Administrative Region rehabilitation opportunities.
Photovoltaic Systems command the largest installed base, with Wind Turbines expanding most quickly.
End User:
Customer type segmentation maps directly to procurement sophistication and contract structure complexity, with Industrial and Commercial buyers driving long-term power purchase agreement innovation while Residential and Agricultural segments navigate simpler net metering frameworks.
- Residential:Single-meter rooftop installations dominate Metro Manila condominium associations. The Energy Regulatory Commission's revised net metering rules now enable multi-tenant aggregation models previously blocked by metering restrictions.
- Commercial:Business process outsourcing campuses in Cebu and manufacturing facilities in Laguna Technopark execute direct bilateral contracts. Food and beverage processors leverage the Green Energy Option Program to displace traditional utility supply arrangements.
- Industrial:Semiconductor fabricators in Cavite enforce Scope 2 emissions reduction targets through centralized supply chain mandates from parent companies.
- Agricultural:Central Luzon rice-growing regions pilot agrivoltaic arrays beneath elevated panel structures.
Commercial buyers sit at the top of the volume ranking, with Industrial procurement climbing the fastest.
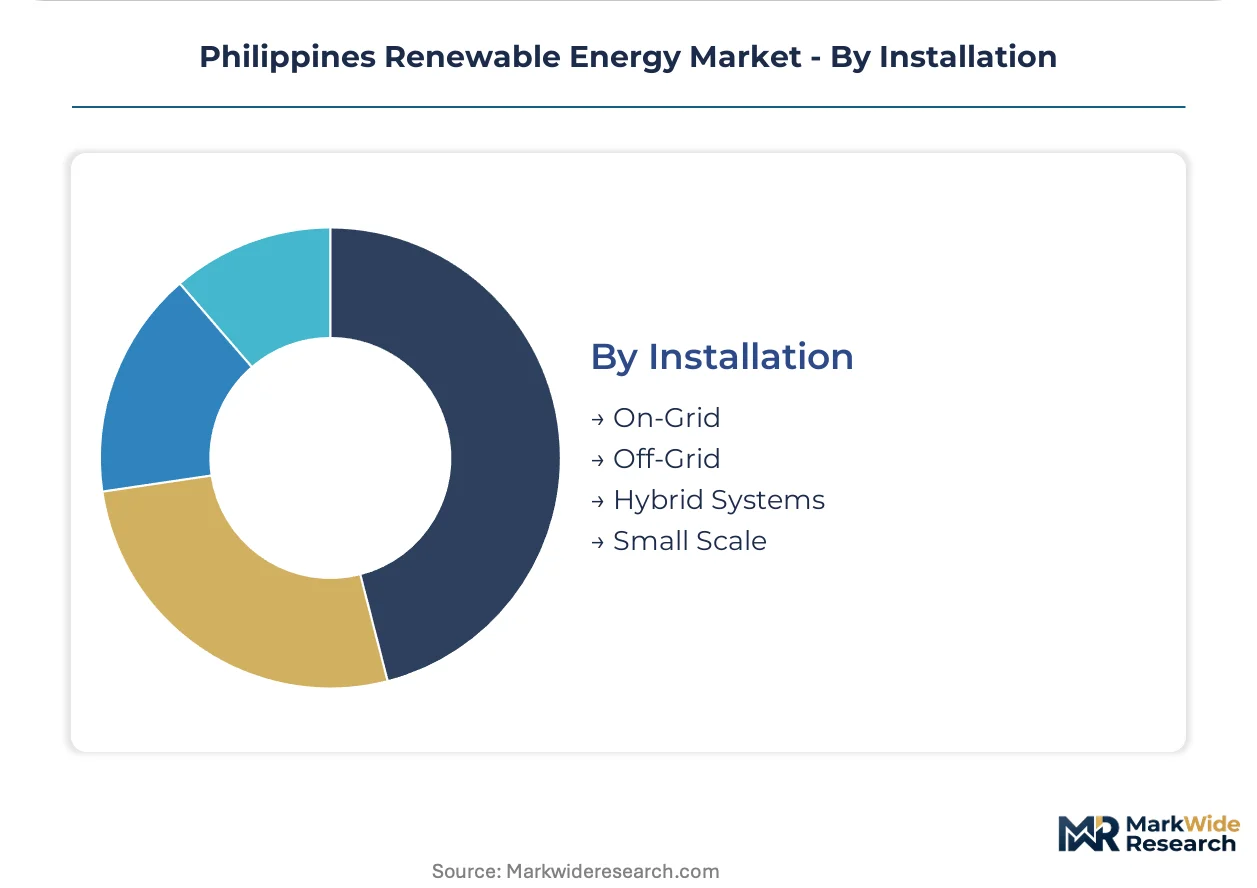
Installation:
Geography and grid maturity shape this segmentation, with On-Grid installations concentrated in Luzon and Visayas transmission corridors while Off-Grid and Hybrid Systems penetrate Mindanao's electrification gaps and remote Palawan municipalities.
- On-Grid:Utility-scale solar farms interconnect through National Grid Corporation of the Philippines substations. Developers face extended commissioning timelines from revised fault ride-through standards for inverter-based resources.
- Off-Grid:Diesel generator substitution economics challenge solar-plus-storage deployment in Mindanao and Palawan remote island grids. Battery capital requirements exceed diesel operating costs at current price levels.
- Hybrid Systems:Dual-fuel backup configurations retain structural importance for frequency regulation.
- Small Scale:Distributed renewable microgrids target the 68% household electrification rate gap in southern island municipalities.
On-Grid installations sit at the top of the volume ranking, with Off-Grid deployment climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
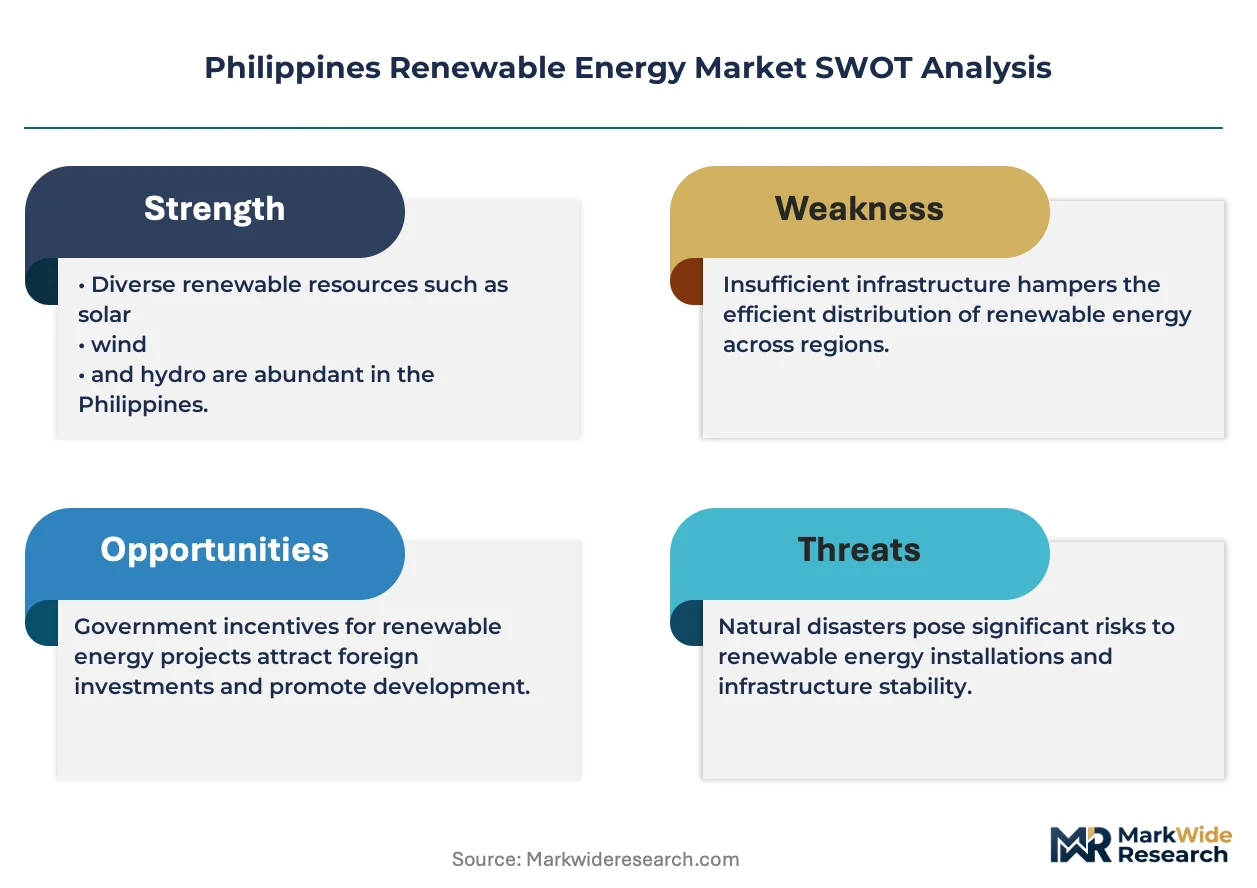
Regulatory arbitrage is redirecting renewable energy capital toward Philippine sub-regions where permitting velocity and grid access economics diverge most sharply from Metro Manila congestion. Developers exploit cost-of-compliance gaps between Luzon's mature transmission corridors and Mindanao's electrification deficit zones.
Luzon
Metro Manila commercial buyers and Cavite semiconductor fabricators drive rooftop solar procurement under the Renewable Portfolio Standard mandate. The Department of Energy's Green Energy Auction Program streamlines utility-scale permitting for fixed-tilt photovoltaic arrays. Northern Luzon wind corridor sites face National Grid Corporation of the Philippines transmission congestion forcing curtailment risk onto project sponsors.
Visayas
Cebu business process outsourcing campuses scale behind-the-meter photovoltaic systems to hedge volatile wholesale electricity spot market prices. Leyte and Negros islands unlock high-enthalpy geothermal reservoirs through volcanic terrain mapping advances. Negros Occidental sugar milling clusters anchor agricultural residue biogas deployment.
Mindanao
The southern island's 68% household electrification rate lags national averages, concentrating demand for distributed renewable microgrids in off-grid municipalities. Diesel generator substitution economics challenge solar-plus-storage capital requirements against current battery prices. Davao del Sur industrial zones attract hybrid system developers targeting frequency regulation contracts.
Palawan
Remote island grids retain dual-fuel backup configurations due to solar-plus-storage deployment costs exceeding diesel operating economics. Puerto Princesa tourism corridors drive commercial rooftop solar adoption under net metering aggregation rules. The Energy Regulatory Commission's revised multi-tenant frameworks enable condominium association pooling previously blocked by single-meter restrictions.
Central Luzon
Rice-growing regions pilot agrivoltaic arrays beneath elevated panel structures, compressing land competition between food security and energy security objectives. Pampanga and Tarlac manufacturing facilities execute direct bilateral power purchase agreements with solar farm operators. The Department of Agriculture's standardized lease frameworks accelerate agricultural land-use dualization.
Philippines Renewable Energy Market Competitive Landscape
Luzon-anchored integrated power producers occupy the premium development tier; Visayas-based geothermal specialists hold baseload stability positions. The market structure concentrates around three strategic archetypes: diversified conglomerates with multi-island development platforms, pure-play renewable independent power producers, and international project sponsors backed by development finance guarantees. Competitive moves center on long-term power purchase agreement tenor compression and transmission capacity reservation at National Grid Corporation of the Philippines substations.
Within the integrated conglomerate tier, ACEN Corporation and Aboitiz Power Corporation exemplify multi-technology portfolio diversification across solar, geothermal, and run-of-river hydropower assets. Energy Development Corporation occupies a specialized position in volcanic terrain resource extraction. These three entities anchor the competitive landscape through distinct geographic and technological positioning rather than overlapping market contestation.
| Leading Market Players |
|---|
| ACEN Corporation |
| Aboitiz Power Corporation |
| Energy Development Corporation |
| Citicore Renewable Energy Corporation |
| First Gen Corporation |
| Solar Philippines Power Project Holdings Inc. |
| Vena Energy |
| Terra Solar Philippines |
| Alternergy Holdings |
| Others |
Value Network & Pricing Analysis
Commercial and industrial buyers in Philippine Economic Zone Authority enclaves concentrate procurement leverage, anchoring contract-based long-term offtake structures that dominate utility-scale solar and geothermal transactions. This buyer archetype's aggregation of demand into multi-year power purchase agreements compresses spot market exposure while transferring development risk onto independent power producers.
Pricing Analysis
Direct-to-OEM discount structures prevail for semiconductor fabricators in Cavite and food processors in Laguna Technopark executing bilateral contracts with solar farm operators. Three-tier pricing structure across premium, standard, and economy levels separates merchant power purchase agreements backed by international development finance guarantees from traditional utility offtake and net-metered rooftop installations. Price differentiation rests on certification grade under the Green Energy Auction Program's technical eligibility requirements and volume scale of grid interconnection capacity reservations. Cost compression in standard-tier utility-scale solar is intensifying because module imports comprise over ninety percent of project equipment costs, exposing developers to Chinese ingot and wafer pricing volatility. Commercial buyers demonstrate lowest price sensitivity due to Scope 2 emissions mandates from parent companies, while agricultural cooperatives piloting agrivoltaic arrays exhibit highest sensitivity to lease rate fluctuations.
Supply Chain Analysis
Certification under the Department of Energy's Renewable Portfolio Standard and the Green Energy Auction Program's technical eligibility requirements gates equipment procurement for all grid-interconnected projects. Geographic supply concentrates in China for photovoltaic modules and inverters, in Germany and Denmark for wind turbine components, and domestically for run-of-river hydropower civil works. Raw material dependencies include polysilicon ingots and wafers, lithium-ion battery cells for hybrid storage configurations, and specialized steel alloys for geothermal drilling equipment. Supply chain risk centers on single-source vulnerability for polysilicon supply given Chinese market concentration and Philippine developers' limited supplier diversification. Distribution runs through engineering-procurement-construction contractors with National Grid Corporation of the Philippines interconnection expertise, who bundle equipment sourcing with commissioning services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Philippines renewable energy market reads as a late-cycle quality story where procurement sophistication among commercial and industrial buyers is forcing independent power producers toward merchant power purchase agreement structures with enhanced bankability requirements.
For Market Incumbents: Hedge against transmission congestion curtailment risk by securing substation capacity reservations at National Grid Corporation of the Philippines interconnection points ahead of competing developers. Deepen backward integration into geothermal drilling capabilities to reduce exposure to premium day rates charged by specialized directional drilling contractors with volcanic formation experience. Reinforce portfolio resilience through run-of-river hydropower assets that provide spinning reserves and frequency regulation services unavailable from inverter-based solar and wind resources. For New Entrants and Emerging Players: Begin with distributed renewable microgrid deployment in Mindanao's off-grid municipalities where household electrification rates lag national averages and diesel substitution economics remain unfavorable for solar-plus-storage at current battery prices. Target agricultural processing clusters in Negros Occidental for biogas anaerobic digester installations leveraging existing sugar milling residue streams. Pursue agrivoltaic lease frameworks in Central Luzon rice-growing regions where the Department of Agriculture's standardized dual-use land agreements compress traditional food-energy competition tensions. For Investors and Strategic Acquirers: Integrated conglomerates with multi-island development platforms are the most active acquirers in this space, seeking to replicate ACEN Corporation's geographic diversification and Aboitiz Power Corporation's multi-technology portfolio balance. Acquisition target archetypes include pure-play solar independent power producers with contracted capacity under the Green Energy Auction Program and geothermal specialists with unclassified high-enthalpy reservoir portfolios in Leyte and Negros. The signal to watch is Energy Regulatory Commission feed-in tariff ceiling adjustments that accelerate migration toward merchant power purchase agreement structures and strain project finance viability for undercapitalized developers.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement | Long-term offtake contracts with Philippine Economic Zone Authority manufacturers anchor project finance structures. |
| Capacity Buildout | Utility-scale solar farm development under the Green Energy Auction Program streamlines permitting timelines. |
| Backward Integration | In-house geothermal drilling capabilities reduce exposure to scarce volcanic formation contractor premiums. |
| Green Certification Program | Renewable Portfolio Standard compliance certification unlocks distribution utility procurement mandates. |
| Technology Licensing | Bifacial photovoltaic module technology licensing accelerates yield optimization on fixed-tilt installations. |
Research Methodology
Bottom-up commercial and industrial buyer modeling reconciled against top-down generation capacity tracking forms the analytical core of this study. Primary interviews with utility planning officers at distribution utilities, independent power producer project developers, engineering-procurement-construction contractors, National Grid Corporation of the Philippines interconnection specialists, and fuel supply specialists for diesel backup systems were validated against secondary sources including Department of Energy auction announcements, Energy Regulatory Commission tariff rulings, National Grid Corporation of the Philippines transmission development plans, and project finance database tracking of power purchase agreement executions.
Input-output matrix framing connects macroeconomic drivers to segment-level capacity deployment across the projection horizon. The analytical framework models technology type, generation capacity tier, project scale, regulatory framework, and regional grid type as core segmentation dimensions. CAGRs were derived from capacity addition trajectories reconciled against interconnection queue processing rates and auction schedule releases. Industry-specific forecast inputs include Green Energy Auction Program bidding participation rates and Renewable Portfolio Standard compliance deadline proximity effects on procurement acceleration.
Several conditions sit outside the modeled scope, including unannounced revisions to feed-in tariff ceilings, unplanned National Grid Corporation of the Philippines transmission infrastructure delays, and abrupt polysilicon supply chain disruptions. Forecasts reflect assumptions regarding auction schedule adherence and interconnection capacity allocation efficiency that material regulatory or logistical friction could invalidate. A model refresh is warranted upon material change in Department of Energy auction calendar releases or Energy Regulatory Commission net metering rule revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Iran Renewable Energy Market
Renewable Energy
Biogas Plant Market
Renewable Energy
Philippines Power Market
Renewable Energy
Kazakhstan Renewable Energy Market
Renewable Energy
Solar Panel Mounting Structure Market
Renewable Energy
Solar Boat Market
Renewable Energy
Russian Federation Renewable Energy Market
Renewable Energy
North America Solar Tracker Market
Renewable Energy
Singapore Renewable Energy Market
Renewable Energy
Hydrokinetic Converters Market
Renewable Energy
Hydroelectric Cells Market
Renewable Energy
North Africa Renewable Energy Market
Renewable Energy
Solar Farm Market
Renewable Energy
Solar Oven Market
Renewable Energy
Renewable Energy Consulting Market
Renewable Energy
Romania Renewable Energy Market