
 Solar Cooker Market | 2026-2036
Solar Cooker Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Cooker Market Analysis
Market Context with Strategic Players
Aluminum reflective sheeting is restructuring cost profiles across solar cooker manufacturing by displacing polished stainless steel in panel and parabolic designs. GoSun Inc leverages proprietary vacuum tube technology to sustain premium positioning in portable hybrid cookers. SunFire Solutions anchors Southern African distribution through established NGO procurement channels. Rudra Solar Energy dominates India's institutional segment with large-scale box cooker deployments for community kitchens.
Technical Definition and Structural Segments
A solar cooker is a thermal device that concentrates or traps solar radiation using reflective surfaces and insulated chambers to achieve cooking temperatures between 90°C and 200°C without fuel combustion, primarily serving energy-deficient households and outdoor users seeking fossil-fuel alternatives. Parabolic cookers lead in thermal efficiency for commercial and institutional buyers due to faster boil times, while panel cookers represent the fastest-growing category among camping enthusiasts and disaster relief organizations seeking collapsible, lightweight designs. Box cookers occupy the mature household segment where margin pools concentrate on durable insulation materials and weather-resistant glazing.
Regulatory Frame and Forward Outlook
The Bureau of Indian Standards (BIS) mandates performance testing for solar cookers sold through government subsidy programs, while Kenya's Energy Regulatory Authority sets thermal efficiency benchmarks for products distributed under national clean cooking initiatives, and ISO 9806 standards govern solar thermal collector testing across export markets. Stakeholders must monitor how evolving carbon credit methodologies for avoided emissions from clean cooking could reshape procurement financing and manufacturer revenue models.
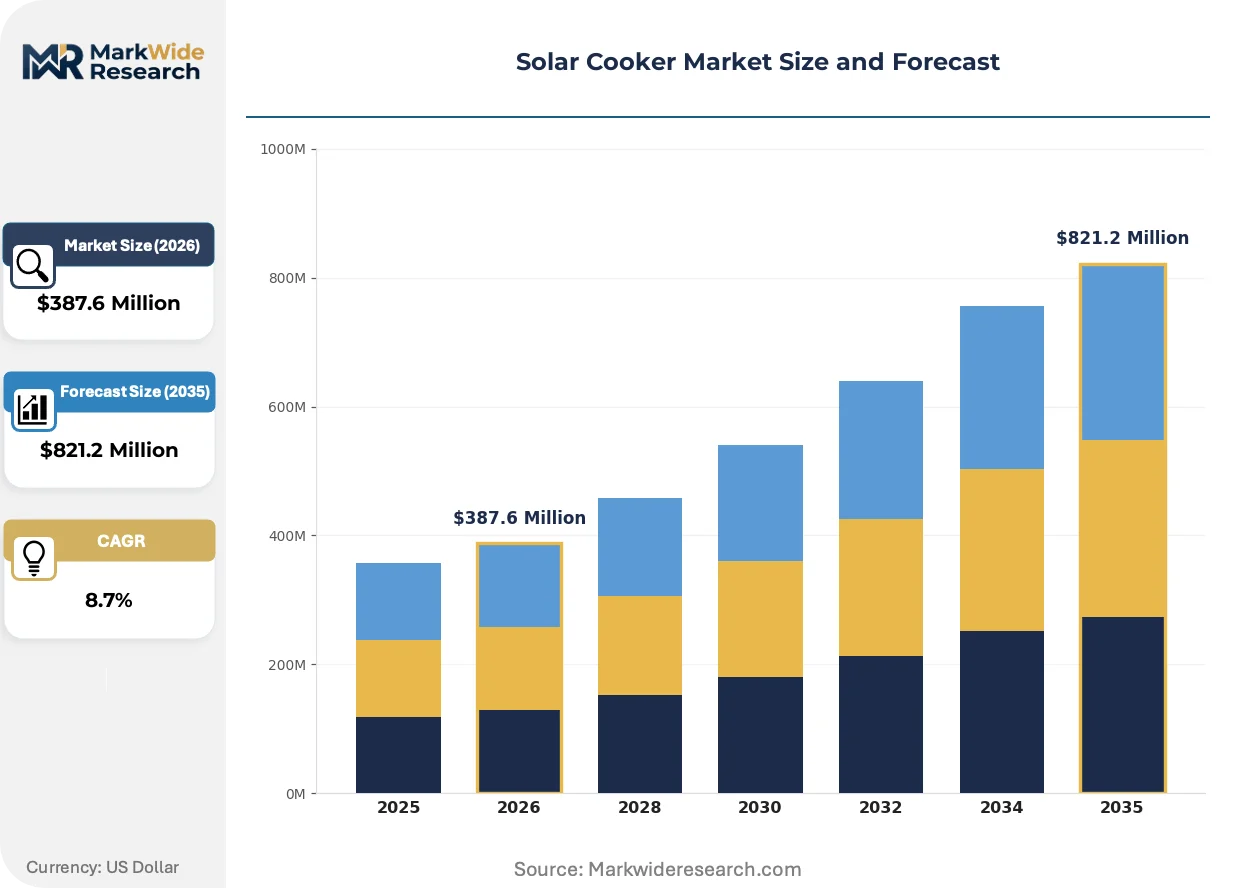
Market Dynamics
Aluminum reflective sheeting is compressing manufacturing costs across panel and parabolic cooker designs while BIS certification requirements in India are forcing quality standardization that separates subsidized from informal supply channels.
Growth Catalysts
- Kenya's Clean Cooking Initiative:National procurement programs channel institutional funding through NGO distribution networks, accelerating household penetration of certified parabolic designs in off-grid regions.
- ISO 9806 Testing Protocols:Standardized thermal performance benchmarks enable cross-border trade by reducing technical barriers for exporters entering multiple subsidy regimes.
- Vacuum Tube Hybridization:Integration of evacuated glass tubes into portable cooker architectures extends operating hours into evening periods, expanding addressable use cases beyond midday solar windows.
Market Restraints
- Aluminum Price Volatility:Reflective sheet metal constitutes the dominant material cost in panel cooker production, exposing manufacturers to commodity swings without pass-through mechanisms in fixed-price government tenders.
- Seasonal Insolation Variability:Technical performance degrades substantially outside equatorial latitudes, limiting year-round reliability in temperate zones and constraining addressable geography.
- Biogas Digester Subsidies:Competing clean cooking infrastructure in South Asia and East Africa captures overlapping rural household segments through established livestock-waste supply chains.
Strategic Opportunities
- Carbon Credit Methodologies:Emerging verification frameworks for avoided emissions from displaced biomass cooking could unlock results-based financing for large-scale deployment programs.
- Refugee Camp Catering:Institutional procurement by UNHCR and WFP for displacement settlements in Uganda and Ethiopia creates concentrated demand for durable box cooker arrays with standardized maintenance protocols.
- Mobile-Enabled Distribution:Pay-as-you-go platforms originally developed for solar home systems are adapting to cooker financing, reducing upfront barriers for cash-constrained rural buyers.
Industry Challenges
- Thermal Engineer Scarcity:Design optimization for local insolation patterns requires specialized expertise in optical geometry and materials science that concentrates in a handful of research institutions.
- BIS Certification Timelines:Laboratory testing queues in India extend product approval cycles, delaying market access for manufacturers targeting government subsidy windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Cooker Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Box Cookers, Panel Cookers, Parabolic Cookers, Hybrid Cookers Application: Household Use, Commercial Use, Emergency Preparedness, Outdoor Cooking Technology: Reflective Materials, Insulation Techniques, Heat Retention, Energy Conversion End User: Residential Users, Camping Enthusiasts, Disaster Relief Organizations, Environmental NGOs |
| Companies Covered | SunSpot Solar Ovens, Sunflair Solar Ovens, GoSun Inc, All American Sun Oven, SolSource, SunFire Solutions, Solar Brother, Rudra Solar Energy, Global Sun Oven, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Cooker Market Emerging Trajectories
Material substitution and regulatory harmonization are compressing cost curves while digital distribution platforms are opening new channel economics for last-mile penetration.
Collapsible panel cooker architectures are modularizing around standardized aluminum frame components and interchangeable reflective film sheets. Disaster relief organizations and camping equipment retailers are adopting these flat-pack designs for inventory efficiency. The shift is modularizing supply chains by decoupling frame manufacturing from reflective surface production, enabling regional assembly near demand clusters.
Kenya's Energy Regulatory Authority thermal efficiency benchmarks are mandating minimum performance thresholds for products distributed under national clean cooking programs. Manufacturers must now submit third-party test reports documenting boil times and heat retention metrics. The policy is compressing informal supply by excluding uncertified imports from subsidized procurement channels.
Institutional buyers in community kitchen programs are consolidating vendor relationships around integrated service contracts covering installation, training, and maintenance. Traditional equipment-only transactions are losing share to multi-year performance agreements. This pattern is most visible in India's midday meal schemes, where state governments prioritize suppliers with established service networks over lowest-bid equipment pricing.
Solar Cooker Market Segmentation
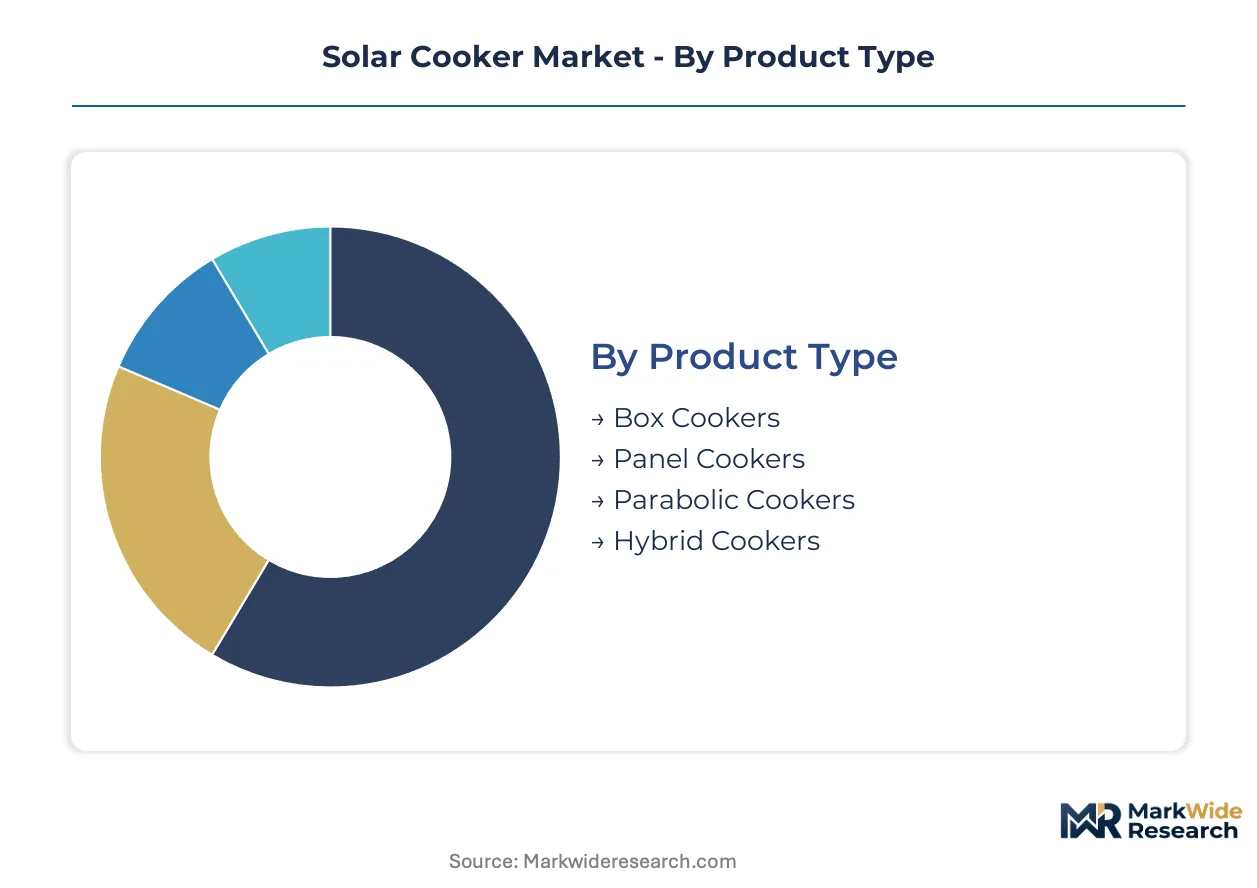
Segmentation in the solar cooker market reveals how capital deployment, technical complexity, and distribution economics split across radically different use cases—from low-cost emergency relief to precision-engineered institutional systems.
Product Type:
Capital intensity varies sharply: parabolic designs demand optical-grade aluminum forming and tracking mechanisms, while panel cookers minimize fixed tooling through flat-pack architectures.
- Box Cookers:Insulated chamber designs with double-glazed lids achieve 90°C to 150°C operating temperatures through passive solar trapping. Kenya's rural households under national clean cooking initiatives drive procurement volumes, though thermal inertia limits cooking flexibility to slow-cook applications.
- Parabolic Cookers:Concentrating reflector geometries focus radiation to focal points exceeding 200°C, enabling rapid boiling and frying. Commercial buyers in India's institutional midday meal schemes prioritize these systems for throughput, accepting higher per-unit costs against labor savings.
- Panel Cookers:Collapsible reflective surfaces fold to briefcase dimensions for backpack portability.
- Hybrid Cookers:Vacuum tube integration extends operating hours past sunset through stored thermal energy.
Most installed capacity flows through Box Cookers. Expansion is steepest in Panel Cookers.
Application:
Volume concentration skews toward subsidized household programs, while margin pools concentrate in institutional service contracts with multi-year performance terms.
- Household Use:Off-grid rural families in Sub-Saharan Africa represent the core addressable base, with procurement channeled through NGO distribution networks and government voucher programs. BIS certification requirements in India now exclude informal suppliers from subsidy eligibility.
- Commercial Use:Community kitchens, schools, and religious institutions require durable arrays with standardized maintenance protocols. Indian state governments increasingly bundle equipment with installation and training under integrated service contracts.
- Emergency Preparedness:UNHCR and WFP procurement for displacement settlements in Uganda and Ethiopia creates surge demand for rapid-deployment box cooker arrays.
- Outdoor Cooking:Camping retailers and adventure tourism operators source lightweight panel designs for recreational markets.
Commercial Use commands the highest average contract values. Emergency Preparedness shows the most volatile demand spikes.
Technology:
Material science differentiation separates premium positioning from commodity competition, with optical performance and thermal persistence as the core technical battlegrounds.
- Reflective Materials:Anodized aluminum sheeting is displacing polished stainless steel across panel and parabolic manufacturing, compressing per-unit costs by 30-40% while maintaining 85%+ reflectivity. Commodity price exposure concentrates risk in fixed-price government tenders.
- Insulation Techniques:Rock wool and aerogel composites in box cooker walls determine heat retention duration. Kenyan thermal efficiency benchmarks now mandate minimum R-values for certified products.
- Heat Retention:Phase-change materials and vacuum insulation panels extend cooking windows beyond peak insolation hours.
- Energy Conversion:Photovoltaic-thermal hybrid systems convert surplus radiation to electricity for device charging.
Reflective Materials absorb the largest share of manufacturing cost. Heat Retention is gaining R&D priority for evening-use extension.
End User:
Customer sophistication spans from price-sensitive rural households to technical buyers with ISO 9806 compliance requirements and carbon credit verification needs.
- Residential Users:Cash-constrained rural households in Kenya and India dominate unit volumes, with pay-as-you-go financing platforms reducing upfront barriers. Seasonal insolation variability constrains year-round reliability outside equatorial latitudes.
- Camping Enthusiasts:Recreational buyers in North American and European markets prioritize packability and rapid setup over thermal efficiency, accepting extended cook times for portability.
- Disaster Relief Organizations:UN agencies and international NGOs procure standardized box cooker arrays with documented spare parts availability and training protocols.
- Environmental NGOs:Carbon credit project developers seek verified emission reductions from displaced biomass cooking, requiring third-party monitoring and reporting infrastructure.
Residential Users account for the greatest installed base. Environmental NGOs are emerging as the most technically demanding customer segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kenya's off-grid rural corridors anchor procurement volumes for parabolic and box cooker designs distributed through national clean cooking initiatives and NGO networks.
Kenya
Rural households in arid and semi-arid lands drive demand for durable box cookers under the national clean cooking strategy. The Energy Regulatory Authority mandates thermal efficiency benchmarks for all subsidized products. Manufacturing activity clusters in Nairobi's industrial zone, where local assemblers integrate imported reflective materials with domestically fabricated insulation housings.
India
State midday meal schemes and community kitchen programs generate institutional demand for high-throughput parabolic systems. The Bureau of Indian Standards certification requirement excludes uncertified suppliers from government procurement channels. Production concentrates in Gujarat and Rajasthan, where solar thermal component ecosystems support integrated manufacturing of reflective surfaces and insulated chambers.
United States
Camping equipment retailers and disaster preparedness agencies source lightweight panel cookers for recreational and emergency stockpiling. No federal certification mandates exist, though ISO 9806 compliance supports export eligibility. Design and distribution activity centers in Colorado and California, where outdoor recreation brands and humanitarian logistics firms co-locate product development with Western consumer markets.
Ethiopia
Refugee settlements and displacement camps create concentrated demand for rapid-deployment box cooker arrays funded by UNHCR and WFP programs. The country's national energy policy prioritizes off-grid clean cooking solutions in rural development corridors. Distribution networks radiate from Addis Ababa, where international NGO procurement hubs coordinate last-mile deployment to the Somali and Gambella regions.
South Africa
SunFire Solutions anchors Southern African distribution through established NGO procurement channels serving peri-urban informal settlements. The national energy regulator maintains voluntary performance standards without mandatory certification. Manufacturing and assembly operations concentrate in Gauteng province, leveraging existing metalworking infrastructure for reflective component fabrication.
Solar Cooker Market Vendor Landscape
Global majors compete with regional champions across distribution channel access, with vacuum tube technology specialists, aluminum reflective sheet fabricators, and institutional service providers occupying distinct strategic tiers. Market structure tilts toward fragmentation due to low capital barriers in panel cooker assembly and geographic fragmentation of subsidy programs. Three archetypes dominate: technology licensors with proprietary thermal designs, regional assemblers serving government tender markets, and humanitarian logistics specialists managing NGO procurement relationships. Competitive moves concentrate on backward integration into reflective material production and multi-year service contract bundling.
Among North American portable equipment developers, GoSun Inc and Sunflair Solar Ovens exemplify the premium-tier vacuum tube and collapsible panel archetypes respectively. SunFire Solutions occupies a position within the regional distribution specialist tier, while Rudra Solar Energy represents the institutional-scale fabricator archetype serving government meal programs. These named entities anchor broader patterns of technology differentiation and channel specialization without exhaustively mapping competitive positions.
| Leading Market Players |
|---|
| SunSpot Solar Ovens |
| Sunflair Solar Ovens |
| GoSun Inc |
| All American Sun Oven |
| SolSource |
| SunFire Solutions |
| Solar Brother |
| Rudra Solar Energy |
| Global Sun Oven |
| Others |
Supply Flow & Price Mechanics
Aluminum reflective sheeting costs cascade through solar cooker manufacturing tiers, with commodity-grade anodized sheet anchoring economy panel designs while optical-grade formed aluminum commands premium positioning in institutional parabolic systems distributed through Kenyan government tenders.
Pricing Analysis
Input-cost pass-through from aluminum commodity markets shapes contract competitiveness, with manufacturers absorbing volatility in fixed-price BIS-certified tenders while passing swings through in commercial segments. Pricing stratifies across premium vacuum-tube hybrids, standard certified box cookers, and economy collapsible panels. Price compression intensifies in Kenyan national procurement channels where thermal efficiency benchmarks disqualify higher-cost uncertified imports. Cash-constrained rural households exhibit highest price sensitivity, while UNHCR institutional buyers prioritize durability over unit cost.
Supply Chain Analysis
Freight costs from Chinese aluminum rolling mills to Indian and Kenyan assembly plants constitute material inbound logistics exposure, with container rate volatility affecting landed costs for reflective sheeting. Manufacturing concentrates in India, Kenya, and South Africa, with component sourcing drawing from Chinese aluminum suppliers and domestic insulation fabricators. Single-source dependency on Guangdong province reflective film producers creates tariff vulnerability. Distribution runs through NGO procurement networks in East Africa and government tender channels in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in aluminum backward integration and vacuum-tube premium tier migration, with material cost control and thermal performance differentiation as the dual levers.
For Market Incumbents: Cement channel control in Kenyan NGO networks and Indian state meal schemes through multi-year service contract bundling that locks out price-only competitors. Deepen captive supply of reflective aluminum components to offset commodity volatility in fixed-price government tenders. Prioritize BIS certification maintenance as regulatory barriers stiffen against informal imports. For New Entrants and Emerging Players: Pay-as-you-go mobile platforms offer a direct-to-household route around established NGO distribution gatekeepers in Kenyan rural markets. Target refugee camp catering procurement in Ethiopia and Uganda where standardized box cooker arrays face limited qualified bidders. Pursue carbon credit methodology alignment as a financing wedge for large-scale deployment programs. For Investors and Strategic Acquirers: Consolidation pressure builds where regional assemblers lack backward integration into reflective materials and struggle to meet tightening thermal efficiency mandates. Long-term viability favors vertically integrated manufacturers with captive aluminum forming and established government tender relationships. Watch for Kenya Energy Regulatory Authority benchmark revisions as inflection signals for technical compliance costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Reflective Aluminum | Captive supply of anodized sheeting insulates margins from commodity volatility in Kenyan tenders. |
| Multi-Year Service Contract Bundling | Installation and maintenance integration locks out price-only competitors in Indian midday meal schemes. |
| Vacuum Tube Hybrid Product Launch | Evening-use extension captures premium positioning among institutional buyers seeking thermal persistence. |
| Carbon Credit Methodology Alignment | Verified emission reduction frameworks unlock results-based financing for large-scale rural deployment. |
| Mobile-Enabled Distribution Partnership | Pay-as-you-go platforms reduce upfront barriers for cash-constrained households in off-grid regions. |
Methodological Framework
Multiple input streams — primary interviews with solar thermal equipment manufacturers, procurement officers at Kenyan Energy Regulatory Authority, and distribution leads at Indian NGO networks; secondary validation through BIS certification databases, UNHCR procurement records, and aluminum trade flow data; plus technical literature on ISO 9806 testing protocols — were reconciled through bottom-up and top-down triangulation to establish market sizing and growth parameters.
Data-stream reconciliation across product type, application, technology, and end-user dimensions supported analytical framework construction over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by pricing tier evolution. Forecast inputs incorporated Kenyan clean cooking initiative procurement schedules, Indian state subsidy allocation patterns, and aluminum price scenario modeling.
The model assumes a particular technology adoption path; alternative pathways for vacuum tube hybridization would alter the outlook if cost curves compress faster than projected. Forecasts reflect documented assumptions on regulatory enforcement intensity and NGO funding continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Europe Single-Axis Solar Tracker Market
Renewable Energy
Renewable Energy Cable Market
Renewable Energy
Solar Boat Market
Renewable Energy
North America Renewable Energy Market
Renewable Energy
Ocean Power Market
Renewable Energy
North America Solar Tracker Market
Renewable Energy
South Korea Renewable Energy Market
Renewable Energy
China Wind Power Market
Renewable Energy
Tidal Energy Generation Systems Market
Renewable Energy
Republic of Congo Renewable Energy Market
Renewable Energy
Philippines Power Market
Renewable Energy
Tidal Turbines Market
Renewable Energy
Renewable Energy Enclosures Market
Renewable Energy
South Africa Solar Energy Market
Renewable Energy
Renewable Energy Inverters Market
Renewable Energy
Solar Tree Market