
 Cryogenic Process Pumps Market | 2026-2036
Cryogenic Process Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Cryogenic Process Pumps Market Analysis
API 610 certification for centrifugal pumps in hydrocarbon services is collapsing the competitive field, leaving only manufacturers with sustained capital for qualification testing and documentation. Nikkiso Co. Ltd. leverages its deep vertical integration into superconducting motor technology for submerged LNG pumps. Ebara Corporation anchors its position through precision casting capabilities in nickel alloys for cryogenic impellers. Sulzer Ltd. competes via specialized service networks positioned near Arctic LNG terminals.
Cryogenic process pumps are engineered fluid-handling machines designed to transfer liquefied gases below minus 150 degrees Celsius, typically constructed with austenitic stainless steel or Inconel bodies to maintain ductility at thermal extremes. These pumps enable continuous circulation in LNG liquefaction trains, air separation units, and superconducting magnet cooling loops where mechanical reliability at cryogenic temperatures determines operational uptime. Submersible motor pumps capture dominant share in LNG loading applications due to elimination of dynamic seals and reduced boil-off losses. Positive displacement configurations represent the fastest-expanding category in hydrogen liquefaction pilot plants where precise flow control at 20 Kelvin proves critical. Centrifugal architectures remain the mature margin pool, though price pressure from standardized API designs compresses differentiation space.
The US EPA enforces methane leakage thresholds under IRA-mandated emissions fees that directly shape pump seal specifications and monitoring requirements. Japan's METI coordinates national hydrogen roadmaps that fund cryogenic pump R&D through designated technology institutes. China's GB standards for cryogenic equipment impose local content rules that condition market access for imported systems. Stakeholders must monitor how hydrogen liquefaction scale-up reshapes material specifications and qualification protocols before committing to capacity expansion.
Market Dynamics
API 610 certification requirements for hydrocarbon service pumps are consolidating the competitive field, forcing sustained capital investment in qualification testing and documentation that only well-capitalized manufacturers can absorb.
Growth Catalysts
- LNG liquefaction capacity expansion:US Gulf Coast terminal operators are scaling liquefaction trains, creating concentrated demand clusters in Texas and Louisiana for high-reliability submerged motor pumps.
- Japan's METI hydrogen roadmap:National funding through designated technology institutes accelerates cryogenic pump R&D for hydrogen liquefaction applications below 20 Kelvin.
- US EPA methane regulations:IRA-mandated emissions fees tighten leakage thresholds, mandating advanced seal specifications and continuous monitoring systems that upgrade installed base requirements.
Market Restraints
- Nickel alloy supply concentration:Precision casting capacity for cryogenic-grade Inconel impellers concentrates among a handful of specialized foundries, creating input bottlenecks during capacity ramps.
- Extended API 610 qualification timelines:Documentation and testing protocols for hydrocarbon service certification stretch 18-24 months, delaying new entrant market entry.
- China's GB local content rules:Mandatory domestic sourcing thresholds for cryogenic equipment condition market access, fragmenting procurement options for multinational operators.
Strategic Opportunities
- Arctic LNG terminal service networks:Specialized maintenance and spare parts logistics positioned near remote liquefaction sites in northern Russia and Norway capture premium aftermarket value.
- Hydrogen liquefaction pilot scale-up:Positive displacement pump architectures optimized for 20 Kelvin operation address flow control precision requirements in emerging hydrogen value chains.
- Superconducting motor integration:Convergence of submerged pump designs with high-temperature superconducting drive systems eliminates dynamic seals and reduces boil-off losses in loading applications.
Industry Challenges
- Cryogenic materials engineering talent scarcity:Specialized expertise in austenitic stainless steel and Inconel behavior at thermal extremes limits design team scaling for qualification programs.
- Legacy control system integration:Digital monitoring capabilities required by EPA methane rules must interface with existing SCADA architectures at operating LNG terminals, complicating retrofit deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryogenic Process Pumps Market |
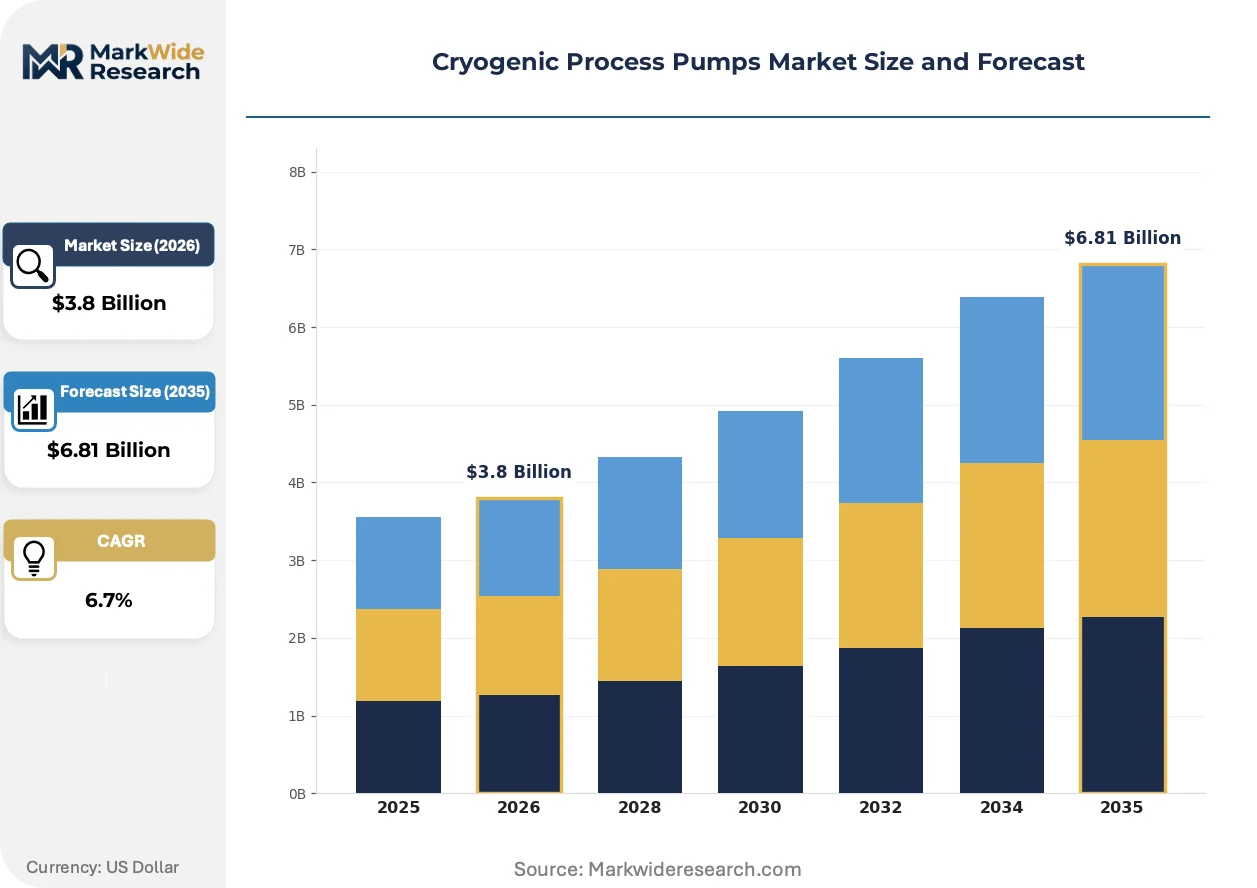
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Submersible, Centrifugal, Positive Displacement, Axial End User: Oil & Gas, Chemical Manufacturing, Energy, Research Institutions Material: Stainless Steel, Nickel Alloys, Composite Materials, Bronze Application: Liquid Nitrogen, Liquid Oxygen, LNG, Refrigeration Systems |
| Companies Covered | Nikkiso Co. Ltd., Atlas Copco AB, Ebara Corporation, Cryostar, Fives Group, Sulzer Ltd., Flowserve Corporation, Sumitomo Heavy Industries Ltd., Ruhrpumpen Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryogenic Process Pumps Market Emerging Trajectories
Active reshaping in cryogenic process pumps centers on material science advances, regulatory compliance architectures, and procurement model evolution that together redefine competitive positioning.
Superconducting motor technology is fragmenting the submerged pump category. These drive systems eliminate mechanical seals entirely, reducing methane leakage pathways that EPA regulations now penalize. LNG terminal operators in the US Gulf Coast are piloting retrofits, though qualification timelines for integrated superconducting units lag conventional designs by 12-18 months.
REACH and F-Gas Regulation amendments in Europe are tightening material disclosure requirements for cryogenic equipment containing fluorinated compounds. Manufacturers must now document full supply chain chemical content, extending procurement qualification cycles. Arctic LNG projects in Norway face particular scrutiny, driving substitution toward fluorine-free seal materials.
After-sales service unbundling is accelerating among US LNG operators. Terminal procurement teams now separate pump supply from long-term maintenance contracts, awarding service to specialized providers with regional stocking presence. This disintermediation compresses OEM margin pools while elevating independent service networks in Texas and Louisiana.
Cryogenic Process Pumps Market Segmentation
Cryogenic process pumps serve radically different thermal and pressure regimes across hydrogen liquefaction, LNG export, and air separation. Segmentation reveals where material science investments concentrate and which qualification protocols dominate procurement decisions.
Product Type:
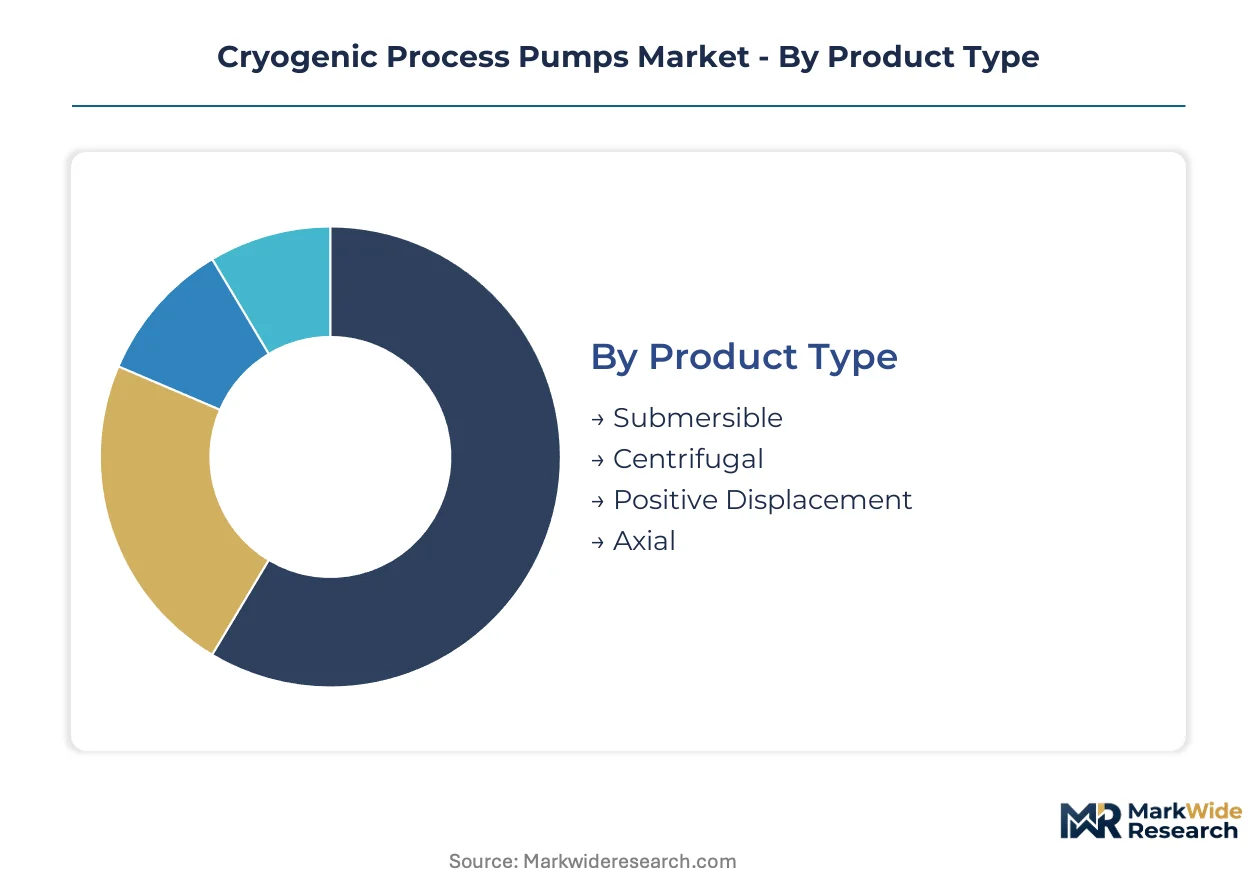
Margin pools concentrate in submerged motor architectures where seal elimination commands premium pricing from LNG terminal operators facing EPA methane penalties.
- Submersible:These pumps integrate electric motors directly into cryogenic fluid columns, eliminating dynamic seals entirely. US Gulf Coast LNG loading terminals in Texas and Louisiana are standardizing on submerged designs to minimize boil-off losses during vessel transfer operations.
- Centrifugal:Radial flow impellers in austenitic stainless steel housings handle high-volume LNG circulation in base-load liquefaction trains. API 610 certification requirements for hydrocarbon service consolidate procurement around established manufacturers with sustained qualification testing budgets.
- Positive Displacement:Precision piston or screw mechanisms deliver exact flow control at 20 Kelvin for hydrogen liquefaction pilots.
- Axial:Propeller-style impellers address low-head, high-flow applications in large-scale air separation units.
The dominant share belongs to Submersible pumps, while Positive Displacement is closing the gap fastest.
End User:
Volume concentrates in hydrocarbon processing where liquefaction train scale determines pump specification complexity and aftermarket service attachment rates.
- Oil & Gas:LNG export terminal operators drive demand for high-reliability submerged motor pumps in liquefaction and loading applications. US Gulf Coast capacity expansion in Texas and Louisiana creates concentrated procurement clusters with stringent EPA methane compliance requirements.
- Chemical Manufacturing:Ethylene crackers and ammonia synthesis plants require cryogenic circulation for feedstock pretreatment and refrigeration loops.
- Energy:Utility-scale hydrogen liquefaction facilities are emerging as a distinct buyer segment with specialized 20 Kelvin flow control requirements.
- Research Institutions:National laboratories and university physics departments operate small-batch systems for superconducting magnet cooling and particle accelerator cryogenics.
Oil & Gas commands the largest installed base, though Energy sector procurement is expanding most quickly.
Material:
Supply bottlenecks in precision nickel alloy casting constrain capacity ramps and inflate lead times for high-performance impeller applications.
- Stainless Steel:Austenitic grades 304 and 316 dominate general cryogenic service where ductility retention at minus 150 degrees Celsius suffices. Standard LNG liquefaction trains specify stainless bodies for non-impeller pressure boundary components.
- Nickel Alloys:Inconel 718 and 625 castings maintain strength and corrosion resistance at thermal extremes approaching absolute zero. Hydrogen liquefaction below 20 Kelvin mandates nickel alloy impellers where stainless embrittlement risks operational failure.
- Composite Materials:Carbon fiber reinforced polymers reduce weight in aerospace and satellite ground support equipment.
- Bronze:Aluminum bronze alloys serve specialized oxygen service where spark resistance prevents ignition hazards.
Stainless Steel retains the broadest application base, while Nickel Alloys are gaining share fastest in next-generation hydrogen infrastructure.
Application:
Regulatory pressure on methane emissions intensifies specification requirements for LNG handling equipment versus inert gas applications.
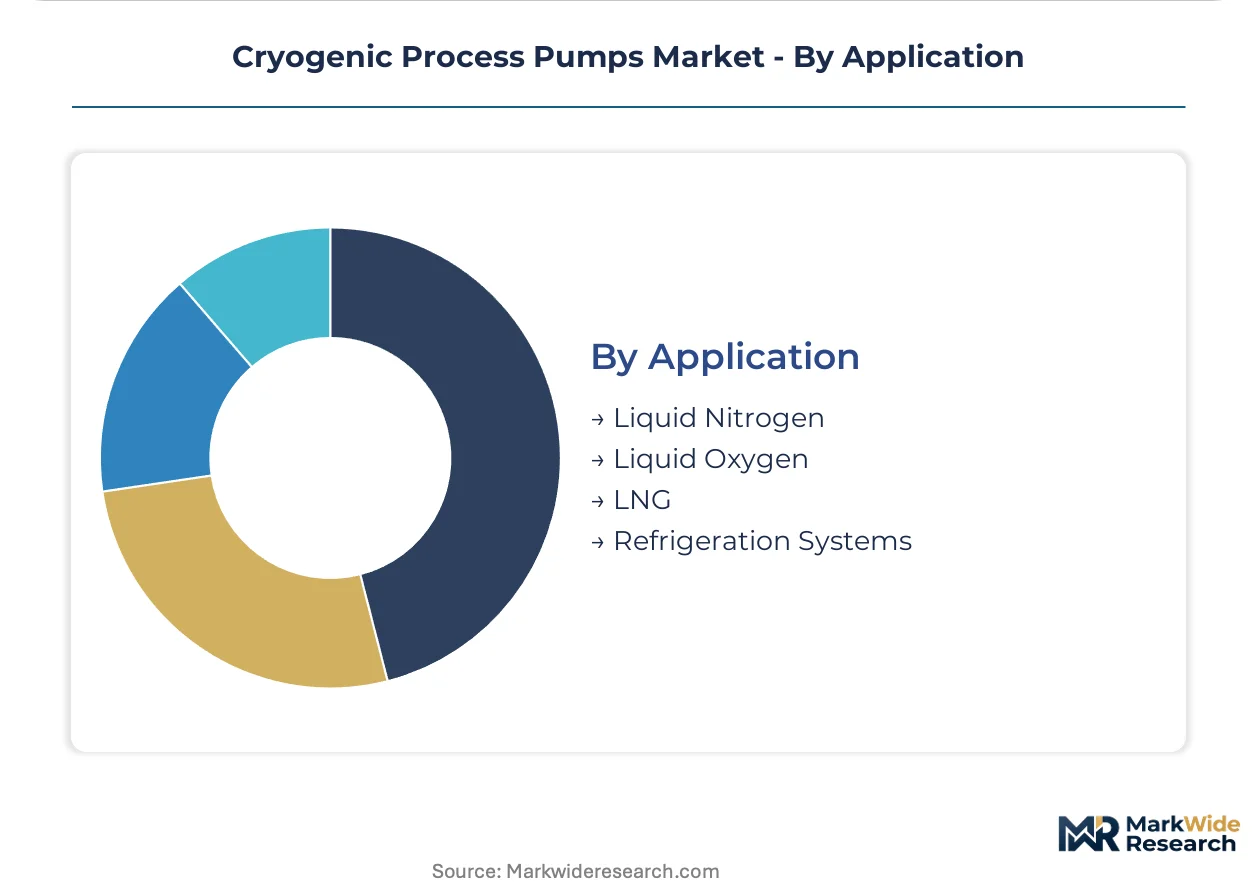
- LNG:Liquefied natural gas circulation demands submerged motor pumps with zero external leakage pathways. US EPA IRA-mandated emissions fees directly shape seal specifications and continuous monitoring system requirements for Gulf Coast terminal operators.
- Liquid Nitrogen:Inert atmosphere generation and cryogenic grinding applications utilize standardized centrifugal designs with less stringent material qualification.
- Liquid Oxygen:Aerospace launch facilities and medical gas production require oxygen-compatible materials and cleanliness protocols.
- Refrigeration Systems:Industrial cold storage and food processing employ smaller-capacity units with shorter operational cycles.
LNG holds the dominant revenue position, while Liquid Oxygen applications are climbing the fastest in aerospace procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
LNG export terminal operators in the United States concentrate procurement volumes, while hydrogen liquefaction pilots in Japan and industrial gas expansion in China diversify demand geography. Regulatory pressure on methane emissions and local content rules reshape vendor qualification requirements across major markets.
United States
Gulf Coast LNG terminal operators in Texas and Louisiana drive submerged motor pump procurement as liquefaction capacity expands. EPA methane emissions fees under the Inflation Reduction Act mandate advanced seal specifications and continuous monitoring systems. Corpus Christi and Lake Charles anchor concentrated demand clusters for high-reliability loading equipment.
Japan
National hydrogen roadmap funding accelerates cryogenic pump R&D for 20 Kelvin liquefaction applications. METI coordinates technology institute grants targeting flow control precision below liquid hydrogen temperatures. Industrial corridors near Nagoya and Osaka host pilot-scale demonstration facilities testing positive displacement architectures.
China
GB standards for cryogenic equipment impose domestic sourcing thresholds that condition market access for imported systems. State-backed air separation unit expansion and LNG receiving terminal construction sustain centrifugal pump demand. Yangtze River Delta manufacturing bases develop captive precision casting capacity for nickel alloy impellers.
Germany
REACH and F-Gas Regulation amendments tighten material disclosure requirements for fluorinated compounds in cryogenic seals. Chemical manufacturing clusters along the Rhine depend on ethylene cracker circulation pumps for feedstock pretreatment. Bavarian industrial gas specialists advance fluorine-free seal material substitution for Arctic LNG project compliance.
Norway
Arctic LNG terminal development in northern waters demands specialized service networks for remote maintenance logistics. ECHA chemical content documentation requirements extend procurement qualification cycles for offshore liquefaction equipment. Hammerfest and surrounding regions attract premium aftermarket providers positioning spare parts inventory near operational sites.
Cryogenic Process Pumps Market Vendor Landscape
Player mix skews toward diversified industrial conglomerates with sustained capital for API 610 qualification testing and documentation. The field consolidates around manufacturers with captive precision casting capabilities and established hydrocarbon service certifications. Strategic archetypes include vertically integrated pump-motor specialists, precision foundry-anchored fabricators, and service-network-differentiated providers. Competitive moves center on superconducting motor technology convergence and Arctic logistics footprint expansion.
Among Japanese industrial groups, Nikkiso Co. Ltd. and Ebara Corporation occupy positions reflecting distinct capability anchors. Nikkiso exemplifies the submerged motor specialist archetype through upstream control over superconducting drive technology. Ebara represents precision casting-anchored competition with in-house nickel alloy impeller production. Sulzer Ltd. anchors the service-network-differentiated tier, with geographic positioning near remote liquefaction sites capturing aftermarket value. Flowserve Corporation and Atlas Copco AB sit within the diversified industrial conglomerate category, leveraging broad hydrocarbon equipment portfolios to absorb qualification cost burdens.
| Leading Market Players |
|---|
| Nikkiso Co. Ltd. |
| Atlas Copco AB |
| Ebara Corporation |
| Cryostar |
| Fives Group |
| Sulzer Ltd. |
| Flowserve Corporation |
| Sumitomo Heavy Industries Ltd. |
| Ruhrpumpen Group |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts with LNG terminal operators lock in multi-year supply commitments for submerged motor pumps while anchoring price visibility through nickel alloy indexation clauses. These arrangements tie procurement costs to London Metal Exchange nickel pricing, insulating manufacturers from raw material volatility while constraining buyer flexibility.
Pricing Analysis
Cost-plus contracts with LME nickel indexation dominate procurement between precision foundries and pump OEMs. API 610 certification tier separates premium-qualified suppliers from standard-tier competitors, while volume scale drives economy-tier pricing for non-hydrocarbon applications. Price differentiation stems from certification burden and captive casting capability. Margins are tightening due to extended qualification timelines stretching 18-24 months. Chemical manufacturing buyers exhibit highest price sensitivity; LNG terminal operators prioritize reliability over unit cost.
Supply Chain Analysis
Strait of Malacca transit routes underpin nickel concentrate flows from Indonesian mining concessions to Japanese and Chinese precision foundries. Inconel 718 and 625 feedstock draws from Australian laterite ore processed through Indonesian hydrometallurgical facilities. Single-source vulnerability concentrates in specialized cryogenic-grade casting capacity at Ebara's Fujisawa facility and select Yangtze River Delta suppliers. Distribution runs through project-based direct sales to EPC contractors, with aftermarket parts flowing through regional service hubs in Texas, Louisiana, and northern Norway.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cryogenic process pumps market functions as a defensive-moat industry where EPA regulatory entrenchment creates switching costs that lock LNG terminal operators into qualified supplier relationships.
For Market Incumbents: Consolidate precision casting capacity through backward integration into nickel alloy foundry operations, securing impeller supply against Inconel bottleneck risks. Deepen API 610 documentation libraries to extend qualification lead times that deter emerging entrants. Prioritize superconducting motor R&D partnerships to preempt substitution threats from seal-elimination technologies.
For New Entrants and Emerging Players: Differentiate on hydrogen liquefaction flow control precision below 20 Kelvin, where positive displacement architectures face less entrenched competition than LNG centrifugal standards. Target Japan's METI-funded pilot facilities near Nagoya and Osaka for initial reference installations. Pursue joint development agreements with national technology institutes rather than direct OEM competition.
For Investors and Strategic Acquirers: Service-network specialists with Arctic LNG positioning command scarcity premia that compound over extended operational lifecycles. Arctic maintenance logistics providers with spare parts inventory pre-positioned near Hammerfest and northern Russian terminals represent attractive acquisition targets. Monitor EPA methane fee enforcement intensity as the signal indicating upgrade cycle acceleration for submerged motor retrofits.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Alloy Foundry Capacity | Captive Inconel 718 casting secures impeller supply against Yangtze River Delta bottleneck risks. |
| Superconducting Motor Technology Licensing | Eliminates dynamic seals entirely, reducing EPA methane penalty exposure for Gulf Coast terminals. |
| Arctic Service Network Expansion | Regional stocking presence near Norway's Hammerfest liquefaction site captures premium aftermarket value. |
| Hydrogen Liquefaction Pilot Partnership | METI-funded collaborations near Nagoya establish 20 Kelvin flow control reference installations. |
| API 610 Documentation Library Expansion | Extended qualification protocols deter new entrants from hydrocarbon service certification. |
Methodological Framework
Cross-validation between primary interviews with LNG terminal maintenance directors and secondary analysis of FERC liquefaction project filings anchors the qualitative findings. The research incorporated discussions with EPC contractor procurement leads, precision foundry operations managers, and aftermarket service heads at Arctic LNG facilities. Secondary sources included EPA regulatory dockets, METI hydrogen roadmap publications, and customs trade data tracking nickel alloy pump component flows. Bottom-up demand modeling triangulated against top-down liquefaction capacity expansion projections.
Sensitivity analysis across nickel price volatility scenarios and qualification timeline variations shaped the forecast framework. The analytical framework segmented demand by pump architecture, application temperature regime, material specification, and end-user industry across the projection horizon. CAGRs derived from capacity-weighted liquefaction train deployment schedules and hydrogen liquefaction pilot scale-up trajectories. Modeled inputs included EPA methane fee enforcement intensity and GB standards local content threshold adjustments.
The analysis sits within stated boundaries; outcomes outside sustained LNG export terminal investment levels or hydrogen liquefaction technology maturation would require recalibration. Forecasts reflect documented assumptions regarding nickel alloy supply continuity and regulatory enforcement trajectories. Practitioners should keep alternative scenarios live as EPA rulemaking timelines and Japanese hydrogen funding allocations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Pressure Washer Pump Oil Market
Pumps and Control Devices
Pressure Pumping Market
Pumps and Control Devices
Cone Penetrometer Market
Pumps and Control Devices
Latin America Positive Displacement Pumps Market
Pumps and Control Devices
Global Compressor Control Systems Market
Pumps and Control Devices
Middle East and Africa Positive Displacement Pumps Market
Pumps and Control Devices
Gasketed Plate Heat Exchanger Market
Pumps and Control Devices
Hydraulic Dosing Pump Market
Pumps and Control Devices
Electrostatic Spraying System Market
Pumps and Control Devices
Liquid Ring Vacuum Pump Market
Pumps and Control Devices
United States Subsea Pumps Market
Pumps and Control Devices
Radial Piston Pumps Market
Pumps and Control Devices
Water Intake Screens Market
Pumps and Control Devices
Rotary Pump Market
Pumps and Control Devices
Single-Use Pump Market
Pumps and Control Devices
Pumps and Trigger Spray Market