
 Automatic Water Level Controller Market | 2026-2036
Automatic Water Level Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Water Level Controller Market Analysis
Chinese sensor manufacturers is expanding production capacity for ultrasonic and conductive sensing modules used in automatic water level controllers. Omron leverages its programmable logic controller ecosystem to bundle water level management with broader factory automation suites. Ajinkya Electronic Systems anchors its position through specialized embedded controllers designed for India's agricultural pump sets. Dingxing Automation competes on manufacturing scale, supplying wall-mounted and submersible units to Southeast Asian infrastructure contractors.
An automatic water level controller is an electromechanical or electronic device that monitors liquid surface elevation through float switches, pressure transducers, or ultrasonic wave reflection, then actuates pumps or valves to maintain programmed setpoints. The device typically operates across voltage ranges of 110-240V AC with switching tolerances of ±2 centimeters, serving primary purposes in reservoir management, sump drainage, and process tank regulation across commercial and industrial facilities. Ultrasonic sensor configurations command premium positioning due to non-contact measurement reliability in corrosive or turbid media, while float switch variants occupy the volume tier through mechanical simplicity and minimal maintenance requirements. IoT-enabled technology segments are recording the fastest uptake as agricultural end users in water-stressed regions demand remote monitoring capabilities via cellular or LoRa networks.
The US Environmental Protection Agency enforces Safe Drinking Water Act provisions that compel municipal utilities to upgrade aging distribution infrastructure with automated monitoring equipment, directly stimulating controller procurement. India's Bureau of Indian Standards and Central Electricity Authority jointly shape product compliance through electromagnetic compatibility and energy efficiency mandates for electronic pump controllers. China's Ministry of Ecology and Environment drives substitution of manual reservoir operations with automated systems under dual carbon goals targeting water-energy nexus reductions. Stakeholders must weigh regulatory divergence against platform standardization when selecting sensor-technology partnerships for multi-country deployment.
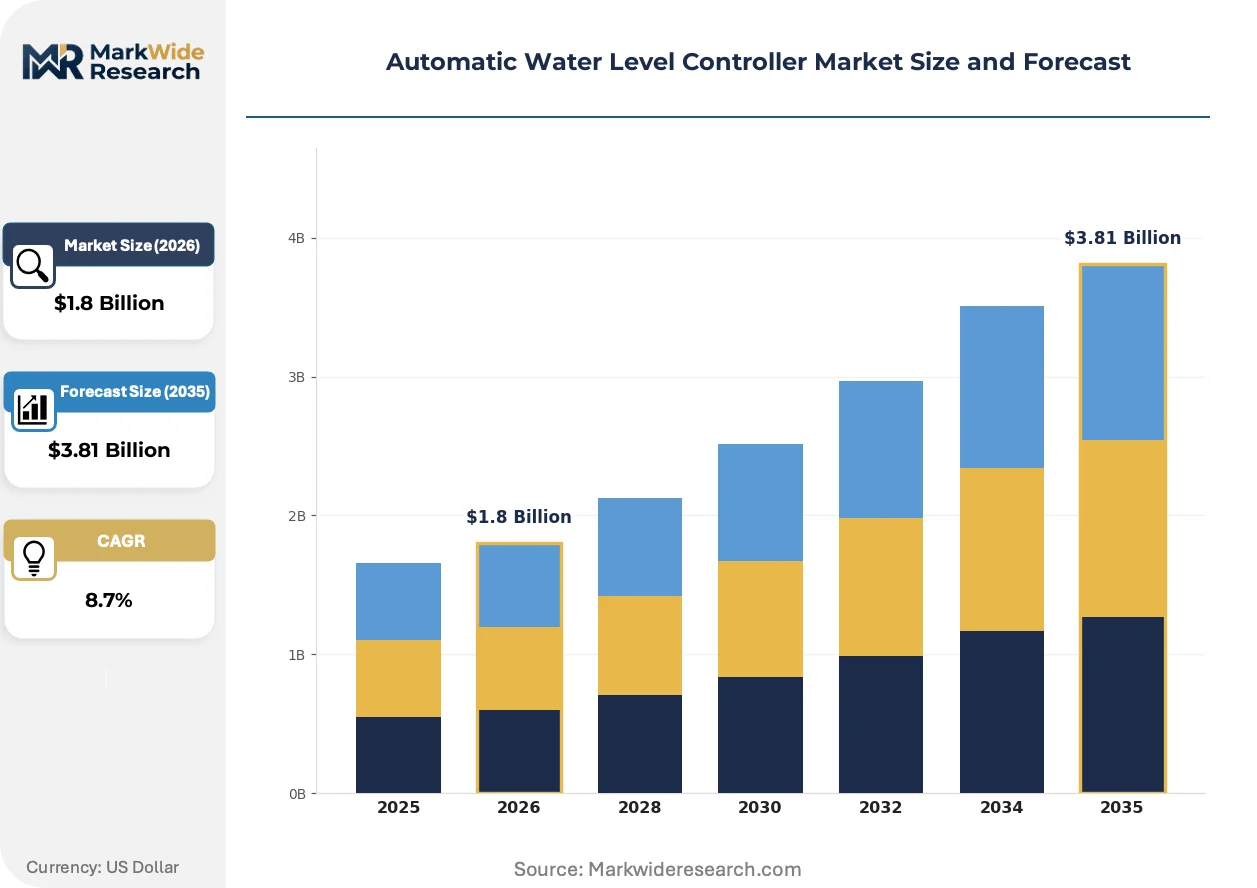
Market Dynamics
IoT-enabled remote monitoring is compressing replacement cycles for legacy float-switch systems as agricultural and municipal buyers demand cellular-connected visibility into reservoir operations across distributed infrastructure networks.
Growth Catalysts
- India's PLI scheme for electronic manufacturing:Domestic production incentives are lowering landed costs for sensor modules and embedded controllers, accelerating substitution of imported electromechanical units in water-stressed states.
- Textile cluster automation:Processing plants across Gujarat and Maharashtra are retrofitting dyeing and finishing tanks with ultrasonic level management to reduce water consumption and chemical waste.
- LoRa network expansion:Low-power wide-area infrastructure rollouts in Southeast Asian farming regions are enabling subscription-based monitoring services for smallholder irrigation cooperatives.
Market Restraints
- Sensor input cost volatility:Piezoelectric ceramics and MEMS wafers face pricing pressure from semiconductor foundry allocation constraints, squeezing margins on ultrasonic configurations.
- Supply concentration in Chinese sensor packaging:Over half of conductive probe assembly capacity sits in Zhejiang and Guangdong provinces, exposing procurement timelines to regional logistics disruptions.
- Electromagnetic compatibility testing backlog:India's BIS certification queues for electronic pump controllers now stretch beyond six months, delaying product launches for domestic manufacturers.
Strategic Opportunities
- Indonesian municipal utility modernization:Provincial water authorities in Java and Sumatra are issuing tenders for SCADA-integrated reservoir automation under public-private partnership frameworks.
- Convergence of ultrasonic sensing with edge AI:On-device pattern recognition enables predictive pump maintenance and anomaly detection without cloud dependency, opening premium pricing tiers.
- Direct-to-farmer digital channels:Agricultural equipment marketplaces are bypassing traditional distributor networks to sell compact controller kits with smartphone-based configuration.
Industry Challenges
- Embedded firmware talent scarcity:Shortages of engineers with combined expertise in real-time operating systems and IEC 61131-3 programming standards are throttling product development pipelines.
- Legacy pump integration complexity:Retrofit installations require custom signal conditioning to interface with decades-old motor control circuits, inflating deployment costs and failure rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Water Level Controller Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Float Switch, Pressure Sensor, Ultrasonic Sensor, Conductive Sensor Technology: Wired, Wireless, IoT-Enabled, Analog End User: Residential, Commercial, Industrial, Agricultural Installation: Wall-Mounted, Submersible, Portable, Embedded |
| Companies Covered | Omron, Puratek, Ajinkya Electronic Systems, Nelso, Attri Enterprises Ltd., Seagull Technologies, Niagara Automation and Company, RMG Automation, Dingxing Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Water Level Controller Market Emerging Trajectories
Edge computing architectures and predictive maintenance algorithms are redefining controller value propositions beyond simple on-off actuation toward continuous operational intelligence.
Ultrasonic time-of-flight sensing is unifying level measurement with flow estimation in single hardware packages. Chemical processing facilities in India's western industrial corridor are adopting these hybrid units to consolidate instrumentation footprints. This convergence is unifying previously separate budget lines for level and flow monitoring into single procurement decisions.
China's Ministry of Ecology and Environment is mandating automated reservoir monitoring for all surface water sources serving populations above 500,000. Provincial environmental bureaus are interpreting this as requiring data logging with tamper-evident timestamps. Municipal water bureaus in the Yangtze River basin are responding by specifying controllers with embedded secure elements and blockchain-ready data structures.
Service unbundling is fragmenting traditional equipment-plus-installation contracts. Large agricultural cooperatives in Vietnam and Thailand now procure hardware through commodity channels while contracting configuration and calibration separately to regional system integrators. This shift is most pronounced in the Mekong Delta, where rice irrigation collectives have standardized on open-communication protocols to avoid vendor lock-in.
Automatic Water Level Controller Market Segmentation
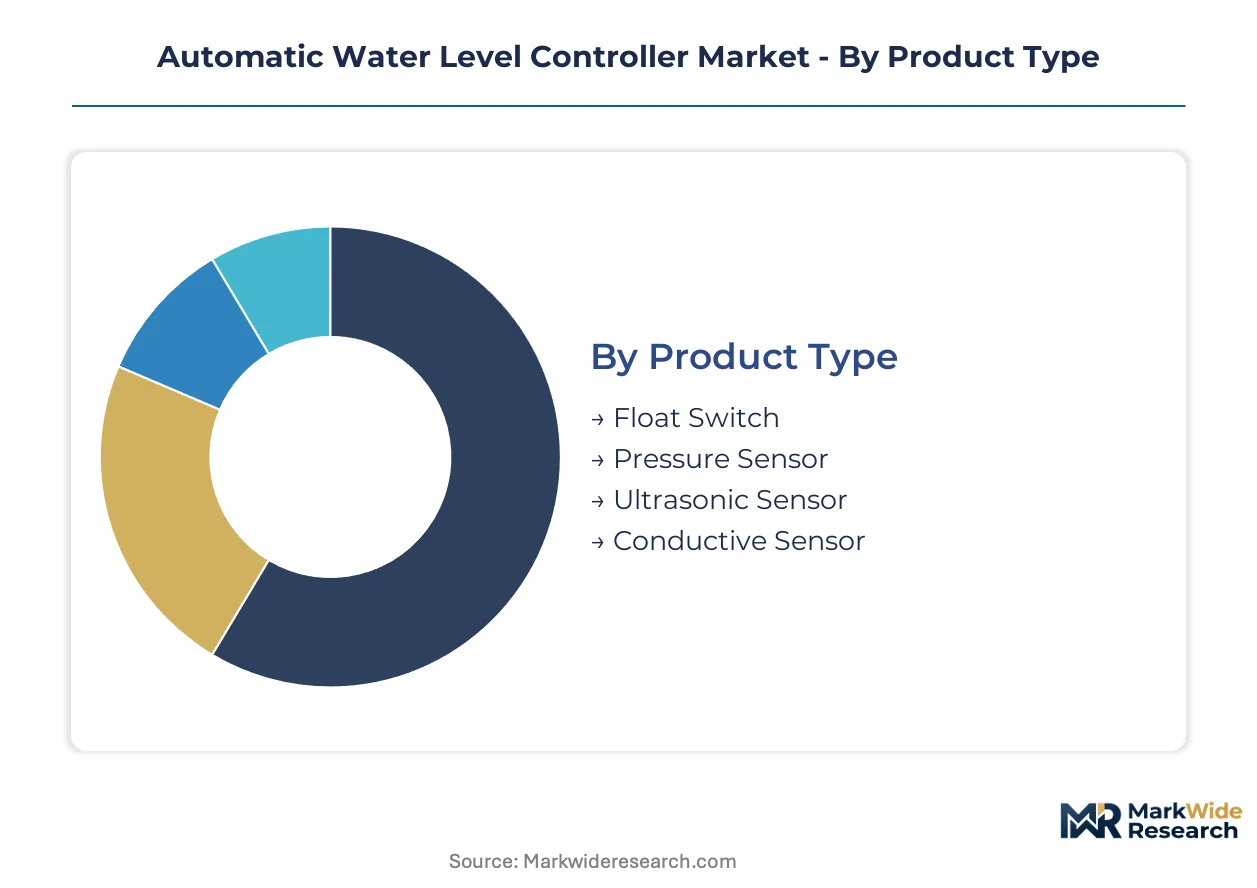
Segmentation in automatic water level controllers reveals distinct procurement patterns across sensing technologies and connectivity architectures. Product managers must align sensor selection with media characteristics, while channel strategy depends heavily on installation complexity and end-user technical sophistication.
Product Type:
Float switch variants dominate unit volumes through mechanical simplicity, while ultrasonic configurations capture premium positioning via non-contact reliability in harsh media.
- Float Switch:Buoyant mechanical actuators trigger electrical contacts at predetermined liquid elevations. Municipal utilities across India's drought-prone states favor these for primary reservoir control due to minimal calibration requirements and field-repairable construction.
- Ultrasonic Sensor:Piezoelectric transducers emit high-frequency pulses and measure time-of-flight reflections to calculate surface distance. Chemical processing facilities in Gujarat's industrial corridor specify these for corrosive dyeing tanks where probe contact risks contamination or material degradation.
- Pressure Sensor:Hydrostatic transducers infer liquid height from fluid column pressure at fixed depth points. Submersible variants serve deep well monitoring in agricultural groundwater extraction across Maharashtra.
- Conductive Sensor:Electrode arrays detect liquid presence through conductivity changes between probe tips. These occupy mid-tier positioning for sump drainage and sewage lift stations where moderate accuracy suffices.
Mature deployment sits with float switch mechanisms in legacy municipal infrastructure. Newer deployment is concentrated in ultrasonic sensing for precision industrial applications.
Technology:
Connectivity architecture determines replacement cadence, with hardwired installations persisting in cost-constrained segments and cellular-enabled units commanding service-subscription revenue streams.
- Wired:Direct electrical signaling through shielded cable runs delivers deterministic response times for safety-critical pump interlocks. These configurations persist in factory automation retrofits where electromagnetic interference immunity overrides flexibility requirements.
- IoT-Enabled:Embedded cellular or LoRa radios transmit level telemetry to cloud dashboards with configurable alerting thresholds. Agricultural cooperatives in Vietnam's Mekong Delta are adopting these for distributed rice paddy monitoring under subscription-based managed service contracts.
- Wireless:Battery-powered radio frequency links eliminate conduit installation for temporary or remote monitoring points. Construction site dewatering operations in Indonesia deploy these for mobile sump management during foundation work.
- Analog:Continuous 4-20mA or 0-10V outputs interface with legacy SCADA systems and programmable logic controllers. These serve as drop-in replacements during brownfield upgrades where digital protocol migration remains incomplete.
Wired infrastructure dominates existing industrial installations. IoT-enabled architectures are climbing the fastest in agricultural water-stressed regions demanding remote visibility.
End User:
Customer archetypes diverge sharply on specification complexity, with residential buyers prioritizing plug-and-play simplicity and industrial purchasers mandating SIL-rated safety integration.
- Industrial:Process tank regulation in continuous manufacturing demands redundant sensing, hazardous area certification, and integration with distributed control systems. Textile wet processing plants across Maharashtra's industrial belt specify these for dye liquor level management tied to chemical dosing automation.
- Agricultural:Irrigation reservoir and borewell automation requires weather-resistant enclosures and compatibility with variable frequency drive pump controllers. India's western states are seeing concentrated uptake here amid groundwater conservation mandates.
- Commercial:Building services applications span rooftop tank management, fire suppression reservoir monitoring, and HVAC condensate handling. These deployments emphasize BACnet or Modbus integration with building management systems.
- Residential:Single-family and small apartment installations prioritize compact wall-mounted controllers with basic dry-run protection for submersible pumps. Southeast Asian urban markets drive volume through distributor channels.
Commercial building automation represents mature standardized demand. Agricultural deployment is expanding most quickly under rural electrification and precision irrigation initiatives.
Installation:
Mounting configuration dictates supply chain structure, with submersible units requiring sealed cable glands and pressure-rated housings that elevate manufacturing complexity against wall-mounted alternatives.
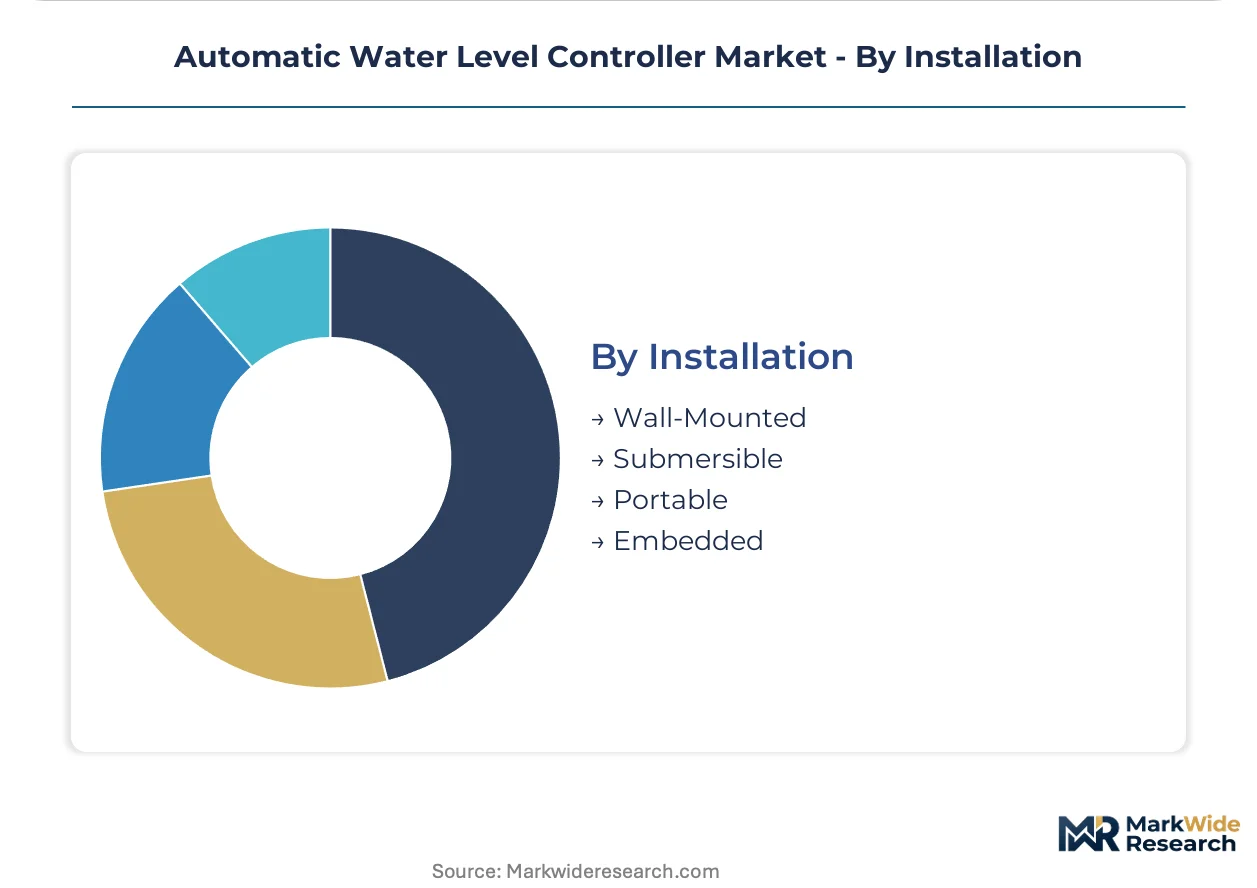
- Submersible:Fully encapsulated electronics withstand hydrostatic pressure at depth for borewell and sump applications. These demand specialized potting compounds and stainless steel enclosures, concentrating production among underwater-rated sensor specialists.
- Wall-Mounted:Surface-mounted control enclosures with remote probe connections simplify maintenance access and wiring termination. Municipal water authorities in Indonesia favor these for above-ground reservoir control rooms.
- Portable:Battery-operated units with magnetic or clamp mounting serve temporary dewatering, flood response, and construction site monitoring. Rental equipment channels distribute these across Southeast Asian infrastructure projects.
- Embedded:OEM-integrated modules install directly into pump housings, tank structures, or process skids during original equipment manufacture. These bypass aftermarket distribution entirely, shipping directly to pump manufacturers and system integrators.
Wall-mounted controllers anchor established municipal procurement patterns. Embedded integration is gaining share fastest as pump OEMs verticalize level sensing into unified product offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sensor-grade piezoelectric ceramics from Zhejiang province anchor Asia-Pacific supply chains for ultrasonic level controllers, while municipal procurement across Southeast Asia and South Asia drives installation demand.
China
Provincial environmental bureaus under the Ministry of Ecology and Environment mandate automated reservoir monitoring for surface water sources serving populations above 500,000. Municipal water bureaus in the Yangtze River basin specify controllers with embedded secure elements and blockchain-ready data structures for tamper-evident logging.
India
Textile and chemical plants across Gujarat and Maharashtra deploy automated reservoir systems under state-level water conservation mandates. The Bureau of Indian Standards tightened electromagnetic compatibility requirements for electronic water management devices, creating six-month certification queues that delay domestic manufacturer product launches.
Indonesia
Provincial water authorities in Java and Sumatra issue tenders for SCADA-integrated reservoir automation under public-private partnership frameworks. Construction site dewatering operations deploy portable battery-operated units for mobile sump management during foundation work in Jakarta and Surabaya.
Vietnam
Rice irrigation collectives in the Mekong Delta standardize on open-communication protocols to avoid vendor lock-in. Agricultural cooperatives adopt IoT-enabled controllers with cellular telemetry under subscription-based managed service contracts for distributed paddy monitoring.
United States
The Environmental Protection Agency enforces Safe Drinking Water Act provisions compelling municipal utilities to upgrade aging distribution infrastructure with automated monitoring equipment. Factory automation retrofits persist with wired configurations where electromagnetic interference immunity overrides flexibility requirements.
Automatic Water Level Controller Market Vendor Landscape
Global majors compete with regional champions across sensing technology and connectivity architectures. The vendor base spans Japanese factory automation conglomerates, Indian embedded controller specialists, and Chinese manufacturing-scale suppliers. Three strategic archetypes dominate: diversified industrial electronics firms bundling water level management into broader automation suites; geography-focused specialists serving agricultural pump-set markets; and scale-driven fabricators supplying infrastructure contractors across Southeast Asia. Competitive moves concentrate on geographic expansion into Indonesian municipal tenders and portfolio diversification toward edge-AI-enabled predictive maintenance.
Within the diversified industrial tier, Omron leverages its programmable logic controller ecosystem to bundle water level management with factory automation suites. Ajinkya Electronic Systems anchors its position through specialized embedded controllers designed for India's agricultural pump sets. Dingxing Automation occupies the manufacturing-scale archetype, supplying wall-mounted and submersible units to Southeast Asian infrastructure contractors. These three exemplify how competitive positioning fragments across technology integration depth, geographic specialization, and production volume.
| Leading Market Players |
|---|
| Omron |
| Puratek |
| Ajinkya Electronic Systems |
| Nelso |
| Attri Enterprises Ltd. |
| Seagull Technologies |
| Niagara Automation and Company |
| RMG Automation |
| Dingxing Automation |
| Others |
Supply Flow & Price Mechanics
Municipal procurement mandates for tamper-evident data logging in China and electromagnetic compatibility certification in India are forcing sensor manufacturers to absorb compliance costs upstream, compressing margins on mid-tier controller configurations while premium ultrasonic variants capture value through embedded secure elements.
Pricing Analysis
Warranty and calibration service bundling separates premium-tier suppliers from commodity competitors in this market. Three-tier pricing structure across premium, standard, and economy levels tracks sensor technology sophistication, with ultrasonic configurations commanding substantial premiums over float-switch alternatives due to non-contact reliability in corrosive media. Price differentiation hinges on certification grade for hazardous area deployment and volume scale for agricultural cooperative procurement. Cost compression in standard-tier wired controllers is intensifying because Indian BIS certification queues extend supplier working capital cycles. Agricultural smallholders exhibit highest price sensitivity, while chemical processing facilities in Gujarat's industrial corridor prioritize specification compliance over unit cost.
Supply Chain Analysis
Freight cost volatility from Zhejiang and Guangdong provinces to Southeast Asian infrastructure sites is elevating landed costs for conductive probe assemblies. Manufacturing concentrates in China for piezoelectric ceramics and MEMS wafers, India for embedded controller firmware integration, and Taiwan for semiconductor components. Raw material dependencies include sensor-grade ceramics, stainless steel enclosures for submersible ratings, and potting compounds for moisture sealing. Single-source vulnerability in Chinese sensor packaging exposes procurement timelines to regional logistics disruptions. Distribution runs through pump OEM channels for embedded modules and electrical distributor networks for aftermarket wall-mounted units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IoT-enabled architectures are displacing legacy float-switch installations across agricultural and municipal segments, creating asymmetric opportunity for connectivity-capable suppliers against electromechanical incumbents.
For Market Incumbents: Anticipate margin erosion in wired controller segments as Indonesian municipal tenders specify SCADA-integrated architectures requiring firmware competencies outside traditional mechanical expertise. Defensive consolidation should prioritize backward integration into ultrasonic sensor production to capture value from premium-tier specification shifts, while channel control investments in Vietnam's Mekong Delta distributor networks protect installed-base service revenue against unbundling trends. For New Entrants and Emerging Players: Direct-to-farmer digital channels offer the most penetrable route for compact controller kits bypassing traditional agricultural equipment distributors. White-space targets include subscription-based monitoring services for Thai rice irrigation cooperatives and edge-AI-enabled predictive maintenance modules for textile wet processing plants in Maharashtra. Configuration simplicity through smartphone-based setup represents the critical go-to-market angle against incumbent technical complexity. For Investors and Strategic Acquirers: The window for entry favors firmware-specialist targets with IEC 61131-3 programming capabilities and existing BIS certification pipelines. Long-term viability rests on platform consolidation across sensing modalities rather than single-technology positioning. Embedded secure element integration for Chinese municipal compliance represents the signal to watch as inflection indicator for premium-tier market access.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Integration | On-device pattern recognition enables predictive pump maintenance without cloud dependency in Yangtze River basin deployments. |
| LoRa Network Partnership | Low-power wide-area infrastructure rollouts in Vietnam's Mekong Delta support subscription telemetry services for irrigation cooperatives. |
| Secure Element Certification | Tamper-evident data logging compliance unlocks Chinese municipal tenders for surface water sources above 500,000 population. |
| Backward Integration | In-house production of ultrasonic transducer modules captures margin from premium-tier chemical processing specifications in Gujarat. |
| Direct-to-Farmer Channel | Smartphone-configurable controller kits bypass traditional distributor markups in Southeast Asian agricultural equipment marketplaces. |
Methodological Framework
Trade databases, regulatory filings, and sensor manufacturer technical documentation formed the secondary backbone for this analysis. Primary interviews with municipal water authority procurement officers, agricultural cooperative irrigation managers, textile plant maintenance directors, and embedded controller firmware engineers combined with secondary validation to construct demand-side segmentation. Bottom-up unit economics from controller bill-of-materials analysis and top-down triangulation against national water infrastructure investment programs anchored market sizing across the projection horizon.
Historical trendline analysis of municipal automation procurement cycles and agricultural electrification penetration rates informed the analytical framework. Segmentation dimensions modeled include sensing technology type, connectivity architecture, installation configuration, and end-user vertical with regional regulatory cluster differentiation. CAGRs were derived from installed-base replacement dynamics and new deployment intensity across water-stressed geographies. Forecast inputs incorporated BIS certification queue duration impacts on domestic manufacturer launch timelines and LoRa network coverage expansion rates in Southeast Asian farming regions.
The model holds under stable semiconductor foundry allocation and continued municipal procurement momentum; deviation in Chinese environmental enforcement intensity or Indian certification processing capacity would shift volume trajectories. Forecasts reflect documented assumptions regarding technology substitution rates and infrastructure investment continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
API 610 Pumps Market
Pumps and Control Devices
Industrial ASME B73.1 Centrifugal Pumps Market
Pumps and Control Devices
Dry Vacuum Pumps Market
Pumps and Control Devices
Radial Flow Pump Market
Pumps and Control Devices
Mist Sprayer Pumps Market
Pumps and Control Devices
Pressure Washer Pump Oil Market
Pumps and Control Devices
Liquid Ring Vacuum Pump Market
Pumps and Control Devices
Middle East and Africa Centrifugal Pumps Market
Pumps and Control Devices
Condensate Pump Market
Pumps and Control Devices
Gasketed Plate Heat Exchanger Market
Pumps and Control Devices
Electrostatic Spraying System Market
Pumps and Control Devices
Global Piston Pumps Market
Pumps and Control Devices
Radial Split Pump Market
Pumps and Control Devices
Global Commercial Pumps Market
Pumps and Control Devices
Europe Centrifugal Pumps Market
Pumps and Control Devices
Water Pump Market