
 Global Pumps Market | 2026-2036
Global Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pumps Market Outlook
Composite materials are displacing cast iron in pump housings and impellers, a material substitution that is recalibrating product economics across the industry. Grundfos Holding A/S leverages its in-house foundry capabilities and polymer research to anchor premium efficiency ratings in circulator pumps. Flowserve Corporation dominates severe-service applications in oil and gas through alloy specialization for corrosion resistance. Wilo SE extends its position in building services through compact wet-rotor designs that reduce installation footprint.
A pump is a mechanical device that transfers fluids by converting rotational kinetic energy into hydrodynamic energy, with critical specifications including head pressure measured in meters, flow rate in cubic meters per hour, and net positive suction head to prevent cavitation. Centrifugal pumps lead volume due to their simplicity and scalability across water treatment and HVAC systems, while positive displacement technology commands higher margins in chemical processing and food applications where precise metering protects product integrity. Submersible installations are gaining share in agricultural groundwater extraction and municipal wastewater networks, displacing above-ground configurations in regions with deepening water tables.
The US Department of Energy enforces pump efficiency standards under the Energy Policy and Conservation Act, while the EU Ecodesign Directive mandates minimum efficiency index thresholds that block non-compliant imports. China's SAMR administers GB national standards that align with IE3 motor efficiency classes, reshaping supplier qualification for access. Stakeholders must monitor how regional efficiency benchmarks diverge and whether local content requirements in India and Brazil fragment certification burdens across product portfolios.
Market Dynamics
Energy efficiency mandates are compressing the competitive set as minimum performance thresholds eliminate marginal producers, while material substitution toward polymer composites redraws cost curves across centrifugal and positive displacement categories.
Growth Catalysts
- EU Ecodesign Directive:Minimum efficiency index thresholds block non-compliant imports, concentrating procurement among certified suppliers in municipal water and building services segments.
- Agricultural mechanization in India:Submersible pump deployment accelerates as groundwater extraction deepens and state irrigation subsidies expand farmer access to mechanized lift systems.
- Composite impeller technology:Polymer housings reduce weight and corrosion susceptibility, enabling OEMs to extend service intervals in chemical processing and marine applications.
Market Restraints
- Rare earth magnet supply concentration:Permanent magnet motors for premium efficiency pumps depend on Chinese processing capacity, exposing cost volatility to export quota fluctuations.
- Cast iron foundry consolidation:European and North American metalcasting capacity contraction limits housing supply for severe-service oil and gas configurations.
- IE3 motor class retrofit limitations:Legacy installed bases in industrial facilities cannot accommodate higher-efficiency drives without shaft alignment and control system replacement.
Strategic Opportunities
- India municipal infrastructure:Smart city investments and AMRUT scheme funding expand procurement of intelligent pumping stations with embedded flow monitoring.
- Digital twin integration:Predictive maintenance algorithms converging with IoT sensor networks enable aftermarket service revenue streams in water treatment utilities.
- US Inflation Reduction Act:Energy efficiency tax credits accelerate building HVAC pump replacement cycles toward wet-rotor circulator configurations.
Industry Challenges
- Multiphysics simulation expertise:CFD and FEA modeling for cavitation prediction and impeller optimization exceeds available talent pools in mid-tier engineering departments.
- Cross-border certification timelines:Concurrent UL, CE, and BIS approval processes extend product launch schedules by 8-14 months for multi-region suppliers.
- Legacy SCADA integration:New variable frequency drives require protocol translation layers to communicate with decades-old municipal control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pumps Market |
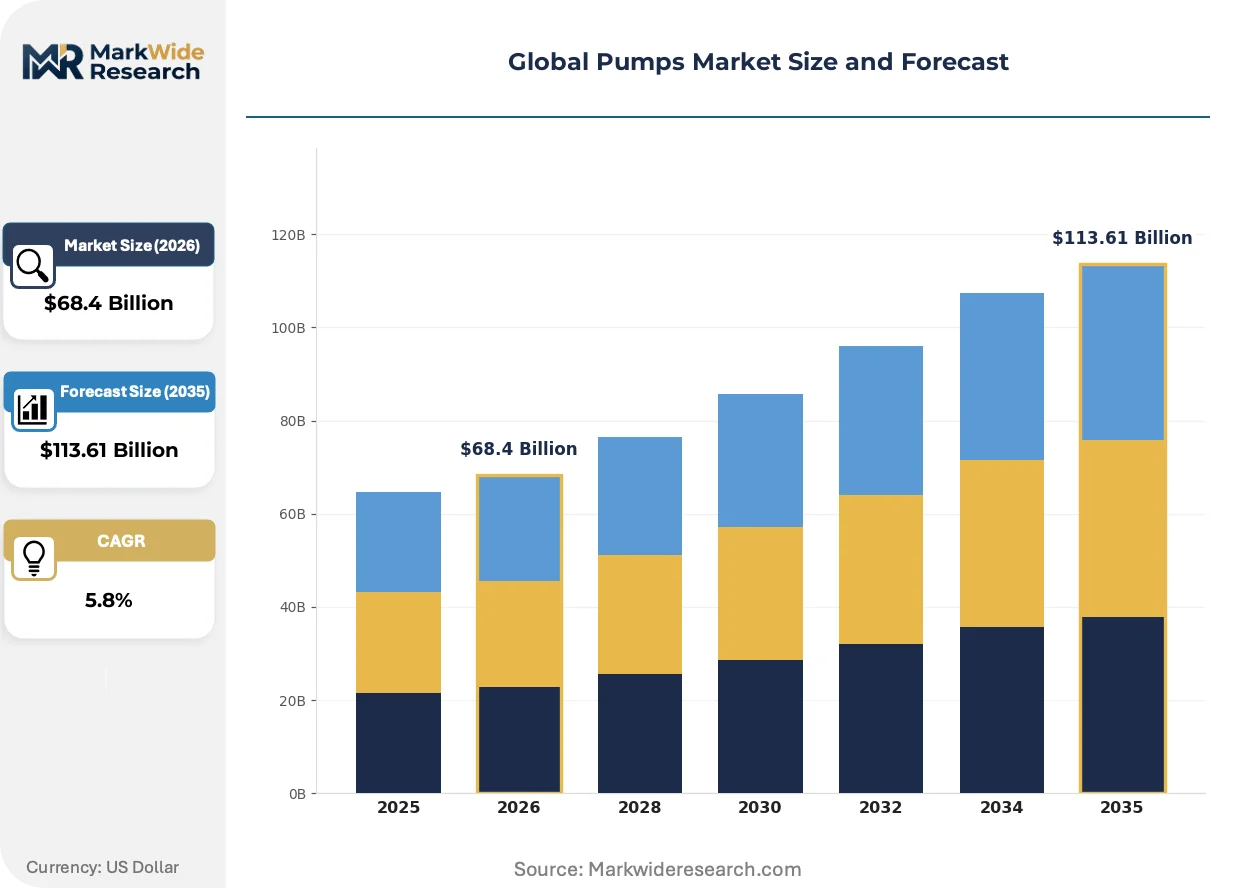
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Positive Displacement, Centrifugal, Gear, Diaphragm End User: Oil & Gas, Water Treatment, Manufacturing, HVAC Application: Agriculture, Chemical Processing, Food & Beverage, Pharmaceuticals Installation: Stationary, Portable, Submersible, Inline |
| Companies Covered | Grundfos Holding A/S, Xylem Inc., Flowserve Corporation, Sulzer Ltd., KSB SE & Co. KGaA, ITT Inc., SPX Flow, The Weir Group PLC, Wilo SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pumps Market Strategic Shifts
Wet-rotor designs and polymer metallurgy are compressing installation footprints while digital instrumentation layers transform pumps from passive hardware into data-generating infrastructure nodes.
Silicon carbide mechanical seals are expanding into high-temperature chemical processing applications where traditional carbon-graphite faces degrade. Specialty chemical manufacturers in Germany and the US Gulf Coast are specifying SiC primary seals for aromatic hydrocarbon duty. The material shift is expanding into adjacent severe-service categories previously reserved for alloy-based sealing systems.
China's GB 18613-2020 motor efficiency standards and SAMR enforcement protocols are eliminating IE2-equivalent pump-motor combinations from domestic procurement. Local manufacturers are redesigning stator laminations and rotor geometries to meet IE3 thresholds. Export-oriented suppliers must maintain parallel certification streams as efficiency benchmarks diverge between Chinese GB classes and EU Ecodesign indices.
Water utilities are consolidating vendor relationships around lifecycle cost metrics rather than upfront capital expenditure. Danish and Dutch municipal operators now specify total cost of ownership guarantees extending 15-20 years. Brazilian state water companies are piloting similar frameworks through ANA-backed efficiency programs in São Paulo and Minas Gerais basins.
Global Pumps Market Segmentation
Pump procurement decisions diverge sharply across end-use contexts, with efficiency mandates, fluid characteristics, and lifecycle cost frameworks driving category selection. Material specifications and installation constraints further fragment supplier positioning across industrial, municipal, and agricultural deployment scenarios.
Product Type:
Buyers in this category differentiate primarily by fluid viscosity, pressure requirements, and tolerance for shear-sensitive handling.
- Centrifugal:Impeller-driven kinetic energy transfer dominates water treatment and HVAC circulation where low-viscosity fluids and high flow rates predominate. Indian municipal utilities and US building services contractors specify these for energy efficiency compliance under IE3 motor classes and DOE conservation standards.
- Positive Displacement:Reciprocating or rotary mechanisms deliver precise volumetric output for chemical metering and food processing where product integrity demands exact dosing. German specialty chemical manufacturers and US Gulf Coast refineries specify these for aromatic hydrocarbon duty with silicon carbide sealing systems.
- Gear:Intermeshing rotors handle viscous lubricants and polymer fluids in manufacturing process lines. Compact configurations suit mobile hydraulic systems in construction and agricultural equipment.
- Diaphragm:Pneumatic or hydraulic actuation isolates pumped media from mechanical components, serving pharmaceutical aseptic transfer and abrasive slurry applications. Wastewater treatment facilities in Brazil and India deploy air-operated double-diaphragm units for chemical dosing.
Volume sits with Centrifugal; growth tilts toward Positive Displacement.
End User:
Capital intensity and regulatory exposure shape procurement sophistication across these verticals.
- Water Treatment:Municipal utilities and industrial effluent plants drive demand for submersible wastewater configurations and high-efficiency clean water lift stations. Dutch and Danish operators now mandate total cost of ownership guarantees spanning 15-20 years.
- Oil & Gas:Severe-service extraction and refining applications require alloy-specialized pumps for high-pressure hydrocarbon transfer and corrosive sour gas handling. US Permian Basin and North Sea operators prioritize corrosion-resistant alloy configurations.
- HVAC:Building services contractors specify compact wet-rotor circulators for hydronic heating and cooling distribution. US Inflation Reduction Act efficiency tax credits accelerate replacement cycles toward premium efficiency ratings.
- Manufacturing:Process cooling, machine tool coolant circulation, and hydraulic power units span diverse pressure and flow requirements. Automotive stamping plants and semiconductor fabrication facilities drive precision coolant delivery specifications.
Revenue concentrates in Water Treatment; margin expansion favors Oil & Gas.
Application:
Fluid contamination risk and batch integrity requirements determine technology selection and material specification.
- Agriculture:Groundwater extraction and pressurized irrigation systems deploy submersible borehole pumps and surface centrifugal units. Indian state subsidy programs and deepening water tables accelerate mechanized lift system deployment across Maharashtra and Gujarat.
- Chemical Processing:Aggressive media handling demands metallurgical specialization in pump housings, impellers, and sealing systems. German and US Gulf Coast aromatic hydrocarbon processors specify silicon carbide mechanical seals for high-temperature duty.
- Food & Beverage:Hygienic design standards mandate stainless steel construction, crevice-free surfaces, and clean-in-place compatibility. Dairy processing and beverage carbonation lines require gentle product handling to preserve emulsion stability.
- Pharmaceuticals:Aseptic manufacturing and active ingredient transfer demand validated contamination control with diaphragm or peristaltic isolation technologies. Bioreactor feed systems and chromatography buffer preparation require precise flow control.
Deployment scale favors Agriculture; specification intensity peaks in Pharmaceuticals.
Installation:
Site constraints and maintenance accessibility dictate configuration trade-offs between footprint, immersion depth, and serviceability.
- Submersible:Motor and pump integrated for immersion in boreholes, wet wells, and tanks eliminates suction lift limitations and noise exposure. Indian agricultural groundwater extraction and Brazilian municipal wastewater networks displace above-ground configurations as water tables deepen.
- Inline:Compact axial or mixed-flow designs install directly in piping with minimal footprint, suiting building services and process line retrofits. Wet-rotor circulators in hydronic systems eliminate mechanical seal maintenance.
- Stationary:Permanent foundation-mounted configurations serve industrial process baselines with predictable duty cycles and scheduled maintenance access. Power generation cooling water and primary chemical process lines favor this reliability-centered approach.
- Portable:Engine-driven or mobile electric units enable dewatering, emergency response, and construction site fluid transfer. Mining operations and flood control agencies maintain rapid deployment inventories.
Submersible configurations claim the steepest expansion trajectory; Inline dominates building services penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates procurement acceleration as municipal infrastructure investment and agricultural mechanization reshape deployment patterns across submersible and positive displacement categories.
United States
The Department of Energy enforces pump efficiency standards under the Energy Policy and Conservation Act, compressing the competitive set as minimum performance thresholds eliminate marginal producers. Building services contractors in Texas and California specify compact wet-rotor circulators for hydronic systems. The Inflation Reduction Act accelerates HVAC pump replacement cycles through energy efficiency tax credits.
Germany
Specialty chemical manufacturers in the Rhine-Ruhr industrial cluster specify silicon carbide mechanical seals for aromatic hydrocarbon duty. The EU Ecodesign Directive mandates minimum efficiency index thresholds that block non-compliant imports from municipal water and building services segments. Bavarian pump OEMs leverage in-house foundry capabilities and polymer research to anchor premium efficiency ratings.
China
Local manufacturers redesign stator laminations and rotor geometries to meet GB 18613-2020 motor efficiency standards administered by SAMR. The Yangtze River Delta concentrates export-oriented suppliers maintaining parallel certification streams as efficiency benchmarks diverge between Chinese GB classes and EU Ecodesign indices. Domestic procurement eliminates IE2-equivalent pump-motor combinations.
India
State irrigation subsidies expand farmer access to mechanized lift systems across Maharashtra and Gujarat as groundwater extraction deepens. The AMRUT scheme and smart city investments expand procurement of intelligent pumping stations with embedded flow monitoring. Municipal utilities concentrate vendor relationships around lifecycle cost metrics rather than upfront capital expenditure.
Brazil
State water companies pilot total cost of ownership frameworks through ANA-backed efficiency programs in São Paulo and Minas Gerais basins. Wastewater treatment facilities deploy air-operated double-diaphragm units for chemical dosing. Submersible configurations displace above-ground installations as water tables deepen in agricultural regions.
Global Pumps Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with efficiency mandates compressing the supplier base as minimum performance thresholds eliminate marginal producers. European and Asian OEMs anchor premium positioning through in-house metallurgy and polymer research capabilities, while regional fabricators compete on retrofit compatibility and local certification speed. Two strategic archetypes dominate: integrated specialists controlling foundry-to-assembly value chains, and technology licensors leveraging CFD modeling partnerships for impeller optimization. Consolidation pressures intensify through alloy foundry capacity contraction and cross-border certification timeline extensions.
Within the integrated specialist tier, Grundfos Holding A/S and Flowserve Corporation exemplify divergent positioning strategies. Grundfos anchors premium efficiency ratings through captive foundry capabilities and polymer research depth. Flowserve occupies a position in severe-service applications through alloy specialization heritage. Wilo SE represents the compact wet-rotor design vector, reducing installation footprint in building services penetration. These three entities collectively illustrate how material substitution and digital instrumentation layers transform competitive differentiation beyond traditional head-and-flow specifications.
| Leading Market Players |
|---|
| Grundfos Holding A/S |
| Xylem Inc. |
| Flowserve Corporation |
| Sulzer Ltd. |
| KSB SE & Co. KGaA |
| ITT Inc. |
| SPX Flow |
| The Weir Group PLC |
| Wilo SE |
| Others |
Value Chain & Pricing Dynamics
Captive foundry operations among European OEMs anchor both supply security and premium pricing power, insulating tier-one producers from raw material volatility while compressing margins for fabricators dependent on spot-market metalcastings. This integration choice separates efficiency-certified suppliers capable of meeting EU Ecodesign thresholds from price-competitive imports facing compliance barriers.
Pricing Analysis
Volume concentrates in centrifugal water-treatment configurations where standard-efficiency units compete on capital cost, while margin expansion sits with positive-displacement chemical-processing pumps carrying silicon-carbide seal premiums. Pricing stratifies across IE3-certified premium tiers, mid-grade municipal procurement bands, and economy agricultural segments lacking efficiency mandates. Cost compression in standard-efficiency tiers is intensifying because Chinese manufacturers are exporting surplus IE2-equivalent capacity into price-sensitive developing markets. Municipal utilities in Denmark and the Netherlands exhibit lowest price sensitivity through lifecycle-cost contracting, while Indian state irrigation programs drive highest sensitivity via upfront subsidy caps.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from water utilities and oil majors, while distribution partners serve fragmented agricultural and building-services contractors. Manufacturing concentrates in Germany, China, and Denmark for finished pump assembly, with India and Brazil emerging as regional fabrication hubs for tariff-advantaged supply. Rare-earth magnet processing rests on Chinese capacity, creating single-source vulnerability for premium-efficiency permanent-magnet motor configurations. Cast iron foundries in Europe and North America face capacity contraction, forcing severe-service oil-and-gas producers toward alloy-specialized Asian suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Pumps Market functions as a cost-of-compliance story where EU Ecodesign Directive efficiency thresholds erect barrier-to-entry moats, concentrating procurement among certified suppliers while eliminating marginal producers from municipal and building-services segments.
For Market Incumbents: Anchor premium positioning through captive polymer-metallurgy R&D and in-house foundry capacity that locks in IE3-equivalent efficiency ratings ahead of tightening GB standards in China. Defend against rare-earth cost volatility by securing long-term magnet supply agreements or pivoting toward synchronous reluctance motor designs that eliminate permanent-magnet dependency. Certification investment represents the critical lever for maintaining access to EU municipal procurement channels as non-compliant imports face automatic exclusion. For New Entrants and Emerging Players: Capture white-space in Indian agricultural submersible deployment where state subsidy expansion outpaces established OEM distribution reach, and in Brazilian wastewater diaphragm-pump chemical-dosing applications where ANA efficiency programs are consolidating vendor relationships. The most penetrable segment is intelligent pumping stations with embedded IoT flow monitoring for smart-city infrastructure in secondary Indian urban centers. A channel partnership strategy with regional system integrators accelerates local certification speed and sidesteps incumbent direct-sales advantages. For Investors and Strategic Acquirers: Exit pathways concentrate in trade-sale acquisition by integrated industrial conglomerates seeking pump technology for water-infrastructure or energy-transition verticals, with secondary IPO routes for scaled specialists achieving regional dominance. Long-term viability favors targets with captive foundry assets and parallel UL-CE-BIS certification streams that compress multi-region launch timelines. Watch for inflection in rare-earth export quota announcements from Chinese regulators, which signal cost-structure pressure on premium-efficiency motor-dependent product lines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Reduces exposure to Chinese export quota volatility for IE3 motor configurations. |
| Parallel Certification Stream Investment | Compresses UL, CE, and BIS approval timelines for multi-region product launches. |
| Digital Twin Platform Development | Enables predictive maintenance revenue from water utilities adopting lifecycle-cost frameworks. |
| Composite Impeller Manufacturing Scale-Up | Captures polymer-substitution trend displacing cast iron in chemical and marine applications. |
| Smart City Partnership Formation | Secures AMRUT scheme procurement channels for intelligent pumping stations in Indian municipalities. |
Study Parameters
Document review covered customs trade databases, SEC 10-K filings, and EU Ecodesign compliance registries, complemented by interviews with plant engineers at water treatment utilities, procurement leads at oil-and-gas operators, and aftermarket service heads at pump OEMs. Secondary validation drew from SAMR GB standard enforcement protocols, ANA efficiency program documentation, and DOE conservation rulemaking records. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Cross-referencing historical shipment data against expert panel input on efficiency-mandate compliance timelines shaped the analytical framework. Segmentation dimensions spanned product type, end-user vertical, application context, and installation configuration across the projection horizon. CAGRs were derived from installed-base replacement cycles, agricultural mechanization penetration curves, and municipal infrastructure investment pipelines without year-specific anchoring.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare-earth supply disruptions, foundry capacity contraction, and divergence between regional efficiency benchmarks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Droplet Separator Market
Pumps and Control Devices
Chopper Pumps Market
Pumps and Control Devices
North America Positive Displacement Pumps Market
Pumps and Control Devices
Intelligent Pump Market
Pumps and Control Devices
Global Leak Detection Solutions Market
Pumps and Control Devices
United States Positive Displacement Pumps Market
Pumps and Control Devices
Gasketed Plate Heat Exchanger Market
Pumps and Control Devices
Global Smart Pumps Market
Pumps and Control Devices
Rotary Pump Market
Pumps and Control Devices
Solar Pump Inverter Market
Pumps and Control Devices
Slurry Pumps Market
Pumps and Control Devices
Fire Pump Test Meters Market
Pumps and Control Devices
Centrifugal Pumps Machines Market
Pumps and Control Devices
Residential Pumps Market
Pumps and Control Devices
Multi-Stage Centrifugal Pumps Market
Pumps and Control Devices
Global High Pressure Pumps Market