
 Turbomolecular Pumps Market | 2026-2036
Turbomolecular Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Turbomolecular Pumps Market Intelligence
The expansion of semiconductor fabrication capacity in China and South Korea is fragmenting the competitive landscape for high-vacuum equipment suppliers. Pfeiffer Vacuum GmbH leverages its strong European base to serve industrial and R&D clients. Edwards Vacuum specializes in solutions for semiconductor and display manufacturing, competing on performance and reliability. ULVAC Technologies positions itself with a broad portfolio targeting diverse applications from electronics to research.
A turbomolecular pump is a kinetic vacuum pump that uses a high-speed rotating turbine to impart momentum to gas molecules. Operating at rotational speeds often exceeding 20,000 RPM, it creates or maintains ultra-high vacuum conditions essential for contamination-sensitive processes. Magnetic bearing technology commands a premium due to its oil-free operation and lower vibration, critical for semiconductor fabrication. Within applications, mass spectrometry and research laboratories represent stable, high-margin segments.
Compliance with CE marking in Europe and SEMI standards for semiconductor equipment dictates pump design and material selection. Regulations like the EU's RoHS directive restrict hazardous substances, influencing manufacturing processes and supply chain choices. Vendor selection will increasingly hinge on demonstrating compliance with evolving energy efficiency benchmarks and cleanroom compatibility standards.
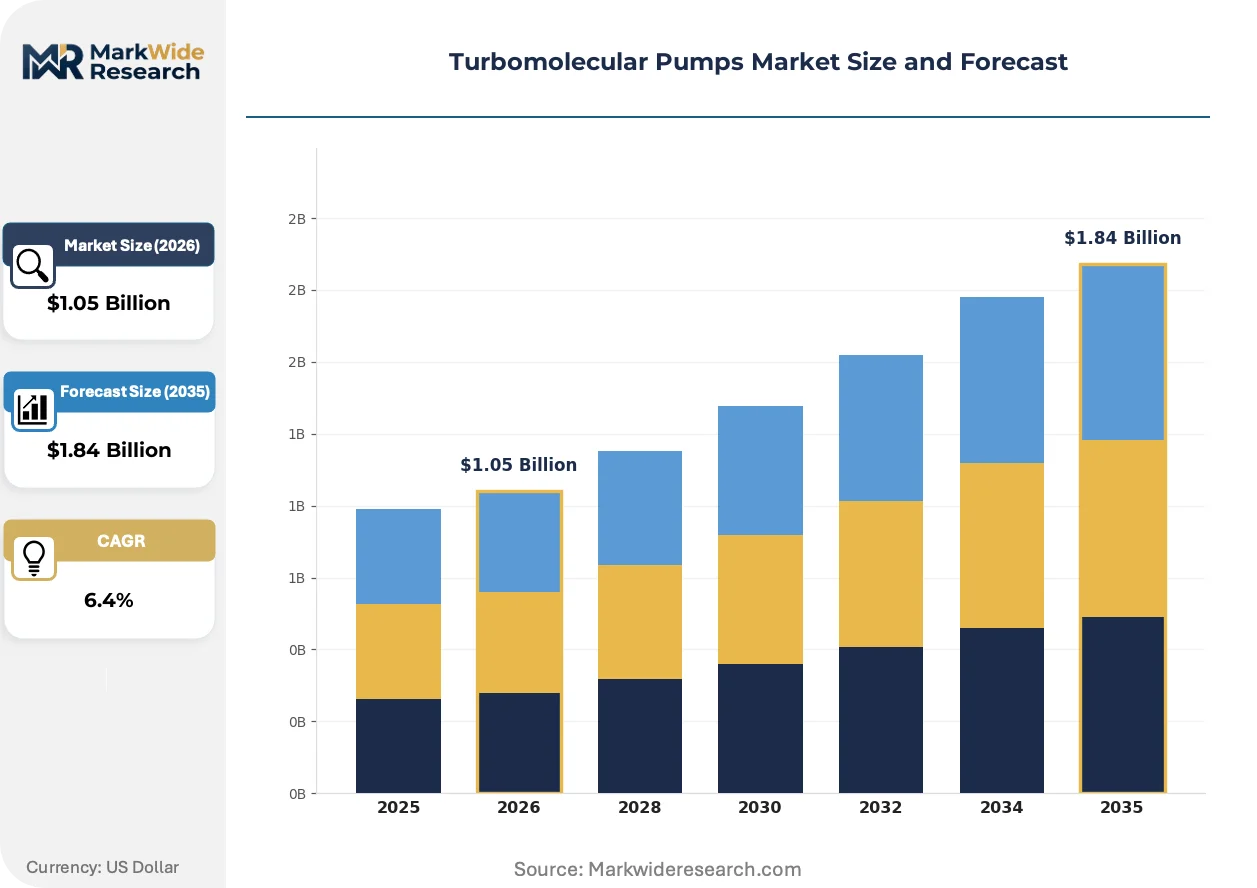
Market Dynamics
The semiconductor industry's capital expenditure cycle, particularly concentrated in China's electronics manufacturing clusters, is the central force shaping demand. This dictates technology requirements for ultra-high vacuum environments and drives investment in advanced pump capabilities like magnetic bearings, which are critical for contamination-sensitive processes.
Growth Catalysts
- Semiconductor Fab Expansion:Policy initiatives like the EU Chips Act are spurring investment in new fabrication plants, which require extensive high-vacuum systems for lithography and deposition processes.
- Advancements in Mass Spectrometry:Expanding use in life sciences and environmental analysis demands higher performance and oil-free pumps to ensure analytical precision and avoid sample contamination.
- R&D Investment:Government funding for fundamental physics research, particularly in large-scale projects, creates a stable, high-margin demand base for specialized ultra-high vacuum equipment.
Market Restraints
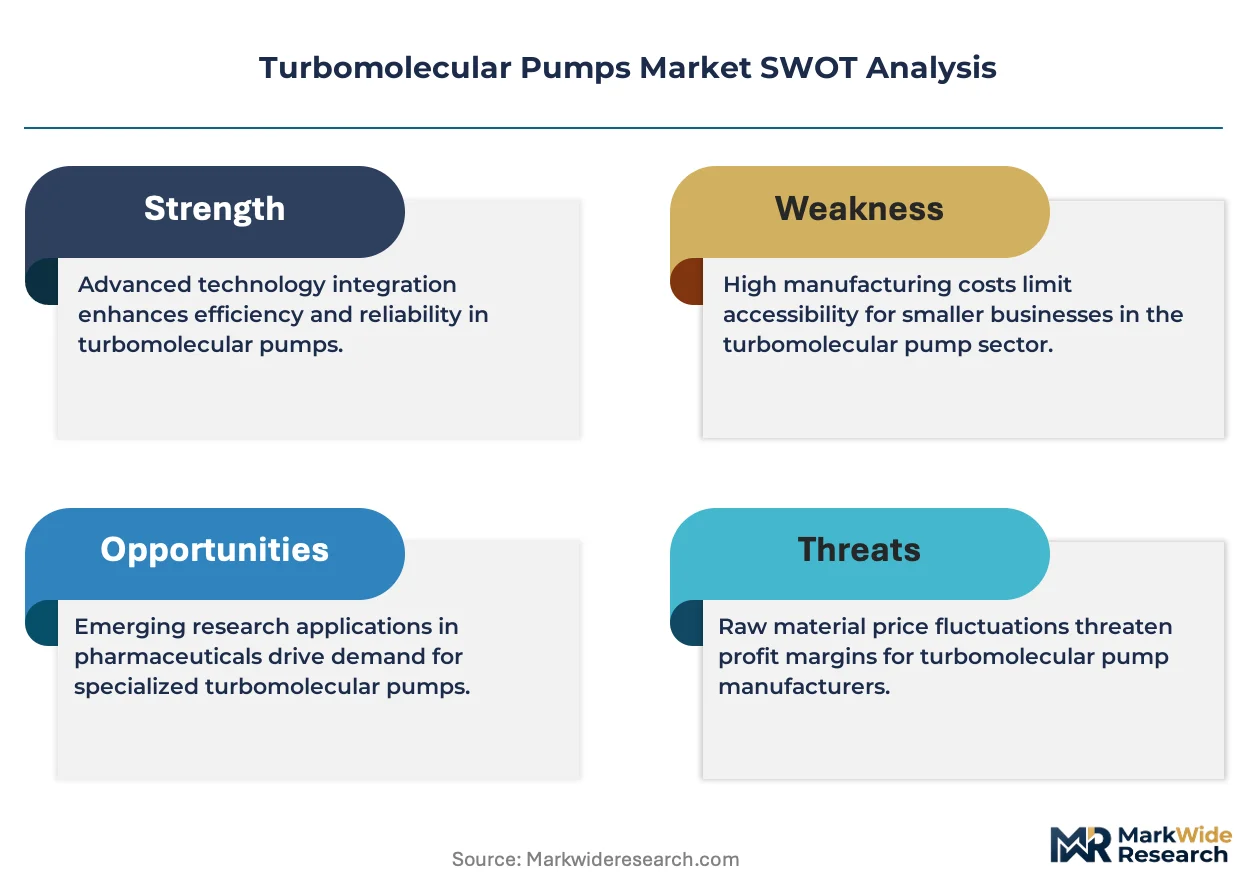
- High Initial Cost:The significant upfront investment for magnetic bearing turbomolecular pumps limits adoption in cost-sensitive academic research and smaller industrial applications.
- Specialized Component Sourcing:Reliance on a concentrated group of suppliers for high-precision rotors and advanced ceramic bearings creates supply chain vulnerabilities and price sensitivity.
- Maintenance Expertise:Servicing high-speed kinetic pumps requires specialized training, posing an operational barrier for end-users lacking dedicated in-house technical support staff.
Strategic Opportunities
- Solar PV Manufacturing:The scaling of production for next-generation photovoltaic cells, including perovskite technologies, opens a significant new application segment requiring vacuum deposition processes.
- Underpenetrated Geographies:Growth of electronics and medical device manufacturing in Southeast Asian countries like Vietnam and Malaysia presents new market entry points for vacuum equipment suppliers.
- Energy Efficiency Mandates:Developing pumps that comply with emerging energy efficiency benchmarks, guided by frameworks like the EU's Ecodesign Directive, offers a clear path for product differentiation.
Industry Challenges
- Skilled Technician Scarcity:A persistent shortage of trained personnel to install, operate, and service complex UHV systems slows equipment deployment and increases total cost of ownership for customers.
- Compliance Burden:Navigating the dual requirements of SEMI standards for semiconductor fabs and CE marking for European market access demands significant, ongoing engineering and documentation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turbomolecular Pumps Market |
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Speed Pumps, Compact Pumps, Variable Speed Pumps, Oil-Sealed Pumps, Dry Pumps Technology: Magnetic Bearing, Ball Bearing, Active Magnetic, Mechanical Bearing, Foil Bearing Application: Semiconductor Fabrication, Vacuum Coating, Mass Spectrometry, Particle Accelerators, Research Laboratories End User Industry: Electronics Manufacturing, Photovoltaic Production, Aerospace Engineering, Scientific Research |
| Companies Covered | Leybold GmbH, Agilent Technologies, Edwards Vacuum, Osaka Vacuum Ltd., Shimadzu Corporation, Pfeiffer Vacuum GmbH, ULVAC Technologies, KYKY Technology Co., Ltd., Ebara Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turbomolecular Pumps Market Strategic Shifts & Innovations
The market's technical evolution is defined by the pursuit of cleaner vacuum environments and reduced operational overhead. Innovations are focused on integrating intelligence into the pump itself to improve reliability and energy performance across critical applications.
Onboard diagnostics and integrated control electronics represent a key product evolution. Semiconductor fabs are the primary adopters, seeking to maximize equipment uptime. This integrated intelligence is virtualizing traditional maintenance schedules, shifting from fixed intervals to predictive, condition-based servicing that reduces unexpected downtime and lowers total cost of ownership.
European Union regulations, specifically the RoHS directive restricting hazardous substances, directly impact pump manufacturing. This rule forces redesigns of control units to eliminate materials like lead-based solders. Suppliers selling into European R&D and industrial markets are most affected, requiring full requalification of their electronic component supply chains to ensure compliance.
A behavioral shift toward comprehensive service agreements that bundle pump maintenance with support for entire vacuum systems is gaining traction. This model displaces transactional, single-component repair services, favoring suppliers with integrated system monitoring. The trend is most visible in semiconductor manufacturing clusters in Taiwan and South Korea, where tool availability is a primary performance metric.
Turbomolecular Pumps Market Segmentation
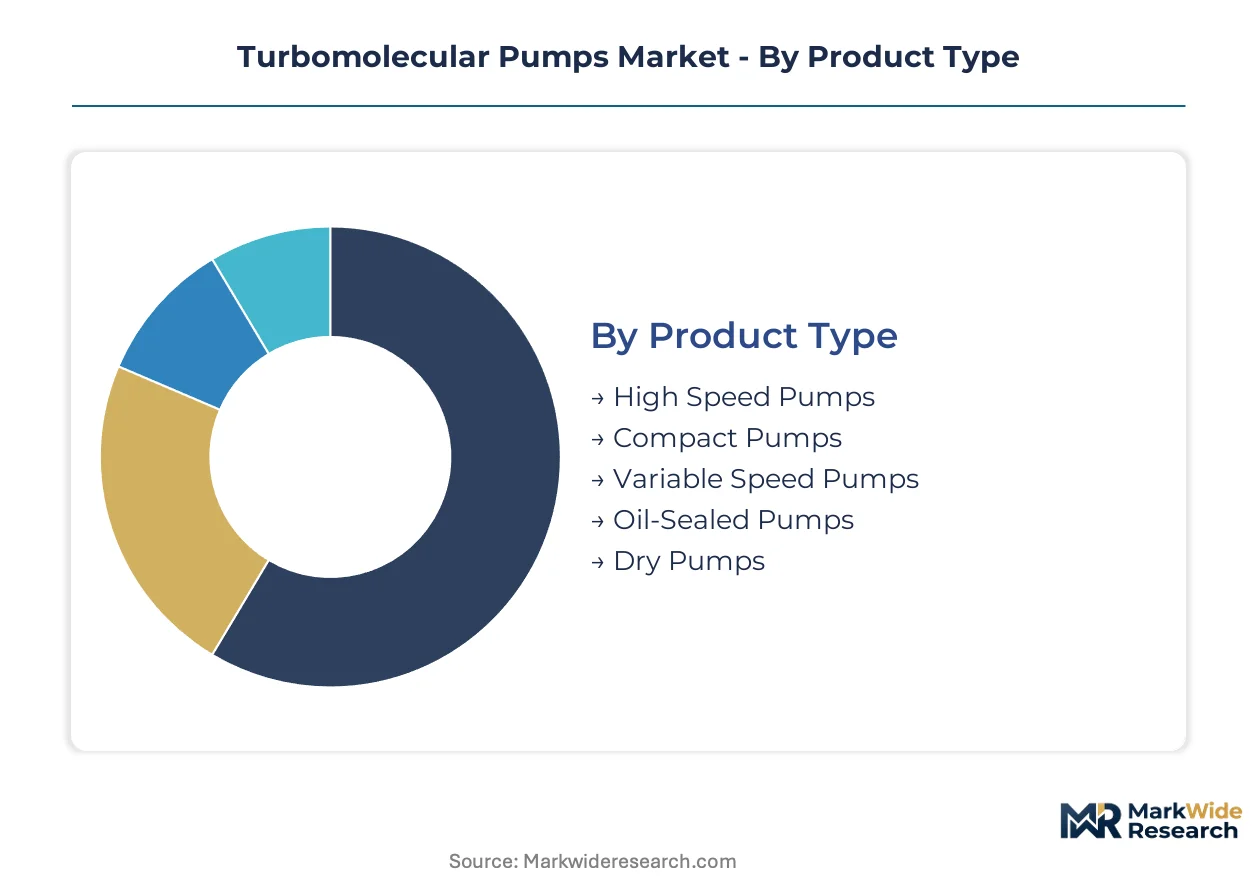
The turbomolecular pumps market is segmented by product type, technology, application, and end-user industry, reflecting the diverse technical requirements and operational environments of high-vacuum processes. Understanding these distinct segments is crucial for suppliers to tailor product development and market penetration strategies across the global industrial landscape.
Product Type:
Different product types within turbomolecular pumps exhibit varying turnover rates, with some designs evolving rapidly to meet new performance benchmarks while others maintain a stable, long-lifecycle presence in the market.
- High Speed Pumps:These pumps operate at very high rotational velocities, often exceeding 60,000 RPM, to achieve maximum pumping speed for light gases. Demand concentrates in semiconductor fabrication facilities in China and South Korea, where faster process times are critical for lithography and etching.
- Variable Speed Pumps:These advanced pumps allow for dynamic adjustment of rotational speed, optimizing performance for different gas loads and process conditions, which enhances energy efficiency. Their adoption is expanding in complex R&D environments and advanced materials processing where precise vacuum control is essential.
- Compact Pumps:These smaller footprint pumps are designed for integration into space-constrained systems, such as portable analytical instruments or compact research setups.
- Oil-Sealed Pumps:These traditional pumps utilize oil for lubrication and sealing, providing a cost-effective solution for less contamination-sensitive industrial applications.
- Dry Pumps:These pumps operate without any sealing or lubricating fluids, delivering a clean vacuum environment essential for sensitive processes.
High Speed Pumps dominate the installed base for performance-critical applications. Variable Speed Pumps are where expansion concentrates due to their adaptability and efficiency benefits.
Technology:
The cost structure of turbomolecular pump technologies varies significantly, influencing adoption patterns from high-end research to cost-sensitive industrial applications.
- Magnetic Bearing:This technology employs magnetic fields to levitate the rotor, eliminating mechanical contact and providing oil-free, vibration-free operation crucial for ultra-high vacuum. Magnetic bearing pumps command a premium due to their precision and reduced maintenance requirements in semiconductor fabs.
- Ball Bearing:Ball bearing pumps use conventional mechanical bearings, offering a lower initial cost and simpler design, making them accessible for a broader range of industrial and academic applications. Their maintenance cycles are typically shorter compared to magnetic bearing systems.
- Active Magnetic:This advanced magnetic bearing variant allows real-time control of rotor position, further enhancing stability and reducing vibration for highly sensitive processes.
- Mechanical Bearing:These pumps rely on physical contact bearings, representing a mature and cost-effective technology for less demanding vacuum applications.
- Foil Bearing:Foil bearings use gas films to support the rotor, offering a dry and relatively low-cost alternative to magnetic bearings for specific applications.
Magnetic Bearing technology sets the performance benchmark for high-purity environments. Ball Bearing technology maintains broad utility across diverse industrial sectors.
Application:
Turbomolecular pump applications are highly specialized, with each segment demanding specific performance characteristics and contributing differently to market stability and growth.
- Semiconductor Fabrication:This segment requires ultra-high vacuum conditions for critical processes like deposition, etching, and ion implantation, driving demand for magnetic bearing pumps. Investment in new fabrication plants in China and Europe directly fuels growth in this application.
- Mass Spectrometry:High-performance turbomolecular pumps are essential for maintaining the vacuum required for ion separation and detection in analytical instruments. This application demands oil-free pumps to prevent sample contamination and ensure analytical precision in life sciences.
- Vacuum Coating:These applications, including architectural glass and decorative coatings, utilize turbomolecular pumps for thin-film deposition processes.
- Particle Accelerators:Large-scale scientific research facilities rely on these pumps to achieve and maintain extreme high vacuum for particle beam stability.
- Research Laboratories:Academic and industrial research facilities use turbomolecular pumps for various experiments requiring controlled vacuum environments.
Demand from Semiconductor Fabrication dictates technological evolution. Mass Spectrometry offers stable, specialized revenue streams.
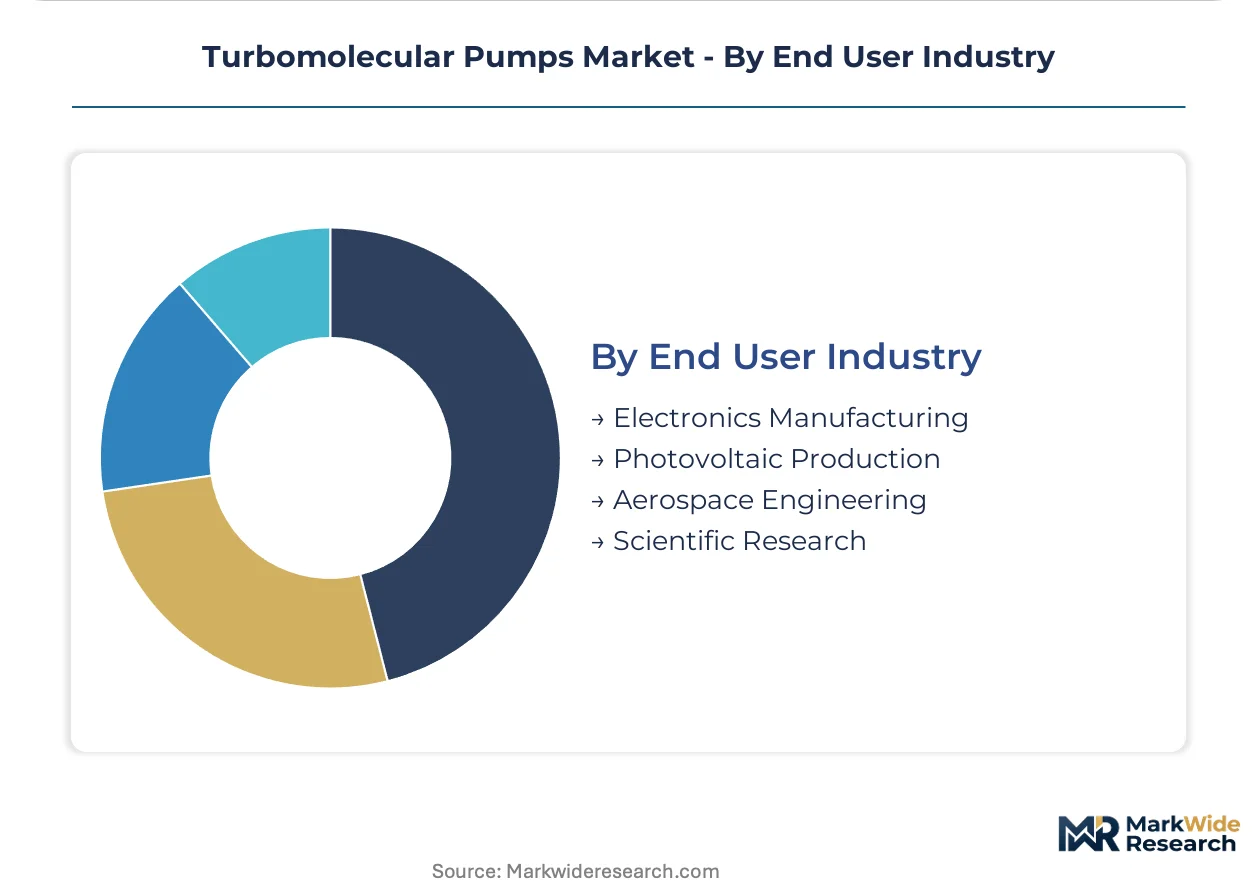
End User Industry:
The end-user industries for turbomolecular pumps vary significantly in their procurement scale and technical requirements, influencing supplier engagement models and product development cycles.
- Electronics Manufacturing:This industry, encompassing integrated circuits and display production, represents the largest volume consumer of turbomolecular pumps. Facilities in Taiwan and South Korea prioritize high throughput and uptime, driving demand for integrated diagnostics.
- Scientific Research:This segment includes universities, government labs, and private research institutions, often requiring highly specialized and custom vacuum solutions for fundamental physics and materials science. Government funding for large-scale projects creates stable, high-margin demand.
- Photovoltaic Production:The manufacturing of solar cells, particularly advanced perovskite technologies, requires vacuum deposition processes for thin-film layers.
- Aerospace Engineering:Vacuum chambers are critical for testing spacecraft components and simulating high-altitude conditions.
The largest volume is concentrated in Electronics Manufacturing. Scientific Research represents a growing opportunity for specialized equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The market for turbomolecular pumps exhibits a distinct geographical concentration in key electronics manufacturing hubs. Semiconductor fabrication expansion, particularly in East Asia, drives significant demand for ultra-high vacuum equipment. Policy initiatives like the EU Chips Act further stimulate investment in advanced manufacturing facilities across Europe.
China
Demand for high-speed turbomolecular pumps in China stems from its rapidly expanding integrated circuit and display production. The Chinese government's dual carbon goals influence manufacturing processes and material selection for vacuum equipment. Electronics manufacturing clusters in the Yangtze River Delta and Pearl River Delta are scaling up production capacities.
South Korea
South Korea's robust semiconductor and display manufacturing sectors require continuous investment in advanced vacuum technology. The country's national manufacturing policies promote high-throughput and contamination-sensitive processes. Major fabrication facilities in Gyeonggi Province prioritize integrated diagnostics for maximum tool availability.
Germany
Germany's strong industrial and R&D base creates stable demand for specialized ultra-high vacuum equipment. Compliance with CE marking and the EU's RoHS directive dictates pump design and material choices for European suppliers. Research laboratories and industrial clients in Bavaria and Baden-Württemberg require high-performance, compliant systems.
United States
The United States benefits from significant R&D investment in fundamental physics and advanced materials science. Federal funding initiatives support large-scale projects requiring specialized ultra-high vacuum environments. Silicon Valley and other tech hubs drive demand for clean, oil-free pumps in advanced semiconductor research.
Japan
Japan maintains a strong position in advanced materials processing and precision instrumentation, necessitating high-performance vacuum solutions. METI regulations often guide technology development towards energy efficiency and environmental compliance. Tokyo's research institutions and industrial centers in Kansai continue to innovate in vacuum coating and analytical applications.
Turbomolecular Pumps Market Key Industry Players
Specialized equipment providers and diversified industrial conglomerates split the market for turbomolecular pumps. The competitive landscape features distinct segments for niche technology leaders, cost-effective generalists, and integrated system suppliers. Strategic archetypes include those focused on ultra-high vacuum performance and others emphasizing broad industrial utility. Dominant competitive moves involve both technology licensing and strategic partnerships, alongside continuous product portfolio diversification to expand market reach.
Within the high-performance segment, Pfeiffer Vacuum GmbH, a German-based entity, represents a long-standing presence in vacuum technology, catering to specialized industrial and R&D clients. Edwards Vacuum, as a solutions provider, exemplifies specialization for critical applications requiring stringent performance and reliability, particularly in semiconductor manufacturing. ULVAC Technologies, a Japanese company, occupies a position with a broad portfolio across diverse applications, from electronics production to fundamental research. These companies collectively anchor the market for demanding industrial and research environments.
| Leading Market Players |
|---|
| Leybold GmbH |
| Agilent Technologies |
| Edwards Vacuum |
| Osaka Vacuum Ltd. |
| Shimadzu Corporation |
| Pfeiffer Vacuum GmbH |
| ULVAC Technologies |
| KYKY Technology Co., Ltd. |
| Ebara Corporation |
| Others |
Cost & Logistics Intelligence
Single-source dependency for high-precision rotors and advanced ceramic bearings determines both pricing tier spreads and the overall supply chain shape in the turbomolecular pumps market.
Pricing Analysis
CE marking dictates the pricing tier structure for turbomolecular pumps sold into European markets, ensuring compliance costs are factored. The dominant pricing model is value-based for high-performance magnetic bearing pumps, reflecting their precision and reliability. Price differentiation stems from performance specifications, such as rotational speed and ultimate vacuum, and also from the level of integrated diagnostics offered. Pricing pressure stems from increased competition in the ball bearing segment, particularly for less contamination-sensitive industrial applications. Academic research and smaller industrial applications represent the most price-sensitive buyer segments, while semiconductor fabrication facilities exhibit lower price sensitivity due to critical process requirements.
Supply Chain Analysis
Upstream feedstock for advanced ceramic bearings and high-purity metals primarily sources from specialized manufacturers in Germany, Japan, and South Korea. Raw material dependencies include rare earth elements for magnetic components and high-strength alloys for rotors. The primary supply chain risk is single-source vulnerability for these specialized, high-precision components, which can lead to lead time extensions. Distribution runs through a combination of direct sales channels for major semiconductor OEMs and a network of specialized technical distributors for research laboratories and smaller industrial clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The turbomolecular pumps market is undergoing a buyer-power shift, driven by the consolidated procurement needs of large semiconductor manufacturing clusters in Asia and Europe.
For Market Incumbents:Insulate core market share by investing heavily in next-generation magnetic bearing technology, focusing on even lower vibration and higher energy efficiency. Expand comprehensive service agreements, especially in critical semiconductor fabrication regions like Taiwan and South Korea, to counter emerging competitive threats from regional players. Vertical integration into critical component manufacturing, such as advanced control electronics, can mitigate supply chain risks and protect margins against commodity price volatility.
For New Entrants and Emerging Players:Pursue white-space opportunities in underpenetrated geographies, specifically the growing electronics and medical device manufacturing sectors in Southeast Asian countries like Vietnam and Malaysia. The most penetrable segment lies within compact pumps designed for portable analytical instruments, where footprint and energy efficiency are paramount. A viable go-to-market angle involves offering cost-effective, compliant solutions specifically tailored to emerging energy efficiency benchmarks, guided by frameworks like the EU's Ecodesign Directive.
For Investors and Strategic Acquirers:The market sits at a mature growth phase that favors specialized technology providers with strong intellectual property and established compliance frameworks. Long-term viability remains robust, anchored by persistent demand from the semiconductor and scientific research sectors. Acquisition targets should include specialized component manufacturers for advanced ceramic bearings or niche software developers for integrated diagnostics. A key signal to watch is the capital expenditure cycles of major semiconductor foundries in China and South Korea, indicating future demand spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Magnetic Bearing R&D | Enhances performance leadership for contamination-sensitive semiconductor processes. |
| Expand Comprehensive Service Agreements | Secures recurring revenue and maximizes equipment uptime for electronics manufacturers. |
| Target Southeast Asian Electronics Manufacturing | Captures growth in emerging markets with expanding production capacities. |
| Develop Energy-Efficient Pump Solutions | Addresses evolving regulatory mandates and offers product differentiation in Europe. |
| Acquire Specialized Component Manufacturers | Mitigates single-source dependency and strengthens supply chain control for OEMs. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews with industry stakeholders and rigorous secondary validation of market intelligence. The study incorporated insights from R&D directors, procurement managers at leading semiconductor fabrication facilities, vacuum equipment engineers, and academic researchers specializing in ultra-high vacuum applications. Secondary data sources included industry association reports, company annual reports, government science funding databases, and relevant patent filings. A robust bottom-up and top-down triangulation approach ensured comprehensive market sizing and validation.
Forecast inputs being considered included historical market performance and projected demand drivers across the analysis window. The analytical framework modeled market dynamics across key segmentation dimensions: product type, technology, application, end-user industry, and regional investment cycles. Compound annual growth rates were derived from a synthesis of historical data trends and forward-looking projections based on anticipated capital expenditure in the electronics sector and government funding for scientific research. Semiconductor capital expenditure and government R&D funding were critical industry-specific forecast inputs.
Sensitivities concentrate around macroeconomic shifts, geopolitical trade policies, and technological breakthroughs that could revise forecasts. The forecasts reflect assumptions documented through expert consensus and quantitative modeling. Cross-checking against major semiconductor industry reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Global Positive Displacement (PD) Pumps Market
Pumps and Control Devices
Magnetic Drive Pumps Market
Pumps and Control Devices
Volute Pump Market
Pumps and Control Devices
Regenerative Turbine Pump Market
Pumps and Control Devices
Fertilizer Injection Pumps Market
Pumps and Control Devices
Air-Operated Double Diaphragm (AODD) Pumps Market
Pumps and Control Devices
Sanitary Pumps Market
Pumps and Control Devices
Global Hydraulic Gear Pump Market
Pumps and Control Devices
Liquid Ring Vacuum Pump Market
Pumps and Control Devices
Spiral Classifier Market
Pumps and Control Devices
APAC Centrifugal Pumps Market
Pumps and Control Devices
Chemical Pump Market
Pumps and Control Devices
Electrostatic Spraying System Market
Pumps and Control Devices
Dewatering Pumps Market
Pumps and Control Devices
Asia Pacific Industrial Pumps Market
Pumps and Control Devices
Global Compressor Control Systems Market