
 Membrane Pump Market | 2026-2036
Membrane Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Membrane Pump Market Analysis
China's Jiangsu and Zhejiang provinces is fragmenting as local pump fabricators expand diaphragm production lines. Ingersoll Rand leverages its compressor technology heritage to anchor high-pressure industrial applications. Grundfos Holding sustains leadership in water treatment integration through intelligent pump controls. KNF Neuberger specializes in precision gas-handling diaphragm systems for laboratory and medical environments.
A membrane pump displaces fluid through the oscillation of an elastomeric or thermoplastic diaphragm, typically achieving flow rates from microliters per minute to hundreds of cubic meters per hour while maintaining hermetic separation between process fluid and mechanical drive. Its primary purpose is to transfer corrosive, abrasive, sterile, or shear-sensitive fluids without contamination or leakage. Diaphragm pumps occupy the largest value share due to their versatility across chemical resistance profiles and pressure ranges. Electric pumps represent the fastest-expanding installation category as industrial facilities replace compressed-air infrastructure with energy-efficient motor drives. Water treatment end users generate concentrated margin pools where OEM service contracts and predictive maintenance bundling extend customer lifetime value.
The EPA enforces emissions and effluent standards that compel chemical processors to specify zero-leakage pump architectures for volatile organic compound handling. REACH and RoHS constrain elastomer selection in European supply chains, favoring perfluoroelastomer and advanced thermoplastic diaphragm materials with documented substance safety. FDA cGMP guidelines govern pump surface finish and cleanability protocols for pharmaceutical manufacturing equipment. Stakeholders must monitor how regional decarbonization mandates reshape energy source preferences between pneumatic and electric drive configurations.
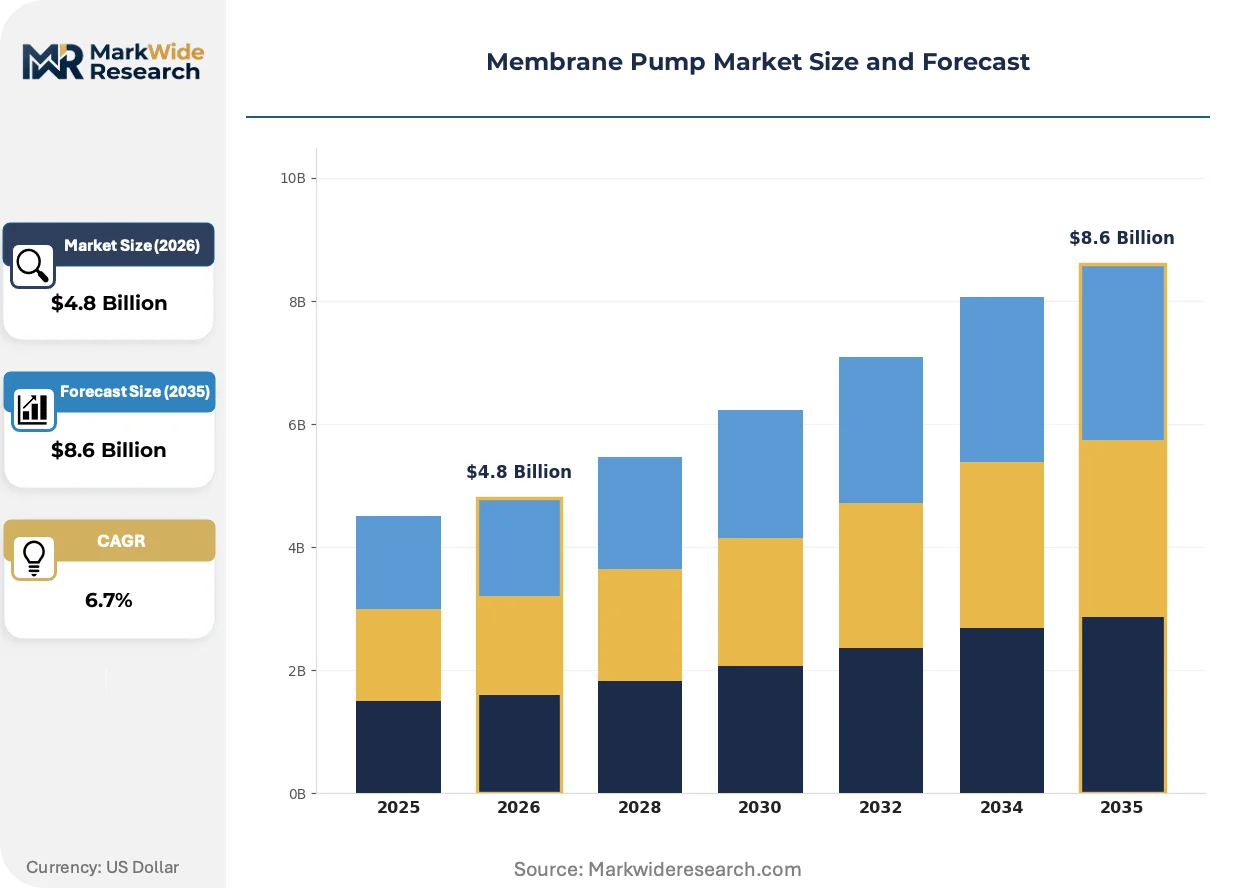
Market Dynamics
Electric drive architectures are displacing pneumatic infrastructure across chemical processing and water treatment facilities, compressing the installed base of compressed-air systems while expanding addressable margins for motor-integrated pump OEMs.
Growth Catalysts
- EU MDR material traceability:Tighter documentation requirements for wetted components are locking in premium diaphragm suppliers with certified supply chains across German pharmaceutical manufacturing.
- Perfluoroelastomer diaphragm adoption:Advanced elastomer formulations meeting REACH and RoHS substance restrictions are opening replacement cycles in corrosive chemical handling throughout European process industries.
- Jiangsu-Zhejiang manufacturing corridor:Concentrated pump demand from China's eastern coastal chemical and electronics clusters is pulling dedicated diaphragm production capacity into regional fabrication networks.
Market Restraints
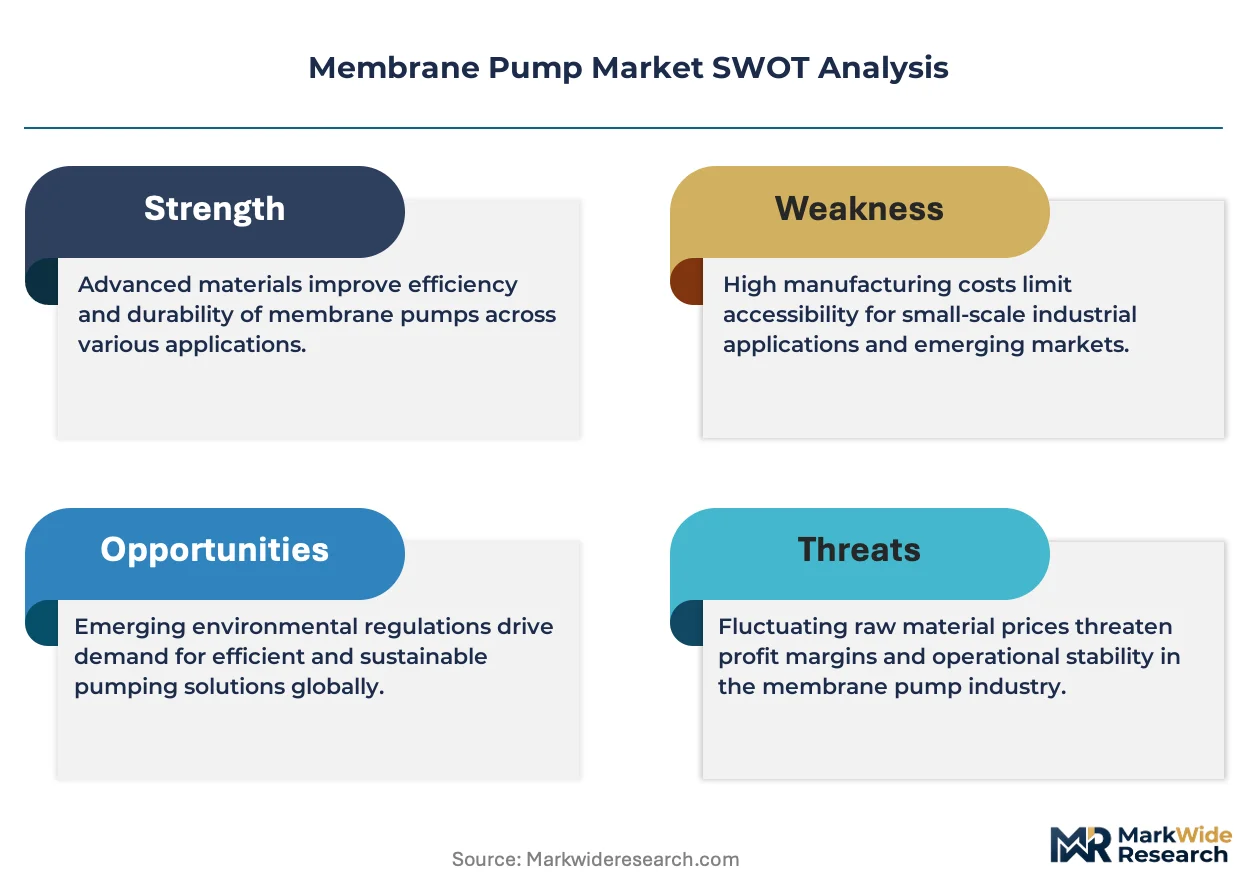
- Fluoropolymer feedstock volatility:Perfluoroelastomer and PTFE diaphragm materials face input cost instability tied to fluorochemical regulatory phase-downs in multiple jurisdictions.
- Precision machining concentration:High-tolerance pump head manufacturing for sterile applications clusters among specialized European and Japanese machine shops, creating single-source vulnerability.
- Compressed-air infrastructure lock-in:Legacy pneumatic pump installations in mature chemical plants resist capital replacement despite electric drive efficiency advantages.
Strategic Opportunities
- Predictive maintenance bundling:OEM service contracts integrating vibration sensing and diaphragm wear monitoring are extending customer lifetime value in water treatment end-use segments.
- EPA zero-leakage mandates:Emissions enforcement for volatile organic compound handling is mandating hermetic pump architectures in US chemical processing, favoring diaphragm technology over mechanical seals.
- Intelligent pump control convergence:Integration of variable frequency drives with pressure-feedback algorithms is enabling energy-optimized operation in distributed water treatment networks.
Industry Challenges
- Surface finish certification timelines:FDA cGMP validation for pharmaceutical pump installations extends qualification periods, compressing effective sales windows within capital budget cycles.
- Cross-contamination protocol complexity:Multi-product biopharma facilities demand rapid changeover validation, straining pump cleanability documentation and operator training regimes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Membrane Pump Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diaphragm Pumps, Air-operated Pumps, Electric Pumps, Hydraulic Pumps End User: Water Treatment, Food & Beverage, Chemical Processing, Pharmaceuticals Installation: Onshore, Offshore, Portable, Fixed Size: Small, Medium, Large, Extra Large |
| Companies Covered | Ingersoll Rand, Flowserve Corporation, Grundfos Holding, Xylem, LEWA GmbH, Dover Corporation, Idex Corporation, KNF Neuberger, Verder International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Membrane Pump Market Emerging Trajectories
Sensor-embedded diaphragm systems and cloud-connected drive controls are converging to enable condition-based maintenance models that shift revenue from equipment sales to recurring service streams.
Smart diaphragm monitoring is digitizing pump reliability management. Pressure transducers and accelerometers embedded in pump heads transmit real-time elastomer stress data to centralized maintenance platforms. Water treatment utilities and chemical processors are piloting these systems at scale. The technology is digitizing traditional time-based maintenance schedules into predictive replacement workflows that reduce unplanned downtime.
REACH substance restrictions are compressing elastomer formulation options. ECHA regulatory updates targeting per- and polyfluoroalkyl substances are forcing diaphragm suppliers to qualify alternative chemistries with equivalent chemical resistance profiles. European process industries face accelerated material requalification timelines. Pharmaceutical and fine chemical manufacturers in Germany and Switzerland are most affected, driving collaborative R&D between pump OEMs and compounders.
Specification authority is consolidating among engineering-procurement-construction firms. Large infrastructure and industrial project developers are centralizing pump selection decisions within centralized technical standards, reducing direct end-user influence. Tier-1 EPCs in Middle Eastern desalination and Asian chemical complexes now dictate approved vendor lists. This concentration is visible in Saudi Arabia's water sector and Singapore's industrial park developments, where master specifications favor pre-qualified diaphragm pump platforms.
Membrane Pump Market Segmentation
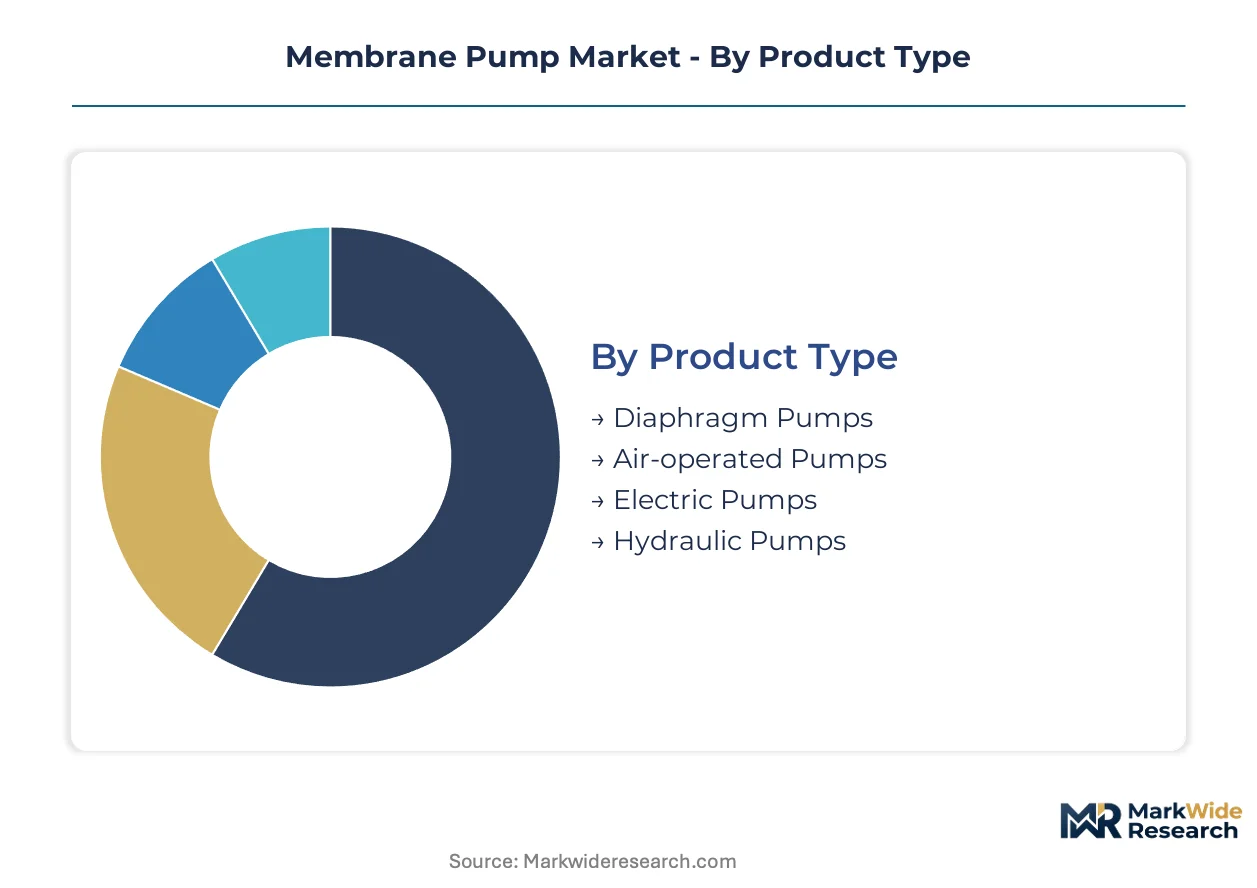
Membrane pump procurement decisions cascade through multiple technical dimensions. Product architecture determines chemical compatibility and energy sourcing. End-use requirements dictate material certifications and surface finish protocols. Installation context and flow capacity specifications complete the specification matrix.
Product Type:
Use-case spectrum spans laboratory precision dosing to heavy industrial chemical transfer, with drive mechanism and pressure capability as the primary differentiators.
- Diaphragm Pumps:Elastomeric or thermoplastic diaphragm oscillation achieves hermetic fluid isolation across microliter-to-cubic-meter flow ranges. German pharmaceutical manufacturers specify these for sterile fluid handling under EU MDR traceability mandates. Established volume favors Diaphragm Pumps; emerging adoption favors Electric Pumps.
- Electric Pumps:Motor-integrated architectures eliminate compressed-air infrastructure while enabling variable frequency drive optimization. Industrial facilities in China's Jiangsu-Zhejiang corridor are replacing pneumatic systems with these configurations to meet dual carbon goals.
- Air-operated Pumps:Pneumatic double-diaphragm designs persist in explosive atmosphere applications and legacy chemical plants where electrical classification upgrades prove capital-intensive.
- Hydraulic Pumps:Fluid-power drive systems serve ultra-high-pressure applications in oilfield services and specialized industrial processes requiring precise pressure control.
Cost tier stratification separates premium electric drives from commodity pneumatic alternatives.
End User:
Regulatory intensity and fluid purity requirements create divergent procurement patterns across process industries.
- Water Treatment:Predictive maintenance bundling and OEM service contracts extend customer lifetime value in municipal and industrial water networks. EPA zero-leakage mandates for volatile organic compound handling favor hermetic diaphragm architectures over mechanical seals.
- Pharmaceuticals:FDA cGMP surface finish and cleanability protocols govern equipment qualification timelines. Multi-product biopharma facilities demand rapid changeover validation, straining documentation and operator training regimes.
- Chemical Processing:REACH and RoHS substance restrictions constrain elastomer selection, favoring perfluoroelastomer diaphragms with documented safety profiles in European process industries.
- Food & Beverage:Hygienic design standards and clean-in-place compatibility drive specification toward electropolished surfaces and FDA-compliant elastomer formulations.
Margin concentration pools in Water Treatment service contracts; qualification complexity concentrates in Pharmaceuticals.
Installation:
Deployment context determines structural requirements, mobility needs, and integration with existing infrastructure.
- Fixed:Permanent installations dominate municipal water treatment and continuous chemical processing operations where capital equipment amortization favors long operational lifecycles.
- Portable:Mobile configurations serve emergency response, temporary process bypass, and field service applications in distributed industrial networks.
- Onshore:Ground-based installations encompass the majority of manufacturing, utility, and commercial applications with standard environmental protection ratings.
- Offshore:Marine-grade specifications with enhanced corrosion resistance and compact footprints address oil platform and coastal desalination requirements.
Application maturity favors Fixed installations; operational flexibility favors Portable configurations.
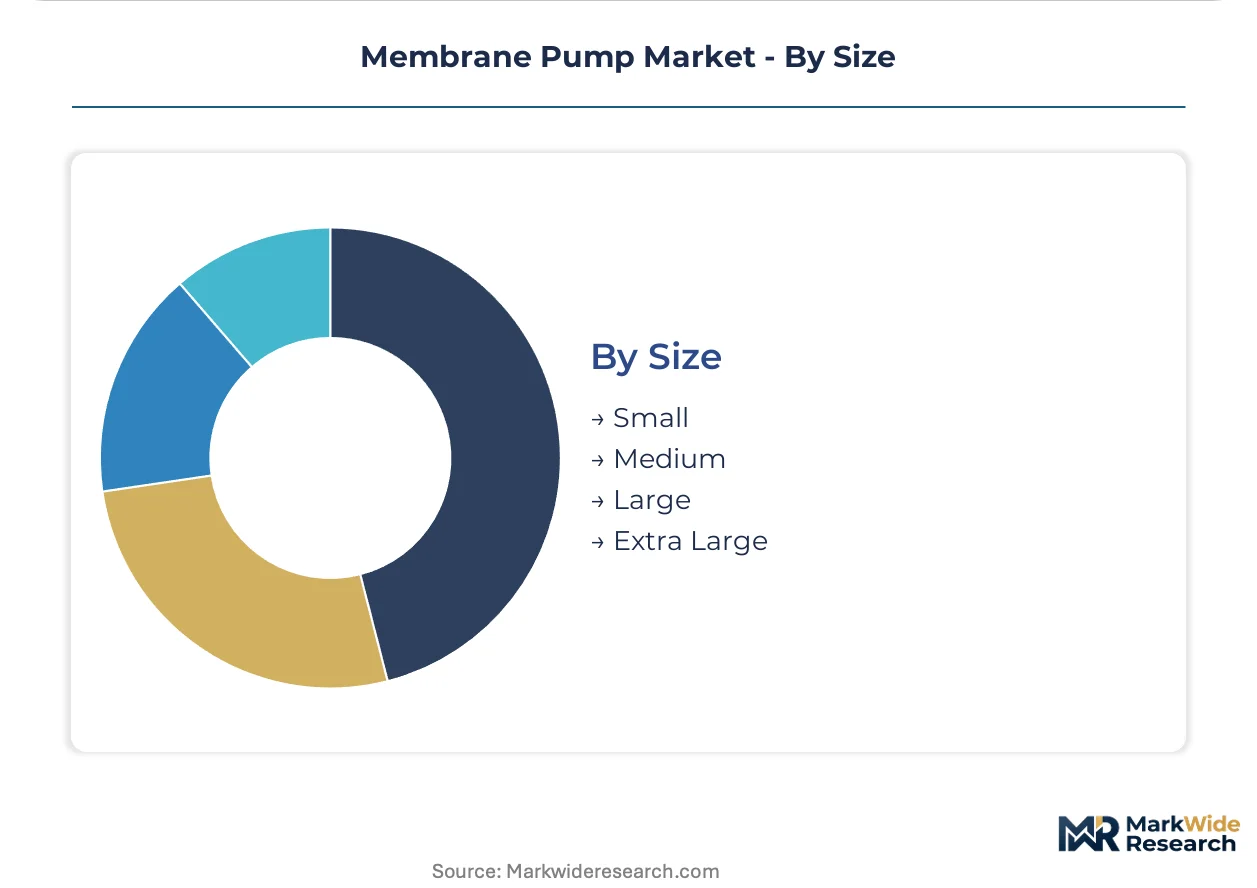
Size:
Flow capacity and physical footprint correlate with end-use scale and integration constraints.
- Medium:Balanced capacity-to-footprint ratios serve distributed chemical processing and commercial water treatment where space optimization matters.
- Large:High-volume configurations address centralized municipal treatment and bulk chemical transfer with minimized unit count.
- Small:Compact designs integrate into analytical instrumentation, medical devices, and precision dosing skids where milliliter accuracy dominates.
- Extra Large:Custom-engineered systems handle exceptional flow requirements in desalination plants and major industrial complexes.
Procurement volume concentrates in Medium and Large; specification diversity concentrates in Small.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA zero-leakage mandates for volatile organic compound handling are reshaping procurement patterns in the United States, while EU MDR material traceability requirements tighten supply chain documentation across German pharmaceutical manufacturing corridors.
United States
Chemical processors in the Gulf Coast petrochemical belt are retrofitting facilities with hermetic diaphragm architectures to satisfy EPA emissions enforcement. The EPA enforces effluent standards that compel zero-leakage specifications for volatile organic compound handling. Houston-area refineries and Baton Rouge chemical complexes are consolidating approved vendor lists around pre-qualified diaphragm pump platforms.
Germany
Pharmaceutical manufacturers in Baden-Württemberg and Bavaria are expanding membrane pump procurement for sterile fluid handling under tightened documentation regimes. The EU MDR mandates material traceability for all wetted pump components in medical device applications. Stuttgart and Munich industrial clusters are locking in premium diaphragm suppliers with certified supply chains.
China
Jiangsu and Zhejiang province manufacturers are replacing compressed-air systems with electric drive configurations to satisfy national dual carbon goals. The MEE enforces emissions standards that accelerate energy-efficient motor adoption in coastal chemical processing. Suzhou and Hangzhou electronics clusters are pulling dedicated diaphragm production capacity into regional fabrication networks.
Japan
Precision gas-handling applications in Osaka and Tokyo metropolitan laboratories are sustaining demand for specialized diaphragm systems. METI industrial efficiency guidelines favor intelligent pump controls with integrated variable frequency drives. Nagoya automotive chemical suppliers are qualifying advanced thermoplastic diaphragm materials for corrosive fluid transfer.
Switzerland
Fine chemical manufacturers in Basel and Zurich pharmaceutical corridors face accelerated material requalification timelines under ECHA substance restrictions. Swissmedic governs medical device component documentation parallel to EU MDR requirements. Basel-Land chemical parks are driving collaborative R&D between pump OEMs and perfluoroelastomer compounders.
Membrane Pump Market Vendor Landscape
Capability concentration sits with specialized European and Japanese fabricators; scale advantage sits with diversified industrial conglomerates. The vendor base organizes into three tiers: integrated multinational pump divisions with water treatment service networks, precision diaphragm specialists serving pharmaceutical and laboratory niches, and regional fabricators capturing chemical processing replacement cycles. Dominant competitive moves include predictive maintenance bundling that extends customer lifetime value, and strategic partnerships between pump OEMs and advanced elastomer compounders to secure REACH-compliant material supply.
Among diversified industrial holdings, Ingersoll Rand and Flowserve Corporation exemplify scale-driven architectures with compressor technology heritage anchoring high-pressure industrial applications. Grundfos Holding occupies a position within the intelligent controls tier, sustaining leadership in water treatment integration through motor-integrated drive optimization. KNF Neuberger represents the precision specialist archetype, with German GmbH structure indicating focused engineering heritage in laboratory and medical gas-handling diaphragm systems.
| Leading Market Players |
|---|
| Ingersoll Rand |
| Flowserve Corporation |
| Grundfos Holding |
| Xylem |
| LEWA GmbH |
| Dover Corporation |
| Idex Corporation |
| KNF Neuberger |
| Verder International |
| Others |
Supply Flow & Price Mechanics
Fluoropolymer feedstock volatility tied to regulatory phase-downs across multiple jurisdictions compresses margin structures while simultaneously reshaping supplier geography toward captive compounders in Germany and Japan. This input-cost instability widens spreads between REACH-certified premium diaphragm tiers and commodity elastomer alternatives, forcing procurement teams to balance compliance documentation against unit economics.
Pricing Analysis
European pharmaceutical manufacturers pay 15-25% premiums over Gulf Coast chemical processors for identical pump architectures due to EU MDR traceability documentation and perfluoroelastomer certification requirements. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical units from industrial chemical configurations and replacement diaphragm aftermarket. Pricing pressure stems from fluorochemical regulatory restrictions constraining elastomer formulation options. Municipal water utilities exhibit highest price sensitivity due to capital budget rigidity, while German biopharma facilities demonstrate lowest sensitivity given qualification timeline costs.
Supply Chain Analysis
Export-control regimes limiting precision machining technology flows constrain high-tolerance pump head manufacturing to specialized European and Japanese fabricators. Germany, Switzerland, and Japan anchor diaphragm supply chains for sterile applications, while China dominates electric drive motor integration and Jiangsu-Zhejiang corridor fabrication networks. Raw material dependencies center on perfluoroelastomer compounds, PTFE diaphragm substrates, and precision-machined ceramic pump heads. Single-source vulnerability clusters in European machine shops serving pharmaceutical validation requirements. Distribution runs through engineering-procurement-construction firms consolidating approved vendor lists in Middle Eastern desalination and Asian chemical complex developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision machining capacity for sterile pump heads concentrates among a handful of specialized European and Japanese suppliers, creating a structural bottleneck that determines competitive access to pharmaceutical margin pools. This capability scarcity rewards early qualification investments and long-term supply agreements with certified fabricators.
For Market Incumbents: Insulate market position through backward integration into perfluoroelastomer compounding capabilities or exclusive partnerships with REACH-certified material suppliers, while expanding predictive maintenance service contracts in water treatment segments to capture recurring revenue streams against emerging electric-drive competitors. For New Entrants and Emerging Players: Build out portable pump configurations for emergency response and temporary process bypass applications where qualification timelines compress and price sensitivity moderates, targeting China's Jiangsu-Zhejiang manufacturing corridor through direct sales to electronics cluster maintenance departments. For Investors and Strategic Acquirers: The market sits at a substitution-acceleration phase that favors precision diaphragm specialists with established pharmaceutical validation records over diversified industrial conglomerates with compressed-air heritage. Long-term viability over the next decade hinges on intelligent control integration and material chemistry R&D capabilities. Acquisition targets should demonstrate documented EU MDR supply chain certification and active predictive maintenance pilot programs. The signal to watch is ECHA regulatory updates targeting per- and polyfluoroalkyl substances, which would force accelerated material requalification timelines and favor compounders with alternative chemistry pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Perfluoroelastomer Compounding | REACH compliance and supply security anchor pharmaceutical pricing power against commodity competitors. |
| Predictive Maintenance Service Bundling | Water treatment utilities in the United States and Germany pilot vibration-sensing contracts extending customer lifetime value. |
| Electric Drive Platform Standardization | Jiangsu-Zhejiang corridor manufacturers replace pneumatic infrastructure under China's MEE emissions enforcement. |
| Pharmaceutical Surface Finish Certification Investment | FDA cGMP validation timelines in German Baden-Württemberg clusters lock in premium supplier relationships. |
| Intelligent Pump Control Convergence | Variable frequency drive integration with pressure-feedback algorithms enables energy optimization in distributed networks. |
Methodological Framework
Cross-validation between primary interviews with pump OEM product managers, EPC procurement leads, pharmaceutical maintenance directors, and water utility operations managers anchors the qualitative findings against secondary validation through SEC filings of diversified industrial holdings, customs trade data on fluoropolymer imports, EPA enforcement action databases, and ECHA substance restriction updates. Bottom-up triangulation across installation base estimates and top-down reconciliation against capital expenditure disclosures in chemical processing and water treatment sectors ensures dimensional consistency.
Calibration against historical replacement cycle data and documented qualification timelines in pharmaceutical manufacturing refines the analytical framework across the projection horizon. Segmentation dimensions modeled include drive mechanism architecture, end-use regulatory intensity, installation mobility requirements, and flow capacity tiers. CAGRs were derived from elasticity-adjusted demand curves incorporating energy efficiency mandates and emissions enforcement trajectories. Industry-specific forecast inputs include EPC vendor list consolidation patterns and REACH substance restriction implementation schedules.
Stress conditions across fluoropolymer feedstock availability, precision machining capacity utilization, and electric drive adoption rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and substitution elasticity in pneumatic-to-electric transitions. Material shifts in ECHA per- and polyfluoroalkyl substance regulatory scope or EPA zero-leakage mandate expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Middle East and Africa Positive Displacement Pumps Market
Pumps and Control Devices
Dewatering Pumps Market
Pumps and Control Devices
Vane Pump Market
Pumps and Control Devices
Global Diaphragm Pump Market
Pumps and Control Devices
Flow Back Equipment Market
Pumps and Control Devices
Glycol Pumps Market
Pumps and Control Devices
Twin Screw Pumps Market
Pumps and Control Devices
Bubble Membrane Disc Diffuser Market
Pumps and Control Devices
Progressive Cavity Pump (PCP) Market
Pumps and Control Devices
Europe Asia Submerged Pump Market
Pumps and Control Devices
Subsea Pumps Market
Pumps and Control Devices
Pool Heat Pumps Market
Pumps and Control Devices
Rental Industrial Pump Market
Pumps and Control Devices
Dispensing Pump Market
Pumps and Control Devices
Energy-Saving Canned Motor Pump Market
Pumps and Control Devices
Global Industrial Submersible Pumps Market