
 Europe Centrifugal Pumps Market | 2026-2036
Europe Centrifugal Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Centrifugal Pumps Market Foresight
Asset-light leasing and performance-based service contracts is rewriting competitive entry barriers for mid-sized pump operators. KSB SE & Co. KGaA anchors its position through captive manufacturing scale across German production sites. Sulzer Ltd differentiates via specialized alloy casting capabilities for corrosive chemical duty. Xylem Inc extends its reach through digital monitoring overlays bundled with vertical installations.
Europe centrifugal pumps convert rotational kinetic energy into hydrodynamic energy through an impeller assembly, typically handling flow rates from cubic meters per hour to thousands of cubic meters per hour at heads spanning meters to hundreds of meters, with single-stage designs dominating low-pressure water transfer and multi-stage configurations addressing high-pressure boiler feed and reverse osmosis duties. Single-stage pumps occupy the largest installed base across municipal water networks due to simpler maintenance protocols, while magnetic drive variants capture margin pools in chemical processing as sealless construction eliminates fugitive emissions liability under REACH compliance. Submersible installations lead growth in wastewater infrastructure renewal across Benelux and British utilities.
The EU Green Deal and Ecodesign Directive progressively tighten minimum efficiency index requirements for clean water pumps, while REACH and RoHS constrain material selection in wetted components. CE marking under the Machinery Directive governs safety integration for portable and fixed installations alike. Stakeholders must monitor how the EU AI Act's risk classification affects predictive maintenance algorithms embedded in smart pump controllers.
Market Dynamics
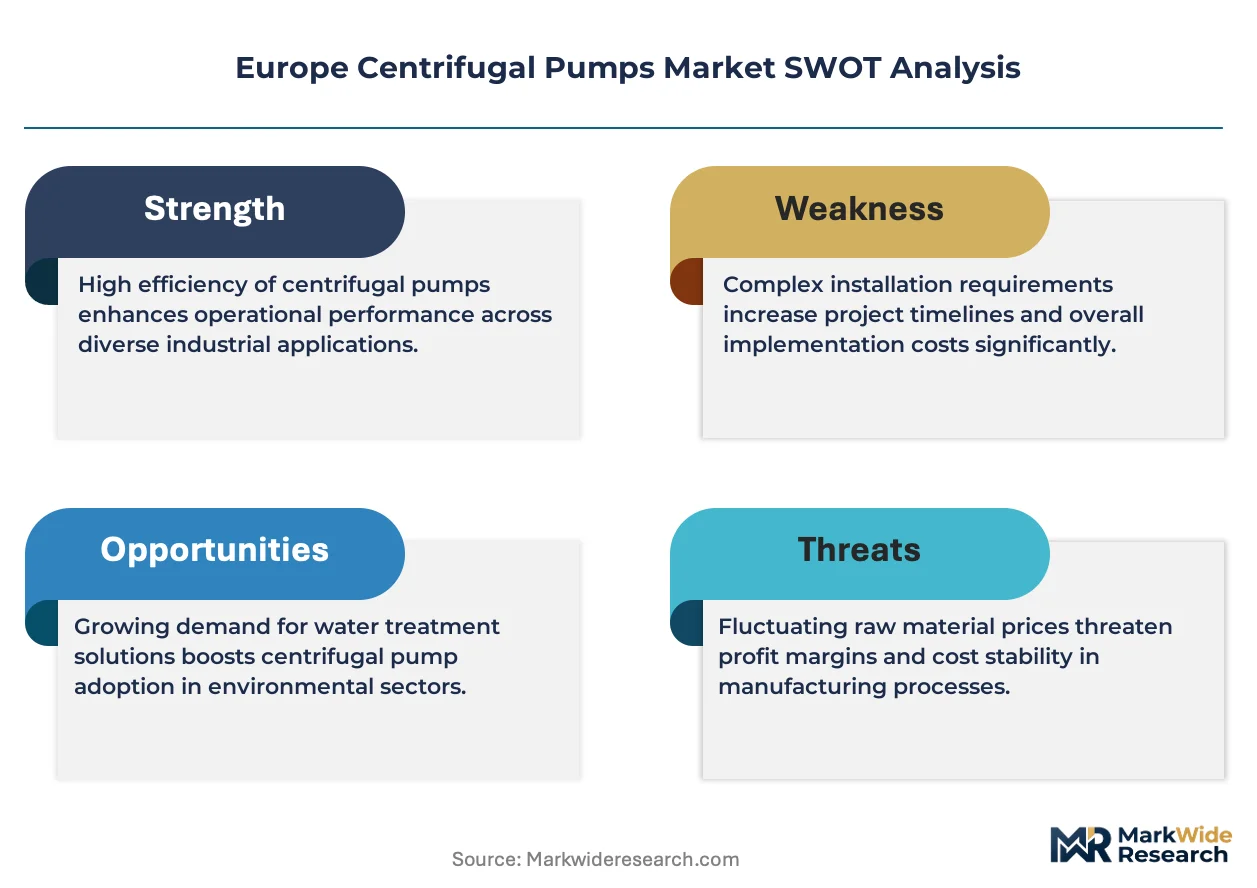
EU Ecodesign Directive efficiency mandates are compressing the installed base of sub-IE3 motor-pump combinations, forcing asset replacement cycles to accelerate across German municipal water authorities and French chemical processors.
Growth Catalysts
- Nordic District Heating Networks:Denmark and Sweden are expanding fourth-generation low-temperature heat distribution, requiring high-efficiency circulating pumps with variable frequency drives.
- REACH Compliance:Sealless magnetic drive configurations eliminate fugitive emissions liability in chemical processing, expanding addressable market share for corrosion-resistant alloy pump variants.
- Benelux Wastewater Infrastructure:Dutch and Belgian utilities are prioritizing submersible pump renewal in combined sewer overflow systems, creating procurement volume concentration.
Market Restraints
- Specialized Casting Supply:Super-duplex and Hastelloy impeller castings concentrate among a handful of European foundries, creating input bottlenecks for corrosive-duty pump manufacturers.
- F-Gas Regulation Phase-Down:Refrigerant-based pump cooling systems face retrofit obligations, adding compliance cost layers to existing installed assets.
- Permanent Magnet Cost Volatility:Rare-earth magnet price swings for high-efficiency synchronous motors compress margin predictability in premium pump segments.
Strategic Opportunities
- EU AI Act Risk Classification:Predictive maintenance algorithms in smart pump controllers present first-mover positioning for vendors achieving conformity assessment.
- Polish Industrial Clusters:Central European manufacturing expansion creates greenfield demand for process cooling and boiler feed pump installations.
- Performance Contracting Models:Energy-as-a-service arrangements allow pump OEMs to capture lifetime value streams from guaranteed efficiency outcomes.
Industry Challenges
- Electromechanical Skill Shortage:Maintenance technicians with combined mechanical seal and VFD commissioning expertise are scarce across German industrial regions.
- CE Marking Documentation Burden:Machinery Directive technical file requirements extend product launch timelines for modular pump platform expansions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Centrifugal Pumps Market |
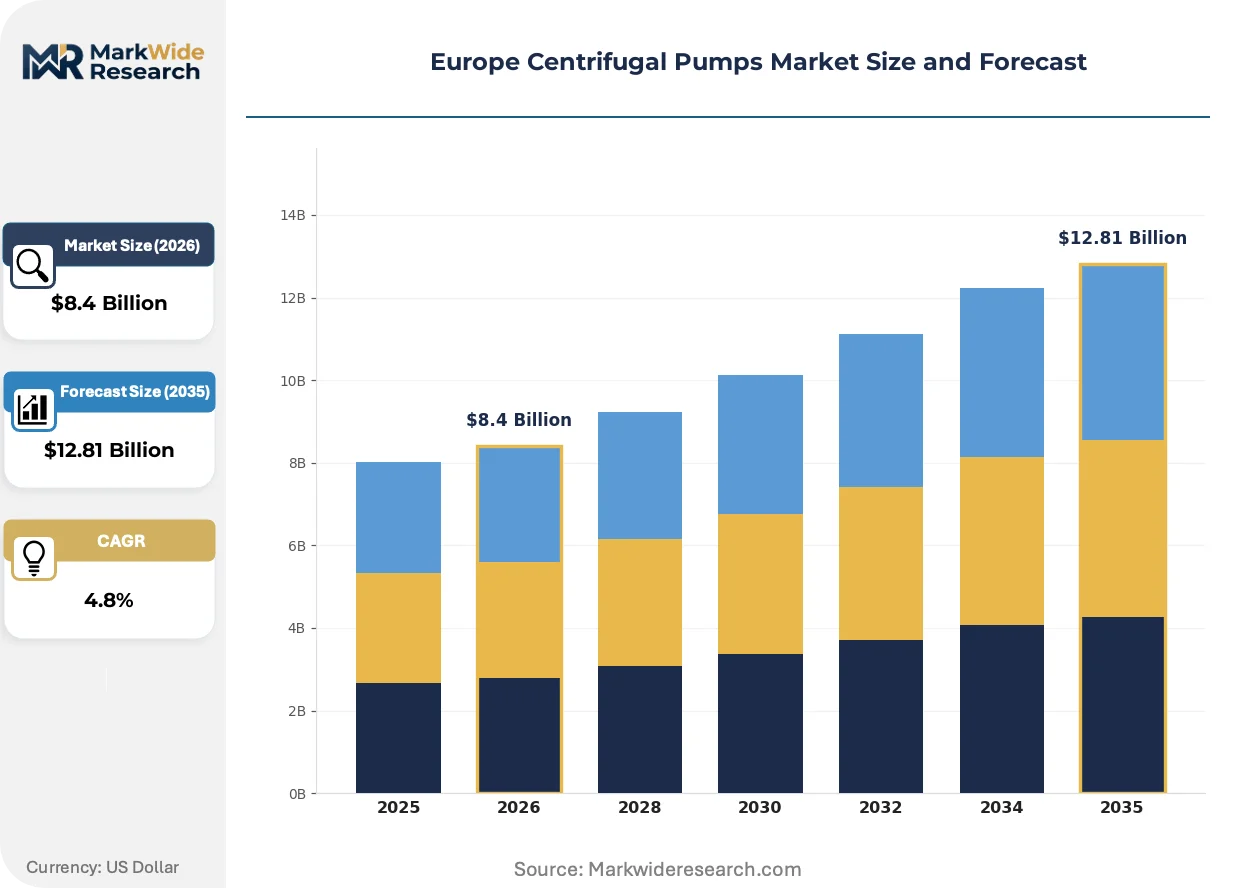
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.81 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Stage, Multi Stage, Submersible, Magnetic Drive End User: Water Treatment, Chemical Processing, Oil & Gas, Power Generation Installation: Horizontal, Vertical, Portable, Fixed Capacity: Low Capacity, Medium Capacity, High Capacity, Others |
| Companies Covered | Baker Hughes Company, Sulzer Ltd, The Weir Group PLC, Flowserve Corporation, KSB SE & Co. KGaA, Ebara Corporation, Dover Corporation, Xylem Inc, Edur Pumpenfabrik Eduard Redlien GmbH & Co., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Centrifugal Pumps Market Shifts & Advancements
Digital twin integration and additive manufacturing are converging to compress development cycles and enable mass customization in pump hydraulics, reshaping how European OEMs configure product platforms.
Computational fluid dynamics is hybridizing with generative design algorithms to optimize impeller vane geometry for specific duty points. German pump engineers are deploying these tools for municipal water applications with non-standard head-flow requirements. This convergence is compressing the traditional prototype-test-iterate cycle from months to weeks.
The EU F-Gas Regulation progressively restricts hydrofluorocarbon use in cooling circuits integrated with high-temperature pump motors. Industrial pump OEMs are redesigning thermal management architectures to accommodate natural refrigerant alternatives. Chemical processing installations in France and Belgium face the most immediate retrofit obligations.
Water utilities in Germany and the Netherlands are consolidating procurement through framework agreements with embedded uptime guarantees. Traditional equipment-only sales are losing share to integrated service contracts bundling monitoring, maintenance, and efficiency performance. Municipal buyers in the Rhine-Ruhr metropolitan region are driving this structural shift fastest.
Europe Centrifugal Pumps Market Segmentation
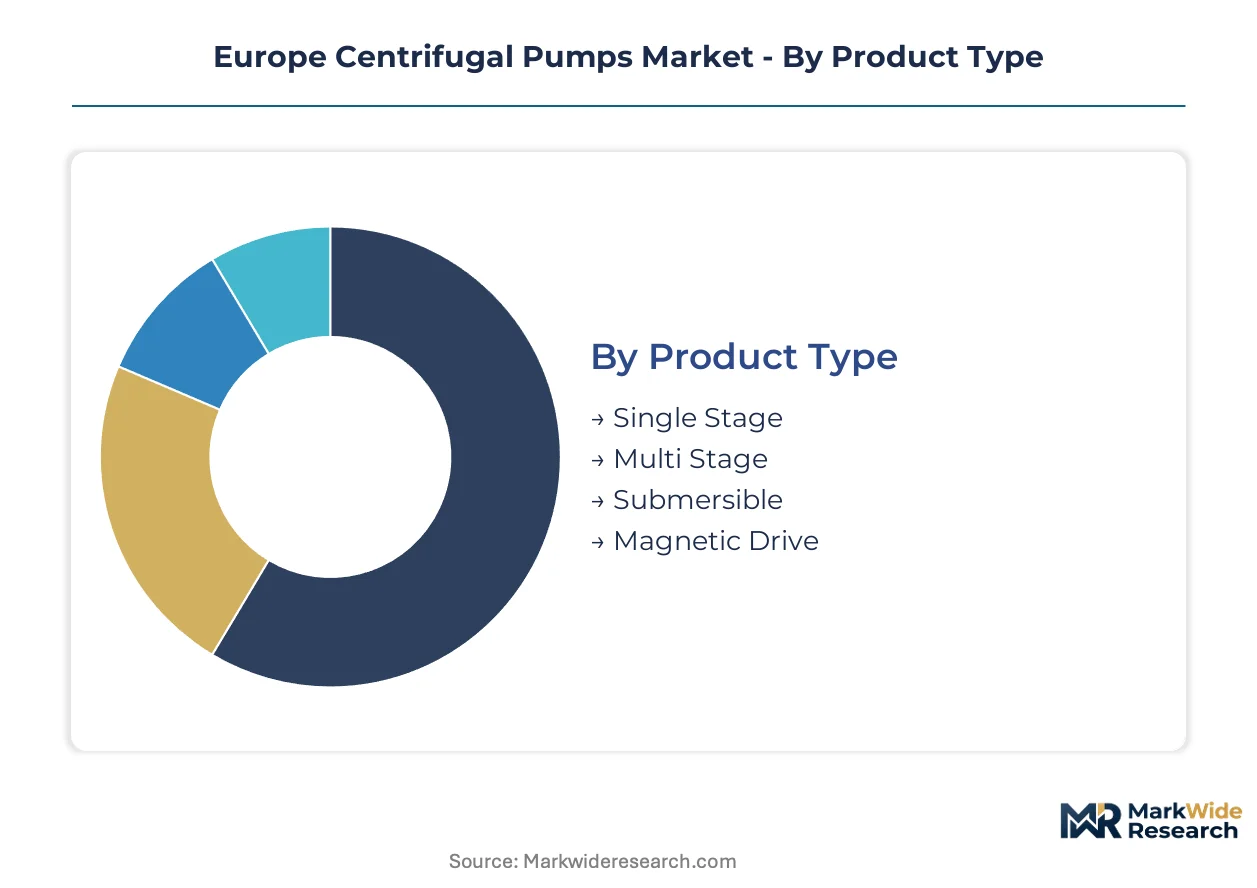
Centrifugal pump procurement patterns diverge sharply across duty specifications and installation contexts. Replacement cycles, energy efficiency mandates, and site-specific hydraulic requirements create distinct commercial pockets within each segment dimension.
Product Type:
Single-stage pumps turn over fastest in municipal water networks where preventive maintenance schedules dominate, while magnetic drive configurations cycle slowly due to specialized alloy lead times and extended capital approval processes in chemical processing.
- Single Stage:These pumps employ one impeller to generate moderate head pressures up to 150 meters. German municipal water authorities in the Rhine-Ruhr corridor are consolidating procurement through framework agreements that prioritize standardized single-stage units for distribution network redundancy.
- Multi Stage:Stacked impeller assemblies deliver high-pressure outputs exceeding 300 meters for boiler feed and reverse osmosis duties. French nuclear power operators and Polish district heating utilities are driving specification upgrades toward IE4 motor compatibility under Ecodesign Directive pressure.
- Submersible:Motor-pump integrated units for wet-pit installations dominate Benelux wastewater infrastructure renewal where combined sewer overflow systems require flood-proof operation.
- Magnetic Drive:Sealless construction eliminates mechanical seal maintenance and fugitive emissions liability under REACH compliance, concentrating demand in Belgian and Dutch chemical clusters handling aggressive media.
Single-stage pumps anchor the volume base while magnetic drive configurations gain share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive process industries from operational-expense-driven municipal utilities, with chemical processors absorbing premium alloy pricing and water authorities optimizing for lifecycle energy cost.
- Water Treatment:Municipal and industrial water utilities specify corrosion-resistant cast iron or stainless steel wet ends for raw water intake, filtration, and distribution. Dutch drinking water companies are embedding digital monitoring requirements into tender specifications for new pumping stations.
- Chemical Processing:Aggressive media handling demands super-duplex or Hastelloy wetted components with specialized mechanical seals or magnetic drive isolation. French petrochemical complexes along the Rhône corridor are retrofitting cooling circuits to accommodate F-Gas Regulation phase-down timelines.
- Oil & Gas:Offshore platform and refinery duties require API 610 compliance for high-temperature hydrocarbon transfer, with North Sea operators prioritizing compact vertical turbine configurations.
- Power Generation:Boiler feed and cooling water circuits specify multi-stage barrel pumps with precision balancing for continuous duty. Swedish and Finnish nuclear facilities are extending maintenance intervals through predictive analytics integration.
Water treatment commands the largest installed base while chemical processing delivers the highest average selling prices per unit.
Installation:
Volume concentration favors fixed horizontal installations in industrial process lines, whereas portable configurations serve intermittent construction dewatering and emergency flood response with minimal upfront capital commitment.
- Horizontal:Foot-mounted split-case or end-suction designs dominate permanent industrial process installations. German automotive manufacturing clusters specify these for cooling tower and parts washing circuits with standardized spare parts strategies.
- Vertical:Space-constrained installations and deep well applications favor vertical turbine or canned motor configurations. Nordic district heating networks in Copenhagen and Stockholm are specifying vertical inline pumps for fourth-generation low-temperature distribution.
- Portable:Engine-driven or electric submersible units serve construction site dewatering and emergency response. British water utilities maintain rental fleets for storm event deployment.
- Fixed:Permanent foundation-mounted installations with dedicated electrical infrastructure characterize municipal water treatment and industrial process applications across the European core.
Fixed installations retain the majority of capital deployment while portable configurations expand most quickly in climate adaptation infrastructure.
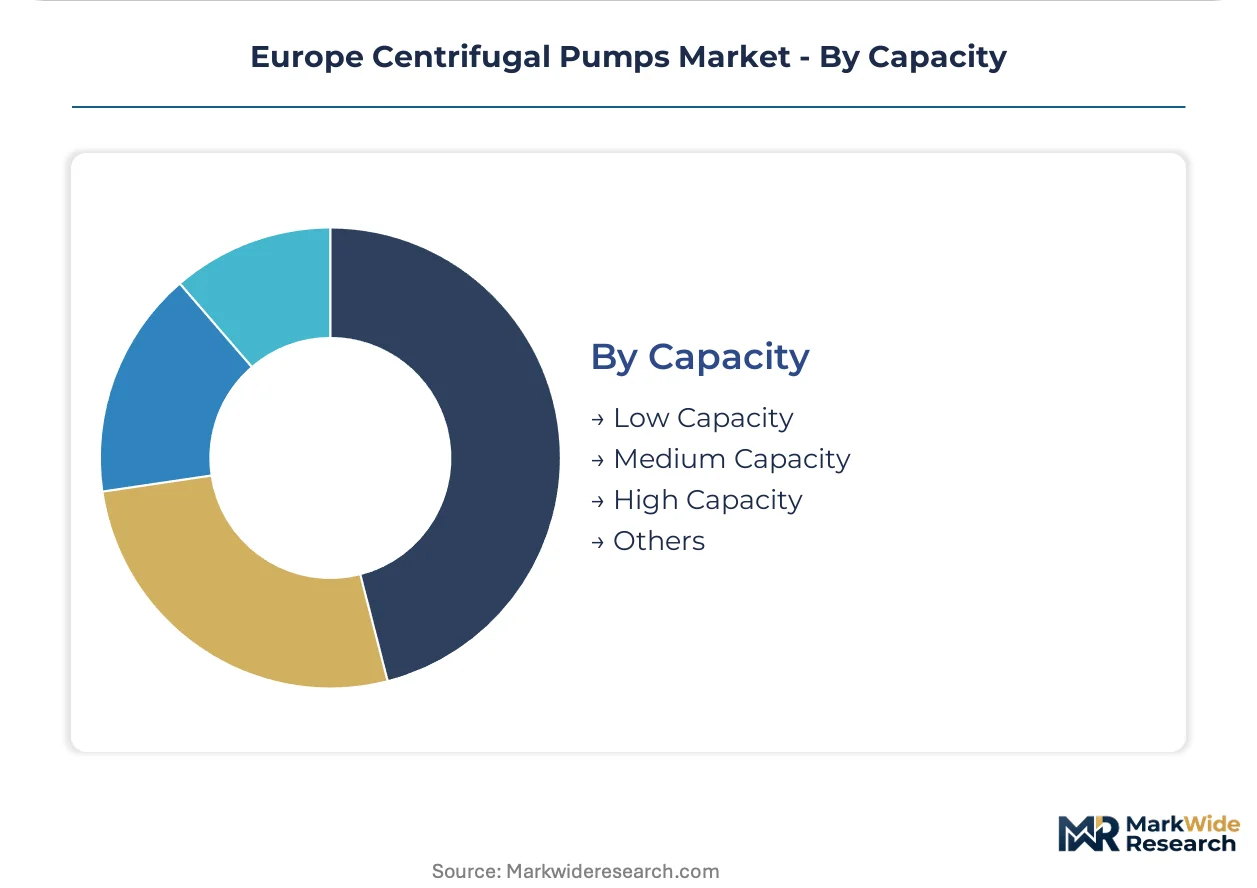
Capacity:
Customer type separation distinguishes large-scale utility bulk transfer from distributed industrial process loops, with specification authority residing in engineering procurement departments versus maintenance operations.
- Low Capacity:Small fractional horsepower units serve building services, laboratory circulation, and light industrial process support. German Mittelstand manufacturers specify these for machine tool cooling and parts washing.
- Medium Capacity:Mid-range flows from 50 to 500 cubic meters per hour address municipal booster stations and industrial process water loops. French regional water utilities are standardizing on this band for network pressure management.
- High Capacity:Large axial split-case or vertical turbine pumps handle raw water intake and flood control duties exceeding 1,000 cubic meters per hour. Dutch polder drainage authorities specify these for low-head high-volume applications.
- Others:Specialized micro-pumps and custom-engineered units outside standard catalog ranges serve medical, laboratory, and precision manufacturing niches with extended lead times.
Medium capacity pumps generate the broadest revenue footprint while high capacity units concentrate in the largest infrastructure projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal and Ecodesign Directive are redistributing procurement volumes across European industrial clusters, with efficiency mandates accelerating replacement cycles in municipal water networks and chemical processing hubs.
Germany
Rhine-Ruhr metropolitan water authorities are consolidating single-stage pump procurement through multi-year framework agreements. The Ecodesign Directive's IE3 motor mandates are compressing installed base renewal timelines. Bavarian automotive manufacturing clusters specify standardized horizontal pumps for cooling tower circuits with captive spare parts strategies.
France
Nuclear power operators along the Rhône corridor are upgrading multi-stage boiler feed pumps toward IE4 motor compatibility. The F-Gas Regulation phase-down is forcing cooling circuit retrofits in petrochemical complexes. Île-de-France municipal utilities are embedding digital monitoring requirements into tender specifications for new pumping stations.
Netherlands
Dutch drinking water companies and polder drainage authorities are driving submersible and high-capacity axial split-case procurement. REACH compliance is concentrating demand for sealless magnetic drive configurations in Rotterdam chemical clusters. Combined sewer overflow system renewals across Randstad utilities are creating procurement volume concentration.
Sweden
Stockholm and Copenhagen district heating networks are specifying vertical inline pumps for fourth-generation low-temperature distribution. Swedish nuclear facilities are extending maintenance intervals through predictive analytics integration. The Nordic investment in circulating pumps with variable frequency drives is outpacing continental European replacement rates.
Poland
Central European manufacturing expansion is generating greenfield demand for process cooling and boiler feed installations. Polish district heating utilities are specification-upgrading multi-stage pumps under Ecodesign Directive pressure. Silesian industrial clusters are emerging as procurement concentration points for medium-capacity process water loops.
Europe Centrifugal Pumps Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement tiers. The vendor base organizes around three strategic archetypes: captive manufacturing scale operators, specialized alloy casting fabricators, and digital service integrators. M&A activity concentrates on predictive maintenance platform acquisitions, while geographic expansion targets Polish and Nordic greenfield installations.
Among German-based manufacturers, KSB SE & Co. KGaA anchors the captive production scale archetype through domestic manufacturing concentration. Sulzer Ltd exemplifies specialized alloy capabilities for corrosive chemical duty. Xylem Inc occupies a position within the digital overlay tier, bundling monitoring systems with vertical installation bases.
| Leading Market Players |
|---|
| Baker Hughes Company |
| Sulzer Ltd |
| The Weir Group PLC |
| Flowserve Corporation |
| KSB SE & Co. KGaA |
| Ebara Corporation |
| Dover Corporation |
| Xylem Inc |
| Edur Pumpenfabrik Eduard Redlien GmbH & Co. |
| Others |
Supply & Pricing Matrix
German foundry clusters in the Ruhr region anchor super-duplex and Hastelloy casting capacity for corrosion-resistant impellers, concentrating input pricing power among a handful of specialized suppliers serving chemical-duty pump OEMs. This geographic concentration of alloy casting expertise translates directly into margin pressure for manufacturers sourcing wetted components under REACH compliance timelines.
Pricing Analysis
Certification level under EU Ecodesign Directive and Machinery Directive CE marking creates the primary spread between premium and standard pump tiers. Three-tier pricing structure across premium IE4-motor configurations, standard IE3-compliant units, and economy replacement-grade equipment dominates procurement. Cost compression in economy tiers is intensifying because municipal water authorities are consolidating framework agreements with embedded uptime guarantees. Water treatment utilities exhibit highest price sensitivity due to lifecycle energy cost optimization mandates, while chemical processors absorb premium alloy pricing for sealless magnetic drive configurations.
Supply Chain Analysis
Super-duplex stainless steel and rare-earth permanent magnets for high-efficiency synchronous motors feed from concentrated European and Asian supply nodes. Foundry capacity for specialized alloy castings rests on German, Italian, and Swedish production sites, while neodymium magnet processing hinges on Chinese separation and refining infrastructure. Single-source vulnerability in super-duplex impeller casting creates procurement bottlenecks for corrosive-duty manufacturers. Distribution runs through OEM direct sales for large industrial projects and authorized distributor networks for municipal maintenance replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe centrifugal pumps market functions as a defensive-moat arena where regulatory entrenchment through Ecodesign Directive compliance and CE marking documentation creates substantial switching costs for installed asset bases.
For Market Incumbents: Entrench position through captive backward integration into specialized alloy casting capabilities, insulating margin structures from Ruhr foundry pricing power. Accelerate predictive maintenance platform certification under EU AI Act risk classification timelines to lock in municipal framework agreement renewals before emerging digital challengers achieve conformity assessment.
For New Entrants and Emerging Players: Build out service-only market presence through performance-based contracting models in Polish industrial clusters where greenfield installation demand outpaces established OEM service coverage. Target medium-capacity process water loops in Silesian manufacturing expansion zones with energy-as-a-service arrangements that bypass capital-intensive manufacturing scale requirements.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors predictive maintenance software specialists with embedded pump controller algorithms over pure hardware fabricators. Long-term viability accrues to vendors controlling digital twin integration capabilities that compress development cycles for municipal custom hydraulics. Watch for inflection signals in rare-earth magnet price stabilization that would restore margin predictability to premium IE4 motor-pump combinations.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Certification | EU AI Act conformity assessment creates first-mover positioning in smart municipal pumping stations. |
| Specialized Alloy Casting Acquisition | Ruhr foundry capacity control insulates margin structures from super-duplex input bottlenecks. |
| Performance Contracting Model Launch | Energy-as-a-service arrangements capture lifetime value streams from guaranteed efficiency outcomes. |
| Polish Greenfield Service Expansion | Silesian industrial cluster proximity addresses unmet process cooling and boiler feed demand. |
| Digital Twin Integration Development | Generative design algorithm deployment compresses prototype-test-iterate cycles for custom hydraulics. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU Ecodesign Directive implementation reports, REACH compliance databases, and Machinery Directive technical file repositories. Primary interviews engaged maintenance directors at German municipal water authorities, procurement leads at French nuclear operators, plant engineers at Belgian chemical clusters, and aftermarket service heads at Nordic district heating utilities. Secondary validation drew from customs trade data for pump and motor imports, SEC filings of listed pump OEMs, and national energy agency efficiency program disclosures. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Forecast inputs span product type segmentation by stage configuration and drive architecture, end-user segmentation by water treatment versus chemical processing duty, and installation segmentation by fixed versus portable deployment. Capacity tier modeling incorporated low, medium, and high flow rate bands with motor efficiency grade stratification. CAGRs were derived from replacement cycle compression under Ecodesign Directive mandates and greenfield installation trajectories in Central European manufacturing expansion zones.
Sensitivities concentrate around rare-earth magnet price volatility, REACH material restriction scope expansion, and EU AI Act enforcement timelines for predictive maintenance algorithms. Forecasts embed assumptions regarding Ecodesign Directive phase-in adherence and municipal procurement consolidation patterns. Cross-checking against national energy efficiency program expenditure disclosures and utility capital plan filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Asia Pacific Submersible Pump Market
Pumps and Control Devices
Single-Stage Centrifugal Pumps Market
Pumps and Control Devices
Fuel Feed Pumps Market
Pumps and Control Devices
North America Submersible Pumps Market
Pumps and Control Devices
Suction Pump Market
Pumps and Control Devices
Chemical Pump Market
Pumps and Control Devices
Progressive Cavity Pump (PCP) Market
Pumps and Control Devices
Food and Beverages Industry Pumps Market
Pumps and Control Devices
Centrifugal Pump Market
Pumps and Control Devices
Wind Powered Water Pumps Market
Pumps and Control Devices
Vertical Immersion Pumps Market
Pumps and Control Devices
Subsea Pump System Market
Pumps and Control Devices
Paint Pump Market
Pumps and Control Devices
Global Commercial Pumps Market
Pumps and Control Devices
Global Solar-Powered Pump Market
Pumps and Control Devices
Subsea Pumps Market