
 Glycol Pumps Market | 2026-2036
Glycol Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Glycol Pumps Market Insights
API 610 certification for centrifugal pumps is bifurcating the competitive landscape into qualified system suppliers and commodity component vendors. Grundfos leverages its integrated drive technology to capture premium retrofit contracts in district energy networks. Flowserve Corporation anchors its position through backward integration into precision casting for corrosion-resistant alloys. KSB SE & Co. KGaA competes on modular platform designs that reduce field commissioning time for chemical processing clients.
Glycol pumps are sealed fluid-handling devices engineered to circulate propylene or ethylene glycol solutions across temperature ranges from minus forty to plus two hundred degrees Celsius, serving as the thermal transfer backbone for closed-loop heating and cooling systems. Positive displacement configurations dominate high-viscosity chemical processing duties where precise flow control protects reactor stability. Centrifugal variants lead in HVAC Systems and Power Generation due to lower maintenance overhead at high throughput volumes. Gear pump installations concentrate margin pools in food-grade applications requiring sanitary compliance and CIP compatibility.
The EPA enforces refrigerant containment standards under Section 608 that mandate leak detection integration, while OSHA's Process Safety Management rules govern glycol pump installations in chemical facilities. The EU F-Gas Regulation indirectly shapes demand by accelerating hydrocarbon and glycol-based secondary loop adoption in European commercial refrigeration. Stakeholders must monitor evolving refrigerant phase-down schedules and assess whether their pump portfolios align with low-global-warming-potential system architectures.
Market Dynamics
Building electrification mandates and refrigerant phase-down schedules are compressing specification cycles for thermal transfer equipment, forcing pump manufacturers to align portfolios with low-GWP system architectures faster than traditional replacement timelines allow.
Growth Catalysts
- AIM Act Implementation:EPA refrigerant management rules under Section 608 are accelerating glycol-based secondary loop retrofits in US commercial refrigeration infrastructure.
- Data Center Thermal Loads:Hyperscale computing clusters in Northern Virginia and Phoenix are specifying high-capacity centrifugal glycol pumps for liquid cooling architectures.
- Stainless Steel Casting Advances:Precision investment casting improvements are extending mean time between failures for corrosive chemical processing duties.
Market Restraints
- Alloy Input Volatility:Nickel and molybdenum price swings distort margin planning for corrosion-resistant pump housings.
- Foundry Concentration:Premium stainless steel casting capacity clusters in Germany and Japan, creating supply bottlenecks for rapid scaling.
- Mechanical Seal Limitations:Standard cartridge seals face temperature-pressure envelopes that exclude ultra-low-temperature hydrocarbon processing applications.
Strategic Opportunities
- India Cold Chain Buildout:FSSAI food safety mandates and PLI scheme incentives are opening commercial refrigeration pump demand in Mumbai and Delhi logistics corridors.
- Hydrogen Economy Thermal Management:Electrolyzer cooling loops represent emerging specification territory for high-purity glycol circulation systems.
- CE-MDR Certification Arbitrage:EU medical device regulation compliance creates premium positioning for sanitary-grade positive displacement pumps in pharmaceutical manufacturing.
Industry Challenges
- API 610 Qualification Timelines:Centrifugal pump certification for oil and gas applications demands 18-24 month validation cycles that strain R&D resource allocation.
- Legacy Control Integration:Smart pump variable frequency drives must interface with decades-old BAS protocols in district heating retrofits.
- Specialized Welding Expertise:Orbital welding certification for food-grade installations exceeds available technician supply in expanding markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glycol Pumps Market |
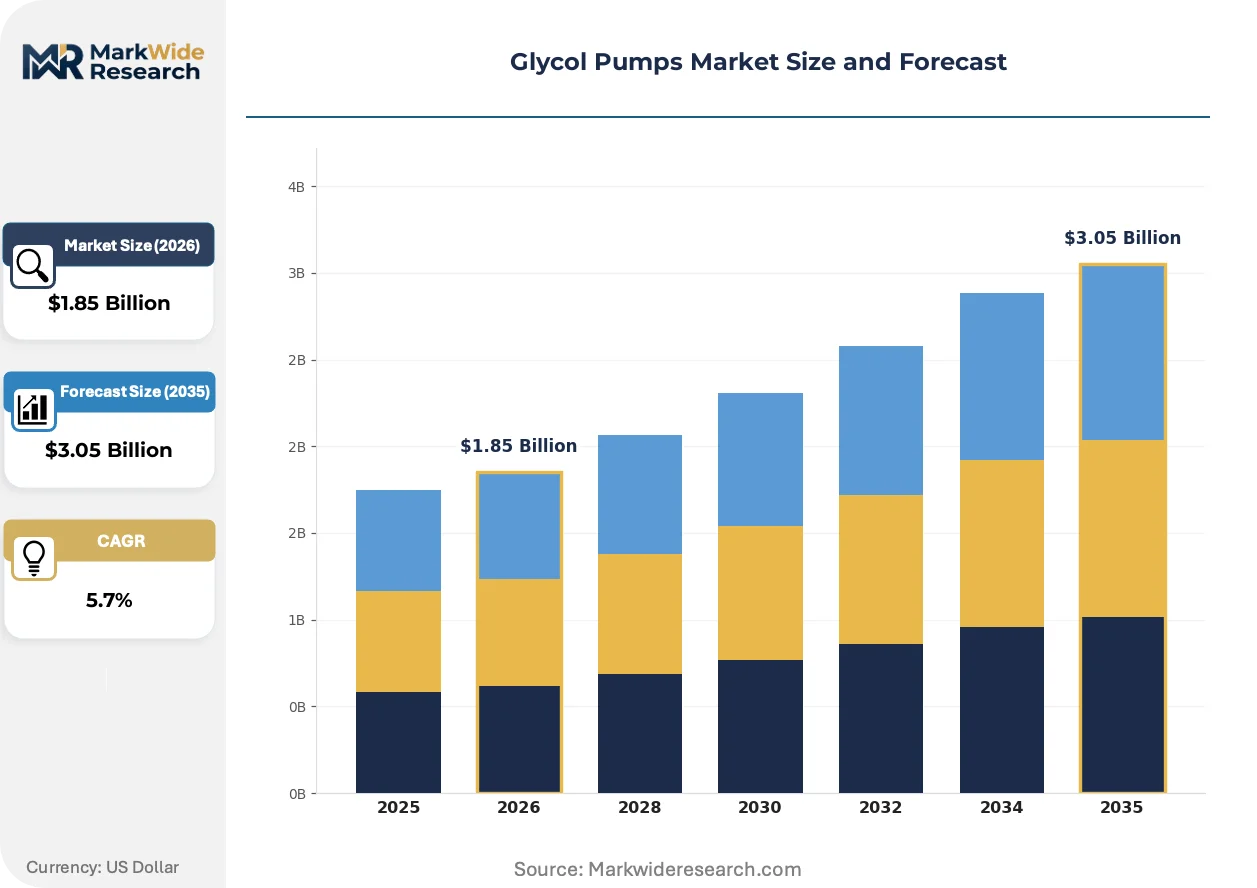
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.05 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Positive Displacement, Centrifugal, Gear, Diaphragm End User: Power Generation, HVAC Systems, Chemical Processing, Food & Beverage Installation Type: Horizontal, Vertical, Submersible, Portable Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Grundfos, ITT Inc., Flowserve Corporation, Xylem Inc., KSB SE & Co. KGaA, SPX Flow, Inc., Goulds Pumps, Cat Pumps, HERMETIC-Pumpen GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glycol Pumps Market Trends and Innovations
Digital twin integration and predictive maintenance architectures are rewriting service revenue models for fluid handling equipment, while material science advances expand operating envelopes.
Magnetic drive sealless pump technology is displacing traditional mechanical seal configurations in chemical processing and pharmaceutical applications. BASF and Dow chemical facilities are specifying canned motor and magnetic coupling designs to eliminate fugitive emissions. This shift is displacing aftermarket seal replacement revenue streams while compressing total cost of ownership calculations for end users.
EU F-Gas Regulation phase-down schedules are tightening refrigerant containment requirements for commercial cooling systems. Equipment OEMs must now integrate leak detection and pump redundancy into secondary loop designs. Food retail chains in Germany and France are accelerating glycol chiller deployments ahead of 2030 reduction targets.
Performance-based service contracting is restructuring buyer-supplier relationships in district energy networks. Copenhagen and Stockholm utilities now specify energy-per-thermal-delivered metrics rather than capital equipment procurement. This model transfers operational risk to pump manufacturers while locking in decade-long maintenance revenue commitments.
Glycol Pumps Market Segmentation
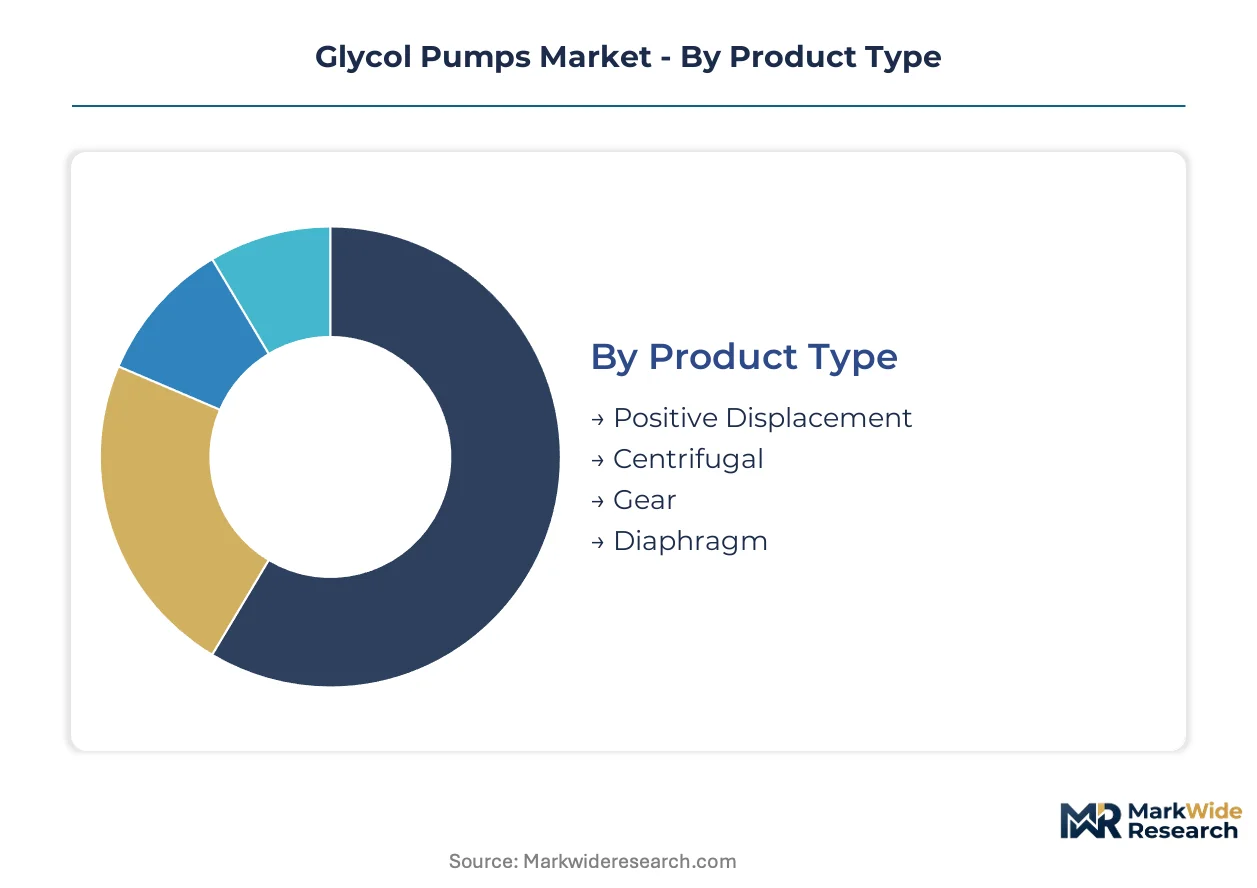
Glycol pump procurement splits across technical specifications, installation constraints, and channel economics. Each segmentation axis carries distinct margin profiles and qualification barriers that reshape competitive positioning.
Product Type:
EPA Section 608 leak detection mandates and EU F-Gas Regulation phase-down schedules are bifurcating certification requirements between sealless magnetic drive systems and conventional mechanical seal configurations.
- Positive Displacement:Reciprocating or rotary mechanisms deliver precise volumetric flow control across viscosity ranges from 1 to 10,000 centipoise. Chemical processing facilities in Texas and Louisiana specify these for reactor feed loops where flow deviation risks thermal runaway. API 675 compliance for controlled volume pumps extends qualification timelines to 18 months.
- Centrifugal:Radial flow impellers generate pressure through rotational kinetic energy conversion, enabling throughputs exceeding 5,000 gallons per minute. Data center liquid cooling projects in Northern Virginia and Phoenix are specifying these for primary glycol distribution loops. Lower maintenance overhead at high volumes displaces positive displacement units in HVAC Systems.
- Gear:Intermeshing rotors provide pulsation-free discharge for viscous heat transfer fluids. Food-grade installations requiring 3A sanitary certification and CIP compatibility concentrate demand in dairy processing corridors.
- Diaphragm:Flexible membrane isolation separates pumped fluid from mechanical actuation, eliminating seal wear in abrasive or crystallizing glycol mixtures. Pharmaceutical batch processing in New Jersey and Massachusetts specifies these for high-purity loops.
Centrifugal pumps handle the majority of throughput; Positive Displacement is climbing the fastest on share as chemical processing capacity expands.
End User:
Customer capital deployment cycles range from 7-year utility replacement schedules to 18-month hyperscale data center construction timelines, compressing specification windows for equipment vendors.
- Power Generation:Combined cycle gas turbine plants and nuclear facilities deploy glycol pumps for turbine inlet cooling and auxiliary heat rejection systems. ERCOT grid reliability mandates in Texas are accelerating turbine cooling retrofits. Stainless steel construction withstands chloride stress corrosion in coastal installations.
- HVAC Systems:District heating networks and commercial building chilled water loops represent the largest addressable equipment volume. Building electrification mandates in California and New York are displacing gas-fired heating with glycol-based heat pump distribution. ASHRAE 90.1 efficiency standards tighten pump motor specifications.
- Chemical Processing:Ethylene oxide production and polyester manufacturing require corrosion-resistant circulation for sub-zero reaction control. OSHA Process Safety Management rules govern installation integrity testing frequencies.
- Food & Beverage:Brewery wort cooling and dairy pasteurization systems demand sanitary-grade positive displacement configurations. FSSAI cold chain mandates in India are opening specification opportunities in Mumbai logistics corridors.
HVAC Systems captures the dominant equipment volume; Food & Beverage shows the steepest expansion trajectory as cold chain infrastructure multiplies.
Installation Type:
Footprint constraints and NPSH availability dictate orientation selection, with vertical configurations commanding 15-20% price premiums for space-constrained urban substations.
- Horizontal:Split-case or end-suction designs dominate industrial process floors with adequate ceiling clearance. Chemical plants in the Gulf Coast petrochemical corridor standardize on these for maintenance accessibility.
- Vertical:Inline or can-type pumps reduce horizontal footprint by 60% in high-rise building mechanical rooms. District heating substations in Copenhagen and Stockholm specify these for basement installation constraints.
- Submersible:Hermetically sealed motors eliminate shaft penetration points in flooded sump or tank applications. Geothermal heat pump systems in the Midwestern United States deploy these for ground loop circulation.
- Portable:Skid-mounted or cart-based configurations enable temporary cooling for emergency shutdown maintenance. Refinery turnaround contractors in Louisiana and Texas rent these for 30-90 day campaigns.
Horizontal installations carry the majority of existing stock; Vertical configurations are gaining share fastest as urban building density increases.
Distribution Channel:
Channel selection correlates with project scale and technical complexity, with direct relationships locking in decade-long service revenue for district energy utilities.
- Direct Sales:Manufacturer-employed engineers specify integrated pump-drive packages for performance-based contracting models. Copenhagen and Stockholm utilities negotiate energy-per-thermal-delivered metrics directly with Grundfos and Flowserve.
- Online Retail:E-commerce platforms capture replacement component demand for standardized HVAC maintenance. Small commercial contractors in the Sun Belt states source cartridge seals and impellers through Amazon Business and Grainger.
- Wholesalers:Regional inventory stocking points serve mechanical contractors with 24-48 hour availability requirements. Ferguson Enterprises and Watsco branches dominate Southeast and Southwest United States distribution.
- Distributors:Authorized representatives provide application engineering support for specification-sensitive process industries. KSB and Sulzer rely on these for chemical processing penetration in the Ohio River Valley.
Direct Sales commands the highest revenue per transaction; Online Retail is expanding most quickly as standardized HVAC maintenance shifts to digital procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA refrigerant phase-down rules under the AIM Act are accelerating glycol pump retrofits in US commercial refrigeration infrastructure. District heating electrification mandates across Northern Europe and data center thermal management buildouts in Asia-Pacific are redrawing regional demand maps.
United States
Data center liquid cooling projects in Northern Virginia and Phoenix are specifying high-capacity centrifugal glycol pumps for hyperscale computing clusters. EPA Section 608 leak detection mandates are forcing secondary loop retrofits in supermarket refrigeration chains. The Gulf Coast petrochemical corridor in Texas and Louisiana maintains demand for corrosion-resistant positive displacement configurations.
Germany
EU F-Gas Regulation phase-down schedules are tightening refrigerant containment requirements for commercial cooling systems. The country's national environmental regulator is accelerating hydrocarbon and glycol-based secondary loop adoption in food retail chains. Industrial clusters in North Rhine-Westphalia and Bavaria are deploying magnetic drive sealless pumps to eliminate fugitive emissions.
India
FSSAI food safety mandates and PLI scheme incentives are opening commercial refrigeration pump demand in Mumbai and Delhi logistics corridors. The central food safety regulator's cold chain infrastructure requirements are driving specification opportunities for sanitary-grade positive displacement pumps. Dairy processing corridors in Gujarat and Maharashtra are expanding brewery wort cooling and pasteurization system deployments.
China
Dual carbon goals and building electrification mandates are displacing gas-fired heating with glycol-based heat pump distribution in commercial construction. The Ministry of Ecology and Environment is tightening industrial cooling system efficiency standards. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta are scaling precision investment casting for corrosion-resistant pump housings.
Sweden
Performance-based service contracting is restructuring buyer-supplier relationships in district energy networks. The national energy agency's efficiency metrics now specify energy-per-thermal-delivered rather than capital equipment procurement. Utilities in Stockholm and Copenhagen are negotiating decade-long maintenance commitments with integrated pump-drive package suppliers.
Glycol Pumps Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and geographic coverage. The vendor base stratifies between API-qualified system suppliers and commodity component vendors serving replacement markets. Three archetypes dominate: integrated drive-technology platforms, precision casting backward integrators, and modular platform specialists. Competitive moves concentrate on performance-based contracting models and magnetic drive sealless technology licensing.
Within the integrated technology tier, Grundfos and Flowserve Corporation exemplify positions anchored in district energy network retrofits and chemical processing penetration. KSB SE & Co. KGaA occupies a specialist position in modular platform designs that reduce field commissioning time. These three listed entities represent distinct strategic postures across premium specification, backward integration, and application engineering vectors.
| Leading Market Players |
|---|
| Grundfos |
| ITT Inc. |
| Flowserve Corporation |
| Xylem Inc. |
| KSB SE & Co. KGaA |
| SPX Flow, Inc. |
| Goulds Pumps |
| Cat Pumps |
| HERMETIC-Pumpen GmbH |
| Others |
Pricing and Supply Chain Analysis
API 610 certification gates both supplier qualification and price differentiation simultaneously, compressing commodity vendors into lower-margin replacement channels while elevating certified system integrators into performance-contracting relationships with district energy utilities.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers. Three-tier pricing structure across API-qualified, CE-marked, and uncertified commodity levels dominates project procurement. Price differentiation hinges on corrosion-resistant alloy grade and aftermarket service bundling. Cost compression in standard centrifugal configurations is intensifying because foundry capacity constraints limit rapid scaling. Small commercial contractors exhibit highest price sensitivity; district energy utilities prioritize energy-per-thermal-delivered metrics over capital outlay.
Supply Chain Analysis
Strait of Hormuz transit risk shadows alloy feedstock flows from Middle Eastern nickel sources to German and Japanese foundries. Precision investment casting capacity concentrates in Germany, Japan, and select Yangtze River Delta manufacturing clusters. Raw material dependencies center on nickel, molybdenum, and high-grade stainless steel scrap. Single-source vulnerability persists in magnetic drive sealless pump motor assemblies. Distribution runs through authorized representatives for specification-sensitive process industries, with direct sales capturing district energy network retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Performance-based service contracting expands faster than hardware shipments, converting pump manufacturers into decade-long thermal delivery partners with recurring maintenance revenue streams locked to energy-per-thermal-delivered metrics.
For Market Incumbents: Secure API 675 qualification for controlled volume pumps to defend chemical processing market share against modular platform specialists. Deepen backward integration into precision casting for corrosion-resistant alloys to offset nickel price volatility. Capture district energy retrofit contracts through integrated drive technology bundles that transfer operational risk from utilities. For New Entrants and Emerging Players: CE-MDR certification fast-tracks entry into pharmaceutical manufacturing sanitary pump segments where incumbent capacity is constrained. Target India cold chain buildout in Mumbai and Delhi logistics corridors where FSSAI mandates outpace local supplier scaling. Lead with portable skid-mounted configurations for refinery turnaround contractors seeking 30-90 day rental flexibility. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across magnetic drive sealless pump manufacturing as licensed motor technology commoditizes. Five-to-ten year viability favors targets with captive foundry relationships and installed base service contracts. Watch for electrolyzer cooling loop specification activity as hydrogen economy thermal management inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Service Contracting | Copenhagen and Stockholm utilities now procure energy-per-thermal-delivered rather than capital equipment. |
| Magnetic Drive Sealless Technology Licensing | BASF and Dow facilities specify canned motor designs to eliminate fugitive emissions compliance exposure. |
| Backward Integration into Precision Casting | Flowserve anchors corrosion-resistant alloy supply against nickel price swings distorting margin planning. |
| Modular Platform Standardization | KSB reduces field commissioning time for chemical processing clients through configurable pump-drive packages. |
| India Cold Channel Partnership | FSSAI mandates and PLI scheme incentives open specification opportunities in Gujarat dairy processing corridors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with district energy utility engineers, chemical processing plant managers, HVAC mechanical contractors, aftermarket service directors, and foundry operations leads. Secondary validation drew from EPA Section 608 enforcement data, EU F-Gas Regulation implementation timelines, SEC 10-K equipment disclosures, and ASHRAE 90.1 efficiency standard updates. Bottom-up installation forecasts triangulated against top-down end-use industry capital expenditure patterns.
Across the analysis window, projections model product type splits between positive displacement, centrifugal, gear, and diaphragm configurations alongside end-use segmentation across HVAC systems, chemical processing, power generation, and food and beverage applications. CAGRs derive from historical replacement cycle analysis and regulatory-driven retrofit acceleration curves. Forecast inputs incorporate AIM Act refrigerant phase-down schedules and data center liquid cooling deployment timelines in Northern Virginia and Phoenix.
Underlying assumptions cover alloy price stability and foundry capacity expansion, with deviation risk concentrated in nickel and molybdenum volatility and API 610 qualification timeline delays. Practitioners should keep alternative scenarios live as EPA refrigerant management rule enforcement intensity and EU F-Gas Regulation reduction targets evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Slurry Pumps Market
Pumps and Control Devices
Vane Pump Market
Pumps and Control Devices
Gasketed Plate Heat Exchanger Market
Pumps and Control Devices
Progressive Cavity Pump (PCP) Market
Pumps and Control Devices
Progressing Cavity Pump Market
Pumps and Control Devices
Solar Water Pump Market
Pumps and Control Devices
India Solar Water Pump Systems Market
Pumps and Control Devices
Pressure Washer Pump Oil Market
Pumps and Control Devices
Radial Flow Pump Market
Pumps and Control Devices
Turbomolecular Pumps Market
Pumps and Control Devices
Global High Pressure Pumps Market
Pumps and Control Devices
Rotary Pump Market
Pumps and Control Devices
Circulators Market
Pumps and Control Devices
Hydrogen Circulation Pump Market
Pumps and Control Devices
Peristaltic Pumps Market
Pumps and Control Devices
Global Variable Displacement Pumps Market